
 High-Density Racks Market | 2026-2036
High-Density Racks Market Size, Share, and Industry Trends Forecast 2026-2036
High-Density Racks Market Insights
Power-purchase-agreement-backed project finance is rewriting capital deployment rules for high-density rack infrastructure. Vertiv Group Corp leverages its thermal management integration to anchor premium positions in liquid-cooled deployments. Schneider Electric SE sustains broad geographic coverage through modular factory strategies. Eaton Corporation differentiates via electrical distribution systems purpose-built for 100+ kW rack densities.
High-density racks are engineered structural enclosures designed to support equipment loads exceeding 30 kW per cabinet, typically fabricated from cold-rolled steel with precision-welded frames and integrated cable management channels, serving to maximize compute or storage capacity within fixed floor space. Modular rack configurations lead procurement volumes as operators phase capacity additions in 100-200 kW increments. Steel dominates material selection for load-bearing applications above 50 kW, while aluminum gains share in weight-sensitive mobile rack systems. Data center verticals command the largest margin pools due to custom engineering requirements for liquid cooling integration.
ASHRAE thermal guidelines, EU Code of Conduct for Data Centres, and China's GB standards for electronic equipment enclosures collectively mandate efficiency thresholds that filter supplier eligibility. OSHA workplace safety rules in the United States and Germany's KBA-adjacent structural load certifications shape installation protocols and maintenance access designs. Stakeholders must weigh captive manufacturing against outsourced fabrication as rack power densities render thermal-mechanical integration the decisive procurement criterion.
Market Dynamics
Liquid cooling integration is forcing rack manufacturers to reengineer structural frames for fluid distribution compatibility, as thermal-mechanical convergence becomes the decisive procurement criterion for hyperscale operators deploying 50+ kW cabinets.
Growth Catalysts
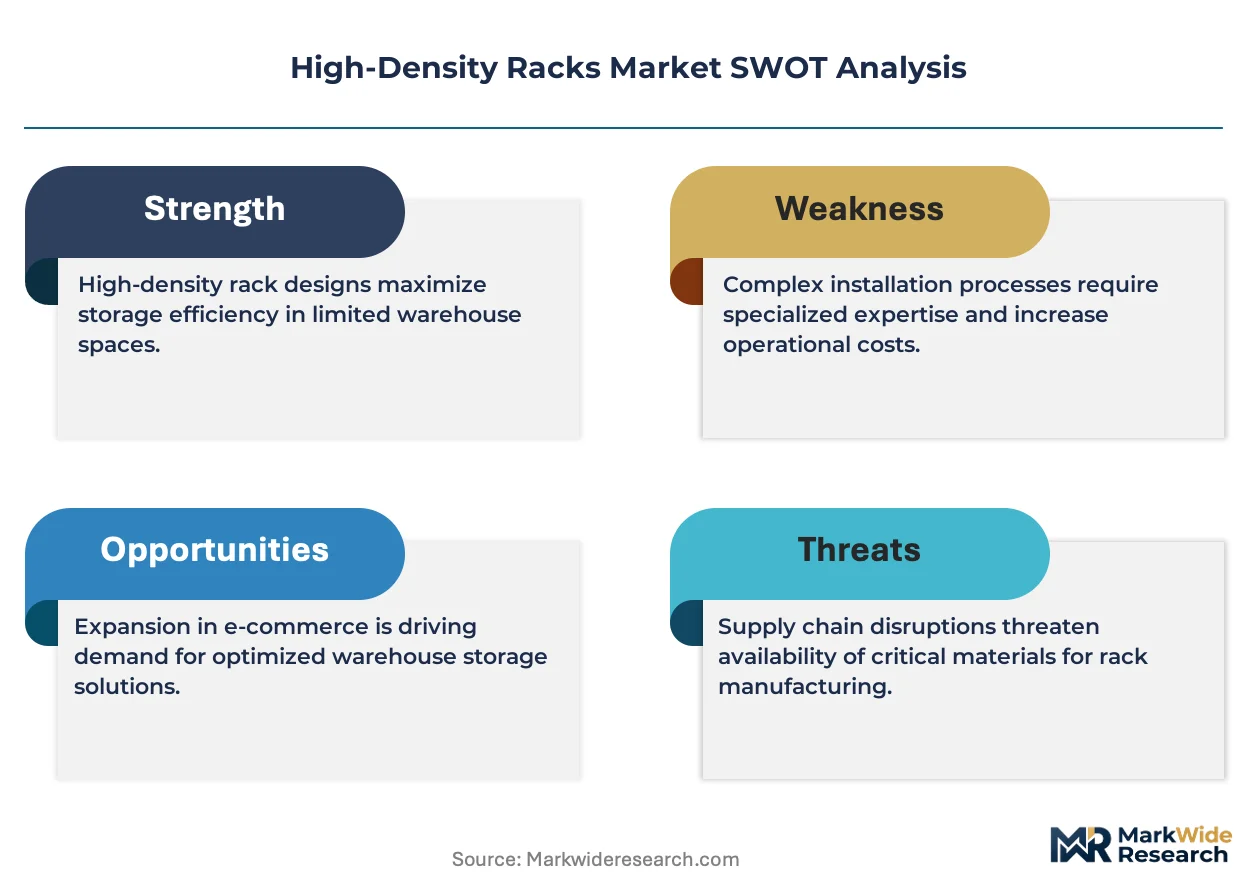
- ASHRAE thermal guidelines:Efficiency thresholds for data center equipment are filtering supplier eligibility and accelerating replacement cycles for legacy air-cooled infrastructure.
- Hyperscale data center buildouts:Cloud operators in the United States, Germany, and China are phasing capacity additions in 100-200 kW modular increments that favor high-density rack procurement.
- Steel precision-welding advances:Cold-rolled steel fabrication improvements enable load-bearing applications above 50 kW with integrated cable management channels.
Market Restraints
- Aluminum supply concentration:Weight-sensitive mobile rack systems depend on aluminum feedstocks vulnerable to price volatility and geographic supply constraints.
- EU energy efficiency code complexity:Evolving certification requirements for electronic equipment enclosures create compliance friction and extend sales cycles.
- Air cooling substitution limits:Legacy thermal management infrastructure in existing facilities constrains rapid adoption of liquid-cooled high-density configurations.
Strategic Opportunities
- China GB standards alignment:NMPA-equivalent structural certifications for electronic equipment enclosures create procurement tailwinds for compliant rack suppliers.
- Edge computing micro-data centers:Distributed infrastructure deployments require compact, high-density rack solutions in underpenetrated secondary cities.
- Power-purchase-agreement financing:Project finance structures backed by renewable energy contracts are unlocking capital deployment for rack infrastructure at new scales.
Industry Challenges
- Thermal-mechanical engineering talent scarcity:Integration of liquid cooling manifolds with precision-welded steel frames requires specialized skills in short supply across the supplier base.
- OSHA installation protocol compliance:Workplace safety rules in the United States and Germany's KBA-adjacent structural load certifications mandate complex access designs that extend deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Density Racks Market |
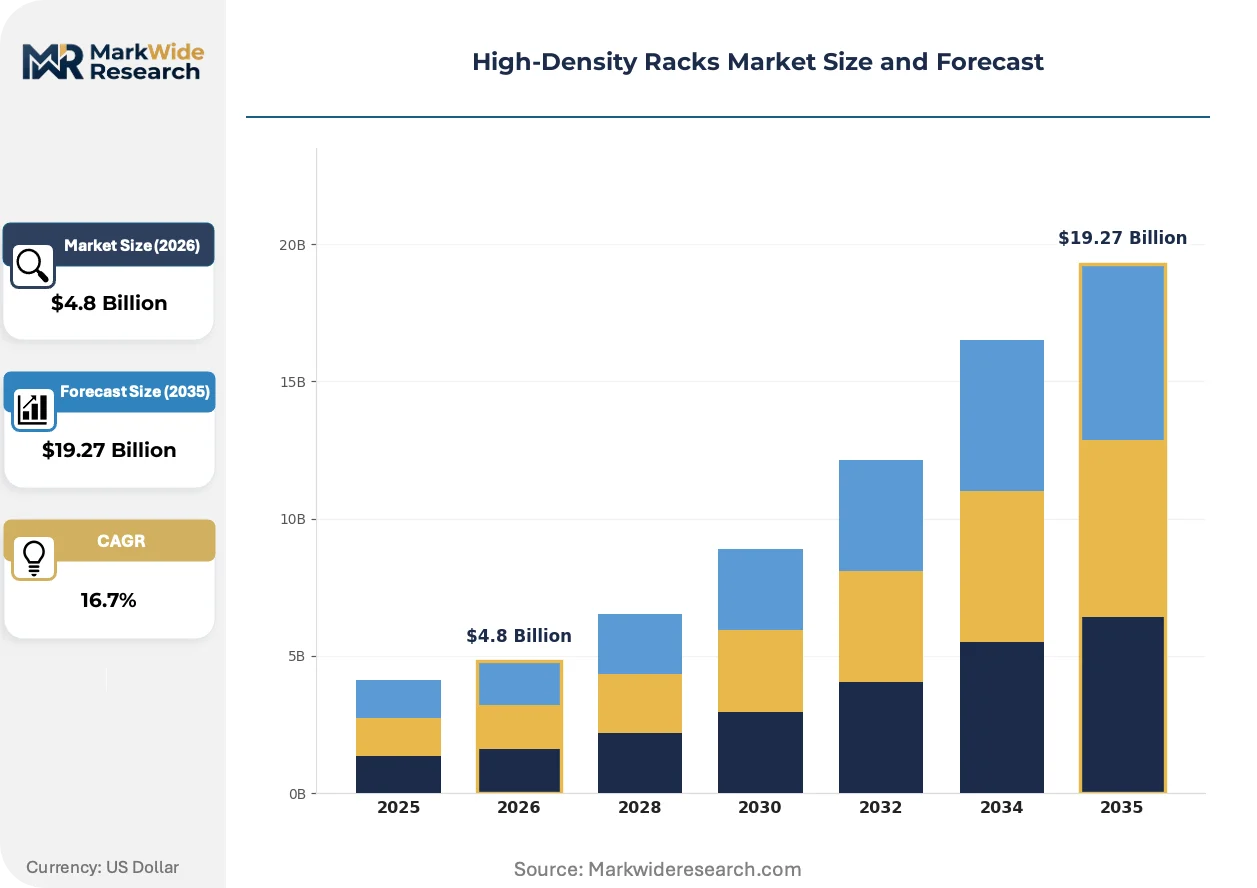
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Static Racks, Mobile Racks, Custom Racks, Modular Racks Industry Vertical: Warehouse & Logistics, Healthcare, Retail, Data Centers Material: Steel, Aluminum, Composite Materials, Plastic Size: Small, Medium, Large, Extra Large |
| Companies Covered | Vertiv Group Corp, Schneider Electric SE, Rittal GmbH & Co. KG, Eaton Corporation, Hewlett Packard Enterprise, Dell Technologies Inc., Emerson Electric Co., Ridg-U-Rak, AK Material Handling Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Density Racks Market Trends and Innovations
Computational fluid dynamics simulation is virtualizing thermal validation workflows, compressing design cycles and reducing physical prototyping requirements for rack-integrated cooling systems.
Immersion cooling dielectric fluids are virtualizing traditional air-handling architectures in high-performance computing environments. Research institutions and AI training facilities are piloting two-phase immersion systems at 100+ kW densities. The technology is virtualizing conventional raised-floor data center designs and enabling rack-level thermal isolation that was previously impractical.
EU F-Gas Regulation phase-down schedules are accelerating adoption of low-global-warming-potential refrigerants in precision cooling systems integrated with high-density racks. Equipment manufacturers must recertify thermal management units under stricter leakage thresholds. German and French data center operators are prioritizing rack suppliers with pre-certified low-GWP cooling compatibility to avoid retrofit liabilities.
Colocation buyers are consolidating vendor relationships around integrated rack-and-cooling packages rather than discrete component procurement. Traditional electrical and mechanical distributors are losing share to direct manufacturer engagement models. This concentration is most visible in Northern Virginia and Frankfurt, where hyperscale-adjacent colocation buildouts favor single-source accountability for thermal-mechanical performance.
High-Density Racks Market Segmentation
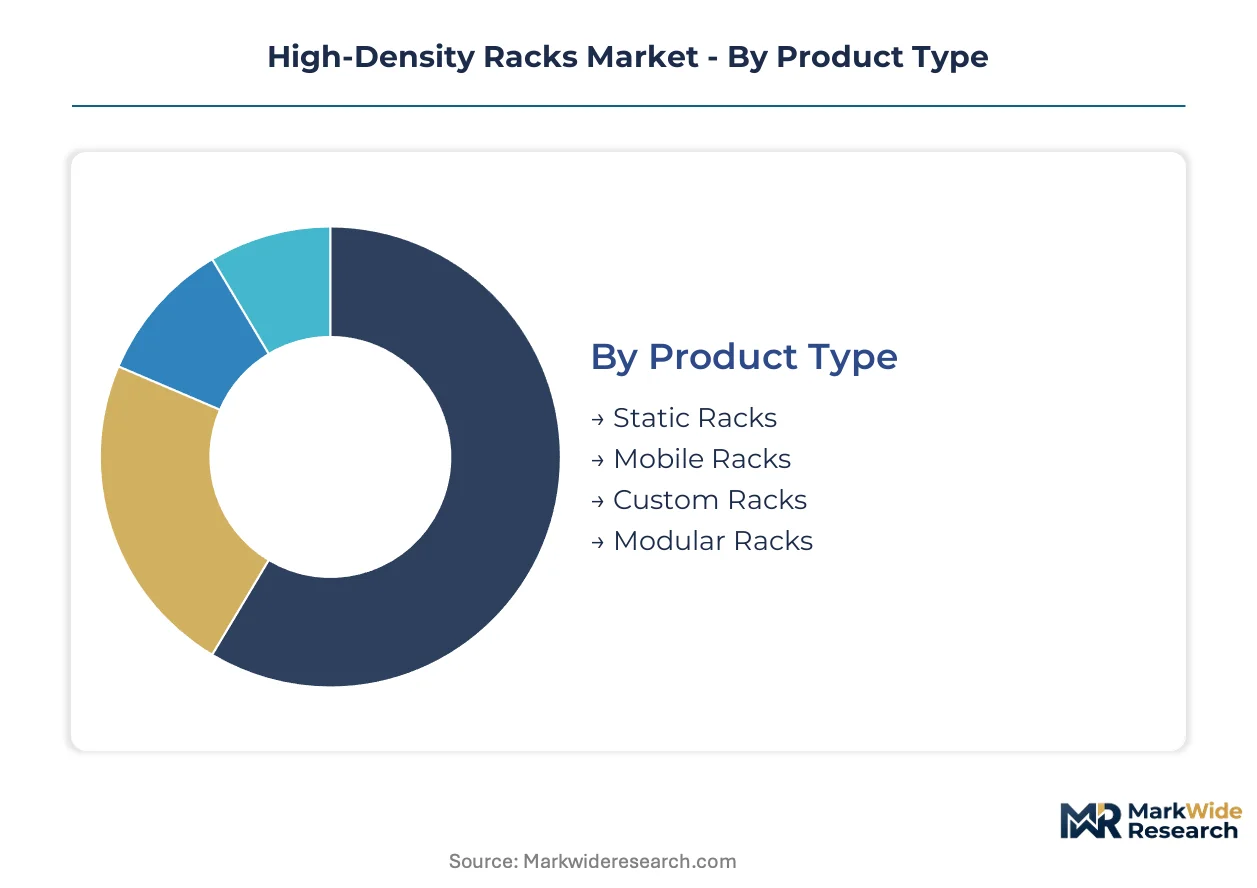
High-density rack procurement diverges sharply by deployment context, with hyperscale data centers demanding thermal-mechanical integration while logistics operators prioritize mobility and reconfiguration speed. Material selection and sizing conventions further fragment supplier strategies across load-bearing requirements and facility constraints.
Product Type:
Mature configurations dominate established verticals, while emerging formats capture liquid-cooled and edge-computing deployments.
- Modular Racks:Precision-welded steel frames with standardized connection interfaces enable 100-200 kW capacity phasing. Cloud operators in Northern Virginia and Frankfurt specify these for hyperscale-adjacent colocation buildouts where thermal-mechanical integration determines procurement.
- Static Racks:Fixed-position cold-rolled steel enclosures engineered for 50+ kW loads with integrated cable management channels. Legacy data centers in Germany and the United States retain these for air-cooled infrastructure refresh cycles constrained by raised-floor configurations.
- Mobile Racks:Aluminum-framed systems with castor mounting for weight-sensitive warehouse and healthcare environments requiring frequent repositioning.
- Custom Racks:Application-specific fabrications for immersion cooling manifolds and non-standard equipment footprints in AI training facilities.
Static racks retain volume leadership; modular configurations hold the steepest expansion curve.
Industry Vertical:
Margin concentration varies dramatically by engineering complexity and thermal integration requirements.
- Data Centers:Purpose-built enclosures supporting liquid cooling distribution at 100+ kW densities with ASHRAE-compliant thermal validation. Operators in the United States, Germany, and China command premium pricing for rack-integrated cooling packages.
- Warehouse & Logistics:High-bay storage systems with seismic-rated steel framing for automated retrieval environments. Distribution hubs in Germany's Rhine-Ruhr corridor specify KBA-adjacent structural load certifications.
- Healthcare:Mobile aluminum racks for medical equipment mobility with OSHA-mandated access clearances in United States hospital networks.
- Retail:Compact static configurations for backroom inventory systems with rapid deployment requirements in urban store formats.
Data centers capture the highest margin pool; warehouse and logistics applications deliver the most consistent volume base.
Material:
Load-bearing thresholds and weight sensitivity drive divergent supply chain strategies across fabrication methods.
- Steel:Cold-rolled precision-welded frames dominate 50+ kW applications with integrated cable channels and seismic bracing. Fabricators serving hyperscale operators in China align with GB standards for electronic equipment enclosures.
- Aluminum:Extruded and cast components for mobile systems under 30 kW where weight reduction enables manual repositioning. Supply concentration in specific geographic regions creates price volatility exposure.
- Composite Materials:Fiber-reinforced polymer panels for electromagnetic interference shielding in specialized computing environments.
- Plastic:Injection-molded components for lightweight non-structural elements and cable management accessories.
Steel commands the revenue base; aluminum applications are expanding most quickly in edge-computing mobile deployments.
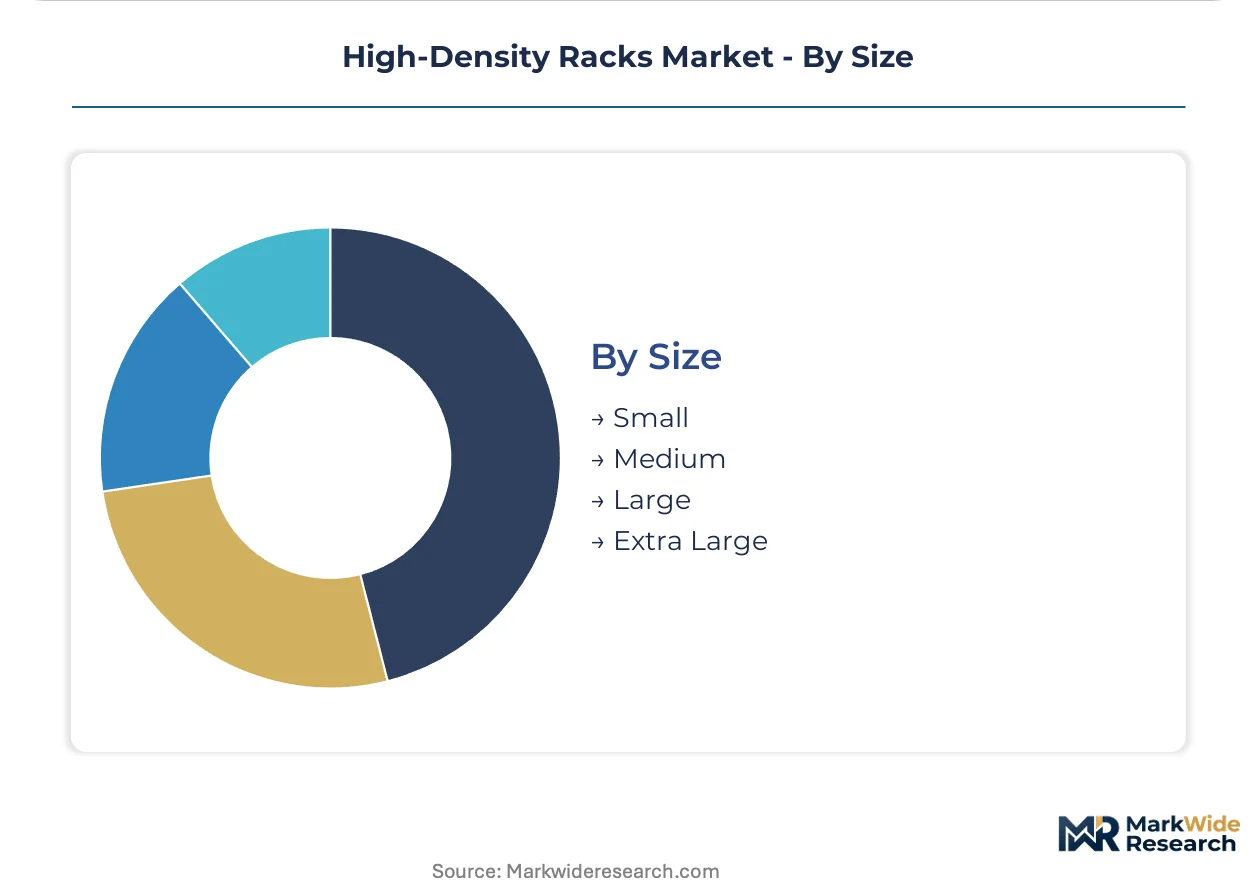
Size:
Facility footprint constraints and power density trajectories reshape dimensional preferences across installation types.
- Large:42U to 52U enclosures for standard hyperscale cabinet footprints with liquid cooling manifold integration. Colocation operators in Northern Virginia specify these for 100+ kW AI training clusters.
- Medium:24U to 40U configurations for enterprise data centers and regional cloud nodes with 30-50 kW air-cooled densities.
- Small:Sub-24U compact enclosures for edge computing micro-data centers in secondary cities with constrained floor space.
- Extra Large:Custom multi-cabinet integrated frames for immersion cooling tanks and high-performance computing arrays.
Large sizes anchor procurement volumes; small configurations are gaining share fastest in distributed infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in high-density rack infrastructure tilt toward import dependency in European and Asian markets, while the United States sustains near-balanced equipment trade through captive manufacturing clusters. Domestic fabrication capacity in China and Germany absorbs regional demand, compressing cross-border shipment volumes.
United States
Hyperscale cloud operators in Northern Virginia and Dallas-Fort Worth drive procurement volumes for 100+ kW liquid-cooled cabinets. OSHA workplace safety rules mandate complex access clearances that extend deployment timelines. Ashburn's Data Center Alley hosts the densest concentration of colocation buildouts, with operators consolidating vendor relationships around integrated rack-and-cooling packages.
Germany
Frankfurt's banking and colocation sectors demand KBA-adjacent structural load certifications for seismic-rated steel framing. The EU F-Gas Regulation phase-down accelerates supplier recertification under stricter refrigerant leakage thresholds. The Rhine-Ruhr corridor anchors warehouse and logistics applications, with distribution hubs specifying precision-welded frames for automated retrieval environments.
China
GB standards for electronic equipment enclosures filter supplier eligibility for domestic hyperscale operators in Beijing and Shanghai. NMPA-equivalent structural certifications create procurement tailwinds for compliant fabricators. The Yangtze River Delta cluster concentrates manufacturing capacity, with local producers aligning cold-rolled steel fabrication to dual carbon goals.
Japan
METI efficiency guidelines for data center equipment compress replacement cycles for legacy air-cooled infrastructure. JIS standards govern precision-welded frame specifications for high-load applications. Tokyo and Osaka metro areas host AI training facilities piloting two-phase immersion cooling at 100+ kW densities.
United Kingdom
CSRD disclosure requirements reshape procurement criteria for rack-integrated cooling packages in London and Slough colocation markets. The country's national building regulator mandates structural load documentation for seismic-rated installations. Thames Valley data center clusters favor modular configurations enabling 100-200 kW capacity phasing.
High-Density Racks Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in precision-welded steel fabrication and thermal manifold production. Market structure consolidates around three to five vertically integrated players capturing premium positions in liquid-cooled deployments, while regional fabricators serve price-sensitive static rack segments. Archetypes span thermal-mechanical integrators, electrical distribution specialists, and modular factory operators. Competitive moves center on strategic partnerships for cooling technology licensing and geographic expansion through localized fabrication facilities.
Among diversified electrical and infrastructure conglomerates, Schneider Electric SE and Eaton Corporation exemplify platform-scale positioning through broad geographic coverage and integrated system portfolios. Vertiv Group Corp anchors the thermal-mechanical specialist tier, representing concentrated exposure to liquid-cooled rack architectures. Rittal GmbH & Co. KG occupies a fabrication-focused position within German engineering traditions. These three entities collectively illustrate the competitive spectrum spanning electrical integration, thermal management, and precision manufacturing.
| Leading Market Players |
|---|
| Vertiv Group Corp |
| Schneider Electric SE |
| Rittal GmbH & Co. KG |
| Eaton Corporation |
| Hewlett Packard Enterprise |
| Dell Technologies Inc. |
| Emerson Electric Co. |
| Ridg-U-Rak |
| AK Material Handling Systems |
| Others |
Pricing and Supply Chain Analysis
Cold-rolled steel fabrication clusters in China's Yangtze River Delta concentrate precision-welding capacity for 50+ kW load-bearing frames, anchoring margin capture by tier-one thermal-mechanical integrators serving hyperscale operators in Northern Virginia and Frankfurt.
Pricing Analysis
Hyperscale data center operators anchor project-based contract pricing for liquid-cooled rack systems, with thermal-mechanical integration certification and ASHRAE compliance tiering quotations. Cost compression in air-cooled static rack segments is intensifying because aluminum supply volatility feeds input uncertainty. Colocation buyers in Germany demonstrate least price sensitivity due to KBA-adjacent structural certification requirements, while warehouse operators in secondary logistics corridors exhibit highest sensitivity to freight-adjusted delivered pricing.
Supply Chain Analysis
Aluminum feedstock sourcing centers on Australian bauxite refining and Chinese smelter output, with cold-rolled steel plate drawing from integrated mills in China, Germany, and the United States. Precision-welded frame production rests on robotic fabrication cells and thermal manifold CNC machining. Single-source vulnerability concentrates in liquid-cooling component supply from German and Japanese specialist tiers. Distribution runs through direct manufacturer engagement for hyperscale contracts, with electrical distributors retaining share in sub-50 kW enterprise refresh cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermal-mechanical engineering talent capable of integrating liquid cooling manifolds with precision-welded steel frames remains scarce across the supplier base, constraining expansion velocity for rack manufacturers attempting to capture hyperscale procurement volumes.
For Market Incumbents: Build captive thermal validation capabilities through computational fluid dynamics simulation centers to accelerate design cycles for 100+ kW liquid-cooled deployments. Vertiv Group Corp and Schneider Electric SE already anchor premium positions via integrated rack-and-cooling packages; challengers must match this convergence or cede Northern Virginia and Frankfurt colocation buildouts. Certification investment in China's GB standards and EU F-Gas Regulation compliance creates procurement gatekeeping power against unqualified fabricators. For New Entrants and Emerging Players: Edge computing micro-data centers in underpenetrated secondary cities across Southeast Asia and Eastern Europe represent the most penetrable entry point for compact sub-24U rack configurations. Mobile aluminum rack systems for healthcare environments in the United States offer a second white-space channel given OSHA-mandated access clearance requirements that favor nimble engineering teams. Direct sales engagement with regional cloud operators bypasses entrenched electrical distributor relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid-cooled rack manufacturing due to precision-welding automation and thermal validation equipment requirements. Long-term viability over the coming decade favors platform integrators with demonstrated hyperscale operator relationships rather than component fabricators lacking thermal-mechanical convergence capabilities. The signal to watch is power-purchase-agreement financing volume for data center infrastructure, as renewable-backed project finance structures indicate committed deployment pipelines for high-density rack procurement. Cross-checking against hyperscaler capex disclosure patterns is advised before commitment-grade decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Thermal-Mechanical Integration Partnership | Liquid cooling manifold co-development with Vertiv Group Corp anchors hyperscale eligibility in Northern Virginia. |
| GB Standards Certification Investment | NMPA-equivalent structural compliance unlocks procurement access to Beijing and Shanghai hyperscale operators. |
| Computational Fluid Dynamics Capability Buildout | Virtual thermal validation compresses design cycles for ASHRAE-compliant 100+ kW rack systems. |
| Localized Precision-Welding Fabrication | Regional steel frame production in Germany satisfies KBA-adjacent load certification requirements for Frankfurt colocation. |
| Low-GWP Refrigerant Pre-Certification | EU F-Gas Regulation alignment avoids retrofit liabilities for French and German data center operators. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, customs and trade databases, ASHRAE technical standards documentation, and hyperscaler capital expenditure disclosures. Data center engineering directors, thermal management procurement leads at colocation operators, precision-welding fabrication plant managers, and electrical distributor channel heads contributed structured interviews. Bottom-up rack shipment tallies by configuration and material were triangulated against top-down infrastructure investment flow analysis.
Forecast inputs include modeled projections across product type, industry vertical, material composition, and dimensional sizing categories, with additional segmentation by thermal management integration level. CAGRs were derived from installed base replacement cycle analysis and capacity phasing patterns at hyperscale facilities. Hyperscale operator buildout pipelines, EU energy efficiency code evolution, and China GB standards adoption curves served as industry-specific demand drivers throughout the projection horizon.
Practitioners should monitor aluminum price volatility, EU F-Gas Regulation recertification timelines, and OSHA installation protocol amendments for early signals requiring forecast revision. Cross-checking against hyperscaler announced capacity expansion commitments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Portable Forklift Ramps Market
Material Handling Equipment
Reinforced Ultrafine Mill Market
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Industrial Carts Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Dust Extractors Market
Material Handling Equipment
Metal Plain Washer Market
Material Handling Equipment
Helical Gear Market
Material Handling Equipment
Port Material Handling Equipment Vehicle Market
Material Handling Equipment
Water Hose Market
Material Handling Equipment
Mining Hoses Market
Material Handling Equipment
North America Industrial Duct for Dust Collection Market
Material Handling Equipment
Material Handling Equipment Tires Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
Wire Pulling and Tensioning Market