
 Food Grade Calcium Lactate Market | 2026-2036
Food Grade Calcium Lactate Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Calcium Lactate Market Insights
Asset-light toll manufacturing and third-party fermentation leasing is narrowing the capital barrier for mid-tier entrants in food-grade mineral salts. Jungbunzlauer Suisse AG leverages its Swiss fermentation heritage to sustain premium positioning across European nutraceutical channels. Henan Jindan Lactic Acid Technology Co., Ltd. anchors cost-competitive powder output through captive corn starch feedstock in China's Henan province. Corbion N.V. differentiates via biotechnology leadership in controlled-purity lactate strains for infant formula-grade specifications.
Food grade calcium lactate is a white crystalline salt produced by neutralizing lactic acid with calcium carbonate or hydroxide, yielding a compound with minimum 98% purity and specified heavy metal limits under food additive codex standards. It functions primarily as a calcium fortifier, acidity regulator, and firming agent in processed foods, beverages, and dietary supplements. Powder formulations dominate current volume owing to stability in dry blending operations and extended shelf compatibility with infant cereals and bakery premixes. Beverage stabilization represents the fastest-expanding application segment as sparkling water and plant milk brands incorporate calcium lactate for suspension uniformity and mineral content claims. Direct sales channels capture the highest margin pool by bypassing distributor markups for large-scale food manufacturers with recurring bulk contracts.
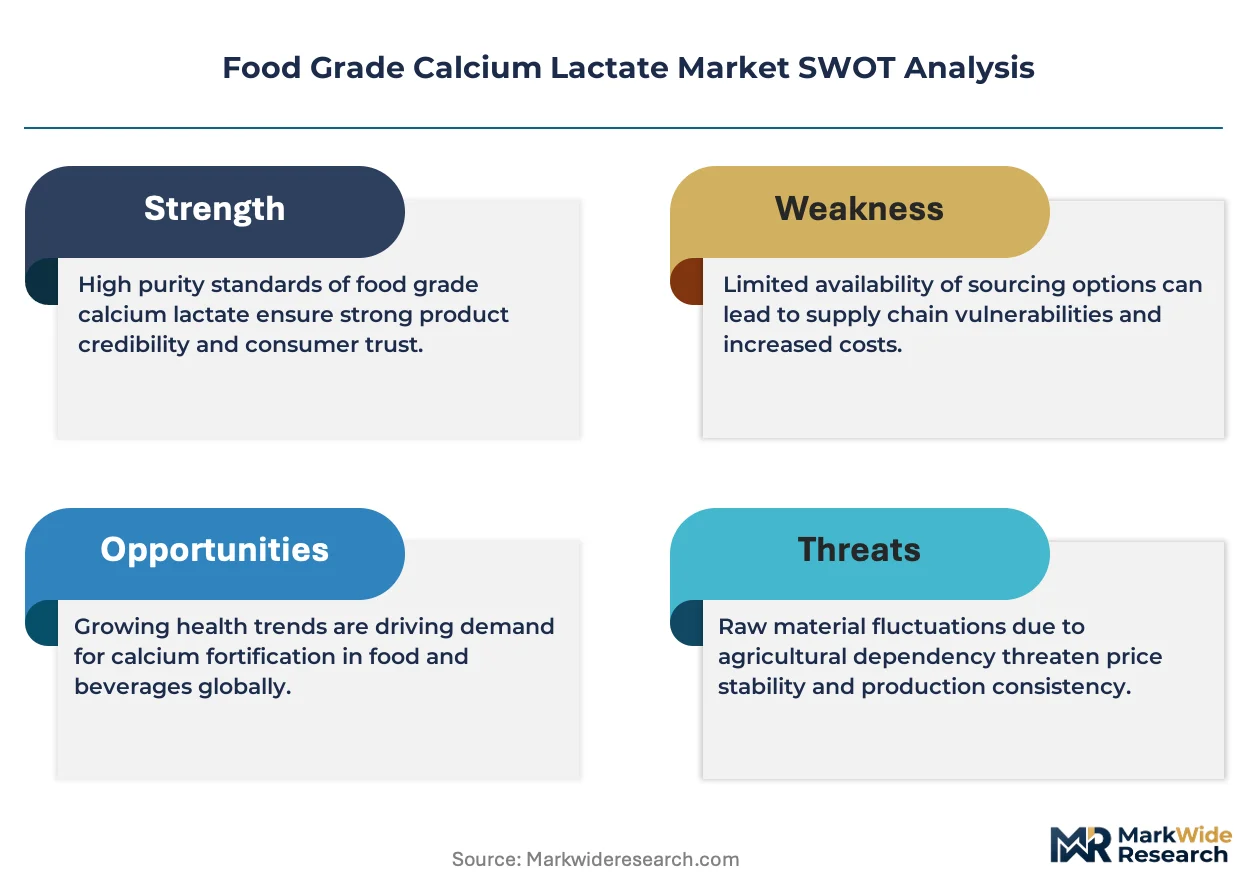
FDA food additive regulations under 21 CFR 184.1207 and EFSA's re-evaluation of calcium additives under Regulation (EU) No 257/2010 shape purity thresholds and label disclosure requirements for calcium lactate in fortified foods. China's SAMR enforces GB 25555-2010 standards for food-grade calcium lactate production licensing, creating compliance differentiation between domestic and import suppliers. Stakeholders must monitor evolving infant formula mineral specifications across Codex Alimentarius, EFSA, and China's NMPA, as tightening purity benchmarks will determine which fermentation-based producers can maintain market access without costly process revalidation.
Market Dynamics
Fermentation capacity concentration in China's corn-belt provinces is tightening feedstock access for mid-tier calcium lactate refiners, forcing capital-light entrants toward toll-manufacturing partnerships or third-party fermentation leasing arrangements.
Growth Catalysts
- EFSA Purity Re-evaluation:Tightening calcium additive specifications under Regulation (EU) No 257/2010 are filtering out sub-scale producers and consolidating volume with codex-compliant suppliers capable of infant-grade certification.
- Sparkling Water Fortification:Beverage stabilization applications are absorbing incremental powder output as European and Asian brands incorporate calcium lactate for suspension uniformity in carbonated mineral waters.
- Shandong Fermentation Clusters:Downstream refiners in this Chinese province benefit from captive lactic acid supply, reducing logistics costs and enabling just-in-time delivery to coastal export terminals.
Market Restraints
- Corn Starch Price Volatility:Feedstock cost swings in North American and Chinese grain markets compress margin predictability for fermentation-dependent producers without backward integration into starch processing.
- Heavy Metal Purity Ceilings:China's GB 25555-2010 and FDA's 21 CFR 184.1207 impose stringent lead and arsenic limits that disqualify legacy thermal precipitation methods still operational in certain South Asian facilities.
- Citrate Substitution:Calcium citrate maintains stronger positioning in acidic beverage applications where flavor neutrality outweighs lactate's solubility advantage, capping share in certain fortification segments.
Strategic Opportunities
- India Nutraceutical Channels:FSSAI's evolving food additive schedules are opening import pathways for codex-certified calcium lactate as domestic dietary supplement formulators seek alternatives to carbonate-based fortification.
- Plant Milk Stabilization:Oat and pea protein beverage manufacturers are trialing calcium lactate for mineral suspension and protein interaction control, creating application white space beyond traditional dairy analogs.
- Direct-to-Manufacturer Distribution:Large-scale bakery premix and infant cereal producers are consolidating procurement through volume contracts that bypass regional distributor markups, favoring suppliers with dedicated technical service teams.
Industry Challenges
- Fermentation Strain Validation:Producers must revalidate controlled-purity lactobacillus cultures for each infant formula-grade certification renewal, extending compliance timelines and freezing process modifications.
- Cross-Contamination Controls:Multi-product facilities face capital-intensive clean-room segregation requirements when alternating between food-grade and pharmaceutical-grade lactate runs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Calcium Lactate Market |
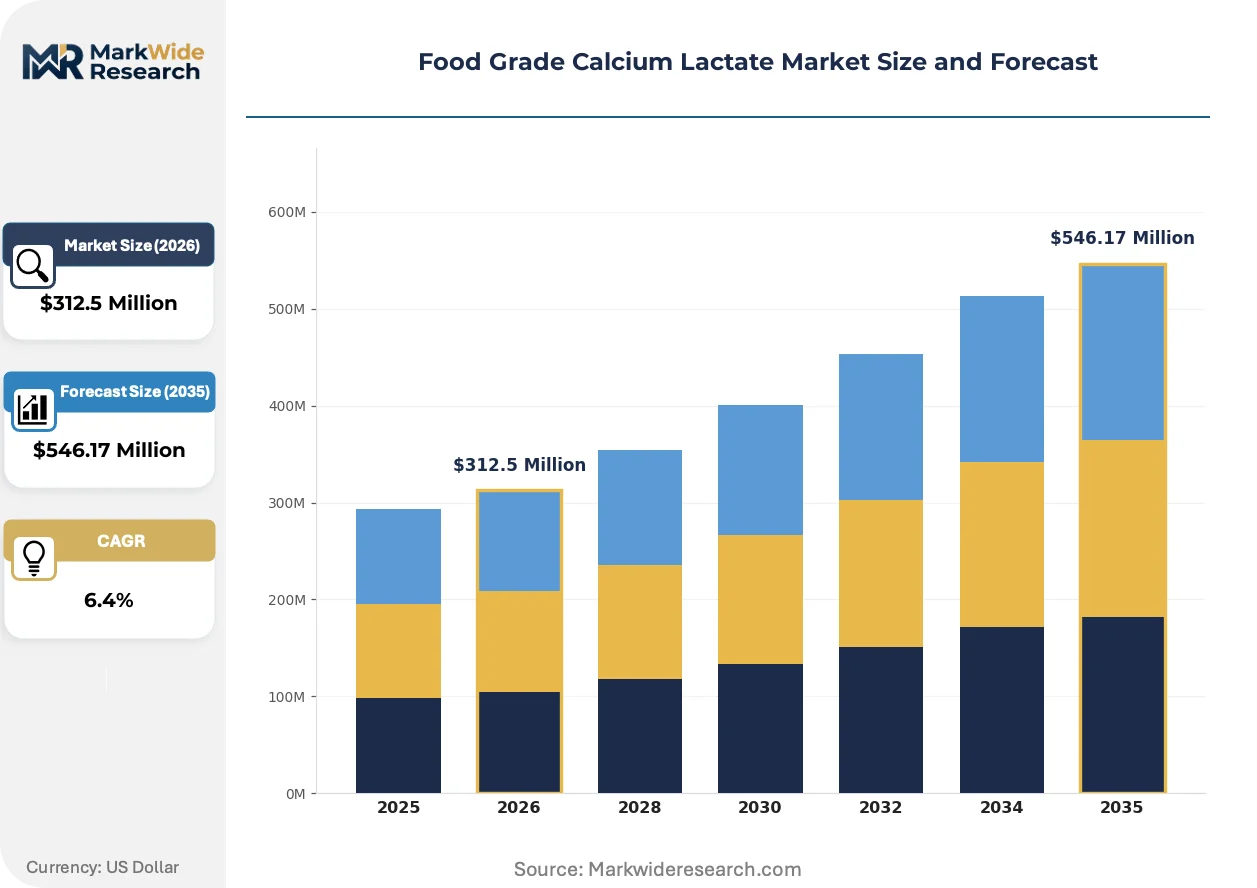
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid, Tablets Application: Food Fortification, Dietary Supplements, Food Preservation, Beverage Stabilization End User: Food Manufacturers, Nutraceutical Companies, Beverage Producers, Health-Conscious Consumers Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Corbion N.V., Jungbunzlauer Suisse AG, Henan Jindan Lactic Acid Technology Co., Ltd., Musashino Chemical Laboratory, Ltd., Alfa Aesar, American Elements, Gadot Biochemical Industries Ltd., Qingdao Health Food Co., Ltd., Shandong Parkson Biotechnology Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Calcium Lactate Market Trends and Innovations
Biotechnology advances in strain engineering and downstream purification are compressing quality variance between commodity and premium-grade calcium lactate outputs.
Continuous fermentation systems with real-time metabolite monitoring are hybridizing batch consistency with continuous throughput economics. Powder blenders in North American nutraceutical channels are adopting these systems to reduce lot-to-lot variation in mineral fortification premixes. The technology is hybridizing capital efficiency benchmarks previously separating artisan-scale and industrial-scale suppliers.
China's SAMR is tightening enforcement of GB 25555-2010 production licensing through unannounced facility audits and third-party laboratory verification of heavy metal claims. Domestic refiners face temporary suspension risks for documentation gaps, accelerating investment in in-house inductively coupled plasma mass spectrometry capabilities. Import-dependent Southeast Asian formulators are diversifying supplier bases to reduce single-country regulatory exposure.
Long-term offtake agreements with fixed-price escalators are displacing spot-market purchasing among multinational beverage and cereal manufacturers. Procurement teams at European and North American food conglomerates are consolidating vendor lists to three to five qualified suppliers with dual-source geographic redundancy. This pattern is most pronounced in infant nutrition verticals where input traceability requirements exceed standard food-grade protocols.
Food Grade Calcium Lactate Market Segmentation
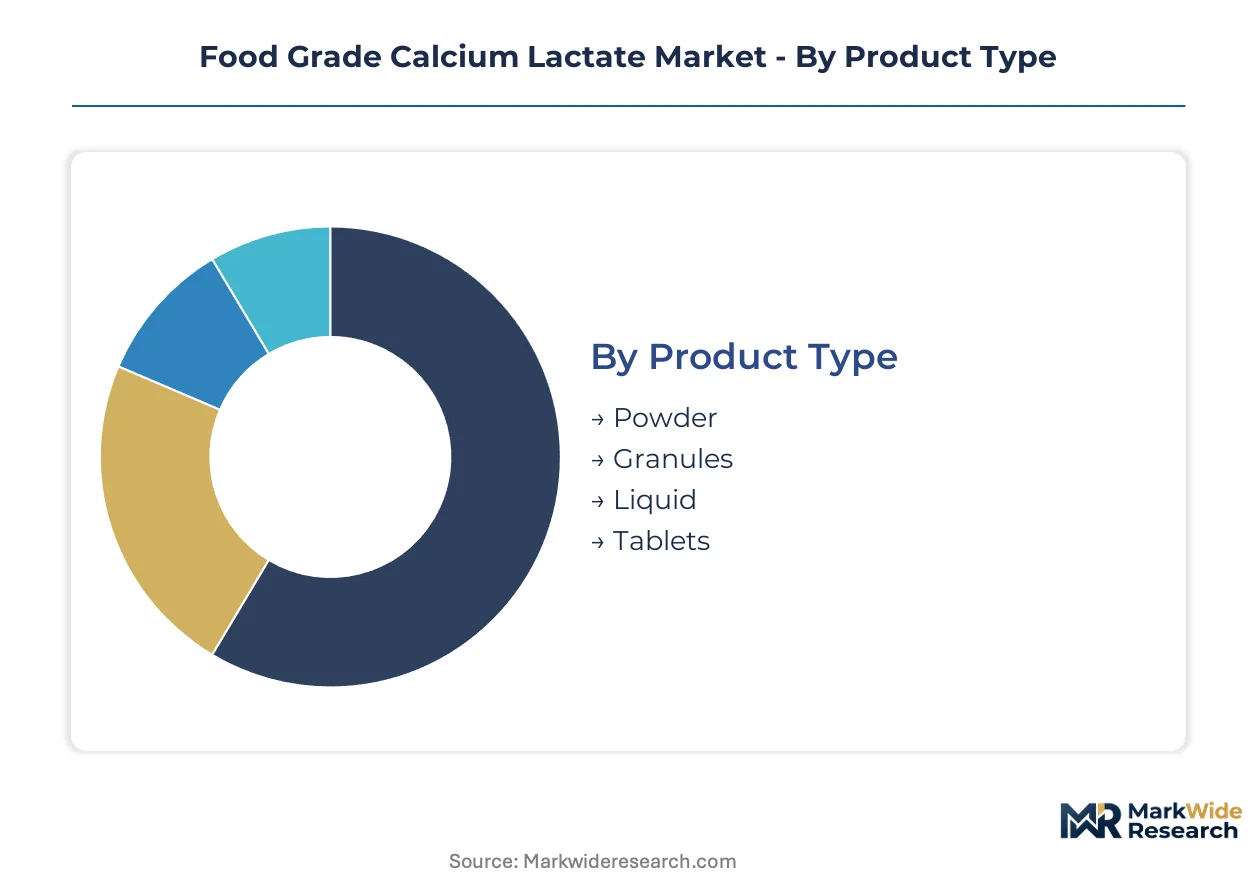
Calcium lactate specifications diverge sharply across end-use applications, with infant formula certification demanding fermentation strain traceability that commodity food grades bypass entirely. Powder and granule formats dominate industrial procurement, while liquid concentrates serve beverage stabilization where dissolution speed outweighs shelf stability concerns.
Product Type:
Mature dry formats anchor volume, yet liquid concentrates are accelerating as carbonated beverage brands prioritize cold-chain distribution economics.
- Powder:Crystalline particles with 98% minimum purity enable dry-blending compatibility with infant cereals and bakery premixes. China's Shandong province refiners supply coastal export terminals through just-in-time logistics networks serving multinational cereal manufacturers. Powder retains volume leadership; liquid holds the steepest expansion curve.
- Granules:Agglomerated particles reduce dusting during high-speed packaging lines and improve flowability in automated dosing equipment. European nutraceutical contract manufacturers specify granule grades for tablet compression operations where particle size distribution directly impacts dissolution profiles.
- Liquid:Aqueous solutions at 20-30% concentration eliminate hydration steps in ready-to-drink formulation. Oat and pea protein beverage trials in North American pilot facilities are validating suspension uniformity performance against citrate alternatives.
- Tablets:Direct-compression formats with excipient matrices target health-conscious consumer self-selection in pharmacy and specialty retail channels.
Powder commands the largest procurement volumes; liquid formats are climbing the fastest as beverage applications expand.
Application:
Cost tier stratification separates infant-grade certification premiums from commodity food additive pricing, with beverage stabilization occupying the middle ground.
- Food Fortification:Calcium enrichment of flour, cereals, and dairy analogs requires codex-compliant heavy metal thresholds under FDA 21 CFR 184.1207. India's FSSAI schedule revisions are opening import pathways for certified lactate as domestic formulators seek alternatives to carbonate-based mineral sources.
- Dietary Supplements:Capsule and tablet formulations demand USP-grade specifications with documented fermentation strain genealogy. EFSA's re-evaluation under Regulation (EU) No 257/2010 is filtering sub-scale producers toward consolidated codex-compliant supply bases.
- Food Preservation:Acidity regulation and firming functions in processed vegetables and pickled products utilize technical-grade specifications with relaxed purity ceilings compared to infant nutrition applications.
- Beverage Stabilization:Suspension uniformity in carbonated mineral waters and plant milks leverages lactate solubility advantages over citrate in neutral pH formulations.
Food fortification maintains the broadest installed base; beverage stabilization is gaining share fastest as sparkling water brands proliferate.
End User:
Customer type determines procurement modality, with multinational food manufacturers consolidating vendor lists while nutraceutical specialists prioritize technical service depth.
- Food Manufacturers:Large-scale bakery premix and cereal producers negotiate direct volume contracts bypassing distributor markups, requiring suppliers with dedicated formulation support teams.
- Nutraceutical Companies:Dietary supplement formulators specify infant-grade certification for mineral premixes even when final products target adult consumption, anticipating regulatory trajectory tightening.
- Beverage Producers:Carbonated water and plant milk brands trial calcium lactate for protein interaction control in oat and pea protein matrices, creating specification white space beyond traditional dairy analogs.
- Health-Conscious Consumers:Direct-to-consumer tablet purchases through online retail channels represent marginal volume but carry premium pricing multiples over industrial procurement.
Food manufacturers represent the largest procurement segment; beverage producers are expanding most quickly as fortification extends into novel categories.
Distribution Channel:
Margin structure varies dramatically across channels, with direct sales capturing the highest value pool through technical service bundling.
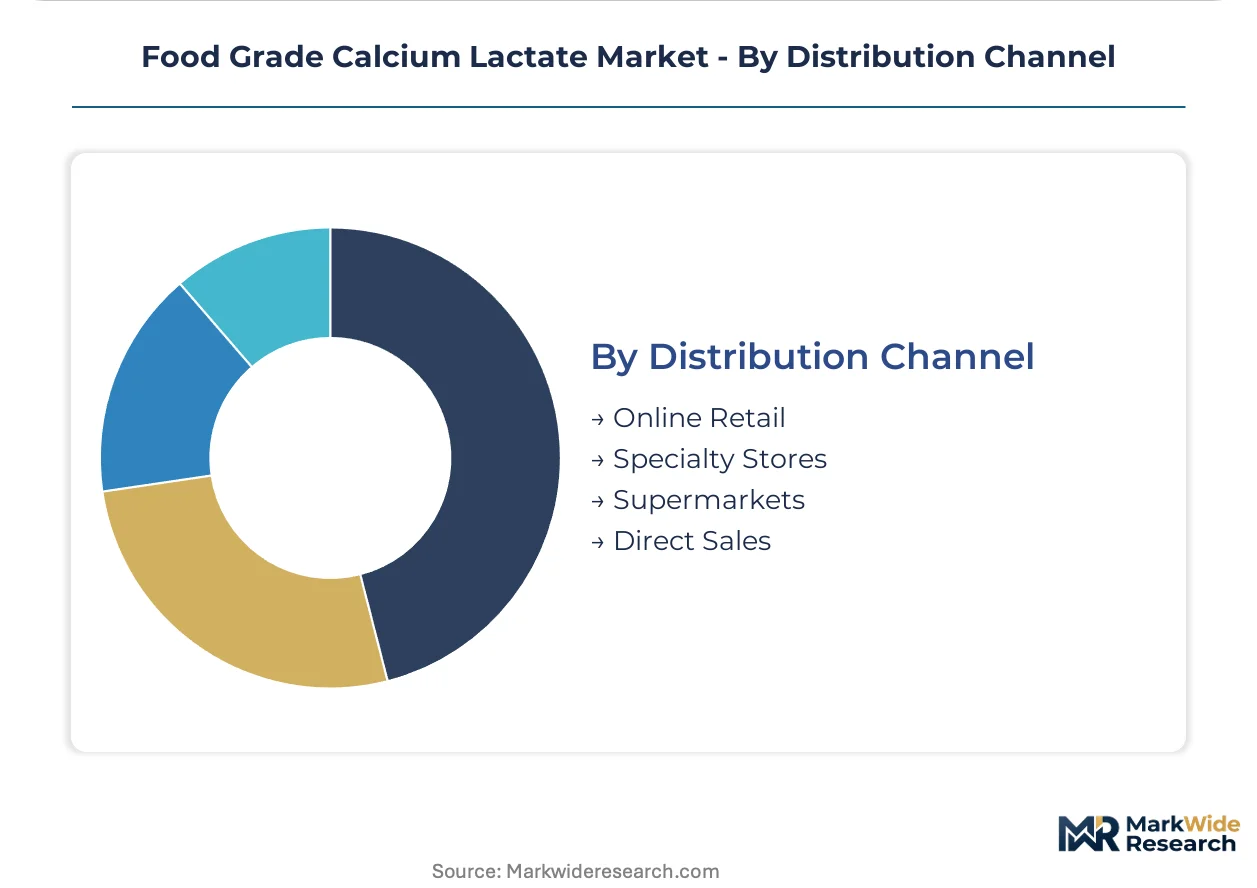
- Direct Sales:Volume contracts with fixed-price escalators displace spot purchasing among multinational manufacturers, consolidating procurement through three to five qualified suppliers with geographic redundancy.
- Online Retail:E-commerce platforms serve health-conscious consumers and small-scale nutraceutical formulators with minimum order quantities below distributor thresholds.
- Specialty Stores:Pharmacy and health food retail channels stock tablet formats targeting self-directed mineral supplementation with premium positioning.
- Supermarkets:Mass retail distribution of fortified food products occurs indirectly through manufacturer-branded finished goods rather than ingredient sales.
Direct sales dominate value capture; online retail is expanding most quickly as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage manufacturers in Germany and China drive the highest contract volumes for calcium-fortified formulations, while infant nutrition processors in Switzerland and the Netherlands specify the strictest purity certifications.
China
Shandong province fermentation clusters supply captive lactic acid to downstream calcium lactate refiners serving coastal export terminals. SAMR enforces GB 25555-2010 through unannounced facility audits and third-party laboratory verification. Henan province corn starch processors anchor cost-competitive powder output for domestic bakery premix manufacturers.
Germany
Sparkling water brands in Bavaria and North Rhine-Westphalia trial calcium lactate for suspension uniformity in carbonated mineral formulations. EFSA's re-evaluation under Regulation (EU) No 257/2010 filters sub-scale producers toward consolidated codex-compliant supply bases. The Baden-Württemberg nutraceutical corridor demands infant-grade certification for mineral premixes targeting adult dietary supplements.
United States
North American nutraceutical contract manufacturers specify USP-grade powder with documented fermentation strain genealogy for tablet compression operations. FDA regulations under 21 CFR 184.1207 shape purity thresholds and label disclosure requirements for fortified foods. Midwest corn-belt starch processors face margin compression from feedstock price volatility without backward integration.
Switzerland
Swiss fermentation heritage sustains premium positioning across European nutraceutical channels demanding controlled-purity lactate strains. Swissmedic oversight aligns with EFSA benchmarks for infant formula-grade specifications. Basel-region technical service teams support direct volume contracts with multinational cereal manufacturers.
India
Dietary supplement formulators in Maharashtra and Gujarat seek alternatives to carbonate-based fortification as FSSAI schedules evolve. Central drug standard control protocols open import pathways for codex-certified calcium lactate. Andhra Pradesh toll-manufacturing partnerships narrow capital barriers for mid-tier mineral salt entrants.
Food Grade Calcium Lactate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Consolidation pressures favor codex-compliant suppliers capable of infant-grade certification as EFSA and FDA purity thresholds tighten. Strategic archetypes include fermentation-heritage premium positioned players, corn-belt cost-optimized volume producers, and biotechnology-differentiated purity specialists. Dominant competitive moves center on long-term offtake agreements with fixed-price escalators and toll-manufacturing partnerships that reduce capital barriers for mid-tier entrants.
Within the fermentation-heritage tier, Jungbunzlauer Suisse AG exemplifies Swiss premium positioning across European nutraceutical channels. Henan Jindan Lactic Acid Technology Co., Ltd. occupies the cost-optimized volume archetype through captive corn starch feedstock integration. Corbion N.V. represents biotechnology-differentiated purity leadership in controlled-purity lactate strains for infant formula-grade specifications.
| Leading Market Players |
|---|
| Corbion N.V. |
| Jungbunzlauer Suisse AG |
| Henan Jindan Lactic Acid Technology Co., Ltd. |
| Musashino Chemical Laboratory, Ltd. |
| Alfa Aesar |
| American Elements |
| Gadot Biochemical Industries Ltd. |
| Qingdao Health Food Co., Ltd. |
| Shandong Parkson Biotechnology Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Shandong province fermentation clusters concentrate lactic acid supply capacity, translating upstream feedstock control into pricing leverage for downstream calcium lactate refiners serving coastal export terminals. Corn starch cost pass-through mechanisms in China's corn-belt provinces ripple through contract structures, while EFSA purity re-evaluations filter sub-scale competitors and consolidate margin pools with codex-compliant suppliers.
Pricing Analysis
Cost-plus contracts with corn starch indexation dominate procurement between multinational food manufacturers and fermentation-based suppliers. Three-tier pricing structure across infant-grade certification, standard food-grade, and technical specifications separates premium strain-traceable output from commodity powder. Pricing pressure stems from citrate substitution in acidic beverage applications where flavor neutrality outweighs lactate solubility advantages. Beverage producers exhibit highest price sensitivity due to formulation cost targets, while infant nutrition processors accept premium positioning for certification security.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Shandong refiners support working capital for mid-tier toll-manufacturing partners lacking backward integration. Production gravity centers on China, Switzerland, and the Netherlands, with raw material dependencies spanning corn starch, calcium carbonate, and controlled-purity lactobacillus cultures. Single-source vulnerability concentrates in China's corn-belt provinces where feedstock access tightening threatens mid-tier entrants. Distribution runs through direct volume contracts with multinational cereal and beverage manufacturers, bypassing regional distributor markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where fermentation strain certification interoperability across EFSA, FDA, and China's SAMR creates winner-take-most dynamics for suppliers achieving multi-jurisdictional infant-grade approval.
For Market Incumbents: Insulate certification moats by accelerating in-house inductively coupled plasma mass spectrometry capabilities ahead of SAMR's unannounced audit expansion. Deepen captive corn starch processing in Henan province to compress feedstock cost volatility that threatens margin predictability. Jungbunzlauer's Swiss fermentation heritage and Corbion's biotechnology leadership demonstrate how controlled-purity strain portfolios defend against citrate substitution in beverage applications. For New Entrants and Emerging Players: Build out toll-manufacturing partnerships with Shandong fermentation clusters to narrow capital barriers without owning strain validation infrastructure. India's FSSAI schedule evolution presents the most penetrable geography as dietary supplement formulators seek carbonate alternatives. Target direct-to-manufacturer distribution with dedicated technical service teams for oat and pea protein beverage trials, bypassing established distributor relationships. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because EFSA and FDA purity threshold tightening will filter sub-scale producers toward codex-compliant supply bases with infant-grade certification. Acquisition targets should display dual-source geographic redundancy and existing long-term offtake agreements with fixed-price escalators. The signal to watch is SAMR enforcement intensity through third-party laboratory verification mandates, which accelerates capital requirements for in-house testing capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Starch Processing | Captive feedstock supply in China's corn-belt provinces compresses margin volatility for fermentation-dependent producers. |
| Infant-Grade Certification Investment | Multi-jurisdictional EFSA, FDA, and SAMR approval creates pricing power in nutraceutical channels demanding strain traceability. |
| Long-term Offtake Agreements | Fixed-price escalators with multinational beverage manufacturers displace spot purchasing and consolidate vendor lists. |
| Toll-Manufacturing Partnerships | Third-party fermentation leasing narrows capital barriers for mid-tier entrants lacking strain validation infrastructure. |
| Direct-to-Manufacturer Distribution | Technical service bundling with large-scale cereal and bakery premix producers captures highest margin pools bypassing distributors. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation plant managers, procurement leads at multinational food manufacturers, nutraceutical contract manufacturing executives, and distribution channel partners, and refined through secondary validation across SAMR GB standard filings, EFSA re-evaluation documentation, FDA 21 CFR registers, and customs trade data for lactic acid derivatives. Bottom-up volume modeling triangulated with top-down market sizing across powder, granule, liquid, and tablet format segments.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product type, application tier, end-user category, and distribution channel. CAGRs derived from weighted average growth contributions across infant formula certification, beverage stabilization, and food fortification verticals. Forecast inputs incorporated corn starch price elasticity, EFSA purity timeline enforcement probability, and toll-manufacturing capacity expansion trajectories.
The forecast holds incumbent behavior within observed patterns; aggressive certification investment by biotechnology-differentiated entrants or accelerated SAMR enforcement would shift outcomes beyond modeled ranges. Macroeconomic deviation in grain markets, regulatory harmonization failures across Codex Alimentarius jurisdictions, or breakthrough citrate formulation advances would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Cream of Tartar Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Cake Enzyme Market
Food Additives and Ingredients
Gardenia Food Color Market
Food Additives and Ingredients
Global Food Release Agents Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
Chymosine Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Food Acidulants Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Dairy Stabilizer Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Coconut Fatty Acids Market