
 Latin America Food Enzymes Market | 2026-2036
Latin America Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Food Enzymes Market Intelligence
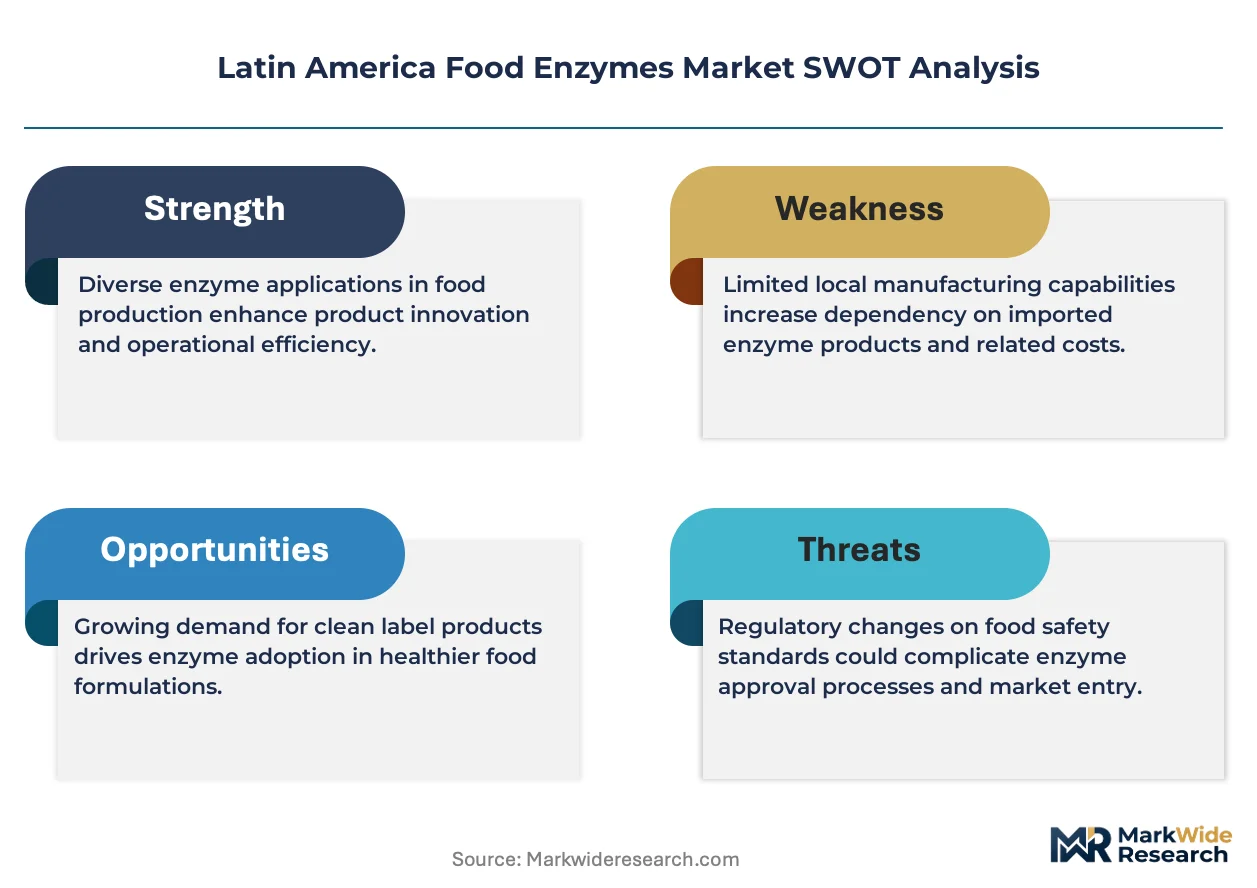
ISO 22000 certification is bifurcating the Latin America Food Enzymes Market into qualified suppliers and marginal participants. Novozymes leverages its fermentation technology platform to anchor premium supply contracts across Brazilian dairy processors. BASF competes through backward integration into specialty amylase production, sustaining margin control in a price-sensitive environment. Kerry Group differentiates via localized application laboratories in São Paulo, positioning technical service as a barrier to commodity traders.
Food enzymes comprise proteinaceous biocatalysts, typically operating at temperatures between 30°C and 60°C and pH ranges of 4.0 to 8.0, that accelerate specific biochemical reactions in food matrices without permanent consumption in the process. These catalysts reduce processing time, improve yield extraction, and enable clean-label formulation by replacing chemical additives in industrial food production. Amylase dominates volume throughput due to its ubiquity in starch hydrolysis for beverage and bakery applications, while lipase generates disproportionate margin contribution from specialty dairy flavor enhancement. The liquid form leads installation base in large-scale continuous processing, though powder formulations gain traction among small and mid-size bakeries seeking dosing flexibility and ambient storage stability.
Brazil's ANVISA and Mexico's COFEPRIS enforce divergent enzyme approval pathways, fragmenting registration timelines and favoring established multinationals with dedicated regulatory affairs capacity. Argentina's INAL and Chile's Ministry of Health maintain aligned positive lists for processing aids, creating a partial harmonization zone that simplifies cross-border formulation strategies. Stakeholders must monitor pending Mercosur food additive harmonization protocols and pre-position compliant documentation ahead of anticipated regulatory convergence.
Market Dynamics
ISO 22000 certification is bifurcating the Latin America Food Enzymes Market into qualified suppliers and marginal participants, forcing processors to consolidate procurement around audited fermentation houses while excluding spot-market traders from formal supply agreements.
Growth Catalysts
- ANVISA Process Optimization:Brazil's streamlined enzyme approval pathways for GRAS-equivalent substances compress registration timelines for established suppliers, accelerating bakery sector adoption.
- Starch Hydrolysis Intensification:Beverage processors across São Paulo's industrial corridor deploy thermostable amylase variants to maximize fermentable sugar extraction from local corn and cassava feedstocks.
- Clean-Label Reformulation:Mexican tortilla manufacturers substitute chemical conditioners with lipase-modified dough systems to meet COFEPRIS additive reduction guidelines.
Market Restraints
- Fermentation Feedstock Volatility:Molasses and dextrose prices fluctuate with Brazilian sugarcane harvest cycles, compressing margin predictability for enzyme producers dependent on localized carbohydrate sources.
- Regulatory Fragmentation:Divergent COFEPRIS and ANVISA approval timelines force multinationals to maintain parallel registration dossiers, inflating compliance overhead relative to unified markets.
- Biochemical Substitute Pressure:Chemical acid hydrolysis retains cost advantage in small-scale juice processing, limiting enzyme penetration among price-sensitive artisanal producers.
Strategic Opportunities
- Argentine Dairy Expansion:Underpenetrated specialty cheese production in Córdoba and Santa Fe provinces creates demand for lipase-based flavor modulation systems absent from current supplier portfolios.
- Mercosur Harmonization:Pending regional food additive convergence protocols will enable single-registration deployment across Brazil, Argentina, Paraguay, and Uruguay, reducing regulatory duplication costs.
- Powder Format Migration:Small and mid-size bakeries in Colombia and Chile seek ambient-stable enzyme formulations, opening distribution channels bypassing cold-chain-dependent liquid concentrate networks.
Industry Challenges
- Fermentation Specialist Scarcity:Industrial microbiology and downstream processing expertise concentrates in São Paulo and Mexico City, constraining scale-up capacity for regional greenfield facilities.
- ISO 22000 Audit Backlogs:Certification body capacity limitations in Brazil extend compliance timelines, delaying supplier qualification for multinational processor approved vendor lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Food Enzymes Market |
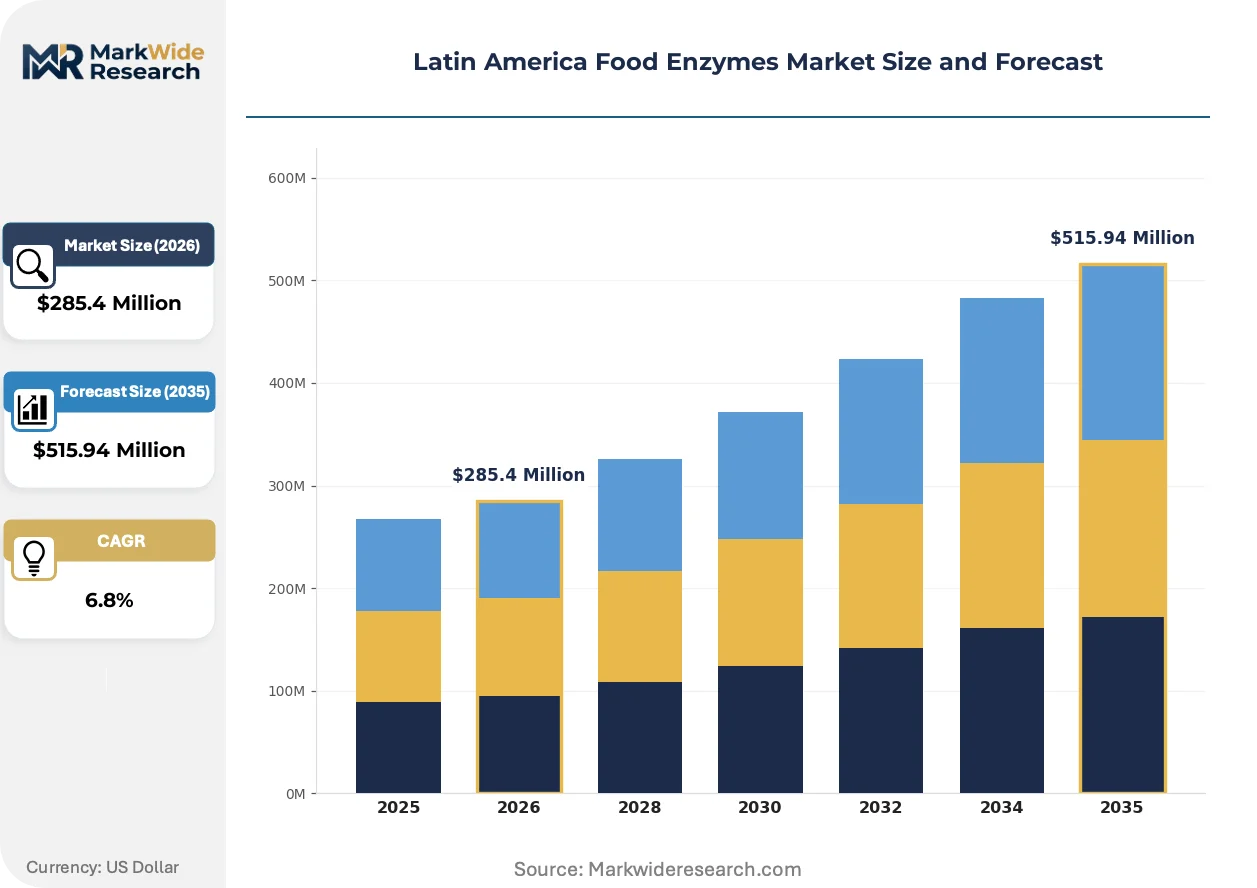
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Protease, Lipase, Lactase Application: Beverages, Dairy, Bakery, Meat Processing Form: Liquid, Powder, Granular, Tablet End User: Food & Beverage, Dairy Industry, Bakery Sector, Meat Industry |
| Companies Covered | BASF, Associated British Foods plc, Novozymes, Advanced Enzyme Technologies, Chr. Hansen Holding A/S, DuPont, Kerry Group, Amano Enzyme Inc., DSM, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Food Enzymes Market Strategic Shifts & Innovations
Cell-free enzyme engineering and precision fermentation platforms are compressing development cycles while regulatory data requirements for novel biocatalysts expand, creating tension between innovation velocity and approval certainty.
Immobilized enzyme systems for continuous starch processing are fragmenting batch-reactor dominance in large-scale facilities. Brazilian ethanol distilleries and Mexican beverage conglomerates pilot fixed-bed and membrane-encapsulated configurations to reduce enzyme consumption rates and stabilize catalytic output across extended operational windows. This hardware-enzyme convergence is fragmenting traditional supplier-processor relationships by introducing equipment vendors as gatekeepers to biocatalyst deployment.
COFEPRIS is tightening substantiation requirements for enzyme function claims in food additive petitions, demanding quantitative performance data under specified processing conditions. Mexican regulators now require stability studies across pH and temperature ranges relevant to target applications, elevating documentation burdens for imported preparations. Domestic tortilla and bakery processors face reformulation delays as suppliers recertify existing products under the enhanced evidentiary framework.
Technical service unbundling is altering procurement patterns among mid-size Latin American processors. São Paulo-based application laboratories now sell formulation support separately from enzyme supply contracts, enabling buyers to mix suppliers across product categories. Chilean and Argentine bakery cooperatives leverage this service fragmentation to optimize enzyme blends without sole-source dependency, compressing loyalty premiums previously captured by integrated providers.
Latin America Food Enzymes Market Segmentation
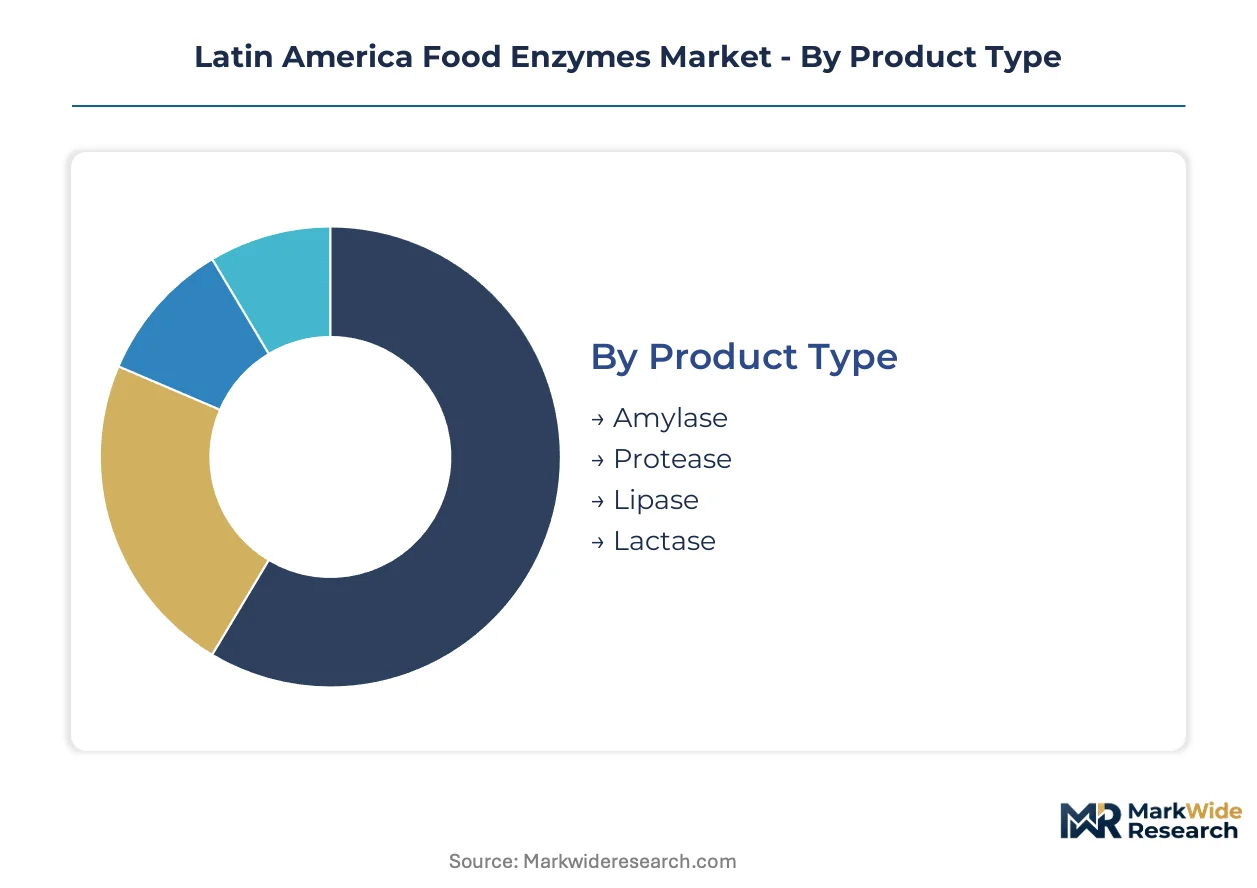
Enzyme procurement in Latin America fragments across multiple technical and commercial dimensions. Processors select biocatalyst formats and specifications based on scale, cold-chain access, and regulatory compliance requirements rather than price alone.
Product Type:
Liquid concentrates flow through direct supplier relationships with multinational dairy and beverage processors, while powder and granular formats reach smaller bakeries through regional distributors.
- Amylase:Thermostable variants hydrolyze starch chains at temperatures exceeding 90°C, enabling continuous processing in Brazilian ethanol distilleries and Mexican beverage plants. São Paulo's industrial corridor concentrates demand as corn and cassava processors maximize fermentable sugar extraction.
- Lipase:Position-specific esterases generate free fatty acids for flavor modulation in specialty cheese production. Argentine dairy processors in Córdoba and Santa Fe provinces deploy lipase systems to replace chemical flavor enhancers under tightening clean-label specifications.
- Protease:Endo- and exopeptidase blends hydrolyze protein matrices for meat tenderization and hydrolysate production.
- Lactase:Beta-galactosidase preparations convert lactose to glucose-galactose for reduced-lactose dairy lines.
Amylase dominates installed base. Lipase is where expansion concentrates.
Application:
Cost tier stratification separates premium enzyme blends for multinational processors from standard-grade formulations serving regional cooperatives.
- Beverages:Glucoamylase and pullulanase cocktails complete starch saccharification in Brazilian corn-based ethanol and Mexican agave spirits. Thermostable variants reduce enzyme dosage rates while maintaining conversion efficiency across variable feedstock quality.
- Bakery:Fungal alpha-amylase and xylanase combinations strengthen dough rheology and extend shelf life without chemical conditioners. Brazil's São Paulo-Minas Gerais baking corridor drives volume as industrial bakeries reformulate for extended distribution cycles.
- Dairy:Chymosin and lipase systems accelerate cheese ripening and flavor development.
- Meat Processing:Transglutaminase and protease blends improve texture and water-binding in processed protein matrices.
Beverage applications command premium pricing tiers. Bakery represents the steepest expansion trajectory as clean-label reformulation accelerates.
Form:
Volume concentration favors liquid formats in continuous processing installations, while ambient-stable alternatives gain share among distributed production networks.
- Liquid:Standardized activity concentrates in stabilized aqueous solutions enable precise dosing through automated injection systems. Large-scale Brazilian dairy processors and Mexican beverage conglomerates specify liquid formats for integration with CIP-compatible equipment.
- Powder:Spray-dried preparations with maltodextrin carriers store at ambient conditions without cold-chain dependency. Colombian and Chilean mid-size bakeries prefer powder formats for dosing flexibility and reduced logistics complexity.
- Granular:Agglomerated particles reduce dust exposure during manual handling in smaller facilities.
- Tablet:Unit-dose formats target artisanal producers without calibrated dosing equipment.
Liquid leads volume throughput. Powder is where customer acquisition concentrates among small and mid-size processors.
End User:
Customer type determines technical service intensity, with multinational food and beverage manufacturers demanding integrated formulation support while regional dairy and meat processors prioritize supply security.
- Food & Beverage:Integrated multinational processors procure enzyme systems as part of broader ingredient portfolios, requiring suppliers to maintain ISO 22000 certification and dedicated technical service capacity. These buyers consolidate procurement around audited fermentation houses with regional application laboratories.
- Dairy Industry:Cheese manufacturers and fluid milk processors specify enzyme activity levels tailored to local milk composition and seasonal variation. Argentine and Brazilian dairy cooperatives negotiate supply agreements based on consistent activity guarantees rather than brand loyalty.
- Bakery Sector:Industrial and artisanal bread producers seek shelf-life extension and dough conditioning without chemical additive declarations.
- Meat Industry:Processed meat manufacturers deploy enzymes for texture modification and yield improvement.
Food and beverage multinationals anchor supplier revenue. Dairy is where technical service differentiation produces contract renewals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multinational food processors concentrate procurement authority in São Paulo and Mexico City, while regional cooperatives in secondary markets fragment demand across localized supplier networks.
Brazil
Industrial bakeries along the São Paulo-Minas Gerais corridor drive amylase consumption for shelf-life extension in extended distribution cycles. ANVISA maintains streamlined GRAS-equivalent approval pathways that compress registration timelines for established fermentation houses. Campinas and Piracicaba host downstream processing facilities supplying ethanol distilleries with thermostable starch-hydrolyzing biocatalysts.
Mexico
Tortilla manufacturers substitute chemical conditioners with lipase-modified dough systems to satisfy clean-label specifications. COFEPRIS tightened substantiation requirements for enzyme function claims, demanding quantitative performance data under specified processing conditions. Guadalajara's industrial baking cluster faces reformulation delays as suppliers recertify existing products under enhanced evidentiary frameworks.
Argentina
Specialty cheese production in Córdoba and Santa Fe provinces creates demand for lipase-based flavor modulation systems. INAL maintains aligned positive lists for processing aids with Chile, creating partial harmonization that simplifies cross-border formulation strategies. Rosario's dairy cooperatives negotiate supply agreements based on consistent activity guarantees rather than brand loyalty.
Chile
Mid-size bakery cooperatives leverage technical service unbundling to optimize enzyme blends without sole-source dependency. The Ministry of Health maintains regulatory alignment with Argentina on processing aid approvals. Santiago's application laboratories sell formulation support separately from enzyme supply contracts, compressing loyalty premiums previously captured by integrated providers.
Colombia
Small and mid-size bakeries seek ambient-stable powder formulations to bypass cold-chain-dependent liquid concentrate networks. The national food and drug surveillance institute enforces additive regulations that favor documented stability studies. Bogotá's distributed production networks drive customer acquisition toward granular formats with reduced logistics complexity.
Latin America Food Enzymes Market Key Industry Players
Player mix skews toward diversified multinationals with fermentation technology platforms and regional application laboratories. Market structure concentrates around audited suppliers with ISO 22000 certification, excluding spot-market traders from formal procurement agreements. Three archetypes dominate: integrated life-science conglomerates with backward integration into specialty production, ingredient specialists with localized technical service capacity, and regional distributors serving ambient-format demand in secondary markets. Competitive moves center on regulatory dossier pre-positioning ahead of Mercosur harmonization and capacity expansion in powder formulation lines for distributed bakery networks.
Among integrated life-science conglomerates, BASF and DSM exemplify archetypes combining captive production with margin control in price-sensitive environments. Novozymes occupies a position representing fermentation technology leadership anchored through premium supply contracts. Kerry Group sits within the technical-service-differentiation tier, with São Paulo-based application laboratories positioning localized support as a barrier to commodity traders. Associated British Foods plc, DuPont, and Chr. Hansen Holding A/S represent additional multinational anchors with diversified biocatalyst portfolios spanning dairy, bakery, and beverage applications.
| Leading Market Players |
|---|
| BASF |
| Associated British Foods plc |
| Novozymes |
| Advanced Enzyme Technologies |
| Chr. Hansen Holding A/S |
| DuPont |
| Kerry Group |
| Amano Enzyme Inc. |
| DSM |
| Others |
Cost & Logistics Intelligence
Lipase substitution for chemical flavor enhancers in Argentine and Mexican dairy processing simultaneously shifts procurement geography toward São Paulo-based fermentation houses and compresses margin structures for commodity-grade amylase suppliers. This input replacement dynamic concentrates pricing power with ISO 22000-certified producers while fragmenting spot-market participation.
Pricing Analysis
Cost-plus contracts indexed to Brazilian sugarcane-derived molasses and dextrose spot markets dominate long-term supply agreements between multinational processors and fermentation houses. Three-tier pricing structure across premium certified, standard industrial, and economy generic levels separates audited suppliers from marginal traders. Pricing pressure stems from chemical acid hydrolysis retaining cost advantage in small-scale juice processing, forcing enzyme producers to absorb feedstock volatility. Artisanal tortilla manufacturers in Guadalajara exhibit highest price sensitivity, while São Paulo ethanol distilleries prioritize thermostable performance over unit cost.
Supply Chain Analysis
Inventory cycles extending sixty to ninety days for powder formulations contrast with continuous replenishment schedules for liquid concentrates in Brazilian dairy corridors. Supply concentrates in Brazil, Denmark, and the Netherlands, with downstream processing facilities clustering in Campinas and Piracicaba. Raw material dependencies center on sugarcane molasses, corn dextrose, and specialized nitrogen sources for fermentation media. Single-source vulnerability persists for thermostable amylase variants patented by select life-science conglomerates. Distribution runs through direct supplier relationships with multinationals and regional distributors serving ambient-format demand in Colombia and Chile.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized fermentation microbiologists and downstream processing engineers concentrate in São Paulo and Mexico City, creating geographic capability scarcity that constrains regional greenfield expansion and inflates technical service premiums for qualified suppliers.
For Market Incumbents: Fortify margin structures by deepening backward integration into specialty lipase production and expanding powder formulation capacity in Colombian distribution corridors. Chemical acid hydrolysis resurgence among price-sensitive artisanal juice processors threatens volume-based revenue streams; prioritize thermostable variant patent portfolios as defensive moats. ISO 22000 certification investments anchor procurement relationships with multinational processors consolidating approved vendor lists. For New Entrants and Emerging Players: Technical service unbundling in Chilean and Argentine bakery cooperatives creates white-space opportunity for standalone formulation laboratories without captive fermentation assets. Underpenetrated specialty cheese production in Córdoba and Santa Fe provinces offers the most penetrable application segment, with lipase-based flavor modulation systems absent from current portfolios. Pursue partnership-based go-to-market models with São Paulo application laboratories to bypass capital-intensive fermentation infrastructure. For Investors and Strategic Acquirers: Pending Mercosur food additive harmonization protocols reshape the acquisition landscape by enabling single-registration asset deployment across Brazil, Argentina, Paraguay, and Uruguay. Long-term viability favors targets with pre-positioned regulatory dossiers and established relationships with ANVISA and COFEPRIS. Vertically integrated mid-tier fermentation houses with regional application laboratories represent priority acquisition archetypes. Monitor ISO 22000 audit backlog resolution as inflection indicator for supplier qualification velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Dossier Pre-Positioning | Mercosur harmonization protocols will compress multi-country registration timelines for prepared suppliers. |
| Powder Formulation Capacity Expansion | Ambient-stable formats unlock Colombian and Chilean mid-size bakery networks bypassing cold-chain logistics. |
| Technical Service Laboratory Localization | São Paulo-based formulation support anchors multinational processor contracts against commodity traders. |
| Backward Integration into Lipase Production | Captive specialty enzyme supply protects margin structures in Argentine dairy flavor modulation segments. |
| ISO 22000 Certification Acceleration | Audited supplier status excludes spot-market competitors from formal procurement agreements with multinationals. |
Research Approach
Initial hypotheses were tested against primary input from fermentation technology directors, regulatory affairs specialists at ANVISA and COFEPRIS, dairy procurement managers in Córdoba, and bakery technical directors in São Paulo and Guadalajara and refined through secondary validation against customs trade records, SEC filings from listed life-science conglomerates, ANVISA enzyme registration databases, and COFEPRIS food additive petitions. Bottom-up volume estimates from individual facility consumption patterns triangulated with top-down market sizing from trade flow analysis.
Variance decomposition across enzyme type, application segment, formulation format, and end-user scale anchors the analytical framework over the projection horizon. CAGRs derive from segment-level growth rate reconciliation against macroeconomic drivers including industrial food production expansion and clean-label regulatory pressure. Modeled inputs incorporate ANVISA approval velocity, COFEPRIS substantiation requirement evolution, and regional bakery sector consolidation patterns.
Forecasts assume regulatory continuity in Brazilian ANVISA and Mexican COFEPRIS regimes; material policy shifts toward stricter enzyme function claim requirements would require re-modeling. Commodity feedstock price volatility and certification body capacity constraints in Brazil represent specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Food Glazing Agents Market
Food Additives and Ingredients
Ammonium Chloride Food Grade Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Isodecanol Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Blueberry Ingredient Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Europe Food Colorants Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Italy Food Emulsifier Market