
 Pyranose Oxidase Market | 2026-2036
Pyranose Oxidase Market Size, Share, and Industry Trends Forecast 2026-2036
Pyranose Oxidase Market Analytics
The gap between premium recombinant grades and commodity fermentation-derived pyranose oxidase is rebalancing as biofuel producers demand higher catalytic efficiency while food manufacturers prioritize cost-stable supply contracts. Amano Enzymes leverages decades of fermentation expertise to anchor supply reliability for Asian food manufacturers. Codexis specializes in protein engineering workflows that differentiate its biocatalysis portfolio for pharmaceutical applications. Thermo Fisher Scientific controls distribution density across North American research institutions through integrated reagent channels.
Pyranose oxidase is a flavoprotein enzyme that catalyzes the oxidation of aldopyranoses at the C-2 position, typically sourced from fungal genera such as Trametes or Peniophora and characterized by optimal activity near pH 6.0 and 35°C. Its primary commercial purpose centers on selective carbohydrate modification for food texture enhancement, pharmaceutical intermediate synthesis, and lignocellulosic biomass pretreatment in biofuel production. Recombinant enzymes command the steepest margin pools due to batch-to-batch consistency requirements in pharmaceutical cGMP environments. Powdered enzymes still dominate volume throughput among food manufacturers seeking dry-blend formulation compatibility. Liquid formulations are gaining traction in automated biofuel processing lines where pumpability reduces handling labor.
FDA enzyme GRAS notifications and EPA biofuel pathway certifications shape product qualification timelines for US market entry, while REACH registration obligations in Europe constrain small-volume importers. The EU Green Deal's biorefinery targets are redirecting public funding toward enzymatic process validation, tightening competitive pressure on chemical synthesis alternatives. Stakeholders must monitor evolving pharmacopeial monograph standards for enzyme purity and decide whether to build in-house fermentation capacity or secure long-term toll manufacturing agreements before feedstock volatility escalates.
Market Dynamics
Precision fermentation capacity concentration in Germany and Japan is bifurcating supply reliability between pharmaceutical-grade recombinant producers and commodity food-grade suppliers, forcing buyers into long-term toll manufacturing commitments before feedstock volatility accelerates.
Growth Catalysts
- EU Green Deal biorefinery targets:Public funding redirection toward enzymatic process validation is compressing qualification timelines for lignocellulosic biomass pretreatment applications in biofuel production.
- Clean-label ingredient regulations:Tightening EU food additive standards are displacing chemical carbohydrate modifiers with enzymatic alternatives in texture-enhancement applications.
- Pharmaceutical cGMP environments:Batch-to-batch consistency mandates are pulling premium recombinant grades into intermediate synthesis workflows for active pharmaceutical ingredients.
Market Restraints
- Feedstock input volatility:Carbon source price swings for fungal fermentation media constrain margin stability for commodity-grade producers.
- REACH registration obligations:European chemical registration requirements impose fixed compliance costs that disproportionately burden small-volume importers.
- Glucose oxidase substitution:Established peroxidase-coupled systems in food processing retain incumbent status due to lower switching costs and familiar handling protocols.
Strategic Opportunities
- Automated biofuel processing lines:Pumpable liquid formulations are opening specification wins against powdered competitors in continuous-flow biorefinery operations.
- Indian PLI scheme for biotechnology:Production-linked incentives for precision fermentation infrastructure are attracting toll manufacturing investments for Asian pharmaceutical supply.
- Pharmacopeial monograph evolution:Emerging enzyme purity standards are creating first-mover certification advantages for recombinant producers with existing analytical capabilities.
Industry Challenges
- Fermentation scale-up talent scarcity:Experienced bioprocess engineers capable of transferring lab-scale pyranose oxidase production to industrial bioreactors command premium compensation in Germany and Japan.
- cGMP certification timeline compression:FDA enzyme GRAS notification delays and EPA biofuel pathway certification backlogs extend product qualification cycles for US market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pyranose Oxidase Market |
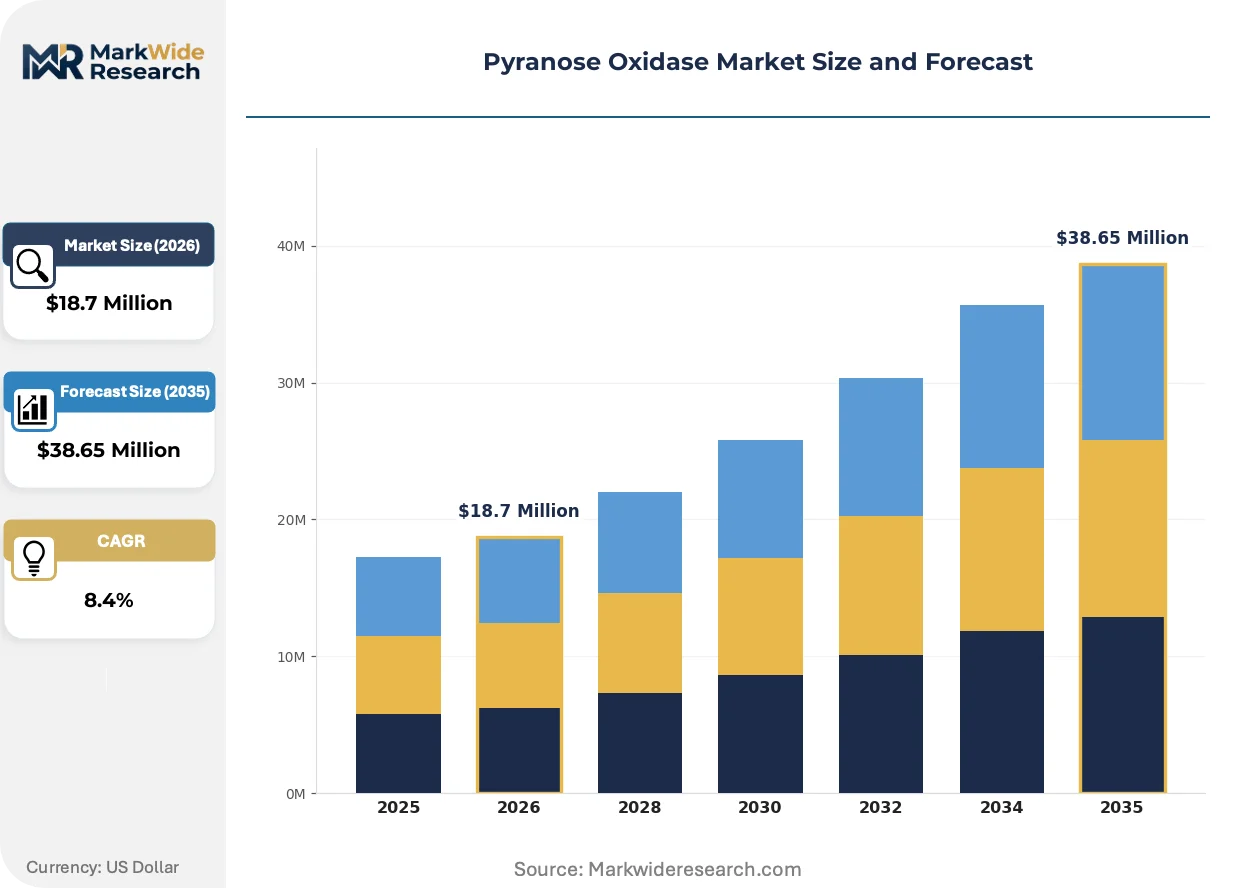
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $38.65 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
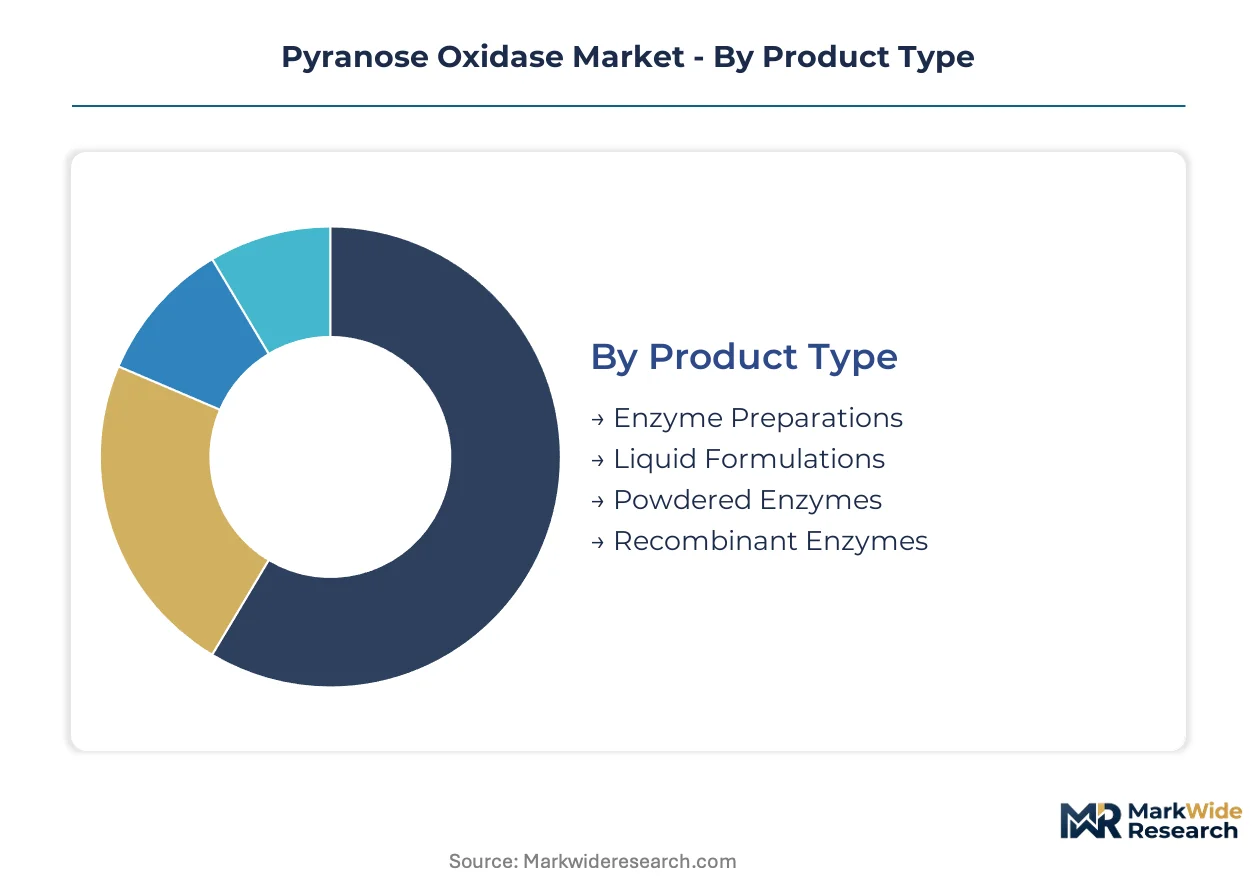
| Segmentation | Product Type: Enzyme Preparations, Liquid Formulations, Powdered Enzymes, Recombinant Enzymes Application: Food & Beverage, Pharmaceuticals, Biofuels, Animal Feed Technology: Biocatalysis, Fermentation Technology, Enzymatic Processes, Chemical Synthesis End User: Food Manufacturers, Pharmaceutical Companies, Biofuel Producers, Research Institutions |
| Companies Covered | Ikeda Tohka Industries, Enzymaker Lab, CUSAg, Amano Enzymes, Codexis, Roche, Sanofi, Thermo Fisher Scientific, Aldevron, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pyranose Oxidase Market Evolving Landscape
Continuous bioprocessing architectures are displacing traditional batch fermentation across pharmaceutical and biofuel applications, compressing capital intensity requirements while demanding new enzyme formulation compatibilities.
Single-use bioreactor technology is decentralizing production geography for recombinant pyranose oxidase by eliminating stainless-steel infrastructure dependencies. Mid-scale pharmaceutical manufacturers in Singapore and Switzerland are adopting disposable fermentation systems to bypass capital-heavy fixed-asset investments. This diffusion is fragmenting supply concentration away from established German and Japanese production hubs toward regional contract manufacturing organizations.
REACH authorization amendments for industrial biotechnology substances are tightening substance data requirements for enzyme imports into the European Union. Manufacturers must now submit expanded toxicity dossiers for fermentation-derived proteins previously exempt under bulk chemical thresholds. Pharmaceutical-grade suppliers with existing ECHA registration expertise are capturing specification advantages over commodity importers lacking regulatory affairs capacity.
Specification-driven procurement is consolidating buyer power among North American research institutions through integrated reagent distribution channels. Thermo Fisher Scientific's consolidated purchasing agreements are compressing independent enzyme supplier margins while elevating batch documentation requirements. This channel concentration is most visible in academic and government laboratory segments where grant-funded researchers prioritize supply reliability over unit cost optimization.
Pyranose Oxidase Market Segmentation
Segmentation in pyranose oxidase markets tracks how specification tiers diverge across cGMP pharmaceutical environments, automated biofuel processing lines, and cost-sensitive food manufacturing. Buyers select product grades based on batch consistency requirements, handling format preferences, and regulatory qualification burdens rather than unit price alone.
Product Type:
Specification tiers separate pharmaceutical-grade recombinant material from commodity fermentation outputs, with liquid versus powdered formats diverging on automation compatibility and supply chain stability.
- Recombinant Enzymes:Engineered protein variants deliver batch-to-batch consistency required for FDA enzyme GRAS notifications and EMA pharmaceutical intermediate synthesis. Pharmaceutical companies in Germany and Switzerland pay premium toll manufacturing rates to secure cGMP-compliant supply with full analytical documentation.
- Powdered Enzymes:Spray-dried or lyophilized preparations optimize dry-blend formulation compatibility for food texture modification. Food manufacturers in Japan prioritize cost-stable annual contracts over performance variability, accepting broader activity specifications in exchange for supply predictability.
- Liquid Formulations:Pumpable aqueous concentrates reduce handling labor in continuous-flow biorefinery operations. Biofuel producers in the US Midwest specify liquid grades for automated dosing systems integrated with lignocellulosic pretreatment lines.
- Enzyme Preparations:Standardized activity blends with stabilizers and carriers serve research institutions requiring reproducible assay conditions. Thermo Fisher Scientific's distribution channels dominate North American academic procurement with consolidated reagent purchasing agreements.
Mature deployment sits with powdered enzymes in Asian food manufacturing. Newer deployment is concentrated in recombinant grades for European pharmaceutical intermediate synthesis.
Application:
End-use concentration reflects diverging margin structures: pharmaceutical cGMP workflows command steepest premiums, while biofuel enzymatic pretreatment scales volume throughput.
- Pharmaceuticals:Selective carbohydrate oxidation for active pharmaceutical ingredient intermediates demands recombinant enzyme purity with pharmacopeial monograph compliance. Swiss and German contract manufacturers capture specification advantages through existing ECHA registration expertise for REACH-authorized biotechnology substances.
- Biofuels:Lignocellulosic biomass pretreatment applications scale precision fermentation output for cellulosic ethanol pathway certification. EPA biofuel pathway qualification timelines compress as EU Green Deal biorefinery targets redirect public funding toward enzymatic process validation.
- Food & Beverage:Texture enhancement and carbohydrate modification displace chemical additives under tightening EU clean-label regulations. Amano Enzymes anchors supply reliability for Japanese and Southeast Asian food processors through decades of fungal fermentation expertise.
- Animal Feed:Prebiotic carbohydrate conversion for gut health applications represents emerging specification territory with limited current volume. Feed compounders in Brazil and India trial pyranose oxidase against established phytase and xylanase systems.
Pharmaceutical applications carry the steepest margin pool. Biofuel processing is climbing the fastest on volume expansion driven by EU Green Deal biorefinery targets.
Technology:
Process technology selection determines capital intensity, regulatory qualification burden, and geographic production concentration for each supply tier.
- Fermentation Technology:Submerged fungal cultivation of Trametes or Peniophora strains generates commodity-grade enzyme with optimal activity near pH 6.0 and 35°C. German and Japanese precision fermentation infrastructure concentrates supply reliability for pharmaceutical-grade recombinant producers.
- Biocatalysis:Immobilized enzyme systems and protein-engineered variants enable continuous-flow pharmaceutical intermediate synthesis. Codexis specializes in workflow integration for active pharmaceutical ingredient manufacturers requiring engineered catalytic efficiency.
- Enzymatic Processes:Single-use bioreactor technology decentralizes recombinant production geography by eliminating stainless-steel infrastructure dependencies. Singapore and Switzerland mid-scale manufacturers adopt disposable fermentation systems to bypass capital-heavy fixed-asset investments.
- Chemical Synthesis:Non-enzymatic carbohydrate modification retains incumbent status in cost-sensitive applications where switching costs and familiar handling protocols dominate procurement decisions.
Mature deployment sits with fermentation technology in commodity food-grade supply. Newer deployment is concentrated in biocatalysis workflows for pharmaceutical cGMP environments.
End User:
Buyer concentration patterns fragment across integrated reagent distributors, toll manufacturing relationships, and direct fermentation supply contracts.
- Pharmaceutical Companies:cGMP batch consistency mandates drive long-term toll manufacturing commitments before feedstock volatility accelerates. EMA-qualified suppliers with existing analytical capabilities capture first-mover advantages as pharmacopeial monograph standards evolve.
- Food Manufacturers:Dry-blend formulation compatibility and cost-stable supply contracts outweigh performance optimization in procurement criteria. EU clean-label regulatory tightening displaces chemical carbohydrate modifiers with enzymatic alternatives.
- Biofuel Producers:Automated processing lines specify pumpable liquid formulations to reduce handling labor in continuous-flow biorefinery operations. EPA pathway certification backlogs extend product qualification cycles for US market entry.
- Research Institutions:Grant-funded researchers prioritize supply reliability over unit cost optimization through consolidated purchasing agreements. Thermo Fisher Scientific's channel concentration compresses independent enzyme supplier margins in North American academic and government laboratory segments.
Mature deployment sits with food manufacturers in Asian markets. Newer deployment is concentrated in biofuel producers responding to EU Green Deal biorefinery funding redirection.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main biotech corridor around Frankfurt anchors European precision fermentation capacity for pharmaceutical-grade recombinant enzymes. Japanese fungal fermentation clusters in Nagoya supply cost-stable food-grade material to Southeast Asian processors. North American biofuel demand concentrates in the US Midwest corn belt.
Germany
Baden-Württemberg and North Rhine-Westphalia host mature precision fermentation infrastructure serving EMA-qualified pharmaceutical contract manufacturers. REACH registration obligations under ECHA constrain small-volume enzyme importers while rewarding domestic producers with existing regulatory affairs capacity. The Rhine-Main corridor around Frankfurt concentrates toll manufacturing agreements for cGMP-compliant recombinant pyranose oxidase.
Japan
Nagoya and Osaka-based fungal fermentation specialists anchor supply reliability for Asian food manufacturers seeking dry-blend formulation compatibility. METI industrial biotechnology programs redirect public funding toward enzymatic process validation for biofuel applications. Aichi Prefecture fermentation clusters leverage decades of Trametes cultivation expertise to secure cost-stable annual contracts.
United States
Midwest biorefinery operators in Iowa and Illinois specify pumpable liquid enzyme formulations for automated lignocellulosic pretreatment lines. EPA biofuel pathway certification backlogs extend product qualification timelines while FDA enzyme GRAS notifications shape pharmaceutical market entry. Chicago-area distribution hubs consolidate reagent purchasing for North American research institutions.
India
Maharashtra and Karnataka biotechnology parks attract toll manufacturing investments under the PLI scheme for precision fermentation infrastructure. CDSCO pharmaceutical regulations and FSSAI food additive standards bifurcate procurement between research-grade and commercial-grade enzyme supply. Mumbai-Pune corridor contract manufacturers trial single-use bioreactor adoption to bypass capital-heavy fixed-asset requirements.
Switzerland
Basel and Zurich mid-scale pharmaceutical manufacturers adopt disposable fermentation systems for recombinant enzyme production targeting EMA intermediate synthesis workflows. Swissmedic pharmacopeial standards create first-mover certification advantages for producers with existing analytical capabilities. The Basel biotech cluster captures specification wins through integrated biocatalysis service offerings.
Pyranose Oxidase Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade and application-specific dimensions, with recombinant producers commanding steepest pools for pharmaceutical cGMP environments. The vendor base separates into three strategic archetypes: fungal fermentation heritage houses, protein engineering specialists, and integrated reagent distributors. Capacity expansion through toll manufacturing agreements and geographic diversification through single-use bioreactor adoption represent the dominant competitive moves.
Within the fermentation heritage tier, Amano Enzymes and Ikeda Tohka Industries occupy positions anchored by decades of fungal cultivation expertise in Japanese supply chains. Codexis exemplifies the protein engineering specialist archetype, sitting within the biocatalysis workflow integration segment for pharmaceutical applications. Thermo Fisher Scientific anchors the integrated distribution tier, controlling specification-driven procurement channels across North American research institutions.
| Leading Market Players |
|---|
| Ikeda Tohka Industries |
| Enzymaker Lab |
| CUSAg |
| Amano Enzymes |
| Codexis |
| Roche |
| Sanofi |
| Thermo Fisher Scientific |
| Aldevron |
| Others |
Value Network & Pricing Analysis
Single-use bioreactor adoption is compressing capital barriers for mid-scale recombinant enzyme producers while fragmenting supply geography away from German and Japanese precision fermentation hubs. This technology shift simultaneously reduces fixed-cost recovery pressures on pricing and enables regional contract manufacturers to undercut established toll manufacturing rates for pharmaceutical-grade material.
Pricing Analysis
Value-based pricing anchored to batch-to-batch consistency outcomes dominates pharmaceutical cGMP procurement, with recombinant grades commanding substantial premiums over commodity fermentation outputs. Three-tier pricing structure across premium, standard, and economy levels separates pharmacopeial-certified recombinant enzymes from food-grade powders and research-grade preparations. Cost compression in commodity food-grade tiers is intensifying because glucose oxidase substitution retains incumbent status in peroxidase-coupled systems. Food manufacturers in Japan exhibit highest price sensitivity, prioritizing cost-stable annual contracts over performance optimization, while Swiss pharmaceutical contract manufacturers show lowest sensitivity due to cGMP compliance mandates.
Supply Chain Analysis
India's PLI scheme for biotechnology is reshaping sourcing patterns by attracting toll manufacturing investments away from established German and Japanese production clusters. Geographic supply concentrates in Germany, Japan, and India, with emerging diffusion toward Singapore and Switzerland through single-use bioreactor adoption. Raw material dependencies center on fungal fermentation media carbon sources, pharmacopeial-grade stabilizers, and single-use bioreactor consumables. Single-source vulnerability around precision fermentation capacity in the Rhine-Main corridor creates concentration risk for pharmaceutical-grade supply. Distribution runs through integrated reagent channels for North American research institutions and direct toll manufacturing agreements for pharmaceutical and biofuel end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous bioprocessing architectures are displacing traditional batch fermentation across pharmaceutical and biofuel applications, creating asymmetric opportunity windows for technology-advantaged suppliers and stranded-asset risk for legacy batch operators.
For Market Incumbents: Deepen analytical documentation capabilities to capture first-mover advantages as pharmacopeial monograph standards evolve for enzyme purity. Incumbents should secure long-term toll manufacturing agreements before feedstock volatility accelerates, while investing in single-use bioreactor capacity to defend against regional contract manufacturers undercutting German and Japanese production hubs. For New Entrants and Emerging Players: Mid-scale pharmaceutical manufacturers in Singapore and Switzerland represent an underserved buyer archetype seeking disposable fermentation systems to bypass capital-heavy fixed-asset investments. New entrants should target automated biofuel processing lines in the US Midwest with pumpable liquid formulations, entering through specification wins against powdered competitors in continuous-flow biorefinery operations. For Investors and Strategic Acquirers: Exit pathways concentrate in precision fermentation infrastructure plays with existing ECHA registration expertise for REACH-authorized biotechnology substances. Long-term viability favors recombinant enzyme producers with pharmacopeial certification capabilities and analytical documentation depth. The signal to watch is EPA biofuel pathway certification timeline compression, which would accelerate volume throughput validation for lignocellulosic biomass pretreatment applications.| Strategic Initiative | Industry Significance |
|---|---|
| Single-Use Bioreactor Adoption | Singapore and Switzerland manufacturers bypass capital-heavy fixed-asset investments through disposable fermentation systems. |
| Long-Term Toll Manufacturing Agreements | Pharmaceutical companies secure cGMP-compliant supply before feedstock volatility accelerates in German production hubs. |
| Pharmacopeial Monograph Certification | Recombinant producers with existing analytical capabilities capture specification advantages as enzyme purity standards evolve. |
| Liquid Formulation Specification Wins | Biofuel producers in the US Midwest reduce handling labor through pumpable grades for automated dosing systems. |
| Backward Integration into Fermentation Media | Commodity-grade producers stabilize margins against carbon source price swings through captive supply of fungal cultivation inputs. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this pyranose oxidase market analysis. Primary interviews with bioprocess engineers, regulatory affairs specialists at EMA-qualified contract manufacturers, procurement leads at biofuel processing operators, and toll manufacturing agreement negotiators combined with bottom-up and top-down triangulation. Secondary sources included FDA enzyme GRAS notification databases, ECHA REACH registration records, EPA biofuel pathway certification filings, and METI industrial biotechnology program disclosures. Customs records tracked enzyme import volumes across European, North American, and Asian trade corridors.
Data-stream reconciliation across production capacity surveys, toll manufacturing rate benchmarks, and end-user procurement databases generated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type tier, application end-use, process technology, and geographic production hub. CAGRs were derived from production capacity expansion timelines and end-user demand elasticity assessments. Industry-specific forecast inputs incorporated EU Green Deal biorefinery funding redirection timelines and pharmacopeial monograph evolution trajectories.
Revisions become necessary when feedstock input volatility accelerates beyond current carbon source price bands, when REACH authorization amendments impose expanded toxicity dossier requirements, or when FDA enzyme GRAS notification delays extend beyond historical backlogs. Forecasts reflect assumptions around precision fermentation capacity concentration stability and single-use bioreactor adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Sugar Reduction Technology Market
Food Additives and Ingredients
Western Europe Food Phosphate Market
Food Additives and Ingredients
Food Grade Acetic Acid Market
Food Additives and Ingredients
Global Gamma Linolenic Acid Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Glandular Ingredients Market
Food Additives and Ingredients
Germany Feed Additives Market
Food Additives and Ingredients
United States Food Acidulants Market
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
United Kingdom Food Colorants Market
Food Additives and Ingredients
Australia Food Colorants Market