
 US Food Emulsifiers Market | 2026-2036
US Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
US Food Emulsifiers Market Analytics
The FDA's updated Nutrition Facts labeling mandate is restructuring formulation economics for emulsifier suppliers. Cargill, Incorporated leverages its Midwest grain processing network to anchor domestic lecithin supply chains. Kerry Group plc competes through integrated taste-and-texture systems that bundle emulsifiers with flavor solutions. Archer Daniels Midland Company dominates oilseed-derived emulsifier output from its Decatur, Illinois complex.
Food emulsifiers are surface-active agents that reduce interfacial tension between immiscible phases such as oil and water, typically containing hydrophilic and lipophilic moieties in ratios expressed by HLB values ranging from 2 to 20. These compounds stabilize emulsions, control crystallization, and modify rheology in processed foods. Mono- and Diglycerides occupy the largest volume position due to cost efficiency and broad regulatory acceptance across bakery and dairy applications. Lecithin segments are gaining fastest in plant-based dairy alternatives where non-GMO and allergen-free claims command premium positioning. Polysorbates retain specialized roles in confectionery coatings where thermal stability requirements exclude natural alternatives.
FDA food additive regulations, USDA organic certification standards, and state-level California Proposition 65 enforcement collectively shape emulsifier approval pathways and clean-label positioning requirements. The EPA's bio-based procurement preferences are redirecting R&D spending toward enzymatically modified lecithin and microbial-derived alternatives. Stakeholders must monitor pending FDA guidance on refined ingredient disclosure thresholds that could force reformulation across conventional mono- and diglyceride portfolios.
Market Dynamics
FDA labeling modernization is forcing simultaneous reformulation across conventional mono- and diglyceride portfolios and enzymatically modified lecithin alternatives, compressing supplier R&D cycles while plant-based dairy expansion tightens emulsifier specification requirements.
Growth Catalysts
- Clean-label bakery demand:Reformulation activity accelerates across Midwest and Southeast manufacturing corridors as processors replace synthetic emulsifiers with plant-derived alternatives to meet retailer certification requirements.
- USDA organic certification:Premium positioning opportunities expand for non-GMO lecithin suppliers serving plant-based dairy alternative producers seeking dual organic and allergen-free claims.
- Enzymatic modification:Bio-based procurement preferences under EPA guidelines redirect capital toward microbial-derived emulsifier production platforms with lower carbon intensity profiles.
Market Restraints
- Soybean input volatility:Lecithin cost structures fluctuate with Illinois and Iowa grain processing corridor harvest yields and export demand cycles.
- Decatur supply concentration:Oilseed-derived emulsifier output clusters at single Illinois complex, creating geographic vulnerability to localized disruption.
- Thermal stability limitations:Natural alternatives fail confectionery coating applications where Polysorbates retain specialized roles due to heat resistance requirements.
Strategic Opportunities
- California Proposition 65 enforcement:Refined ingredient disclosure thresholds create first-mover advantage for suppliers with established contaminant testing protocols and transparent supply chains.
- Integrated taste-texture systems:Bundling emulsifiers with flavor solutions opens higher-margin positioning beyond commodity ingredient sales.
- Microbial fermentation platforms:Cell-culture derived phospholipids bypass agricultural input constraints while satisfying clean-label positioning requirements.
Industry Challenges
- HLB formulation expertise:Shortage of technologists skilled in hydrophilic-lipophilic balance optimization across bakery and dairy application matrices slows customer co-development timelines.
- Dual certification complexity:Simultaneous FDA food additive compliance and California Proposition 65 documentation extends product qualification cycles for national distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Food Emulsifiers Market |
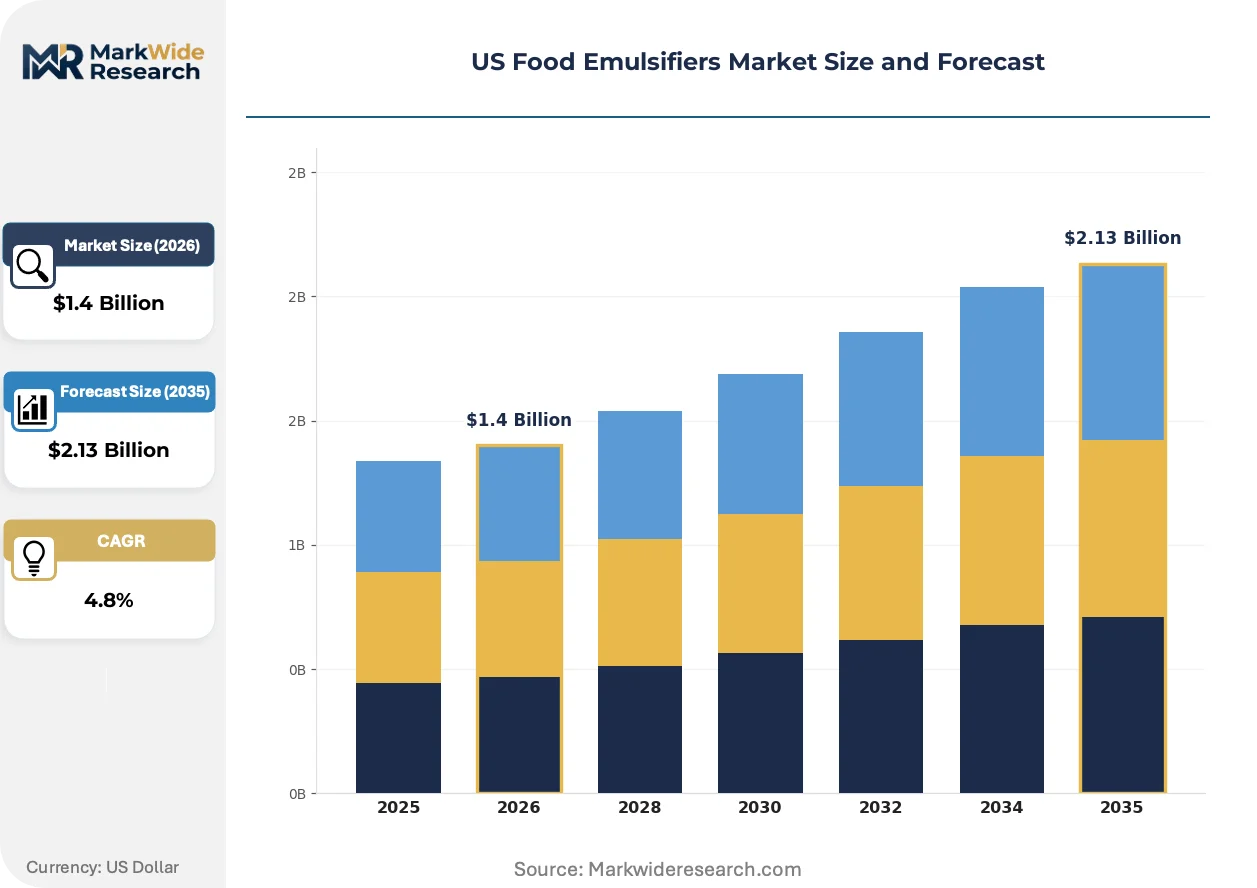
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mono- and Diglycerides, Lecithin, Polysorbates, Sorbitan Esters Application: Bakery Products, Dairy Alternatives, Sauces, Confectionery Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale End User: Food Manufacturers, Bakeries, Restaurants, Home Cooks |
| Companies Covered | Cargill, Incorporated, BASF SE, Kerry Group plc, Archer Daniels Midland Company, DuPont de Nemours Inc, Ingredion Incorporated, International Flavors & Fragrances Inc, Tate & Lyle PLC, Corbion N.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Food Emulsifiers Market Evolving Landscape
Enzymatic processing platforms are restructuring competitive economics as bio-based alternatives achieve functional parity with petrochemical-derived emulsifiers across temperature-sensitive applications.
Enzymatically modified lecithin is absorbing reformulation budgets previously allocated to synthetic mono- and diglycerides as plant-based dairy processors seek non-GMO positioning without sacrificing emulsion stability. Bakery manufacturers in the Midwest corridor adopt these alternatives at accelerating pace to preempt retailer clean-label mandates. The technology is absorbing market share from conventional lecithin fractions that fail to meet refined ingredient disclosure thresholds under pending FDA guidance.
California Proposition 65 enforcement actions against food processors using refined emulsifiers with detectable processing contaminants are tightening supplier documentation requirements nationwide. The state's attorney general settlements create precedent for contaminant testing protocols that exceed federal minimums. Plant-based dairy alternative producers in California processing clusters now require third-party certified emulsifier supply chains, forcing national suppliers to upgrade testing infrastructure or exit premium positioning tiers.
Direct procurement relationships between emulsifier suppliers and plant-based dairy alternative brands are displacing traditional distributor intermediaries as formulation complexity demands technical collaboration. Ingredient bundling contracts now specify integrated taste-texture system development rather than commodity spot purchasing. This pattern concentrates most visibly in Illinois and Iowa processing clusters where Cargill's captive grain supply enables vertically coordinated emulsifier-lecithin-flavor offerings that distributors cannot replicate.
US Food Emulsifiers Market Segmentation
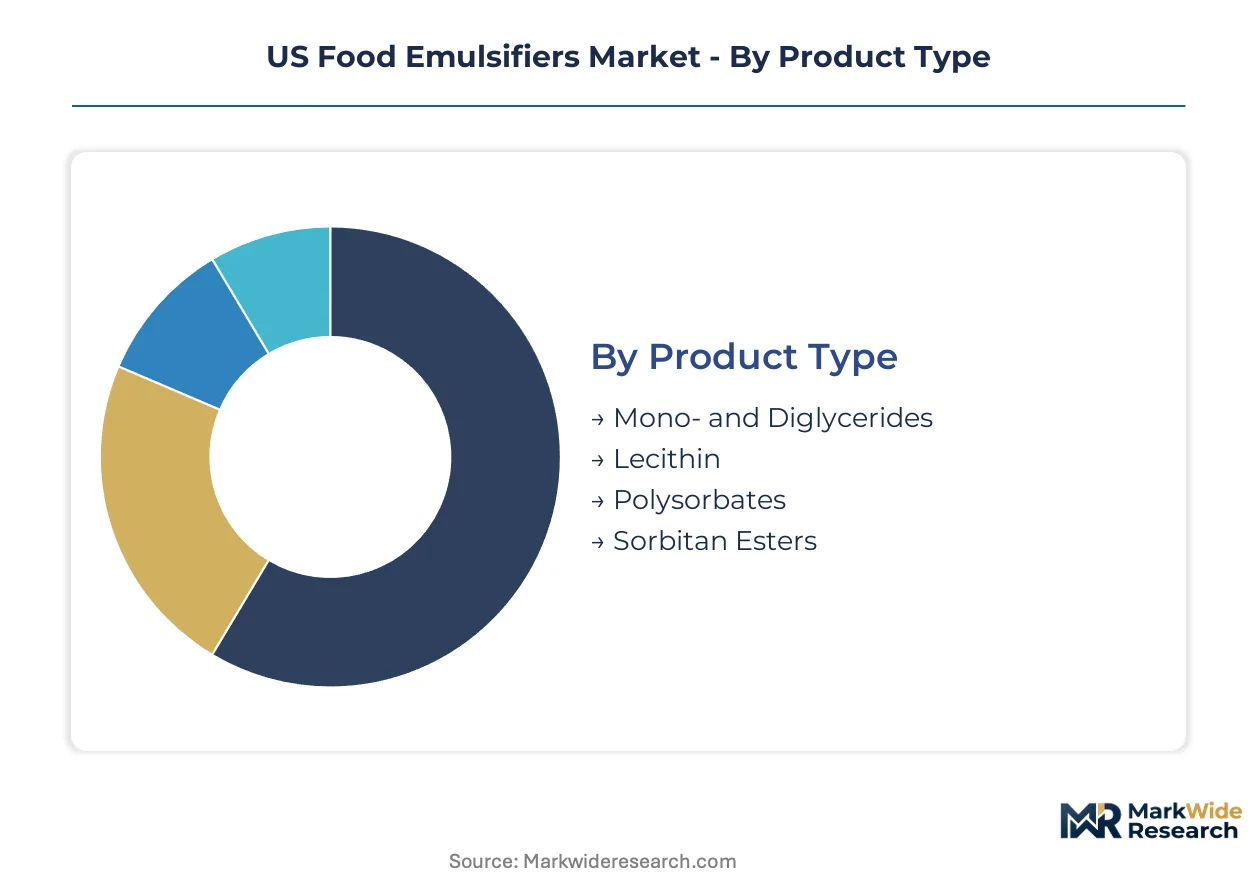
Emulsifier procurement patterns diverge sharply between commodity bulk buyers and specialized formulators seeking certified-clean supply chains. The US market fragments across four structural dimensions where specification requirements, channel economics, and end-user technical capabilities reshape supplier priorities.
Product Type:
Standardization dominates synthetic-derived segments while enzymatically modified and naturally extracted variants command customization premiums tied to certification depth.
- Mono- and Diglycerides:Glycerol esters of fatty acids produced through glycerolysis of triglycerides deliver cost-efficient interfacial tension reduction across high-volume bakery applications. Demand concentrates in Midwest manufacturing corridors where Illinois and Iowa processors prioritize unit economics over clean-label positioning for conventional bread and bun production.
- Lecithin:Phospholipid complexes extracted from soybean, sunflower, or egg yolk provide multifunctional emulsification with non-GMO and allergen-free certification tiers. California plant-based dairy alternative producers drive specification intensity here, requiring third-party contaminant testing that exceeds FDA minimums under Proposition 65 enforcement patterns.
- Polysorbates:Ethoxylated sorbitan esters retain specialized roles in confectionery coatings where thermal stability above 120°C excludes natural alternatives.
- Sorbitan Esters:Lipophilic surfactants derived from sorbitol dehydration serve niche applications in fat-based systems requiring HLB values below 8.
Leading the category by volume: Mono- and Diglycerides. Growing fastest: Lecithin.
Application:
Reformulation pressure intensity escalates from shelf-stable categories toward refrigerated plant-based alternatives where emulsion failure carries premium spoilage costs.
- Bakery Products:Bread, cake, and pastry applications leverage emulsifiers for dough conditioning, crumb softening, and shelf-life extension. Midwest and Southeast manufacturing corridors absorb the bulk of clean-label reformulation activity as retailers impose certification requirements on private-label suppliers.
- Dairy Alternatives:Oat, almond, and soy milk processors require emulsifier systems that stabilize fat-protein interactions through thermal processing and extended refrigerated distribution. California processing clusters set specification benchmarks that propagate nationally.
- Sauces:Mayonnaise, dressings, and condiment applications demand freeze-thaw stability and acid tolerance that constrain natural emulsifier substitution rates.
- Confectionery:Chocolate coatings and fat-based centers rely on synthetic emulsifiers where melt point control and bloom resistance override clean-label preferences.
Dairy Alternatives impose the steepest specification escalation. Bakery Products anchor volume absorption.
Distribution Channel:
Channel selection correlates with buyer technical sophistication and volume scale, fragmenting supplier engagement models between transactional and collaborative relationships.
- Wholesale:Bulk ingredient distributors serving food manufacturers with established formulation capabilities dominate tonnage movement through Illinois and Iowa grain processing corridors.
- Online Retail:E-commerce platforms capture specialty and small-batch producers seeking certified organic or non-GMO emulsifiers with documented supply chain transparency.
- Supermarkets:Mass retail channels supply home bakers and small commercial kitchens through repackaged consumer formats with limited technical support.
- Specialty Stores:Regional distributors serving artisan bakeries and restaurants emphasize local sourcing claims and expedited delivery for time-sensitive production schedules.
Wholesale channels concentrate supply relationships. Online Retail expands fastest among emerging plant-based brands.
End User:
Technical co-development requirements separate industrial-scale buyers from price-sensitive segments where emulsifier selection follows standard specification sheets.
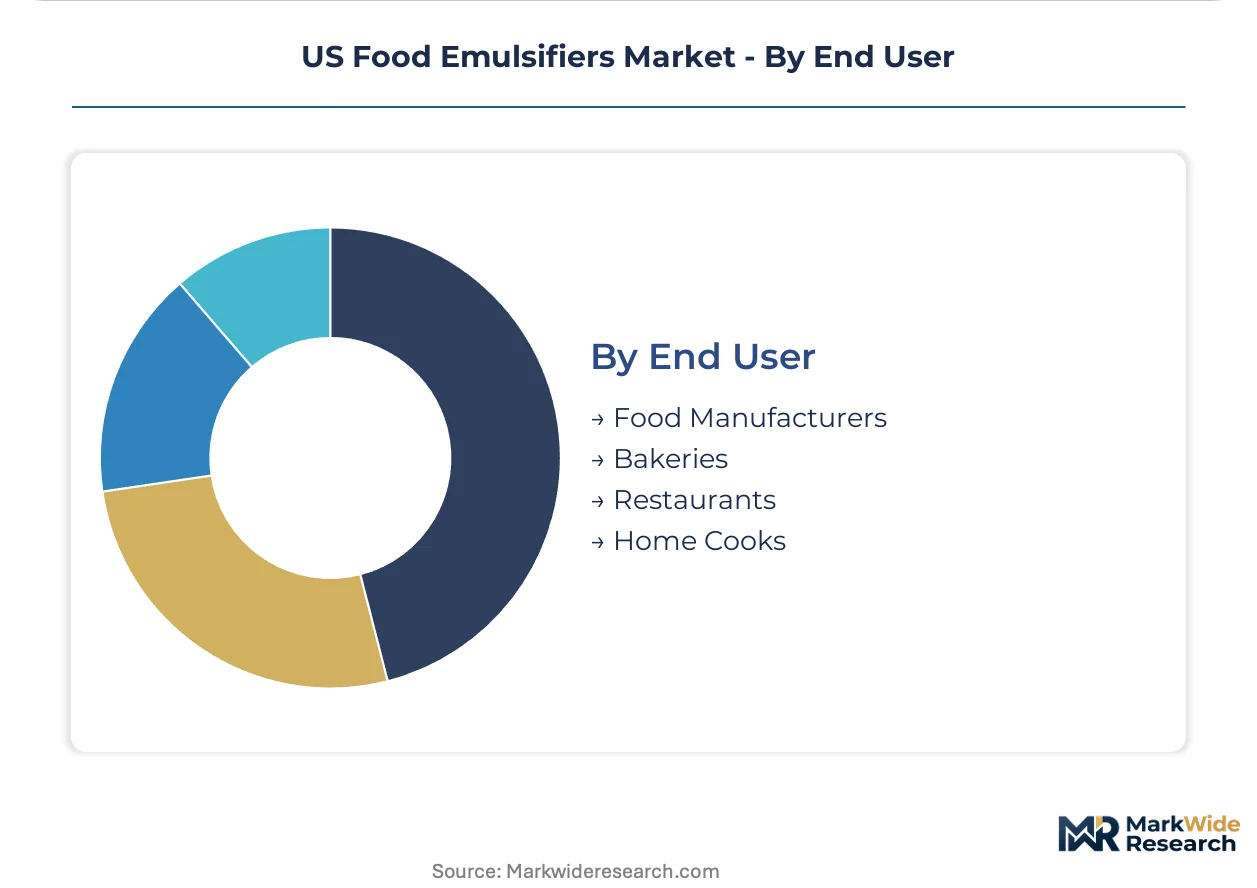
- Food Manufacturers:National processors operating integrated R&D facilities demand bundled taste-texture systems with emulsifier-flavor co-development and regulatory documentation packages.
- Bakeries:Regional and artisan operations prioritize consistent performance across variable ingredient inputs, driving preference for established mono- and diglyceride formulations with broad tolerance windows.
- Restaurants:Commercial kitchen and commissary operators source through foodservice distributors with emphasis on cost control and supply reliability over certification depth.
- Home Cooks:Consumer segment purchases emulsifiers as components of baking mixes or specialty ingredients, with minimal technical specification engagement.
Food Manufacturers command supplier R&D allocation. Bakeries represent the largest addressable base by establishment count.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest Opportunity Zones concentrating grain processing infrastructure anchor domestic emulsifier production capacity. Illinois and Iowa processing corridors generate the majority of lecithin and oilseed-derived emulsifier output. California's Proposition 65 enforcement patterns propagate specification requirements nationally.
Illinois
Decatur's integrated oilseed complex dominates glycerol ester and lecithin production volume. EPA bio-based procurement preferences redirect capital toward enzymatic modification platforms at existing facilities. Chicago-area food manufacturers demand bundled taste-texture systems with integrated regulatory documentation packages.
Iowa
Soybean harvest yields and export demand cycles directly influence lecithin input costs for regional suppliers. USDA organic certification programs expand premium positioning opportunities for non-GMO phospholipid processors. Cedar Rapids processing clusters absorb clean-label reformulation demand from Midwest bakery manufacturers.
California
Plant-based dairy alternative producers in Los Angeles and Bay Area processing clusters set contaminant testing benchmarks exceeding FDA minimums. State attorney general settlements against refined emulsifier users force third-party certification requirements. Sacramento regulatory pressure propagates disclosure standards to national suppliers serving California brands.
Texas
Houston petrochemical corridors supply synthetic emulsifier precursors for confectionery and industrial applications. State environmental permitting frameworks accommodate expanded microbial fermentation capacity for bio-based alternatives. Dallas-Fort Worth distribution hubs consolidate Southwest regional supply chains for bakery and dairy processors.
New York
Metropolitan food manufacturers drive specification intensity for clean-label emulsifiers in premium positioning tiers. State-level contaminant disclosure legislation mirrors California Proposition 65 enforcement patterns. Hudson Valley specialty ingredient distributors serve artisan bakery segments with documented supply chain transparency requirements.
US Food Emulsifiers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct capability tiers. The market structures around three archetypes: integrated agribusinesses with captive grain supply, ingredient bundlers combining emulsifiers with flavor systems, and specialty phospholipid processors. Dominant competitive moves include enzymatic platform investments and direct procurement relationships displacing distributor intermediaries.
Among Midwest-based integrated agribusinesses, Cargill, Incorporated and Archer Daniels Midland Company exemplify the grain-captive supply archetype. Kerry Group plc occupies a position within the taste-texture bundling tier. These three anchors represent distinct strategic postures: upstream control over oilseed inputs, integrated formulation development, and co-development service models respectively.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| BASF SE |
| Kerry Group plc |
| Archer Daniels Midland Company |
| DuPont de Nemours Inc |
| Ingredion Incorporated |
| International Flavors & Fragrances Inc |
| Tate & Lyle PLC |
| Corbion N.V. |
| Others |
Value Network & Pricing Analysis
National food manufacturers operating integrated R&D facilities command contract-based pricing with volume-commitment discounts, while smaller Midwest bakeries absorb spot-market volatility in lecithin fractions. This buyer-tier stratification concentrates pricing power among grain-captive suppliers with enzymatic modification capabilities.
Pricing Analysis
Short lead-time premiums apply to enzymatically modified lecithin shipments for California plant-based dairy processors facing Proposition 65 compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels separates certified-organic phospholipids from conventional soy-derived fractions and synthetic mono-and-diglyceride commodities. Cost compression in standard-grade lecithin is intensifying because Illinois and Iowa harvest volatility feeds directly into input cost structures. Food manufacturers with annual offtake agreements exhibit lowest price sensitivity, while regional bakeries purchasing through distributors face highest exposure to spot-market swings.
Supply Chain Analysis
Direct-to-manufacturer channels handle national food processor demand, bypassing traditional distributors as formulation complexity demands technical collaboration. Domestic production draws from Illinois, Iowa, and California processing clusters, with Illinois anchoring oilseed-derived emulsifier output and California setting contaminant-testing benchmarks. Raw material flows hinge on Midwest soybean harvest yields, sunflower seed imports, and synthetic precursor supplies from Texas petrochemical corridors. Single-complex concentration at Decatur, Illinois creates geographic vulnerability to localized disruption. Distribution runs through captive grain networks for integrated agribusinesses and independent distributors for specialty phospholipid processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US food emulsifiers market sits in a technology-transition phase as enzymatic modification platforms displace conventional glycerolysis for clean-label positioning. Microbial fermentation and cell-culture derived phospholipids are absorbing R&D budgets previously allocated to petrochemical-derived alternatives.
For Market Incumbents: Extend enzymatic platform investments to defend margin position against microbial-fermentation entrants. Backward integration into captive grain supply secures input cost stability across Illinois and Iowa corridors. Certification infrastructure for California Proposition 65 compliance creates switching costs that lock in national food manufacturer accounts. For New Entrants and Emerging Players: Capture white-space in microbial-derived phospholipids bypassing agricultural input constraints. California plant-based dairy alternative producers represent the most penetrable segment given their third-party certification requirements and willingness to pay premium positioning prices. Direct procurement relationships with technical co-development clauses offer the strongest go-to-market angle against established distributor networks. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty phospholipid processors with established contaminant-testing protocols in California processing clusters. Long-term viability over a multi-year horizon rests on enzymatic modification capabilities and regulatory documentation infrastructure. The signal to watch is FDA guidance on refined ingredient disclosure thresholds forcing portfolio restructuring among synthetic-emulsifier dependent suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Platform Investment | Enables clean-label positioning for plant-based dairy applications under California Proposition 65 enforcement. |
| Backward Integration into Grain Supply | Cargill's captive soybean network anchors cost stability across Illinois and Iowa processing corridors. |
| Certification Infrastructure Buildout | Third-party contaminant testing exceeds FDA minimums for premium positioning in California clusters. |
| Direct Procurement Relationships | Bundled taste-texture contracts displace distributor intermediaries for national food manufacturers. |
| Microbial Fermentation Capacity | Cell-culture derived phospholipids bypass agricultural input volatility while satisfying clean-label requirements. |
Research Methodology
Trade databases, SEC filings, and FDA food additive petitions formed the secondary backbone for supply-side capacity assessment and regulatory pathway mapping. Primary interviews with emulsifier R&D directors, plant-based dairy procurement leads, Midwest grain processing managers, and California regulatory affairs specialists validated functional performance claims and certification requirements. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against end-use application demand anchored the analytical framework.
Bottom-up modeling of enzymatically modified lecithin, conventional phospholipids, and synthetic glycerol ester segments fed into application-level aggregation across bakery, dairy alternatives, sauces, and confectionery categories. CAGRs were derived from regression analysis of historical volume trends and forward projection of plant-based dairy expansion rates, clean-label reformulation timelines, and EPA bio-based procurement preference implementation. Input variables included Illinois and Iowa soybean harvest yield forecasts, California Proposition 65 enforcement patterns, and enzymatic modification technology adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA labeling modernization timing and microbial fermentation scale-up economics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Food Texturants Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
Antimicrobial Packaging Ingredients for Food Packaging Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Ph Adjuster Market
Food Additives and Ingredients
Beverage Clarifier and Stabilizer Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Leavening Acids Market
Food Additives and Ingredients
Food Supplement Ingredients Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Global Food Grade Calcium Chloride Market
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market