
 Global Crystalline Maltitol Market | 2026-2036
Global Crystalline Maltitol Market Size, Share, and Industry Trends Forecast 2026-2036
Global Crystalline Maltitol Market Analysis
ISO 22000 certification is unwinding competitive access for crystalline maltitol suppliers lacking integrated food safety management systems. Cargill leverages its global grain sourcing network to secure feedstock cost advantages for hydrogenation and crystallization stages. Roquette sustains European production leadership through decades of polyol refining expertise and pharma-grade qualification pathways. Shandong Bailong Chuangyuan Bio-Tech anchors Asia-Pacific supply with captive starch processing and regional distribution density.
Crystalline maltitol is a hydrogenated disaccharide alcohol derived from maltose, typically manufactured through catalytic hydrogenation of starch hydrolysates followed by crystallization to achieve purity above 98.5% and a melting point near 146-150°C, functioning primarily as a bulk sweetener with approximately 90% sucrose sweetness and negligible glycemic impact. The confectionery end-user segment dominates value capture due to chocolate and chewing gum applications requiring precise tempering behavior and cooling sensation control. Crystalline maltitol powder leads product-type margins because spray-drying and controlled crystallization yield superior flow properties for direct compression tableting in pharmaceutical and sugar-free candy formats.
FDA GRAS status for maltitol under 21 CFR 184.1835 shapes US formulation decisions, while EFSA's 2015 scientific opinion on laxative thresholds for polyols governs European product labeling and daily intake guidance. China's NMPA and national food safety standards under SAMR enforce purity specifications for maltitol used in functional foods and diabetic-targeted products. Stakeholders must monitor evolving WHO guidelines on sugar reduction targets and corresponding national implementation frameworks that will determine regional demand acceleration for crystalline maltitol alternatives.
Market Dynamics
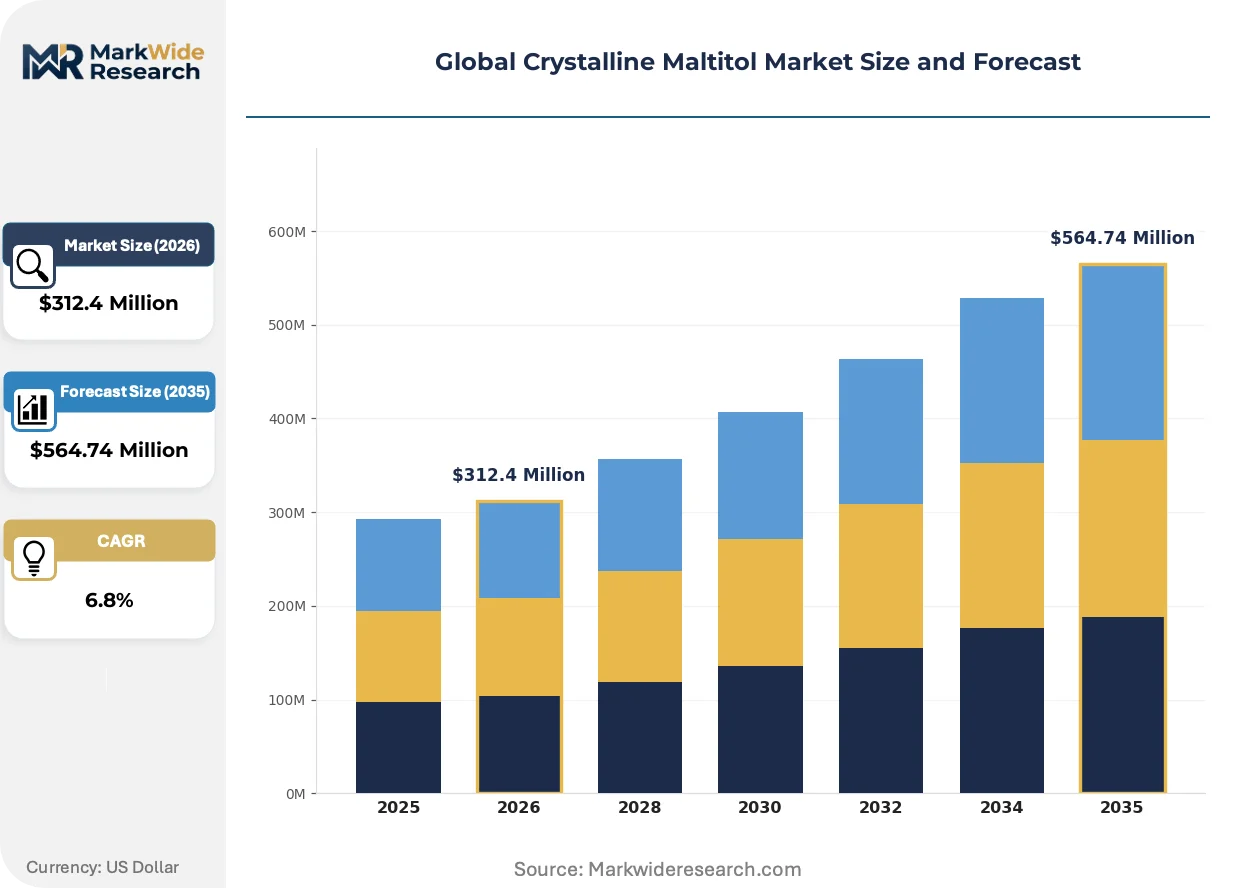
Clean-label formulation mandates and EFSA polyol labeling guidance are compressing sucrose substitution timelines across European and North American food processing clusters, forcing crystalline maltitol suppliers to accelerate pharma-grade qualification pathways.
Growth Catalysts
- EFSA Laxative Threshold Guidance:European food safety standards now require explicit polyol intake labeling, accelerating maltitol adoption in portion-controlled confectionery formats.
- Diabetic-Targeted Functional Foods:China's SAMR enforcement of purity specifications for sugar-reduction claims is pulling crystalline grades into domestic pharma-food crossover applications.
- Biotech Fermentation Scale-Up:Integrated starch-to-maltitol processing in Shandong and Jiangsu provinces is compressing production costs for 98.5%+ purity crystalline grades.
Market Restraints
- Feedstock Cost Volatility:Wheat and corn starch price swings directly hydrogenation economics, squeezing margin structures for non-integrated maltitol refiners.
- Supply Concentration Risk:Asia-Pacific crystallization capacity clusters in eastern Chinese provinces, creating single-geography exposure for global confectionery formulators.
- Technical Cooling Limitation:Maltitol's endothermic dissolution profile limits dosage rates in chocolate tempering below sucrose replacement thresholds.
Strategic Opportunities
- Underpenetrated Latin American Markets:Brazil's ANVISA regulatory harmonization with CODEX standards is opening formulation pathways for sugar-free hard candy exports.
- Pharmaceutical Direct Compression:Excipient-grade crystalline powder specifications for tablet manufacturing remain undersupplied outside European qualified facilities.
- WHO Sugar Reduction Mandates:National implementation frameworks in Gulf Cooperation Council states are mandating reformulation timelines for processed foods.
Industry Challenges
- ISO 22000 Certification Timeline:Food safety management system audits for crystallization facilities average 14-18 months, blocking market access for new entrants.
- Hydrogenation Reactor Capex Intensity:High-pressure catalytic equipment for maltose reduction requires specialized pressure-vessel compliance exceeding standard chemical plant investment.
- Polyol Patent Licensing Complexity:Crystallization process IP held by legacy European and Japanese filers creates royalty stacking for spray-drying technology adopters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Crystalline Maltitol Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crystalline Maltitol, Liquid Maltitol, Maltitol Syrup, Maltitol Powder End User: Food & Beverage, Pharmaceutical, Personal Care, Confectionery Application: Baking, Candy Manufacturing, Dietary Products, Beverages Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Shandong Bailong Chuangyuan Bio-Tech, SPI Polyols, Cargill, Ingredion, Towa Chemical Industry, Roquette, Shandong Lujian Biological Technology, Futaste, Mitsubishi Shoji Foodtech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Crystalline Maltitol Market Emerging Trajectories
Continuous crystallization control systems and membrane filtration advances are compressing impurity profiles while enabling real-time process adjustment, fundamentally altering how maltitol refiners compete on specification consistency.
Continuous chromatographic separation technology is miniaturizing downstream purification footprints. Mid-scale confectionery manufacturers in Poland and Mexico are adopting skid-mounted systems previously restricted to integrated biorefineries. This equipment compression is enabling distributed crystallization nodes that bypass traditional bulk-shipping economics for high-purity grades.
REACH registration requirements for hydrogenation catalysts are forcing substitution from nickel-based to ruthenium-based systems in European production facilities. The catalyst transition extends batch cycle times but eliminates residual metal contamination risks for pharma-grade output. German and Dutch refiners are absorbing these process changes ahead of 2026 re-authorization deadlines.
Specification-driven procurement now dominates bulk sweetener purchasing for multinational confectionery chains. Buyers are unbundling supplier qualification from volume contracting, creating parallel vendor pools for standard versus pharma-grade crystalline maltitol. This bifurcation is most visible in Swiss and Belgian chocolate manufacturing clusters where tempering performance guarantees carry premium pricing.
Global Crystalline Maltitol Market Segmentation
Crystalline maltitol specifications diverge sharply across end-use certifications, with pharma-grade and food-grade pathways demanding separate hydrogenation and crystallization protocols. Segmentation strategy must align purity thresholds against regulatory frameworks in target markets.
Product Type:
EFSA's polyol labeling requirements and FDA GRAS specifications under 21 CFR 184.1835 create divergent purity mandates that reshape supplier qualification across crystalline versus liquid formats.
- Crystalline Maltitol:Hydrogenated disaccharide alcohol achieving 98.5%+ purity through controlled crystallization with melting point specification of 146-150°C. Chocolate manufacturers in Belgium and Switzerland specify this grade for precise tempering behavior in sugar-free formulations. EMA pharmacopeia compliance opens pharmaceutical excipient channels.
- Liquid Maltitol:Aqueous solution maintaining 70-75% solids content with reduced crystallization tendency. Beverage formulators in Germany and Japan favor this format for seamless integration into reduced-sugar drink bases without heating stages.
- Maltitol Syrup:Partially hydrogenated starch hydrolysate with broader saccharide distribution. Industrial bakeries in France leverage cost positioning for bulk cake and pastry applications.
- Maltitol Powder:Spray-dried amorphous or crystalline particulate engineered for direct compression tableting. Excipient specifications for tablet manufacturing in India and the US drive qualification investments.
Crystalline Maltitol handles the majority of throughput; Maltitol Powder is expanding most quickly on share.
End User:
Customer procurement patterns split between multinational chains demanding audit-ready certification and regional processors prioritizing unit economics over documentation depth.
- Confectionery:Sugar-free chocolate and chewing gum applications requiring cooling sensation control and precise tempering curves. Swiss and Belgian manufacturers specify crystalline grades with guaranteed particle size distribution for enrobing operations.
- Food & Beverage:Broad reformulation category spanning bakery, dairy, and beverage sectors. Clean-label mandates in the UK and Germany accelerate sucrose substitution in yogurts and ice creams.
- Pharmaceutical:Excipient-grade specifications for chewable tablets and sugar-free syrups. USP-NF and EP compliance requirements limit qualified supplier pools.
- Personal Care:Toothpaste and oral care formulations leveraging non-cariogenic properties. South Korean and Japanese cosmetic manufacturers specify low-moisture grades for stability.
Confectionery commands the dominant revenue position; Pharmaceutical climbs the fastest on margin expansion.
Application:
Process temperature tolerance and water activity requirements determine grade selection across thermal versus ambient manufacturing stages.
- Candy Manufacturing:Hard candy and chocolate applications demanding precise thermal behavior. Italian and Spanish producers specify crystalline maltitol for pulled sugar alternatives in traditional confectionery formats.
- Baking:Maillard reaction limitations require adjusted formulation protocols. German industrial bakeries integrate maltitol syrups for moisture retention in reduced-sugar cakes.
- Dietary Products:Diabetic-targeted and weight-management formulations. China's SAMR enforcement of purity specifications shapes domestic functional food development.
- Beverages:Solubility and stability requirements in reduced-sugar drinks. Japanese beverage conglomerates specify liquid maltitol for RTD tea and coffee applications.
Candy Manufacturing processes the greatest volume; Dietary Products gains share fastest on health claim expansion.
Distribution Channel:
Supply chain configuration separates bulk industrial procurement from specification-intensive spot purchasing for qualified grades.
- Wholesale:Tanker and bulk bag logistics serving integrated food manufacturers. Rotterdam and Hamburg port clusters anchor European distribution for crystalline grades.
- Specialty Stores:Ingredient distributors serving artisanal and mid-scale confectioners. Paris and Milan specialty chemical distributors stock pharma-qualified inventory.
- Supermarkets:Consumer-packaged formats for home baking and small-scale food service. Limited penetration outside Japanese and South Korean retail markets.
- Online Retail:Emerging channel for specialty grades and documentation packages. Alibaba and specialty chemical platforms serve SME formulators in China and Southeast Asia.
Wholesale manages the dominant flow; Online Retail shows steepest expansion trajectory on procurement digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and SAMR enforcement of purity specifications are pulling crystalline maltitol capacity expansion toward integrated starch-processing clusters. National sugar-reduction frameworks in Germany, Switzerland, and Belgium are compressing reformulation timelines for confectionery exporters.
China
Domestic biotech fermentation scale-up in Shandong and Jiangsu provinces is compressing production costs for 98.5%+ purity grades. SAMR's enforcement of national food safety standards for diabetic-targeted functional foods mandates crystalline specifications. The Yangtze River Delta processing corridor anchors integrated supply chains linking captive starch refining to downstream confectionery manufacturing.
Germany
REACH re-authorization deadlines for hydrogenation catalysts are forcing ruthenium-based system transitions ahead of 2026. EFSA's polyol labeling guidance accelerates portion-controlled confectionery reformulation. The North Rhine-Westphalia chemical cluster hosts specialized refineries serving Swiss and Belgian chocolate manufacturers with pharma-grade qualification pathways.
United States
FDA GRAS status under 21 CFR 184.1835 shapes bulk sweetener procurement for sugar-free chocolate and chewing gum. Clean-label formulation mandates from major retail chains drive sucrose substitution in yogurt and ice cream segments. Midwest grain-processing corridors supply feedstock for hydrogenation economics, though domestic crystallization capacity remains limited relative to demand.
Switzerland
Swissmedic pharmacopeia compliance requirements limit qualified supplier pools for pharmaceutical excipient applications. Precision tempering performance guarantees in chocolate manufacturing command premium pricing for crystalline grades with guaranteed particle size distribution. The Lake Geneva biotech corridor concentrates formulation R&D for diabetic-targeted functional foods.
Japan
METI guidelines on processed food sugar content are mandating reformulation timelines for traditional confectionery formats. PMDA oversight of pharmaceutical excipients creates parallel qualification pathways for direct compression tableting grades. The Kansai industrial belt maintains specialized demand for low-moisture crystalline specifications in oral care and cosmetic applications.
Global Crystalline Maltitol Market Vendor Landscape
Player mix skews toward integrated biorefiners with captive starch supply and regional distribution density. Three archetypes dominate: Asia-Pacific fermentation specialists with backward integration into agricultural feedstock, European polyol refiners leveraging decades of pharma-grade qualification expertise, and North American grain processors optimizing hydrogenation economics through global sourcing networks. Competitive moves concentrate on ISO 22000 certification acceleration and continuous crystallization technology licensing.
Within the integrated biorefiner tier, Shandong Bailong Chuangyuan Bio-Tech and Shandong Lujian Biological Technology represent Chinese fermentation specialists with provincial clustering advantages. Roquette occupies a position exemplifying European polyol refining expertise and EMA pharmacopeia compliance pathways. Cargill anchors the grain-processor archetype with Midwest feedstock access and global hydrogenation network scale.
| Leading Market Players |
|---|
| Shandong Bailong Chuangyuan Bio-Tech |
| SPI Polyols |
| Cargill |
| Ingredion |
| Towa Chemical Industry |
| Roquette |
| Shandong Lujian Biological Technology |
| Futaste |
| Mitsubishi Shoji Foodtech |
| Others |
Supply Flow & Price Mechanics
Fourteen-to-eighteen-month ISO 22000 certification timelines crystallize supplier scarcity into pricing power for qualified crystalline maltitol refiners, compressing procurement options for multinational confectionery chains while elevating spot premiums for pharma-grade inventory.
Pricing Analysis
Certification level creates the primary spread across crystalline maltitol tiers, with EMA pharmacopeia-compliant grades commanding substantial premiums over standard food-grade specifications. Three-tier pricing structure across premium, standard, and economy levels reflects purity thresholds, with 98.5%+ crystalline grades priced distinctly from liquid formats and maltitol syrups. Pricing pressure stems from feedstock volatility in wheat and corn starch markets, squeezing margin structures for non-integrated hydrogenation operators. Regional processors and mid-scale confectioners exhibit highest price sensitivity, while Swiss and Belgian chocolate manufacturers prioritize tempering performance guarantees over unit cost.
Supply Chain Analysis
China anchors global crystalline maltitol crystallization capacity through integrated starch-processing clusters in Shandong and Jiangsu provinces, with secondary refining presence in Germany and the Netherlands. Production draws from captive corn and wheat starch feedstocks, ruthenium-based hydrogenation catalysts, and continuous chromatographic separation equipment. Single-geography concentration in eastern Chinese provinces creates structural vulnerability for global confectionery formulators dependent on qualified supply. Distribution runs through Rotterdam and Hamburg port clusters for European downstream access, with bulk tanker and bag logistics serving integrated food manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate substitution pressure from allulose and monk fruit extracts in premium confectionery segments, defending crystalline maltitol's formulation advantages through technical service depth and certification barriers.
For Market Incumbents: Shield market position by accelerating ISO 22000 certification for captive crystallization facilities and deepening backward integration into agricultural feedstock sourcing. Roquette and Cargill demonstrate defensive value through decades-long EMA pharmacopeia qualification pathways that emerging Asian fermentation specialists cannot replicate rapidly. Prioritize continuous crystallization technology licensing to compress impurity profiles and sustain specification premiums against commodity-grade imports.
For New Entrants and Emerging Players: FDA GRAS fast-track pathways for maltitol excipient applications offer the most penetrable entry vector for qualified crystalline powder supply to US pharmaceutical tablet manufacturers. Target underpenetrated Latin American markets where Brazil's ANVISA regulatory harmonization with CODEX standards is opening formulation pathways for sugar-free hard candy exports. Lead with direct compression tableting specifications and documentation packages that incumbent commodity suppliers underserve.
For Investors and Strategic Acquirers: Long-term, this sits as a substitution-defense play because sugar-reduction mandates across WHO member states will sustain polyol demand even as novel sweeteners emerge. Acquisition targets should cluster around European refiners with EMA pharmacopeia compliance and ruthenium-based hydrogenation transitions already absorbed. Watch for national implementation frameworks for WHO sugar reduction targets as the primary inflection signal for regional demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Starch Feedstock | Cargill leverages Midwest grain corridors to secure hydrogenation economics against price volatility. |
| Pharma-Grade Qualification Pathway | Roquette's EMA compliance opens excipient channels for direct compression tableting applications. |
| Continuous Crystallization Technology Licensing | Real-time process control enables specification consistency that commodity refiners cannot match. |
| Ruthenium Catalyst Transition | German and Dutch refiners absorb REACH-mandated shifts ahead of 2026 re-authorization deadlines. |
| Regional Distribution Density Expansion | Shandong Bailong Chuangyuan anchors Asia-Pacific supply through Yangtze River Delta processing corridors. |
Methodological Framework
Cross-validation between primary interviews with plant managers at hydrogenation facilities and secondary analysis of customs trade data anchors the qualitative findings on supply concentration and feedstock cost dynamics. Conversations with procurement leads at Swiss and Belgian chocolate manufacturers, technical R&D directors at polyol refiners, and distribution channel partners across Rotterdam and Hamburg port clusters informed demand-side segmentation. Bottom-up volume modeling triangulates against top-down value estimates derived from SEC filings and Cefic industry reports.
Sensitivity analysis across hydrogenation reactor utilization rates, starch feedstock price bands, and certification timeline scenarios frames the projection horizon. Segmentation dimensions include crystalline versus liquid product formats, confectionery versus pharmaceutical end-use applications, and regional production hub clusters. CAGRs derive from curve-fitting historical volume trajectories against national sugar-reduction policy implementation schedules and WHO guideline adoption patterns.
The analysis sits within stated boundaries; outcomes outside sustained EFSA enforcement of polyol labeling thresholds or disruption to Chinese starch processing clusters would require recalibration. Forecasts reflect assumptions on biotech fermentation scale-up economics and ruthenium catalyst availability. Recalibration cycles align with material shifts in REACH re-authorization outcomes and SAMR purity specification enforcement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
Global Baking Powder Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
China Food Additives Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
India Food Preservatives Market
Food Additives and Ingredients
Lactylated Monoglyceride Market
Food Additives and Ingredients
Instant Fat Powder Market
Food Additives and Ingredients
Food Encapsulation Market
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
Alcohol Additives Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market