
 South Africa Food Emulsifiers Market | 2026-2036
South Africa Food Emulsifiers Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Food Emulsifiers Market Analytics
Market Context
A chronic shortage of food technologists with lipid chemistry expertise is unwinding capacity expansion plans across South African emulsifier facilities. Palsgaard leverages its application laboratory in Johannesburg to sustain technical service relationships with regional bakery chains. Cargill Incorporated anchors supply security through its oilseed processing footprint in the Western Cape. Fourchem competes on import substitution, manufacturing select emulsifier blends locally to reduce dollar-denominated raw material exposure.
Technical Definition and Segment Structure
Food emulsifiers are surface-active agents, typically comprising esterified fatty acids or phospholipid fractions, that reduce interfacial tension between immiscible phases such as oil and water in processed food matrices. These compounds stabilize texture, extend shelf life, and control fat crystallization in products ranging from margarine to aerated confectionery. Mono- and diglycerides dominate volume consumption in South Africa due to entrenched use in margarine and bread improver formulations. Lecithin commands premium positioning among clean-label product lines targeting health-conscious consumers. Powder emulsifier forms lead industrial procurement patterns for dry-mix manufacturers, while liquid formats retain importance in large-scale dairy and sauce operations.
Regulatory Framework and Outlook
The Department of Health's food additive regulations, aligned with Codex Alimentarius principles, govern maximum usage levels and labeling requirements for emulsifiers in South Africa. BIS-equivalent SANS standards and FSSAI-referenced import protocols shape compliance costs for international suppliers entering the market. SEBI-listed parent companies of major suppliers must additionally navigate disclosure requirements for environmental and governance risks in their South African operations. Stakeholders should monitor pending amendments to the country's food labeling regulations and the pace of local HACCP certification adoption among mid-tier manufacturers.
Market Dynamics
The South Africa Food Emulsifiers Market pivots on chronic food technologist shortages, which compress capacity expansion timelines and force manufacturers toward automated formulation platforms and regional technical service partnerships.
Growth Catalysts
- Clean-label formulation mandates:South Africa's Department of Health food additive regulations are accelerating reformulation toward lecithin and plant-derived emulsifier systems in premium bakery lines.
- Gauteng-KwaZulu-Natal manufacturing corridor expansion:Industrial clustering around Johannesburg-Pretoria zones concentrates demand for powder emulsifiers in dry-mix operations.
- Import substitution programs:Local blending capabilities for mono- and diglycerides reduce dollar-denominated raw material exposure and shorten lead times for regional margarine producers.
Market Restraints
- Palm oil price volatility:Fatty acid feedstock costs swing with Malaysian and Indonesian export policy shifts, squeezing margin predictability for emulsifier compounders.
- Western Cape supply concentration:Oilseed processing infrastructure clusters heavily in this province, creating geographic single-point vulnerability for domestic lecithin sourcing.
- HACCP certification bottlenecks:Mid-tier manufacturers face 12-18 month compliance timelines, delaying market entry and freezing out smaller compounders.
Strategic Opportunities
- Free State agricultural processing:Underdeveloped emulsifier demand in this grain belt region offers first-mover positioning for technical service-led market development.
- Plant-based dairy alternatives:Oat and almond milk formulation requirements are opening novel application vectors for stabilizer-emulsifier hybrid systems.
- SANS standards harmonization:Alignment with Codex Alimentarius principles is streamlining export qualification for regional suppliers targeting SADC markets.
Industry Challenges
- Lipid chemistry expertise scarcity:Universities produce fewer than fifty qualified food technologists annually, forcing manufacturers to poach talent or outsource R&D.
- Legacy equipment retrofit costs:Dry-mix facilities require capital-intensive pneumatic handling upgrades to process next-generation low-dust emulsifier granules.
- Labeling regulation uncertainty:Pending amendments to South Africa's food labeling requirements are freezing new product launch timelines as legal teams assess disclosure obligations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Food Emulsifiers Market |
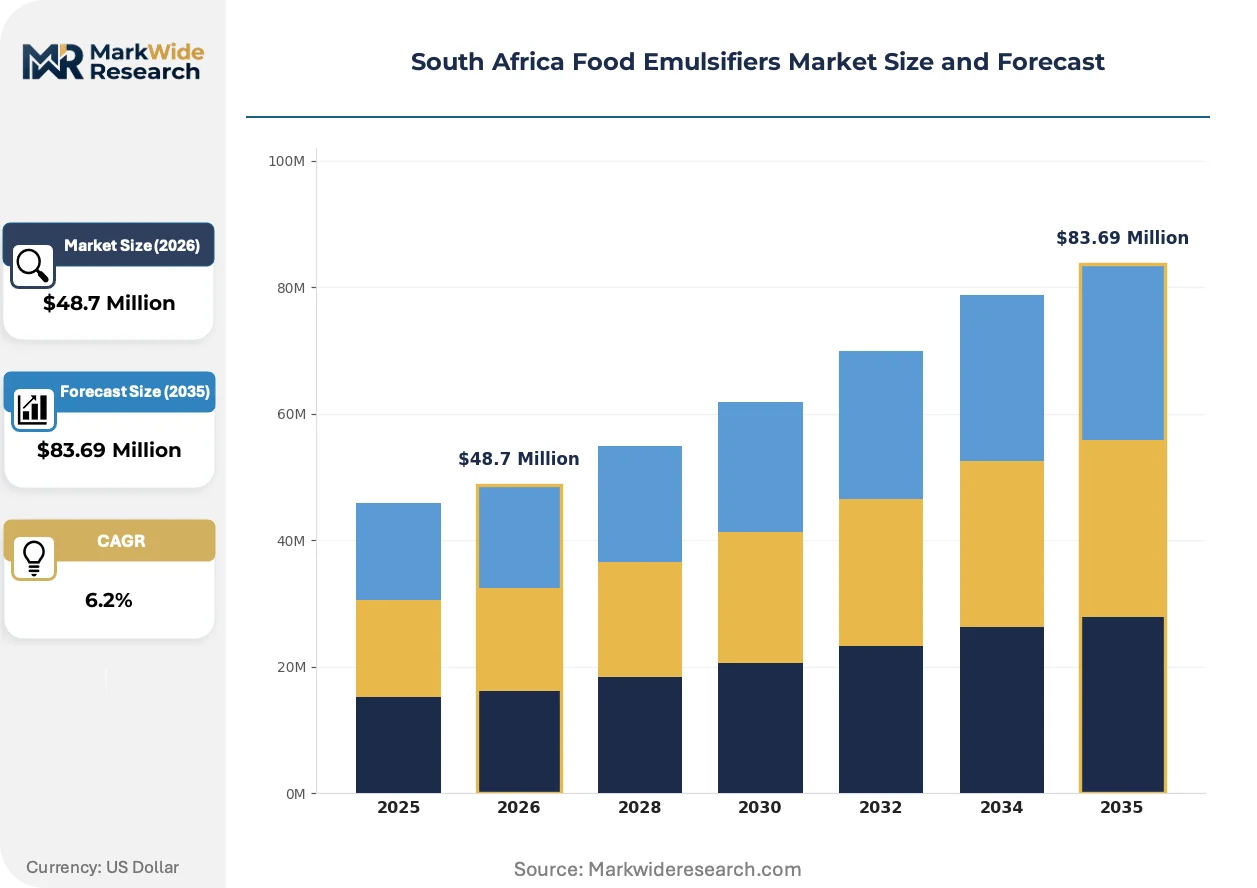
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $83.69 Million |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lecithin, Mono- and Diglycerides, Stearoyl Lactylate, Polysorbates Application: Baked Goods, Dairy Products, Sauces, Dressings Form: Liquid, Powder, Granular, Paste End User: Food Manufacturers, Bakeries, Beverage Producers, Snack Companies |
| Companies Covered | DuPont de Nemours Inc., The Dow Chemical Company, Palsgaard, ChemSystems, Fourchem, South Bakels Pty Ltd, Protea Chemicals, Cargill Incorporated, Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Food Emulsifiers Market Evolving Landscape
Enzymatic modification processes and precision fermentation platforms are displacing conventional chemical esterification, while regulatory pressure on synthetic additives accelerates natural emulsifier adoption across South African formulation labs.
Microfluidization technology for lecithin fractionation is miniaturizing. This process achieves superior phospholipid separation for clean-label applications. Specialty margarine manufacturers in the Western Cape are piloting these systems at pilot-plant scale. The technology is compressing minimum efficient scale thresholds, enabling mid-tier compounders to enter premium lecithin segments previously reserved for integrated multinationals.
Amendments to South Africa's food labeling regulations are tightening additive disclosure requirements. Manufacturers must now declare emulsifier sources and processing aids on front-of-pack panels. Premium bakery chains in Gauteng are responding by qualifying enzymatically produced mono- and diglycerides that meet simplified ingredient list standards.
Direct technical service engagement is displacing traditional distributor relationships. Large-scale food manufacturers in KwaZulu-Natal now demand on-site formulation support and joint development agreements rather than spot procurement. This behavioral shift concentrates purchasing power among suppliers with Johannesburg-based application laboratories and trained food technologist teams.
South Africa Food Emulsifiers Market Segmentation
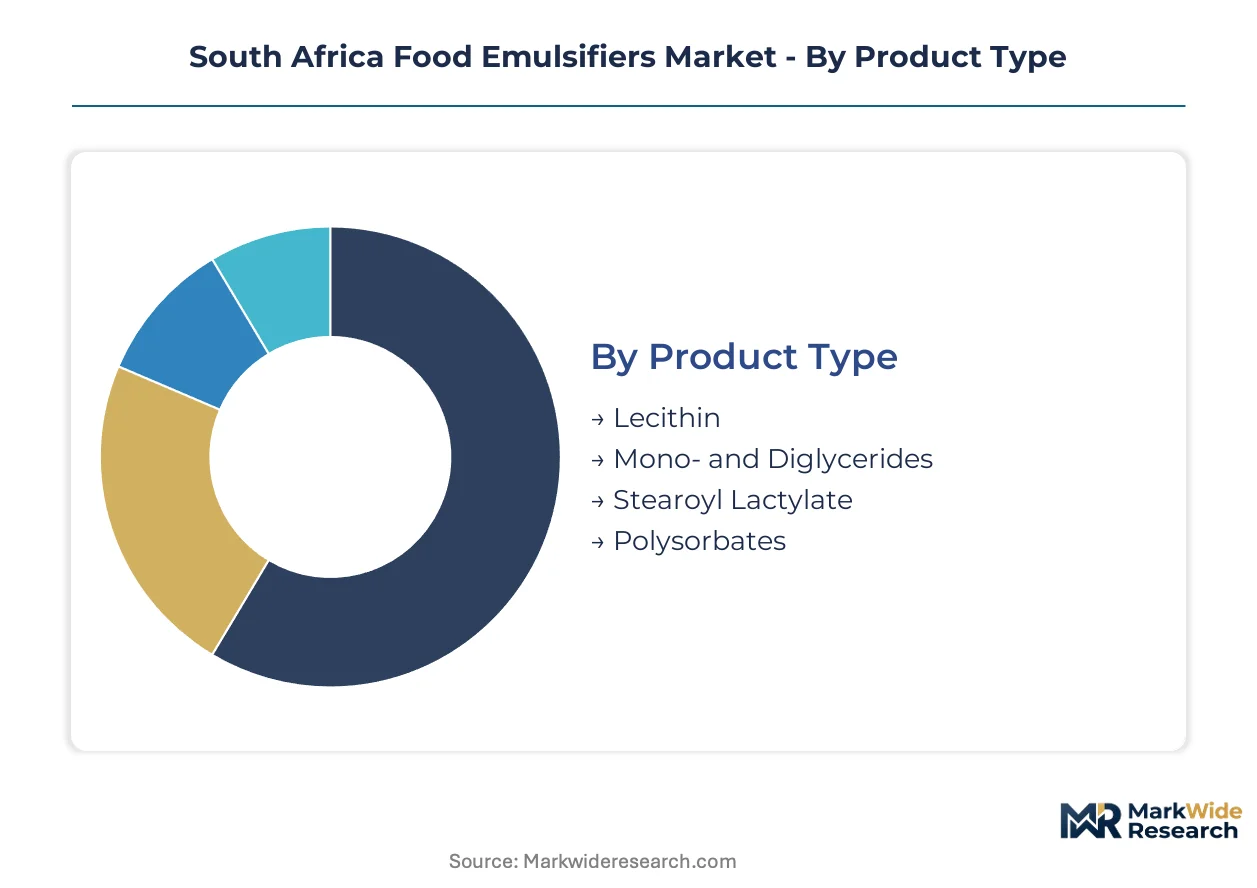
Segmentation in South Africa's food emulsifiers market reveals how regulatory pressure on clean-label formulations and geographic clustering of manufacturing capacity reshape procurement patterns across distinct product categories and end-use channels.
Product Type:
The Department of Health's food additive regulations differentiate maximum usage levels and labeling requirements across emulsifier chemistries, steering compounder portfolios toward compliant ingredient systems.
- Mono- and Diglycerides:Esterified fatty acid compounds dominate volume consumption in South African margarine and bread improver formulations. Demand concentrates in Johannesburg-Pretoria industrial zones where large-scale bakery manufacturers cluster for dry-mix operations.
- Lecithin:Phospholipid fractions extracted from oilseeds command premium positioning among clean-label product lines targeting health-conscious consumers in Gauteng premium bakery chains. Regulatory alignment with Codex Alimentarius principles accelerates adoption as manufacturers reformulate to meet simplified ingredient list standards.
- Stearoyl Lactylate:Lactic acid esters of fatty acids strengthen dough systems and extend shelf life in commercial bread production.
- Polysorbates:Sorbitan ester derivatives stabilize oil-in-water emulsions in sauce and dressing applications.
Established volume favors Mono- and Diglycerides; emerging adoption favors Lecithin.
Application:
Cost tier differentiation separates commodity-scale users from premium formulation buyers, with mid-tier manufacturers facing compressed margins between automated high-volume operations and specialized clean-label positioning.
- Baked Goods:Bread, pastry, and confectionery applications consume the largest emulsifier volumes through dough conditioning and crumb softening functions. KwaZulu-Natal manufacturing corridors expand adoption as regional bakery chains qualify enzymatically produced emulsifiers for front-of-pack compliance.
- Dairy Products:Margarine and spread formulations rely on fat crystallization control and water-in-oil emulsion stability. Western Cape oilseed processing infrastructure anchors domestic lecithin sourcing for this segment despite geographic concentration risk.
- Sauces:Dressing and condiment manufacturers utilize emulsifiers for viscosity control and phase separation prevention.
- Dressings:Mayonnaise and vinaigrette applications demand specific hydrophilic-lipophilic balance specifications for shelf-stable emulsions.
Procurement volume concentrates in Baked Goods; margin expansion concentrates in Dairy Products.
Form:
Supply chain configuration favors powder and liquid formats that align with existing handling infrastructure, while granular and paste innovations target retrofit avoidance and dust exposure reduction.
- Powder:Spray-dried emulsifier forms lead industrial procurement patterns for dry-mix manufacturers requiring precise dosing and extended shelf stability. Legacy pneumatic handling systems in Free State grain belt facilities accommodate this format without capital-intensive upgrades.
- Liquid:Fluid emulsifier concentrates retain importance in large-scale dairy and sauce operations with dedicated pumping and metering infrastructure. Cargill's Western Cape oilseed processing footprint secures supply security for liquid lecithin derivatives.
- Granular:Low-dust agglomerated particles reduce inhalation exposure and improve flow characteristics for automated dosing systems.
- Paste:Semi-solid concentrates serve niche applications requiring high-viscosity handling and minimal dust generation.
Equipment compatibility favors Powder; safety and handling innovation favors Granular.
End User:
Customer type stratification separates integrated multinationals with in-house formulation capabilities from mid-tier buyers dependent on supplier technical service partnerships.
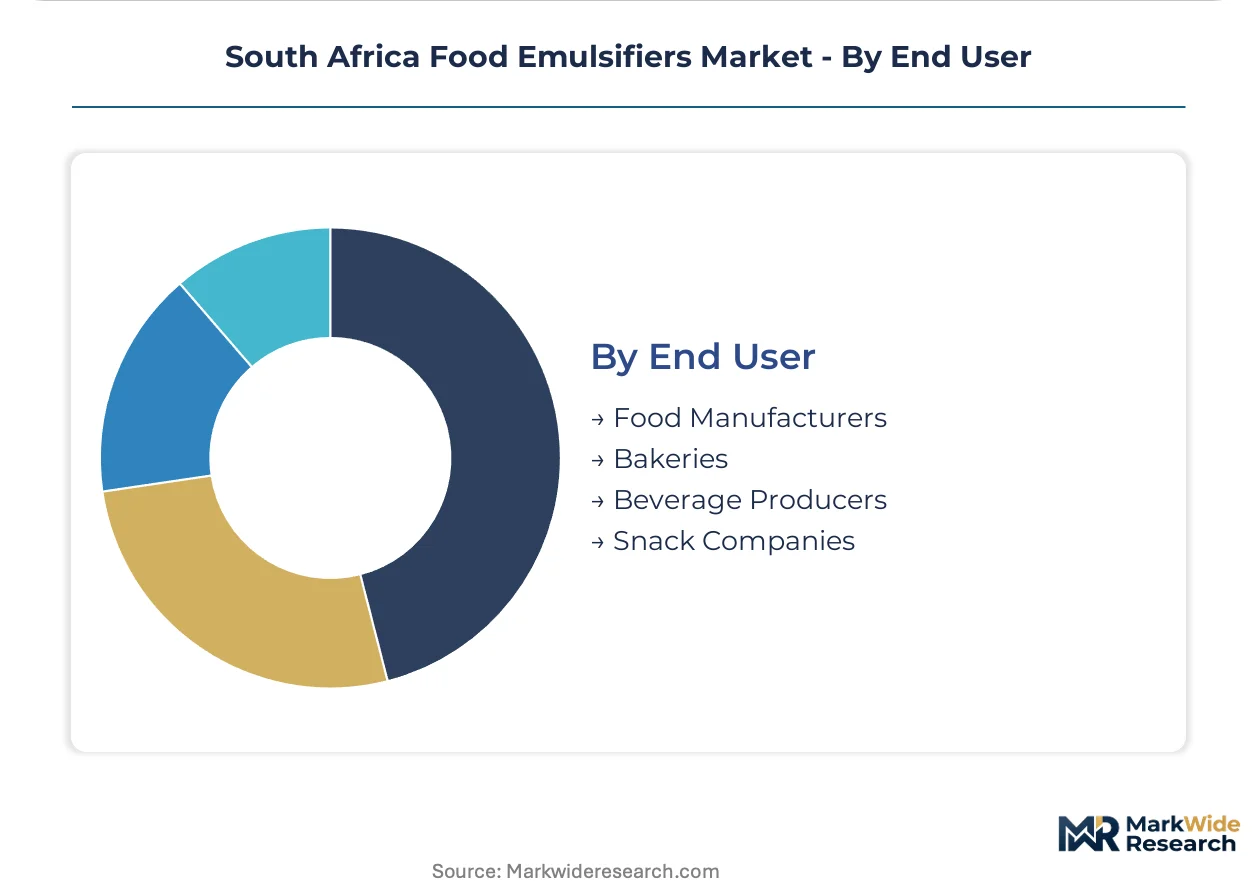
- Food Manufacturers:Integrated processing operations spanning multiple categories drive bulk procurement and joint development agreements. Direct technical service engagement from Johannesburg-based application laboratories displaces traditional distributor relationships for this segment.
- Bakeries:Regional chains and independent operations concentrate in Gauteng and KwaZulu-Natal manufacturing corridors. Palsgaard sustains technical service relationships with these buyers through on-site formulation support.
- Beverage Producers:Plant-based dairy alternative formulators in oat and almond milk segments open novel application vectors for stabilizer-emulsifier hybrid systems.
- Snack Companies:Savory snack manufacturers utilize emulsifiers for flavor encapsulation and oil binding in extruded products.
Purchasing power concentrates in Food Manufacturers; application innovation concentrates in Beverage Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Health's food additive regulations anchor South Africa's emulsifier governance, while provincial industrial clustering concentrates manufacturing capacity across distinct geographic corridors with varying technical service demands.
Gauteng
Johannesburg-Pretoria industrial zones drive powder emulsifier procurement for dry-mix bakery operations. The Department of Health's labeling amendments accelerate enzymatic emulsifier qualification among premium bakery chains. Midrand manufacturing corridors host large-scale food manufacturers demanding direct technical service partnerships over traditional distribution.
Western Cape
Oilseed processing infrastructure anchors domestic lecithin sourcing for margarine and dairy applications. Cargill's regional footprint secures liquid emulsifier supply security despite geographic concentration vulnerability. Stellenbosch-Paarl agri-processing clusters pilot microfluidization technology for premium lecithin fractionation at reduced scale thresholds.
KwaZulu-Natal
Durban-Pinetown manufacturing corridors expand bakery emulsifier adoption as regional chains reformulate for front-of-pack compliance. HACCP certification bottlenecks delay mid-tier manufacturer market entry despite strong demand signals. Palsgaard's technical service relationships target this corridor's joint development agreement preferences.
Free State
Grain belt agricultural processing presents underdeveloped emulsifier demand with first-mover positioning potential. Legacy pneumatic handling systems accommodate powder formats without capital-intensive upgrades. Bloemfontein-centered food manufacturing remains below critical scale for dedicated technical service deployment.
South Africa Food Emulsifiers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across South Africa's emulsifier supply base. Multinational integrated suppliers with Johannesburg application laboratories command premium positioning through formulation partnerships. Regional compounders compete on import substitution and shortened lead times. Dominant competitive moves include technical service-led customer lock-in and local blending capacity expansion to reduce dollar-denominated raw material exposure.
Among multinational integrated suppliers, Palsgaard and Cargill Incorporated represent the technical service archetype, anchoring customer relationships through Johannesburg-based application laboratories and trained food technologist teams. Fourchem occupies a position within the regional compounder tier, exemplifying import substitution strategy through local manufacturing of select emulsifier blends. These three players collectively illustrate the market's bifurcation between global technical depth and regional cost optimization.
| Leading Market Players |
|---|
| DuPont de Nemours Inc. |
| The Dow Chemical Company |
| Palsgaard |
| ChemSystems |
| Fourchem |
| South Bakels Pty Ltd |
| Protea Chemicals |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Others |
Value Network & Pricing Analysis
Ninety-day inventory cycles for palm oil-derived fatty acid feedstocks compress margin predictability for South African emulsifier compounders, binding pricing power to Malaysian export policy volatility and the geographic concentration of Western Cape oilseed processing infrastructure.
Pricing Analysis
Johannesburg-Pretoria dry-mix manufacturers pay premium freight-adjusted rates against Western Cape liquid lecithin buyers, reflecting the inland logistics penalty. Pricing stratifies across enzymatic premium tiers, standard chemical-esterified grades, and economy blended formats differentiated by certification grade and volume scale. Cost compression in economy tiers is intensifying because mid-tier manufacturers face 12-18 month HACCP certification timelines that freeze spot procurement. Large-scale food manufacturers exhibit lowest price sensitivity through joint development agreements, while independent Free State bakeries remain most exposed to spot market swings.
Supply Chain Analysis
Sixty-day lead times for dollar-denominated mono- and diglyceride raw materials tether South African compounders to Malaysian and Indonesian palm oil export schedules. Domestic supply draws from Western Cape oilseed crushing, KwaZulu-Natal import blending facilities, and Gauteng dry-mix compounding sites. Single-source vulnerability concentrates in Western Cape lecithin fractionation, where Cargill's infrastructure anchors national supply. Distribution runs through technical service-led direct relationships for large manufacturers and regional chemical distributors for mid-tier buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's food emulsifiers market represents early-cycle expansion, with clean-label reformulation mandates accelerating penetration of enzymatic and plant-derived systems beyond traditional margarine and bakery applications.
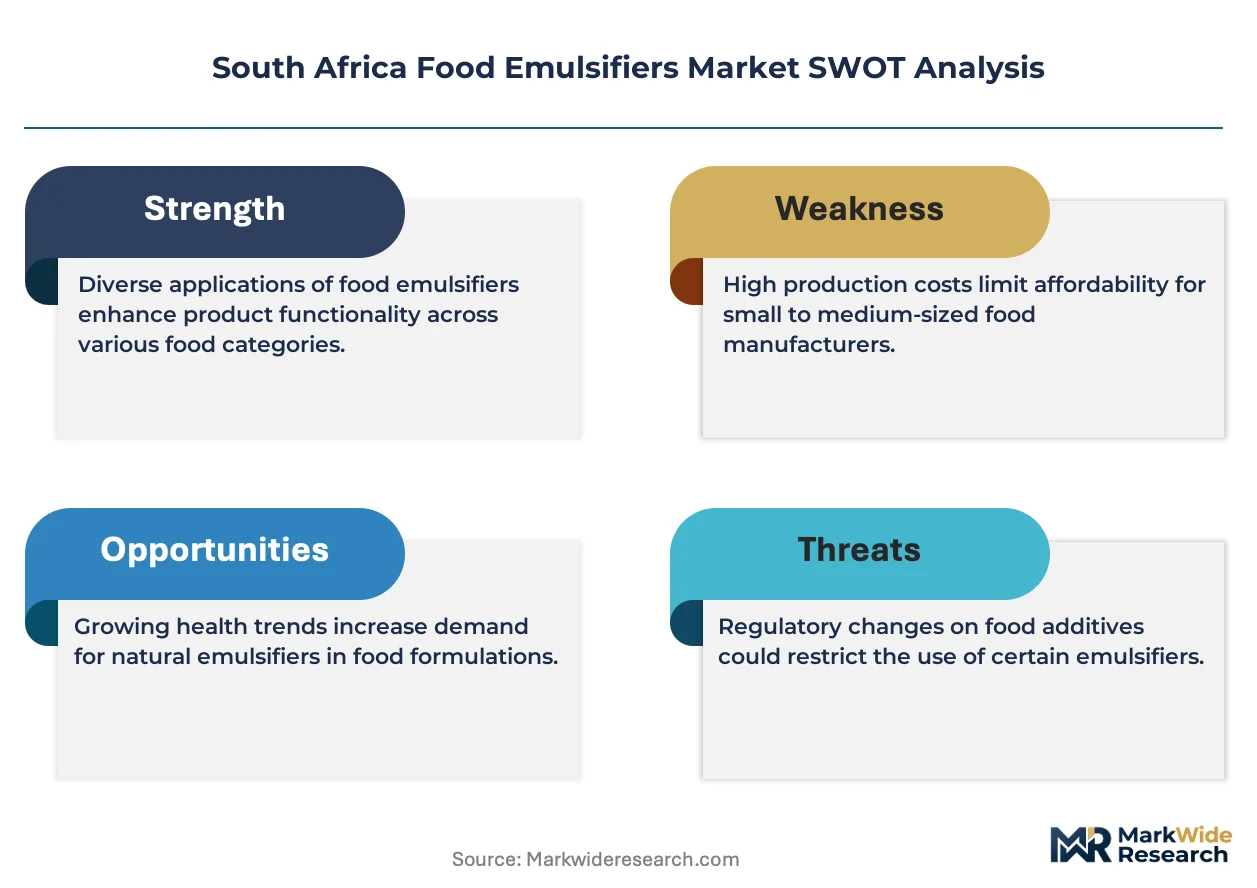
For Market Incumbents: Compound technical service capabilities through expanded Johannesburg application laboratory staffing to defend against regional compounders poaching mid-tier accounts with shortened lead times. Deepen backward integration into palm oil sustainability certification to preempt Department of Health labeling amendments that will disadvantage uncertified supply chains. Prioritize HACCP certification support programs for KwaZulu-Natal bakery chains to accelerate their market entry and lock in long-term supply agreements. For New Entrants and Emerging Players: Lead with enzymatic emulsifier qualification services targeting Free State grain belt facilities, where legacy pneumatic handling systems accommodate powder formats without capital-intensive upgrades and first-mover technical relationships remain unclaimed. The plant-based dairy alternatives segment offers the most penetrable white space, with oat and almond milk formulators seeking stabilizer-emulsifier hybrid systems lacking established supplier relationships. Deploy direct technical service teams rather than distributor networks to mirror incumbent partnership models. For Investors and Strategic Acquirers: Carve-out targets emerge from SEBI-listed parent companies seeking to divest non-core South African operations amid environmental disclosure pressure and governance risk reassessment. Long-term viability hinges on enzymatic platform transitions and clean-label certification depth rather than commodity blending scale. Monitor pending Department of Health food labeling amendments as the critical inflection signal, with accelerated implementation likely to compress valuations for synthetic-dependent compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Technical Service Laboratory Expansion | Johannesburg-based application facilities anchor joint development agreements with Gauteng bakery chains. |
| Enzymatic Production Platform Investment | Precision fermentation capabilities qualify suppliers for front-of-pack clean-label compliance requirements. |
| Backward Integration into Certified Palm Oil | Sustainable sourcing credentials preempt Department of Health disclosure regulation tightening. |
| Free State Market Development Program | First-mover technical relationships capture underdeveloped grain belt emulsifier demand. |
| HACCP Certification Partnership Offering | Compliance support accelerates mid-tier manufacturer market entry and supplier lock-in. |
Research Methodology
A standing panel of food technologists, procurement leads at large-scale manufacturers, distribution channel partners, and Department of Health regulatory affairs specialists provided ongoing calibration against secondary validation from Codex Alimentarius documentation, SANS standards filings, SEC 10-K disclosures from parent companies, and South African customs trade data. Primary interviews with bakery chain R&D directors and margarine compounder plant managers combined with bottom-up and top-down triangulation to cross-check volume estimates.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation modeling spanning product chemistry tiers, application categories, form factors, and end-user scale bands. CAGRs were derived from trend extrapolation anchored to observed capacity expansion timelines and regulatory implementation schedules. Forecast inputs incorporated palm oil price volatility indices, HACCP certification pipeline data, and enzymatic technology adoption curves from Western Cape pilot installations.
The analysis sits within stated boundaries; outcomes outside Department of Health regulatory amendment timelines or sustained palm oil supply disruption would require recalibration. Forecasts reflect documented assumptions regarding clean-label penetration rates and mid-tier manufacturer certification velocity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Low-Sodium Salt Substitute Market
Food Additives and Ingredients
Natural Food Color Additives Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Asia Food Emulsifiers Market
Food Additives and Ingredients
Russia Food Additives Market
Food Additives and Ingredients
Spain Food Acidulants Market
Food Additives and Ingredients
Low Methoxyl Pectin Market
Food Additives and Ingredients
North America Food Additives Market
Food Additives and Ingredients
Mexico Food Preservatives Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
Bakery Release Agents Market
Food Additives and Ingredients
Germany Feed Additives Market