
 Spain Food Additives Market | 2026-2036
Spain Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Food Additives Market Analytics
The Spain food additives sector is consolidating around a sharp divergence between premium natural-extract tiers and commodity synthetic grades. Kerry Group leverages its Spanish flavor application centers to anchor clean-label positioning for Iberian dairy clients. Cargill Incorporated competes through integrated sweetener and texturant supply chains reaching Valencia's beverage corridor. Corbion NV specializes in fermentation-derived preservatives that navigate tightening consumer scrutiny on chemical additives.
Food additives comprise functional substances incorporated at concentrations below twenty-five percent of a finished food to enhance stability, sensory profile, or processing tolerance, with emulsifiers maintaining fat-water dispersion in dairy matrices and antioxidants interrupting lipid oxidation pathways in baked goods. Flavoring agents capture margin concentration as Spanish beverage manufacturers reformulate around reduced-sugar profiles requiring complex taste modulation systems. Preservatives face structural pressure from refrigerated logistics expansion yet sustain volume in ambient confectionery exports to Latin American markets.
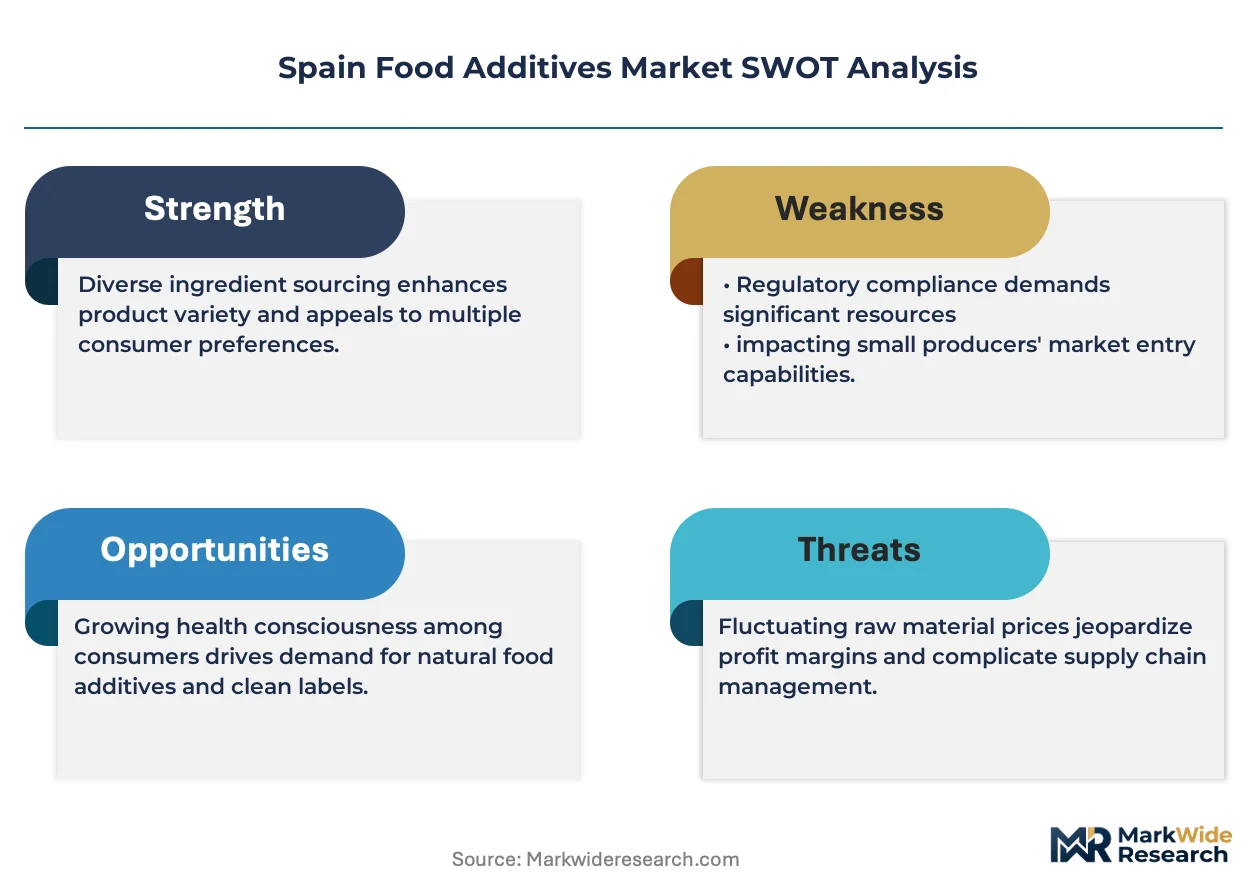
AESAN enforces EU Regulation 1333/2008 on food additives through national control plans, while EFSA scientific opinions determine acceptable daily intakes that directly shape Spanish reformulation roadmaps. REACH chemical registration requirements from ECHA constrain synthetic additive introductions, pushing Spanish manufacturers toward botanical extract portfolios. Stakeholders must monitor how Spain's transposition of the EU Green Deal farm-to-fork targets will redefine permissible additive categories in processed food exports.
Market Dynamics
Spain's food additives sector is bifurcating around EFSA's accelerated novel food approval timelines, which compress reformulation cycles for Madrid's dairy and bakery clusters while forcing smaller Andalusian processors into compliance bottlenecks.
Growth Catalysts
- EU Green Deal farm-to-fork targets:Spain's transposition of these sustainability mandates creates preferential market access for botanical-derived preservatives and natural colorants in export-oriented confectionery.
- Valencia beverage corridor expansion:Functional drink manufacturers are driving demand for microencapsulated flavor systems that mask off-notes in reduced-sugar formulations.
- Catalonia clean-label sourcing:Packaged food producers in Barcelona's metropolitan area are consolidating supplier relationships around fermentation-derived texturants with full traceability documentation.
Market Restraints
- REACH chemical registration:ECHA's data requirements for synthetic additive introductions impose six-figure compliance costs that exclude mid-tier Spanish ingredient distributors from novel molecule portfolios.
- Botanical raw material concentration:Spain's natural extract supply chains depend on Moroccan saffron and Portuguese grape skin sources, creating weather-linked input volatility for antioxidant manufacturers.
- Refrigerated logistics substitution:Cold chain expansion across Castile and León is displacing traditional chemical preservatives in ambient-stable meat applications.
Strategic Opportunities
- Basque Country precision fermentation:San Sebastián's biotech cluster offers underutilized capacity for dairy protein alternatives requiring specialized emulsifier co-development.
- AESAN novel food fast-track:Spain's national food safety agency is piloting accelerated timelines for enzyme-based processing aids, rewarding early applicants with twelve-month approval advantages.
- Direct-to-manufacturer digital platforms:Ingredient marketplaces are bypassing traditional distribution layers between Galician seaweed extract producers and Madrid's reformulation laboratories.
Industry Challenges
- Reformulation chemist scarcity:Spain's technical universities produce insufficient graduates trained in clean-label substitution protocols for legacy synthetic additive systems.
- Dual certification complexity:Exporters to Latin American markets must simultaneously satisfy AESAN domestic requirements and destination-country Mercosur additive standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Food Additives Market |
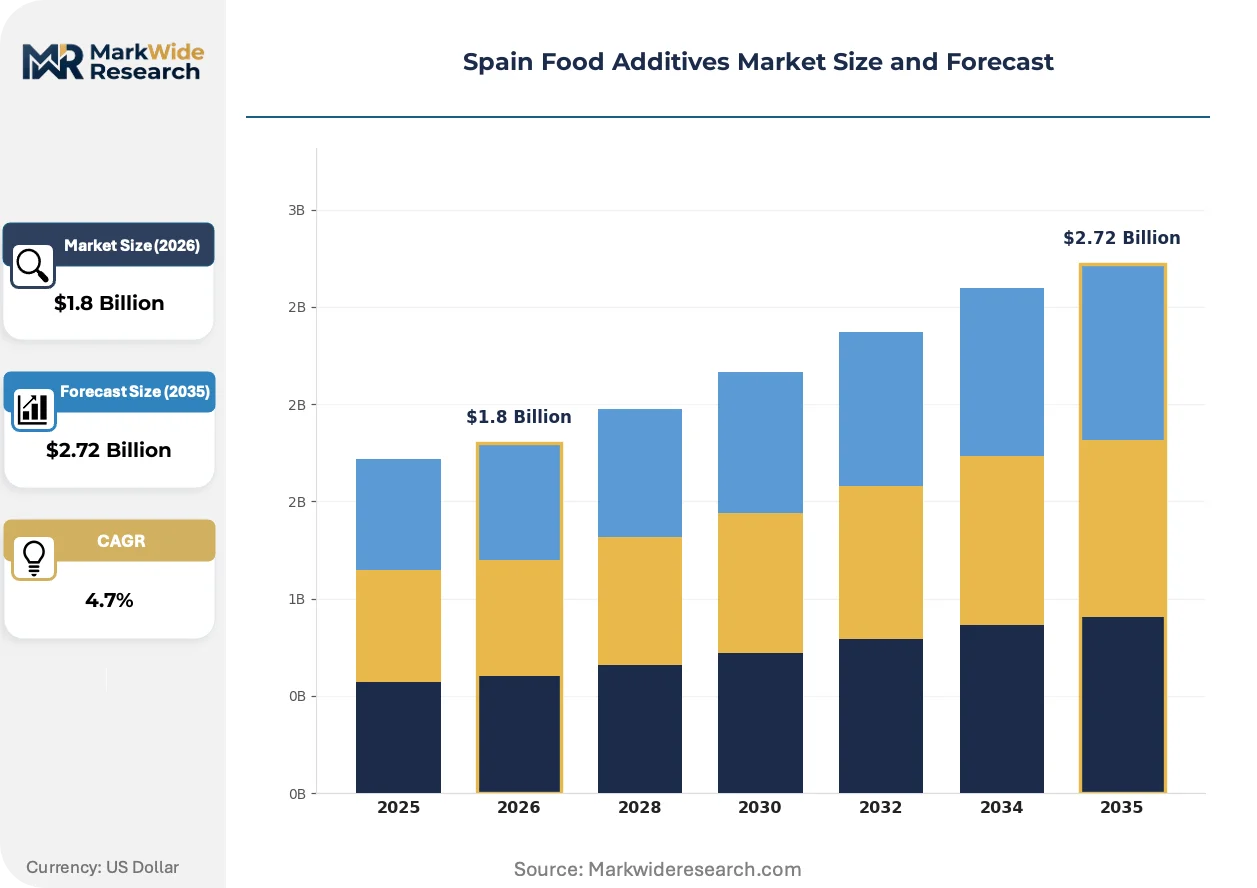
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Emulsifiers, Flavoring Agents, Preservatives Application: Beverages, Dairy Products, Bakery, Confectionery Form: Powder, Liquid, Granule, Crystal End User: Food Manufacturers, Restaurants, Retailers, Consumers |
| Companies Covered | Kerry Group, Archer Daniels Midland Company, Firmenich, Cargill Incorporated, Tate & Lyle PLC, International Flavors and Fragrances, Corbion NV, Givaudan, Palsgaard A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Food Additives Market Evolving Landscape
Spanish food additive innovation is converging on three vectors: precision biotechnology replacing commodity chemistry, regulatory data transparency reshaping supplier qualification, and procurement centralization compressing vendor margins.
Fermentation-derived natural preservatives are overtaking synthetic benzoate and sorbate systems in Iberian dairy applications. Barcelona-based yogurt manufacturers have adopted these bioprotective cultures at commercial scale since 2023. The technology is overtaking conventional chemical preservation in ambient dessert categories previously dominated by potassium sorbate.
EFSA's 2023 guidance on novel food data requirements is forcing Spanish additive suppliers to commission chronic toxicity studies earlier in development pipelines. This regulatory shift extends time-to-market for synthetic molecules while accelerating botanical extract registrations with existing safety dossiers. Madrid's reformulation service providers are responding by building in-house toxicology capabilities previously outsourced to CROs.
Consolidated procurement by Catalonia's retail-private-label manufacturers is disintermediating regional ingredient distributors. Direct contracting between supermarket chains and Kerry Group's Spanish flavor centers is replacing multi-tier supply relationships. This concentration is most visible in Barcelona's metropolitan food technology corridor, where three buyers now account for the majority of emulsifier volume.
Spain Food Additives Market Segmentation
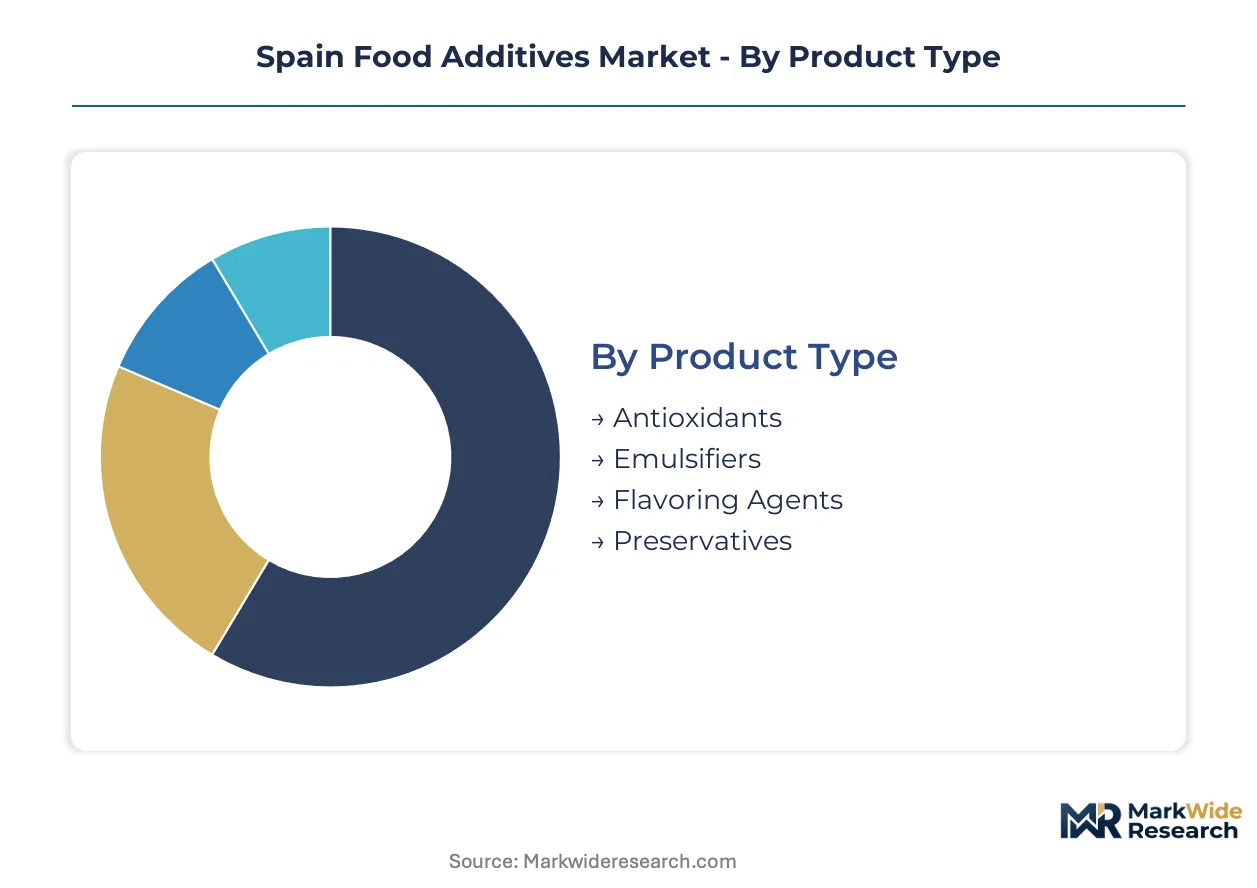
Food additive procurement in Spain stratifies sharply across product chemistry and end-use specifications, with Madrid's reformulation corridors driving premium-tier demand while commodity grades flow toward Andalusian bulk processors. Understanding these segment boundaries clarifies where AESAN regulatory pressure and clean-label substitution cycles concentrate margin pressure.
Product Type:
Replacement cycles for legacy synthetic additives are accelerating as EFSA novel food timelines compress and botanical alternatives achieve cost parity in Iberian dairy applications.
- Antioxidants:These compounds interrupt lipid oxidation pathways through free radical scavenging or metal chelation mechanisms. Spain's bakery sector in Castile and León consumes the majority volume as manufacturers reformulate palm oil-based products for extended ambient shelf stability without synthetic BHA/BHT systems.
- Flavoring Agents:Complex taste modulation systems incorporating natural extracts, reaction flavors, and encapsulated volatile compounds. Valencia's beverage corridor demands these most intensely as reduced-sugar formulations proliferate and off-note masking becomes critical for consumer acceptance.
- Emulsifiers:Surface-active agents stabilizing fat-water dispersions in processed foods.
- Preservatives:Microbial growth inhibitors spanning organic acids, bacteriocins, and fermentation-derived protective cultures.
Flavoring agents sit at the top of the volume ranking, with antioxidants climbing the fastest as clean-label bakery reformulation gathers momentum across Catalonia.
Application:
Margin capture varies dramatically by processing sophistication, with ambient-stable categories commanding premium additive specifications over chilled fresh segments.
- Dairy Products:Yogurt, cheese, and dessert applications requiring emulsifier-protein interactions and bioprotective cultures. Barcelona manufacturers have adopted fermentation-derived preservation at commercial scale, displacing potassium sorbate in ambient dessert categories.
- Beverages:Functional and conventional drinks demanding microencapsulated flavor systems, acidulants, and clouding agents. Valencia's corridor expansion drives concentrated demand for reduced-sugar taste modulation technologies.
- Bakery:Bread, pastry, and biscuit applications requiring dough conditioners, anti-staling enzymes, and mold inhibitors.
- Confectionery:Chocolate, sugar confectionery, and chewing gum utilizing glazing agents, humectants, and intense sweeteners for Latin American export markets.
Dairy products command the highest additive spend per ton processed, with beverages expanding most quickly through functional drink proliferation.
Form:
Physical specification directly determines handling economics and dissolution kinetics in Spanish manufacturing environments.
- Powder:Spray-dried or milled particulates offering extended shelf stability and precise dosing in automated systems. Madrid's reformulation laboratories prefer powder antioxidants for bakery premix standardization.
- Liquid:Aqueous or oil-based solutions enabling rapid dispersion in continuous processing. Valencia beverage manufacturers specify liquid emulsifiers for streamlined tank incorporation without hydration steps.
- Granule:Agglomerated particles balancing flowability with reduced dust generation.
- Crystal:Purified solid forms for high-intensity sweeteners and acidulants requiring exact crystalline specification.
Powder dominates current procurement volumes, with liquid formats gaining share fastest through beverage corridor automation investments.
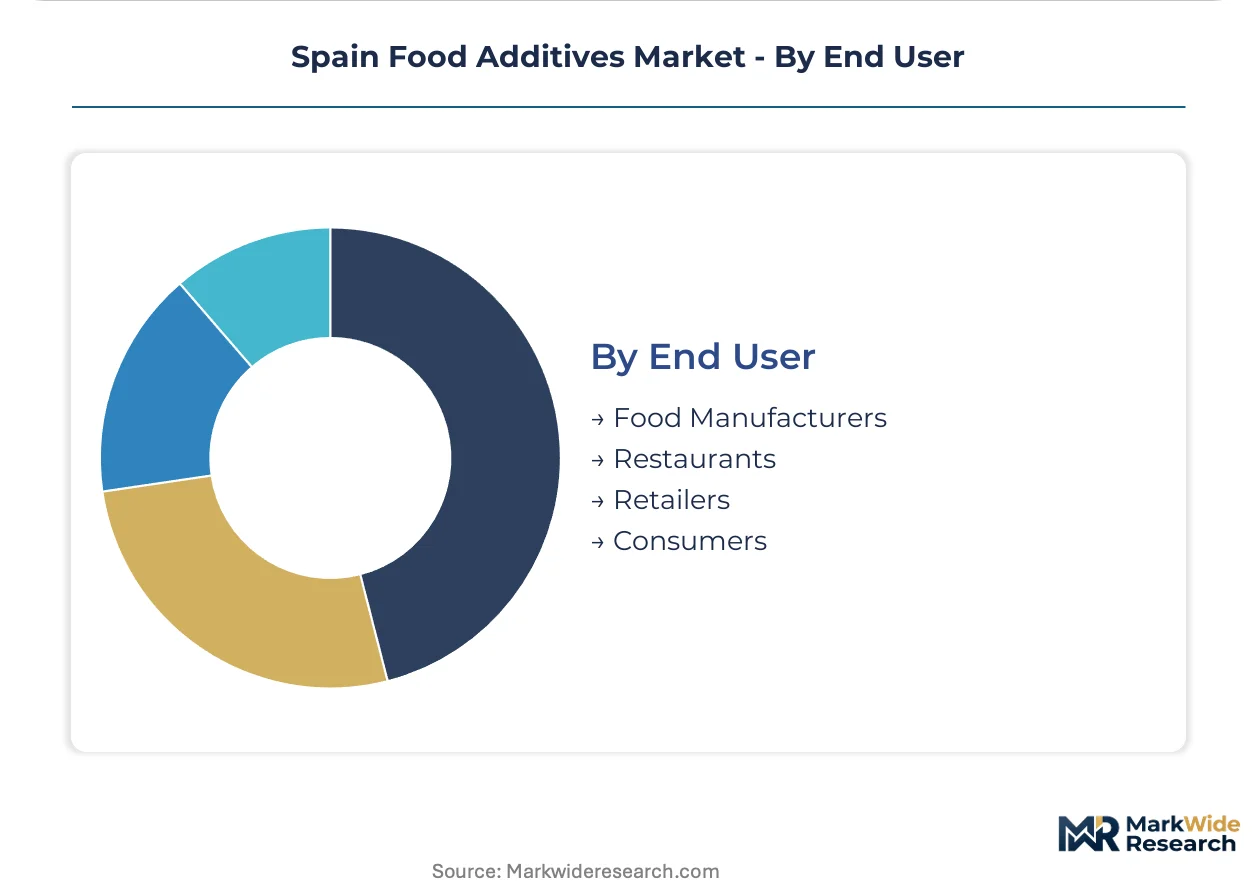
End User:
Buyer sophistication and regulatory exposure create four distinct purchasing behaviors across the Spanish value chain.
- Food Manufacturers:Industrial processors with dedicated reformulation capabilities and direct AESAN compliance responsibility. Catalonia's private-label producers consolidate procurement through centralized technical buying functions.
- Restaurants:Foodservice operators sourcing prepared bases and finishing ingredients with clean-label positioning for menu differentiation.
- Retailers:Supermarket chains controlling private-label specifications and demanding full traceability documentation from additive suppliers.
- Consumers:Direct purchasers of table-top sweeteners, food colors, and home baking additives through specialty channels.
Food manufacturers represent the deepest additive expertise, with retailers climbing fastest as private-label consolidation concentrates buying power in Barcelona's metropolitan corridor.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's food additive sector prioritizes wine and dairy applications, whereas Spain concentrates reformulation expertise in Madrid's technology corridor and Catalonia's clean-label manufacturing belt. Both countries navigate EFSA authorization timelines, yet Spain's AESAN pilot programs create distinct regulatory velocity advantages for enzyme-based processing aids.
Madrid
Madrid's food technology corridor clusters reformulation laboratories alongside major dairy production zones, driving concentrated demand for emulsifier-protein interaction systems. AESAN's national headquarters coordinates EU Regulation 1333/2008 enforcement through control plans that shape acceptable daily intake calculations. The metropolitan area hosts the majority of Spain's technical buying functions for private-label manufacturers seeking direct supplier relationships.
Catalonia
Catalonia's packaged food manufacturers in Barcelona's metropolitan area are consolidating procurement around fermentation-derived texturants with full traceability documentation. The region's national food safety agency field office enforces tightened additive authorization timelines that compress reformulation cycles. Clean-label sourcing expansion here is displacing traditional distribution layers between supermarket chains and flavor application centers.
Basque Country
San Sebastián's biotech cluster offers underutilized precision fermentation capacity for dairy protein alternatives requiring specialized emulsifier co-development. Spain's transposition of EU Green Deal farm-to-fork targets creates preferential market access for botanical-derived preservatives originating from this region. The concentration of food technology research institutions here supports early-stage novel food applications.
Valencia
Valencia's beverage corridor expansion drives concentrated demand for microencapsulated flavor systems that mask off-notes in reduced-sugar formulations. EFSA novel food approval timelines directly impact reformulation cycles for functional drink manufacturers concentrated along this coastal production zone. Liquid emulsifier specifications dominate procurement as automation investments streamline tank incorporation without hydration steps.
Andalusia
Andalusian bulk processors face compliance bottlenecks from accelerated EFSA timelines that favor Madrid's dedicated reformulation capabilities. The region's commodity-grade additive consumption concentrates in ambient-stable meat applications where refrigerated logistics expansion is displacing traditional chemical preservatives. Smaller processors here depend on regional ingredient distributors vulnerable to procurement centralization from Catalonia's retail chains.
Spain Food Additives Market Competitive Landscape
Top-tier vendors anchor premium natural-extract tiers, while mid-tier commodity synthetic distributors struggle against REACH registration cost barriers. The sector exhibits tiered concentration around clean-label positioning versus legacy chemical portfolios. Two strategic archetypes dominate: integrated sweetener-texturant suppliers leveraging supply chain control, and fermentation-derived specialists navigating consumer scrutiny on synthetic systems. Competitive moves concentrate on direct-to-manufacturer digital platform development and in-house toxicology capability building.
Among Ireland-based multinationals, Kerry Group occupies a position exemplifying clean-label flavor application anchoring for Iberian dairy clients. Cargill Incorporated represents the integrated supply chain archetype, with its Spanish operations reaching Valencia's beverage corridor through captive sweetener and texturant networks. Corbion NV sits within the fermentation-derived specialist tier, its bioprotective culture portfolios navigating tightening AESAN scrutiny on chemical preservatives.
| Leading Market Players |
|---|
| Kerry Group |
| Archer Daniels Midland Company |
| Firmenich |
| Cargill Incorporated |
| Tate & Lyle PLC |
| International Flavors and Fragrances |
| Corbion NV |
| Givaudan |
| Palsgaard A/S |
| Others |
Value Network & Pricing Analysis
Saffron futures from Moroccan exchanges and Portuguese grape skin spot markets cascade through Spain's antioxidant supply chain, compressing margin structures for mid-tier botanical extract manufacturers while amplifying pricing power for vertically integrated flavor houses serving Catalonia's private-label consolidators.
Pricing Analysis
Capacity additions in Basque Country precision fermentation facilities are reshaping price floors for dairy protein alternative emulsifiers. Three-tier pricing structure across premium natural-extract, standard fermentation-derived, and economy synthetic grades dominates procurement. Price differentiation hinges on EFSA novel food dossier completeness and volume commitment scale. Cost compression in commodity synthetic tiers is intensifying because REACH registration cost barriers exclude smaller distributors. Private-label manufacturers in Barcelona's metropolitan corridor exhibit lowest price sensitivity due to consolidated technical buying functions, while Andalusian bulk processors face acute margin pressure.
Supply Chain Analysis
Freight cost volatility from Moroccan saffron corridors and Portuguese grape skin routes into Valencia's processing hubs is amplifying input price instability for natural antioxidant manufacturers. Geographic supply concentration centers on Morocco, Portugal, and domestic Spanish fermentation capacity. Raw material dependencies include saffron stigmas, grape skin anthocyanins, and seaweed-derived polysaccharides from Galician coasts. Single-source vulnerability from weather-linked botanical harvests creates structural risk for clean-label preservative lines. Distribution runs through direct-to-manufacturer digital platforms bypassing traditional regional distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Green Deal farm-to-fork transposition accelerates demand for botanical-derived additives with traceable supply chains.
For Market Incumbents: Deepen in-house toxicology capabilities to compress EFSA novel food approval timelines. Invest in captive supply agreements with Moroccan saffron cooperatives to hedge input volatility. Defend against procurement centralization by embedding application scientists directly within Madrid's reformulation laboratories. For New Entrants and Emerging Players: Enter via AESAN's pilot fast-track for enzyme-based processing aids to capture twelve-month approval advantages. Target San Sebastián's underutilized precision fermentation capacity for dairy protein alternative co-development. Pursue white-label manufacturing partnerships with Galician seaweed extract producers lacking Madrid market access. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation-derived specialists possessing chronic toxicity study archives. Five-to-ten-year viability favors botanical extract portfolios with established EFSA safety dossiers. Monitor AESAN authorization velocity as inflection indicator for regulatory arbitrage opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Basque Country biotech clusters unlock dairy protein alternative emulsifier co-development with shorter development cycles. |
| Backward Integration into Botanical Supply | Moroccan saffron cooperative acquisitions secure antioxidant input stability against weather-linked harvest volatility. |
| In-House Toxicology Capability Buildout | Madrid reformulation laboratories reduce outsourcing dependence and compress EFSA novel food timelines. |
| Direct-to-Manufacturer Digital Platform Launch | Galician seaweed extract producers bypass distributor layers to reach Catalonia's consolidated private-label buyers. |
| EFSA Novel Food Fast-Track Application | Early AESAN pilot program entrants capture twelve-month approval advantages for enzyme-based processing aids. |
Research Methodology
Direct dialogue with reformulation chemists, AESAN regulatory affairs officers, procurement directors at Catalonia's private-label manufacturers, and Galician seaweed extract producers grounded this analysis. Secondary validation drew from EFSA scientific opinions, AESAN national control plan disclosures, EU Regulation 1333/2008 transposition documents, and REACH registration databases. Bottom-up volume estimates from individual additive categories triangulated against top-down expenditure flows from Spain's food manufacturing sector.
Segment-level projections across product type, application, form, and end-user dimensions were generated through the analysis window. CAGRs were derived from regression analysis of historical authorization timelines, substitution elasticity parameters for clean-label transitions, and capacity expansion announcements in Basque Country fermentation facilities. Industry-specific inputs included EFSA novel food approval velocity indices and refrigerated logistics penetration rates across Castile and León.
Inputs from EFSA guidance documents and AESAN enforcement bulletins were available through the study window; gaps in real-time saffron harvest yield data introduce uncertainty bands around natural antioxidant supply forecasts. Forecasts reflect assumptions regarding EU Green Deal implementation timelines and botanical extract cost parity achievement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South Africa Food Emulsifiers Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Film Forming Starches Market
Food Additives and Ingredients
Flavophospholipol Market
Food Additives and Ingredients
Instant Fat Powder Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Canada Food Acidulants Market
Food Additives and Ingredients
Africa Food Hydrocolloids Market
Food Additives and Ingredients
Egg Emulsifier Market
Food Additives and Ingredients
Hydrocolloid Carrier Market