
 Coconut Fatty Acids Market | 2026-2036
Coconut Fatty Acids Market Size, Share, and Industry Trends Forecast 2026-2036
Coconut Fatty Acids Market Outlook
Enzymatic interesterification is reconfiguring how split fatty acids achieve tailored carbon-chain profiles for niche cosmetic and pharmaceutical applications. Musim Mas Holdings leverages integrated plantation-to-oleochemical operations across Southeast Asia to sustain cost-advantaged feedstock security. Godrej Industries Ltd. anchors its position through backward integration into Indian coconut oil crushing, while KLK OLEO competes on specialized high-purity lauric acid fractions for European personal care markets.
Coconut fatty acids comprise saturated medium-chain carboxylic acids—primarily lauric acid (C12:0, 45-52% of crude oil composition), caprylic acid (C8:0), capric acid (C10:0), and myristic acid (C14:0)—obtained through high-pressure splitting of coconut oil triglycerides at 200-260°C with subsequent fractional distillation. These acids serve as foundational oleochemical intermediates for surfactants, lubricants, and nutritional formulations where plant-derived carbon chains replace petrochemical feedstocks. Lauric acid dominates volume throughput due to its centrality in sodium lauryl sulfate alternatives and glycerol monolaurate antimicrobials, while caprylic and capric acid fractions command premium positioning in MCT oil and pharmaceutical excipient applications where shorter chain lengths enable rapid metabolic pathways. The powder and granule forms concentrate margin pools where free-flowing handling properties reduce downstream formulation complexity for cosmetic manufacturers.
EU REACH registration requirements and the F-Gas Regulation constrain fluorinated process alternatives, indirectly bolstering demand for bio-based fatty acid derivatives in industrial coolant and lubricant formulations. FDA cosmetic ingredient scrutiny under the Modernization of Cosmetics Regulation Act tightens supply chain documentation burdens for US-bound exports. Chemical manufacturers must monitor how Indonesia's downstream oleochemical investment policies and the Philippines' coconut levy restructuring reshape feedstock availability and export tariff structures.
Market Dynamics
Enzymatic interesterification is collapsing the traditional carbon-chain customization economics that once required dedicated fractionation assets, allowing mid-scale processors to compete for pharmaceutical-grade lauric acid contracts without captive distillation capacity.
Growth Catalysts
- EU F-Gas Regulation:Industrial coolant formulators are redirecting procurement toward bio-based fatty acid derivatives as fluorinated alternatives face phase-down schedules, expanding addressable demand for caprylic acid fractions in heat-transfer fluids.
- Sulfate-free surfactant systems:Personal care manufacturers are formulating sodium cocoyl isethionate and disodium cocoyl glutamate alternatives to sodium lauryl sulfate, pulling refined lauric acid through cosmetic ingredient supply chains.
- Indonesia's downstream oleochemical investment policies:Jakarta's tax incentives for integrated plantation-to-derivative facilities are drawing Asian chemical manufacturers to establish captive fractionation capacity near Medan and Surabaya feedstock clusters.
Market Restraints
- Copra price volatility:Philippine coconut levy restructuring and Indonesian export tariff uncertainty transmit raw material cost swings directly to split fatty acid margin structures, compressing processor working capital cycles.
- Upstream concentration risk:Over sixty percent of global crude coconut oil originates from Indonesian and Philippine plantation networks, creating single-origination vulnerability to El Niño drought cycles and port logistics disruptions.
- Fractional distillation energy intensity:High-pressure splitting at 200-260°C requires sustained natural gas or biomass thermal inputs, exposing processors to carbon border adjustment mechanisms under EU CBAM implementation timelines.
Strategic Opportunities
- Indian pharmaceutical excipient demand:CDSCO's tightening purity standards for parenteral-grade lipids are opening premium positioning for capric acid fractions in intravenous emulsion formulations, with Mumbai and Hyderabad clusters driving procurement.
- Biodegradable lubricant mandates:EU Green Deal bio-based content thresholds for industrial hydraulic fluids are creating specification pull-through for C8-C10 methyl esters in German and Benelux machinery markets.
- Direct-to-manufacturer digital platforms:Specialty chemical distributors are deploying blockchain-traceable procurement portals that bypass traditional oleochemical trading houses, capturing margin from cosmetic compounders seeking certified sustainable documentation.
Industry Challenges
- Enzyme biocatalyst sourcing:Lipase immobilization expertise for interesterification processes concentrates among Danish and Japanese enzyme suppliers, creating technology access bottlenecks for Southeast Asian processors scaling specialty fraction production.
- REACH registration documentation burdens:ECHA's substance data requirements for lauric acid derivatives demand toxicological dossiers that stretch mid-cap oleochemical houses across twelve-to-eighteen month compliance timelines, delaying European market entry.
- Legacy batch reactor retrofit costs:Continuous processing adoption for fractional distillation requires capital deployment that conflicts with depreciation schedules on existing high-pressure splitting assets, slowing technology transition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coconut Fatty Acids Market |
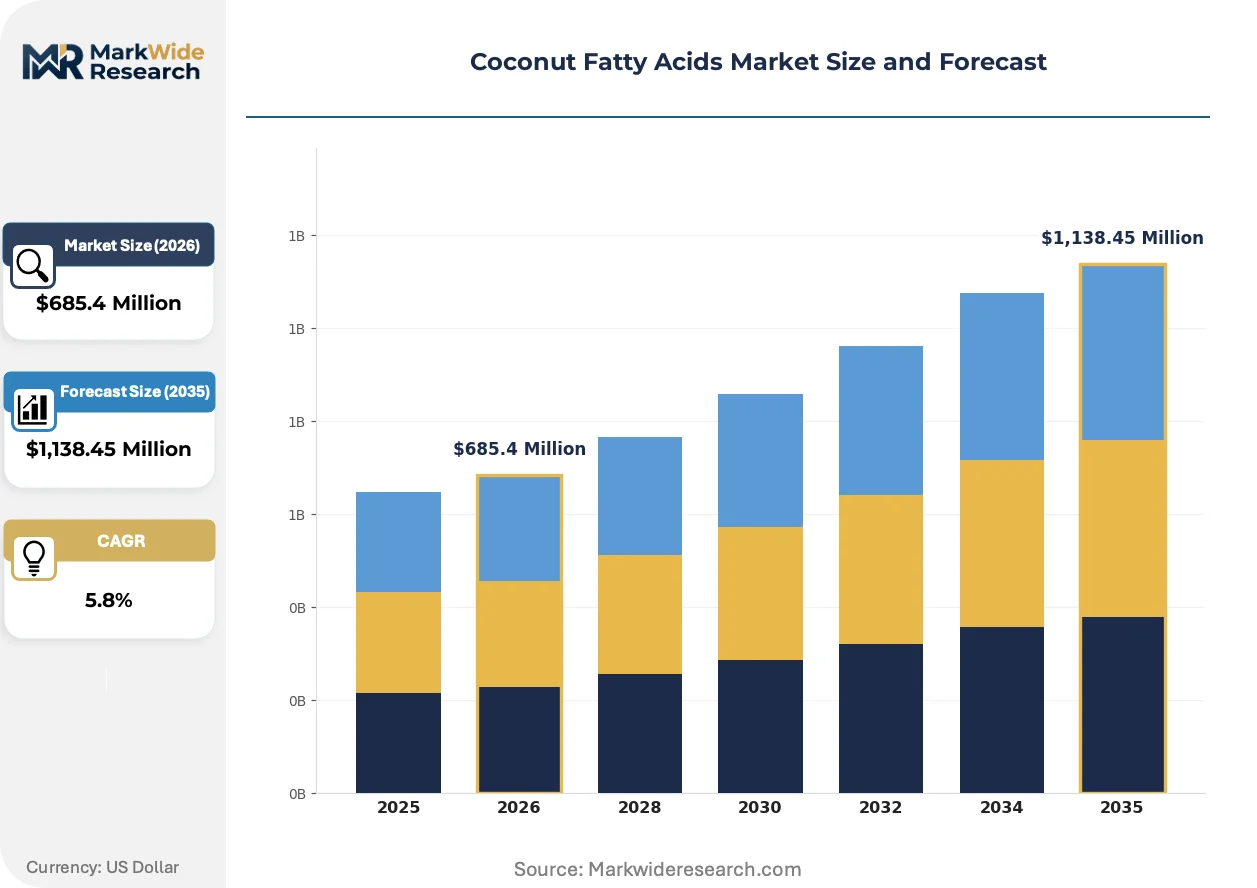
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caprylic Acid, Capric Acid, Lauric Acid, Myristic Acid Application: Personal Care, Food & Beverage, Pharmaceuticals, Industrial End User: Cosmetic Manufacturers, Food Producers, Wellness Companies, Chemical Manufacturers Form: Liquid, Powder, Granules, Emulsions |
| Companies Covered | Mewah Group, Musim Mas Holdings, Wilmar International Ltd., Royal Coconut Company, Godrej Industries Ltd., Cargill, Incorporated, Vantage Specialty Chemicals, Inc., PT. Energi Sumber Bumi, KLK OLEO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coconut Fatty Acids Market Strategic Shifts
Process intensification and regulatory chemistry are rewriting the competitive map for medium-chain fatty acid value capture, compressing the advantage once held by integrated plantation operators.
Enzymatic interesterification is collapsing the capital barrier between commodity splitters and specialty fraction producers. Immobilized lipase systems now achieve carbon-chain redistribution at ambient pressure, eliminating the 200-260°C thermal requirements of conventional high-pressure splitting. Pharmaceutical excipient manufacturers in Italy and Spain are qualifying these biocatalytic routes for glycerol monolaurate production, enabling toll processors without distillation assets to capture antimicrobial-grade margins.
REACH registration requirements for lauric acid derivatives are tightening substance documentation obligations across European cosmetic and industrial chemical supply chains. ECHA's 2023 updated guidance on skin sensitization endpoints demands additional in vitro testing for C12-C14 fatty acid salts, extending registration timelines for non-integrated importers. German and French formulators are responding by consolidating supplier bases toward REACH-registered Indonesian and Malaysian producers with existing dossier coverage, squeezing trading house intermediaries.
Certification-driven procurement is fragmenting traditional oleochemical distribution channels. Personal care manufacturers in California and New York are bypassing conventional distributors to contract directly with RSPO- and Fair Trade-certified Philippine processors, capturing margin and traceability documentation simultaneously. This disintermediation is most visible in sulfate-free surfactant supply chains, where cosmetic compounders require lot-specific sustainability credentials that trading houses cannot economically provide.
Coconut Fatty Acids Market Segmentation
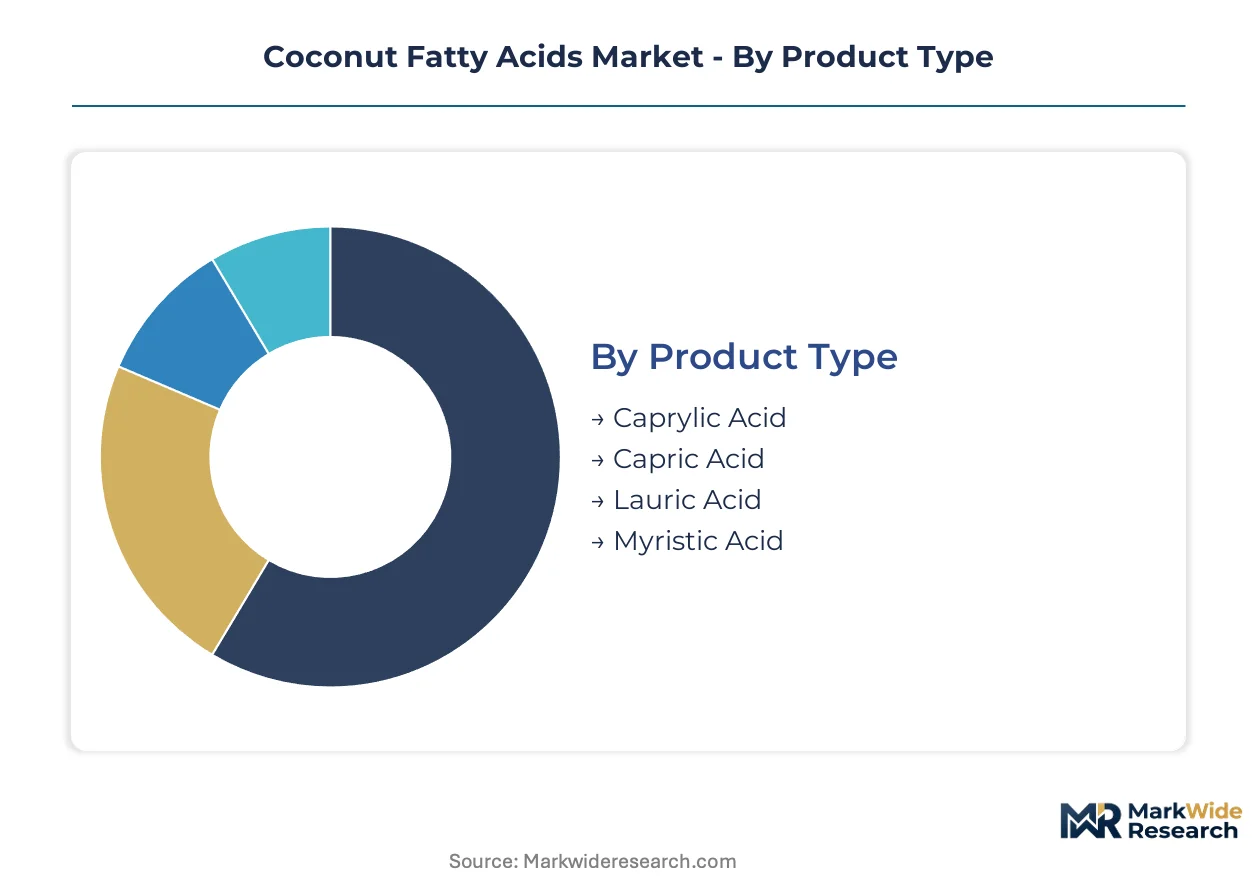
Coconut fatty acids fragment across carbon-chain length, application chemistry, and handling requirements. Each segmentation axis reveals distinct margin pools and procurement patterns that processors must navigate to capture value.
Product Type:
Mature commodity grades dominate volume throughput while emerging specialty fractions command premium positioning in pharmaceutical and antimicrobial applications.
- Lauric Acid:C12:0 saturated carboxylic acid comprising 45-52% of crude coconut oil composition. Personal care formulators in Germany and France pull refined grades for sodium cocoyl isethionate production as sulfate-free surfactant systems displace conventional SLS. REACH registration dossiers from integrated Indonesian producers consolidate supplier bases toward certified sources.
- Caprylic Acid:C8:0 medium-chain fatty acid fraction. Mumbai and Hyderabad pharmaceutical clusters drive procurement for parenteral-grade lipids under CDSCO tightening purity standards, with caprylic acid enabling rapid metabolic pathways in intravenous emulsion formulations.
- Capric Acid:C10:0 fraction serving MCT oil and nutritional excipient applications where shorter chain lengths support ketogenic metabolic routing.
- Myristic Acid:C14:0 component at lower crude oil concentrations, finding niche positioning in cosmetic ester chemistry and fragrance compound synthesis.
Lauric acid handles the majority of throughput; caprylic acid is the fastest mover on share.
Application:
Cost tier differentiation separates mass-market surfactant demand from specification-driven pharmaceutical and food-grade procurement.
- Personal Care:Sulfate-free surfactant systems including sodium cocoyl isethionate and disodium cocoyl glutamate. California and New York cosmetic compounders require lot-specific RSPO and Fair Trade credentials that bypass traditional trading houses.
- Pharmaceuticals:Parenteral-grade lipids and glycerol monolaurate antimicrobials. Italian and Spanish excipient manufacturers qualify enzymatic interesterification routes at ambient pressure, eliminating high-pressure splitting thermal requirements.
- Food & Beverage:MCT oil formulations and nutritional emulsifiers where medium-chain triglycerides support rapid energy metabolism applications.
- Industrial:Bio-based lubricants and heat-transfer fluids. EU F-Gas Regulation phase-down schedules redirect coolant formulators toward caprylic acid fractions as fluorinated alternatives face constraint.
Personal care absorbs the largest volume base; pharmaceutical applications are climbing the fastest.
End User:
Customer type determines documentation burden and certification requirements across the procurement chain.
- Cosmetic Manufacturers:Sulfate-free formulators with stringent sustainability documentation needs. Direct-to-manufacturer digital platforms with blockchain traceability disintermediate conventional oleochemical distributors.
- Chemical Manufacturers:Industrial surfactant and lubricant compounders. German and Benelux machinery markets specify bio-based content thresholds under EU Green Deal mandates for hydraulic fluids.
- Food Producers:Nutritional and functional food developers incorporating MCT fractions into ketogenic and sports nutrition products.
- Wellness Companies:Dietary supplement and nutraceutical marketers targeting metabolic health positioning with medium-chain fatty acid derivatives.
Cosmetic manufacturers represent the most demanding customer tier; chemical manufacturers show the steepest expansion trajectory.
Form:
Handling characteristics segment margin pools by downstream formulation complexity reduction.
- Liquid:Standard bulk delivery for industrial surfactant and lubricant applications where pumpable handling suits continuous process integration.
- Powder:Free-flowing handling properties reduce formulation complexity for cosmetic manufacturers. Premium positioning concentrates where dust-free processing and precise dosing matter.
- Granules:Intermediate handling format balancing flowability with reduced caking tendency in humid storage conditions.
- Emulsions:Pre-dispersed aqueous systems for direct incorporation into personal care formulations without intermediate processing steps.
Liquid forms move the highest tonnage; powder forms gain share fastest on margin capture.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic compounders in Germany and France drive premium-grade lauric acid procurement for sulfate-free formulations, while pharmaceutical clusters in Italy and Spain qualify enzymatic production routes. Industrial buyers in the United States and Indonesia reshape procurement patterns through sustainability documentation requirements and downstream investment incentives.
Germany
Personal care formulators in Düsseldorf and Hamburg pull refined lauric acid for sodium cocoyl isethionate production. ECHA's REACH registration requirements for C12-C14 fatty acid salts consolidate supplier bases toward certified Indonesian producers. The Rhine-Ruhr industrial corridor hosts cosmetic compounders requiring lot-specific sustainability credentials that bypass traditional trading houses.
United States
California and New York cosmetic manufacturers demand RSPO- and Fair Trade-certified coconut fatty acids for sulfate-free surfactant systems. FDA cosmetic ingredient scrutiny under the Modernization of Cosmetics Regulation Act tightens supply chain documentation burdens for imports. Direct-to-manufacturer digital platforms with blockchain traceability disintermediate conventional oleochemical distributors in these coastal markets.
Indonesia
Jakarta's tax incentives for integrated plantation-to-derivative facilities draw Asian chemical manufacturers to establish captive fractionation capacity. The country's downstream oleochemical investment policies reshape feedstock availability and export tariff structures. Medan and Surabaya feedstock clusters concentrate upstream fractionation capacity with subsequent downstream investment from regional chemical manufacturers.
Italy
Pharmaceutical excipient manufacturers in Milan and Bologna qualify enzymatic interesterification routes for glycerol monolaurate production at ambient pressure. EMA oversight of parenteral-grade lipids drives procurement standards for antimicrobial-grade fractions. These northern Italian processors capture specialty margins without conventional high-pressure splitting assets through biocatalytic toll processing arrangements.
India
Mumbai and Hyderabad pharmaceutical clusters drive procurement for caprylic acid fractions in intravenous emulsion formulations. CDSCO's tightening purity standards for parenteral-grade lipids open premium positioning for C8:0 fractions with rapid metabolic pathways. Godrej Industries anchors supply security through backward integration into domestic coconut oil crushing operations.
Coconut Fatty Acids Market Competitive Environment
Channel-controlling players compete with product-specialist players across a tiered structure where integrated plantation operators hold feedstock security advantages and mid-scale processors capture specialty margins through enzymatic flexibility. The vendor base separates into three archetypes: integrated plantation-to-oleochemical operators with captive supply, regional fractionators with distillation asset specialization, and toll processors leveraging biocatalytic technology access. Dominant competitive moves include capacity expansion near Indonesian feedstock clusters and strategic partnerships with enzyme suppliers for interesterification licensing.
Within the integrated operator tier, Musim Mas Holdings and Wilmar International exemplify plantation-anchored supply security across Southeast Asian feedstock networks. KLK OLEO occupies a specialist position in high-purity lauric acid fractions for European personal care markets. Godrej Industries represents the backward-integrated archetype through in-house coconut oil crushing operations in India. These three companies anchor the competitive map without dominating share, leaving room for mid-scale processors to capture pharmaceutical-grade and certified-sustainable niches.
| Leading Market Players |
|---|
| Mewah Group |
| Musim Mas Holdings |
| Wilmar International Ltd. |
| Royal Coconut Company |
| Godrej Industries Ltd. |
| Cargill, Incorporated |
| Vantage Specialty Chemicals, Inc. |
| PT. Energi Sumber Bumi |
| KLK OLEO |
| Others |
Value Chain & Pricing Dynamics
Singapore-Jakarta freight corridors transmit copra price volatility directly into European cosmetic compounder procurement costs, amplifying the margin compression that already runs through Philippine and Indonesian upstream concentration. This logistics-cost feedback loop forces downstream buyers toward long-term offtake structures while mid-scale processors exploit enzymatic flexibility to capture premium positioning.
Pricing Analysis
Cost-plus contracts indexed to Malaysian Palm Oil Board reference prices dominate lauric acid procurement between Indonesian integrated producers and German personal care formulators. Three-tier pricing structure across pharmaceutical-grade, cosmetic-grade, and technical-grade levels separates specification purity from handling format and certification documentation. Pricing pressure stems from El Niño-driven copra harvest variability compressing processor working capital cycles. Small-scale cosmetic manufacturers in Southern Europe exhibit highest price sensitivity, while parenteral-grade lipid buyers in Italian pharmaceutical clusters absorb premium differentials for CDSCO-compliant documentation.
Supply Chain Analysis
Extended payment terms through supply-chain finance facilities anchored in Singapore trading houses sustain working capital for Philippine copra crushers facing coconut levy restructuring uncertainty. Indonesian, Philippine, and Indian plantation networks feed 60-plus percent of global crude coconut oil throughput, with Medan and Surabaya clusters drawing downstream Asian chemical manufacturer investment. Raw material dependencies center on copra meal, immobilized lipase biocatalysts from Danish and Japanese suppliers, and natural gas for high-pressure splitting thermal inputs. Single-origination vulnerability to port logistics disruptions in Southeast Asian archipelago geography constitutes the dominant structural risk. Distribution runs through integrated plantation-to-oleochemical operators with captive fractionation capacity, supplemented by toll processors leveraging enzymatic interesterification licensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified sustainability documentation services expand faster than commodity fatty acid volume, creating recurring-revenue attachment opportunities for processors that integrate blockchain traceability into direct-to-manufacturer platforms.
For Market Incumbents: Entrench feedstock security through backward integration into Philippine and Indonesian plantation networks before Jakarta's tax incentive windows close. Secure immobilized lipase technology licensing from Japanese enzyme suppliers to defend specialty fraction margins against toll processor encroachment. REACH registration dossier maintenance represents the priority defensive lever as ECHA tightens skin sensitization endpoint requirements. For New Entrants and Emerging Players: Build out enzymatic interesterification toll processing capacity in Italian and Spanish pharmaceutical corridors where ambient-pressure production routes displace conventional high-pressure splitting assets. Indian parenteral-grade lipid demand under CDSCO tightening presents the most penetrable white-space target. Pursue direct-to-manufacturer digital platform positioning with RSPO and Fair Trade certification bundling to bypass entrenched oleochemical trading houses. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshape the acquisition landscape toward bio-based heat-transfer fluid formulators with caprylic acid fraction capabilities. Five-to-ten year viability favors integrated plantation-to-oleochemical operators with existing REACH dossier coverage over pure-play trading intermediaries. Watch for Indonesian export tariff restructuring announcements as the critical inflection signal for feedstock cost trajectory revision.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Networks | Captive copra supply insulates Musim Mas and Wilmar from Philippine levy volatility. |
| Enzymatic Interesterification Licensing | Ambient-pressure production routes enable toll processors to compete for pharmaceutical-grade contracts. |
| REACH Dossier Consolidation | ECHA substance data requirements squeeze non-integrated importers toward registered Indonesian producers. |
| Direct-to-Manufacturer Platform Launch | Blockchain traceability portals capture margin from California cosmetic compounders seeking lot-specific credentials. |
| CDSCO Parenteral-Grade Certification | Mumbai and Hyderabad pharmaceutical clusters drive premium positioning for caprylic acid fractions. |
Study Parameters
Desk research of customs trade databases, ECHA registration filings, and Indonesian downstream investment policy documents preceded structured interviews with oleochemical plant managers, procurement leads at German personal care OEMs, distribution channel partners in Singapore trading houses, and technical R&D directors at enzyme suppliers. Primary fieldwork across Medan, Surabaya, Mumbai, and Northern Italian pharmaceutical corridors combined with secondary validation from SEC 10-K disclosures and Cefic sector reports. Bottom-up capacity utilization modeling and top-down demand segmentation triangulation anchored volume estimates.
Assumption sets held EU F-Gas Regulation phase-down schedules and REACH registration timelines fixed while varying copra harvest yield scenarios and Indonesian export tariff structures across sensitivity bands. Segmentation dimensions modeled include carbon-chain length fraction, application chemistry tier, handling format, and regional production hub classification. CAGRs derived from slope-intercept extrapolation of historical trade flow data against projected downstream capacity additions. Industry-specific forecast inputs incorporated CDSCO purity standard implementation pacing and EU CBAM thermal input carbon border adjustment mechanism coverage expansion.
Sensitivities concentrate around El Niño drought cycle intensity, Indonesian coconut levy restructuring outcomes, and lipase immobilization technology licensing availability. Forecasts reflect documented assumptions on regulatory implementation fidelity and plantation yield stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Sodium Hydroxide Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Food Processing Ingredients Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Titanium-Free Food Color Alternatives Market
Food Additives and Ingredients
Alpha-Amylase Baking Enzyme Market
Food Additives and Ingredients
Food Coating Ingredients Market
Food Additives and Ingredients
Sustained Release Excipients Market
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Mexico Food Enzymes Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Beverages Additives Market
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
North America Food Anti Caking Agents Market
Food Additives and Ingredients
Octadecanedioic Acid (ODDA) Market