
 Global Radar Sensor Market | 2026-2036
Global Radar Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radar Sensor Market Foresight
China's Yangtze River Delta manufacturing cluster is reconfiguring regional supply chains for millimeter-wave radar modules. Robert Bosch GmbH leverages its Stuttgart engineering base to sustain dominance in 77 GHz automotive radar systems. Infineon Technologies AG anchors European semiconductor supply for radar chipsets through its Dresden fabrication complex. NXP Semiconductors competes in short-range radar silicon with specialized 40 nm process technology for blind-spot detection modules.
A radar sensor emits radio waves and detects reflected signals to determine object range, velocity, and angle, typically operating between 24 GHz and 77 GHz for automotive applications with detection ranges from 0.5 meters to 250 meters depending on antenna configuration and power output. These devices serve collision avoidance, adaptive cruise control, and autonomous navigation systems by providing real-time environmental mapping independent of weather or lighting conditions. Short-range radar modules command premium positioning in parking assistance and cross-traffic alert systems where angular resolution requirements exceed long-range alternatives. Frequency modulated continuous wave technology leads volume shipments for automotive applications due to its simultaneous range and velocity measurement capability, while phased array architectures gain traction in defense and aerospace end uses where electronic beam steering eliminates mechanical components.
The EU's General Safety Regulation and CE marking requirements under the Radio Equipment Directive shape product certification timelines for radar sensor manufacturers accessing European vehicle assembler contracts. The US NHTSA Federal Motor Vehicle Safety Standards and FCC Part 15 rules govern emission limits and spectrum allocation for 60-64 GHz and 76-81 GHz bands in domestic automotive deployments. China's MIIT radio frequency allocations and GB standards for vehicular radar establish technical thresholds for domestic and export-qualified suppliers. Stakeholders must monitor evolving spectrum harmonization between regional regulators to preserve cross-platform design economics.
Market Dynamics
Automotive radar sensor supply chains are compressing around 77 GHz frequency modulated continuous wave architectures as tier-one suppliers consolidate chip-to-module integration capabilities. This technical convergence is eliminating discrete component sourcing layers while OEMs demand single-supplier accountability for ADAS performance validation.
Growth Catalysts
- EU General Safety Regulation:Mandated advanced driver assistance systems in new vehicle platforms create binding procurement volumes for long-range and short-range radar modules across European vehicle assemblers.
- China's Yangtze River Delta:Domestic electric vehicle manufacturers source radar modules locally, building captive supply ecosystems for autonomous driving platforms with integrated perception stacks.
- Millimeter-wave frequency migration:77 GHz systems deliver superior angular resolution and range precision compared to legacy 24 GHz alternatives, compelling platform redesigns across premium and mass-market vehicle segments.
Market Restraints
- Silicon germanium substrate concentration:Foundry capacity for radar-specific semiconductor processes concentrates in European and East Asian fabrication complexes, creating input bottlenecks during demand surges.
- Spectrum allocation fragmentation:Divergent national radio frequency allocations between 76-81 GHz and 60-64 GHz bands force redundant product variants, inflating engineering overhead for multi-market certification.
- LiDAR cost compression:Solid-state optical sensing alternatives achieve price parity in certain autonomous navigation applications, pressuring radar positioning in high-resolution environmental mapping segments.
Strategic Opportunities
- India's automotive safety mandate expansion:Proposed NCAP alignment and potential ADAS requirements in commercial vehicle categories open greenfield radar deployment in price-sensitive market tiers.
- Drone and urban air mobility platforms:Detect-and-avoid systems for low-altitude flight corridors represent emerging volume demand with distinct form-factor and weight requirements from automotive specifications.
- Industrial automation convergence:Radar sensors integrated with collaborative robotics for human presence detection in manufacturing environments leverage existing 60 GHz chipset investments with modified antenna configurations.
Industry Challenges
- Radio frequency engineering talent scarcity:Specialized expertise in antenna design and electromagnetic simulation for automotive-grade reliability remains concentrated among experienced practitioners in Germany, Japan, and the United States.
- Functional safety certification timelines:ISO 26262 ASIL-B and ASIL-C validation for radar-based emergency braking systems extends development cycles by 12-18 months, compressing platform launch windows.
- Legacy vehicle electrical architecture integration:Older CAN bus and power distribution systems in existing fleets require costly gateway modules to support radar sensor data throughput and latency requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radar Sensor Market |
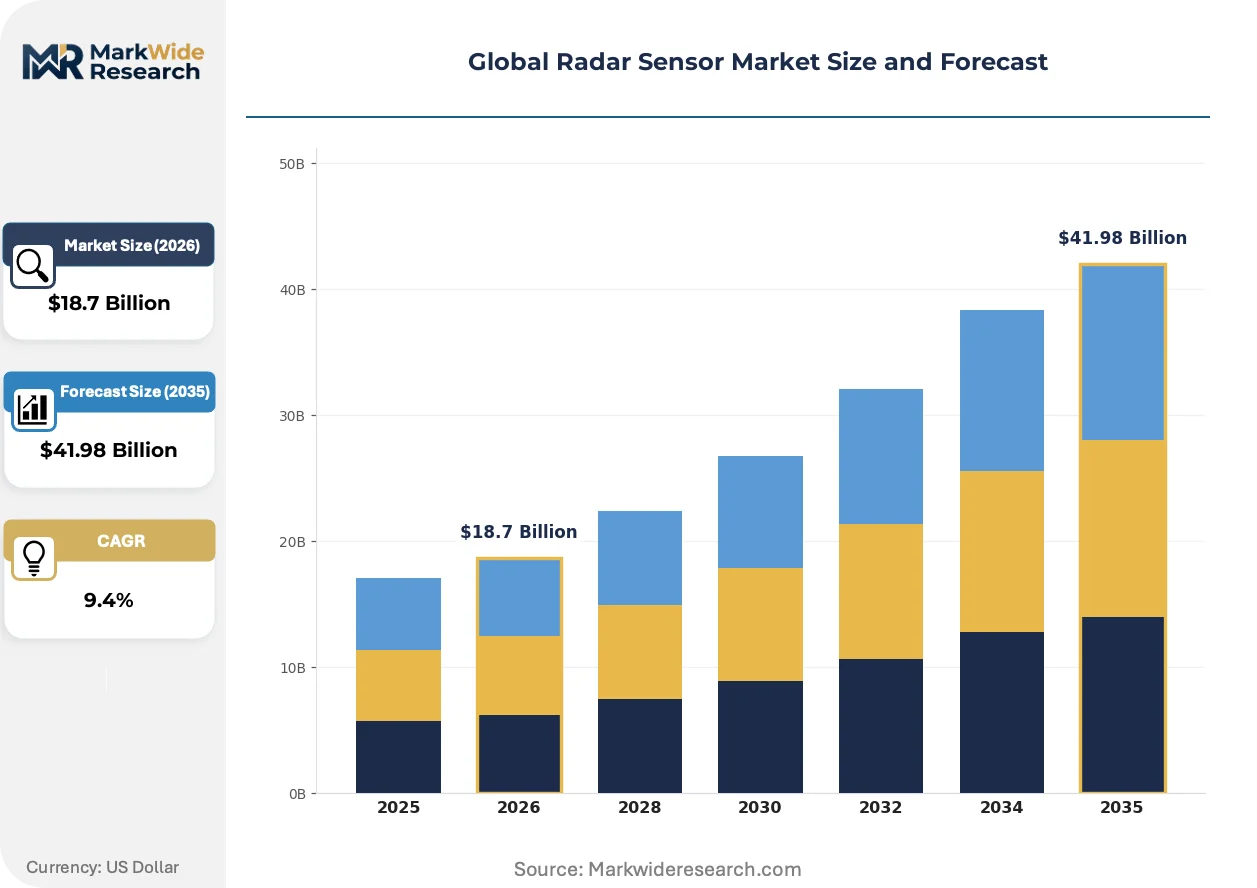
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Short-Range Radar, Mid-Range Radar, Long-Range Radar, Ultra-Wideband Radar Technology: Doppler, Frequency Modulated Continuous Wave, Pulse Radar, Phased Array Application: Collision Avoidance, Speed Measurement, Object Detection, Navigation Assistance End User: Vehicle Assemblers, Aerospace Manufacturers, Defense Contractors, Shipment Tracking Providers |
| Companies Covered | Robert Bosch GmbH, Continental AG, Infineon Technologies AG, DENSO Corporation, ZF Friedrichshafen AG, HELLA GmbH & Co. KGaA, Lockheed Martin Corporation, NXP Semiconductors, Texas Instruments Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radar Sensor Market Shifts & Advancements
Radar sensor architectures are consolidating around system-on-chip designs that merge radio frequency front-ends with digital signal processing, eliminating discrete component boundaries. This integration wave is compressing supplier tiers and redefining competitive differentiation toward software-defined perception capabilities.
Silicon germanium bipolar CMOS technology is collapsing the cost curve for 77 GHz automotive radar modules while maintaining thermal performance under hood-mounted operating conditions. Tier-one suppliers in Germany and Japan are adopting these integrated chipsets for next-generation adaptive cruise control platforms. The technology is collapsing the historical separation between radar module manufacturers and semiconductor foundries, forcing tier-one suppliers to deepen direct silicon partnerships.
China's MIIT radio frequency allocations for vehicular radar under GB standards are harmonizing technical thresholds with European UNECE frameworks, reducing certification duplication for export-qualified suppliers. This alignment accelerates product launch timelines for radar manufacturers serving both domestic Chinese and European vehicle assembler contracts. The regulatory convergence most benefits mid-range radar module producers seeking scale economies across multiple geography-qualified product lines.
Fleet operators and mobility service providers are consolidating radar sensor procurement around performance-based specifications rather than branded component sourcing. Automotive OEMs respond with modular radar platforms that support software upgrade pathways for evolving autonomous driving functionality. This specification-driven purchasing pattern is most visible in China's electric vehicle sector, where domestic producers prioritize cost-optimized radar integration for volume autonomous driving deployment.
Global Radar Sensor Market Segmentation
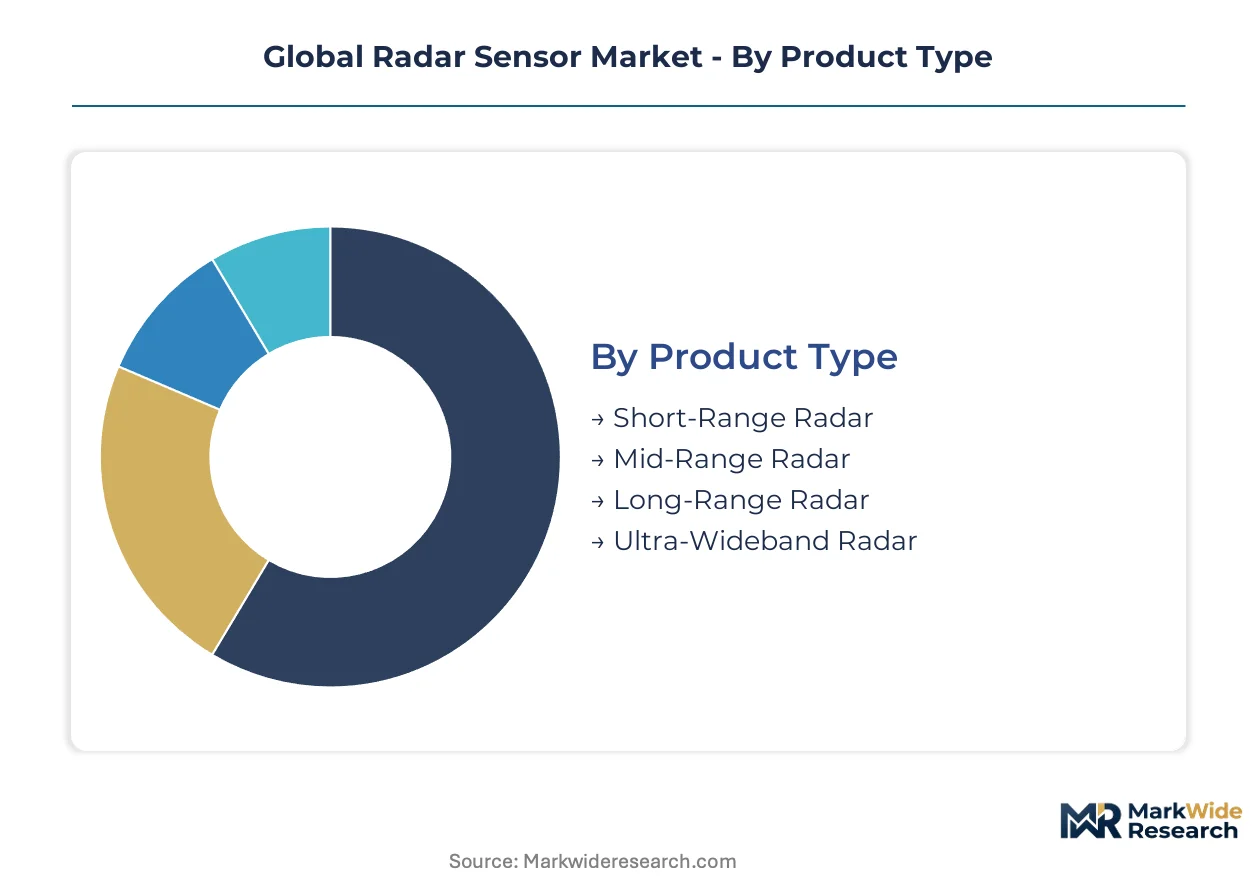
Radar sensor segmentation reveals distinct engineering requirements across range capabilities and signal processing architectures. Product type and technology categories determine semiconductor substrate choices, antenna configurations, and regulatory certification pathways.
Product Type:
Mature long-range platforms coexist with emerging ultra-wideband architectures as automakers recalibrate perception stack layering.
- Short-Range Radar:Operates at 24 GHz or 77 GHz with detection ranges under 30 meters for parking assistance and blind-spot monitoring. German vehicle assemblers source these modules for urban maneuvering systems where angular resolution exceeds range requirements. Parking assistance mandates in Japan's Ministry of Land, Infrastructure, Transport and Tourism technical standards sustain procurement volumes.
- Mid-Range Radar:Bridges 30-100 meter detection envelopes for cross-traffic alert and lane-change assistance functions. China's Yangtze River Delta electric vehicle manufacturers integrate these modules as standard equipment across mid-tier autonomous driving platforms. MIIT GB standards for vehicular radar establish technical thresholds that domestic suppliers must meet for assembler qualification.
- Long-Range Radar:Achieves 150-250 meter detection for highway adaptive cruise control and emergency braking.
- Ultra-Wideband Radar:Occupies 3.1-10.6 GHz spectrum for high-resolution imaging in confined environments.
Long-range radar retains volume leadership; ultra-wideband radar holds the steepest expansion curve.
Technology:
Cost tier stratification separates volume automotive deployments from aerospace-grade precision systems requiring electronic beam steering.
- Frequency Modulated Continuous Wave:Simultaneously measures range and velocity through continuous frequency modulation, eliminating range-Doppler ambiguity. Stuttgart-based tier-one suppliers consolidate chip-to-module integration around 77 GHz SiGe BiCMOS implementations for adaptive cruise control platforms. The technology dominates automotive shipments due to component count reduction and thermal performance under hood-mounted conditions.
- Phased Array:Enables electronic beam steering without mechanical components through controlled phase relationships across antenna elements. Defense contractors in the United States and France specify these architectures for missile guidance and airborne surveillance where rapid beam repositioning is mission-critical. NRE costs limit adoption outside aerospace and defense end uses.
- Doppler:Measures velocity through frequency shift analysis of reflected signals.
- Pulse Radar:Transmits discrete energy bursts for long-range detection in maritime and aviation applications.
Frequency modulated continuous wave technology commands the dominant cost tier; phased array systems occupy the premium aerospace and defense tier.
Application:
Customer type differentiation separates OEM-integrated safety systems from aftermarket speed enforcement procurement.
- Collision Avoidance:Integrates radar perception with braking actuation for automatic emergency intervention. EU General Safety Regulation mandates for heavy commercial vehicles create binding procurement volumes across European vehicle assemblers. ISO 26262 ASIL-C functional safety certification extends development cycles but secures platform exclusivity for qualified suppliers.
- Navigation Assistance:Fuses radar returns with inertial measurement for autonomous positioning in GPS-denied environments. Shipment tracking providers in the United States deploy these systems for yard management and port automation where satellite signal occlusion is common. FCC Part 15 emission limits constrain 60-64 GHz implementations in indoor logistics settings.
- Speed Measurement:Law enforcement agencies and traffic management authorities deploy dedicated Doppler units.
- Object Detection:Industrial automation and robotics applications leverage 60 GHz variants for human presence sensing.
Collision avoidance retains volume leadership; navigation assistance holds the steepest expansion curve.
End User:
Supply concentration patterns diverge between automotive scale manufacturing and defense contract batch production.
- Vehicle Assemblers:Consolidate procurement around tier-one module suppliers capable of ASIL-certified system integration. Germany's KBA type approval requirements and Japan's Ministry of Land, Infrastructure, Transport and Tourism technical standards create dual certification burdens for export-qualified suppliers. Single-source accountability demands compress supplier tiers toward semiconductor-foundry partnerships.
- Defense Contractors:Procure phased array and pulse radar systems through national security classified procurement channels. France's Direction Générale de l'Armement and the United States Department of Defense maintain distinct technical specifications that fragment addressable markets. ITAR and EU dual-use export controls constrain supplier mobility across NATO and partner nations.
- Aerospace Manufacturers:Specify radar altimeters and weather detection for commercial aviation platforms.
- Shipment Tracking Providers:Deploy radar for yard management and container positioning in logistics hubs.
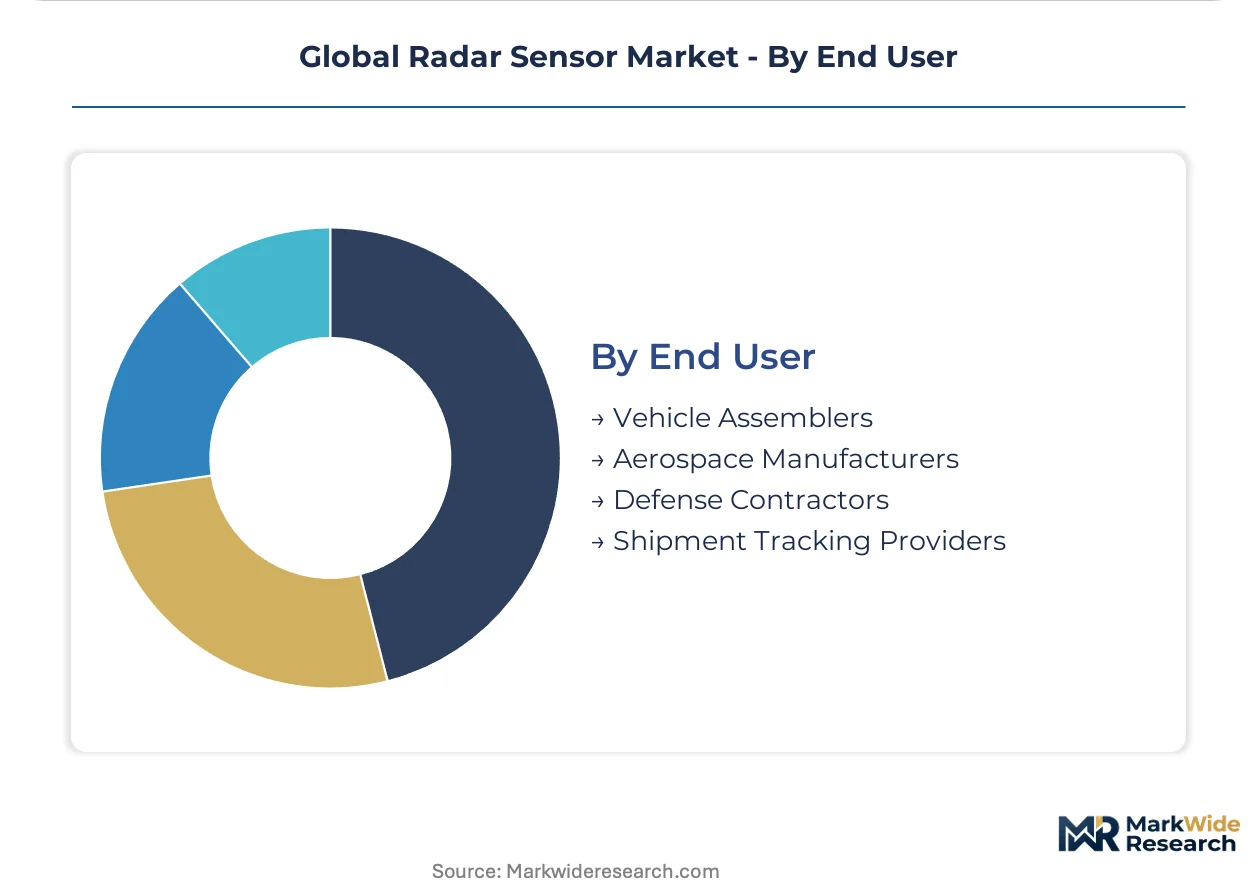
Vehicle assemblers retain volume leadership; shipment tracking providers hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radar sensor fabrication concentrates in European and East Asian foundry complexes, with module integration gravitating toward German engineering centers and China's eastern manufacturing corridor. Tier-one suppliers compress chip-to-module capabilities around 77 GHz architectures, reconfiguring procurement geography for automotive assemblers.
Germany
Stuttgart-based engineering clusters sustain dominance in 77 GHz automotive radar systems through captive semiconductor partnerships. The KBA type approval requirements create dual certification burdens for export-qualified suppliers seeking European vehicle assembler contracts. Bavaria's precision manufacturing ecosystem anchors functional safety validation for ASIL-certified emergency braking platforms.
China
Domestic electric vehicle manufacturers in the Yangtze River Delta source radar modules locally, building integrated perception stacks for autonomous driving platforms. MIIT radio frequency allocations under GB standards establish technical thresholds that domestic suppliers must meet for assembler qualification. Shanghai's manufacturing corridor reconfigures regional supply chains for millimeter-wave module production.
United States
Defense contractors in aerospace corridors sustain demand for phased array architectures with electronic beam steering capabilities. FCC Part 15 rules govern emission limits and spectrum allocation for 60-64 GHz and 76-81 GHz bands in domestic automotive deployments. California's autonomous vehicle testing ecosystem drives procurement for navigation assistance radar in GPS-denied environments.
Japan
Ministry of Land, Infrastructure, Transport and Tourism technical standards sustain procurement volumes for short-range radar in parking assistance systems. Nagoya's automotive supplier cluster integrates 77 GHz frequency modulated continuous wave modules for adaptive cruise control platforms. Kansai-based tier-one suppliers consolidate chip-to-module capabilities around silicon germanium bipolar CMOS implementations.
India
Proposed NCAP alignment and potential ADAS requirements in commercial vehicle categories open greenfield radar deployment opportunities. The country's automotive safety mandate expansion targets price-sensitive market tiers with localized module sourcing. Tamil Nadu's vehicle assembly corridor attracts tier-one suppliers seeking scale economies in emerging safety system categories.
Global Radar Sensor Market Competitive Landscape
Integrated semiconductor-module specialists and discrete component suppliers split the market along vertical integration fault lines. Tier-one automotive suppliers consolidate chip-to-module capabilities, eliminating discrete sourcing layers while OEMs demand single-supplier accountability for ADAS performance validation. Two strategic archetypes dominate: Stuttgart-engineered system houses with captive silicon partnerships, and East Asian fabricators with scale-driven cost structures. Competitive moves center on semiconductor-foundry partnerships and software-defined perception capability acquisition.
Within the integrated system house tier, Robert Bosch GmbH and Continental AG exemplify European engineering-centric positioning with deep semiconductor partnerships. Infineon Technologies AG anchors European supply for radar chipsets through fabrication assets, while NXP Semiconductors occupies a position in short-range radar silicon specialization. DENSO Corporation represents Japanese tier-one integration capabilities, and Texas Instruments Incorporated sits within the semiconductor supplier archetype serving module manufacturers. These entities collectively illustrate the market's consolidation around chip-to-module integration capabilities and software-defined differentiation vectors.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Infineon Technologies AG |
| DENSO Corporation |
| ZF Friedrichshafen AG |
| HELLA GmbH & Co. KGaA |
| Lockheed Martin Corporation |
| NXP Semiconductors |
| Texas Instruments Incorporated |
| Others |
Supply & Pricing Matrix
The Yangtze River Delta freight corridor channels radar module logistics from Shanghai's wafer fabs to Stuttgart engineering centers, concentrating transport cost leverage among German tier-one suppliers while Chinese domestic producers exploit localized sourcing for price differentiation in electric vehicle platforms. This corridor's cost dynamics amplify pricing power for integrated semiconductor-module houses and compress margins for discrete component suppliers lacking captive silicon partnerships.
Pricing Analysis
The EU's General Safety Regulation dictates the pricing tier structure across European vehicle assembler contracts, separating ASIL-certified premium modules from standard-grade alternatives through functional safety validation requirements. Price differentiation rests on certification grade and volume scale, with mass-market EV producers in China exhibiting highest price sensitivity against German premium OEMs absorbing certification premiums. Pricing pressure stems from LiDAR cost compression in high-resolution mapping segments, forcing radar suppliers to defend positioning through software-defined perception bundling.
Supply Chain Analysis
TSMC and GlobalFoundries hold foundry capacity for 77 GHz silicon germanium BiCMOS processes, while Infineon's Dresden complex and Samsung's Hwasung lines anchor radar-specific semiconductor fabrication. Raw material dependencies center on high-purity silicon substrates, gallium arsenide for phased array components, and specialized laminate materials for antenna substrates. Single-source vulnerability concentrates in European and East Asian fabrication complexes, with distribution running through tier-one module suppliers directly to vehicle assembler integration lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Radar sensor markets occupy early-cycle expansion territory, with EU ADAS mandates and China's autonomous driving platform deployment providing structural tailwinds for module procurement volumes across the analysis window.
For Market Incumbents: Pre-empt LiDAR displacement in high-resolution environmental mapping by deepening software-defined perception capabilities and securing ASIL-D certification pathways for next-generation emergency braking platforms. Prioritize backward integration into silicon germanium foundry partnerships to eliminate substrate cost volatility exposure. Lock tier-two supplier conversion through performance-based specifications rather than branded component sourcing.
For New Entrants and Emerging Players: India's proposed NCAP alignment and commercial vehicle ADAS requirements represent the most penetrable entry point among price-sensitive market tiers, with localized module sourcing mandates favoring domestic assembly partnerships. Drone detect-and-avoid systems for urban air mobility corridors offer second-mover positioning with distinct form-factor requirements from automotive specifications. Pursue qualification under harmonized MIIT-UNECE frameworks to access both Chinese and European assembler contracts through single certification investment.
For Investors and Strategic Acquirers: Carve-out targets emerge from defense contractor radar divisions seeking to monetize non-core automotive-adjacent phased array intellectual property. Long-term viability favors integrated semiconductor-module specialists with captive silicon partnerships and software-defined differentiation vectors over discrete component suppliers facing tier compression. Watch fleet operator procurement consolidation around specification-driven purchasing as the inflection signal for modular platform winners.
| Strategic Initiative | Industry Significance |
|---|---|
| System-on-Chip Integration | Infineon and NXP consolidate RF front-ends with digital signal processing to eliminate discrete component boundaries. |
| 77 GHz Platform Standardization | Bosch and Continental compress supplier tiers around frequency modulated continuous wave architectures for adaptive cruise control. |
| Software-Defined Perception Investment | DENSO acquires machine learning capabilities to differentiate radar modules through upgradeable environmental mapping. |
| Geographic Manufacturing Footprint | Tier-one suppliers establish Dresden and Shanghai corridors to satisfy KBA type approval and MIIT GB standards simultaneously. |
| Charging Infrastructure Partnership | Radar suppliers integrate with autonomous valet charging systems for electric vehicle fleet operators. |
Research Methodology
The analysis maps short-range, mid-range, and long-range radar architectures alongside frequency modulated continuous wave and phased array technologies, each validated through tier-one supplier procurement directors, OEM platform engineers, semiconductor foundry planning officers, and automotive regulatory affairs leads. Primary fieldwork combined with secondary validation from SEC 10-K filings, vehicle production databases, IHS Markit registration data, and MIIT radio frequency allocation records supports bottom-up and top-down triangulation across the modeling period.
Forecast assumptions held fixed the EU General Safety Regulation implementation trajectory and China's MIIT-UNECE harmonization pathway while varying electric vehicle penetration rates and LiDAR cost compression curves across vehicle class, propulsion architecture, and regional production cluster segmentation. CAGRs derive from installed base accumulation modeling and content-per-vehicle scaling, with semiconductor foundry capacity utilization and spectrum allocation fragmentation serving as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in automotive production volumes, semiconductor capital expenditure cycles, or raw material substrate pricing would shift the trajectory. Quarterly review of tier-one supplier order backlogs, foundry capacity announcements, and regulatory harmonization progress is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
Global PH Sensor Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
MEMS for Mobile Devices Market
Sensors and Controls
Global Industrial Smart Sensors Market
Sensors and Controls
Africa Robotic Sensors Market
Sensors and Controls
Bioacoustics Sensing Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Wireless Sensor Tags Market
Sensors and Controls
APAC Chemical Sensors Market
Sensors and Controls
Germany Digital Thermometer Market
Sensors and Controls
Europe Water Detection Sensors Market
Sensors and Controls
China Pressure Sensors Market