
 US Vibration Sensors Market | 2026-2036
US Vibration Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
US Vibration Sensors Market Analytics
Equipment-as-a-service leasing for industrial monitoring hardware is rewriting competitive entry barriers for vibration sensor suppliers. SKF USA Inc leverages its bearing-service heritage to bundle sensors with lubrication contracts, sustaining recurring revenue streams. Rockwell Automation Inc anchors factory-floor integration by embedding vibration diagnostics within its Logix control architecture. Emerson Electric Co competes through in-house production of piezoelectric sensing elements, controlling cost structures across its condition monitoring portfolio.
Vibration sensors measure mechanical oscillation amplitude, frequency, and phase, typically operating across bandwidths from 0.1 Hz to 30 kHz with sensitivities calibrated in mV/g or pC/g, to detect imbalance, misalignment, and bearing degradation in rotating equipment. Their primary commercial purpose centers on preventing unplanned shutdowns in capital-intensive operations where hourly downtime costs exceed sensor system prices by orders of magnitude. Accelerometers dominate product type revenue due to versatility across low-frequency structural health monitoring and high-frequency gearbox analysis, while MEMS technology is displacing traditional piezoelectric designs in cost-constrained automotive applications. Optical sensing retains premium positioning in aerospace testing environments where electromagnetic immunity and extreme temperature tolerance command specialized procurement budgets.
FAA airworthiness directives for rotorcraft drivetrain monitoring and OSHA machinery guarding standards collectively expand mandated sensor installations across US industrial and aviation assets. The Department of Transportation's rail safety mandates and FERC pipeline integrity management rules further broaden addressable demand for continuous vibration surveillance infrastructure. NHTSA defect investigation protocols increasingly reference accelerometer data traces, embedding sensor reliability into product liability frameworks. Stakeholders must weigh calibration traceability investments against the risk of excluded market access from forthcoming federal procurement standards requiring domestic sensor manufacturing or allied-country sourcing certifications.
Market Dynamics
Predictive maintenance mandates from OSHA and the Department of Energy are compressing sensor deployment cycles across US manufacturing, forcing asset owners to upgrade from periodic inspection to continuous vibration surveillance.
Growth Catalysts
- FAA rotorcraft directives:Airworthiness mandates for drivetrain monitoring expand accelerometer installations across commercial helicopter fleets and regional aviation operators.
- Texas Gulf Coast petrochemical density:Refinery uptime economics justify premium sensor instrumentation where unplanned shutdowns cost millions hourly.
- MEMS cost curves:Microelectromechanical manufacturing advances enable vibration sensing penetration into cost-constrained automotive and consumer applications previously served by piezoelectric alternatives.
Market Restraints
- Piezoelectric ceramic supply concentration:Lead zirconate titanate sourcing depends on limited domestic and allied-country manufacturers, exposing sensor producers to material availability shocks.
- Calibration infrastructure gaps:NIST-traceable vibration calibration facilities concentrate in aerospace clusters, creating certification bottlenecks for mid-market industrial sensor vendors.
- Optical sensing cost floors:Fiber-optic interferometer systems remain economically inaccessible for routine industrial monitoring despite superior electromagnetic immunity.
Strategic Opportunities
- Appalachian shale basin expansion:FERC pipeline integrity management rules create greenfield demand for continuous vibration monitoring across gathering and transmission infrastructure.
- Equipment-as-a-service bundling:Sensor hardware leasing combined with predictive analytics subscriptions transforms capital expenditure barriers into recurring revenue relationships.
- DOE industrial efficiency incentives:Federal grants for smart manufacturing retrofits subsidize vibration sensor deployment in energy-intensive process industries.
Industry Challenges
- Vibration analyst certification scarcity:ISO 18436-2 qualified personnel shortages constrain condition monitoring program scaling at multi-site industrial operators.
- Legacy control system integration:Proprietary industrial Ethernet protocols and aged PLC architectures complicate sensor data stream incorporation into existing plant historian systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Vibration Sensors Market |
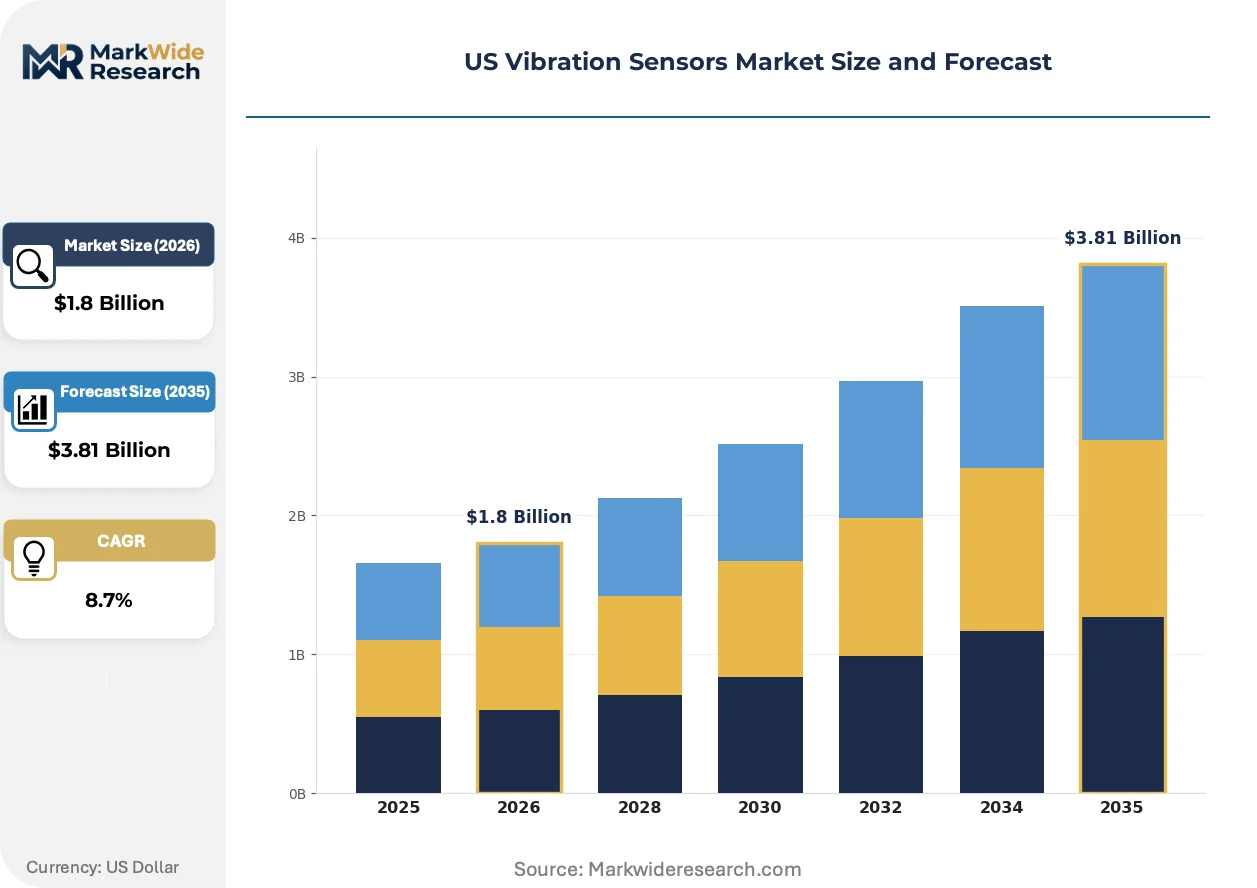
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accelerometers, Displacement Sensors, Velocity Sensors, Sensors with Digital Output Technology: Piezoelectric, MEMS, Optical, Capacitive Application: Structural Health Monitoring, Machinery Condition Monitoring, Automotive Systems, Aerospace Testing End User: Manufacturing, Automotive, Aerospace, Energy |
| Companies Covered | SKF USA Inc, Rockwell Automation Inc, Honeywell International Inc, TE Connectivity Ltd, Analog Devices Inc, Emerson Electric Co, National Instruments Corporation, PCB Piezotronics, Texas Instruments Incorporated, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Vibration Sensors Market Evolving Landscape
Wireless vibration sensing architectures and edge-computing analytics are collapsing the traditional separation between data acquisition hardware and diagnostic software layers.
MEMS accelerometers with integrated digital signal processing are rendering obsolete standalone charge amplifiers and external conditioning electronics in mid-frequency industrial applications. Food processing and packaging machinery OEMs are adopting these compact units for bearing fault detection. The elimination of analog cabling infrastructure is compressing installed system costs and enabling rapid retrofit deployment.
OSHA machinery guarding standards are tightening equipment surveillance requirements across metalworking and material handling operations. The 2023 directive updates mandate continuous monitoring for rotating assemblies above specified power thresholds. Metal fabrication shops in the Great Lakes industrial corridor are accelerating sensor procurement to achieve compliance before enforcement phase-ins.
Asset owners are unbundling predictive maintenance contracts from original equipment manufacturer service agreements. Third-party vibration monitoring specialists are capturing data interpretation work previously captive to machinery builders. This disintermediation is most pronounced in pulp and paper mills across the Pacific Northwest, where specialized condition monitoring firms now operate independent of press and dryer OEM service networks.
US Vibration Sensors Market Segmentation
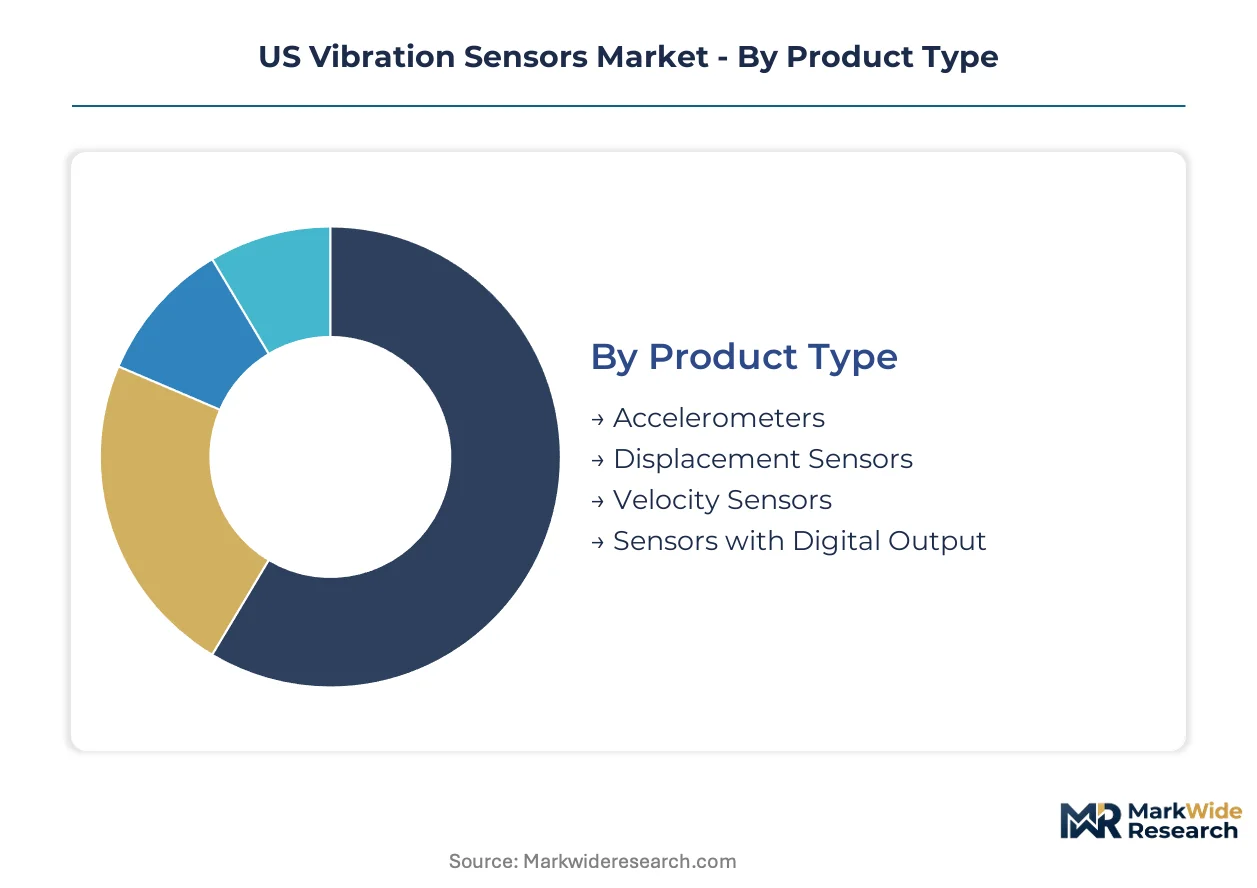
US Vibration Sensors Market segmentation reveals how sensor specifications, fabrication methods, and deployment contexts create distinct procurement channels. Each dimension—product type, technology, application, and end user—carries unique certification requirements and pricing structures that shape supplier positioning.
Product Type:
Cost tier differentiation across product types separates premium instrumentation from commoditized sensing elements.
- Accelerometers:These devices measure vibration amplitude across 0.1 Hz to 30 kHz bandwidths with sensitivities calibrated in mV/g or pC/g. Demand concentrates in Texas Gulf Coast petrochemical corridors where refinery uptime economics justify premium instrumentation capable of detecting bearing degradation before catastrophic failure.
- Sensors with Digital Output:Integrated digital signal processing eliminates standalone charge amplifiers and external conditioning electronics. Food processing machinery OEMs across the Great Lakes industrial corridor are adopting these compact units for rapid retrofit deployment and reduced installed system costs.
- Displacement Sensors:Eddy-current and laser-based designs measure shaft position and runout in rotating machinery with non-contact precision.
- Velocity Sensors:Seismic velocity transducers excel in low-frequency structural monitoring applications where displacement measurement is impractical.
Accelerometers hold installed capacity. Sensors with Digital Output are rotating up the share rankings.
Technology:
Application context determines technology selection, with electromagnetic immunity and temperature tolerance driving premium procurement decisions.
- MEMS:Microelectromechanical manufacturing advances enable penetration into cost-constrained automotive applications previously served by piezoelectric alternatives. NHTSA defect investigation protocols increasingly reference accelerometer data traces, embedding MEMS reliability into product liability frameworks.
- Piezoelectric:Lead zirconate titanate ceramic elements deliver wide dynamic range and stability across extreme temperatures. FAA airworthiness directives for rotorcraft drivetrain monitoring sustain demand for these proven sensing elements in commercial helicopter fleets.
- Optical:Fiber-optic interferometer systems command specialized procurement budgets in aerospace testing environments where electromagnetic immunity is non-negotiable.
- Capacitive:Silicon micromachined capacitive designs serve consumer electronics and low-cost industrial monitoring with moderate performance requirements.
Piezoelectric technology holds installed capacity. MEMS is rotating up the share rankings.
Application:
Volume concentration varies dramatically by application, with capital-intensive operations absorbing premium sensor system prices.
- Machinery Condition Monitoring:Continuous vibration surveillance prevents unplanned shutdowns where hourly downtime costs exceed sensor system prices by orders of magnitude. OSHA machinery guarding standards mandate continuous monitoring for rotating assemblies above specified power thresholds, accelerating sensor procurement in metal fabrication shops.
- Aerospace Testing:Optical sensing retains premium positioning where extreme temperature tolerance and electromagnetic immunity justify specialized instrumentation budgets. FAA directives expand mandated sensor installations across regional aviation operators and commercial helicopter fleets.
- Structural Health Monitoring:Bridge and building instrumentation employs low-frequency accelerometers for long-term degradation tracking.
- Automotive Systems:MEMS cost curves enable vibration sensing penetration into vehicle dynamics control and powertrain monitoring.
Machinery Condition Monitoring holds installed capacity. Aerospace Testing is rotating up the share rankings.
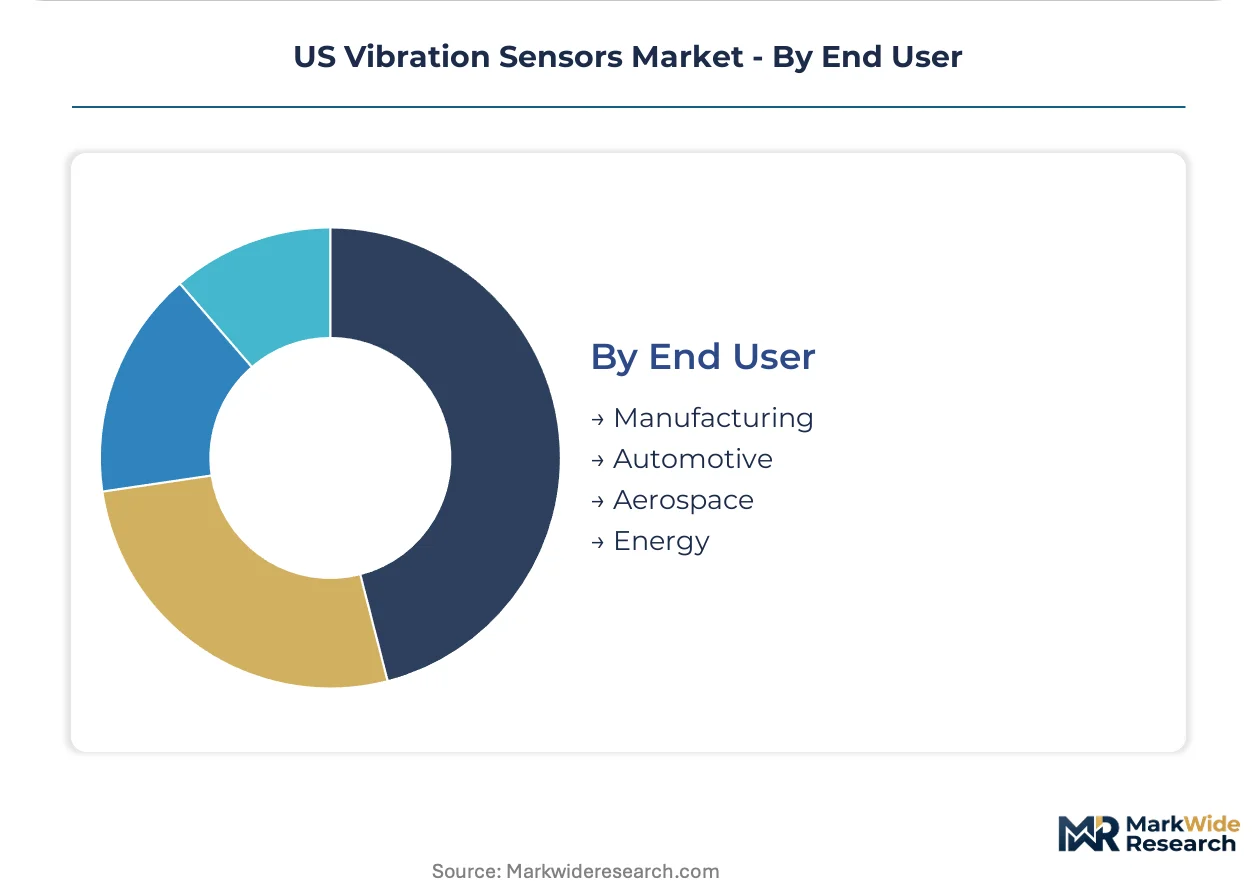
End User:
Customer type segmentation reflects divergent procurement authority structures and technical specification sophistication.
- Manufacturing:Predictive maintenance programs in US manufacturing plants are expanding sensor deployments as scheduled downtime gives way to condition-based intervention. Department of Energy industrial efficiency mandates tighten equipment surveillance requirements across energy-intensive process industries.
- Energy:FERC pipeline integrity management rules create greenfield demand for continuous vibration monitoring across Appalachian shale basin gathering and transmission infrastructure. Refinery uptime economics in Texas justify premium sensor instrumentation.
- Aerospace:FAA rotorcraft directives and airworthiness mandates drive accelerometer installations with strict calibration traceability requirements.
- Automotive:OEMs and Tier 1 suppliers integrate MEMS-based sensing for vehicle dynamics, powertrain monitoring, and safety systems.
Manufacturing holds installed capacity. Energy is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment buyers in US manufacturing and energy operations concentrate demand across distinct industrial corridors, with procurement authority varying by facility scale and technical sophistication. State-level energy mandates and federal safety directives reshape deployment patterns. Metropolitan clusters anchor sensor installation volumes.
Texas Gulf Coast
Petrochemical refineries and LNG export terminals drive continuous vibration surveillance adoption, where unplanned shutdowns cost millions hourly. OSHA Process Safety Management standards mandate equipment monitoring across high-hazard chemical facilities. The Houston Ship Channel concentration absorbs premium piezoelectric instrumentation for critical rotating machinery.
Appalachian Basin
Shale gas gathering infrastructure and pipeline compression stations create greenfield demand for ruggedized sensors. FERC pipeline integrity management rules require continuous monitoring across transmission networks. Pennsylvania and West Virginia wellhead clusters deploy wireless vibration architectures for remote asset surveillance.
Great Lakes Industrial Corridor
Metal fabrication and automotive stamping operations accelerate sensor procurement under updated OSHA machinery guarding directives. Department of Energy industrial efficiency grants subsidize smart manufacturing retrofits in Michigan and Ohio. Detroit-area automotive Tier 1 suppliers integrate MEMS-based monitoring into press and assembly line equipment.
Pacific Northwest
Pulp and paper mills disintermediate predictive maintenance from OEM service agreements, creating third-party monitoring specialist opportunities. FAA rotorcraft directives sustain accelerometer demand for commercial helicopter operators in Washington and Oregon. Boeing supplier networks in the Puget Sound region maintain aerospace-grade calibration traceability requirements.
Southeast Manufacturing Belt
Food processing and packaging machinery OEMs adopt compact digital-output sensors for rapid compliance deployment. USDA food safety modernization protocols intersect with OSHA equipment surveillance mandates in Georgia and North Carolina poultry processing plants. Charlotte-area industrial distributors report accelerating sensor inventory turns.
US Vibration Sensors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. The vendor base stratifies between integrated automation suppliers and component-focused sensing specialists. Three archetypes dominate: bearing-service heritage firms bundling hardware with maintenance contracts, control architecture providers embedding diagnostics within factory-floor systems, and piezoelectric element manufacturers controlling upstream material costs. Capacity expansion and strategic partnerships represent the dominant competitive vectors.
Among US-based industrial automation suppliers, SKF USA Inc, Rockwell Automation Inc, and Emerson Electric Co exemplify distinct positioning archetypes. SKF occupies the bearing-service bundling tier, leveraging rotating equipment heritage into recurring revenue relationships. Rockwell anchors factory-floor integration through control architecture dominance. Emerson represents upstream materials control, with in-house piezoelectric element production insulating cost structures. Each sits within a defendable procurement channel without direct segment overlap.
| Leading Market Players |
|---|
| SKF USA Inc |
| Rockwell Automation Inc |
| Honeywell International Inc |
| TE Connectivity Ltd |
| Analog Devices Inc |
| Emerson Electric Co |
| National Instruments Corporation |
| PCB Piezotronics |
| Texas Instruments Incorporated |
| Others |
Value Network & Pricing Analysis
Texas Gulf Coast petrochemical corridors anchor North American piezoelectric element production, with Houston-area ceramic foundries feeding sensor assembly operations across the Midwest. Their capacity utilization rates directly transmit into pricing power for vibration instrumentation destined for refinery condition monitoring programs.
Pricing Analysis
Certification level creates the primary spread between NIST-traceable aerospace-grade units and industrial maintenance sensors. Three-tier pricing structure across premium, standard, and economy levels separates FAA-compliant helicopter drivetrain monitors from food-processing retrofit accelerometers. Pricing pressure stems from MEMS cost compression in automotive applications, where semiconductor-scale manufacturing erodes piezoelectric market share. OEM procurement teams in Detroit exhibit highest price sensitivity, while Texas refinery reliability engineers absorb premium instrumentation costs given unplanned shutdown economics.
Supply Chain Analysis
Export-control restrictions on high-frequency accelerometer technology limit flows from US and allied-country manufacturers to designated end users. Lead zirconate titanate ceramic sourcing draws from domestic Pennsylvania suppliers and Japanese specialty ceramics producers, with limited alternative qualified vendors. Single-source vulnerability concentrates in aerospace-grade calibration equipment, where NIST-traceable vibration tables represent fixed infrastructure bottlenecks. Distribution runs through industrial automation distributors and bearing-service heritage firms with embedded maintenance contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists as asset owners disintermediate predictive maintenance from OEM service agreements, creating specialist niches for independent monitoring providers.
For Market Incumbents: Build calibration-traceability moats by securing NIST-accredited vibration laboratory capacity before federal procurement standards mandate domestic certification infrastructure. Defend against MEMS displacement in mid-frequency applications by embedding piezoelectric sensors within lubrication-service contracts that lock in recurring revenue. Capacity addition in Appalachian shale basin service hubs counters wireless sensor specialist encroachment into pipeline integrity monitoring. For New Entrants and Emerging Players: Appalachian Basin gathering infrastructure represents the most penetrable geography, with FERC pipeline rules creating greenfield demand absent entrenched incumbent relationships. Food processing machinery OEMs in the Southeast Manufacturing Belt offer rapid retrofit deployment opportunities for compact digital-output sensors. A direct-to-plant-engineer go-to-market angle bypasses distributor markups and captures price-sensitive metal fabrication shops under OSHA compliance deadlines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors MEMS-to-piezoelectric hybrid specialists with automotive qualification pathways and industrial crossover capability. Long-term viability hinges on sensor-as-a-service revenue model adoption, where hardware leasing plus analytics subscriptions transform capital expenditure barriers into recurring relationships. Watch for DOE industrial efficiency grant acceleration as the inflection signal for smart manufacturing retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Infrastructure Investment | NIST-traceable laboratory capacity secures federal procurement compliance before mandated domestic sourcing rules take effect. |
| Sensor-as-a-Service Bundling | Hardware leasing with predictive analytics subscriptions transforms capital barriers into recurring revenue at Texas Gulf Coast refineries. |
| MEMS Technology Licensing | Automotive-qualified MEMS accelerometer IP enables penetration into cost-constrained industrial monitoring applications. |
| Wireless Architecture Development | Elimination of analog cabling infrastructure compresses installed costs for Appalachian Basin remote pipeline surveillance. |
| Vibration Analyst Certification Programs | ISO 18436-2 training capacity addresses personnel scarcity constraining condition monitoring program scaling. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors at Texas Gulf Coast refineries, vibration monitoring specialists in the Pacific Northwest pulp and paper sector, industrial automation procurement teams in Detroit, and aftermarket service heads at bearing-distribution networks. Secondary validation drew from FAA airworthiness directive filings, OSHA machinery guarding standard updates, FERC pipeline integrity management rulemakings, and Department of Energy industrial efficiency program disclosures. Bottom-up sensor shipment estimates triangulated against top-down capital expenditure patterns across petrochemical, automotive, and energy infrastructure end markets.
Calibration against historical deployment cycles anchored growth projections across the analysis window without assuming technology disruption acceleration. Segmentation modeling incorporated product type, sensing technology, application intensity, and end-user procurement sophistication dimensions. CAGRs derived from equipment replacement cycles, regulatory compliance phase-in schedules, and MEMS cost curve trajectories. Forecast inputs included refinery utilization rates, shale basin wellhead completion counts, and automotive production platform standardization trends.
The forecast holds incumbent behavior within observed patterns; aggressive moves by wireless sensor startups or semiconductor-scale MEMS entrants would shift outcomes. Material shifts in FAA rotorcraft directive enforcement timing, OSHA machinery guarding penalty structures, or lead zirconate titanate ceramic supply availability would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Environmental Sensing and Monitoring Technologies Market
Sensors and Controls
Sensor Patch Market
Sensors and Controls
Off-Highway Machine Position and Angle Sensor Components Market
Sensors and Controls
Fluid Sensors Market
Sensors and Controls
Digital Infrared Thermometer Market
Sensors and Controls
Hall-Effect Sensors Market
Sensors and Controls
Asia-Pacific Thermocouple Temperature Sensors Market
Sensors and Controls
Global Industrial Smart Sensors Market
Sensors and Controls
Ultrasonic Air in Line Sensor Market
Sensors and Controls
Current Calibrator Market
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
MEMS Combo Sensors Market
Sensors and Controls
ASEAN Safety Sensors and Switches Market
Sensors and Controls
Battery Free Wireless Sensor Market