
 Europe Fetal and Neonatal Care Equipment Market | 2026-2036
Europe Fetal and Neonatal Care Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fetal and Neonatal Care Equipment Market Foresight
A shift from single-source to multi-source procurement for critical neonatal components is realigning supply relationships across European hospital networks. Drägerwerk AG & Co. KGaA leverages its vertically integrated manufacturing footprint in Germany to dominate incubator and ventilator supply chains. Koninklijke Philips N.V. anchors its position through IT-enabled monitoring platforms that integrate wireless data streams into hospital information systems. Siemens Healthineers AG competes on diagnostic imaging interoperability with neonatal care workflows.
Europe fetal and neonatal care equipment encompasses electromechanical and IT-enabled devices designed to regulate thermal environment, respiratory function, and vital signs in preterm or compromised newborns, typically operating within precision ranges of 0.5°C temperature control and 1 bpm heart rate resolution. The primary purpose is to reduce neonatal mortality and morbidity through continuous physiological support and early intervention capability. Incubators and monitors command the largest installed base, while IT-enabled and wireless segments capture expanding margin pools as hospitals prioritize data integration and remote surveillance capabilities. Phototherapy equipment sustains steady replacement demand driven by jaundice treatment protocols, whereas resuscitation devices face elongated procurement cycles tied to capital budget approvals in public health systems.
The EU Medical Device Regulation (MDR) and CE marking framework impose escalating clinical evidence requirements on manufacturers of incubators and respiratory support devices, extending time-to-market for new product introductions. The European Medicines Agency (EMA) coordinates with notified bodies to harmonize post-market surveillance expectations across member states, pressuring smaller suppliers to consolidate or exit. REACH compliance for materials in prolonged skin-contact applications adds formulation constraints on device housings and mattress assemblies. Stakeholders must monitor regulatory transition timelines and notified body capacity bottlenecks to avoid supply disruptions during certificate renewal waves.
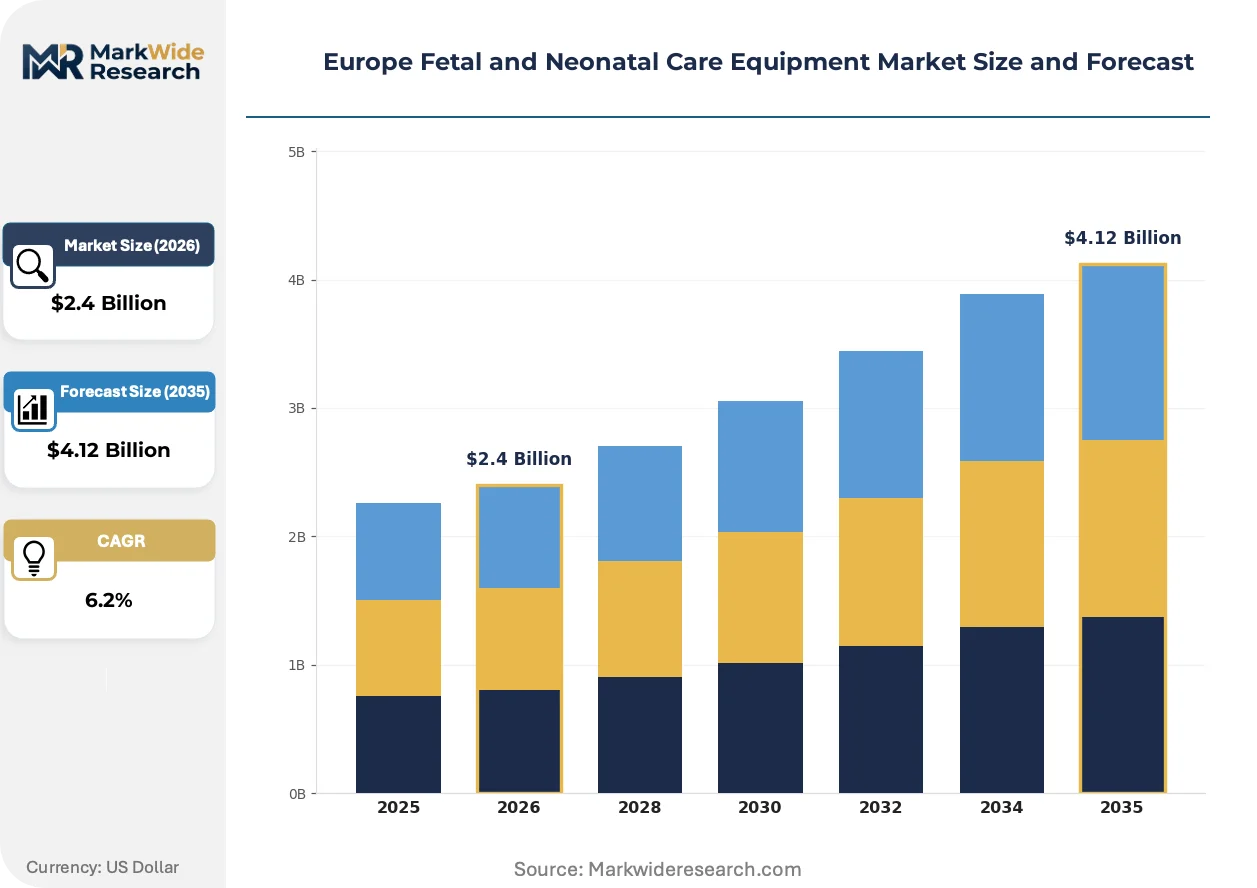
Market Dynamics
The EU Medical Device Regulation is compressing time-to-market for new incubator and ventilator introductions while simultaneously forcing hospital procurement offices toward multi-source supplier strategies to mitigate certificate renewal risks.
Growth Catalysts
- Preterm birth protocols:National health systems in Germany, France, and the United Kingdom are expanding NICU bed capacity and mandating minimum equipment density standards per tertiary care center.
- CE marking convergence:Harmonized conformity assessment pathways under the MDR are reducing cross-border trade friction for notified body-certified devices, accelerating pan-European distribution scale.
- Wireless telemetry:IT-enabled monitoring platforms with 1 bpm heart rate resolution are capturing procurement preference as hospitals prioritize physiological data integration into electronic health records.
Market Restraints
- Notified body bottlenecks:Capacity constraints at EU-authorized conformity assessment bodies are extending MDR certification timelines to 18-24 months, freezing product pipelines for mid-tier manufacturers.
- REACH material constraints:Phthalate restrictions and skin-contact polymer compliance costs are compressing margin pools on incubator mattress assemblies and housing formulations.
- Capital budget rigidity:Public hospital procurement cycles for resuscitation devices and phototherapy systems stretch across 36-48 month approval windows, elongating replacement demand.
Strategic Opportunities
- Central and Eastern Europe:NICU infrastructure in Poland, Romania, and Czechia remains underpenetrated relative to Western European equipment density benchmarks, creating greenfield installation demand.
- Remote surveillance convergence:Integration of wireless patient monitors with cloud-based clinical decision support systems is opening recurring revenue streams beyond device hardware sales.
- Green procurement mandates:EU Green Deal-aligned hospital purchasing criteria are favoring energy-efficient incubator designs with reduced thermal mass and recyclable component architectures.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in neonatal ventilation algorithm development and precision thermal control engineering is concentrating at a handful of German and Dutch research institutions.
- Legacy system interoperability:Integration of new IT-enabled monitors with proprietary hospital information systems from incumbent vendors requires costly middleware development and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fetal and Neonatal Care Equipment Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.12 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Incubators, Monitors, Resuscitation Devices, Phototherapy Equipment End User: Hospitals, Clinics, Home Care, Neonatal Units Technology: Electromechanical, IT-Enabled, Wireless, Standalone Application: Therapeutic, Diagnostic, Preventive, Monitoring |
| Companies Covered | Drägerwerk AG & Co. KGaA, F. Hoffmann-La Roche Ltd, Koninklijke Philips N.V., Siemens Healthineers AG, GE Healthcare, Medtronic PLC, Getinge AB, Fisher & Paykel Healthcare Ltd, Becton, Dickinson and Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fetal and Neonatal Care Equipment Market Shifts & Advancements
Neonatal care equipment is undergoing architectural transformation driven by regulatory compression, data integration imperatives, and supply chain reconfiguration pressures across European hospital networks.
Neonatal incubator platforms with swappable thermal regulation and respiratory support modules are modularizing product architectures to accommodate variable acuity levels within single device footprints. Tertiary NICUs in Germany and the Netherlands are piloting these configurations to reduce capital expenditure per patient bed while maintaining clinical flexibility. This modularity is compressing the traditional segmentation between intensive care incubators and intermediate care warming devices, forcing manufacturers to consolidate development roadmaps.
EMA coordination with notified bodies on post-market surveillance expectations is elevating clinical evidence requirements for respiratory support devices and phototherapy systems. Manufacturers must now submit extended follow-up data on preterm infant outcomes to maintain CE marking validity through certificate renewal cycles. Incubator and ventilator segments face the steepest compliance burden, with several mid-sized suppliers consolidating to share notified body application costs.
Hospital procurement offices are unbundling after-sales service contracts from equipment purchases and competitively tendering maintenance separately across multi-year frameworks. This disintermediation is compressing vendor margins on traditional full-service agreements while opening opportunities for independent service organizations. The United Kingdom's NHS Supply Chain and France's Resah purchasing consortia are most advanced in this separation, with Germany's university hospital networks following through 2025-2026 tender cycles.
Europe Fetal and Neonatal Care Equipment Market Segmentation
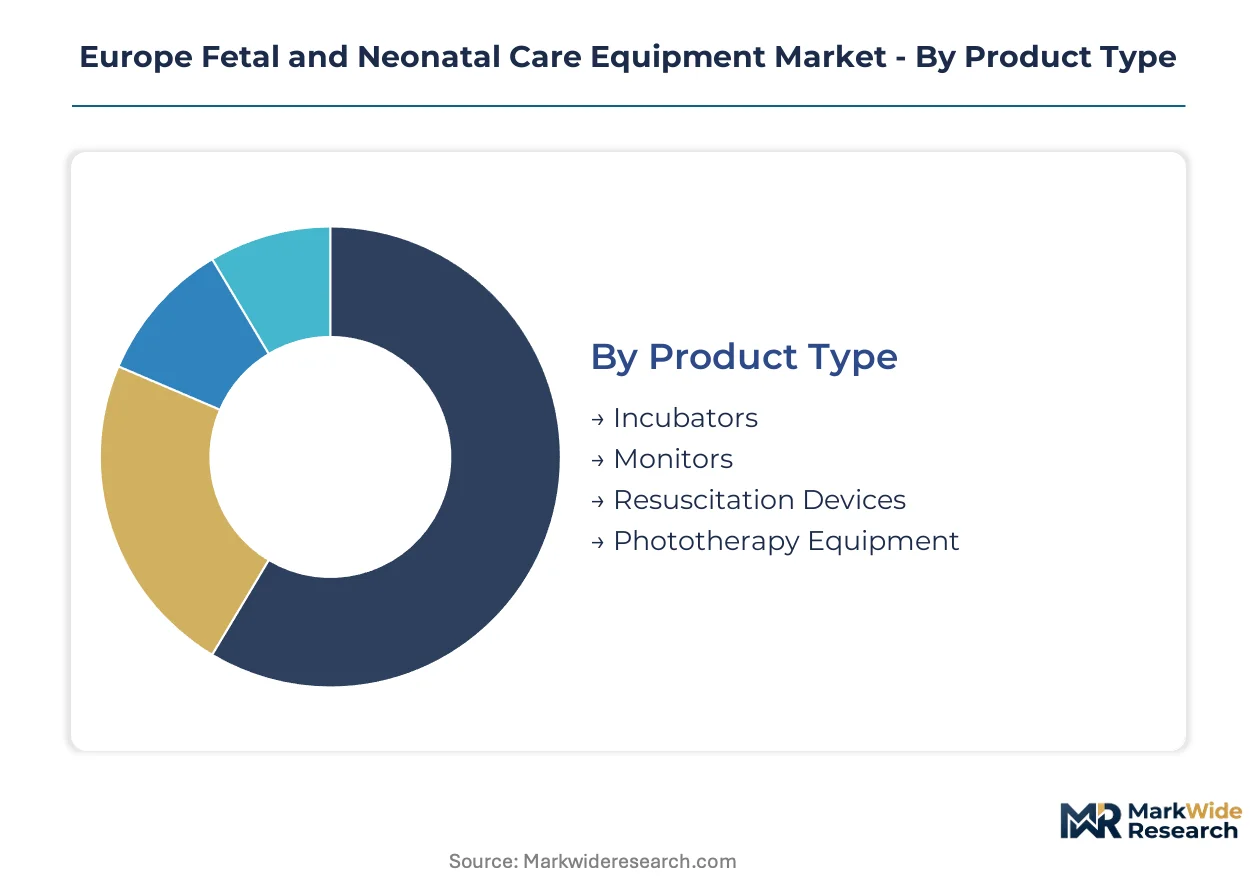
Segmentation in Europe's fetal and neonatal care equipment market reveals how procurement priorities diverge across clinical settings and technology maturity levels. Understanding these splits exposes where capital concentrates versus where replacement cycles accelerate.
Product Type:
Customization intensity varies sharply across this category, from precision-engineered thermal systems to standardized phototherapy arrays.
- Incubators:Double-walled thermal regulation systems with servo-controlled humidification maintain 0.5°C precision for preterm infants. German and French tertiary NICUs drive specification upgrades toward modular platforms with swappable respiratory modules. REACH compliance costs for polymer housings compress margin pools on new installations.
- Monitors:IT-enabled platforms with 1 bpm heart rate resolution integrate wireless telemetry into hospital information systems. Procurement in the United Kingdom and Netherlands prioritizes EHR interoperability over standalone functionality. MDR clinical evidence requirements extend replacement cycles for mid-tier suppliers.
- Resuscitation Devices:Positive pressure ventilation systems with T-piece connectors serve delivery room protocols.
- Phototherapy Equipment:LED-based jaundice treatment arrays follow standardized irradiance protocols with shorter procurement windows.
Most installed capacity flows through Incubators. Expansion is steepest in Monitors.
End User:
Capital intensity and regulatory exposure stratify sharply across this category, from centralized tertiary infrastructure to distributed home settings.
- Hospitals:Tertiary centers with Level III NICU designation concentrate procurement of integrated monitoring ecosystems. Public budget frameworks in Germany and France sustain 36-48 month capital cycles for incubator fleet renewal. EMA-coordinated post-market surveillance elevates compliance burdens on multi-device installations.
- Neonatal Units:Dedicated perinatal centers within hospital networks command priority allocation of IT-enabled respiratory support. United Kingdom NHS Supply Chain tenders increasingly separate equipment from service contracts. Wireless telemetry integration drives specification divergence from general pediatric wards.
- Clinics:Secondary maternity facilities operate intermediate care warming devices with reduced acuity specifications.
- Home Care:Portable monitoring and phototherapy systems serve post-discharge surveillance protocols.
Procurement volume concentrates in Hospitals. Capability investment is climbing fastest in Neonatal Units.
Technology:
Architecture maturity spans from legacy electromechanical platforms to emerging wireless telemetry stacks with cloud backend dependencies.
- IT-Enabled:Networked monitoring platforms with HL7 FHIR interoperability embed clinical decision support algorithms. Dutch university hospital networks pilot centralized surveillance stations spanning multiple NICU pods. GDPR compliance for neonatal physiological data adds deployment complexity absent in standalone alternatives.
- Wireless:Battery-powered telemetry patches eliminate tethering constraints during kangaroo mother care. Pilot programs in Belgian and Swedish tertiary centers validate transmission reliability for critical alarms. EU AI Act scrutiny of automated alert thresholds shapes algorithm development roadmaps.
- Electromechanical:Hardwired thermal regulation and analog monitoring systems persist in legacy installations.
- Standalone:Non-networked devices serve backup redundancy and budget-constrained procurement scenarios.
Electromechanical platforms retain the largest installed base. IT-Enabled systems are gaining share fastest.
Application:
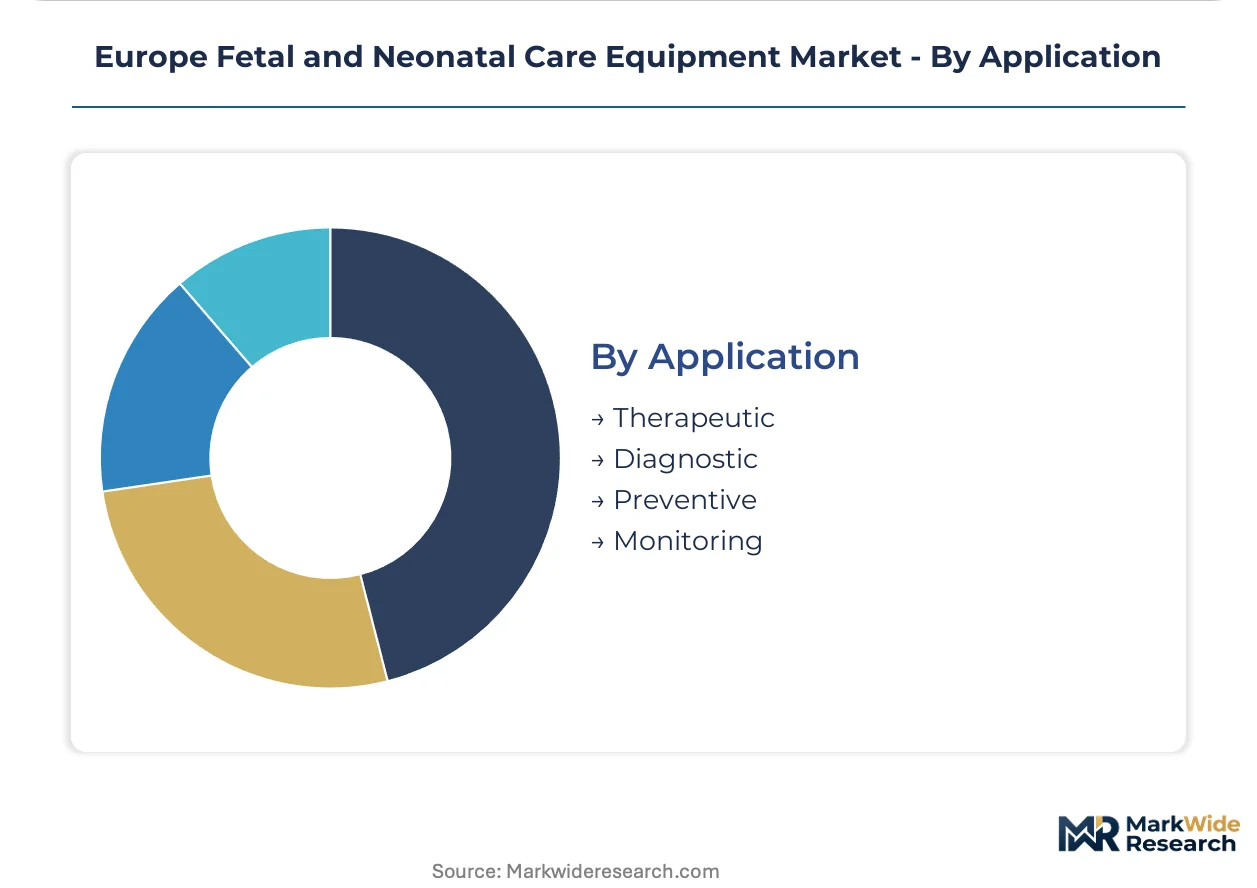
Clinical purpose determines reimbursement pathways and equipment utilization intensity across European health systems.
- Therapeutic:Active intervention systems including ventilators, incubators, and phototherapy arrays command premium pricing tied to outcome metrics. German DRG reimbursement frameworks incentivize equipment density per intensive care bed. MDR clinical evidence requirements weigh heaviest on therapeutic device categories.
- Monitoring:Continuous vital signs surveillance generates recurring data infrastructure revenue beyond hardware margins. French Resah purchasing consortia prioritize remote surveillance integration in tender specifications. Cloud-based analytics subscriptions are displacing traditional capital-only procurement models.
- Diagnostic:Imaging and laboratory adjunct devices support etiological assessment.
- Preventive:Risk stratification tools and early warning systems target morbidity reduction protocols.
Therapeutic applications absorb the majority of capital expenditure. Monitoring is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial clusters in Lübeck and Tuttlingen anchor European manufacturing capacity for precision neonatal thermal regulation systems, while procurement demand disperses across tertiary hospital networks in France, the United Kingdom, and the Netherlands.
Germany
Level III NICU bed expansion in Bavaria and North Rhine-Westphalia drives incubator fleet renewal at university hospitals. The EU Medical Device Regulation imposes 18-24 month certification timelines through German notified bodies like TÜV SÜD. Lübeck-based manufacturing operations supply servo-controlled humidification modules to hospital networks across Central Europe.
France
Resah purchasing consortia aggregate procurement for neonatal monitoring ecosystems across Île-de-France and Auvergne-Rhône-Alpes. ANSM coordinates with EMA on post-market surveillance for respiratory support devices. Parisian tertiary centers pilot wireless telemetry integration with centralized surveillance stations spanning multiple NICU pods.
United Kingdom
NHS Supply Chain tenders separate equipment from multi-year service contracts, compressing vendor margins on traditional full-service agreements. MHRA enforces MDR transition timelines for CE marking renewals. London and Manchester hospital networks prioritize IT-enabled platforms with HL7 FHIR interoperability for electronic health record integration.
Netherlands
Dutch university hospital networks in Amsterdam and Rotterdam lead pilot programs for modular incubator platforms with swappable respiratory modules. GDPR compliance requirements for neonatal physiological data add deployment complexity to wireless monitoring rollouts. Eindhoven-region research institutions concentrate specialized expertise in precision thermal control engineering.
Poland
NICU infrastructure in Warsaw and Krakow remains underpenetrated relative to Western European equipment density benchmarks, creating greenfield installation demand for intermediate care warming devices. Polish notified bodies face capacity constraints extending MDR certification timelines. Regional hospital networks procure through EU structural fund allocations targeting perinatal care infrastructure.
Europe Fetal and Neonatal Care Equipment Market Competitive Landscape
Global majors compete with regional champions across regulatory compliance and service contract bundling, producing a tiered structure where scale-driven conglomerates anchor premium segments and specialized mid-cap fabricators occupy niche thermal regulation applications. Three archetypes dominate: vertically integrated German engineering conglomerates with captive component manufacturing, Dutch-Anglo health technology platforms prioritizing IT interoperability, and Nordic-Asian specialists in respiratory support accessories. Competitive moves concentrate on unbundling service contracts from equipment sales and consolidating notified body application costs through supplier mergers.
Within the integrated engineering tier, Drägerwerk AG & Co. KGaA and Siemens Healthineers AG exemplify archetypes combining precision manufacturing with hospital information system integration, while Koninklijke Philips N.V. occupies a position emphasizing wireless telemetry platforms and cloud-based clinical decision support. These three anchors represent distinct strategic postures: Lübeck-based captive production control, Erlangen-rooted diagnostic imaging interoperability, and Amsterdam-centered IT-enabled monitoring ecosystems.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| F. Hoffmann-La Roche Ltd |
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| GE Healthcare |
| Medtronic PLC |
| Getinge AB |
| Fisher & Paykel Healthcare Ltd |
| Becton, Dickinson and Company |
| Others |
Supply & Pricing Matrix
Specialized biomedical engineering talent concentrated in Lübeck and Eindhoven drives labor-cost differentials that widen pricing-tier spreads between precision thermal regulation systems and standardized phototherapy arrays. REACH compliance expenses for polymer housings and mattress assemblies further stratify cost structures across premium incubator platforms and economy warming devices.
Pricing Analysis
Input-cost pass-through from phthalate-restricted polymer formulations and servo-controlled humidification modules intensifies margin compression in mid-tier equipment categories. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by MDR certification grade and after-sales service bundling. Pricing pressure stems from hospital procurement offices unbundling maintenance contracts from equipment purchases. Neonatal units in France and the United Kingdom exhibit highest price sensitivity, while German tertiary centers prioritize IT interoperability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements mandated by NHS Supply Chain and Resah purchasing consortia are forcing manufacturers to qualify secondary component suppliers for thermal regulation modules and wireless telemetry chipsets. Manufacturing concentrates in Germany, the Netherlands, and Sweden for precision electromechanical assemblies. Supply chains draw from specialized polymer compounders in Belgium and sensor fabricators in Switzerland. Single-source vulnerability persists for CE-marked respiratory support algorithms. Distribution runs through hospital procurement consortia and GPO frameworks rather than direct vendor relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story where procurement committees increasingly specify IT-enabled platforms with HL7 FHIR interoperability as baseline requirements rather than premium upgrades.
For Market Incumbents: Anticipate notified body capacity constraints extending MDR certificate renewal timelines by consolidating development roadmaps around modular incubator architectures. Defensive moves center on captive manufacturing of servo-controlled humidification modules in Lübeck-region facilities and pre-emptive clinical evidence generation for respiratory support algorithms. Threat from mid-tier supplier consolidation elevates competitive pressure on service contract pricing. Vertical integration into polymer formulation reduces REACH compliance exposure. For New Entrants and Emerging Players: Launch via independent service organization partnerships targeting unbundled maintenance contracts in United Kingdom and French hospital networks. White-space targets include wireless telemetry patches for kangaroo mother care protocols in Belgian and Swedish tertiary centers, and intermediate care warming devices for Polish regional hospital networks. Most penetrable segment remains Central and Eastern European greenfield NICU installations funded through EU structural allocations. Go-to-market angle emphasizes GDPR-compliant cloud backend architecture for physiological data streams. For Investors and Strategic Acquirers: Health technology conglomerates with existing hospital information system footprints are the most active acquirer in this space, seeking wireless telemetry capabilities to complement diagnostic imaging portfolios. Long-term viability over a multi-year horizon hinges on recurring revenue from remote surveillance subscriptions displacing capital-only procurement models. Acquisition target archetype: mid-cap specialists with notified body-certified respiratory support devices and established service technician networks. Signal to watch is EMA coordination timelines for post-market surveillance requirement expansion.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Pathway | EMA-coordinated post-market surveillance requirements extend time-to-market for new incubator introductions through German notified bodies. |
| Hospital System Partnership | Integration with NHS Supply Chain and Resah purchasing consortia secures multi-year framework agreements for IT-enabled monitoring platforms. |
| Software Companion Development | Cloud-based clinical decision support algorithms for wireless telemetry generate recurring revenue beyond hardware margins in Dutch university networks. |
| CE Marking Pathway | Harmonized conformity assessment under MDR reduces cross-border trade friction for modular respiratory support modules. |
| Reimbursement Strategy | German DRG frameworks incentivize equipment density per intensive care bed, anchoring premium pricing for therapeutic device categories. |
Research Methodology
Multiple input streams — primary interviews with neonatologists and biomedical engineers, hospital procurement database analysis, and regulatory filing review — were reconciled to construct segment-level demand estimates. Conversations with GPO contracts managers in Germany, France, and the United Kingdom informed tender specification trends and service contract unbundling patterns. Secondary validation drew from EMA post-market surveillance documentation, notified body capacity reports, and NHS Supply Chain award notices. Bottom-up equipment installation counts and top-down health expenditure allocations were triangulated to anchor market sizing.
Historical shipment patterns were cross-referenced against panel input from incubator and monitor manufacturers to calibrate growth trajectories across the projection horizon. Segmentation modeling spanned product type, end-user setting, technology architecture, and application purpose. CAGRs were derived from equipment replacement cycle analysis and NICU bed expansion forecasts. Industry-specific inputs included MDR transition timeline assumptions and EU structural fund allocation trajectories for perinatal infrastructure.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body capacity bottlenecks and REACH polymer restriction expansion. Deviation in EMA post-market surveillance requirement timing would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neonatal Care
Neonatal Critical Care Equipment Market
Neonatal Care
India Neonatal and Prenatal Devices Market
Neonatal Care
Perinatal Software Market
Neonatal Care
UAE Neonatal and Prenatal Devices Market
Neonatal Care
Neonatal Ventilators Market
Neonatal Care
Spain Neonatal and Prenatal Devices Market
Neonatal Care
Preterm Birth Prevention and Management Market
Neonatal Care
India Fetal and Neonatal Care Equipment Market
Neonatal Care
Neonatal Respiratory Distress Syndrome Market
Neonatal Care
Global Neonatal Thermoregulation Market
Neonatal Care
Germany Neonatal and Prenatal Devices Market
Neonatal Care
Global NICU Catheter Market
Neonatal Care
Neonatal Dialysis Market
Neonatal Care
Australia Neonatal and Prenatal Devices Market
Neonatal Care
Umbilical Market
Neonatal Care
United States Neonatal and Prenatal Devices Market