
 North America Feed Probiotics Market | 2026-2036
North America Feed Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
North America Feed Probiotics Market Analytics
Canada's Prairie Provinces are adding probiotic blending capacity to serve cross-border livestock operations, a build-out that is reshaping supply patterns across the northern tier. Cargill Inc. leverages its integrated grain-protein infrastructure to control distribution economics in the central United States. Lallemand Inc. specializes in yeast-based and bacterial strain development, sustaining technical differentiation against commodity competitors. Kerry Group PLC anchors its position through direct sales relationships with major poultry integrators in the southeastern states.
Feed probiotics comprise live microbial cultures—primarily lactic acid bacteria, bacillus species, and saccharomyces yeasts—formulated to colonize the gastrointestinal tract and modulate nutrient absorption, immune response, and pathogen exclusion in production animals. These formulations are manufactured through controlled fermentation, freeze-drying or spray-drying stabilization, and precision blending into feed matrices or drinking water systems. Dry probiotics dominate current volume due to extended shelf stability and compatibility with existing feed mill infrastructure, while liquid probiotics and feed premixes capture faster growth in automated delivery systems. The poultry livestock segment leads absolute consumption, though aquaculture applications are expanding fastest as RAS facilities adopt precision nutrition protocols.
The FDA's Veterinary Feed Directive framework and ongoing antimicrobial stewardship programs shape product registration pathways and label claims for direct-fed microbials. USDA Organic certification requirements and state-level environmental regulations in Iowa, North Carolina, and California further constrain formulation choices and manufacturing site qualifications. The EPA's concentrated animal feeding operation permitting rules indirectly drive probiotic adoption as producers seek waste management compliance through improved gut efficiency. Stakeholders must monitor strain-specific efficacy data requirements and evolving state feed control official interpretations as regulatory science catches up to commercial microbial diversity.
Market Dynamics
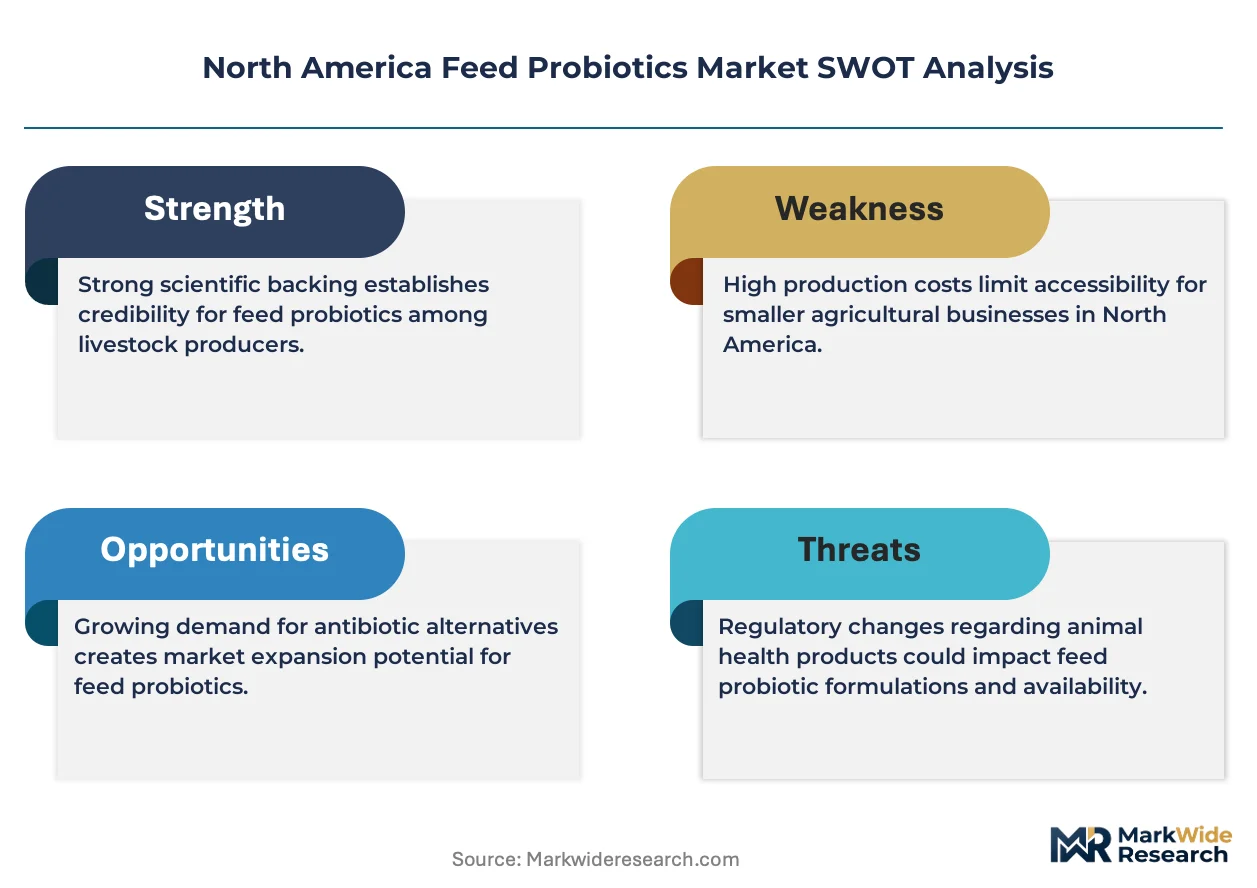
The FDA's phased Veterinary Feed Directive implementation is redirecting livestock producers toward microbial feed additives as antimicrobial growth promoters exit the supply chain, compressing the timeline for probiotic adoption across integrated animal feeding operations.
Growth Catalysts
- Veterinary Feed Directive:The FDA framework mandates veterinary oversight for medically important antimicrobials, forcing producers to source direct-fed microbials as performance alternatives in poultry and swine operations.
- Concentrated Animal Feeding Operations:EPA permitting rules for waste management compliance drive adoption of gut-efficiency solutions that reduce nutrient excretion and environmental liability exposure.
- Freeze-drying stabilization:Advances in cryoprotectant formulations and spray-drying protocols extend shelf stability of bacillus spores and saccharomyces cultures, enabling distribution to remote feed mills.
Market Restraints
- Strain validation costs:Efficacy data requirements for species-specific claims under FDA Center for Veterinary Medicine guidelines inflate registration timelines and R&D expenditure for novel bacterial isolates.
- Corn Belt supply concentration:Procurement volumes cluster in Iowa, Illinois, and Nebraska, creating freight cost penalties for probiotic manufacturers lacking regional blending infrastructure.
- Enzyme substitution:Exogenous carbohydrases and proteases compete for feed additive budget allocation in cost-sensitive broiler operations, particularly during grain price volatility.
Strategic Opportunities
- Recirculating Aquaculture Systems:RAS facilities in the southeastern United States and Atlantic Canada adopt precision nutrition protocols, creating demand for water-stable probiotic delivery formats.
- USDA Organic certification:Approved strain lists for organic livestock production constrain supplier pools, rewarding early movers with qualified bacillus subtilis and lactic acid bacteria libraries.
- Automated drinking water systems:Liquid probiotic dosing equipment penetrates sow farms and layer houses, shifting volume from dry premixes toward soluble concentrate formulations.
Industry Challenges
- Microbiome analytical talent:Commercialization of next-generation sequencing for strain-specific efficacy claims requires bioinformatics capacity scarce among mid-tier feed additive suppliers.
- State feed control official variability:Interpretation of direct-fed microbial label claims differs between Iowa, California, and North Carolina regulators, complicating multi-state distribution strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Feed Probiotics Market |
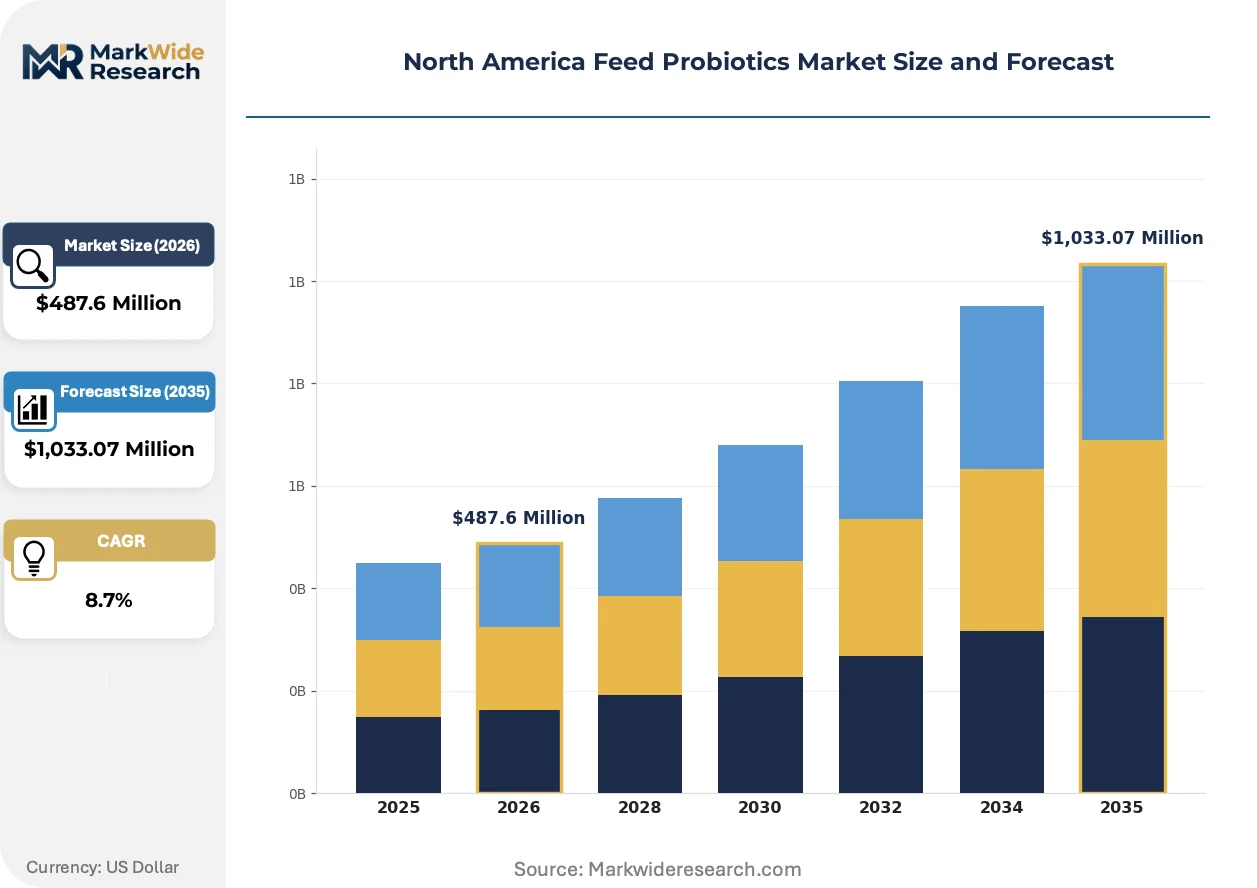
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dry Probiotics, Liquid Probiotics, Feed Premixes, Blends Livestock Type: Poultry, Cattle, Swine, Aquaculture Distribution Channel: Direct Sales, Retail, Online, Distributors Packaging Type: Bags, Bottles, Sachets, Bulk |
| Companies Covered | Adisseo, DSM-Firmenich AG, Evonik Industries AG, IFF (Danisco Animal Nutrition), Kerry Group PLC, Chr. Hansen A/S, Cargill Inc., Kemin Industries, Lallemand Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Feed Probiotics Market Evolving Landscape
Multi-omics strain characterization and precision fermentation capacity are reshaping competitive boundaries between commodity probiotic suppliers and differentiated microbial platform developers.
Next-generation sequencing and metabolomics profiling is collapsing the information asymmetry between strain developers and livestock producers regarding colonization kinetics and immune modulation mechanisms. Large poultry integrators in Georgia and Arkansas now demand transcriptomic validation data as a procurement prerequisite. This transparency compression is eliminating technical differentiation for suppliers relying on legacy plate-count specifications alone.
The FDA's ongoing antimicrobial stewardship programs and state-level environmental regulations in California and North Carolina are tightening the evidentiary threshold for direct-fed microbial label claims. Producers must submit peer-reviewed efficacy studies for species-specific performance assertions, extending registration timelines. Swine operations in the Midwest face the steepest compliance burden as they transition from antibiotic growth promoter baselines.
Buyer concentration among vertically integrated poultry and pork processors is consolidating procurement authority into centralized nutrition teams. These technical buyers negotiate multi-year supply agreements with volume commitments and performance guarantees, displacing spot-market transactions through feed distributors. The southeastern United States exhibits this pattern most acutely, where Tyson Foods and Pilgrim's Pride anchor regional demand.
North America Feed Probiotics Market Segmentation
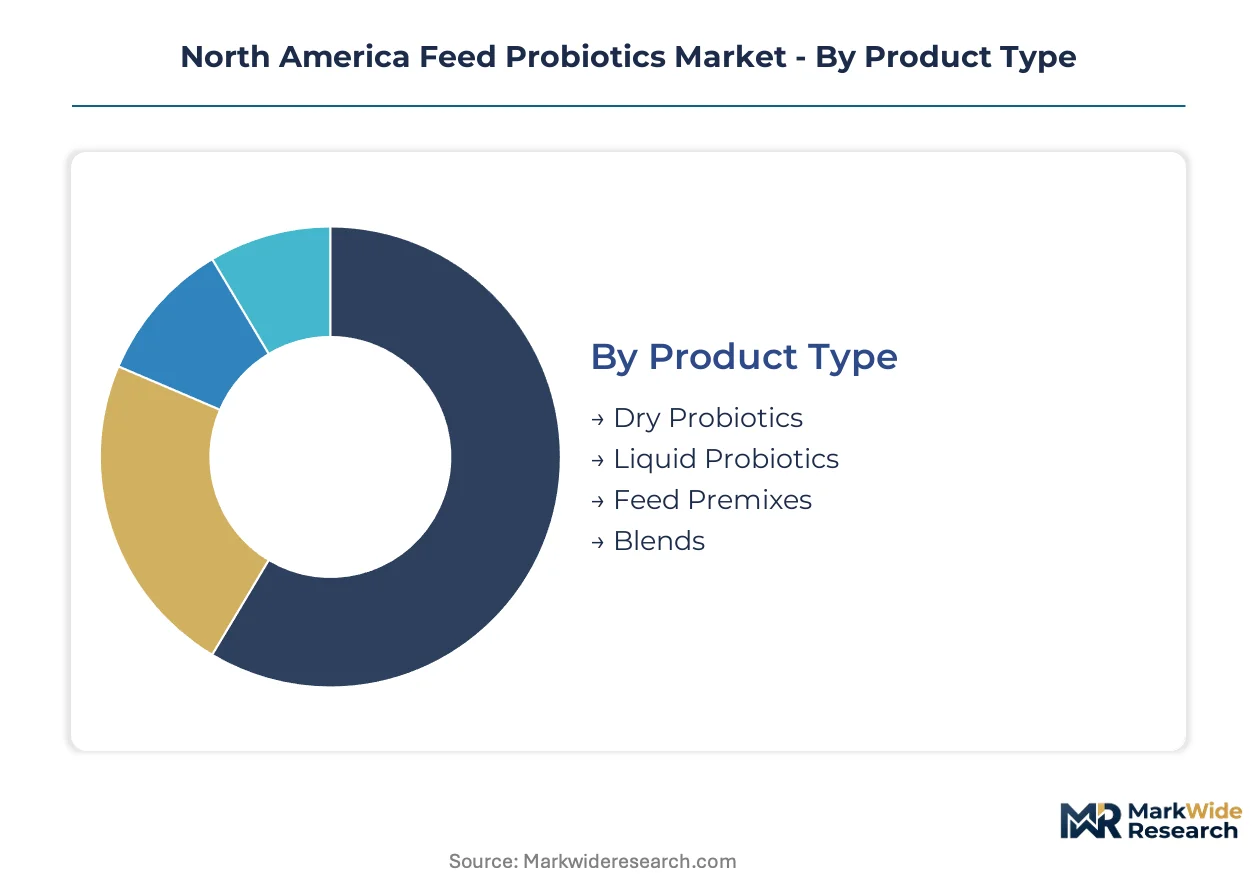
Feed probiotic formulations vary dramatically in shelf stability, delivery mechanics, and customer procurement patterns. Understanding these segment boundaries reveals where technical differentiation commands premium positioning versus where commodity competition dominates.
Product Type:
Freeze-dried and spray-dried formats turn inventory fastest in Corn Belt feed mills, while liquid concentrates tie up working capital longer but penetrate automated systems more deeply.
- Dry Probiotics:Bacillus spores and saccharomyces cultures stabilized through cryoprotectant formulations achieve 18-24 month shelf stability. Iowa and Nebraska feed mills favor these for compatibility with existing pelleting infrastructure and minimal storage complexity.
- Liquid Probiotics:Soluble concentrates require refrigerated distribution chains and shorter rotation cycles. Automated drinking water systems in North Carolina sow farms and Georgia layer houses absorb these despite higher logistics burden.
- Feed Premixes:Precision-blended matrices incorporating vitamins and minerals alongside live cultures serve mid-sized independent producers lacking in-house formulation capacity.
- Blends:Multi-strain combinations with prebiotic substrates target species-specific gut colonization protocols in integrated poultry operations.
Dry probiotics anchor the volume base while liquid formats gain share at the steepest rate as water-dosing equipment penetrates contract grower facilities.
Livestock Type:
Species-specific regulatory pathways and gut physiology create divergent margin profiles across animal categories.
- Poultry:Broiler and layer operations in the southeastern United States consume the largest absolute volumes, with integrators demanding transcriptomic validation data for immune modulation claims.
- Cattle:Dairy operations across Wisconsin and New York prioritize feed conversion efficiency in high-producing Holstein herds, while beef feedlots in Texas and Kansas focus on acidosis mitigation.
- Swine:Post-weaning diarrhea protocols drive nursery-phase supplementation, though FDA registration timelines for species-specific claims compress supplier margins.
- Aquaculture:Recirculating aquaculture systems in Florida and Atlantic Canada adopt water-stable delivery formats, climbing the fastest as RAS facilities scale precision nutrition protocols.
Poultry anchors the volume base while aquaculture gains share at the steepest rate as land-based fish production expands.
Distribution Channel:
Customer scale and technical sophistication determine whether procurement flows through intermediaries or direct manufacturer relationships.
- Direct Sales:Vertically integrated Tyson Foods and Pilgrim's Pride nutrition teams negotiate multi-year supply agreements with performance guarantees, displacing distributor spot markets.
- Distributors:Regional feed additive distributors serve independent pork producers and smaller dairy operations across the Upper Midwest with inventory buffering and technical support.
- Retail:Farm supply cooperatives and veterinary clinics cater to hobby farmers and small-scale livestock owners with packaged consumer formats.
- Online:E-commerce penetration remains limited to specialty strains and organic-certified products for niche producer segments.
Direct sales anchors the volume base while distributor relationships gain share at the steepest rate as mid-tier integrators consolidate procurement.
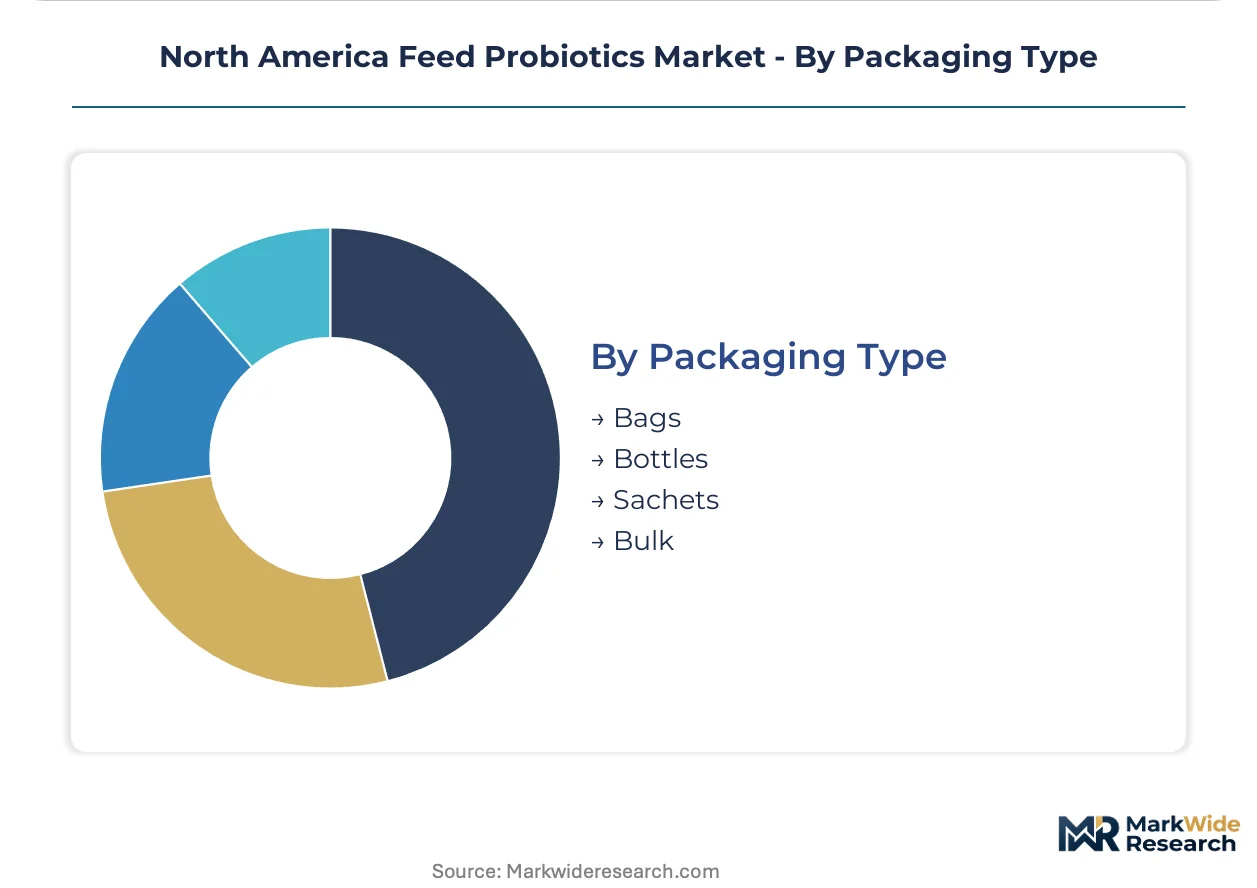
Packaging Type:
Unit economics and contamination risk shape format selection across customer tiers.
- Bulk:Tanker and tote deliveries serve high-volume feed mills with rapid throughput, minimizing per-dose packaging cost.
- Bags:Multi-wall paper and woven polypropylene containers dominate dry probiotic shipment to regional blending facilities.
- Bottles:HDPE and glass containers protect liquid concentrate viability through controlled-atmosphere sealing.
- Sachets:Single-dose foil pouches serve trial quantities and species-specific rotation protocols in research settings.
Bulk packaging anchors the volume base while sachet formats gain share at the steepest rate as precision dosing protocols penetrate research and development operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA antimicrobial stewardship programs anchor the United States as the dominant geography, with Canada and Mexico developing complementary supply corridors to serve cross-border livestock operations.
United States
Dairy operations across Wisconsin and New York drive demand for feed conversion efficiency solutions in high-producing Holstein herds. The FDA's Veterinary Feed Directive mandates veterinary oversight for medically important antimicrobials, compressing adoption timelines for direct-fed microbials. Iowa and Nebraska feed mills concentrate procurement volumes, creating freight cost penalties for manufacturers lacking regional blending infrastructure.
Canada
Prairie Provinces are adding probiotic blending capacity to serve cross-border livestock operations, reshaping supply patterns across the northern tier. Health Canada and the Pest Management Regulatory Agency oversee feed additive registrations, with approved strain lists constraining supplier pools for organic-certified operations. Ontario and Quebec anchor eastern demand through integrated poultry and swine processors.
Mexico
Grain-fed beef operations in northern states import U.S.-formulated probiotics through integrated supply chains serving export markets. The Secretariat of Agriculture and Rural Development (SADER) aligns veterinary feed regulations with FDA frameworks to maintain U.S. market access. Jalisco and Nuevo León concentrate poultry integration, driving centralized procurement of water-soluble delivery formats.
North America Feed Probiotics Market Competitive Landscape
Integrated nutrition conglomerates and specialized microbial developers split the market into distinct capability tiers. The structure consolidates around grain-protein infrastructure control and strain-specific technical differentiation. Three archetypes dominate: diversified agribusinesses with captive distribution, dedicated fermentation specialists with genomic libraries, and hybrid nutrition-technology platforms. Competitive moves center on backward integration into fermentation capacity and multi-year performance guarantee contracts with integrated processors.
Within the specialized fermentation tier, Lallemand Inc. and Chr. Hansen A/S exemplify strain-development capabilities, while Cargill Inc. occupies a position as the diversified agribusiness archetype with grain-protein infrastructure leverage. Kerry Group PLC anchors the hybrid nutrition platform segment through direct sales relationships with major poultry integrators. These three represent the strategic positioning vectors that other competitors must match or circumvent.
| Leading Market Players |
|---|
| Adisseo |
| DSM-Firmenich AG |
| Evonik Industries AG |
| IFF (Danisco Animal Nutrition) |
| Kerry Group PLC |
| Chr. Hansen A/S |
| Cargill Inc. |
| Kemin Industries |
| Lallemand Inc. |
| Others |
Value Network & Pricing Analysis
Fermentation capacity concentration in France and Canada anchors upstream supply, concentrating margin capture with strain developers while downstream feed mills absorb freight penalties for remote delivery. Price differentiation between dry and liquid formats reflects cold-chain logistics burden rather than microbial load alone.
Pricing Analysis
Iowa and Nebraska command price spreads 15-20% below southeastern poultry integrators due to Corn Belt supply concentration and bulk procurement scale. Three-tier pricing structure across premium transcriptomic-validated strains, standard plate-count specifications, and economy bulk bacillus spores dominates contract negotiations. Pricing pressure stems from enzyme substitution in cost-sensitive broiler operations during grain price volatility. Independent pork producers in the Upper Midwest exhibit highest price sensitivity, while vertically integrated Tyson Foods and Pilgrim's Pride nutrition teams prioritize performance guarantees over unit cost.
Supply Chain Analysis
Export-control regimes on precision fermentation technology limit strain development equipment flows to Chinese and Russian biotechnology firms, constraining competitor emergence outside OECD markets. Supply concentrates in the United States, Canada, and France for cryoprotectant formulations, freeze-drying infrastructure, and genomic strain libraries. Raw material dependencies include glucose feedstocks from Corn Belt ethanol byproducts, specialized yeast extracts from European suppliers, and HDPE packaging resins from Gulf Coast petrochemical complexes. Single-source vulnerability runs through Canadian Prairie Province blending capacity serving cross-border operations. Distribution runs through Cargill's grain-protein infrastructure for captive routes, regional feed additive distributors for mid-tier independents, and direct manufacturer relationships for integrated poultry processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as FDA antimicrobial stewardship splinters procurement authority across state feed control officials with divergent label claim interpretations. Niche openings emerge for strain-specific validation services and organic-certified bacillus libraries.
For Market Incumbents: Harden technical differentiation through backward integration into precision fermentation capacity in Wisconsin and New York dairy corridors. Lock in multi-year performance guarantee contracts with southeastern poultry integrators before transcriptomic validation becomes table stakes. Defend against enzyme substitution threats by bundling probiotic-enzyme synergies in bundled premix offerings. For New Entrants and Emerging Players: Build out water-stable liquid concentrate capacity targeting North Carolina sow farms and Georgia layer houses with automated drinking water penetration. White-space sits in USDA Organic-certified strain libraries where approved supplier pools remain constrained. Penetrate through veterinary clinic channel partnerships offering trial sachet formats to independent pork producers lacking in-house nutrition teams. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier fermentation specialists holding genomic libraries but lacking grain-protein infrastructure leverage. Five-to-ten year viability hinges on regulatory science catching up to commercial microbial diversity, rewarding early movers with validated strain portfolios. Watch for FDA Center for Veterinary Medicine guidance harmonization on species-specific efficacy claims as inflection signal for consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Captures margin upstream from Iowa and Nebraska feed mills through captive strain production. |
| Transcriptomic Validation Partnership | Secures procurement prerequisites from Georgia and Arkansas poultry integrators demanding immune modulation data. |
| Organic Certification Investment | Constrains competitor pools for USDA Organic livestock operations in California and North Carolina. |
| Cross-Border Blending Infrastructure | Reshapes supply patterns across the northern tier serving Prairie Provinces and Upper Midwest dairy operations. |
| Automated Water-Dosing Equipment Integration | Shifts volume from dry premixes toward soluble concentrates in North Carolina sow farms. |
Research Methodology
The analysis maps dry probiotics, liquid concentrates, feed premixes, and multi-strain blends, each validated through nutrition directors at integrated poultry processors, procurement leads at Corn Belt feed mills, regulatory affairs specialists navigating FDA Center for Veterinary Medicine pathways, and veterinary practitioners advising independent pork producers. Primary interview data triangulates against FDA Veterinary Feed Directive filings, USDA Organic certification databases, EPA concentrated animal feeding operation permit records, and state feed control official interpretation documents. Bottom-up strain-specific volume estimates reconcile with top-down feed additive expenditure flows across the analysis window.
Assumption sets held regulatory pathway timelines and antimicrobial stewardship program intensity fixed while varying grain price volatility scenarios and RAS facility penetration rates across the projection horizon. Segmentation dimensions modeled include product format stability requirements, livestock species gut physiology, distribution channel customer scale, and packaging type unit economics. CAGRs derive from installed fermentation capacity expansion curves and species-specific adoption S-curves calibrated against historical enzyme substitution patterns.
Sensitivities concentrate around FDA guidance harmonization timelines and state feed control official variability in direct-fed microbial label claim interpretation. Forecasts reflect assumptions regarding continued antimicrobial growth promoter phase-out and sustained organic livestock certification growth. Material shifts in EPA waste management compliance stringency or breakthrough enzyme-probiotic substitution economics would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Biorational Pesticides Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Germany Biostimulants and Biopesticides Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
Bovine High-Mountain Disease Market
Bio-Agriculture
Middle East and Africa Biopesticides Market
Bio-Agriculture
Biosolids Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
Red Algae Market
Bio-Agriculture
North America Biofertilizer Market
Bio-Agriculture
Animal Eubiotics Market