
 France Biopesticides Market | 2026-2036
France Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
France Biopesticides Market Foresight
The EU Green Deal's pesticide reduction targets is recalibrating procurement priorities across French agriculture. BASF SE leverages its microbial platform to anchor biological solutions in the viticulture corridor. Bayer CropScience competes through integrated seed-treatment portfolios that bridge conventional and biological crop protection. Syngenta AG specializes in biocontrol agent formulations tailored to Mediterranean climate stressors.
Biopesticides comprise living organisms, naturally occurring substances, and semiochemicals formulated for pest, disease, and weed management in agricultural systems. These products typically deliver active concentrations measured in colony-forming units per gram for microbial agents or defined botanical extract percentages for biochemical variants, functioning through modes including competition, antibiosis, parasitism, or induced systemic resistance in host plants. Microbial formulations dominate current revenue pools as established Bacillus thuringiensis and Trichoderma products command premium positioning in vine and orchard applications. Biochemical segments occupy faster expansion trajectories where pheromone-based mating disruption and plant extract formulations capture vineyard operator budgets shifting from synthetic insecticides.
ANSM and the EU's EFSA jointly govern product authorization pathways, with France's national phytopharmaceutical regulator enforcing field efficacy standards and residue monitoring protocols that determine market access timelines. The EU Green Deal's pesticide reduction mandate and France's national Ecophyto plan shape demand by binding subsidized crop insurance to integrated pest management compliance. Stakeholders must monitor regulatory divergence between national accelerated approval pathways and centralized EU authorization timelines that could fragment competitive positioning.
Market Dynamics
The EU Green Deal's pesticide reduction mandate is compressing adoption timelines for biological crop protection across French agriculture. Vineyard operators in Bordeaux and Champagne now face binding Ecophyto compliance thresholds that accelerate procurement shifts from synthetic chemistries.
Growth Catalysts
- Ecophyto Plan Mandates:France's national pesticide reduction framework binds subsidized crop insurance to integrated pest management compliance, forcing vineyard and cereal producers to expand biological program budgets.
- Bacillus thuringiensis Formulations:Microbial agents with established field efficacy profiles command premium positioning in vine and orchard applications, displacing synthetic insecticide rotations.
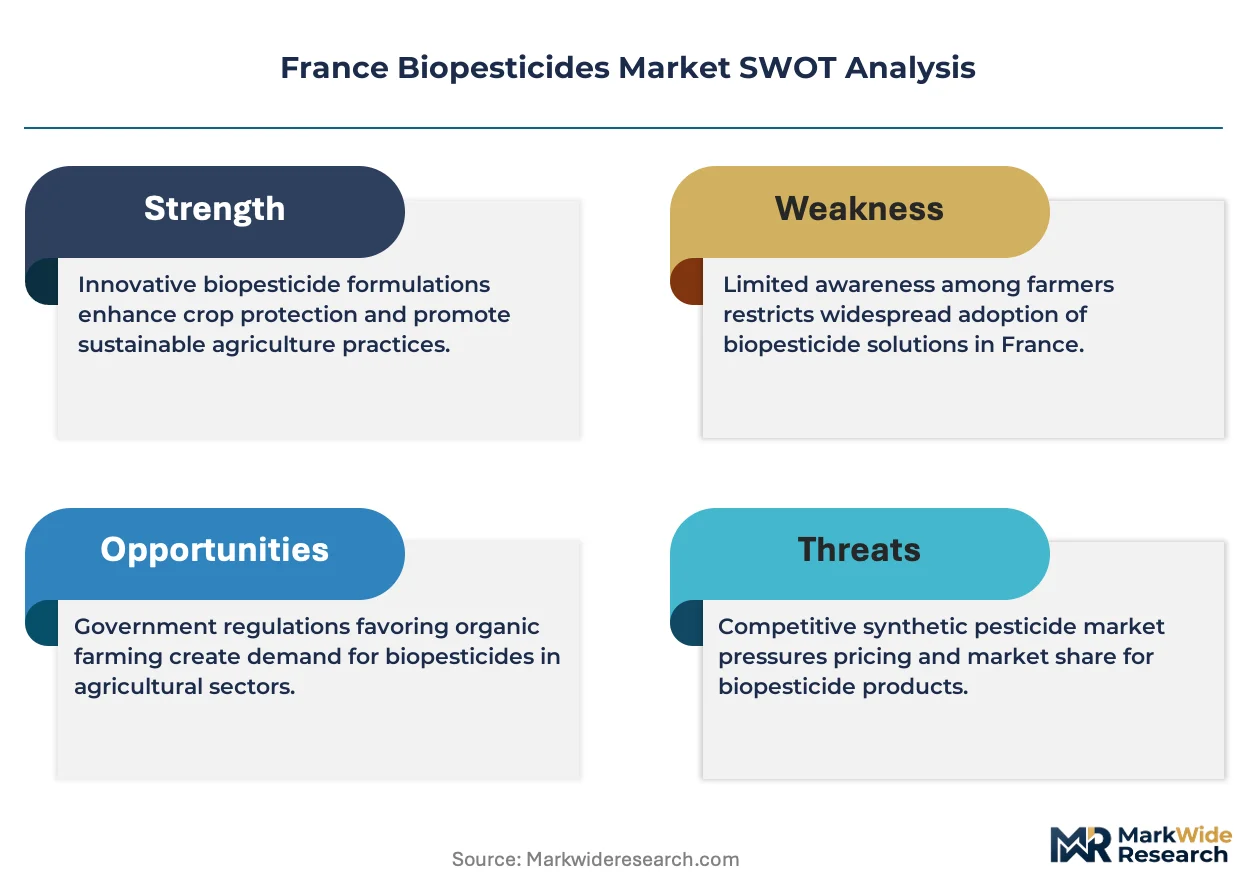
- Champagne Vineyard Cluster:Large-scale cooperatives in this protected designation of origin zone are consolidating biological pest management procurement, creating concentrated demand pools for biocontrol suppliers.
Market Restraints
- Dual Authorization Friction:ANSM and EFSA joint review pathways extend field efficacy validation timelines, compressing effective patent windows for novel microbial strains.
- Input Cost Volatility:Fermentation substrate prices for Trichoderma and Bacillus production fluctuate with agricultural commodity cycles, squeezing formulation margins.
- Synthetic Chemistry Substitution:Conventional neonicotinoid alternatives retain cost advantages in broad-acre cereal applications, limiting biological penetration in price-sensitive grain regions.
Strategic Opportunities
- Occitania Orchard Expansion:Stone fruit and nut producers in this southern region remain underpenetrated by biocontrol distributors, offering first-mover positioning for pheromone-based mating disruption programs.
- Pheromone-Drone Convergence:Aerial application technologies paired with semiochemical formulations enable precision distribution in Bordeaux's fragmented vineyard parcels.
- EU Carbon Farming Incentive:The Common Agricultural Policy's eco-scheme payments reward biological input adoption, creating direct subsidy flows for compliant French growers.
Industry Challenges
- Field Efficacy Certification Bottlenecks:ANSM's residue monitoring protocols and regional trial requirements delay product launches by 18-24 months beyond centralized EU authorization.
- Microbial Strain Stewardship Expertise:Shortages of fermentation technologists and formulation chemists constrain domestic manufacturing scale-up for indigenous biocontrol agents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Biopesticides Market |
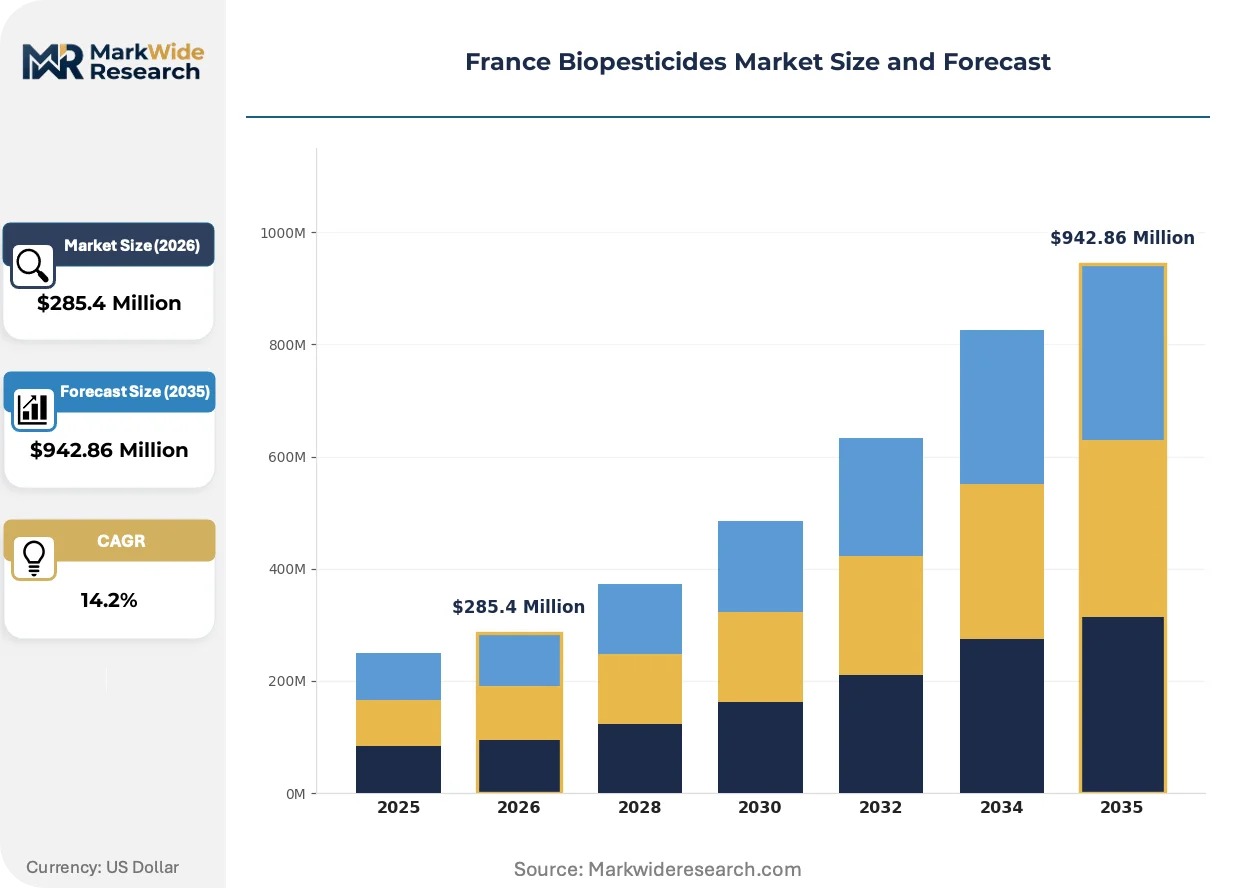
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $942.86 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Biochemical, Botanical, Bio-Control Agents Application: Cereal Crops, Horticulture, Oilseeds, Fiber Crops, Fruits & Vegetables Formulation: Liquid, Granular, Wettable Powder, Emulsifiable Concentrate End User: Crop Producers, Agricultural Cooperatives, Research Institutes, Government Agencies |
| Companies Covered | BASF SE, Bayer CropScience, Corteva Agriscience, Syngenta AG, Novozymes, Koppert Biological Systems, UPL Limited, Marrone Bio Innovations, Lallemand Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Biopesticides Market Shifts & Advancements
Biological formulation science is compressing performance gaps with synthetic chemistries. French agriculture's regulatory trajectory is accelerating investment in precision delivery systems and climate-adapted microbial strains.
RNA interference biopesticides is rewriting competitive positioning in lepidopteran pest control. Vineyard operators in Alsace and Loire Valley are piloting sprayable dsRNA formulations against grapevine moth populations. This technology is compressing the efficacy window between biological and conventional insecticides from seasons to weeks.
France's accelerated biocontrol approval pathway under ANSM's national derogation framework is truncating field trial requirements for low-risk substances. Microbial agents with established safety profiles now access provisional commercial authorization pending full EFSA review. Vineyard operators in Burgundy are leveraging this regulatory channel to deploy novel Trichoderma strains against esca disease complexes.
Cooperative procurement consolidation is displacing distributor-centric supply models in cereal-growing regions. Large grain cooperatives in Centre-Val de Loire and Grand Est are negotiating direct biological input contracts with formulation manufacturers, compressing channel margins and standardizing product specifications across member farms.
France Biopesticides Market Segmentation
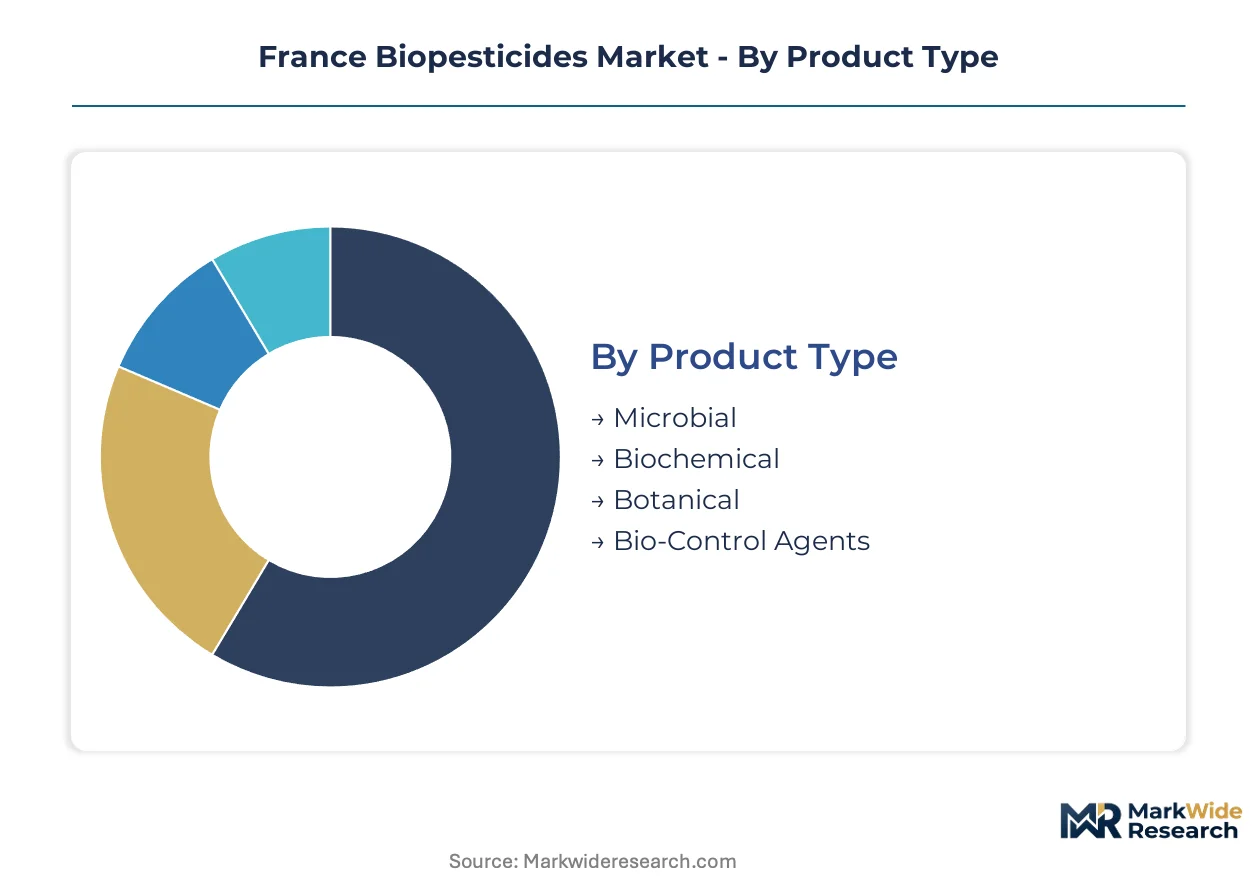
Segmentation in the France Biopesticides Market reveals distinct procurement patterns across product technologies and crop systems. Vineyard operators in Champagne and Bordeaux drive premium microbial demand, while cereal cooperatives in Centre-Val de Loire prioritize cost-efficient biochemical formulations. Understanding these segment boundaries enables suppliers to align R&D investment with regulatory-driven adoption timelines under Ecophyto mandates.
Product Type:
Standardization dominates microbial platforms with established fermentation protocols, while biochemical variants require customization to match regional pest pressure profiles across French growing zones.
- Microbial:Living organisms including Bacillus thuringiensis and Trichoderma strains formulated at defined colony-forming units per gram. Vineyard operators in Bordeaux deploy these against grapevine moth complexes, pressured by ANSM residue thresholds that favor biological over synthetic rotations.
- Biochemical:Naturally occurring substances and semiochemicals including pheromone disruptors and plant-derived extracts. Champagne cooperatives consolidate procurement of mating disruption formulations as Ecophyto compliance binds subsidized crop insurance to integrated pest management adoption.
- Botanical:Plant extract concentrates from neem, pyrethrin, and essential oil sources.
- Bio-Control Agents:Macro-organisms including beneficial nematodes and predatory mites for specialized applications.
Most installed capacity flows through Microbial. Expansion is steepest in Biochemical.
Application:
Volume concentration in cereal regions contrasts with value concentration in protected designation of origin zones, creating divergent margin structures across the category.
- Cereal Crops:Wheat, barley, and maize applications where large-scale cooperatives in Grand Est negotiate direct biological input contracts. Input cost volatility in fermentation substrates squeezes margins, yet EU Carbon Farming eco-scheme payments offset price premiums over conventional chemistries.
- Horticulture:Protected cultivation and open-field vegetable systems across Brittany and Pays de la Loire. Tomato and strawberry producers face accelerated pesticide reduction timelines under departmental Ecophyto implementation plans, driving biocontrol agent procurement.
- Oilseeds:Rapeseed and sunflower pest management programs.
- Fiber Crops:Flax and hemp applications in Normandy textile supply chains.
- Fruits & Vegetables:Apple, pear, and stone fruit orchards in Occitania and Auvergne-Rhône-Alpes.
Procurement volumes concentrate in Cereal Crops. Margin expansion is strongest in Horticulture.
Formulation:
Application method determines field efficacy certification complexity, with liquid platforms facing streamlined ANSM pathways versus granular variants requiring extended soil residue validation.
- Liquid:Suspension concentrates and soluble liquids enabling precision spray application. Drone-pheromone convergence in Bordeaux's fragmented vineyard parcels favors liquid semiochemical distribution, compressing labor costs versus manual placement.
- Granular:Clay-based carriers for soil-incorporated microbial inoculants. Maize producers in Nouvelle-Aquitaine adopt granular Trichoderma formulations for root disease suppression, though dual authorization friction extends field efficacy validation timelines.
- Wettable Powder:Dust-free dispersible granules for high-volume field crops.
- Emulsifiable Concentrate:Oil-in-water systems for lipophilic botanical extracts.
Manufacturing throughput centers on Liquid. Technology investment is heaviest in Granular.
End User:
Customer type shapes contract structure, with cooperatives demanding standardized multi-year supply agreements versus research institutes requiring bespoke strain development partnerships.
- Crop Producers:Individual farm operators managing biological program implementation. Burgundy vineyard owners leverage ANSM's national derogation framework to deploy novel microbial strains against esca disease complexes ahead of full EFSA authorization.
- Agricultural Cooperatives:Member-owned purchasing consortia consolidating biological input demand. Large grain cooperatives in Centre-Val de Loire displace distributor-centric supply models through direct manufacturer negotiations, standardizing specifications across member farms.
- Research Institutes:INRAE and regional agricultural experiment stations conducting field efficacy trials.
- Government Agencies:Departmental agricultural directorates administering Ecophyto compliance monitoring.
Revenue concentration sits with Crop Producers. Procurement reform is most advanced among Agricultural Cooperatives.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France pioneered modern biocontrol science through INRAE's microbial strain collections dating to the 1970s. The national Ecophyto framework now channels this research heritage into commercial field deployment. Regional specialization patterns reflect soil microbiome diversity and crop protection intensity gradients.
Occitanie
Stone fruit orchards and vineyard margins in this Mediterranean zone drive pheromone-based mating disruption procurement. ANSM's accelerated approval pathway for low-risk substances enables faster field deployment of novel semiochemical formulations. Montpellier's agtech cluster anchors formulation R&D partnerships between regional cooperatives and biocontrol distributors.
Nouvelle-Aquitaine
Maize and sunflower producers in this southwestern region adopt granular Trichoderma formulations for root disease suppression under Ecophyto compliance pressure. The EU Carbon Farming eco-scheme subsidizes biological input costs for grain cooperatives. Bordeaux's fragmented vineyard parcels favor drone-pheromone convergence for precision semiochemical distribution.
Grand Est
Large-scale cereal cooperatives in this northeastern region negotiate direct biological input contracts with formulation manufacturers. The national pesticide reduction framework binds subsidized crop insurance to integrated pest management adoption. Strasbourg-based procurement consortia standardize microbial specifications across member wheat and barley farms.
Provence-Alpes-Côte d'Azur
Horticulture and protected cultivation systems in this coastal region face accelerated departmental Ecophyto implementation timelines. ANSM residue monitoring protocols favor biological rotations over synthetic chemistries in export-oriented vegetable supply chains. Nice-Cannes corridor distributors specialize in climate-adapted microbial strains for Mediterranean stress conditions.
France Biopesticides Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation complexity and strain stewardship capabilities. Market structure consolidates around three tiers: integrated agrochemical conglomerates with microbial platforms, specialized biocontrol pure-plays with fermentation expertise, and regional distributors with technical advisory capacity. Dominant competitive moves include backward integration into strain libraries and strategic partnerships with agricultural cooperatives to displace independent distributor networks.
Among integrated agrochemical conglomerates, BASF SE and Bayer CropScience exemplify archetypes that bridge conventional and biological crop protection portfolios. Syngenta AG occupies a position within the climate-specialized formulation tier. These three entities anchor competitive dynamics through their capacity to bundle biological solutions with established distribution relationships across French viticulture and cereal production zones.
| Leading Market Players |
|---|
| BASF SE |
| Bayer CropScience |
| Corteva Agriscience |
| Syngenta AG |
| Novozymes |
| Koppert Biological Systems |
| UPL Limited |
| Marrone Bio Innovations |
| Lallemand Inc |
| Others |
Supply & Pricing Matrix
Fermentation substrate price indices for molasses and soybean meal cascade through French biopesticide manufacturing into three distinct procurement tiers. Large cereal cooperatives in Grand Est negotiate volume-based standard formulations, while Bordeaux vineyard operators absorb premium positioning for climate-adapted Trichoderma strains with ANSM fast-track authorization.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs biopesticide procurement in France. Premium tier differentiation rests on ANSM derogation status and strain stewardship documentation, while standard formulations compete on fermentation yield efficiency. Cost compression in economy-tier Bacillus thuringiensis products is intensifying because grain cooperatives consolidate direct manufacturer contracts. Cereal producers in Centre-Val de Loire exhibit highest price sensitivity, whereas Champagne protected designation of origin zones show lowest elasticity due to Ecophyto compliance binding.
Supply Chain Analysis
Fermentation technologist shortages in France and neighboring Germany constrain domestic manufacturing scale-up for indigenous biocontrol agents. Active ingredient production draws from Belgium, the Netherlands, and Spain for microbial strain libraries, while pheromone synthesis feeds from specialty chemical producers in Switzerland and Italy. Single-source vulnerability concentrates in Trichoderma master seed stocks held by limited European culture collections. Distribution runs through agricultural cooperative procurement consortia displacing independent distributor networks in cereal regions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Biopesticides Market functions as a stable compounder anchored by binding Ecophyto mandates that lock in biological input demand through subsidized crop insurance linkages.
For Market Incumbents: To counter cooperative procurement consolidation displacing distributor margins, BASF SE and Bayer CropScience should deepen backward integration into proprietary strain libraries and secure multi-year supply agreements with Centre-Val de Loire grain cooperatives. ANSM regulatory divergence from EFSA timelines threatens patent windows; investment in accelerated field trial infrastructure preserves first-mover positioning for novel microbial formulations.
For New Entrants and Emerging Players: The price-point gap between premium vineyard formulations and economy cereal products creates entry space for mid-tier biocontrol specialists. Occitania stone fruit orchards remain underpenetrated by pheromone distributors, offering first-mover positioning for mating disruption programs. Drone-pheromone convergence in fragmented Bordeaux parcels enables service-based revenue models beyond product sales.
For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation-capable pure-plays holding ANSM-authorized strain portfolios. The sector's five-to-ten year viability rests on EU Carbon Farming eco-scheme durability. Acquisition targets should demonstrate proven field efficacy in Mediterranean climate stressors. Watch for EFSA-ANSM regulatory harmonization announcements as inflection signals for margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Strain Library Backward Integration | Captive supply of Trichoderma and Bacillus master cultures reduces dependency on European culture collections. |
| Cooperative Direct Contracting | Long-term supply agreements with Grand Est grain consortia displace distributor margins and standardize specifications. |
| ANSM Fast-Track Investment | Provisional authorization infrastructure compresses field-to-market timelines for low-risk microbial agents. |
| Drone-Pheromone Convergence | Aerial semiochemical distribution in Bordeaux's fragmented parcels reduces labor costs versus manual placement. |
| Mediterranean Climate Formulation | Climate-adapted microbial strains for Occitania and Provence-Alpes-Côte d'Azur stress conditions command premium positioning. |
Research Methodology
Multiple input streams — regulatory filing analysis, cooperative procurement database review, and fermentation facility technical assessments — were reconciled to construct market estimates. Primary interviews with ANSM regulatory affairs officers, INRAE research directors, vineyard technical managers in Champagne, and cereal cooperative procurement heads informed demand-side validation. Secondary sources included ANSM authorization registries, EFSA peer-reviewed safety assessments, EU Farm to Fork Strategy implementation reports, and French Ministry of Agriculture Ecophyto monitoring data. Bottom-up strain-level production estimates and top-down agricultural input spending analysis were cross-referenced for triangulation.
Historical authorization timelines were cross-referenced against panel input from regulatory consultants and biocontrol distributors to model adoption curves across the projection horizon. Segmentation dimensions encompassed product technology, crop system intensity, formulation complexity, and end-user procurement structure. CAGRs were derived from regulatory mandate enforcement schedules and cooperative consolidation patterns. Forecast inputs included Ecophyto compliance threshold trajectories and EU Carbon Farming eco-scheme payment durability assumptions.
Caveats apply where ANSM-EFSA regulatory divergence, fermentation substrate commodity cycles, or synthetic chemistry price wars could materially shift the outlook. Forecasts embed assumptions regarding Ecophyto mandate continuity and cooperative procurement consolidation velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Europe Biostimulants Market
Bio-Agriculture
Horticulture Bioplastic Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Nannochloropsis Market
Bio-Agriculture
Biofibre Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
United States Biocontrol Agents Market
Bio-Agriculture
North America Bio Succinic Acid Market
Bio-Agriculture
Europe Biocontrol Agents Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Poultry Manure Biofertilizers Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
Bioethanol Yeast Market