
 Hydroponics Nutrients Market | 2026-2036
Hydroponics Nutrients Market Size, Share, and Industry Trends Forecast 2026-2036
Hydroponics Nutrients Market Foresight
Subscription-based nutrient monitoring and automated dosing software is recalibrating how commercial growers procure and manage fertility programs. Scotts Miracle-Gro leverages its retail distribution network to reach hobbyist and semi-professional segments. Haifa Group anchors its position through precision-grade potassium nitrate and calcium formulations for high-value greenhouse crops. ICL Group specializes in fully soluble, chloride-free nutrient portfolios tailored to recirculating hydroponic architectures.
Hydroponics nutrients are chemically complete, water-soluble fertilizer formulations engineered for soilless cultivation systems, typically specified by electrical conductivity tolerance, pH stability range, and elemental purity grades measured in parts per million. Their primary commercial purpose is to replace soil-derived mineral availability with precisely metered ionic nutrition delivered directly to root zones via aqueous solution. Liquid nutrients dominate volume in large-scale operations due to ease of automated injection and reduced handling labor, while customized formulations capture margin pools among research institutions and premium greenhouse enterprises optimizing for cultivar-specific phenotypic targets. Powder nutrients retain share in remote or import-dependent regions where freight cost sensitivity favors concentrated shipping weights.
The EPA oversees discharge and runoff standards that constrain nutrient effluent from commercial hydroponic facilities in the United States, while REACH governs the registration and hazard classification of synthetic chelating agents and micronutrient compounds across European supply chains. The EU Fertilizing Products Regulation further shapes market access by mandating biodegradability thresholds for organic additive components and recovered nutrient sources. Stakeholders must monitor evolving contaminant limits and circular-economy certification requirements to sustain product registrations and avoid reformulation costs.
Market Dynamics
Closed-loop recirculating architectures are forcing wholesale reformulation of nutrient chemistry as commercial greenhouse operators confront mounting effluent compliance costs and water scarcity premiums.
Growth Catalysts
- EU Fertilizing Products Regulation:Stricter biodegradability thresholds for organic additives are accelerating R&D investment in recovered nutrient streams across Dutch and Spanish supply chains.
- Controlled-environment agriculture clusters:Concentrated greenhouse development in Almeria, Spain and Leamington, Canada is creating dedicated demand corridors for precision-grade potassium nitrate formulations.
- Automated dosing platforms:IoT-enabled nutrient monitoring systems are embedding software subscriptions into long-term fertility procurement contracts.
Market Restraints
- Potassium nitrate supply concentration:Israeli and Jordanian producers control critical feedstock for premium greenhouse formulations, exposing buyers to geopolitical transit risk.
- REACH registration costs:Synthetic chelating agents face escalating hazard classification scrutiny, forcing smaller blenders toward costly reformulation or exit.
- Freight cost sensitivity:Powder nutrient producers in remote markets absorb disproportionate shipping weight penalties versus liquid concentrate competitors.
Strategic Opportunities
- Western Australian desert greenhouse expansion:Solar-powered controlled-environment projects near Port Hedland present untapped demand for chloride-free soluble portfolios.
- Research institution customization:Cultivar-specific phenotypic targeting contracts command margin premiums unavailable in commodity greenhouse supply.
- Subscription telemetry bundling:Nutrient-as-a-service models integrating hardware, software, and chemistry lock in multi-year revenue streams.
Industry Challenges
- Formulation chemistry expertise gap:Recirculating system operators lack in-house capability to diagnose ionic imbalances before crop damage manifests.
- Dual certification timelines:Products seeking both organic additive approval and conventional fertilizer registration face sequential regulatory queue delays.
- Legacy irrigation infrastructure retrofit:Existing drip and NFT systems require capital-intensive modification to handle precision dosing hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydroponics Nutrients Market |
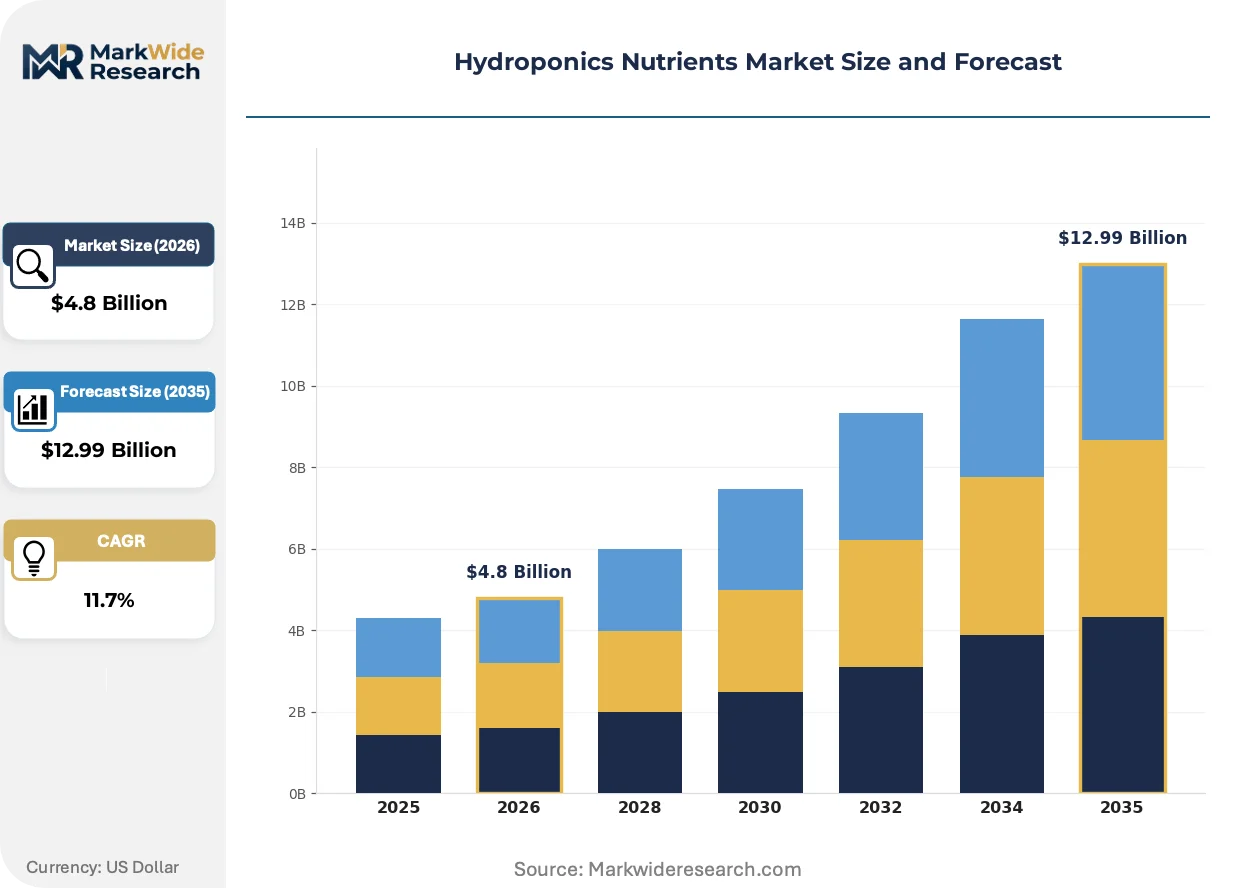
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Nutrients, Powder Nutrients, Off-the-Shelf Solutions, Customized Formulations Application: Vegetable Cultivation, Fruit Production, Herb Farming, Ornamental Plants Composition: Macronutrients, Micronutrients, Organic Additives, Synthetic Nutrients Distribution Channel: Retail Stores, Online Platforms, Agricultural Cooperatives, Hydroponic Supply Shops |
| Companies Covered | Scotts Miracle-Gro, Haifa Group, ICL Group, Nouryon, Sociedad Química y Minera (SQM), Advanced Nutrients, CANNA International, Emerald Harvest, FoxFarm Soil & Fertilizer Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydroponics Nutrients Market Shifts & Advancements
Precision agriculture instrumentation is collapsing the distinction between nutrient supply and real-time crop diagnostics, embedding chemical vendors into continuous production workflows rather than transactional input sales.
Biostimulant-enhanced nutrient formulations are expanding into high-value greenhouse tomato and cucumber operations across the Netherlands and Belgium. Large-scale operators in Westland and Flanders are piloting microbial inoculant integrations at scale. This convergence is expanding into premium pricing tiers previously reserved for pure synthetic chemistry.
REACH Article 57 substance-of-very-high-concern listings are forcing systematic replacement of EDTA chelates with biodegradable alternatives across European supply chains. German and Dutch blenders face accelerated compliance deadlines for micronutrient product lines. Greenhouse operators in the Netherlands are pre-qualifying suppliers based on circular-economy certification status ahead of formal mandate enforcement.
Research institutions and premium greenhouse enterprises are consolidating procurement around cultivar-specific phenotypic targeting contracts. Long-term supply agreements now specify elemental purity grades and electrical conductivity tolerances matched to genetic optimization goals. This specification intensity is most visible in Dutch tomato seed development corridors and Canadian cannabis breeding facilities.
Hydroponics Nutrients Market Segmentation
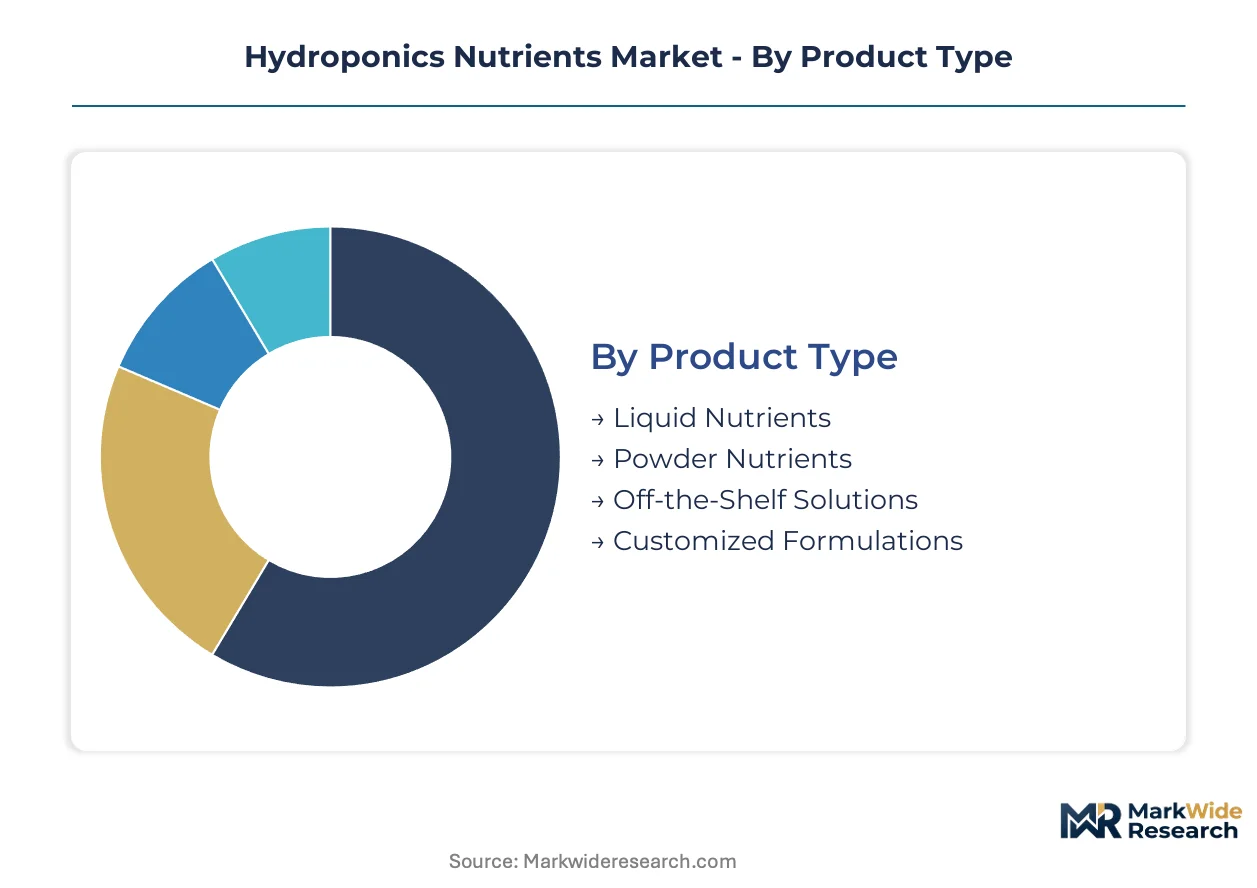
Nutrient formulation chemistry and procurement channel dynamics create distinct margin pools across the hydroponics value chain. Commercial greenhouse operators prioritize solubility specifications and recirculating-system compatibility, while hobbyist segments drive volume through retail accessibility.
Product Type:
Buyers differentiate primarily by operational scale and automation infrastructure, with freight economics and handling labor shaping procurement decisions.
- Liquid Nutrients:Pre-dissolved aqueous formulations with standardized electrical conductivity and pH buffering. Dutch commercial greenhouse operators in Westland and Belgian large-scale tomato facilities specify liquid concentrates for seamless integration with automated injection systems.
- Powder Nutrients:Concentrated dry blends requiring on-site dissolution. Australian remote greenhouse projects near Port Hedland and import-dependent Spanish Almeria operations absorb powder formats to mitigate ocean freight weight penalties.
- Off-the-Shelf Solutions:Standardized NPK ratios packaged for hobbyist and semi-professional growers. Scotts Miracle-Gro retail distribution networks move significant volume through North American home improvement channels.
- Customized Formulations:Cultivar-specific elemental recipes matched to phenotypic targets. Canadian cannabis breeding facilities and Dutch tomato seed development corridors contract precision-grade purity specifications.
Volume sits with Liquid Nutrients; growth tilts toward Customized Formulations.
Application:
End-use crop value per square meter determines specification intensity and supplier qualification requirements.
- Vegetable Cultivation:High-turnover greenhouse tomato and cucumber operations in the Netherlands and Belgium demand chloride-free potassium nitrate formulations with micronutrient chelate stability across recirculating loops.
- Fruit Production:Strawberry and melon operations concentrate in Spanish Almeria and Canadian Leamington clusters, requiring calcium-heavy formulations to prevent blossom-end rot in controlled environments.
- Herb Farming:Basil and leafy green operations prioritize rapid vegetative growth cycles with nitrogen-dominant feeding schedules.
- Ornamental Plants:Lower specification intensity permits commodity-grade nutrient sourcing through agricultural cooperatives.
Revenue concentrates in Vegetable Cultivation; margin expansion is steepest in Fruit Production.
Composition:
Regulatory pressure on synthetic additives and circular-economy certification mandates are restructuring formulation R&D priorities.
- Macronutrients:Nitrogen, phosphorus, and potassium compounds delivered as nitrate, phosphate, and sulfate salts. Israeli and Jordanian producers anchor potassium nitrate supply for premium greenhouse segments.
- Micronutrients:Iron, manganese, zinc, and boron delivered via chelated complexes. REACH Article 57 substance-of-very-high-concern listings force German and Dutch blenders toward biodegradable EDTA replacements.
- Organic Additives:Biostimulant and microbial inoculant integrations. EU Fertilizing Products Regulation biodegradability thresholds accelerate recovered nutrient stream development.
- Synthetic Nutrients:Laboratory-grade mineral salts with parts-per-million purity certification. Research institutions specify these for cultivar genetic optimization protocols.
Macronutrients dominate tonnage; Organic Additives are climbing the fastest.
Distribution Channel:
Customer technical sophistication and purchase frequency determine channel economics and service bundling potential.
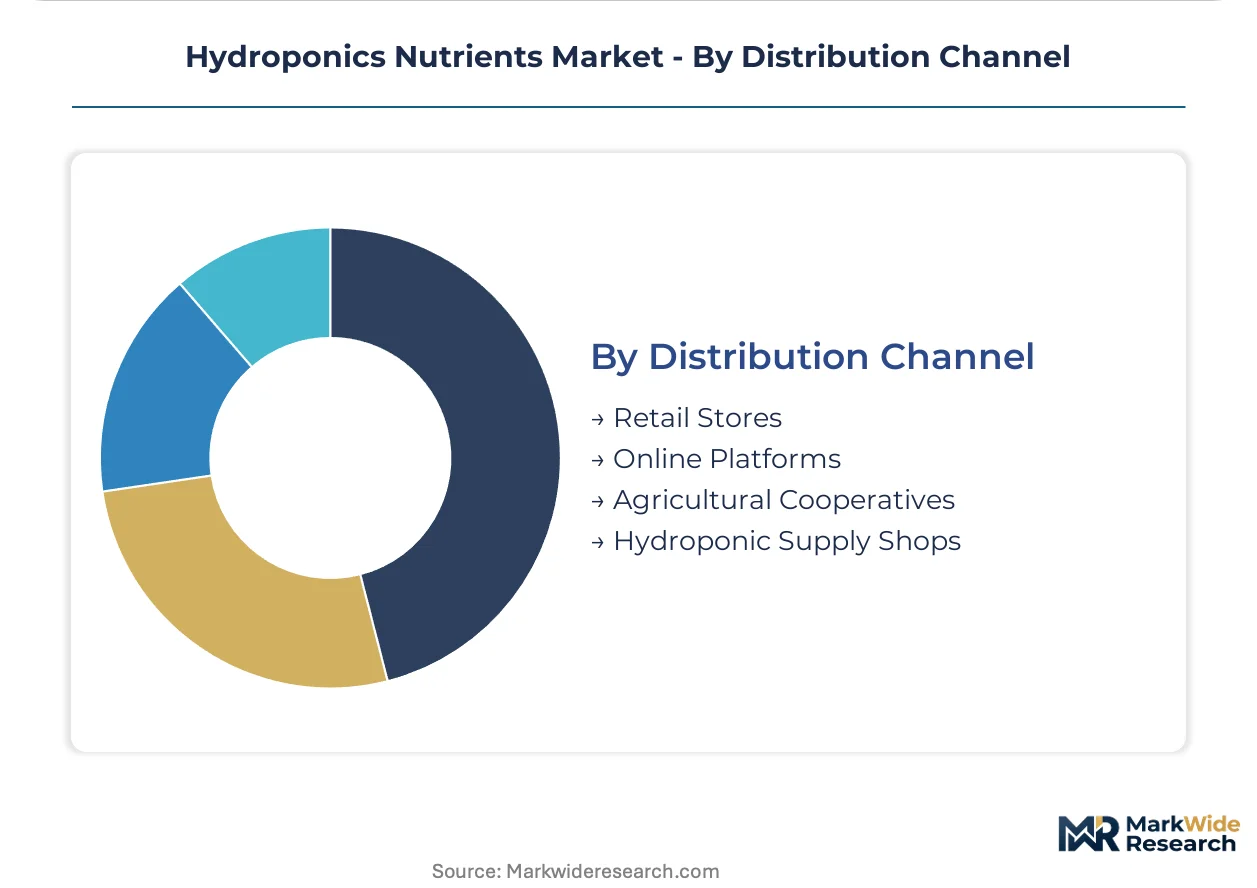
- Retail Stores:Mass-market nutrient lines packaged for home hobbyist segments. Scotts Miracle-Gro leverages North American home center networks for seasonal volume surges.
- Online Platforms:Direct-to-grower sales enabling subscription telemetry bundling and automated reordering algorithms.
- Agricultural Cooperatives:Bulk purchasing consortia serving mid-scale greenhouse operators in clustered growing regions.
- Hydroponic Supply Shops:Technical specialist retailers offering formulation consulting and system compatibility verification.
Transaction volume flows through Retail Stores; customer lifetime value peaks with Online Platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of potassium nitrate feedstock concentrates in Israel and Jordan, while consumption clusters in Dutch greenhouse corridors and Canadian controlled-environment facilities. This geographic disconnect creates transit-dependent supply chains vulnerable to Red Sea routing disruptions. Regulatory divergence between REACH-governed European blenders and EPA-monitored North American operators compounds formulation complexity.
Netherlands
Westland greenhouse operators deploy closed-loop recirculating systems at scale, driving demand for chloride-free soluble formulations. The EU Fertilizing Products Regulation mandates biodegradability thresholds for organic additives by 2026. Dutch blenders in the Randstad cluster are pre-qualifying suppliers on circular-economy certification status ahead of formal enforcement.
Canada
Leamington, Ontario anchors North American greenhouse vegetable production with concentrated tomato and cucumber operations. Health Canada's PMRA oversees chelating agent registrations, creating parallel compliance tracks to EPA requirements. Cannabis breeding facilities in British Columbia are contracting cultivar-specific phenotypic targeting agreements with precision-grade purity specifications.
Spain
Almeria's solar-powered greenhouse belt generates concentrated demand for calcium-heavy formulations targeting blossom-end rot prevention in melons and strawberries. The EU Fertilizing Products Regulation tightens contaminant limits for recovered nutrient inputs, accelerating R&D investment in alternative feedstock streams. Mid-scale operators rely on agricultural cooperative bulk purchasing to offset freight cost sensitivity.
Australia
Western Australian desert greenhouse projects near Port Hedland exploit solar irradiance advantages for controlled-environment expansion. The country's national agricultural regulator maintains import inspection protocols for micronutrient compounds that delay product registration timelines. Powder nutrient formats dominate procurement decisions due to ocean freight weight penalties on liquid concentrates.
United States
Commercial hydroponic facilities in California and Arizona confront EPA discharge standards constraining nutrient effluent from large-scale operations. The Inflation Reduction Act channels investment tax credits toward solar-integrated controlled-environment agriculture. Scotts Miracle-Gro leverages retail distribution networks through home improvement channels to capture hobbyist segment volume.
Hydroponics Nutrients Market Competitive Landscape
Capital-heavy producers compete with asset-light formulators across the hydroponics nutrients landscape. Israeli and Jordanian feedstock suppliers anchor upstream potassium nitrate supply, while European and North American blenders differentiate through formulation chemistry and regulatory compliance services. Three strategic archetypes dominate: integrated mining-to-blending conglomerates, specialty chemical precision formulators, and retail-channel consumer brands. Competitive intensity centers on M&A-driven portfolio diversification and geographic expansion into controlled-environment agriculture clusters.
Among integrated chemical conglomerates, ICL Group and Nouryon exemplify the upstream-controlled archetype, leveraging captive mineral processing capabilities. Haifa Group represents the precision-formulation specialist tier, with geographic signaling in its name anchoring Israeli potassium nitrate expertise. Scotts Miracle-Gro occupies the consumer-access position, with its corporate structure indicating retail-channel dominance. These three patterns illustrate how supply chain control, technical specification intensity, and distribution reach define competitive positioning.
| Leading Market Players |
|---|
| Scotts Miracle-Gro |
| Haifa Group |
| ICL Group |
| Nouryon |
| Sociedad Química y Minera (SQM) |
| Advanced Nutrients |
| CANNA International |
| Emerald Harvest |
| FoxFarm Soil & Fertilizer Company |
| Others |
Supply & Pricing Matrix
Sovereign-backed Israeli and Jordanian producers anchor potassium nitrate feedstock ownership, enabling disciplined pricing power across premium greenhouse formulations while forcing downstream blenders to absorb transit risk premiums or seek alternative sourcing.
Pricing Analysis
Margin tightening in standard-grade liquid concentrates reflects freight cost sensitivity among Australian and Spanish import-dependent operators. Three-tier pricing structure across premium, standard, and economy levels separates cultivar-specific customized formulations from commodity greenhouse supply and retail hobbyist lines. Price differentiation hinges on elemental purity certification and recirculating-system compatibility grades. Hobbyist segments through North American retail channels exhibit highest price sensitivity, while Dutch commercial greenhouse operators prioritize specification compliance over unit cost.
Supply Chain Analysis
EU Fertilizing Products Regulation certification gates and REACH biodegradability mandates constrain supplier qualification timelines across European blenders. Feedstock concentrates in Israel and Jordan, blending capacity in the Netherlands and Germany, and consumption clusters in Canada and Australia create geographic dispersion. Raw material dependencies span potassium nitrate salts, synthetic and biodegradable chelating agents, and recovered nutrient streams. Single-source vulnerability around Israeli-Jordanian potassium nitrate exposes buyers to Red Sea routing disruptions. Distribution runs through agricultural cooperatives in clustered growing regions, direct-to-grower online platforms, and technical specialist retailers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive potassium nitrate supply to secure formulation margins and insulate against geopolitical transit risk.
For Market Incumbents: To counter REACH-driven reformulation costs and EDTA chelate replacement deadlines, ICL Group and Haifa Group should deepen backward integration into mineral processing while acquiring biodegradable chelation technology. Certification investment in EU Fertilizing Products Regulation compliance ahead of 2026 enforcement locks in supplier qualification status. For New Entrants and Emerging Players: Begin with Western Australian desert greenhouse corridors near Port Hedland, where solar-powered controlled-environment expansion outruns established supplier coverage. White-space exists in subscription telemetry bundling for mid-scale operators lacking in-house ionic diagnostics capability. A nutrient-as-a-service model integrating hardware, software, and chemistry commands multi-year contract lock-in. For Investors and Strategic Acquirers: Distressed-cycle entries favor precision-formulation specialists with cultivar-specific contract portfolios in Canadian cannabis breeding and Dutch tomato seed development corridors. Long-term viability rests on R&D intensity and regulatory compliance service bundling rather than commodity volume. Watch for circular-economy certification pre-qualification momentum among Dutch greenhouse operators as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Potassium Nitrate Feedstock | Captive mineral supply from Israeli and Jordanian producers insulates against Red Sea transit disruption. |
| Biodegradable Chelating Agent R&D Investment | German and Dutch blenders accelerate EDTA replacement to meet REACH Article 57 compliance deadlines. |
| Subscription Telemetry Bundling Launch | IoT-enabled nutrient monitoring locks in multi-year revenue streams with commercial greenhouse operators. |
| Circular-Economy Certification Pre-Qualification | Dutch Westland operators select suppliers based on recovered nutrient stream credentials ahead of EU mandate enforcement. |
| Western Australian Distribution Partnership | Port Hedland solar greenhouse projects create dedicated demand corridor for chloride-free soluble portfolios. |
Research Methodology
Independent corroboration across primary interviews with commercial greenhouse operators, nutrient formulation chemists, and agricultural cooperative procurement leads, combined with secondary validation through EU Fertilizing Products Regulation filings, REACH registration databases, and customs trade data, underwrites the qualitative findings. Bottom-up demand modeling across product type, application, and composition segments triangulates against top-down market sizing.
Comparable-period anchoring to historical cultivation area expansion and controlled-environment agriculture investment cycles structures the projection framework. Segmentation dimensions span liquid versus powder format, vegetable cultivation versus fruit production versus herb farming, and macronutrient versus micronutrient versus organic additive composition. CAGRs derive from installed greenhouse capacity growth, automation penetration rates, and regulatory compliance cost absorption across the modeling period.
Geopolitical transit disruption, accelerated REACH substance-of-very-high-concern listings, and EU Fertilizing Products Regulation enforcement timeline shifts are the dominant revision risks. Forecasts reflect assumptions around potassium nitrate supply continuity and biodegradability technology maturation. A model refresh is warranted upon material change in Red Sea shipping security or circular-economy certification mandate acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
India Biomass Market
Bio-Agriculture
Biofuel Enzymes Market
Bio-Agriculture
Latin America Biopesticide Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
Biorational Pesticides Market
Bio-Agriculture
Ulva Lactuca Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
Europe Feed Phytogenics Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
Australia Biopesticides Market
Bio-Agriculture
Europe Biological Organic Fertilizer Market
Bio-Agriculture
West Africa Biostimulants Market
Bio-Agriculture
German Biopesticides Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
Bacterial Biopesticides Market