
 Biosolids Market | 2026-2036
Biosolids Market Size, Share, and Industry Trends Forecast 2026-2036
Biosolids Market Intelligence
Premium Class A pathogen-free biosolids is decoupling from commodity Class B land-application material on both price and regulatory treatment. REMONDIS SE & Co. KG leverages integrated wastewater-to-fertilizer infrastructure across German industrial clusters. Veolia sustains technology leadership in advanced thermal drying systems for pathogen reduction. Synagro Technologies anchors North American agricultural channel access through direct contracts with crop producers.
Biosolids denote treated sewage sludge meeting EPA 503 or equivalent pathogen and vector-attraction reduction standards, typically containing 2-5% nitrogen and trace minerals, produced through anaerobic digestion, lime stabilization, or thermal drying for land application or energy recovery. Dried biosolids command margin premiums in bagged fertilizer markets where transportation economics favor low-moisture product. Composted biosolids occupy expanding share in organic-certified agriculture where USDA National Organic Program compliance creates entry barriers. Liquid biosolids compete on proximity to municipal treatment plants, with haul distance limiting viable market radius to roughly 50 miles for cost-effective land spreading.
EPA 503 rule enforcement in the United States and EU F-Gas Regulation alignment with sludge-to-energy pathways shape product classification, market access, and end-user liability exposure. Germany's KBA and federal waste framework impose trace contaminant thresholds that filter out smaller treatment operators. Stakeholders must monitor evolving per- and polyfluoroalkyl substance testing protocols, as emerging analytical limits threaten to reclassify formerly compliant biosolids and redirect volumes toward landfill or incineration alternatives.
Market Dynamics
Landfill diversion mandates under the EU Green Deal and EPA 503 rule enforcement are redirecting municipal sludge volumes toward beneficial reuse pathways, compressing disposal alternatives and elevating processed biosolids to primary fertilizer substitutes.
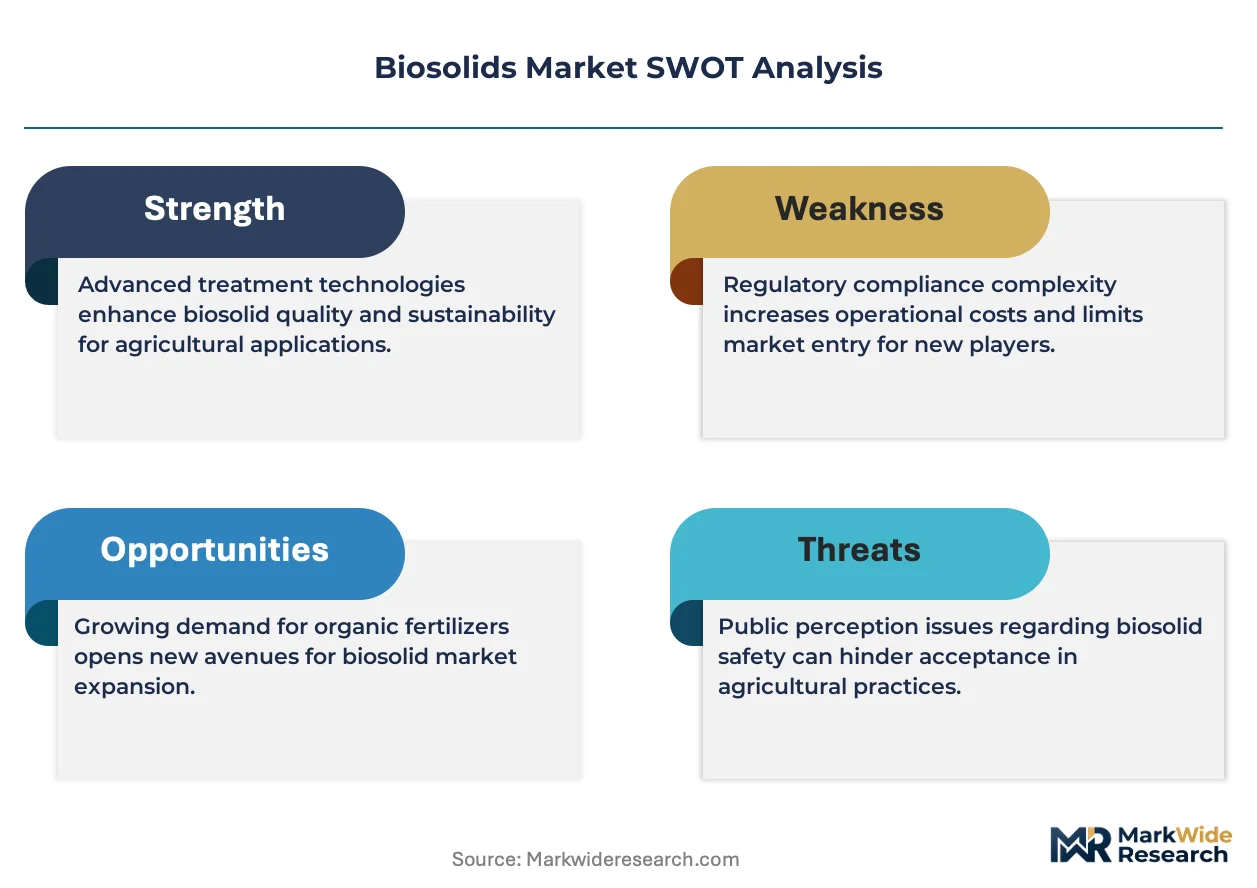
Growth Catalysts
- EU F-Gas Regulation alignment:Sludge-to-energy pathways gain preferential treatment under carbon accounting frameworks, accelerating thermal drying infrastructure deployment across Rhine-Ruhr industrial corridors.
- Agricultural input substitution:Synthetic fertilizer price volatility drives German and Dutch crop producers toward Class A pathogen-free biosolids for nitrogen supplementation.
- Anaerobic digestion technology maturation:Advanced mesophilic and thermophilic systems reduce vector attraction compliance costs for municipal treatment operators.
Market Restraints
- Per- and polyfluoroalkyl substance contamination:Emerging analytical detection limits threaten to reclassify formerly compliant biosolids volumes toward incineration or landfill alternatives.
- Transportation cost density:Liquid biosolids face economically viable haul radii of roughly 50 miles, constraining market access for inland treatment plants without thermal drying capacity.
- Trace contaminant thresholds:Germany's KBA and federal waste framework filter out smaller treatment operators unable to meet heavy metal and organic pollutant limits.
Strategic Opportunities
- Organic-certified agriculture channel:USDA National Organic Program compliance creates entry barriers that favor established composted biosolids producers with certification infrastructure.
- Bagged retail fertilizer positioning:Low-moisture dried biosolids command margin premiums where transportation economics favor shelf-stable product formats.
- Netherlands circular economy procurement:Government-mandated bio-based input quotas for public land management contracts create guaranteed offtake volumes.
Industry Challenges
- PFAS testing protocol evolution:Laboratories face capacity constraints as municipalities rush to characterize sludge inventories against anticipated federal screening limits.
- Thermal drying capex intensity:Advanced pathogen reduction infrastructure requires substantial upfront investment, squeezing mid-sized treatment operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biosolids Market |
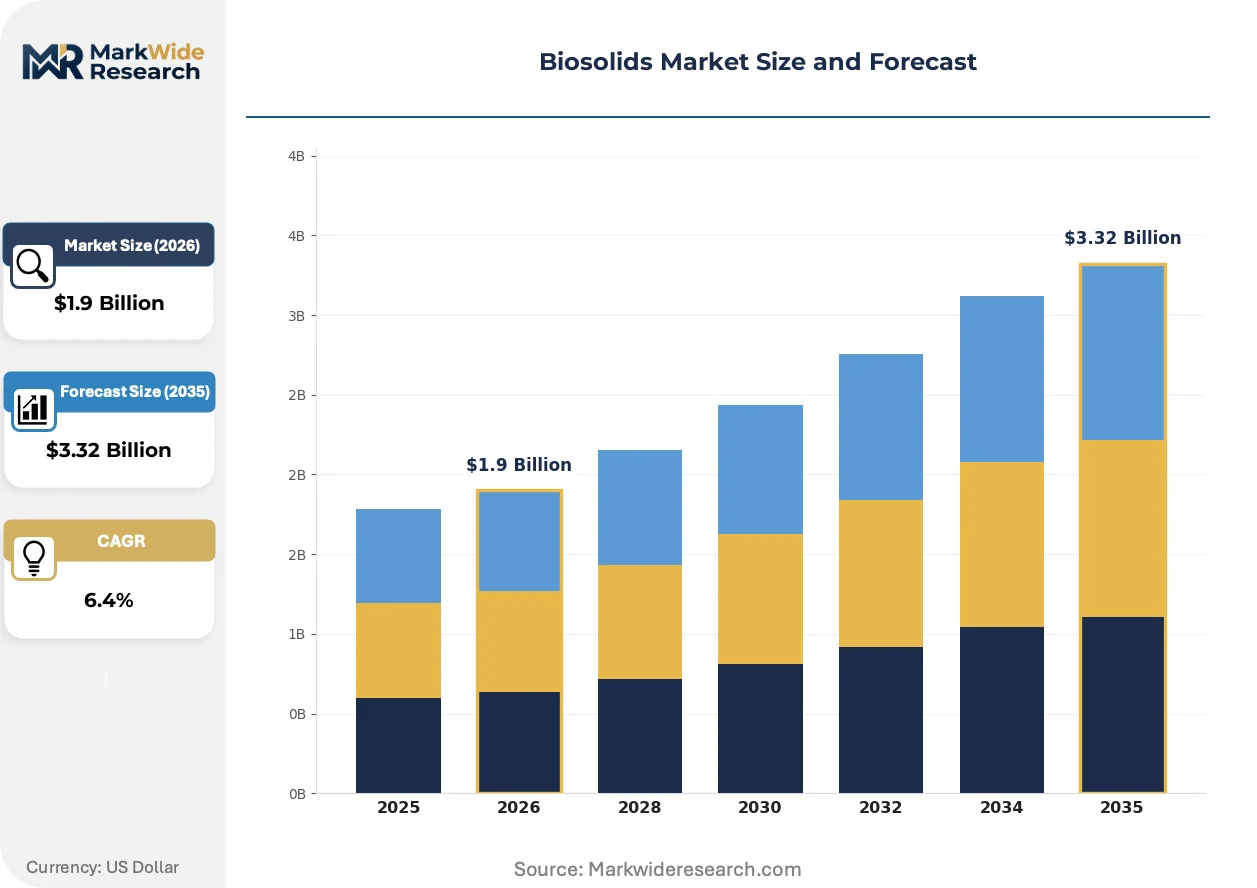
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $3.32 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dried Biosolids, Dewatered Biosolids, Composted Biosolids, Heat-Dried Biosolids, Liquid Biosolids Application: Soil Amendment, Land Reclamation, Fertilizer, Landfill Cover, Land Spreading End User: Agricultural Producers, Municipal Wastewater Treatment Plants, Forestry Management, Landscaping Companies, Construction Firms Distribution Channel: Direct Sales, Third-Party Distributors, Online Platforms, Government Agencies, Environmental Contractors |
| Companies Covered | REMONDIS SE & Co. KG, Cambi ASA, FCC Group, Englobe, Cleanaway, Synagro Technologies, Veolia, SUEZ, Casella Waste Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biosolids Market Strategic Shifts & Innovations
Advanced thermal processing and contaminant characterization technologies are redefining product classification boundaries, separating premium fertilizer-grade material from restricted-use or disposal-bound volumes.
Pyrolysis and gasification systems are expanding into municipal sludge treatment facilities seeking to produce biochar and syngas co-products alongside stabilized solids. Dutch water authorities pilot these configurations at scale. The technology is expanding into regions with constrained landfill capacity and carbon pricing exposure.
EPA 503 rule enforcement intensifies vector attraction reduction documentation requirements for land-applied material. Agricultural buyers now demand third-party certification of pathogen kill steps. Corn and soybean producers in Illinois and Iowa face the steepest compliance verification burdens.
Direct contracting between treatment operators and crop producers displaces traditional broker-mediated distribution. Large-scale farming cooperatives negotiate multi-year offtake agreements securing volume and pricing certainty. This pattern concentrates most visibly across North American corn belt operations with contiguous acreage for surface application.
Biosolids Market Segmentation
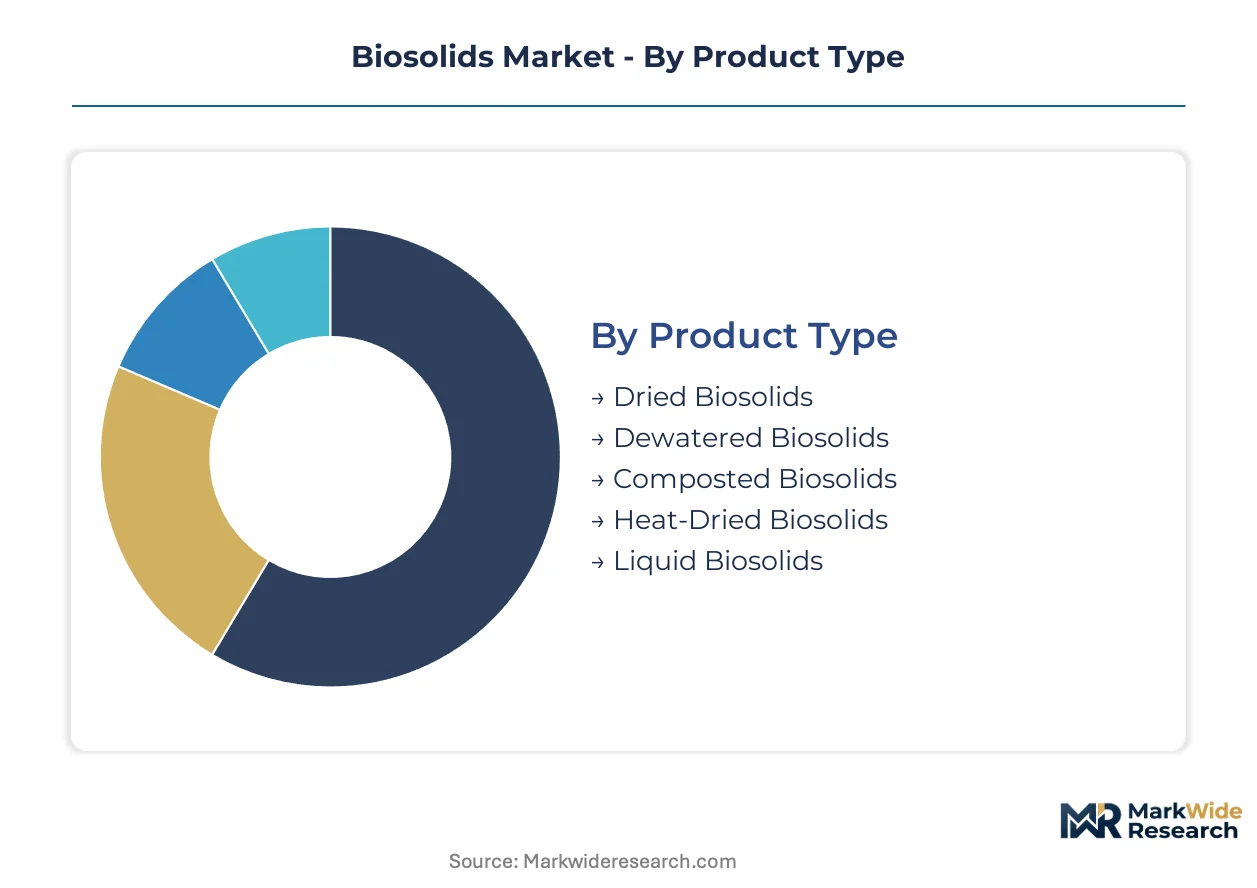
Product differentiation in biosolids markets follows processing intensity and moisture content, with each tier commanding distinct price premiums and regulatory classifications. End-user procurement patterns diverge sharply between bulk agricultural offtake and specialized land reclamation contracts.
Product Type:
Upgrade cycles from basic dewatered material to thermally processed products track regulatory pressure and transportation economics, with capital-intensive drying infrastructure creating tiered supply capabilities.
- Dried Biosolids:Thermal or solar-dried material achieving 90%+ solids content, suitable for long-distance transport and bagged retail distribution. German Rhine-Ruhr industrial corridors host the densest concentration of advanced drying facilities serving premium fertilizer markets.
- Dewatered Biosolids:Mechanically pressed sludge at 15-30% solids, representing the baseline processing tier for municipal plants without thermal infrastructure. Haul distance constraints limit viable market radius to roughly 50 miles for cost-effective land spreading.
- Composted Biosolids:Aerobically digested and matured material meeting USDA National Organic Program compliance standards for certified agriculture.
- Heat-Dried Biosolids:Pathogen-free Class A material produced through rotary drum or belt dryer systems, commanding fertilizer-grade premiums.
- Liquid Biosolids:Thickened sludge at 2-8% solids, applied directly via injection or surface spreading equipment proximal to treatment plants.
Dewatered biosolids sits at the top of the volume ranking, with heat-dried biosolids climbing the fastest.
Application:
Application selection correlates directly with contaminant testing thresholds and liability exposure, with stringent trace substance limits filtering material toward lower-risk use cases.
- Soil Amendment:Incorporation into degraded or marginal soils to improve organic matter, water retention, and microbial activity. Dutch government-mandated bio-based input quotas for public land management contracts create guaranteed offtake volumes for certified material.
- Fertilizer:Direct nutrient supplementation for crop production, requiring Class A pathogen reduction and documented vector attraction compliance. Corn and soybean producers in Illinois and Iowa face the steepest third-party certification verification burdens under intensified EPA 503 enforcement.
- Land Reclamation:Surface application to mined or disturbed lands for vegetation establishment and erosion control.
- Landfill Cover:Daily or intermediate cover material substituting for soil in municipal waste facilities.
- Land Spreading:Broad-acre agricultural application of liquid or dewatered material subject to seasonal restrictions and setback requirements.
Fertilizer dominates current volume, with soil amendment gaining share fastest.
End User:
Customer scale and contracting sophistication determine pricing power, with large cooperatives displacing broker-mediated distribution through multi-year direct agreements.
- Agricultural Producers:Crop and livestock operations purchasing bulk material for nutrient management plans. Large-scale farming cooperatives across the North American corn belt negotiate multi-year offtake agreements securing volume and pricing certainty.
- Municipal Wastewater Treatment Plants:Sludge generators seeking beneficial reuse pathways under landfill diversion mandates. EU Green Deal restrictions redirect volumes toward processing contractors with thermal drying or composting capacity.
- Forestry Management:Timber operations utilizing biosolids for site preparation and mid-rotation fertilization.
- Landscaping Companies:Commercial turf and ornamental plant maintenance contractors sourcing composted material.
- Construction Firms:Soil stabilization and erosion control contractors incorporating processed sludge into grading projects.
Agricultural producers anchor volume demand, with municipal wastewater treatment plants expanding fastest.
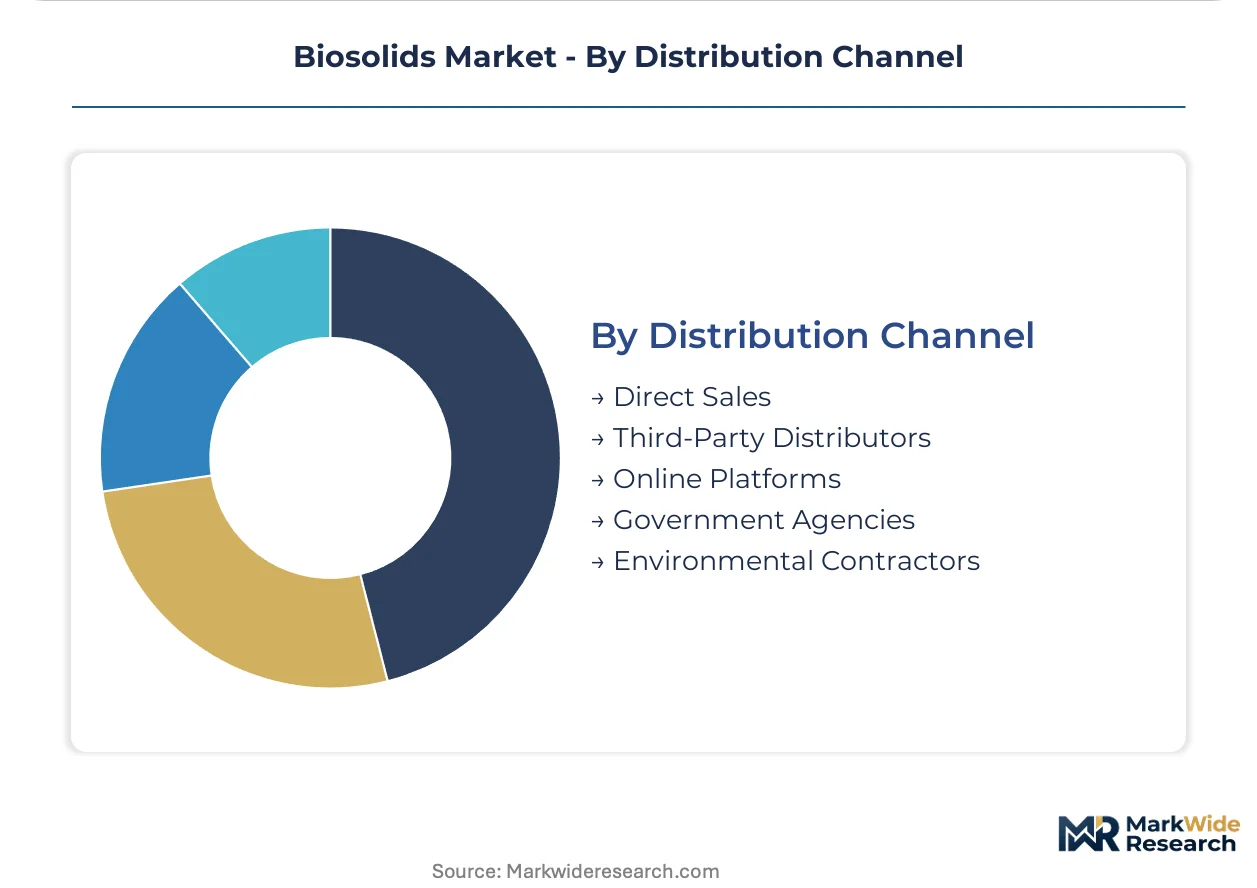
Distribution Channel:
Channel structure reflects product density and certification requirements, with low-moisture grades penetrating retail while liquid material remains captive to direct haul.
- Direct Sales:Treatment operators contracting directly with end-users for bulk material offtake. This pattern concentrates most visibly across contiguous acreage operations capable of surface application without intermediary handling.
- Third-Party Distributors:Regional brokers aggregating volumes from multiple plants for agricultural and landscaping markets.
- Online Platforms:E-commerce channels for bagged retail fertilizer products targeting home gardeners and small-scale organic producers.
- Government Agencies:Public procurement for land management, restoration, and highway maintenance contracts.
- Environmental Contractors:Specialized firms managing application logistics and regulatory compliance for complex sites.
Direct sales leads by volume, with online platforms expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized wastewater treatment engineers concentrate in German industrial clusters, Dutch water authorities, and North American municipal utilities, anchoring regional processing capabilities.
United States
Corn and soybean producers across Illinois and Iowa negotiate multi-year offtake agreements for Class A pathogen-free material. EPA 503 rule enforcement intensifies third-party certification requirements for agricultural buyers. The Midwest corn belt hosts the densest concentration of direct contracting between treatment operators and large-scale farming cooperatives.
Germany
Rhine-Ruhr industrial corridors sustain advanced thermal drying infrastructure serving premium fertilizer markets. The KBA and federal waste framework impose trace contaminant thresholds that filter out smaller treatment operators. REMONDIS and Veolia operate integrated wastewater-to-fertilizer facilities across North Rhine-Westphalia.
Netherlands
Dutch water authorities pilot pyrolysis and gasification configurations producing biochar and syngas co-products. Government-mandated bio-based input quotas for public land management contracts create guaranteed offtake volumes. Randstad municipalities anchor circular economy procurement for soil amendment applications.
Canada
Ontario and Quebec municipal utilities seek beneficial reuse pathways under landfill diversion pressure. Provincial regulators align with emerging PFAS testing protocols threatening to reclassify formerly compliant volumes. The Great Lakes corridor concentrates composting infrastructure serving organic-certified agriculture channels.
France
Île-de-France treatment plants redirect sludge volumes toward thermal processing contractors under EU Green Deal restrictions. ANSM trace substance surveillance shapes end-user liability exposure for agricultural application. Auvergne-Rhône-Alpes hosts expanding anaerobic digestion capacity for biogas recovery.
Biosolids Market Key Industry Players
Top-tier vendors anchor premium Class A processing infrastructure, while mid-sized municipal operators compete on proximity to agricultural offtake. The vendor base stratifies across integrated waste-to-resource conglomerates, specialized thermal technology providers, and regional composting specialists. Three archetypes dominate: European utilities with captive treatment networks, North American agricultural channel specialists, and technology licensors selling drying and digestion systems. Competitive moves concentrate on M&A to secure municipal contracts and capacity expansion into high-margin bagged fertilizer formats.
Within the integrated utility tier, REMONDIS SE & Co. KG and Veolia exemplify operators leveraging captive wastewater infrastructure across industrial clusters. Cambi ASA and SUEZ occupy positions as technology specialists licensing advanced digestion and thermal processing systems to municipal clients. Synagro Technologies represents the North American agricultural channel archetype, anchoring direct contracting relationships with crop producers.
| Leading Market Players |
|---|
| REMONDIS SE & Co. KG |
| Cambi ASA |
| FCC Group |
| Englobe |
| Cleanaway |
| Synagro Technologies |
| Veolia |
| SUEZ |
| Casella Waste Systems |
| Others |
Cost & Logistics Intelligence
Natural gas futures at the Dutch TTF hub cascade through thermal drying economics, compressing margins for Class A pathogen-free material while elevating premiums for low-moisture product grades that defray transport costs across extended haul radii.
Pricing Analysis
The bundled-vs-unbundled service split separates treatment operators charging all-inclusive application logistics from those selling f.o.b. plant gate. Three-tier pricing structure across Class A premium, Class B standard, and dewatered economy levels tracks certification burden and vector attraction documentation intensity. Cost compression in liquid biosolids is intensifying because haul distance constraints trap inland generators within 50-mile market radii. Agricultural cooperatives with contiguous acreage exhibit lowest price sensitivity; small landscaping contractors show highest.
Supply Chain Analysis
Regional distribution centers for bagged fertilizer product concentrate in German Rhine-Ruhr industrial corridors, with hub-and-spoke patterns radiating toward Benelux agricultural markets. Supply concentrates in Germany, the Netherlands, and the United States Midwest. Raw material flows draw from municipal wastewater treatment plants, anaerobic digestion facilities, and lime stabilization operations. Single-source vulnerability runs through thermal drying infrastructure dependent on natural gas feedstock. Distribution runs through direct haul for liquid grades and third-party agricultural brokers for bulk dewatered material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story, justified by crop producers substituting toward Class A pathogen-free biosolids as synthetic fertilizer price volatility persists.
For Market Incumbents: Extend thermal drying capacity into high-margin bagged fertilizer formats to capture retail premiums. Consolidate municipal contract portfolios in Rhine-Ruhr and Midwest corn belt corridors to anchor volume certainty. PFAS testing protocol evolution poses existential reclassification threat; accelerate contaminant characterization infrastructure to defend product access. For New Entrants and Emerging Players: Enter via composted biosolids certification for USDA National Organic Program compliance, the most penetrable channel given entry barriers favoring established infrastructure. Target Dutch government-mandated bio-based input quotas for public land management contracts as guaranteed offtake anchor. Lead with direct contracting to large-scale farming cooperatives, displacing broker-mediated distribution. For Investors and Strategic Acquirers: Asymmetric upside sits with technology licensors possessing advanced thermal drying and pyrolysis system portfolios. Long-term viability hinges on regulatory arbitrage across jurisdictions with divergent PFAS thresholds. Acquisition target archetype: mid-sized municipal operators with captive sludge supply and unutilized drying capacity. Signal to watch: federal screening limit announcements that trigger inventory reclassification waves.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Advanced thermal drying deployment in Rhine-Ruhr corridors captures Class A fertilizer premiums under EU F-Gas Regulation alignment. |
| Backward Integration | Captive wastewater infrastructure secures sludge supply certainty for treatment operators facing landfill diversion mandates. |
| Certification Investment | USDA National Organic Program compliance infrastructure creates defendable moats in composted biosolids channels. |
| Long-term Supply Agreement | Multi-year offtake contracts with Illinois and Iowa farming cooperatives displace spot market volatility. |
| Joint Venture | Dutch water authority partnerships accelerate pyrolysis pilot scale-up for biochar and syngas co-product streams. |
Research Approach
Multiple input streams — structured interviews with wastewater treatment plant managers, agricultural cooperative procurement officers, and thermal technology engineering leads; secondary validation through EPA 503 enforcement records, EU Green Deal implementation documents, and municipal sludge inventory databases; customs and trade flow data — were reconciled through bottom-up volume aggregation and top-down market sizing cross-checks.
Historical capacity utilization patterns were cross-referenced against panel input from equipment vendors and treatment operators to anchor growth assumptions across the projection horizon. Segmentation dimensions modeled include product type tier, application route, end-user scale, and regional regulatory cluster. CAGRs were derived from slope analysis of installed capacity expansion trajectories and agricultural input substitution elasticities, with thermal drying capex cycles and PFAS testing protocol evolution as industry-specific forecast inputs.
The model holds under stable regulatory classification regimes; deviation in federal PFAS screening limit announcements or EU trace contaminant threshold revisions would shift volume allocations toward incineration alternatives. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
Horticulture Bioplastic Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Animal Eubiotics Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
Bio-Seeds Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
US Biofungicide Market
Bio-Agriculture
Lignocellulosic Biomass Market
Bio-Agriculture
Italy Biopesticides Market
Bio-Agriculture
Hybrid Seeds Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
North America Biopesticides Market