
 Europe Feed Phytogenics Market | 2026-2036
Europe Feed Phytogenics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Feed Phytogenics Market Foresight
Aftermarket technical advisory revenue is rewriting value capture in European feed phytogenics, shifting margin pools from commodity ingredient sales toward customized ration-formulation services. Pancosma leverages its Swiss research infrastructure to sustain premium positioning across essential oil blends. Biomin GmbH anchors Central European supply through captive production of standardized herb extracts. Delacon Biotechnik GmbH differentiates via Austrian-based fermentation expertise for bioactive compound stabilization.
Feed phytogenics comprise plant-derived bioactive compounds—essential oils, oleoresins, and flavonoid-rich fractions—typically dosed at 100-500 grams per tonne of complete feed to modulate intestinal microbiota and enhance nutrient digestibility in monogastric and ruminant species. Their primary commercial purpose is to deliver performance equivalent to antibiotic growth promoters while satisfying residue-free certification requirements. Essential oils command the dominant margin pool among product types due to concentrated terpenoid activity and established efficacy documentation. Poultry application outpaces ruminant and swine segments in formulation innovation, driven by shorter production cycles and faster trial-to-adoption pathways.
EMA guidelines on veterinary medicinal product classification, REACH compliance for botanical substance registration, and EU Green Deal methane-reduction targets collectively elevate phytogenics as legally viable alternatives to ionophores and synthetic growth promoters. EFSA novel food and feed additive authorization pathways determine market access timelines for new botanical extracts. Stakeholders must monitor evolving ECHA substance evaluation criteria and pre-position dossier investments ahead of scheduled regulatory review windows.
Market Dynamics
Antibiotic withdrawal mandates under the EU Veterinary Medicinal Products Regulation are compressing feed formulation timelines, forcing integrators to validate phytogenic efficacy within single production cycles rather than multi-year trials. This regulatory compression is redrawing competitive boundaries between established additive suppliers and botanical extract specialists.
Growth Catalysts
- EU Green Deal methane targets:Ruminant producers in Ireland and the Netherlands are substituting ionophores with polyphenol-rich extracts to meet emission benchmarks while maintaining feed conversion ratios.
- Heat stress physiology research:Spanish broiler integrators are deploying essential oil blends containing thymol and carvacrol to stabilize gut integrity during summer temperature spikes.
- REACH botanical substance registration:Standardized authorization pathways for plant-derived compounds are reducing regulatory uncertainty for novel extract commercialization.
Market Restraints
- Raw material supply concentration:Oregano and thyme essential oil production concentrates in Mediterranean growing regions, exposing formulators to climate-induced harvest volatility.
- EFSA novel feed additive timelines:Authorization dossiers for new bioactive compounds face 18-24 month evaluation windows, delaying market entry for innovative extracts.
- Synthetic antioxidant substitution:Butylated hydroxytoluene retains cost advantages in bulk feed applications, limiting phytogenic penetration in price-sensitive compound feed segments.
Strategic Opportunities
- Polish and Romanian pork integration:Consolidating sow operations in Eastern Europe seek gut-health solutions for post-weaning diarrhea management without zinc oxide.
- Fermentation-stabilized bioactives:Anaerobic processing of flavonoid fractions extends shelf stability, enabling premix distribution through conventional feed mill channels.
- CSRD supply chain disclosure:Corporate sustainability reporting mandates are elevating plant-derived additives in procurement scorecards for protein retailers.
Industry Challenges
- Phytochemist talent scarcity:Formulation teams lack specialists capable of standardizing terpenoid profiles across seasonal botanical harvests.
- Multi-species efficacy validation:Broiler-optimized blends require costly re-trialing for layer and turkey applications, fragmenting R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Feed Phytogenics Market |
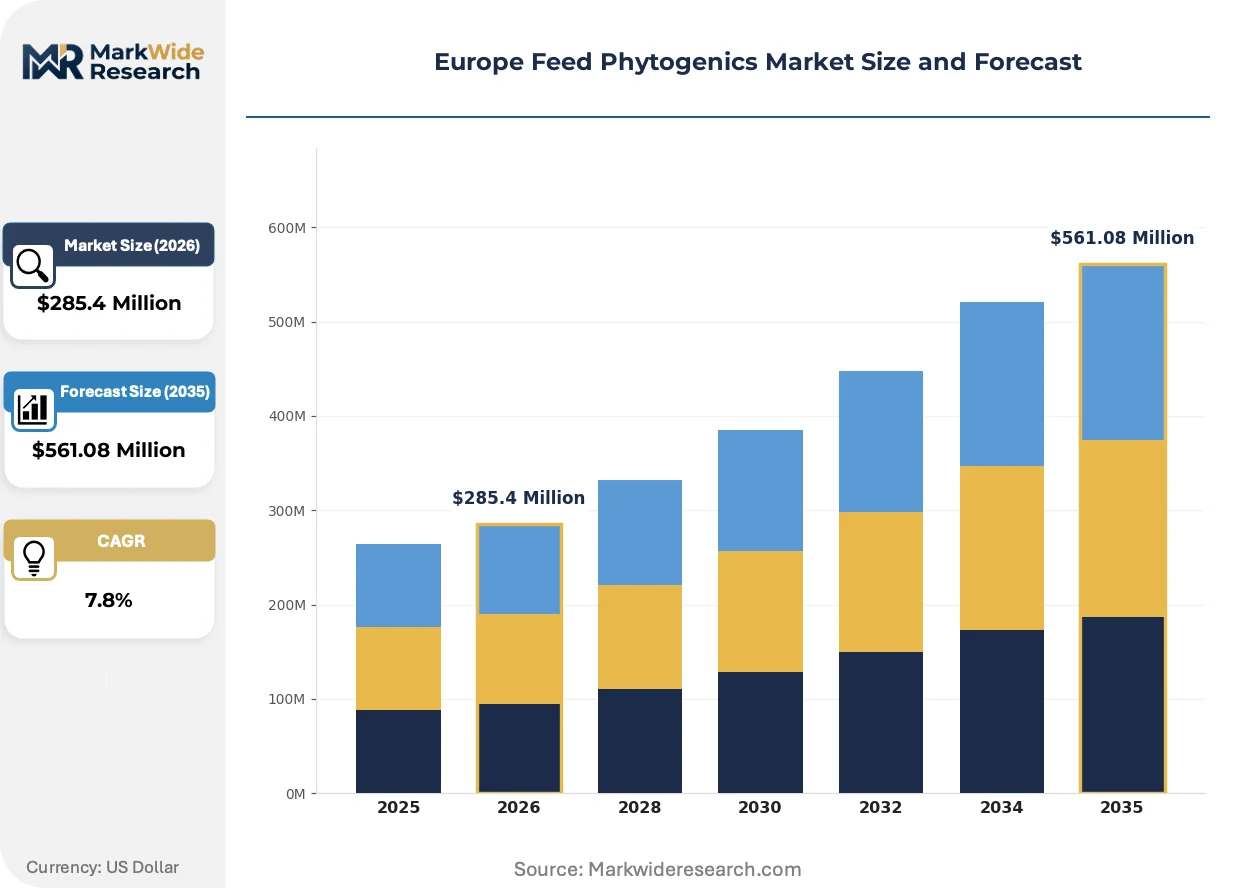
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $561.08 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Essential Oils, Spices, Herbs, Extracts Application: Ruminants, Poultry, Swine, Aquaculture Form: Liquid, Powder, Granules, Tablets Distribution Channel: Direct Sales, Wholesalers, Retailers, Online |
| Companies Covered | Pancosma, Phytosynthese, Biomin GmbH, Dostofarm GmbH, Adisseo France SAS, Cargill Incorporated, Phytobiotics Futterzusatzstoffe GmbH, Dsm-Firmenich, Delacon Biotechnik GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Feed Phytogenics Market Shifts & Advancements
Microencapsulation and targeted-release delivery systems are rewriting efficacy benchmarks for volatile essential oils, enabling phytogenic deployment in pelleted feeds previously hostile to heat-labile compounds.
Spay-dried lipid matrix encapsulation is collapsing the historical trade-off between processing survivability and intestinal release kinetics. German compound feed manufacturers are adopting this technology for thermally treated broiler rations. The compression of formulation constraints is enabling phytogenic inclusion rates previously reserved for synthetic alternatives.
REACH substance evaluation criteria for botanical extracts are tightening purity thresholds for polycyclic aromatic hydrocarbons and pesticide residues. ECHA's scheduled review windows are forcing extract suppliers to upgrade purification infrastructure ahead of compliance deadlines. Spanish and Italian herb processors are investing in supercritical CO2 extraction to preempt regulatory disqualification.
Integrated poultry operators are consolidating phytogenic procurement through captive premix subsidiaries, bypassing independent distributors. This channel compression concentrates volume with formulators capable of custom ration design rather than commodity supply. France's largest broiler integrators have internalized technical advisory functions previously outsourced to additive houses.
Europe Feed Phytogenics Market Segmentation
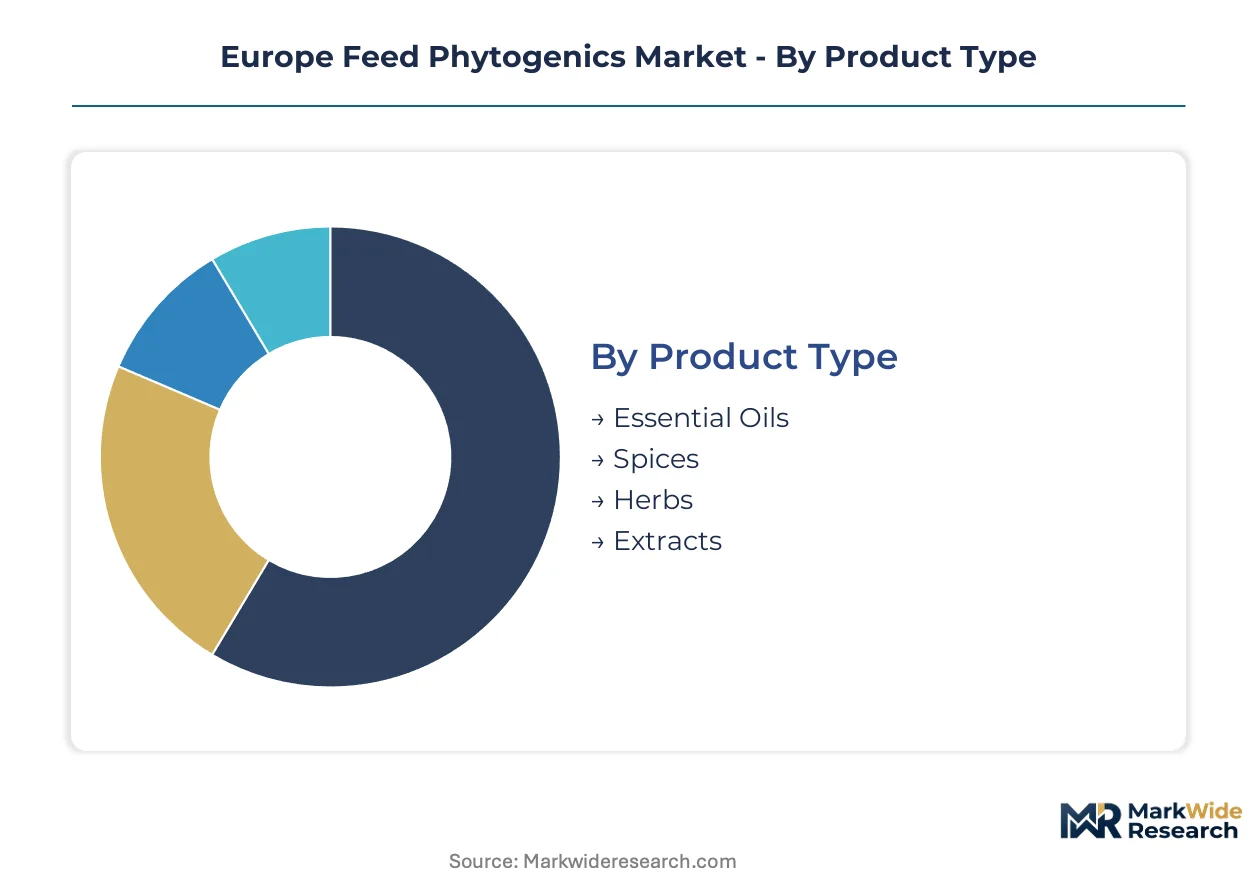
Phytogenic formulators must align product architecture with species-specific production cycles and feed mill processing constraints. Segmentation choices directly determine regulatory pathway complexity and margin capture potential across European livestock systems.
Product Type:
Cycle times vary dramatically: essential oils turn inventory weekly during harvest seasons, while standardized extracts lock working capital for months through EFSA authorization queues.
- Essential Oils:Concentrated terpenoid fractions derived from steam-distilled plant material, typically standardized for thymol, carvacrol, or cinnamaldehyde content. German and French poultry integrators specify these for immediate antibiotic replacement trials, compressing validation timelines to single production cycles. Climate volatility in Mediterranean growing regions exposes supply chains to harvest disruption.
- Extracts:Solvent-derived bioactive concentrates including oleoresins and flavonoid-rich fractions, offering batch-to-batch consistency through HPLC-standardized marker compounds. Irish and Dutch ruminant operators source polyphenol extracts to satisfy EU Green Deal methane benchmarks without sacrificing feed conversion performance. ECHA purity thresholds for polycyclic aromatic hydrocarbons force continuous purification infrastructure investment.
- Spices:Dried and milled botanical material retaining native enzyme and antioxidant activity, dosed as whole-plant matrices rather than isolated actives.
- Herbs:Coarsely processed aerial plant parts with variable phytochemical profiles, typically deployed in organic-certified feed formulations where synthetic additive exclusion is mandatory.
Essential oils dominate installed base. Extracts are where expansion concentrates.
Application:
Customer procurement patterns split between integrators seeking single-species optimization and compound feed mills demanding multi-species compatibility.
- Poultry:Broiler operations drive formulation innovation through compressed trial-to-adoption pathways enabled by short production cycles. Spanish integrators deploy thymol-carvacrol blends against summer heat stress gut integrity challenges. Faster validation turnaround attracts R&D investment away from longer-cycle species.
- Ruminants:Cattle and dairy operations present complex rumen microbiota modulation requirements distinct from monogastric physiology. Irish producers substitute ionophores with tannin-rich extracts to meet emission reduction targets while maintaining milk yield parameters. Methane quantification protocols extend proof-of-concept timelines.
- Swine:Post-weaning diarrhea management in Polish and Romanian sow operations creates demand for gut-health solutions replacing zinc oxide pharmacological doses.
- Aquaculture:Mediterranean seabass and seabream producers trial phytogenic inclusion for disease resistance in antibiotic-restricted marine environments.
Poultry commands current volume leadership. Ruminant applications are climbing the fastest.
Form:
Processing survivability requirements create sharp cost tier differentiation between heat-labile liquids and thermally robust dry forms.
- Powder:Spray-dried or adsorbed formulations offering intermediate stability for mash feed applications without pelleting thermal exposure. German compound feed manufacturers specify powder forms for broiler starter rations processed at moderate temperatures.
- Liquid:Unencapsulated oil-phase products requiring post-pelleting application or cold-processed feed matrices. Highest bioavailability but restricted to specialty feed mills with temperature-controlled handling infrastructure.
- Granules:Microencapsulated or lipid-matrix protected forms enabling inclusion in thermally processed pelleted feeds. Premium positioning reflects spray-drying and targeted-release technology investment.
- Tablets:Compressed unit-dose formats for on-farm top-dressing applications, bypassing feed mill integration entirely.
Powder forms anchor mainstream premix supply. Granules are gaining share fastest.
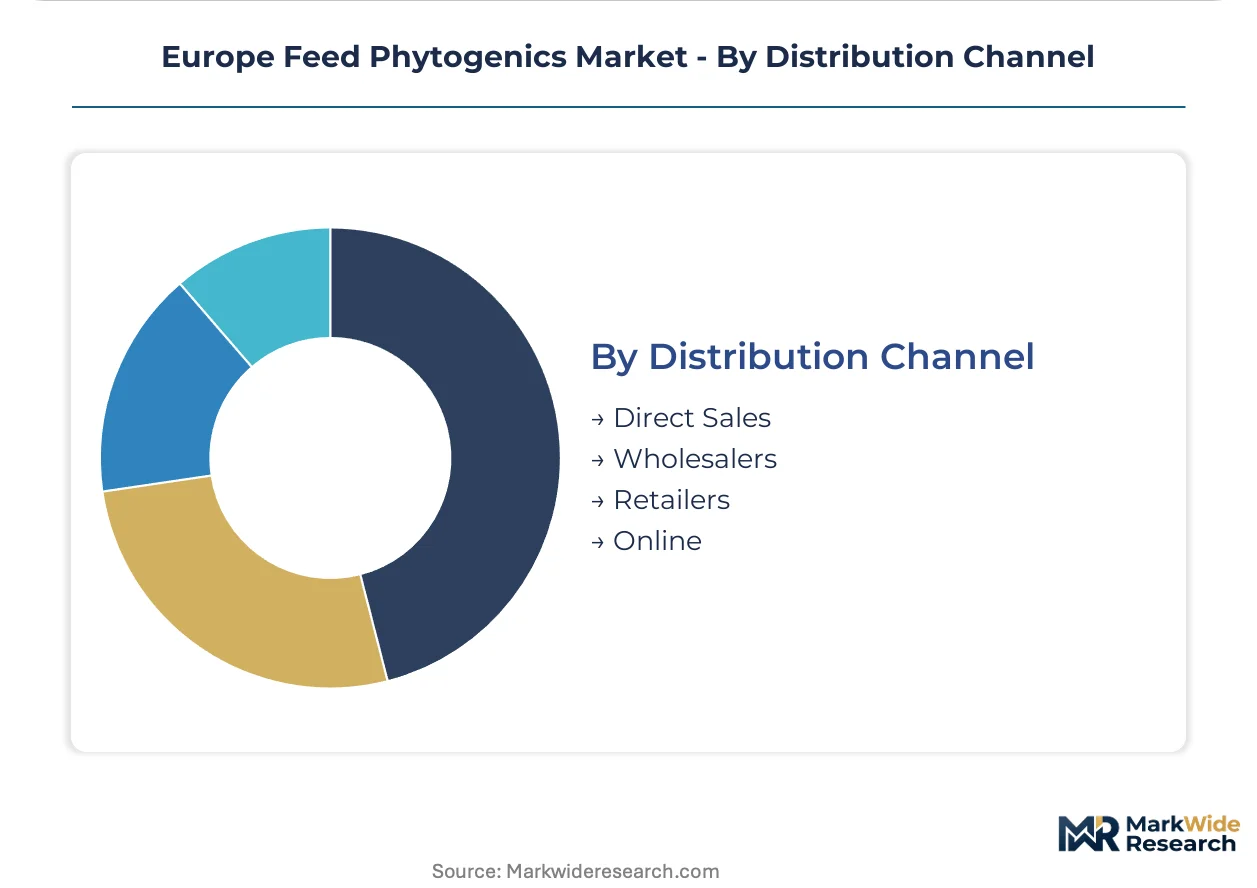
Distribution Channel:
Channel compression is eliminating intermediary margin layers as integrated operators internalize technical advisory functions.
- Direct Sales:Manufacturer-to-integrator relationships capturing full value chain margin through captive premix subsidiaries. France's largest broiler operators have absorbed formulation expertise previously outsourced to additive houses.
- Wholesalers:Regional distributors aggregating demand from independent compound feed mills lacking direct supplier relationships.
- Retailers:Agricultural supply cooperatives serving smaller livestock operations with packaged phytogenic supplements.
- Online:Emerging digital procurement channels for specialty and organic-certified products bypassing traditional distribution infrastructure.
Direct sales dominate value capture. Online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German poultry integrators deploy phytogenics as antibiotic replacements in compressed validation cycles, while Irish ruminant operators prioritize methane-reduction extracts under EU Green Deal benchmarks. This consumption-mix differential separates monogastric-focused markets from emission-driven ruminant systems.
Germany
Broiler integrators in Lower Saxony specify essential oil blends for single-cycle efficacy validation under Veterinary Medicinal Products Regulation withdrawal timelines. EFSA novel feed additive dossiers dominate regulatory bandwidth for extract suppliers. The Oldenburg Münsterland cluster concentrates premix manufacturing capacity for Central European distribution.
France
Large broiler operators in Brittany have internalized phytogenic procurement through captive premix subsidiaries, eliminating independent distributor margins. CSRD supply chain disclosure mandates elevate plant-derived additives in retailer procurement scorecards. The Pays de la Loire integrator belt drives technical advisory service demand.
Spain
Andalusian and Catalonian broiler flocks receive thymol-carvacrol formulations against summer heat stress gut integrity challenges. REACH botanical substance registration creates compliance urgency for Mediterranean herb processors. The Lleida livestock corridor concentrates intensive poultry operations seeking climate-adaptive feed solutions.
Ireland
Dairy and beef producers substitute ionophores with tannin-rich polyphenol extracts to satisfy EU Green Deal methane reduction targets. EMA veterinary medicinal product classification guidelines determine phytogenic versus pharmaceutical regulatory pathways. The Munster grassland dairy belt trials rumen microbiota modulation protocols.
Netherlands
Ruminant emission quantification protocols extend proof-of-concept timelines for methane-reduction extract validation. F-Gas Regulation tightening indirectly elevates plant-derived alternatives through synthetic additive restriction. The Gelderland livestock research corridor hosts controlled environment trials for dairy feed conversion maintenance.
Europe Feed Phytogenics Market Competitive Landscape
Capability concentration sits with botanical extraction specialists possessing fermentation stabilization expertise; scale advantage sits with diversified additive houses commanding integrated premix distribution. The vendor base organizes around three strategic archetypes: Swiss and Austrian research-driven formulators, German captive production operators, and French nutrition-integrated suppliers. M&A activity targets fermentation technology assets, while capacity expansion concentrates in supercritical CO2 extraction infrastructure.
Among Swiss-anchored research specialists, Pancosma exemplifies premium positioning through essential oil blend standardization. German GmbH-structured operators including Biomin GmbH and Dostofarm GmbH occupy positions linking captive herb extract production to Central European compound feed mill supply. These entities represent the scale-capability hybrid archetype bridging research depth with manufacturing throughput.
| Leading Market Players |
|---|
| Pancosma |
| Phytosynthese |
| Biomin GmbH |
| Dostofarm GmbH |
| Adisseo France SAS |
| Cargill Incorporated |
| Phytobiotics Futterzusatzstoffe GmbH |
| Dsm-Firmenich |
| Delacon Biotechnik GmbH |
| Others |
Supply & Pricing Matrix
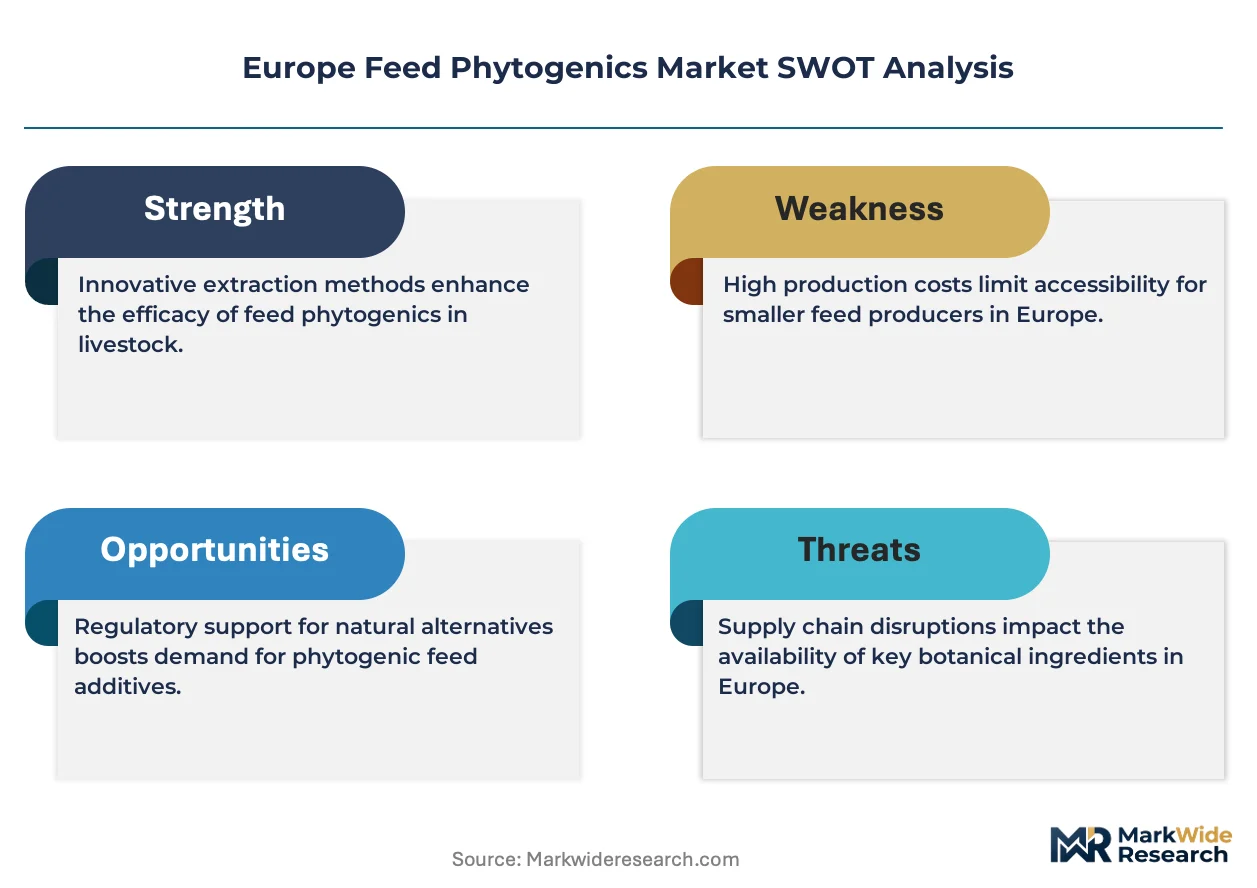
Mediterranean oregano and thyme harvest concentration in Spain and Italy anchors margin capture downstream, where German and French poultry integrators pay premiums for validated essential oil blends. REACH compliance costs and EFSA authorization timelines compress working capital returns for extract suppliers while concentrating pricing power with formulators possessing captive fermentation stabilization capabilities.
Pricing Analysis
Long-term offtake contracts dominate procurement between established phytogenic suppliers and integrated poultry operators, insulating premium-tier formulators from spot-market volatility in raw terpenoid feedstocks. Pricing stratifies across premium, standard, and economy tiers based on EFSA novel food authorization status and microencapsulation technology deployment. Cost compression in standard-grade essential oil blends is intensifying as Spanish and Italian herb processors expand supercritical CO2 extraction capacity. Compound feed mills represent the most price-sensitive buyer segment, while captive premix subsidiaries of large integrators absorb premium positioning for customized ration-formulation services.
Supply Chain Analysis
Upstream aromatic herb cultivation concentrates in Spain, Italy, and Greece, where climate-induced harvest volatility exposes formulators to terpenoid profile inconsistency. The supply chain draws from steam-distillation infrastructure for essential oils, solvent-extraction capacity for oleoresins, and anaerobic fermentation vessels for bioactive stabilization. Single-source vulnerability runs through Mediterranean growing regions susceptible to drought-induced yield compression. Distribution runs through direct manufacturer-to-integrator relationships and regional wholesalers serving independent compound feed mills.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase as antibiotic withdrawal mandates under EU Veterinary Medicinal Products Regulation force accelerated phytogenic validation cycles. The compression of trial-to-adoption timelines is reallocating margin pools toward technical advisory capabilities.
For Market Incumbents: Build regulatory dossier moats by pre-positioning EFSA novel feed additive submissions ahead of scheduled ECHA review windows. Consolidate backward integration into Mediterranean herb processing to secure terpenoid supply against climate volatility. Defend against botanical extract specialists by embedding fermentation stabilization expertise within captive premix subsidiaries. For New Entrants and Emerging Players: Polish and Romanian pork integration presents underpenetrated white-space for post-weaning diarrhea solutions displacing zinc oxide. Target aquaculture applications in Mediterranean seabass and seabream operations where antibiotic restrictions create immediate substitution demand. Pursue go-to-market partnerships with Eastern European compound feed mills lacking direct supplier relationships to established Swiss and Austrian formulators. For Investors and Strategic Acquirers: Capital is best deployed toward fermentation technology assets capable of extending shelf stability for flavonoid fractions. Long-term viability hinges on positioning ahead of CSRD supply chain disclosure mandates elevating plant-derived additives in retailer procurement scorecards. Monitor EMA veterinary medicinal product classification guidance revisions as the critical inflection signal determining phytogenic versus pharmaceutical regulatory pathways.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Herb Cultivation | Captive supply of Mediterranean oregano and thyme secures terpenoid consistency against harvest volatility. |
| EFSA Novel Feed Additive Dossier Investment | Pre-positioned authorization submissions compress market entry timelines for innovative botanical extracts. |
| Fermentation Stabilization Capacity Expansion | Anaerobic processing expertise enables premix distribution through conventional feed mill channels. |
| Microencapsulation Technology Deployment | Spray-dried lipid matrix protection expands addressable market to thermally processed pelleted feeds. |
| Captive Premix Subsidiary Formation | Internalized procurement eliminates distributor margins and captures full value chain margin pools. |
Research Methodology
Cross-validation between primary interviews with feed additive formulators and secondary validation through EFSA novel food authorization databases anchors the qualitative findings. Conversations with poultry integration technical directors, ruminant nutrition consultants, compound feed mill procurement managers, and veterinary medicinal product regulatory specialists were synthesized with REACH substance registration records, ECHA evaluation criteria publications, EU Green Deal implementation progress reports, and customs trade data for essential oil imports. Bottom-up segmentation modeling and top-down market sizing triangulate volume estimates across product type, application, and distribution channel dimensions.
Calibration against historical EFSA authorization timelines and verified installation capacity for supercritical CO2 extraction infrastructure validates growth trajectory assumptions across the projection horizon. The analytical framework models essential oil, extract, spice, and herb product categories against poultry, ruminant, swine, and aquaculture applications, incorporating form-specific processing survivability constraints and direct versus wholesale channel dynamics. CAGRs were derived from segment-level demand build-ups incorporating regulatory compliance cost trajectories and species-specific adoption elasticity.
Practitioners should monitor EMA veterinary medicinal product classification revisions, ECHA scheduled substance evaluation windows, and Mediterranean climate indices for early signals of forecast deviation. Cross-checking against EU livestock production statistics and compound feed manufacturing output data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
India Biopesticides Market
Bio-Agriculture
Middle East and Africa Biofertilizers Market
Bio-Agriculture
Middle East and Africa Animal Genetics Market
Bio-Agriculture
China Feed Probiotics Market
Bio-Agriculture
Bio-Based Succinic Acid Market
Bio-Agriculture
Azotobacter Based Biofertilizer Market
Bio-Agriculture
France Biopesticides Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market
Bio-Agriculture
United States Biopesticides Market
Bio-Agriculture
Brazil Biopesticides Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
Latin America Biostimulants Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
Biofertilizers Market
Bio-Agriculture
Rhizobium-Based Biofertilizer Market
Bio-Agriculture
Cytokinins Market