
 Animal Eubiotics Market | 2026-2036
Animal Eubiotics Market Size, Share, and Industry Trends Forecast 2026-2036
Animal Eubiotics Market Intelligence
Feed additive service revenue is reconfiguring margin pools away from commodity mineral premixes toward microbiome-targeted formulations. Cargill leverages its integrated supply chain from strain development to on-farm technical service. dsm-firmenich anchors European demand through precision-delivery prebiotic platforms. BASF competes on fermentation scale for organic acid production across multiple animal species.
Animal eubiotics comprise live microorganisms, fermentable substrates, and bioactive metabolites that colonize or nourish the gastrointestinal tract to exclude pathogens and enhance nutrient assimilation; industrial production employs submerged fermentation, spray-drying, and microencapsulation to achieve colony-forming unit stability above 10^9 CFU/g through shelf life. Probiotics and prebiotics together command the dominant share of product value, while enzymes represent the fastest-expanding category as phytase and carbohydrase inclusion rates rise in cereal-based diets. Synbiotics occupy a premium niche where coordinated probiotic-prebiotic dosing demonstrates measurable feed conversion improvements in broiler trials.
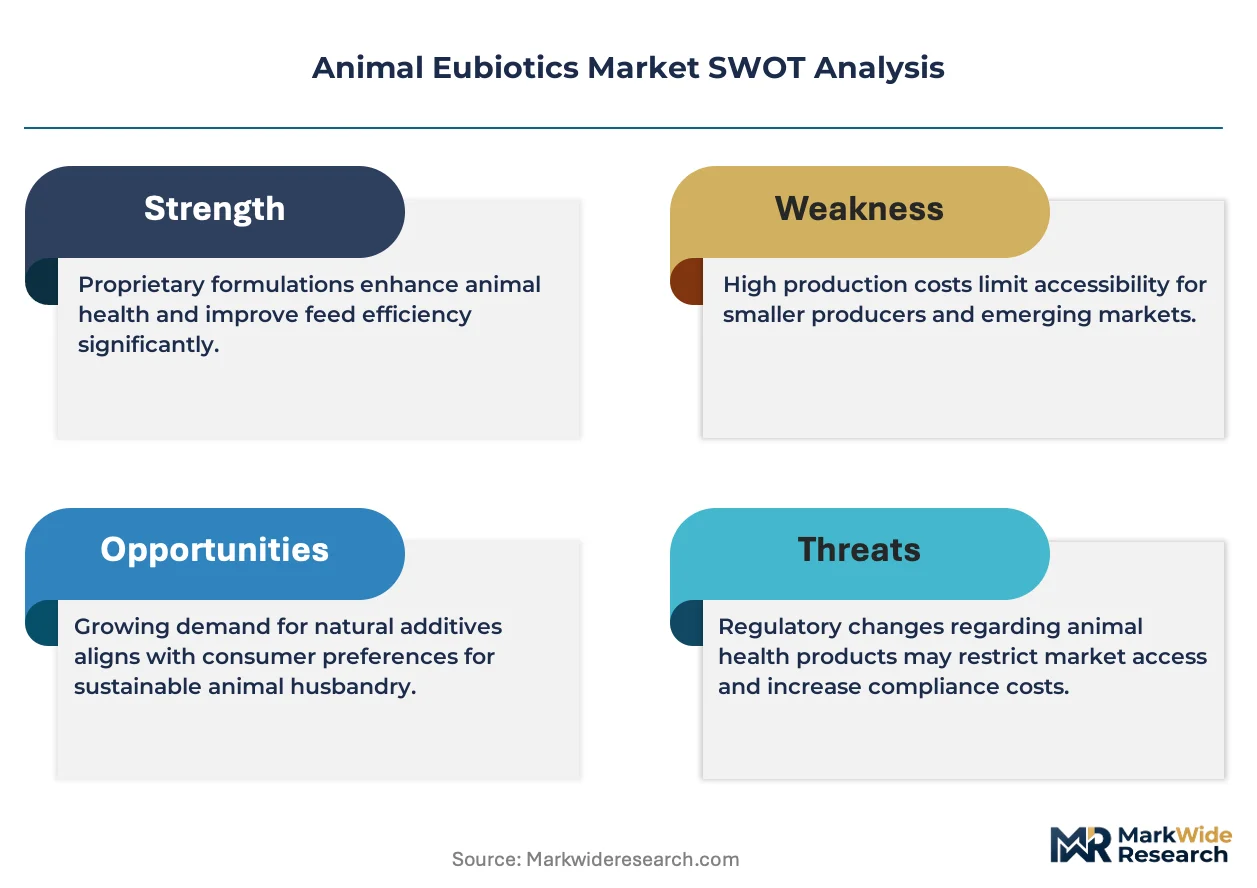
FDA's Veterinary Feed Directive and EU EFSA feed additive authorization process shape product registration timelines and label claims for gut health and growth promotion. BIS feed grade standards in India and China's MEE environmental compliance rules for fermentation effluent further constrain manufacturing location decisions. Stakeholders must monitor evolving regulatory divergence between jurisdictions that accept novel microbial strains and those requiring exhaustive safety dossiers.
Market Dynamics
Antibiotic growth promoter bans under EU REACH and FDA Veterinary Feed Directive are forcing feed compounders to rebuild gut health protocols around live microbial strains and fermentable substrates, restructuring procurement priorities across integrated poultry and swine operations.
Growth Catalysts
- EU REACH enforcement:Complete phase-out of antibiotic growth promoters in broiler and piglet feeds creates mandatory substitution demand for probiotic and organic acid formulations in German, Dutch, and Polish processing clusters.
- Precision fermentation:Advances in submerged culture systems and spray-drying stabilization now deliver colony-forming unit viability above 10^9 CFU/g through 18-month shelf life, unlocking commercial scale for heat-sensitive Lactobacillus and Bacillus strains.
- Brazilian export compliance:EU and Japanese residue standards for poultry imports drive integrated processors in Paraná and Santa Catarina to adopt documented eubiotic programs with full supply chain traceability.
Market Restraints
- Strain banking concentration:Proprietary microbial culture collections reside with a narrow set of European and North American suppliers, creating single-source vulnerability for novel probiotic launches.
- Fermentation feedstock volatility:Molasses and corn steep liquor prices fluctuate with sugar and ethanol markets, compressing margins on organic acid and live culture production.
- EFSA authorization timelines:Novel strain safety dossiers require 18-24 month evaluation cycles, delaying product commercialization and locking out smaller developers lacking regulatory affairs capacity.
Strategic Opportunities
- India BIS feed grade expansion:Formal standards for probiotic stability and prebiotic purity are under development, positioning early entrants to shape specification frameworks before market maturation.
- Aquaculture microbiome targeting:Shrimp and salmonid producers in Vietnam and Norway seek validated synbiotic protocols to replace antibiotic bath treatments and improve feed conversion in high-density systems.
- Layer hen welfare mandates:Cage-free transition requirements in California and EU member states create demand for gut health formulations that maintain productivity under stress conditions of aviary housing.
Industry Challenges
- Microbiome assay standardization:Lack of harmonized methods for measuring colonization efficacy across laboratories complicates label claim substantiation and customer proof-of-concept trials.
- Multi-species formulation complexity:Swine, poultry, and ruminant digestive physiologies require distinct strain combinations and delivery matrices, fragmenting R&D spend and diluting platform economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Animal Eubiotics Market |
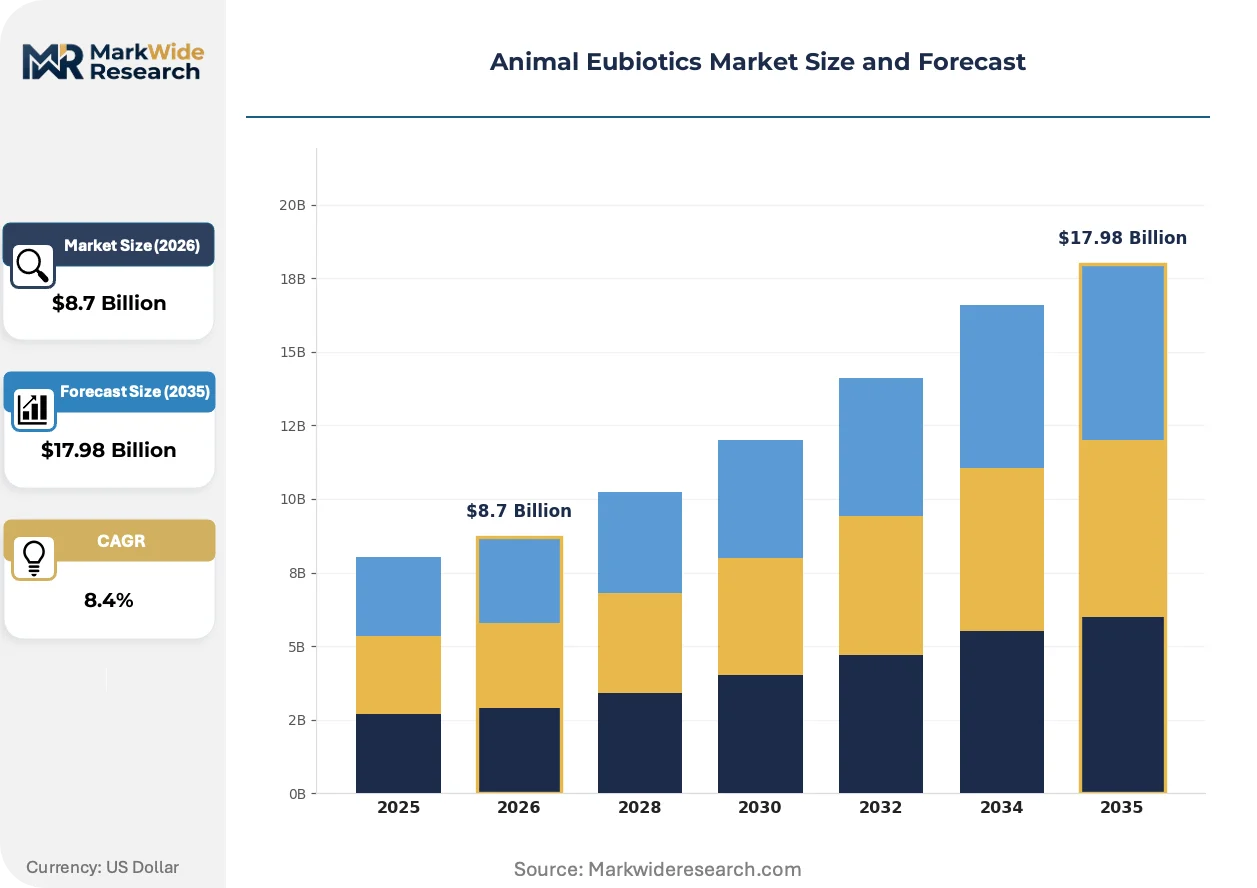
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $17.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Synbiotics, Enzymes, Organic Acids Animal Type: Poultry, Aquaculture, Ruminants, Swine, Pet Animals Application: Growth Promotion, Disease Prevention, Feed Efficiency, Gut Health Improvement, Immune Enhancement End User: Commercial Farms, Veterinary Clinics, Feed Manufacturers, Research Institutions |
| Companies Covered | Cargill, Alltech, dsm-firmenich, Novus International, Lallemand Animal Nutrition, BASF, Kemin Industries, Adisseo, Evonik Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Animal Eubiotics Market Strategic Shifts & Innovations
Live culture stabilization and targeted-release delivery systems are redefining product performance benchmarks, while regulatory chemistry is shifting from growth promotion claims to documented gut health outcomes.
Microencapsulation technology is hybridizing with precision fermentation outputs to protect probiotic viability through pelleting temperatures exceeding 85°C. Feed millers in Denmark and Thailand are adopting lipid-matrix and alginate-shell systems that release active cultures in the distal intestine rather than the acidic stomach environment. This convergence is compressing the performance gap between direct-fed microbials and antibiotic alternatives in starter diets.
EFSA's 2023 updated guidance on feed additive characterization now requires whole-genome sequencing for novel microbial strains and expanded toxicological endpoints for metabolite screening. Authorization dossiers for gut health claims must demonstrate mode-of-action specificity rather than empirical performance data alone. Developers are responding by front-loading bioinformatics and in-vitro colonization modeling to reduce costly animal trial iterations.
Integrated processors are consolidating additive procurement under technical service contracts that bundle strain selection, diet reformulation, and on-farm microbiome monitoring. This displaces traditional mineral premix spot purchasing in Brazil's southern broiler belt and Spain's piglet integration networks. The shift concentrates vendor relationships with firms offering diagnostic-backed dosing optimization rather than commodity volume supply.
Animal Eubiotics Market Segmentation
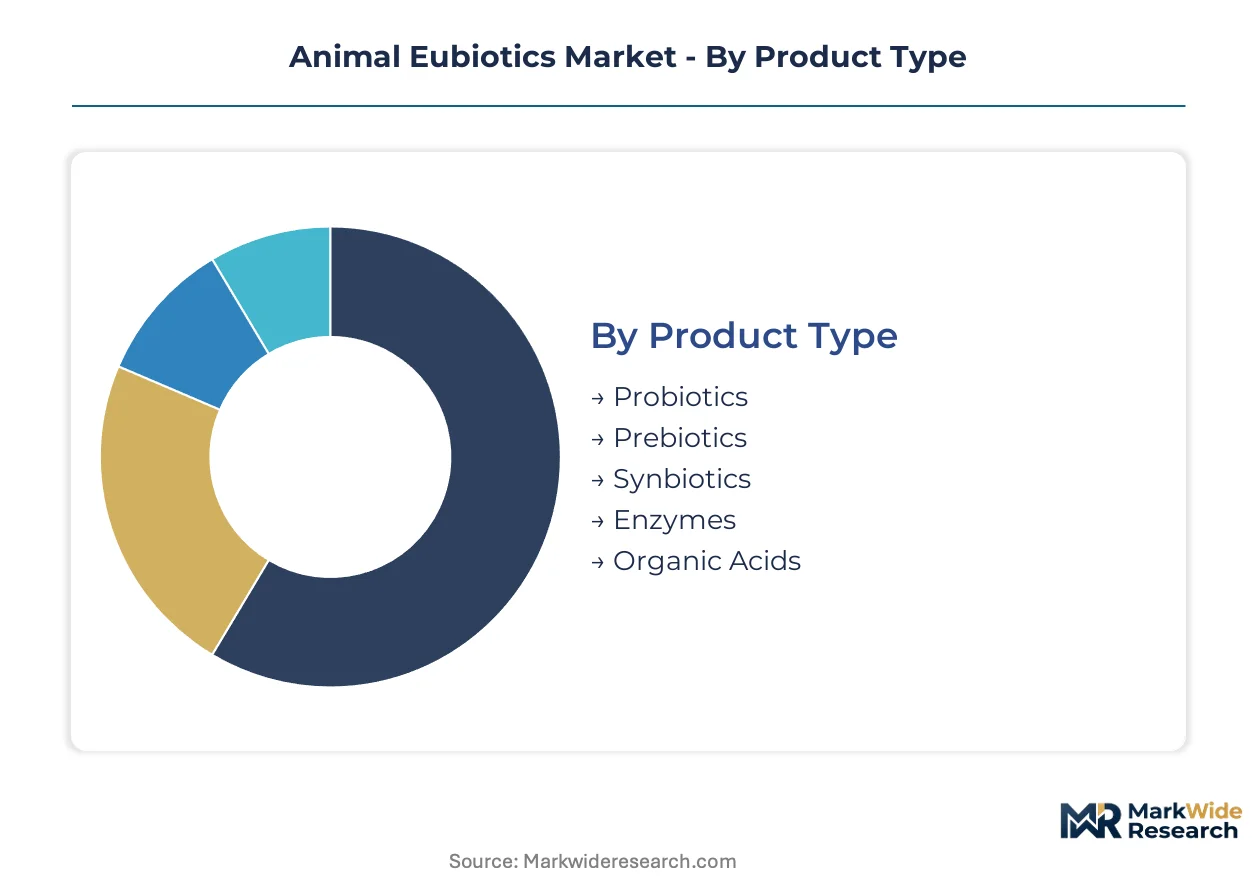
Eubiotic purchasing patterns fragment across species physiology, regulatory claim categories, and integration depth of end-users. Understanding these divides exposes where formulation complexity commands premium pricing versus where commodity substitution prevails.
Product Type:
Cost tier stratification separates live culture platforms from chemical metabolites, with fermentation scale and stabilization technology determining margin capture.
- Probiotics:Live microbial cultures of Lactobacillus, Bacillus, and Enterococcus strains delivered at minimum 10^9 CFU/g viability. Demand concentrates in German and Dutch broiler integration networks where EFSA-enforced antibiotic bans mandate documented gut colonization protocols.
- Prebiotics:Fermentable oligosaccharides including fructans and mannan-oligosaccharides that selectively nourish beneficial microbiota. Brazilian export-oriented processors in Paraná deploy these for residue-compliant documentation required by Japanese importers.
- Synbiotics:Co-formulated probiotic-prebiotic combinations with coordinated dosing.
- Enzymes:Phytase, carbohydrase, and protease preparations for cereal-based diet optimization.
- Organic Acids:Propionic, formic, and butyric acid formulations produced via submerged fermentation.
Probiotics holds installed capacity. Enzymes is rotating up the share rankings.
Animal Type:
Application complexity varies with digestive tract morphology, driving distinct formulation specifications across species.
- Poultry:Short digestive transit times demand acid-stable strains and rapid-colonizing Bacillus formulations. Feed conversion ratio pressure in Brazilian and Thai export operations sustains premium pricing for heat-stable direct-fed microbials.
- Swine:Weaning stress protocols require multi-strain synbiotics targeting ileal and cecal microbiome establishment. Polish and Danish piglet operations prioritize documented mode-of-action claims over empirical performance data.
- Ruminants:Forestomach fermentation complicates live culture delivery.
- Aquaculture:Water-immersion delivery routes and high-density stress create distinct technical requirements.
- Pet Animals:Premium positioning in companion animal nutrition channels.
Poultry commands current volume. Aquaculture is climbing the fastest as shrimp and salmonid producers seek antibiotic replacement protocols.
Application:
Regulatory claim categories determine label authorization timelines and customer proof-of-concept requirements.
- Gut Health Improvement:Mode-of-action specific claims demonstrating pathogen exclusion and intestinal villi integrity. EFSA's updated guidance demands whole-genome sequencing and toxicological endpoints, extending dossier preparation for novel strains.
- Feed Efficiency:Documented feed conversion ratio improvements in controlled trials. Brazilian integrated processors bundle these claims with on-farm technical service contracts displacing spot premix purchasing.
- Growth Promotion:Restricted claim category under FDA Veterinary Feed Directive.
- Disease Prevention:Veterinary medicinal product border in EU jurisdiction.
- Immune Enhancement:Emerging claim category requiring biomarker substantiation.
Gut Health Improvement holds regulatory investment. Feed Efficiency is gaining share fastest as procurement shifts to outcome-based technical service models.
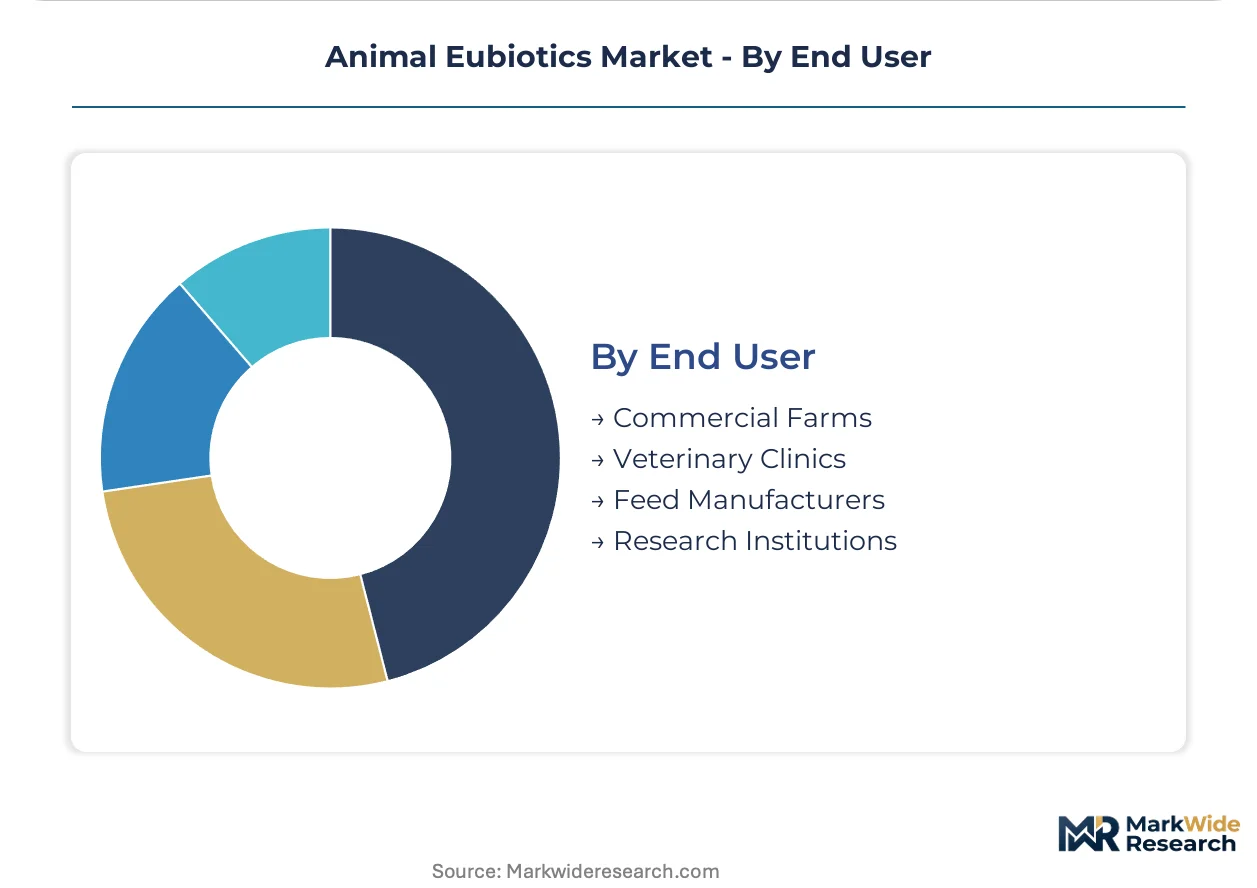
End User:
Integration depth determines whether purchasing optimizes commodity input costs or captures performance-linked value.
- Feed Manufacturers:Compounders reformulating mineral premixes around microbiome-targeted platforms. Cargill and dsm-firmenich capture margin through strain-to-service vertical control.
- Commercial Farms:Large-scale operations with in-house nutritionists and diagnostic capabilities. Spain's piglet integration networks and Brazil's southern broiler belt consolidate vendor relationships around microbiome monitoring partnerships.
- Veterinary Clinics:Prescription and therapeutic application channels.
- Research Institutions:Strain validation and trial execution partners.
Feed Manufacturers anchor platform economics. Commercial Farms is rotating up the share rankings as backward integration into additive procurement accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity for eubiotic formulations varies sharply by market maturity. German and Dutch buyers accept premium synbiotics with documented mode-of-action claims, while Indian and Brazilian procurement prioritizes cost-efficient organic acid blends for antibiotic replacement compliance.
Germany
EFSA-enforced antibiotic growth promoter bans in broiler and piglet feeds create mandatory substitution demand. The country's feed additive authorization process requires whole-genome sequencing and toxicological endpoints for novel strain registration. Dense integration networks in Lower Saxony and North Rhine-Westphalia consolidate vendor relationships around microbiome monitoring partnerships rather than commodity spot purchasing.
Brazil
Export-oriented poultry processors in Paraná and Santa Catarina face stringent EU and Japanese residue standards driving documented eubiotic program adoption. ANVISA feed grade regulations align with importer documentation requirements for full supply chain traceability. Integrated operations in the southern broiler belt bundle technical service contracts with strain selection and on-farm diagnostic capabilities.
United States
Commercial farms with in-house nutritionists prioritize FDA Veterinary Feed Directive-compliant gut health formulations over empirical growth promotion claims. The directive's veterinary prescription requirements reshape procurement relationships toward diagnostic-backed dosing optimization. Midwestern swine operations and southeastern poultry clusters consolidate additive procurement under outcome-based technical service models.
India
BIS feed grade standards under development for probiotic stability and prebiotic purity position early entrants to shape specification frameworks. The country's central pharmaceutical regulator influences fermentation effluent compliance for manufacturing location decisions. Maharashtra and Gujarat host expanding compound feed production capacity serving domestic broiler integration networks.
China
MEE environmental compliance rules for fermentation effluent constrain organic acid and live culture manufacturing location decisions. The country's dual carbon goals pressure energy-intensive submerged fermentation operations toward efficiency upgrades. Yangtze River Delta feed millers adopt precision-delivery prebiotic platforms for antibiotic-free piglet diet protocols.
Animal Eubiotics Market Key Industry Players
Capability concentration sits with strain development specialists; scale advantage sits with diversified chemical and nutrition conglomerates. The vendor base organizes around three strategic archetypes: integrated agricultural supply chains controlling fermentation-to-farm verticals, precision-delivery platform developers, and fermentation-scale organic acid producers. Dominant competitive moves include backward integration into strain banking and diagnostic-backed technical service bundling displacing commodity premix spot sales.
Among integrated agricultural conglomerates, Cargill exemplifies the strain-to-service archetype with captive supply chain control. DSM-Firmenich occupies a position within the precision-delivery tier, anchoring European demand through formulation platforms. BASF represents the fermentation-scale archetype, leveraging submerged culture capacity across multiple animal species applications.
| Leading Market Players |
|---|
| Cargill |
| Alltech |
| dsm-firmenich |
| Novus International |
| Lallemand Animal Nutrition |
| BASF |
| Kemin Industries |
| Adisseo |
| Evonik Industries |
| Others |
Cost & Logistics Intelligence
Fermentation capacity utilization above 85 percent in China's Yangtze River Delta and India's Maharashtra corridor is compressing organic acid spot prices while forcing live culture suppliers toward long-term offtake structures with Brazilian and German integrators.
Pricing Analysis
Long-term offtake contracts dominate procurement between strain developers and integrated poultry processors, displacing spot mineral premix purchasing. Pricing stratifies across premium synbiotics with EFSA dossier backing, standard direct-fed microbials with documented CFU stability, and economy organic acid blends for basic antibiotic replacement. Cost compression in standard-tier formulations stems from molasses feedstock volatility and corn steep liquor price swings. Brazilian export-oriented processors exhibit highest price sensitivity due to margin pressure from EU residue compliance documentation, while German piglet integrators accept premium positioning for mode-of-action-specific claims.
Supply Chain Analysis
Contract manufacturing concentration resides with European fermentation specialists in Denmark and the Netherlands, plus Indian effluent-compliant facilities in Gujarat and Telangana. Raw material flows draw from Brazilian sugarcane molasses, Chinese corn processing byproducts, and European whey permeate streams. Single-source vulnerability concentrates in proprietary Lactobacillus and Bacillus strain collections held by North American and European culture banks. Distribution runs through technical service bundling that combines strain selection, diet reformulation, and on-farm microbiome monitoring rather than commodity spot sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment, where EFSA and FDA authorization timelines create 18-24 month barriers against novel strain commercialization.
For Market Incumbents: Build switching-cost moats by embedding diagnostic-backed dosing optimization into multi-year technical service contracts with Spain's piglet integration networks and Brazil's southern broiler belt. Backward integration into captive strain banking reduces single-source vulnerability from European culture collection suppliers. Capacity addition in effluent-compliant Indian manufacturing hedges against China's MEE environmental enforcement tightening. For New Entrants and Emerging Players: India's BIS feed grade standard development represents the most penetrable entry point, as early entrants can shape probiotic stability and prebiotic purity specifications before market maturation. Vietnamese shrimp aquaculture and Norwegian salmonid operations seeking antibiotic replacement protocols offer validated synbiotic white-space. Go-to-market leverage rests on partnering with established diagnostic platforms for microbiome monitoring rather than standalone strain supply. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision-delivery prebiotic platforms requiring microencapsulation R&D and spray-drying stabilization infrastructure. Long-term viability favors acquisition targets with captive strain development capabilities plus existing EFSA or FDA authorization dossiers. The signal to watch is authorization timeline compression for novel microbial strains, indicating regulatory pathway maturation that would erode entrenchment moats.| Strategic Initiative | Industry Significance |
|---|---|
| Strain Banking Acquisition | Captive microbial culture collections eliminate single-source dependency for Lactobacillus and Bacillus launches. |
| EFSA Dossier Front-Loading | Whole-genome sequencing and toxicological endpoint investment accelerates authorization timelines for gut health claims. |
| Microencapsulation Scale-Up | Lipid-matrix and alginate-shell production protects viability through 85°C pelleting temperatures in Danish feed mills. |
| Technical Service Bundling | Diagnostic-backed dosing optimization contracts displace spot premix purchasing in Brazilian integrated operations. |
| India BIS Standard Engagement | Early participation in probiotic stability specification development shapes barrier architecture before market maturation. |
Research Approach
A spread of perspectives from feed compounder procurement directors, fermentation plant managers, regulatory affairs specialists at strain developers, and veterinary nutritionists at integrated poultry operations converged on the working assumptions. Secondary validation drew from EFSA feed additive authorization databases, FDA Veterinary Feed Directive compliance filings, ANVISA feed grade registrations, and BIS standard development committee documentation. Bottom-up strain-level production estimates and top-down feed additive market sizing were triangulated against customs trade data for molasses and corn steep liquor flows.
Demand-supply balance modeling tracked antibiotic growth promoter substitution mandates against fermentation capacity expansion across the analysis window. Segmentation dimensions included product type tier, animal species physiology, regulatory claim category, and integration depth of end-user procurement. CAGRs were derived from installed capacity trajectories and documented feed conversion improvement elasticities in controlled broiler and piglet trials. Mode-of-action substantiation requirements and microbiome assay standardization gaps were incorporated as adoption friction inputs.
Stress conditions across EFSA authorization timeline extensions, molasses price volatility bands, and MEE effluent compliance enforcement were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding strain viability stabilization technology maturation and importer residue standard harmonization. Quarterly review of authorization dossier approval rates and fermentation feedstock price indices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Bio Rational Fungicides Market
Bio-Agriculture
Asia-Pacific Biofertilizers Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
GCC Biofertilizer Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
Europe Bioethanol Market
Bio-Agriculture
South America Biological Organic Fertilizers Market
Bio-Agriculture
Biofibre Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Bloodroot Market
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
Hydroponics Nutrients Market
Bio-Agriculture
Transgenic Animals Market
Bio-Agriculture
Indonesia Biopesticides Market