
 Brazil Biopesticides Market | 2026-2036
Brazil Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Biopesticides Market Intelligence
Project finance tied to sustainable agriculture certification programs is fragmenting competitive access across the Brazil biopesticides sector. Bayer AG leverages its biologicals pipeline to anchor distribution through major agricultural cooperatives in the Midwest. Koppert Biological Systems specializes in beneficial insect and microbial solutions that dominate protected-culture horticulture in São Paulo state. Marrone Bio Innovations positions its fermentation-derived products to compete in niche fruit and vegetable segments where residue limits drive substitution.
Biopesticides comprise living organisms, naturally occurring substances, and metabolites engineered for pest, disease, and weed management in crop protection systems. These agents function through modes including host-specific pathogenicity, antibiosis, induced systemic resistance, and competitive exclusion, with formulation stability typically requiring pH buffering and UV protectants to maintain viable cell counts or active metabolite integrity. Bioinsecticides lead volume demand in Brazil's soybean and corn complexes where Helicoverpa armigera pressure drives Bacillus thuringiensis adoption, while nematicides represent the fastest-expanding category as Meloidogyne resistance to conventional fumigants accelerates biological seed treatment uptake. Fungicides based on Trichoderma species sustain mature positions in coffee and citrus orchards where perennial cropping demands long-term soil health management rather than seasonal intervention.
ANVISA governs product registration and residue tolerance establishment for biological crop protection agents entering Brazilian commerce. The Ministry of Agriculture's MAPA certification requirements for organic and low-residue production systems directly expand addressable demand for registered biopesticide formulations among export-oriented growers. Stakeholders must monitor pending revisions to Brazil's agrochemical law that could reclassify certain microbial consortia as genetically modified organisms, altering registration pathways and compliance costs for suppliers.
Market Dynamics
ANVISA's streamlined microbial registration pathway is compressing time-to-market for biological crop protection agents, while soybean cooperatives in Mato Grosso and Paraná reallocate procurement budgets toward integrated pest management programs that embed Bacillus thuringiensis and Trichoderma formulations as core inputs.
Growth Catalysts
- Regulatory acceleration:ANVISA's revised agrochemical framework reduces microbial product registration timelines, enabling faster commercialization of fermentation-derived biocontrol agents for row-crop applications.
- Resistance-driven substitution:Meloidogyne nematode populations across the Cerrado frontier exhibit spreading resistance to conventional fumigants, forcing growers toward biological seed treatments containing Purpureocillium lilacinum.
- Export certification alignment:MAPA's organic and low-residue production standards for export-oriented growers mandate documented biological input usage, creating compliance-pull demand for registered bioinsecticides and biofungicides.
Market Restraints
- Formulation stability costs:pH buffering and UV protectant requirements for maintaining viable cell counts in tropical storage conditions elevate production costs relative to synthetic chemistry.
- Technical performance variability:Microbial agent efficacy depends on soil temperature, moisture, and indigenous microbiome competition, creating inconsistent field results that slow grower confidence building.
- Distribution infrastructure gaps:Cold-chain requirements for preserving live-cell biopesticide viability remain underdeveloped in remote Cerrado frontier municipalities, limiting addressable geography.
Strategic Opportunities
- Consortia registration pathway:Pending ANVISA clarification on microbial consortia classification could unlock multi-strain product formats with synergistic mode-of-action claims.
- Perennial crop expansion:Coffee and citrus orchards in Minas Gerais and São Paulo states present underpenetrated demand for Trichoderma-based soil health management programs.
- Biological-synthetic integration:Co-formulation technologies that combine microbial agents with reduced-rate synthetics offer residue-compliant solutions for high-value fruit and vegetable export segments.
Industry Challenges
- Technical field support scarcity:Agronomists trained in biological agent application timing, tank-mix compatibility, and microbiome interaction management remain concentrated in São Paulo and Paraná cooperatives.
- Certification timeline compression:MAPA organic certification audits and ANVISA residue tolerance establishment processes create multi-season gaps between product submission and commercial deployment.
- Legacy synthetic inventory integration:Agricultural cooperatives managing existing synthetic agrochemical stocks face working capital friction when accelerating biological input transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Biopesticides Market |
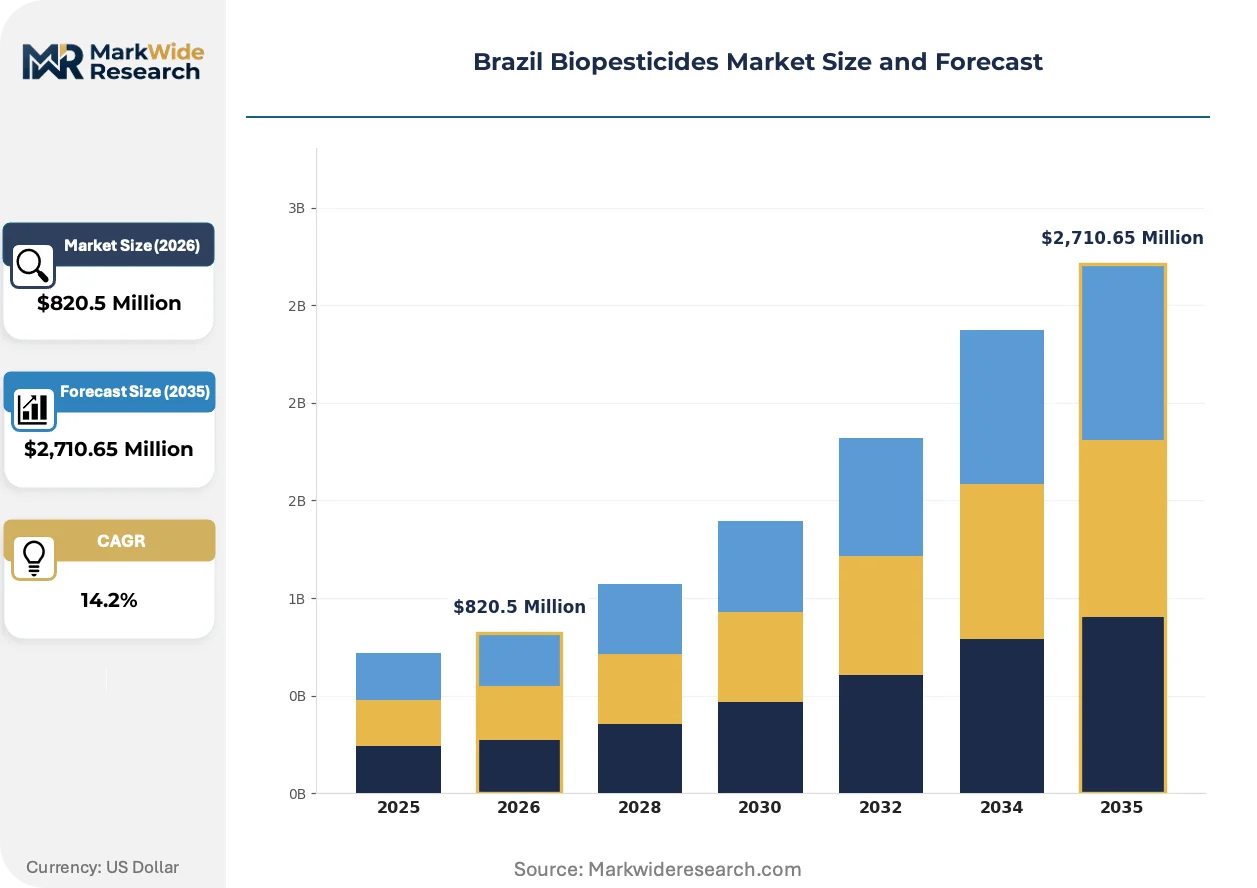
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $2,710.65 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nematicides, Fungicides, Bioinsecticides, Herbicides Application: Agriculture, Horticulture, Forestry, Turf Management Distribution Channel: Online Retail, Specialty Stores, Conventional Retail, Direct Sales End User: Farmers, Agricultural Cooperatives, Distributors, Retailers |
| Companies Covered | Bayer AG, Andermatt Biocontrol AG, FMC Corporation, UPL, Coromandel International, Corteva Agriscience, Koppert Biological Systems, Marrone Bio Innovations, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Biopesticides Market Strategic Shifts & Innovations
Biological crop protection is transitioning from niche organic applications to mainstream integrated pest management architectures, with formulation science and regulatory alignment converging to enable performance parity claims in row-crop segments.
RNA interference-based bioinsecticides targeting Helicoverpa armigera through species-specific gene silencing are rendering obsolete broad-spectrum synthetic pyrethroid applications in Mato Grosso soybean fields. Mid-scale growers in the Cerrado are piloting these precision biocontrol agents during the 2024-2025 growing cycle. The technology compresses non-target organism impact assessments and accelerates residue-free certification timelines for export shipments.
ANVISA's pending reclassification of certain microbial consortia as genetically modified organisms is forcing reformulation strategies among suppliers with multi-strain pipeline candidates. The regulatory uncertainty is diverting R&D investment toward single-specium products with established non-GMO status. Seed treatment applicators in Paraná and Rio Grande do Sul are prioritizing Bacillus firmus-based nematicides with unambiguous regulatory pathways.
Agricultural cooperatives are consolidating procurement decisions at the central level, displacing individual grower spot purchasing through distributor networks. This concentration shifts bargaining power toward volume-scale biological suppliers capable of consistent batch quality and technical service deployment. The Midwest region exhibits the most pronounced cooperative procurement centralization, with Cotriguaçu and Amaggi anchoring multi-year biological supply agreements.
Brazil Biopesticides Market Segmentation
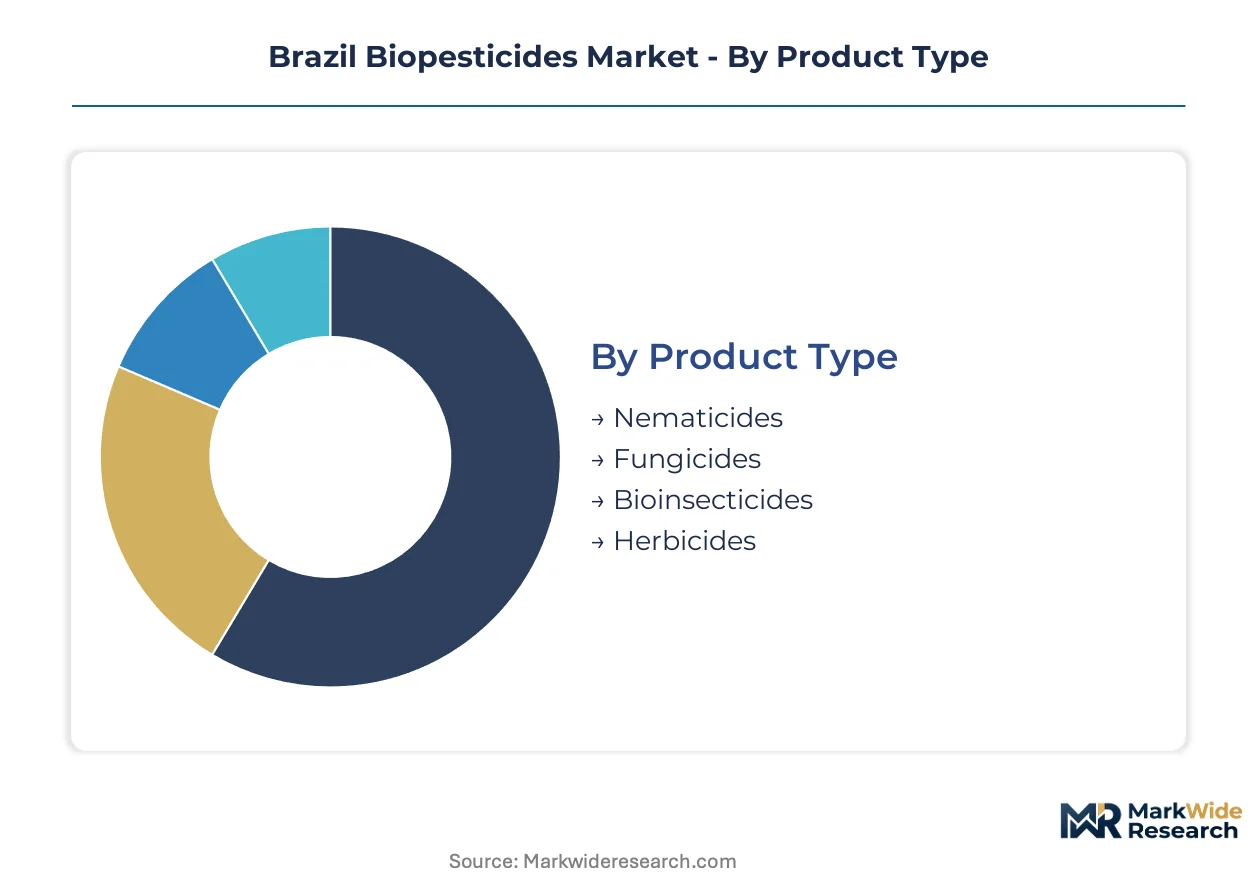
Biopesticide segmentation in Brazil reflects divergent technical requirements across cropping systems and procurement consolidation among agricultural cooperatives. Product type distinctions determine formulation complexity and regulatory pathway, while distribution channel evolution shapes competitive access in remote Cerrado municipalities.
Product Type:
Microbial agent selection varies by pest biology and soil microbiome compatibility across Brazil's agricultural zones.
- Nematicides:Purpureocillium lilacinum and Bacillus firmus formulations target Meloidogyne infestations in soybean and corn seed treatments. Resistance to conventional fumigants across Mato Grosso and Paraná is accelerating biological nematicide uptake among cooperative procurement programs.
- Bioinsecticides:Bacillus thuringiensis products dominate volume demand for Helicoverpa armigera management in soybean and corn complexes. RNA interference-based formulations are piloting in Mato Grosso during current growing cycles, compressing residue-free certification timelines for export shipments.
- Fungicides:Trichoderma-based soil health programs sustain mature positions in perennial cropping systems.
- Herbicides:Microbial and botanical formulations occupy niche positions where synthetic resistance limits conventional chemistry efficacy.
Established volume favors bioinsecticides; emerging adoption favors nematicides.
Application:
Cropping system intensity determines biological input specification and technical service requirements.
- Agriculture:Row-crop soybean and corn production in the Cerrado frontier drives bulk procurement of microbial seed treatments and foliar applications. ANVISA registration alignment with export certification requirements is concentrating demand among MAPA-compliant growers in Mato Grosso.
- Horticulture:Protected-culture operations in São Paulo state require beneficial insect and microbial solutions with precise application timing. Koppert Biological Systems anchors distribution through technical service partnerships with greenhouse operators.
- Forestry:Eucalyptus and pine plantations deploy biological agents for pest suppression in extended rotation systems.
- Turf Management:Golf course and sports field maintenance represents premium pricing segments with residue-sensitive end-users.
Volume concentration sits with agriculture; margin premium concentrates in horticulture.
Distribution Channel:
Cold-chain viability and technical support density shape channel selection for live-cell formulations.
- Direct Sales:Agricultural cooperatives in the Midwest are consolidating procurement decisions at central levels, displacing individual grower spot purchasing. Multi-year supply agreements with volume-scale biological suppliers anchor biological input transitions.
- Specialty Stores:Regional distributors with fermentation-derived product portfolios serve mid-scale growers in Paraná and Rio Grande do Sul.
- Conventional Retail:Broad-line agrochemical distributors carry synthetic-biological co-formulations for residue-compliant fruit and vegetable segments.
- Online Retail:E-commerce penetration remains limited by live-cell viability requirements and technical consultation needs.
Procurement centralization favors direct sales; technical service access favors specialty stores.
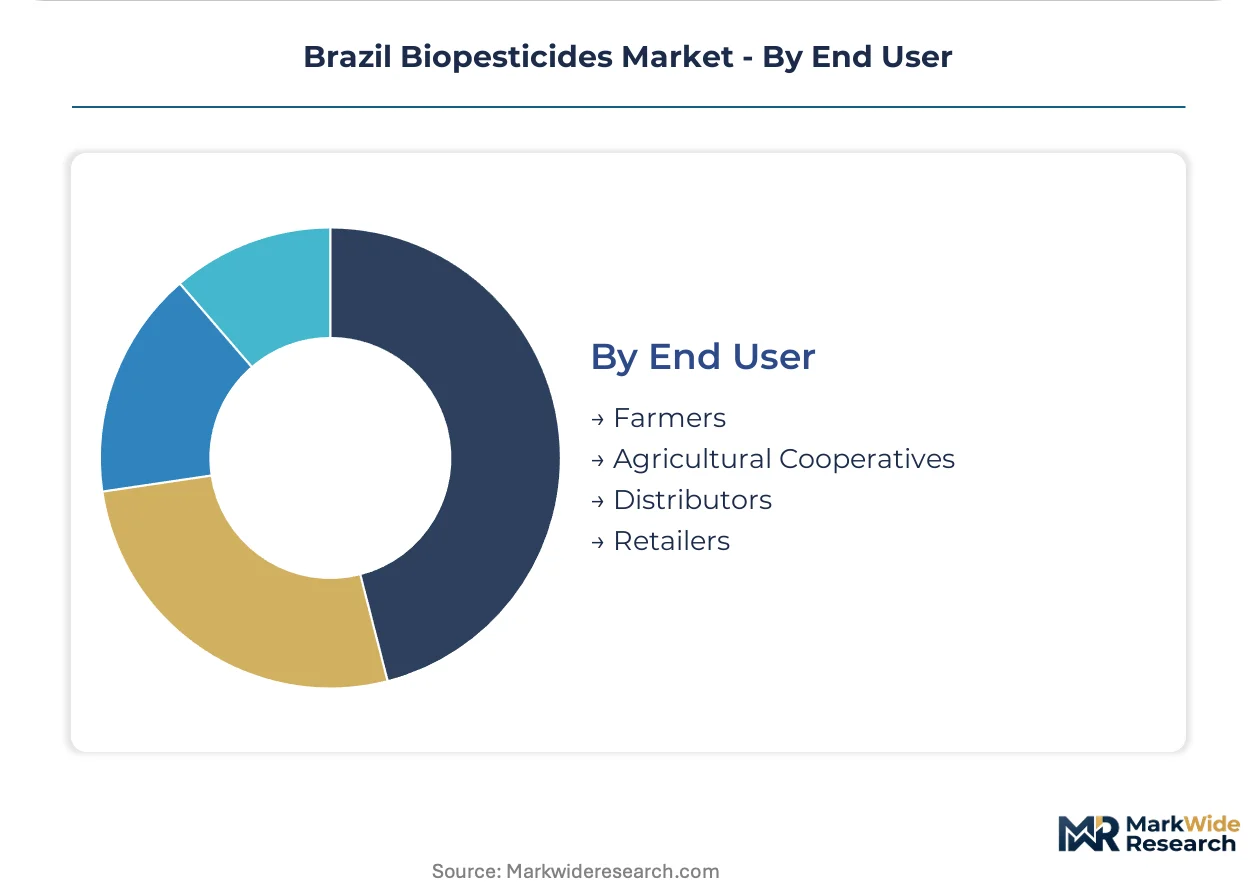
End User:
Scale and certification status differentiate biological input adoption patterns.
- Agricultural Cooperatives:Cotriguaçu and Amaggi anchor multi-year biological supply agreements with consistent batch quality requirements. Centralized procurement shifts bargaining power toward suppliers capable of technical service deployment across remote Cerrado municipalities.
- Farmers:Individual growers in São Paulo and Paraná cooperatives retain spot purchasing for specialty applications requiring tailored advice.
- Distributors:Inventory management of live-cell products with limited shelf life creates working capital constraints in tropical storage conditions.
- Retailers:Point-of-sale technical consultation scarcity limits biological product recommendations in conventional retail channels.
Volume scale favors agricultural cooperatives; specification complexity favors direct farmer relationships.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's biopesticides trade balance tilts toward import substitution as domestic fermentation capacity expands. Export-oriented growers in Mato Grosso and Paraná drive demand alignment with MAPA certification standards for soy and corn shipments.
Mato Grosso
Soybean cooperatives in Mato Grosso reallocate procurement budgets toward Bacillus thuringiensis seed treatments for Helicoverpa armigera management. ANVISA's streamlined microbial registration enables faster commercialization of fermentation-derived biocontrol agents. The Sorriso-Sinop corridor anchors multi-year supply agreements between Cotriguaçu and volume-scale biological suppliers.
Paraná
Corn and soybean producers across Paraná accelerate biological nematicide adoption as Meloidogyne populations exhibit spreading resistance to conventional fumigants. MAPA's organic certification audits create compliance-pull demand for documented biopesticide usage. The Cascavel-Toledo agricultural cluster concentrates technical service partnerships for microbial agent application timing.
São Paulo
Protected-culture horticulture operations in São Paulo state require beneficial insect and microbial solutions with precise application protocols. ANVISA residue tolerance establishment processes govern product registration for export-oriented vegetable growers. The Campinas-Piracicaba greenhouse belt dominates domestic tomato and pepper production using integrated pest management architectures.
Minas Gerais
Coffee and citrus orchards in Minas Gerais present underpenetrated demand for Trichoderma-based soil health management programs. The state's perennial cropping systems require long-term microbiome stewardship rather than seasonal synthetic intervention. The Triângulo Mineiro region anchors fermentation facility investments serving the Cerrado frontier.
Rio Grande do Sul
Soybean and rice producers in Rio Grande do Sul pilot RNA interference-based bioinsecticides during current growing cycles. Seed treatment applicators prioritize Bacillus firmus-based nematicides with unambiguous regulatory pathways under ANVISA's revised framework. The Passo Fundo agricultural hub concentrates distributor networks for biological input transitions.
Brazil Biopesticides Market Key Industry Players
On the supply side, the industry is consolidating around agricultural cooperative procurement centralization and fermentation capacity scale. Three strategic archetypes dominate: multinational agrochemical conglomerates with biologicals pipelines, specialized microbial fermentation houses, and integrated pest management service providers. Competitive moves concentrate on multi-year supply agreements with Midwest cooperatives and cold-chain infrastructure investments for live-cell viability preservation.
Within the multinational tier, Bayer AG anchors distribution through major agricultural cooperatives, while Koppert Biological Systems exemplifies the specialized beneficial insect and microbial solutions archetype. Marrone Bio Innovations occupies a position representing fermentation-derived product competitors in niche fruit and vegetable segments. These three companies collectively illustrate the competitive segmentation between volume-scale row-crop suppliers and margin-focused horticulture specialists.
| Leading Market Players |
|---|
| Bayer AG |
| Andermatt Biocontrol AG |
| FMC Corporation |
| UPL |
| Coromandel International |
| Corteva Agriscience |
| Koppert Biological Systems |
| Marrone Bio Innovations |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Undercapacity in domestic fermentation facilities across the Triângulo Mineiro region is forcing biological suppliers to import active microbial cultures, compressing margins and elevating working capital requirements for cold-chain preservation. Agricultural cooperatives exploit this supply bottleneck to extract volume discounts and technical service commitments from multinational biologicals providers.
Pricing Analysis
Agricultural cooperatives anchor contract-based long-term offtake structures that stratify across premium certified-organic, standard MAPA-compliant, and economy conventional-transition tiers. Price differentiation centers on ANVISA registration tier and cold-chain reliability guarantees, with premium tiers commanding substantial markups for documented residue-free certification. Cost compression in the economy tier is intensifying as Brazilian fermentation capacity lags demand growth. Smallholder farmers in remote Cerrado municipalities exhibit highest price sensitivity, while export-oriented soybean cooperatives prioritize certification compliance over unit cost.
Supply Chain Analysis
Contract manufacturing for microbial fermentation concentrates among specialized biological production houses in the Netherlands, Israel, and select Brazilian facilities near Ribeirão Preto. Active ingredient supply draws from proprietary strain libraries, molasses-based fermentation media, and UV-stabilized formulation chemistries. Single-source vulnerability runs through ANVISA-approved strain deposits held at international culture collections. Distribution runs through cooperative procurement centralization displacing traditional distributor networks, with live-cell viability requirements mandating refrigerated logistics partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical agronomist scarcity across Mato Grosso and Paraná cooperatives creates a persistent capability gap that determines competitive outcomes more than product differentiation alone. Suppliers who embed field advisory services into procurement contracts capture disproportionate share of biological input transitions.
For Market Incumbents: Entrench cooperative relationships through multi-year technical service agreements that lock in application-timing expertise and tank-mix compatibility databases. Backward integration into domestic fermentation capacity near the Triângulo Mineiro region reduces import dependency and shortens registration timelines under ANVISA's revised framework. Seed treatment applicator partnerships in Paraná represent a defensible channel control point against emerging microbial suppliers. For New Entrants and Emerging Players: Mid-scale coffee and citrus orchards in Minas Gerais represent the most penetrable entry point given underdeveloped Trichoderma-based soil health programs and limited incumbent technical service density. RNA interference bioinsecticide pilots in Rio Grande do Sul soybean fields offer a technology wedge for precision biocontrol positioning against established Bacillus thuringiensis suppliers. Go-to-market execution should prioritize distributor technical training partnerships over direct cooperative confrontation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated pest management service providers with annual program contracts rather than transactional product suppliers. Long-term viability across the analysis window favors acquisition targets possessing proprietary strain libraries with established ANVISA registration pathways and embedded cooperative relationships. The signal to watch is ANVISA's pending microbial consortia reclassification ruling, which would abruptly revalue multi-strain pipeline candidates.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Fermentation Capacity Expansion | Triângulo Mineiro facility investments reduce import dependency and accelerate ANVISA registration timelines. |
| Cooperative Technical Service Partnership | Cotriguaçu and Amaggi multi-year agreements embed application expertise and lock out competitor access. |
| RNA Interference Pipeline Advancement | Species-specific gene silencing technology targets Helicoverpa armigera resistance management in Mato Grosso soybeans. |
| Cold-Chain Infrastructure Investment | Refrigerated logistics partnerships preserve live-cell viability across remote Cerrado frontier municipalities. |
| MAPA Certification Alignment Program | Documented biological input usage pathways satisfy organic and low-residue export standards for EU and Asian markets. |
Research Approach
A standing panel of biological R&D directors, agricultural cooperative procurement managers, ANVISA regulatory affairs specialists, and seed treatment applicators provided ongoing calibration across the study period. Primary field engagement combined structured interviews with secondary validation through MAPA certification databases, ANVISA registration filings, customs import records for active microbial cultures, and cooperative procurement disclosure documents. Bottom-up volume estimates from individual biological product registrations were triangulated against top-down agricultural input expenditure surveys.
Scenario bracketing around regulatory acceleration, nematode resistance spread, and cooperative consolidation rates anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, application system intensity, distribution channel structure, and end-user scale tier. CAGRs were derived from trend extrapolation adjusted for adoption curve inflection points, with specific inputs including ANVISA registration pipeline velocity and MAPA certification audit completion rates.
Stress conditions across ANVISA regulatory reclassification timing, Meloidogyne resistance evolution rates, and cooperative procurement centralization pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding microbial formulation stability improvements and cold-chain infrastructure expansion. Quarterly review of ANVISA registration approval velocity and cooperative technical service hiring indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
North America Biopesticides Market
Bio-Agriculture
India Feed Probiotics Market
Bio-Agriculture
United States Bio-Fungicide Market
Bio-Agriculture
Global Citrus Bioflavonoids Market
Bio-Agriculture
Bionematicides Market
Bio-Agriculture
Bio-Based Levulinic Acid Market
Bio-Agriculture
Asia-Pacific Bio-Ethanol Market
Bio-Agriculture
Africa Biological Organic Fertilizers Market
Bio-Agriculture
Vietnam Biopesticides Market
Bio-Agriculture
Brazil Biostimulants Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Germany Biostimulants and Biopesticides Market
Bio-Agriculture
United States Agricultural Biologicals Market
Bio-Agriculture
Bioethanol Yeast Market
Bio-Agriculture
Argentina Biopesticides Market
Bio-Agriculture
China Biocontrol Agents Market