
 India Feed Probiotics Market | 2026-2036
India Feed Probiotics Market Size, Share, and Industry Trends Forecast 2026-2036
India Feed Probiotics Market Outlook
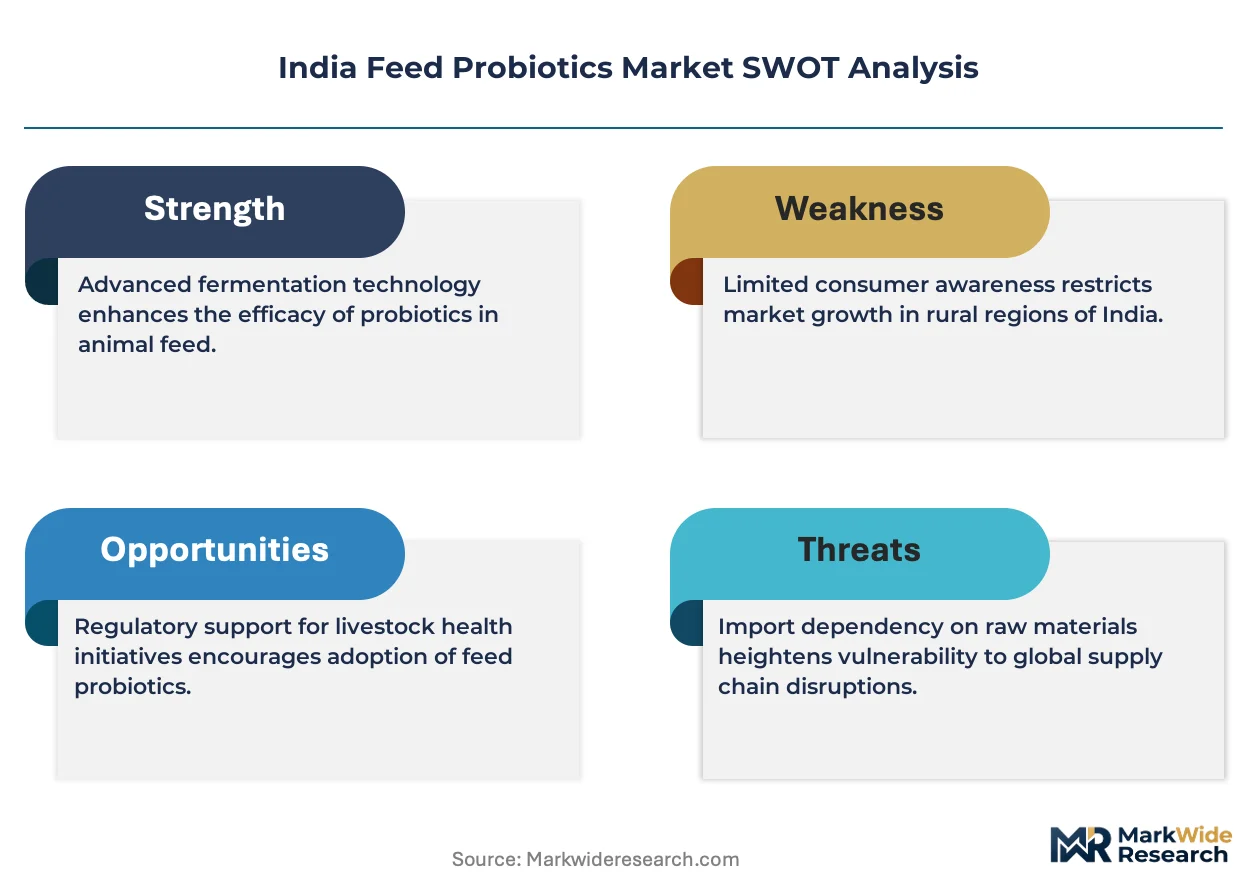
Gujarat is rewriting capacity dynamics in India's feed probiotics sector as fermentation infrastructure expands around the Dahej and Vapi industrial belts. DSM-Firmenich leverages its integrated strain development platform to supply poultry and ruminant applications from regional blending facilities. Adisseo anchors the western market through backward integration into key raw material streams. Novonesis competes on enzyme-probiotic synergy formulations tailored to tropical heat stress conditions.
Feed probiotics comprise live microbial cultures, primarily lactic acid bacteria and Saccharomyces cerevisiae strains, administered via feed to colonize the gastrointestinal tract and modulate nutrient absorption, pathogen exclusion, and immune response in production animals. Commercial formulations typically deliver colony-forming units between 10^8 and 10^11 per gram, with stability enhanced through spray-drying and microencapsulation processes that protect viability during pelleting temperatures up to 85°C. The bacteria segment dominates value capture due to higher unit pricing for multi-strain synbiotic blends, while aquaculture applications represent the fastest-expanding animal type category as shrimp and freshwater fish producers seek alternatives to antibiotic growth promoters in coastal Andhra Pradesh and Tamil Nadu. Powder formulations occupy the largest volume share given compatibility with existing feed mill infrastructure, though liquid probiotics are gaining traction in integrated poultry operations with automated drinking water systems.
The FSSAI feed additive regulations and BIS IS 14818 standards govern microbial count specifications and contaminant limits for probiotic products marketed in India, while the CDSCO veterinary biologicals framework intersects with certain live culture claims. The PLI scheme for animal husbandry inputs incentivizes domestic manufacturing of fermentation-derived feed additives, reducing import dependence on Chinese and European active ingredient sources. Stakeholders must monitor evolving strain registration requirements and state-level antibiotic reduction mandates that will determine which probiotic suppliers secure preferred supplier status with India's consolidating feed mill sector.
Market Dynamics
The PLI scheme for animal husbandry inputs is compressing import dependence by channeling capital toward domestic fermentation capacity, while FSSAI and BIS standards tighten quality benchmarks that filter marginal suppliers from India's consolidating feed mill sector.
Growth Catalysts
- Antibiotic reduction mandates:State-level bans on antibiotic growth promoters in poultry production across Andhra Pradesh and Haryana are accelerating probiotic inclusion in broiler and layer diets as veterinarians seek viable alternatives.
- Fermentation infrastructure expansion:Industrial clusters around Dahej and Vapi in Gujarat are adding spray-drying and microencapsulation capacity that protects microbial viability through feed pelleting temperatures.
- Aquaculture regulatory pivot:Coastal shrimp and freshwater fish producers in Tamil Nadu face mounting pressure to eliminate antibiotic residues from export consignments, driving live culture adoption in feed formulations.
Market Restraints
- Active ingredient import concentration:Domestic blenders remain dependent on Chinese and European sources for concentrated bacterial and yeast strains, exposing margins to currency volatility and shipping disruptions.
- Strain registration friction:CDSCO veterinary biologicals framework creates overlapping jurisdiction with FSSAI feed additive rules, generating compliance ambiguity for multi-strain synbiotic products.
- Thermal stability limitations:Standard lactic acid bacteria formulations degrade above 85°C pelleting temperatures, restricting application in high-temperature extruded feeds without costly microencapsulation upgrades.
Strategic Opportunities
- Automated drinking water systems:Integrated poultry operations in Haryana and Punjab are retrofitting houses with precision dosing equipment that enables liquid probiotic delivery alongside traditional feed-based administration.
- Dairy cooperative verticals:Large federations in Maharashtra and Gujarat with captive feed mills represent underpenetrated accounts for ruminant-specific Saccharomyces cerevisiae formulations targeting rumen pH modulation.
- Enzyme-probiotic convergence:Heat-stable cellulase and phytase combinations with live cultures are opening formulation partnerships between enzyme houses and probiotic specialists for tropical climate applications.
Industry Challenges
- Microbiologist talent scarcity:Strain characterization, viability testing, and quality control functions require specialized personnel that fermentation facilities in secondary cities struggle to recruit and retain.
- Legacy feed mill integration:Older pelleting lines lack temperature control precision needed for unprotected probiotic inclusion, forcing costly equipment retrofits or limited product compatibility.
- Batch-to-batch viability variance:Spray-drying protocol inconsistencies across third-party toll manufacturers create quality assurance headaches for brand owners serving specification-sensitive integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Feed Probiotics Market |
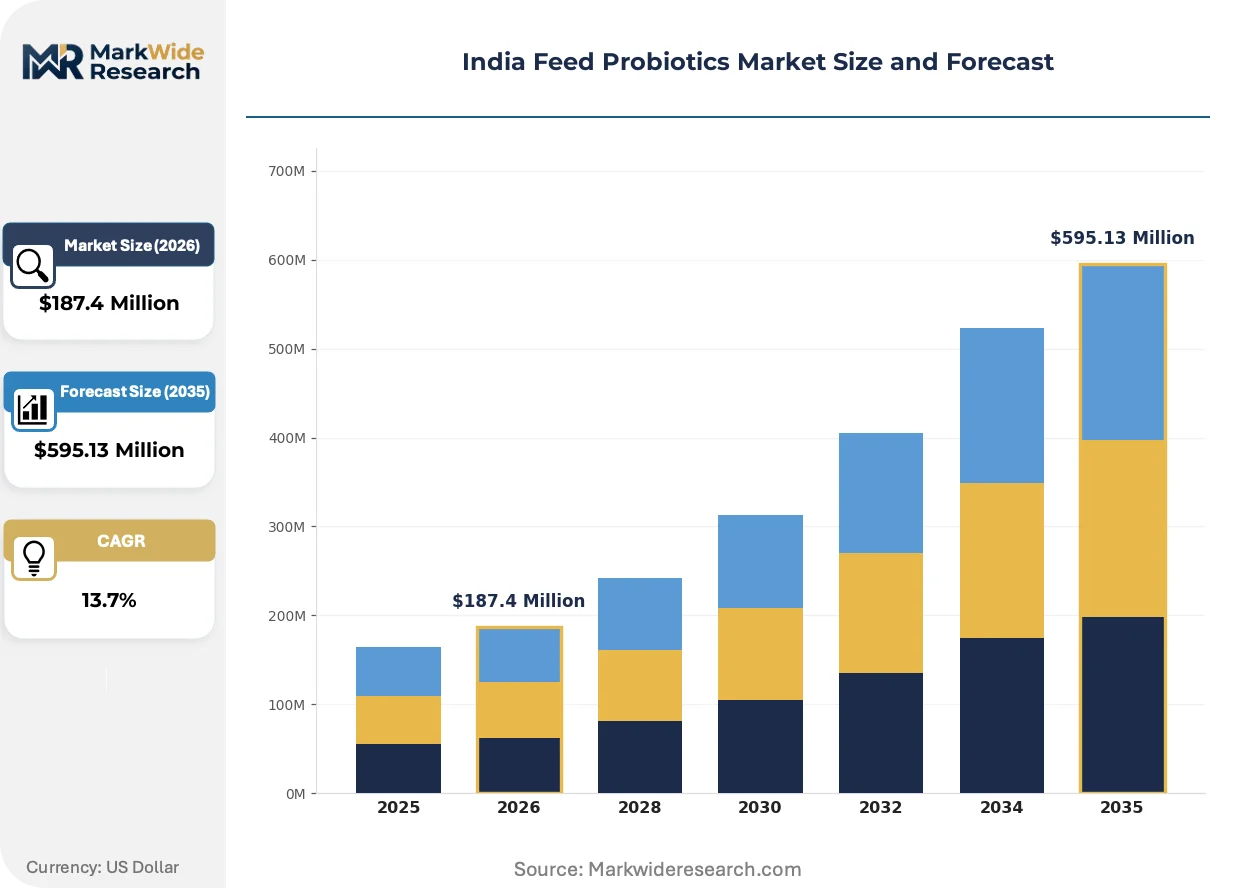
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $595.13 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bacteria, Yeast, Enzymes, Microbial Culture Animal Type: Poultry, Swine, Ruminants, Aquaculture Formulation: Powder, Liquid, Granular, Pelleted Distribution Channel: Online, Offline, Direct Sales, Distributors |
| Companies Covered | DSM-Firmenich, Adisseo, Novonesis, Evonik Industries AG, Kerry Group plc, Chr. Hansen, Lallemand Animal Nutrition, Unique Biotech Ltd., Kemin Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Feed Probiotics Market Strategic Shifts
Formulation science and delivery mechanisms are evolving rapidly as thermal protection technologies mature and regulatory pressure on antibiotic alternatives intensifies across Indian livestock production systems.
Microencapsulation technology is migrating from premium multi-strain blends toward mid-tier single-species products as spray-drying equipment costs decline and toll manufacturing capacity expands in Gujarat. Regional feed mills serving cooperative dairies in Maharashtra are adopting these protected formats to differentiate commodity rations without full extrusion line replacement. The shift is compressing price premiums between standard and thermally stable formulations while raising baseline efficacy expectations among procurement officers.
FSSAI feed additive regulations are tightening microbial count specifications and contaminant limits for probiotic products, forcing domestic blenders to invest in third-party laboratory certification and strain traceability systems. The industrial consequence is a bifurcation between suppliers with captive quality infrastructure and those dependent on external testing. Poultry integrators in Andhra Pradesh are responding by consolidating preferred supplier lists around firms with demonstrated BIS IS 14818 compliance histories.
Large dairy cooperatives are consolidating procurement authority from individual village societies to central feed manufacturing units in Ahmedabad, Pune, and Mumbai, compressing the supplier base accessible to probiotic marketers. This concentration is displacing fragmented distributor networks with direct technical sales relationships where formulation scientists negotiate directly with nutritionists. The pattern is most visible in western Maharashtra, where cooperative feed mills now specify colony-forming unit guarantees and stability documentation that smaller regional blenders cannot provide.
India Feed Probiotics Market Segmentation
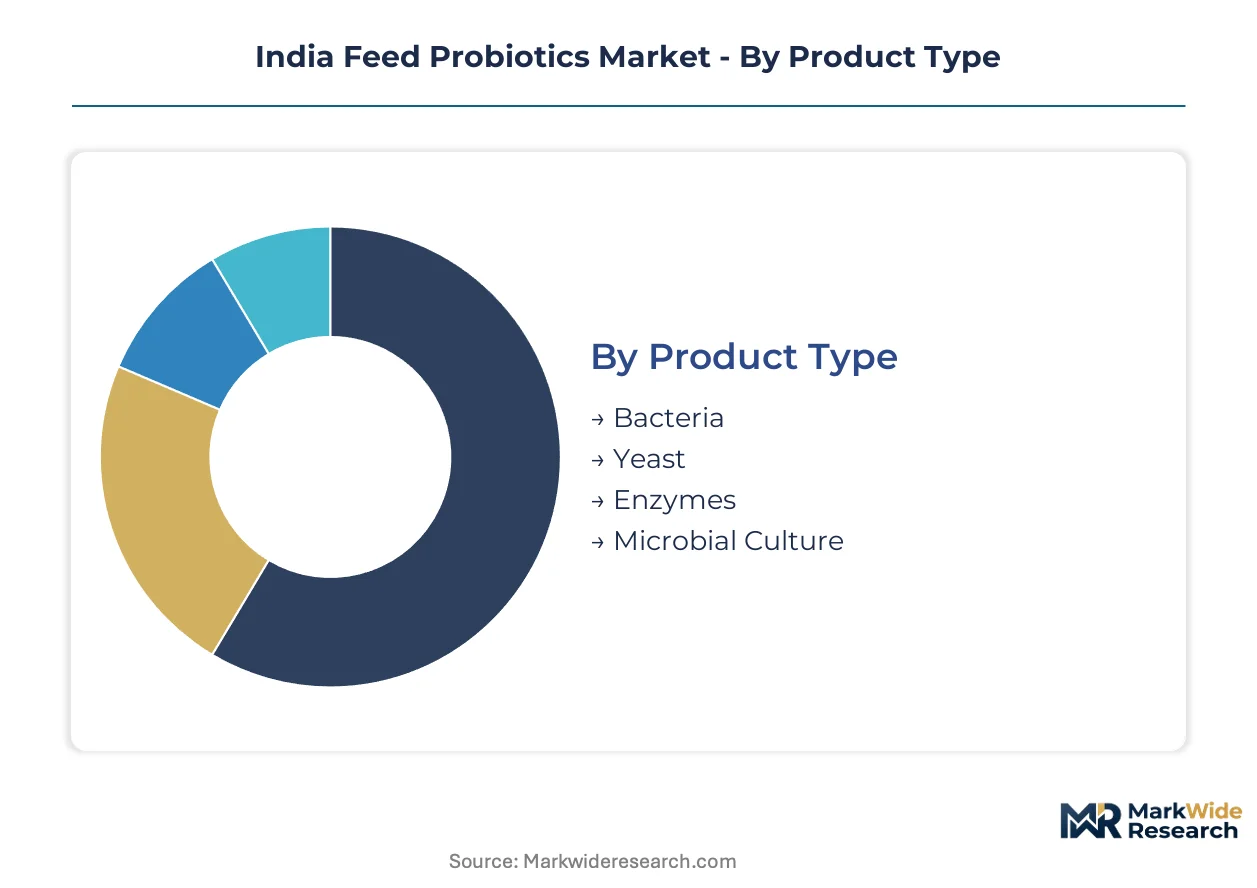
Segmentation in India's feed probiotics market reveals distinct procurement rhythms across product categories. Cycle times vary from quarterly feed formulation adjustments to annual strain registration renewals, creating differentiated commercial windows for suppliers.
Product Type:
Bacteria formulations turn over fastest as poultry integrators rotate strains to maintain efficacy, while enzymes move slowest due to longer stability testing protocols.
- Bacteria:Multi-strain blends of lactic acid bacteria and Bacillus species dominate commercial formulations, typically delivering 10^8 to 10^11 colony-forming units per gram. Andhra Pradesh and Haryana poultry integrators drive demand as they phase out antibiotic growth promoters under state-level mandates. Thermal protection through microencapsulation determines price tier and pelleting compatibility.
- Yeast:Saccharomyces cerevisiae preparations target rumen pH modulation in dairy applications, with western Maharashtra cooperatives specifying viability guarantees through 90-day storage. Strain selection focuses on osmotolerance for tropical storage conditions.
- Enzymes:Cellulase and phytase combinations require extended stability validation before feed mill adoption, slowing procurement cycles to 18-24 months.
- Microbial Culture:Single-species concentrates for on-farm fermentation systems serve smallholder dairy networks in Gujarat with limited cold chain access.
Bacteria anchors the volume base while microbial culture gains share at the steepest rate as decentralized production models spread.
Animal Type:
Cost tier stratification separates commodity poultry applications from premium ruminant formulations requiring specialized strain development.
- Poultry:Broiler and layer operations in Andhra Pradesh and Haryana constitute the largest addressable base, with integrators specifying thermally stable formulations compatible with 85°C pelleting. FSSAI antibiotic residue monitoring accelerates probiotic substitution in export-oriented supply chains.
- Ruminants:Large dairy cooperatives in Maharashtra and Gujarat command premium pricing for Saccharomyces cerevisiae strains with documented rumen pH modulation efficacy. Captive feed mills at cooperative federations consolidate procurement authority from village societies.
- Swine:Northeastern commercial farms in Assam and Punjab represent emerging demand as organized pork production expands beyond backyard systems.
- Aquaculture:Shrimp producers in Tamil Nadu and Andhra Pradesh face EU and US export residue standards, driving live culture adoption faster than any other animal category.
Poultry anchors the volume base while aquaculture climbs the fastest as export compliance pressures intensify.
Formulation:
Supply concentration in Gujarat's spray-drying corridor favors powder formats, while liquid investments cluster around automated poultry houses in Haryana.
- Powder:Spray-dried and microencapsulated formats compatible with existing feed mill infrastructure across western India. Dahej and Vapi industrial belts add capacity that protects viability through standard pelleting temperatures without extrusion line replacement.
- Liquid:Precision dosing systems in integrated Haryana and Punjab poultry operations enable drinking water delivery alongside feed-based administration. Higher per-dose cost limits penetration to automated houses.
- Granular:Intermediate format for regional feed mills lacking precise temperature control on legacy pelleting lines.
- Pelleted:Pre-extruded probiotic feeds for smallholder dairy networks with minimal on-farm mixing equipment.
Powder anchors the volume base while liquid gains share at the steepest rate as automation investments spread.
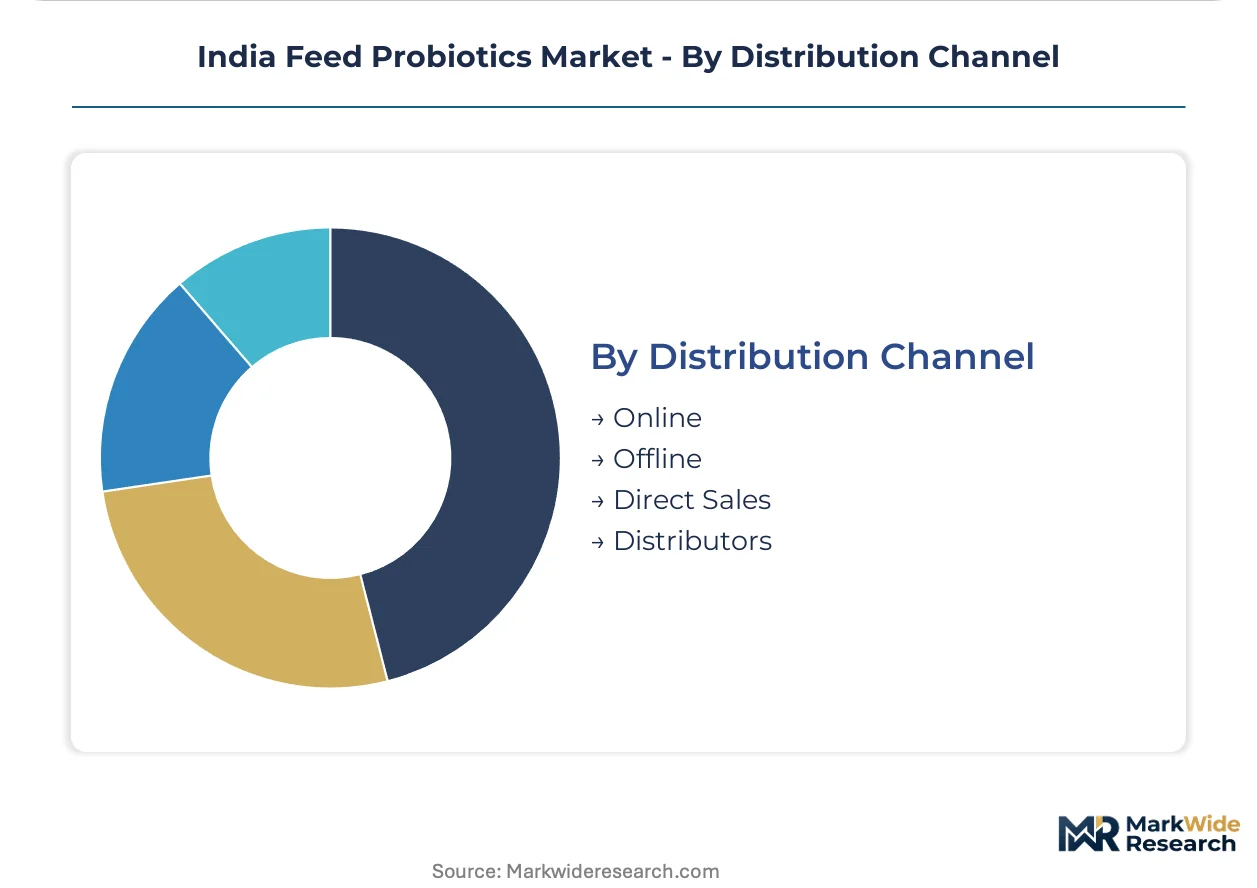
Distribution Channel:
Customer type fragmentation distinguishes direct technical sales to cooperative federations from distributor networks serving fragmented poultry farms.
- Direct Sales:Technical sales teams negotiate directly with nutritionists at large dairy cooperatives and poultry integrators, displacing traditional distributor relationships. Formulation scientists provide strain-specific documentation for BIS IS 14818 compliance.
- Distributors:Regional blenders and veterinary supply networks serve fragmented broiler farms in Tamil Nadu and backyard dairy operations in secondary cities. Margin compression from multi-tier markups limits brand investment capacity.
- Online:Emerging channel for probiotic concentrates targeting small-scale aquaculture operations in coastal Karnataka with limited access to veterinary distribution.
- Offline:Traditional feed dealer networks persist in rural Maharashtra where cooperative penetration remains incomplete.
Direct sales anchors the volume base while online gains share at the steepest rate as digital procurement platforms penetrate tier-2 cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fermentation capacity clusters in Gujarat's industrial corridor, with spray-drying infrastructure expanding around Dahej and Vapi. Western Maharashtra and coastal Andhra Pradesh concentrate demand from dairy cooperatives and poultry integrators respectively.
Gujarat
Dahej and Vapi industrial belts host expanding spray-drying and microencapsulation facilities that protect microbial viability through standard pelleting temperatures. The PLI scheme for animal husbandry inputs channels investment toward domestic fermentation capacity, reducing import dependence on concentrated bacterial strains. Large dairy cooperatives in Ahmedabad consolidate procurement authority from village societies, compressing supplier access for probiotic marketers.
Maharashtra
Cooperative feed mills in Pune and Mumbai specify colony-forming unit guarantees and stability documentation for Saccharomyces cerevisiae formulations targeting rumen pH modulation. FSSAI feed additive regulations tighten microbial count specifications, forcing domestic blenders to invest in third-party laboratory certification. Western Maharashtra dairy federations displace fragmented distributor networks with direct technical sales relationships.
Andhra Pradesh
Poultry integrators in this coastal state accelerate probiotic inclusion in broiler and layer diets under state-level bans on antibiotic growth promoters. FSSAI antibiotic residue monitoring intensifies substitution pressure in export-oriented supply chains. Shrimp producers face mounting EU and US export residue standards, driving live culture adoption faster than any other animal category in this region.
Haryana
Integrated poultry operations retrofit houses with precision dosing equipment that enables liquid probiotic delivery alongside traditional feed-based administration. State-level antibiotic reduction mandates accelerate veterinary adoption of viable alternatives to growth promoters. Automated drinking water systems cluster around large-scale layer and broiler facilities in this northern state.
Tamil Nadu
Coastal shrimp and freshwater fish producers eliminate antibiotic residues from export consignments under tightening international standards. CDSCO veterinary biologicals framework creates overlapping jurisdiction with FSSAI feed additive rules, generating compliance ambiguity for multi-strain synbiotic products. Aquaculture applications represent the fastest-expanding animal type category as producers seek alternatives to antibiotic growth promoters.
India Feed Probiotics Market Competitive Environment
Integrated multinationals and domestic fermentation specialists split the market along technology access and cost positioning vectors. The supplier base concentrates around firms with captive strain development platforms and BIS IS 14818 compliance histories. Three archetypes dominate: global nutrition houses with integrated R&D pipelines, regional blenders dependent on imported active ingredients, and toll manufacturers offering spray-drying services. Competitive moves center on backward integration into fermentation capacity and formulation partnerships spanning enzyme-probiotic convergence.
Within the global nutrition tier, DSM-Firmenich leverages its integrated strain development platform while Adisseo anchors the western market through upstream control over key raw material streams. Novonesis competes on enzyme-probiotic synergy formulations, exemplifying the specialist archetype focused on tropical heat stress applications. These three entities represent distinct strategic positions: integrated platform ownership, raw material backward integration, and climate-specific formulation science respectively.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Adisseo |
| Novonesis |
| Evonik Industries AG |
| Kerry Group plc |
| Chr. Hansen |
| Lallemand Animal Nutrition |
| Unique Biotech Ltd. |
| Kemin Industries |
| Others |
Value Chain & Pricing Dynamics
Dahej and Vapi industrial belts in Gujarat concentrate spray-drying and microencapsulation capacity that protects microbial viability through standard pelleting temperatures, compressing price premiums for thermally stable formulations while raising baseline efficacy expectations among procurement officers at large dairy cooperatives and poultry integrators.
Pricing Analysis
BIS IS 14818 standards dictate the pricing tier structure across the India feed probiotics market by filtering marginal suppliers unable to invest in third-party laboratory certification and strain traceability systems. Three-tier pricing structure across premium, standard, and economy levels separates microencapsulated multi-strain blends from spray-dried single-species products and unprotected commodity powders. Cost compression in the economy tier is intensifying because legacy feed mills lacking temperature control precision force suppliers toward costly equipment retrofits or limited product compatibility. Smallholder dairy networks in Gujarat exhibit highest price sensitivity due to limited cold chain access and fragmented purchasing, while large poultry integrators in Andhra Pradesh prioritize stability documentation over unit cost.
Supply Chain Analysis
Import exposure between China and India dominates supply chain risk for concentrated bacterial and yeast strains that domestic blenders remain dependent upon, exposing margins to currency volatility and shipping disruptions. Active ingredient sourcing draws from Chinese fermentation houses for Bacillus species and European specialists for Saccharomyces cerevisiae strains, while microencapsulation polymers and spray-drying equipment feed from German and Japanese suppliers. Single-source vulnerability concentrates in toll manufacturing capacity around Dahej and Vapi, where batch-to-batch viability variance creates quality assurance headaches for brand owners. Distribution runs through direct technical sales relationships with cooperative federations displacing fragmented distributor networks, though regional blenders persist in secondary cities for backyard dairy operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's feed probiotics sector sits in early-cycle expansion as state-level antibiotic reduction mandates across Andhra Pradesh and Haryana accelerate veterinary adoption of viable alternatives, creating penetration runway for suppliers with demonstrated BIS compliance histories.
For Market Incumbents: Entrench position by deepening backward integration into domestic fermentation capacity around Gujarat's industrial corridor to reduce import dependence on Chinese active ingredient sources, while investing in captive quality infrastructure to meet tightening FSSAI microbial count specifications that filter marginal competitors from preferred supplier lists at consolidating feed mills. For New Entrants and Emerging Players: Establish a beachhead in aquaculture applications along coastal Tamil Nadu and Andhra Pradesh, where shrimp producers face mounting EU and US export residue standards driving live culture adoption faster than any other animal category, leveraging enzyme-probiotic synergy formulations as a differentiated entry angle against established poultry-focused suppliers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors domestic fermentation specialists with captive strain development platforms and demonstrated BIS IS 14818 compliance histories over regional blenders dependent on imported active ingredients. Long-term viability hinges on consolidation plays that capture toll manufacturing capacity in Gujarat while building technical sales relationships with cooperative federations displacing fragmented distribution. The signal to watch is state-level antibiotic reduction mandate expansion beyond current Andhra Pradesh and Haryana coverage, which would step-function demand for thermally stable probiotic formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Reduces import exposure to Chinese active ingredient sources while qualifying for PLI scheme incentives. |
| Microencapsulation Technology Licensing | Enables mid-tier single-species products to compete on thermal stability without full extrusion line replacement. |
| Direct Technical Sales Force Buildout | Displaces fragmented distributor networks as cooperative federations consolidate procurement authority. |
| Enzyme-Probiotic Convergence Partnerships | Opens formulation collaborations targeting tropical heat stress conditions in automated poultry operations. |
| Third-Party Laboratory Certification Investment | Secures preferred supplier status with FSSAI tightening microbial count specifications and contaminant limits. |
Study Parameters
A standing panel of fermentation facility managers, nutritionists at cooperative feed mills, procurement officers at poultry integrators, and regulatory affairs specialists provided ongoing calibration across primary fieldwork, with secondary validation drawing from FSSAI feed additive notifications, BIS IS 14818 standards documentation, PLI scheme disbursement records, and customs data on microbial culture imports. Bottom-up strain registration tracking and top-down feed mill capacity modeling were triangulated against operating metrics.
Scenario-bracketing framed demand projections across the analysis window, with segmentation dimensions spanning product type, animal category, formulation format, and distribution channel. CAGRs were derived from adoption curve modeling of antibiotic reduction mandate compliance, fermentation capacity buildout timelines, and cooperative procurement consolidation patterns. Industry-specific inputs included thermal stability validation protocols and strain viability decay curves under tropical storage conditions.
Stress conditions across currency volatility for imported active ingredients, state-level mandate expansion timing, and toll manufacturing batch consistency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on regulatory enforcement intensity and cooperative federation consolidation velocity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
India Biofertilizer Market
Bio-Agriculture
India Biocontrol Agents Market
Bio-Agriculture
Agriculture Biologicals Testing Market
Bio-Agriculture
Middle East and Africa Biofertilizers Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
Europe Agricultural Biologicals Market
Bio-Agriculture
North America Bio-Ethanol Market
Bio-Agriculture
Lignocellulosic Biomass Market
Bio-Agriculture
Microphytes Market
Bio-Agriculture
Mycorrhiza-Based Biofertilizer Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Europe Feed Probiotics Market
Bio-Agriculture
Bovine Tuberculosis Diagnosis Market
Bio-Agriculture
Indonesia Biopesticides Market
Bio-Agriculture
US Biochar Market