
 Middle East and Africa Biopesticides Market | 2026-2036
Middle East and Africa Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Biopesticides Market Foresight
Subscription-based biological crop protection programs is consolidating how growers access biopesticide technology across the region. Bayer AG leverages its digital farming infrastructure to bundle microbial products with remote sensing diagnostics. Koppert Biological Systems anchors its position through specialized technical advisory services delivered directly to greenhouse operators. Syngenta Group competes by extending its biologicals portfolio through integrated pest management protocols tailored to Mediterranean climate zones.
Middle East and Africa biopesticides comprise living organisms, naturally occurring substances, and plant-incorporated protectants formulated to suppress agricultural pests through biological mechanisms rather than synthetic chemistry. These products typically contain specified colony-forming units per gram for microbial strains, require controlled temperature storage, and function by colonizing plant surfaces, producing antimicrobial metabolites, or inducing systemic resistance in host crops. Microbial formulations dominate current volume due to established Bacillus thuringiensis and Trichoderma production infrastructure, while biochemical segments attract premium positioning where growers seek rapid residue clearance for export certification. Agricultural crops absorb the largest share of biopesticide offtake, though horticulture applications generate superior unit economics through higher per-hectare input intensity on high-value produce.
South Africa's Department of Agriculture regulates biological product registration through Act 36 of 1947, while Egypt's Agricultural Pesticide Committee enforces import licensing for microbial agents. The EU Green Deal's Farm to Fork strategy indirectly reshapes MEA demand by conditioning market access for regional exporters on reduced chemical residue profiles. Stakeholders must monitor how Gulf Cooperation Authority harmonization efforts affect product registration reciprocity across Saudi Arabia, UAE, and Qatar.
Market Dynamics
The EU Green Deal's Farm to Fork strategy is conditioning export market access for Middle East and Africa growers, forcing residue profile reductions across Egypt's vegetable belt and South Africa's fruit corridors. This external regulatory pressure is restructuring input procurement patterns before domestic biological frameworks mature.
Growth Catalysts
- Export Compliance Pressure:EU phytosanitary standards for Nile Delta vegetables and South African stone fruit are mandating residue clearance protocols that favor microbial formulations over synthetic chemistry.
- Act 36 of 1947 Modernization:South Africa's biological product registration pathway is streamlining microbial agent approvals, reducing time-to-market for Bacillus-based formulations targeting row crop pests.
- Greenhouse Technical Advisory Models:Specialized on-site biologicals support is replacing commodity chemical distribution in protected cultivation clusters across Morocco and Tunisia.
Market Restraints
- Cold Chain Infrastructure Gaps:Controlled temperature storage requirements for Trichoderma and Bacillus formulations limit shelf stability in Egypt's Upper Egypt and Sudan's rain-fed zones.
- Import Licensing Bottlenecks:Egypt's Agricultural Pesticide Committee maintains discretionary approval timelines for microbial agents that extend registration cycles beyond commercial planning horizons.
- Synthetic Chemistry Substitution:Generic organophosphate pricing in Kenya's maize belt and Ethiopia's teff regions undercuts biological unit economics at current scale.
Strategic Opportunities
- Nigeria's Underpenetrated Cocoa Belt:West Africa's largest cocoa producer lacks established microbial inoculant programs for black pod disease, presenting first-mover positioning for fermentation-compatible formulations.
- GCC Harmonization Pathways:Gulf Cooperation Authority registration reciprocity discussions between Saudi Arabia, UAE, and Qatar could collapse multi-jurisdiction approval costs for microbial suppliers.
- Remote Sensing Convergence:Integration of drone-based pest detection with precision microbial application is opening subscription-based biological protection models in South Africa's Western Cape vineyards.
Industry Challenges
- Microbial Formulation Expertise Scarcity:Colony-forming unit stabilization and carrier matrix optimization require skills concentrated in South Africa's Stellenbosch research corridor and Egypt's Agricultural Research Center.
- Multi-Jurisdiction Label Compliance:Divergent residue testing protocols between EU member states and Saudi Arabia's SFDA create certification fragmentation for export-oriented growers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Biopesticides Market |
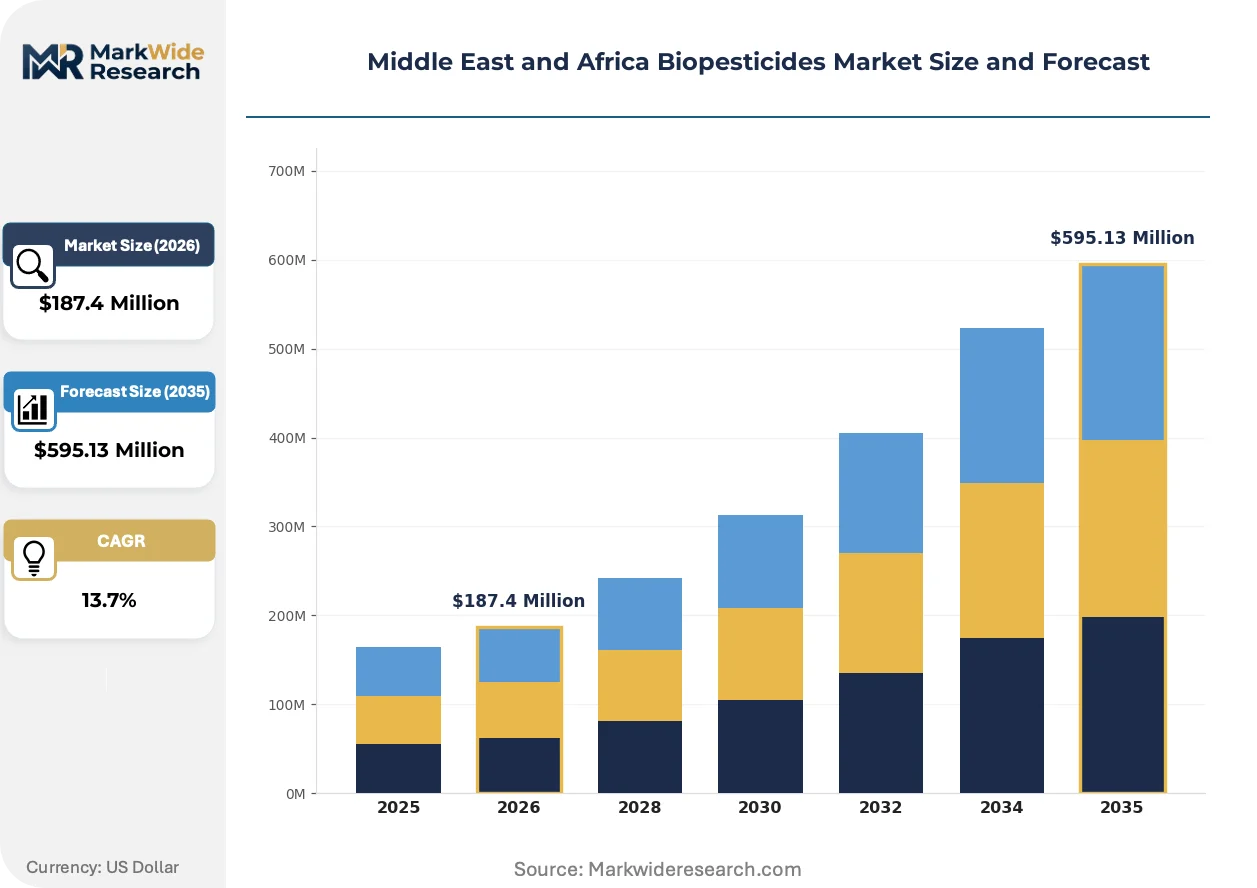
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $595.13 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial, Biochemical, Plant-Incorporated Protectants, Others Application: Agricultural Crops, Horticulture, Turf & Ornamental, Others Formulation Type: Liquid, Powder, Granular, Others Distribution Channel: Direct Sales, Retail, E-Commerce, Others |
| Companies Covered | BASF SE, Bayer AG, FMC Corporation, Syngenta Group, Koppert Biological Systems, Sumitomo Chemical, Corteva, Marrone Bio Innovations, Novozymes, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Biopesticides Market Shifts & Advancements
Biological crop protection is fragmenting from standardized chemical replacement toward tailored microbial consortia. Formulation science, regulatory data requirements, and service delivery models are all undergoing simultaneous recalibration.
Microbial consortia engineering is decentralizing biological product development from centralized R&D facilities toward regional fermentation partnerships. South African row crop cooperatives and Moroccan tomato greenhouse associations are co-developing strain libraries matched to local pathogen pressure. This distributed innovation model is compressing time-to-field for novel biocontrol agents while fragmenting intellectual property ownership across grower-processor alliances.
REACH-equivalent substance data requirements are extending from European import destinations into supplier country regulatory frameworks. Egypt's Agricultural Pesticide Committee has begun requesting ecotoxicology dossiers modeled on ECHA standards for microbial import licenses. Biochemical segment suppliers targeting EU phytosanitary compliance are restructuring manufacturing documentation to satisfy dual jurisdiction submissions.
Subscription-based biological protection programs are displacing transactional input purchasing in high-value export corridors. South African avocado and citrus growers are contracting multi-season microbial and macrobial packages bundled with residue testing and export certification support. This service unbundling is most visible in Western Cape and Limpopo provinces where packhouse consolidation has concentrated buyer negotiating power.
Middle East and Africa Biopesticides Market Segmentation
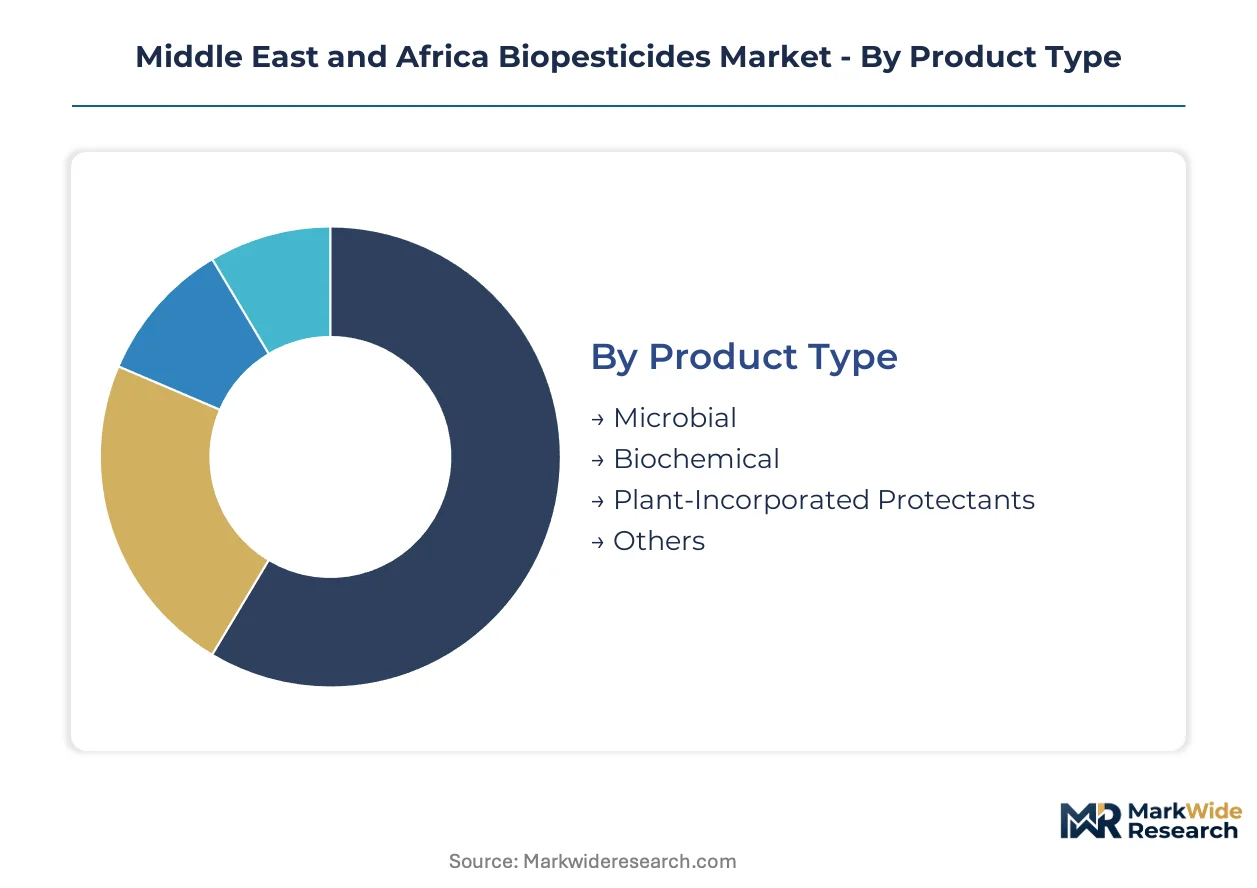
Biopesticide procurement in the Middle East and Africa fragments across product chemistry, application intensity, and service delivery models. Growers select formulations based on residue clearance requirements, cold chain availability, and export certification complexity rather than unit cost alone.
Product Type:
Standardization dominates microbial manufacturing while biochemical formulations require customized ecotoxicology dossiers for dual-jurisdiction submissions.
- Microbial:Bacillus thuringiensis and Trichoderma-based products specify colony-forming units per gram and demand controlled temperature storage. Demand concentrates in South Africa's row crop cooperatives where Act 36 of 1947 registration streamlines time-to-market for fermentation-derived agents.
- Biochemical:Naturally occurring substances including plant extracts and semiochemicals attract premium positioning. Egypt's Nile Delta vegetable belt drives procurement where EU phytosanitary compliance mandates rapid residue clearance protocols for export-oriented produce.
- Plant-Incorporated Protectants:Genetically modified crops expressing pesticidal proteins face limited adoption due to regulatory complexity across national biosafety frameworks.
- Others:Predatory insects and nematode formulations serve niche greenhouse applications in Morocco and Tunisia.
Most installed capacity flows through Microbial. Expansion is steepest in Biochemical.
Application:
Per-hectare input intensity varies by crop value, with horticulture commanding three to five times the biologicals spend of broadacre grains.
- Agricultural Crops:Maize, teff, and sorghum applications in Kenya and Ethiopia absorb volume through commodity distribution channels. Generic organophosphate pricing undercuts biological unit economics at current procurement scale.
- Horticulture:Protected cultivation of tomatoes, peppers, and cucumbers in Morocco and Tunisia generates superior unit economics. Koppert Biological Systems anchors demand through specialized technical advisory services delivered directly to greenhouse operators.
- Turf & Ornamental:Golf course and landscaping maintenance in UAE and Qatar drives consistent offtake for microbial fungicides.
- Others:Forestry and public health applications remain marginal across the region.
Revenue concentrates in Horticulture. Volume expansion runs fastest in Agricultural Crops.
Formulation Type:
Liquid formulations dominate where spray application infrastructure exists; dry formats penetrate regions with storage constraints.
- Liquid:Suspension concentrates and emulsifiable concentrates require calibrated spray equipment. South Africa's Western Cape vineyards favor liquid Bacillus formulations compatible with precision application systems.
- Powder:Wettable powders and water-dispersible granules tolerate ambient storage conditions. Sudan's rain-fed zones and Egypt's Upper Egypt rely on powder formats where cold chain infrastructure gaps limit shelf stability of aqueous suspensions.
- Granular:Soil-applied granules target root-zone pests in Nigeria's cocoa belt where black pod disease pressure demands fermentation-compatible delivery systems.
- Others:Microencapsulated and tablet formulations serve specialized nursery applications.
Manufacturing capacity clusters around Liquid. Powder formats are gaining share fastest in cold-chain-constrained markets.
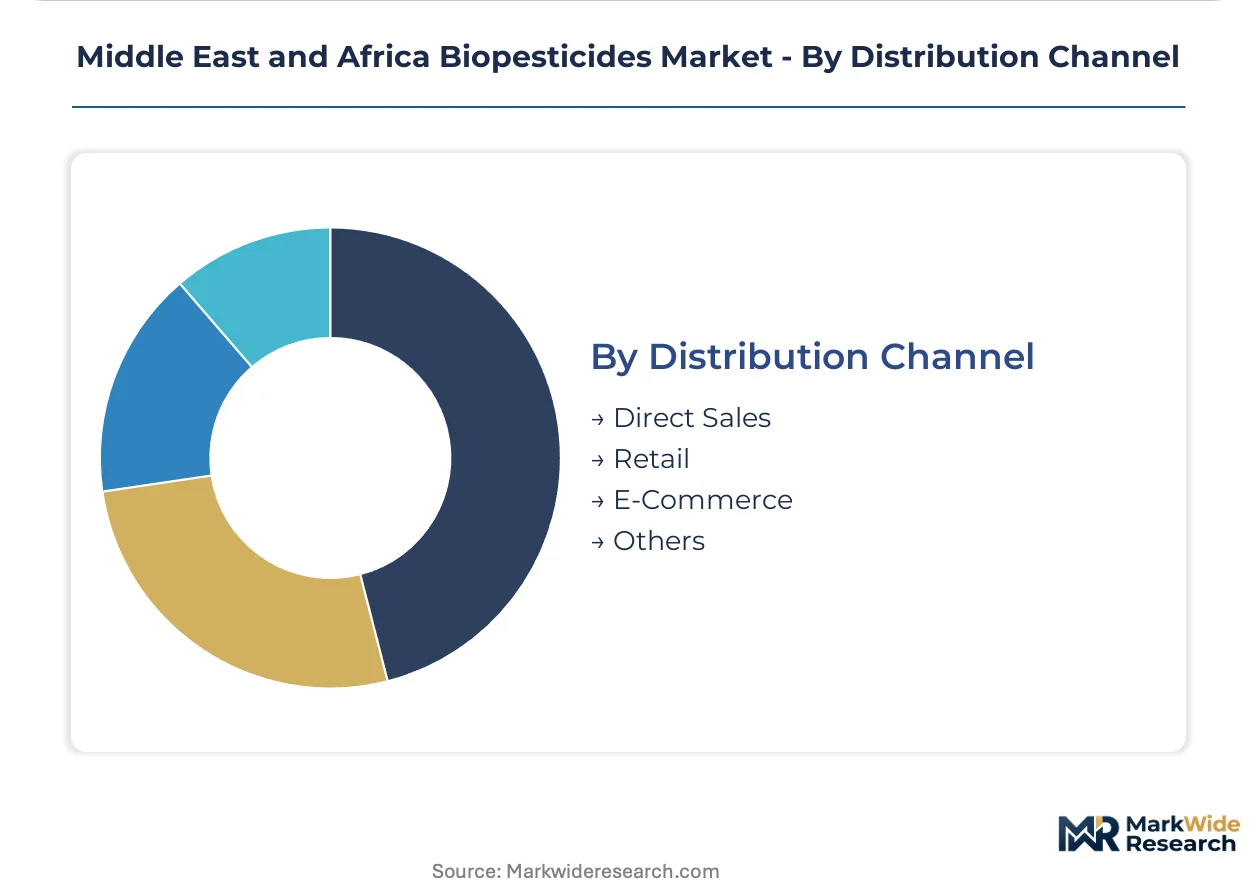
Distribution Channel:
Channel selection tracks buyer scale, technical support requirements, and digital infrastructure maturity across national markets.
- Direct Sales:Bayer AG leverages digital farming infrastructure to bundle microbial products with remote sensing diagnostics. Large-scale avocado and citrus operations in South Africa's Western Cape and Limpopo provinces contract multi-season packages with residue testing support.
- Retail:Agrochemical dealerships and cooperatives serve fragmented smallholder networks. Kenya's maize belt relies on retail channels where transaction sizes limit direct sales economics.
- E-Commerce:Platform-based procurement emerges in UAE and Saudi Arabia where smartphone penetration supports input ordering. Gulf Cooperation Authority harmonization discussions could standardize cross-border digital sales protocols.
- Others:Government extension programs and NGO-led distribution reach subsistence producers.
Transaction volume flows predominantly through Retail. E-Commerce climbs fastest in GCC markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's export-oriented fruit corridors generate more biopesticide revenue per hectare than Egypt's Nile Delta vegetable belt, though the latter commands greater absolute volume through smallholder network density.
South Africa
Western Cape and Limpopo provinces drive demand through avocado and citrus packhouse consolidation. The Department of Agriculture, Land Reform and Rural Development enforces Act 36 of 1947 registration pathways that streamline microbial agent approvals. Stellenbosch anchors fermentation research for Bacillus thuringiensis stabilization protocols.
Egypt
Nile Delta vegetable growers face EU phytosanitary compliance pressure for export-oriented tomatoes and peppers. The Agricultural Pesticide Committee maintains discretionary import licensing timelines for microbial agents. Upper Egypt relies on powder formulations where cold chain gaps limit liquid suspension shelf stability.
Morocco
Protected tomato and cucumber cultivation in the Souss-Massa region generates premium horticulture input intensity. The national food safety authority aligns residue testing protocols with EU import destination requirements. Agadir-based greenhouse clusters contract specialized technical advisory services for integrated pest management.
Saudi Arabia
Date palm and greenhouse vegetable operations in the Riyadh and Qassim regions drive microbial fungicide procurement. The Saudi Food and Drug Authority (SFDA) regulates biological product registration with partial reciprocity discussions underway through Gulf Cooperation Authority harmonization. NEOM agricultural zones pilot precision application systems for microbial consortia.
Nigeria
Cocoa belt smallholders in Ondo and Cross River states lack established microbial inoculant programs for black pod disease. The national agricultural regulator maintains developing frameworks for biological import licensing. Ibadan research corridors anchor regional strain development partnerships with West African cocoa cooperatives.
Middle East and Africa Biopesticides Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational agrochemical conglomerates commanding premium-tier positioning through bundled digital services while regional fermentation partners capture commodity microbial volume. The vendor base organizes around three strategic archetypes: integrated life sciences conglomerates with biologicals portfolios, dedicated biocontrol specialists with technical advisory capabilities, and regional fermentation contractors supplying bulk colony-forming unit concentrates. Dominant competitive moves include subscription-based service unbundling that wraps residue testing with multi-season microbial packages, and distributed strain library partnerships that fragment intellectual property ownership across grower-processor alliances.
Within the integrated conglomerate tier, Bayer AG and Syngenta Group exemplify positioning that leverages digital farming infrastructure and integrated pest management protocols respectively. BASF SE anchors the premium biochemical segment where rapid residue clearance commands pricing power. Among dedicated biocontrol specialists, Koppert Biological Systems occupies a position defined by specialized technical advisory services delivered directly to greenhouse operators. These three companies represent divergent strategic vectors: digital bundling, portfolio breadth, and service-intensive specialization.
| Leading Market Players |
|---|
| BASF SE |
| Bayer AG |
| FMC Corporation |
| Syngenta Group |
| Koppert Biological Systems |
| Sumitomo Chemical |
| Corteva |
| Marrone Bio Innovations |
| Novozymes |
| Others |
Supply & Pricing Matrix
Certification-grade bifurcation between EU-compliant biochemicals and commodity microbial concentrates manifests in parallel supply chain configurations, with residue-clearance premiums commanding dedicated cold-chain logistics while generic Bacillus formulations flow through ambient-temperature cooperatives. This tier divergence concentrates pricing power among packhouse-integrated service providers in South Africa's Western Cape while fragmenting procurement across Egypt's smallholder networks.
Pricing Analysis
Capacity additions in South Africa's Stellenbosch fermentation corridor are reshaping price floors for Bacillus thuringiensis concentrates, compressing margins on standardized colony-forming unit products. Subscription-based biological protection programs bundle residue testing with multi-season microbial packages, creating value-based pricing differentiation against transactional chemical procurement. Price erosion runs through generic microbial tiers as regional fermentation contractors expand output, while EU phytosanitary-compliant biochemicals maintain pricing resilience. Smallholder vegetable growers in Egypt's Nile Delta exhibit highest price sensitivity, whereas South African avocado packhouses prioritize residue clearance certainty over unit cost.
Supply Chain Analysis
EU-equivalent ecotoxicology dossier requirements gate upstream access for biochemical suppliers, forcing dual-jurisdiction documentation investments that concentrate supply among REACH-compliant manufacturers. Production gravity centers on South Africa's Western Cape fermentation infrastructure, Egypt's Agricultural Research Center strain libraries, and Morocco's Souss-Massa greenhouse formulation facilities. Raw material dependencies include molasses feedstocks for microbial fermentation, specialized carrier matrices for powder stabilization, and cold-chain packaging for aqueous suspensions. Single-source vulnerability pervades Trichoderma strain supply from Stellenbosch research partnerships. Distribution runs through packhouse-consolidated direct sales in South Africa, agrochemical retail networks in Kenya's maize belt, and emerging platform-based procurement in UAE.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Middle East and Africa biopesticides rests on cold-chain cost compression through ambient-stable formulation innovation and premium-tier capture via bundled certification services.
For Market Incumbents: Anchor defensible positioning through backward integration into regional fermentation capacity, securing captive supply of colony-forming unit concentrates against emerging contract manufacturers. Deepen technical advisory capabilities to lock in greenhouse operator loyalty in Morocco and Tunisia, insulating against Syngenta's integrated pest management bundling. Prioritize Act 36 of 1947 registration pipeline investments to accelerate time-to-market for novel microbial strains. For New Entrants and Emerging Players: Nigeria's cocoa cooperative smallholders represent an underserved buyer archetype with zero established microbial inoculant penetration for black pod disease. Target West Africa's fermentation-compatible granular formulation gap through Ibadan research corridor partnerships, bypassing cold-chain infrastructure deficits that limit liquid suspension viability. Pursue first-mover positioning via cooperative embedded technical advisors rather than commodity retail channels. For Investors and Strategic Acquirers: Consolidation pressure builds where distributed strain library partnerships fragment intellectual property ownership across grower-processor alliances, creating roll-up opportunities for integrated biologicals platforms. Five-to-ten year viability favors specialists with dual-jurisdiction regulatory dossier capabilities and packhouse-integrated service delivery. Watch for GCC harmonization implementation as inflection signal for multi-jurisdiction approval cost collapse.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Fermentation Partnership | Stellenbosch and Cairo research corridors anchor distributed strain development for local pathogen pressure. |
| Dual-Jurisdiction Dossier Investment | ECHA-modeled ecotoxicology documentation satisfies Egypt's Agricultural Pesticide Committee and EU import requirements simultaneously. |
| Cold-Chain Bypass Formulation | Powder and granular formats penetrate Sudan and Upper Egypt where temperature-controlled storage gaps limit liquid suspension shelf stability. |
| Subscription Service Unbundling | Multi-season microbial packages with residue testing displace transactional input purchasing in Western Cape avocado packhouses. |
| GCC Harmonization Positioning | Registration reciprocity across Saudi Arabia, UAE, and Qatar collapses multi-jurisdiction approval costs for microbial suppliers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biopesticide registration specialists at South Africa's Department of Agriculture, technical advisory leads at Moroccan greenhouse cooperatives, procurement managers at Egyptian export packhouses, and strain development researchers at Ibadan and Stellenbosch universities. Secondary validation drew from EU Green Deal Farm to Fork strategy documents, Act 36 of 1947 regulatory filings, ECHA substance database entries, and Gulf Cooperation Authority harmonization communiques. Bottom-up volume estimates from cooperative procurement records and top-down value projections from packhouse contract values were triangulated for consistency.
Segment-weighting approaches distributed value across microbial, biochemical, and plant-incorporated protectant chemistry types, with application intensity calibrated separately for horticulture versus broadacre grain systems and formulation requirements modeled for liquid, powder, and granular delivery formats. CAGRs were derived from fitted growth curves across the analysis window, with country-level weights reflecting export compliance pressure intensity and cold-chain infrastructure maturity. Industry-specific inputs included EU phytosanitary rejection rate trends for Nile Delta vegetables and South African stone fruit, plus microbial inoculant adoption curves from row crop cooperative procurement data.
Inputs from greenhouse operator associations and export packhouse procurement systems were available through the study window; gaps in smallholder transaction-level data introduce uncertainty bands around volume estimates for Egypt's Upper Egypt and Nigeria's cocoa belt. Forecasts reflect assumptions regarding GCC harmonization timeline implementation and EU residue threshold evolution. A model refresh is warranted upon material change in EU Green Deal phytosanitary enforcement intensity or Gulf Cooperation Authority registration reciprocity activation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
China Biofertilizer Market
Bio-Agriculture
West Africa Biostimulants Market
Bio-Agriculture
Asia-Pacific Agricultural Biologicals Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
Global Bio-Organic Acid Market
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
China Biocontrol Agents Market
Bio-Agriculture
Artificial Insemination Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
North America Bioherbicides Market
Bio-Agriculture
Brazil Agricultural Biologicals Market
Bio-Agriculture
Europe Biofertilizer Market
Bio-Agriculture
Bio-Insecticide Market
Bio-Agriculture
Europe Plant-Based Biologics Market
Bio-Agriculture
Latin America Biopesticide Market