
 Germany Biostimulants and Biopesticides Market | 2026-2036
Germany Biostimulants and Biopesticides Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Biostimulants and Biopesticides Market Foresight
Agronomic expertise in microbial formulation science is reorganizing competitive dynamics across Germany's biological crop input sector. BASF SE leverages its Ludwigshafen research infrastructure to sustain development pipelines for next-generation microbial inoculants. Bayer AG anchors field trial networks across Lower Saxony to validate biostimulant performance under local soil conditions. Koppert Biological Systems specializes in beneficial organism propagation, occupying a distinctive position in integrated pest management supply chains.
Biostimulants comprise substances and microorganisms applied to plants or rhizospheres to stimulate natural processes, enhancing nutrient uptake efficiency, abiotic stress tolerance, and crop quality traits without direct pesticidal action; biopesticides derive from natural materials including plants, bacteria, nematodes, and certain minerals, functioning through non-toxic mechanisms against pests and pathogens. Seaweed extracts and humic acids dominate current volume flows, reflecting established extraction infrastructure and farmer familiarity. Microbial inoculants represent the fastest-expanding product category, driven by Rhizobium and Trichoderma strain innovations that improve nitrogen fixation and disease suppression in cereal crop rotations. Liquid concentrates command preference among greenhouse operators for fertigation compatibility, while powdered formulations retain cost advantages in broad-acre cereal applications.
The EU Green Deal's Farm to Fork Strategy mandates pesticide reduction targets that directly expand addressable demand for biopesticide alternatives. Germany's Federal Office of Consumer Protection and Food Safety enforces registration protocols aligned with REACH and EU F-Gas Regulation compliance requirements for biological active substances. The German Fertilizer Ordinance and national implementation of the EU Sustainable Use Directive shape product labeling claims and application protocols. Stakeholders must monitor forthcoming amendments to EU Regulation 2019/1009 on fertilizing products, as reclassification of certain biostimulant claims could reshape market access requirements and reformulation obligations.
Market Dynamics
The EU Green Deal's Farm to Fork Strategy is compressing synthetic pesticide allowances, forcing German growers to rebuild input protocols around microbial inoculants and botanical extracts before the 2030 reduction targets lock in.
Growth Catalysts
- Regulatory Mandates:The EU Sustainable Use Directive and Germany's Fertilizer Ordinance are hardening pesticide reduction targets, expanding the addressable market for biological alternatives in Rhineland-Palatinate's greenhouse corridors.
- Microbial Strain Innovation:Rhizobium and Trichoderma formulations are improving nitrogen fixation rates in cereal rotations across Lower Saxony, creating measurable yield advantages over untreated controls.
- Irrigation Infrastructure Retrofit:Specialty vegetable producers in Bavaria are converting fertigation systems for liquid biostimulant delivery, embedding biological inputs into existing capital equipment.
Market Restraints
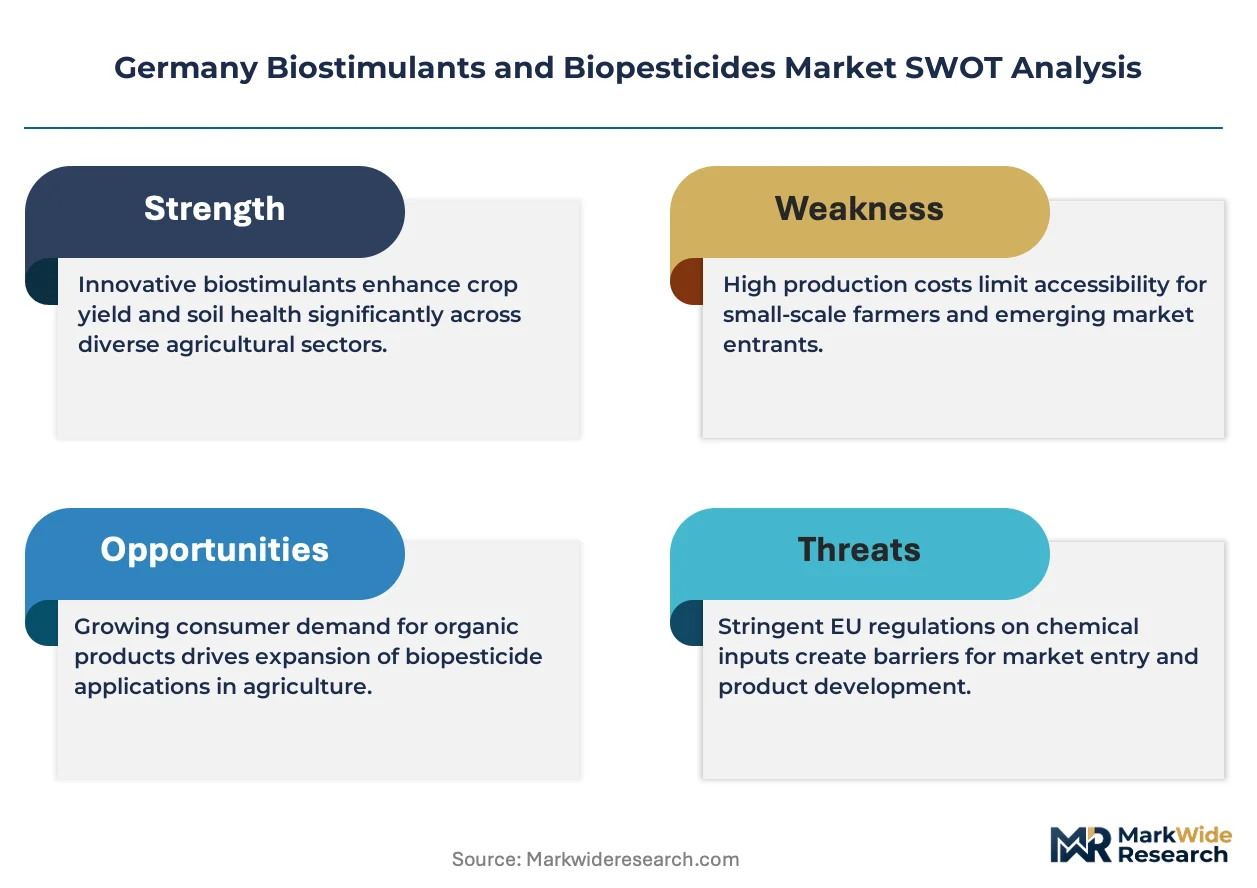
- Registration Protocol Friction:Germany's Federal Office of Consumer Protection and Food Safety applies REACH-aligned substance evaluation timelines that extend product commercialization by 18-36 months versus conventional chemistry.
- Seaweed Extract Supply Concentration:Raw material dependence on North Atlantic harvesting operations creates price volatility and seasonal availability constraints for humic acid processors.
- Performance Variability:Microbial inoculants exhibit inconsistent field efficacy across Germany's heterogeneous soil microbiomes, limiting farmer willingness to fully substitute synthetic programs.
Strategic Opportunities
- Baden-Württemberg Specialty Crops:Vineyard and orchard operators in this southwestern state remain underpenetrated by biological disease management, presenting white space for targeted biofungicide deployment.
- EU Regulation 2019/1009 Reform:Pending amendments to fertilizing product classifications could unlock new labeling claims for biostimulants, reshaping competitive positioning for early movers.
- Precision Application Convergence:Integration of microbial inoculants with drone-based delivery systems and soil sensor networks is enabling variable-rate biological treatments in broad-acre cereal production.
Industry Challenges
- Formulation Science Talent Scarcity:Microbial stabilization and shelf-life extension expertise remains concentrated among a narrow pool of agronomic researchers, constraining product development velocity.
- Legacy Equipment Compatibility:Broad-acre farmers in northern Germany face capital barriers retrofitting existing spray equipment for shear-sensitive biological formulations without clogging nozzles or degrading live cultures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Biostimulants and Biopesticides Market |
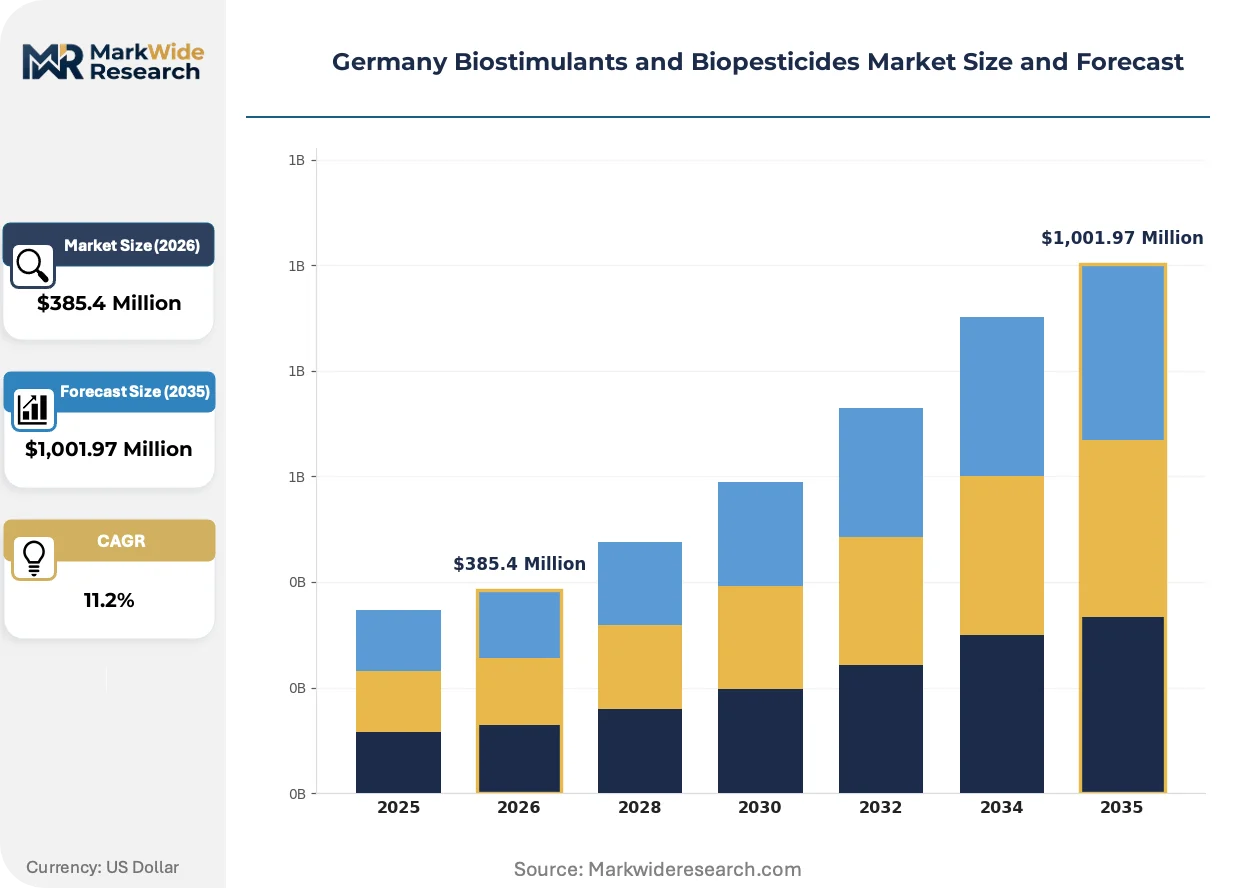
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,001.97 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
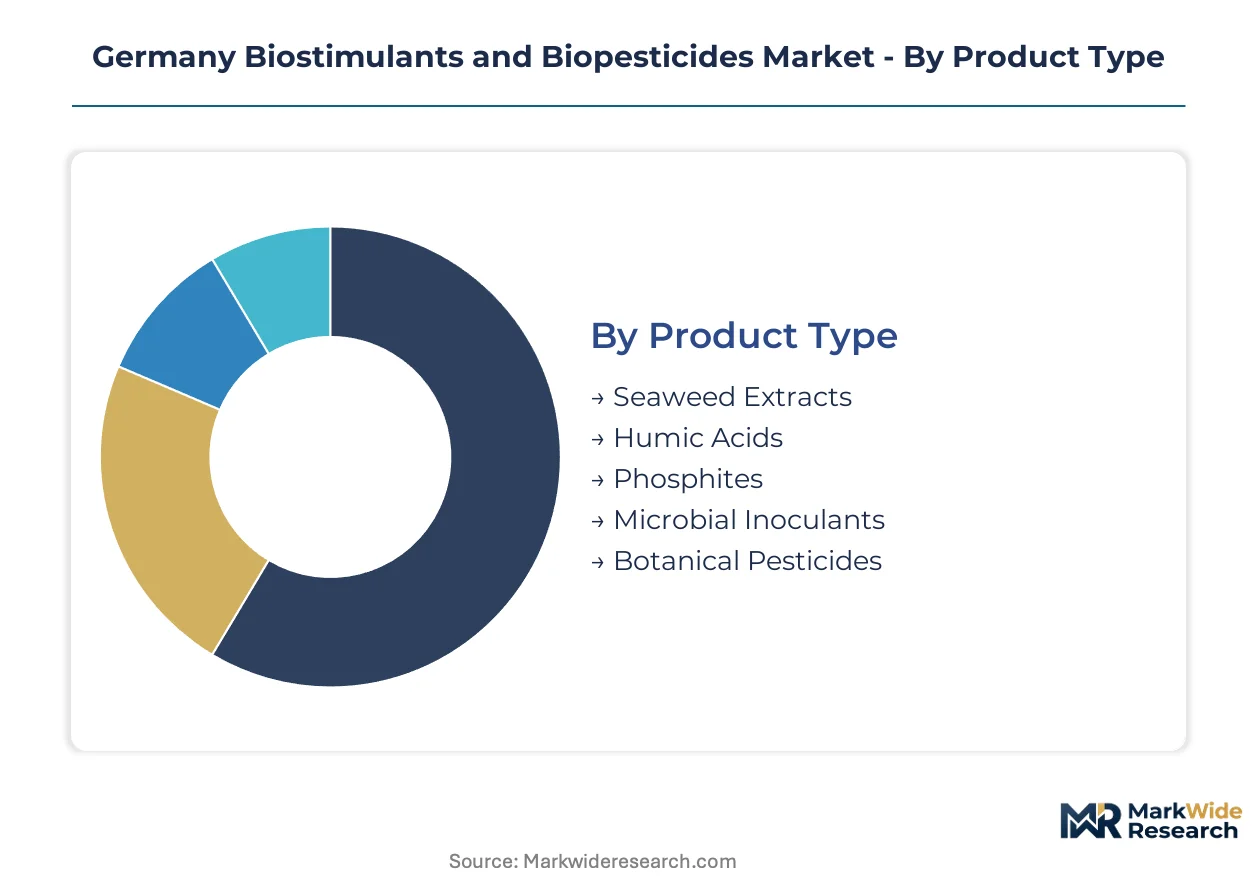
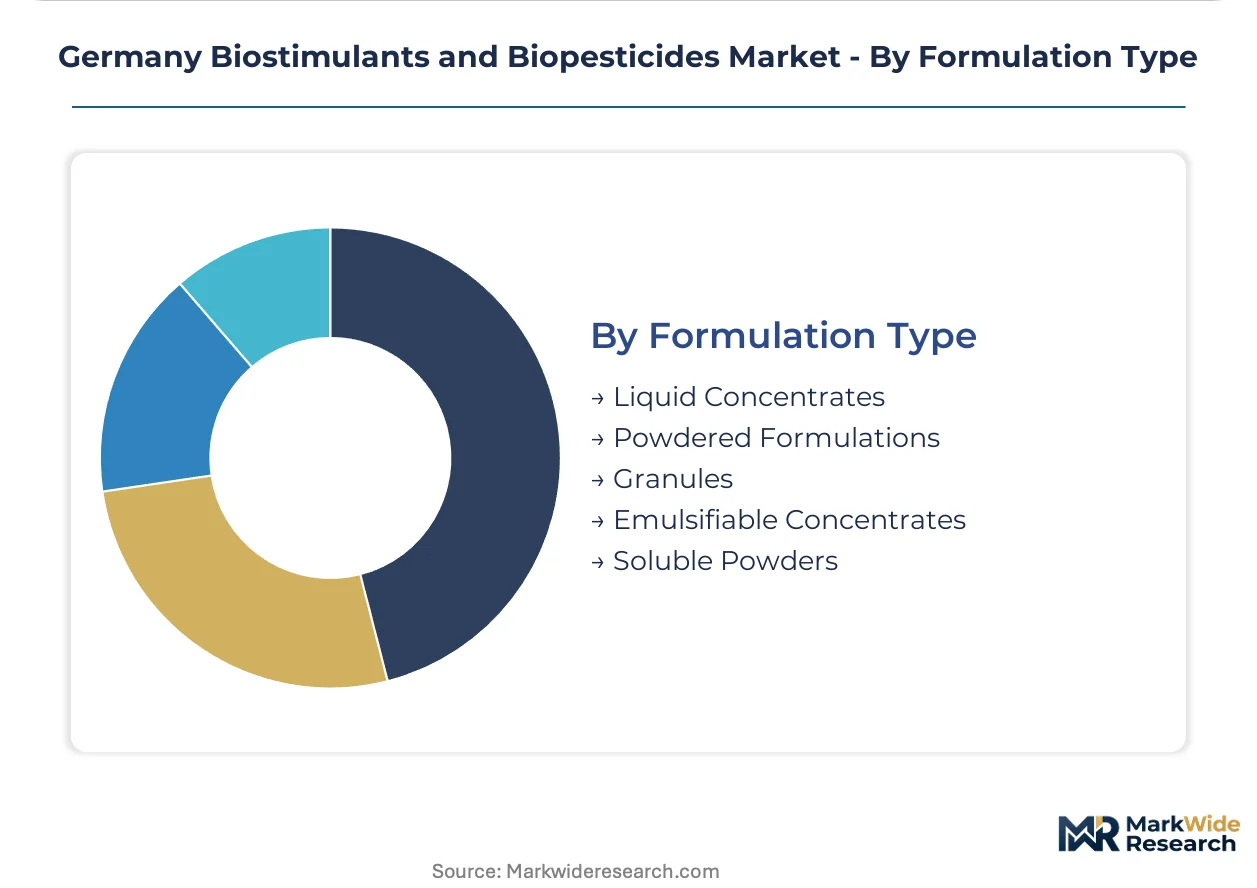
| Segmentation | Product Type: Seaweed Extracts, Humic Acids, Phosphites, Microbial Inoculants, Botanical Pesticides Application: Cereal Crops, Vegetable Farming, Fruit Cultivation, Ornamental Plants, Turf Management End User: Organic Farms, Greenhouses, Research Institutes, Landscape Nurseries, Crop Consultants Formulation Type: Liquid Concentrates, Powdered Formulations, Granules, Emulsifiable Concentrates, Soluble Powders |
| Companies Covered | Koppert Biological Systems, COMPO Expert GmbH, BASF SE, Certis Belchim B.V., Evonik Industries AG, Bayer AG, AlzChem Group AG, Andermatt Group AG, Syngenta AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Biostimulants and Biopesticides Market Shifts & Advancements
Formulation science breakthroughs are compressing the performance gap between biological and synthetic inputs, while regulatory pressure and procurement model evolution are accelerating adoption timelines across German agricultural value chains.
Encapsulation technologies for viable microbial preservation are supplanting conventional liquid fermentation batches in premium product tiers. Greenhouse operators in Rhineland-Palatinate are adopting these stabilized concentrates for extended storage compatibility. The shift is compressing inventory carrying costs and enabling just-in-time procurement previously impossible with live culture products.
The EU F-Gas Regulation and national implementation of the EU Green Deal are tightening synthetic pesticide residue thresholds in food retail channels. German food processors and export-oriented cooperatives are enforcing supplier compliance through integrated pest management scorecards. Bavarian vegetable producers are responding by certifying operations under stricter biological input protocols to maintain supermarket shelf access.
Buying committees at large agricultural cooperatives are consolidating supplier relationships from fragmented regional distributors toward direct manufacturer partnerships. This channel compression is squeezing margin pools for independent agronomic advisors who previously controlled product recommendations. The pattern is most visible in Lower Saxony's cereal belt, where procurement centralization at grain elevator networks is reshaping go-to-market economics for input manufacturers.
Germany Biostimulants and Biopesticides Market Segmentation
German growers navigate input procurement through four intersecting dimensions: product chemistry, crop system, operational scale, and physical formulation. Channel preferences vary sharply across these axes, with greenhouse operators favoring liquid delivery systems while broad-acre cereal producers prioritize cost-efficient dry formulations.
Product Type:
Liquid concentrates and soluble powders flow through Rhineland-Palatinate's greenhouse supply chains, while powdered microbial products dominate Lower Saxony's grain elevator networks.
- Seaweed Extracts:Cold-processed Ascophyllum nodosum and Laminaria digitata concentrates supply cytokinin and auxin bioactives for stress tolerance programs. Bavarian vegetable producers integrate these into fertigation protocols for greenhouse tomato and pepper operations facing EU Green Deal residue restrictions.
- Microbial Inoculants:Rhizobium, Trichoderma, and Bacillus formulations improve nitrogen fixation and induced systemic resistance in cereal rotations. Field trials across Lower Saxony validate yield advantages that drive procurement committee specifications at grain cooperatives.
- Humic Acids:Leonardite-derived humic and fulvic acid complexes enhance cation exchange capacity in sandy soils.
- Phosphites:Potassium and calcium phosphite salts provide systemic resistance induction against oomycete pathogens.
- Botanical Pesticides:Pyrethrin, azadirachtin, and essential oil formulations target specific pest complexes in organic certification programs.
By volume, seaweed extracts lead. By growth pace, microbial inoculants are ahead.
Application:
Cost tier differentiation separates premium greenhouse applications from commodity cereal programs, with input expenditure per hectare varying by an order of magnitude across these segments.
- Vegetable Farming:Intensive greenhouse tomato, cucumber, and pepper operations in Rhineland-Palatinate and Bavaria demand continuous biostimulant application through drip irrigation. German food retail compliance requirements drive biological input substitution rates above national averages.
- Cereal Crops:Wheat, barley, and rye rotations across Lower Saxony and Schleswig-Holstein represent the largest addressable hectarage for microbial seed treatments. Procurement centralization at grain elevator networks compresses supplier margins while scaling volume commitments.
- Fruit Cultivation:Apple, pear, and stone fruit orchards in Baden-Württemberg and the Altes Land region apply biofungicides for scab and brown rot management.
- Ornamental Plants:Nursery stock and floriculture operations prioritize aesthetic quality and shelf-life extension.
- Turf Management:Golf courses and municipal parks use stress tolerance biostimulants for drought recovery.
Cereal crops dominate hectarage coverage. Vegetable farming commands the steepest expansion trajectory.
End User:
Customer type determines technical service intensity, with research institutes and crop consultants requiring formulation science support that greenhouses and organic farms rarely demand.
- Greenhouses:Controlled-environment vegetable producers in Bavaria and Rhineland-Palatinate specify liquid concentrates compatible with fertigation infrastructure. These operations maintain the highest biological input application frequencies and technical advisory relationships.
- Organic Farms:Certified operations across Brandenburg and Mecklenburg-Vorpommern face mandatory synthetic prohibition, creating captive demand for biopesticide alternatives. EU organic regulation compliance audits reinforce input documentation requirements.
- Crop Consultants:Independent agronomic advisors in Lower Saxony influence procurement decisions across multiple farm operations.
- Research Institutes:Julius Kühn-Institut and university trial stations validate strain efficacy under German soil conditions.
- Landscape Nurseries:Ornamental producers serve municipal and private landscaping contracts with varying sustainability specifications.
Greenhouses lead in input expenditure per hectare. Organic farms are gaining share fastest.
Formulation Type:
Supply concentration in microbial stabilization technology favors liquid concentrate manufacturers with encapsulated preservation capabilities.
- Liquid Concentrates:Shear-stabilized microbial suspensions and extract solutions integrate directly into fertigation systems. Rhineland-Palatinate greenhouse operators prefer these for inventory management simplicity and dosing precision.
- Powdered Formulations:Spray-dried and freeze-dried microbial preparations offer extended shelf life and reduced shipping costs. Broad-acre cereal producers in northern Germany favor these for compatibility with existing seed treatment equipment.
- Granules:Clay-carrier formulations enable soil incorporation at planting.
- Emulsifiable Concentrates:Oil-based delivery systems improve botanical pesticide leaf adhesion.
- Soluble Powders:Instant-dissolve formulations bridge greenhouse and field application requirements.
Powdered formulations lead by volume shipped. Liquid concentrates are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biostimulant consumption patterns diverge sharply across German federal states, with greenhouse-intensive southern regions prioritizing liquid fertigation formulations while northern cereal belts favor cost-optimized dry microbial products for broad-acre deployment.
Bavaria
Specialty vegetable producers in the Altmühl Valley and Munich hinterland drive demand for seaweed extract concentrates compatible with drip irrigation systems. The German Fertilizer Ordinance shapes labeling requirements for organic substrate operations. Nuremberg-area greenhouse clusters are retrofitting fertigation infrastructure for continuous biostimulant dosing protocols.
Baden-Württemberg
Vineyard operators in the Stuttgart region and orchardists around Lake Constance apply biofungicides for scab and powdery mildew management in premium wine and fruit production. EU Sustainable Use Directive implementation tightens synthetic fungicide allowances in steep-slope viticulture. The Kaiserstuhl volcanic soil district hosts concentrated trials for Trichoderma-based disease suppression programs.
Lower Saxony
Cereal rotation farmers across the North German Plain specify Rhizobium and Bacillus seed treatments for wheat and barley nitrogen fixation enhancement. REACH-aligned registration timelines from Germany's Federal Office of Consumer Protection and Food Safety delay product commercialization. Göttingen-area grain elevator networks centralize procurement decisions for cooperative members.
Rhineland-Palatinate
Controlled-environment tomato and cucumber producers in the Neustadt-Gimmeldingen greenhouse corridor maintain Germany's highest biostimulant application frequencies per hectare. EU Green Deal Farm to Fork Strategy residue thresholds drive biological input substitution in export-oriented vegetable operations. Ludwigshafen-BASF research infrastructure anchors microbial formulation development pipelines serving regional growers.
North Rhine-Westphalia
Specialty crop diversification in the Lower Rhine vegetable belt and Bergisches Land nursery operations creates segmented demand for botanical pesticides and stress tolerance biostimulants. The EU F-Gas Regulation influences greenhouse heating infrastructure decisions that indirectly affect biological input storage requirements. Mönchengladbach-area ornamental producers serve municipal landscaping contracts with sustainability scorecard compliance obligations.
Germany Biostimulants and Biopesticides Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with multinational chemical conglomerates leveraging fermentation infrastructure and distribution scale against focused biological propagation firms. The market structure rewards players with captive strain libraries and formulation stabilization expertise. Two strategic archetypes dominate: diversified agriscience majors with microbial R&D pipelines, and dedicated biological systems specialists with integrated pest management service capabilities. Competitive dynamics center on registration acceleration partnerships and precision application technology licensing rather than price-based rivalry.
Among diversified agriscience majors, BASF SE and Bayer AG exemplify the integrated-leader archetype through their Ludwigshafen and Monheim research infrastructures. Koppert Biological Systems occupies a distinctive position as a dedicated biological systems specialist with propagation capabilities in beneficial organism supply chains. These three entities represent contrasting strategic postures: chemical conglomerates with biological input diversification versus purpose-built biological propagation operations.
| Leading Market Players |
|---|
| Koppert Biological Systems |
| COMPO Expert GmbH |
| BASF SE |
| Certis Belchim B.V. |
| Evonik Industries AG |
| Bayer AG |
| AlzChem Group AG |
| Andermatt Group AG |
| Syngenta AG |
| Others |
Supply & Pricing Matrix
Fermentation capacity utilization at Ludwigshafen and Monheim facilities shapes both supply concentration and price floors for microbial inoculants across German agricultural value chains. Scale advantages in encapsulated formulation production compress unit economics for liquid concentrates while elevating barriers for regional compounders lacking stabilization expertise.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement between grain cooperatives and microbial suppliers, insulating volume buyers from raw material volatility in North Atlantic seaweed harvesting. Price differentiation hinges on certification tier under EU Regulation 2019/1009 and volume scale, with greenhouse operators paying premiums for encapsulated shelf-stable concentrates. Cost compression in powdered formulations is intensifying because broad-acre cereal producers centralize procurement through elevator networks. Organic certification programs exhibit the lowest price sensitivity, while commodity grain operations demand standard-grade microbial seed treatments.
Supply Chain Analysis
Just-in-time inventory strategies prevail among Rhineland-Palatinate greenhouse operators who lack cold-storage infrastructure for live culture products, while northern cereal cooperatives maintain strategic stockpiles of powdered formulations ahead of planting windows. Geographic supply concentration centers on Germany, the Netherlands, and Spain for microbial propagation and formulation finishing. Raw material dependencies include Ascophyllum nodosum biomass from North Atlantic coasts, leonardite deposits from North America, and specialized fermentation feedstocks. Single-source vulnerability in encapsulated preservation technology creates supply chain risk. Distribution runs through agricultural cooperative buying committees and direct manufacturer partnerships, displacing independent agronomic advisors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's biostimulant sector builds defensive moats through regulatory entrenchment, where REACH-aligned registration timelines and EU Regulation 2019/1009 compliance create switching costs that lock in incumbent relationships.
For Market Incumbents: Fortify market position by deepening backward integration into microbial strain libraries and securing exclusive propagation agreements with Julius Kühn-Institut research stations. Expand encapsulated formulation capacity in Baden-Württemberg to serve vineyard biofungicide demand before generic competitors clear registration. Channel control through direct greenhouse partnerships offsets margin pressure from cooperative procurement centralization. For New Entrants and Emerging Players: Anchor in Baden-Württemberg's underpenetrated orchard and vineyard segments where synthetic fungicide restrictions outpace biological solution availability. Target specialty vegetable operations in Bavaria's Altmühl Valley with precision application compatibility as the go-to-market angle, leveraging drone-based delivery partnerships to bypass incumbent distributor relationships. For Investors and Strategic Acquirers: Purpose-built microbial stabilization specialists with captive strain development capabilities represent the highest-conviction acquisition archetype for long-term viability. Monitor EU Regulation 2019/1009 amendment timelines as the critical inflection signal, as reclassification of biostimulant claims will reshape competitive positioning and unlock premium pricing tiers for early movers with compliant portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Encapsulation Technology Licensing | Preservation expertise from BASF's Ludwigshafen infrastructure commands premium positioning in greenhouse supply chains. |
| Direct Cooperative Partnership | Bypassing independent agronomic advisors captures margin pools in Lower Saxony's centralized grain elevator networks. |
| EU Regulation 2019/1009 Pre-Compliance | Early claim validation positions products for premium tier access when amendments reshape market access requirements. |
| Precision Application Integration | Drone-based microbial delivery partnerships unlock variable-rate treatments in broad-acre cereal production. |
| Strain Library Acquisition | Captive Rhizobium and Trichoderma collections accelerate development velocity against formulation science talent scarcity. |
Research Methodology
Cross-validation between primary interviews with greenhouse operations managers, grain cooperative procurement committees, and regulatory affairs specialists at Germany's Federal Office of Consumer Protection and Food Safety anchors the qualitative findings. Secondary validation draws from EU Regulation 2019/1009 implementation documents, Julius Kühn-Institut field trial publications, and REACH substance evaluation timelines. Bottom-up triangulation of facility-level production data with top-down trade flow analysis ensures segment-level consistency.
Sensitivity analysis around regulatory amendment scenarios and raw material price volatility informs the analytical framework across the projection horizon. Segmentation dimensions modeled include product chemistry tier, crop system intensity, operational scale category, and federal state regulatory cluster. CAGRs derive from historical volume trajectory analysis adjusted for policy-driven demand inflection points. Strain efficacy validation rates and greenhouse retrofit investment cycles constitute industry-specific forecast inputs.
Material uncertainties — EU Regulation 2019/1009 reclassification outcomes, North Atlantic seaweed harvest variability, and microbial field performance consistency across soil microbiomes — sit outside the modeled envelope. Practitioners should keep alternative scenarios live as Farm to Fork Strategy implementation timelines and Federal Office registration backlog conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bio-Agriculture
United Kingdom Biopesticides Market
Bio-Agriculture
North America Feed Probiotics Market
Bio-Agriculture
Asia-Pacific Biocontrol Agents Market
Bio-Agriculture
Global Biofungicides Market
Bio-Agriculture
South America Biopesticides Market
Bio-Agriculture
China Biofuels Market
Bio-Agriculture
Bacterial Biopesticides Market
Bio-Agriculture
Biofibre Market
Bio-Agriculture
Marine Biotechnology Market
Bio-Agriculture
Bioherbicides Market
Bio-Agriculture
Silage Inoculant and Enzyme Market
Bio-Agriculture
Aquatic Animal Vaccines Market
Bio-Agriculture
China Biostimulants Market
Bio-Agriculture
Global Feed Phytobiotics Market
Bio-Agriculture
Ulva Lactuca Market
Bio-Agriculture
US Biofungicide Market