
 United States HVAC Equipment Market | 2026-2036
United States HVAC Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
United States HVAC Equipment Market Analytics
A chronic shortage of certified refrigeration technicians is unwinding installation capacity across the Southeast and Southwest, stretching project timelines and inflating service premiums. Carrier Global Corporation leverages its extensive dealer network and technician training academies to sustain market presence in residential retrofits. Trane Technologies anchors its competitive position through deep vertical integration into compressor manufacturing and controls engineering. Daikin Industries differentiates via inverter-driven heat pump technology leadership and regional distribution density.
United States HVAC Equipment encompasses climate control systems for heating, ventilation, air conditioning, and refrigeration, typically rated by seasonal energy efficiency ratio (SEER), heating seasonal performance factor (HSPF), and British thermal unit (BTU) output capacity, designed to maintain thermal comfort and indoor air quality across built environments. Heat pumps represent the fastest-expanding product category as cold-climate performance thresholds improve and electrification mandates tighten. Smart HVAC technology is displacing traditional thermostat-controlled systems in commercial retrofits, where building automation integration commands premium pricing. Residential application volume dominates unit shipments, though institutional segments generate higher per-project margins through complex specification requirements.
EPA refrigerant regulations under the AIM Act, DOE minimum efficiency standards, and ASHRAE 90.1 building energy codes collectively reshape equipment design cycles and procurement criteria across all end-user segments. DOE enforcement of elevated SEER ratings is forcing manufacturers to redesign coil architectures and compressor platforms ahead of compliance deadlines. Stakeholders must monitor state-level building electrification mandates and utility rebate structures, as these programs increasingly determine product mix and channel strategy faster than federal rulemaking alone.
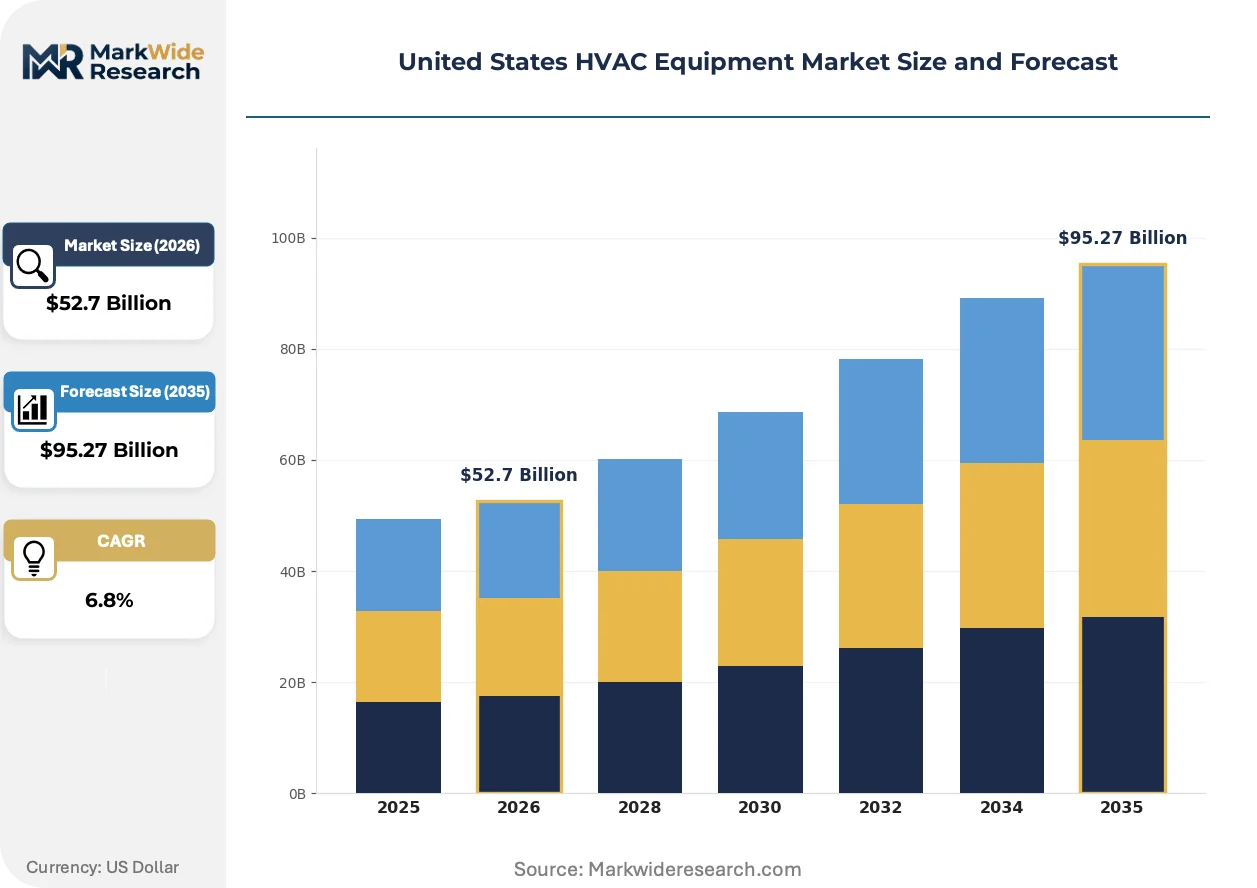
Market Dynamics
The EPA's phasedown of HFC refrigerants under the AIM Act is compressing equipment replacement timelines while simultaneously straining supply chains for alternative chemistries. This regulatory pressure intersects with electrification mandates across Sun Belt states to reshape procurement priorities.
Growth Catalysts
- Data Center Cooling:Hyperscale facilities in Texas and Virginia are deploying liquid-cooled rack architectures at scale, driving demand for high-tonnage chillers and precision air handlers.
- Building Electrification Mandates:California's Title 24 and New York's Local Law 97 are mandating heat pump adoption in new construction and major renovations.
- Utility Rebate Programs:Southeast utilities including Duke Energy and Southern Company are offering tiered incentives for cold-climate heat pump installations.
Market Restraints
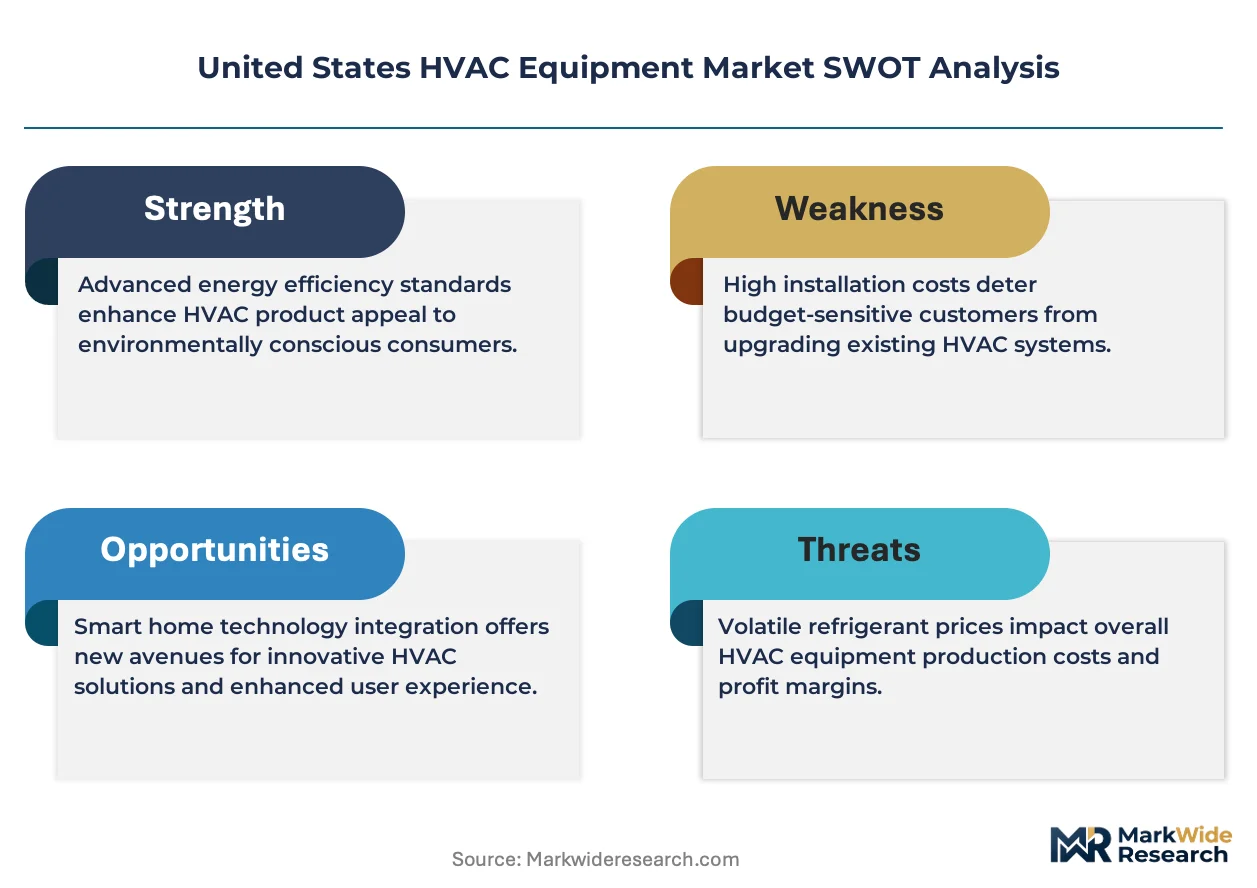
- Copper and Aluminum Volatility:Coil fabrication depends on base metal inputs subject to commodity price swings and tariff exposure.
- Compressor Supply Concentration:Scroll and rotary compressor manufacturing concentrates among a limited set of Asian suppliers, creating single-source risk.
- Low-GWP Refrigerant Scarcity:R-454B and R-32 supply chains remain immature relative to phasedown deadlines, constraining production ramp.
Strategic Opportunities
- Retrofit-Ready Cold-Climate Heat Pumps:DOE funding and IRA tax credits are expanding addressable market for single-digit Fahrenheit performance systems.
- Grid-Interactive Thermal Storage:Integration with utility demand response programs enables monetization of thermal mass in commercial buildings.
- Service-as-Revenue Models:Predictive maintenance contracts leveraging IoT sensor data are displacing break-fix service arrangements.
Industry Challenges
- EPA Section 608 Certification Bottlenecks:Technician training capacity lags equipment shipment growth, extending installation backlogs.
- Legacy Controls Integration:BACnet and Modbus protocol mismatches complicate smart thermostat deployment in existing commercial buildings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States HVAC Equipment Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Conditioners, Heat Pumps, Furnaces, Ventilation Systems Technology: Inverter Technology, Smart HVAC, Traditional Systems, Ductless Systems Application: Residential, Commercial, Industrial, Institutional End User: Homeowners, Contractors, Facility Managers, Building Owners |
| Companies Covered | Carrier Global Corporation, Trane Technologies, Daikin Industries, Lennox International, Johnson Controls, Rheem Manufacturing Company, Mitsubishi Electric, Nortek Air Solutions, AAON, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States HVAC Equipment Market Evolving Landscape
Electrification mandates and refrigerant transitions are forcing simultaneous redesign of thermal cycles, control systems, and service delivery models. Equipment manufacturers are racing to certify platforms ahead of compliance deadlines while building aftermarket capabilities.
Variable refrigerant flow systems are fragmenting the commercial rooftop unit segment. Large-format retail and hospitality operators are specifying multi-zone VRF for renovation projects where ductwork replacement proves cost-prohibitive. This technology is fragmenting procurement patterns away from traditional split-system specifications toward integrated design-build contracts.
ASHRAE 90.1-2022 appendices are tightening minimum efficiency thresholds for packaged terminal air conditioners. Equipment redesign cycles have compressed from five years to three as manufacturers chase successive rating point improvements. The multi-family residential segment faces the steepest compliance climb, triggering portfolio-wide replacement assessments by REITs.
Facility managers are consolidating vendor relationships around full-lifecycle service agreements. Integrated mechanical-electrical contractors are capturing specification influence previously held by specifying engineers. This concentration is most visible in the healthcare and education verticals, where capital planning cycles extend seven to ten years and favor single-source accountability.
United States HVAC Equipment Market Segmentation
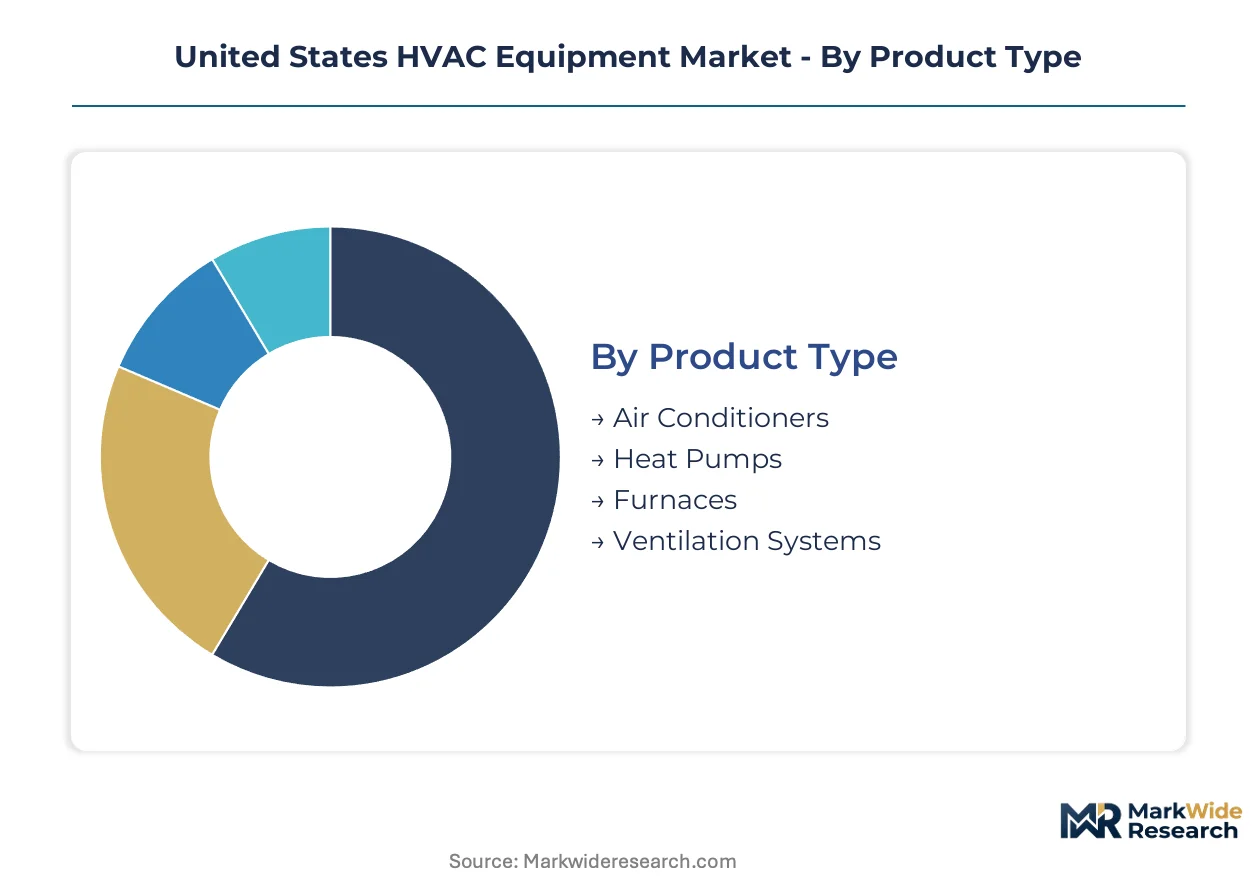
Segmentation in the United States HVAC Equipment Market reveals distinct procurement patterns across product architectures, control technologies, and building applications. Each dimension carries different margin profiles, regulatory exposure, and installation complexity that reshape channel strategy and manufacturer R&D allocation.
Product Type:
Heat pumps face the most acute substitution pressure from furnaces in legacy gas infrastructure regions, while refrigerant-phaseout timelines compress replacement cycles unevenly across equipment categories.
- Heat Pumps:Electrification mandates in California, New York, and Washington State are accelerating displacement of fossil-fuel heating systems. Cold-climate performance improvements below 5°F are expanding addressable markets into the Upper Midwest and Northeast, where natural gas dominance previously limited penetration.
- Air Conditioners:SEER rating escalations under DOE enforcement are forcing coil and compressor redesigns ahead of compliance deadlines. Demand concentrates in the Sun Belt, where Texas, Florida, and Arizona account for outsized replacement volume due to cooling-degree-day intensity and aging installed base.
- Furnaces:Gas-fired units retain dominance in existing residential stock, though municipal gas bans in Berkeley, Seattle, and New York City are constraining new-installation opportunity.
- Ventilation Systems:Energy recovery ventilators and heat recovery ventilators are gaining specification in tight-envelope construction meeting ASHRAE 62.2 standards.
Air conditioners anchor the volume base while heat pumps gain share at the steepest rate.
Technology:
Cost tier stratification separates premium inverter platforms from commodity traditional systems, with smart HVAC commanding installation premiums in commercial retrofits where building automation integration justifies expenditure.
- Inverter Technology:Variable-speed compressor modulation delivers part-load efficiency gains of 30-40% over fixed-speed alternatives. Cold-climate heat pump adoption depends on inverter-driven capacity maintenance at sub-freezing temperatures.
- Smart HVAC:IoT-enabled diagnostics and grid-interactive controls are displacing conventional thermostats in commercial buildings pursuing utility demand-response revenue. Integration complexity with legacy BACnet and Modbus protocols creates implementation friction in existing stock.
- Traditional Systems:Fixed-speed compressors and electromechanical controls retain price-positioning advantage in landlord-owned multifamily replacement cycles.
- Ductless Systems:Mini-split and multi-split configurations are fragmenting residential additions and retrofits where ductwork extension proves cost-prohibitive.
Traditional systems anchor the volume base while inverter technology climbs the fastest.
Application:
Customer type divergence separates price-sensitive residential homeowners from specification-driven institutional procurement teams, with margin concentration inversely correlated to transaction frequency.
- Residential:Unit shipment volume dominates industry output, though per-transaction margins compress in competitive retail and contractor channels. Heat pump adoption accelerates in new construction subject to Title 24 and comparable state codes.
- Commercial:Rooftop units and chillers face replacement pressure from VRF systems in renovation projects. Building automation integration commands premium pricing for packaged controls.
- Industrial:Process cooling and specialized environmental control sustain niche manufacturer relationships with extended service contracts.
- Institutional:Healthcare and education verticals generate highest per-project margins through complex specification requirements and seven-to-ten-year capital planning cycles.
Residential anchors the volume base while institutional expands most quickly on value terms.
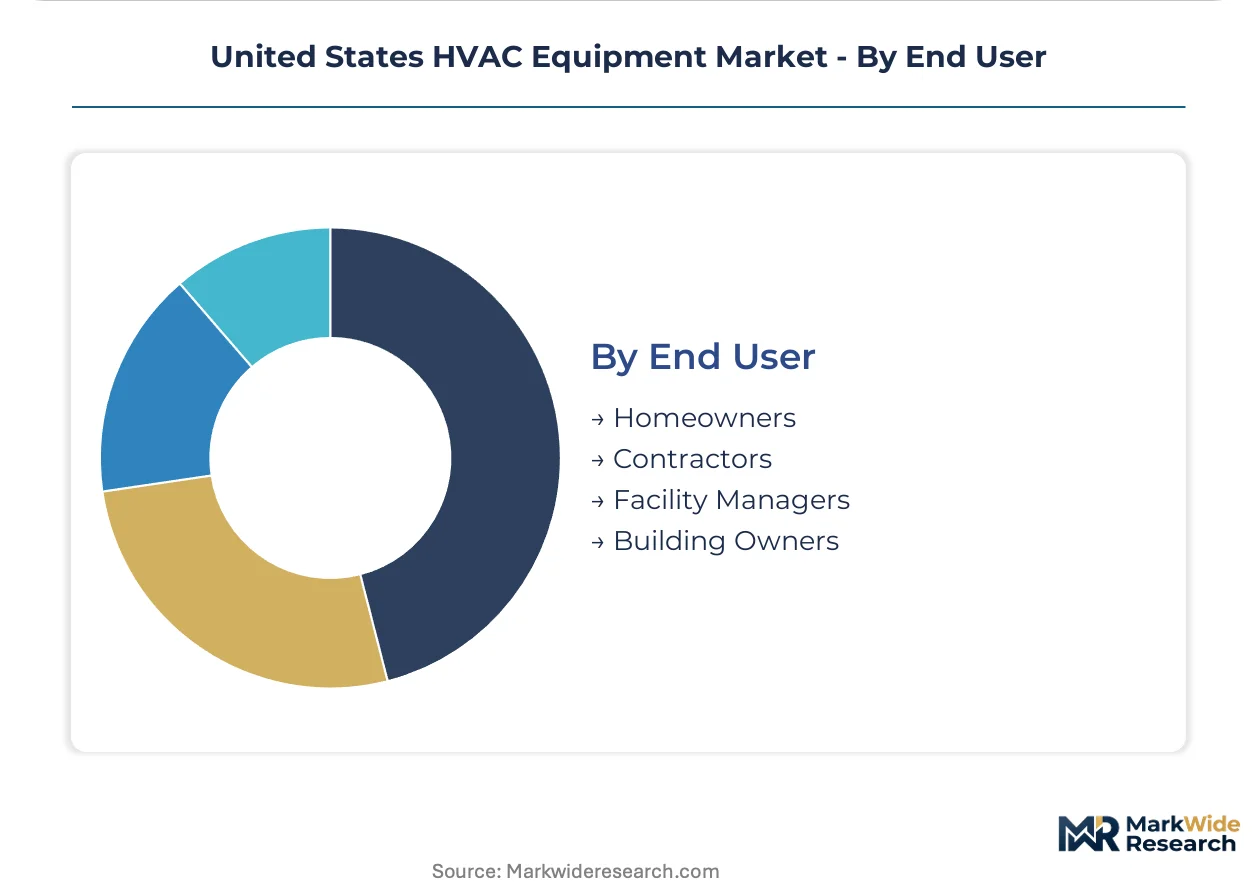
End User:
Supply concentration among certified refrigeration technicians creates procurement friction for homeowners and facility managers alike, with contractor channel relationships determining brand specification in residential retrofits.
- Homeowners:Replacement decisions concentrate in emergency failure scenarios, compressing research windows and privileging contractor recommendations over brand loyalty.
- Contractors:Dealer network relationships with Carrier, Trane, and Daikin determine residential specification influence. EPA Section 608 certification scarcity constrains installation capacity.
- Facility Managers:Full-lifecycle service agreements are consolidating vendor relationships around single-source accountability in healthcare and education.
- Building Owners:REITs and institutional portfolios are triggering portfolio-wide replacement assessments ahead of ASHRAE 90.1-2022 compliance deadlines.
Contractors anchor the volume base while facility managers gain procurement influence fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the Sun Belt states where cooling-degree-day intensity and aging installed bases sustain replacement premiums, while Northeast markets face margin compression from electrification mandates and contractor capacity constraints.
Texas
Hyperscale data center development in Dallas-Fort Worth and Austin drives demand for high-tonnage chillers and precision air handlers. EPA AIM Act phasedown timelines accelerate commercial equipment replacement cycles ahead of compliance deadlines. Houston's petrochemical corridor sustains industrial process cooling requirements through specialized environmental control systems.
Florida
Residential replacement volume dominates unit shipments due to salt-air corrosion shortening equipment lifespans in coastal counties. DOE SEER rating escalations force coil and compressor redesigns across the state's aging housing stock. Miami-Dade and Orlando metro areas concentrate commercial rooftop unit demand from hospitality and retail renovation projects.
California
Title 24 building codes mandate heat pump adoption in new construction and major renovations across the state's residential and commercial segments. IRA tax credits and utility rebate programs expand addressable markets for cold-climate performance systems. Silicon Valley data center clusters deploy liquid-cooled rack architectures requiring specialized precision cooling infrastructure.
Virginia
Northern Virginia's data center alley sustains demand for high-capacity chillers and air handling units serving hyperscale cloud facilities. ASHRAE 90.1-2022 compliance deadlines trigger portfolio-wide replacement assessments by institutional real estate owners. Richmond and Hampton Roads metro areas concentrate multi-family residential HVAC demand subject to tight-envelope ventilation requirements.
New York
Local Law 97 carbon emission caps drive building electrification mandates across commercial real estate portfolios in New York City. Utility rebate structures from Con Edison prioritize cold-climate heat pump installations in legacy gas infrastructure territories. Upstate manufacturing cities face contractor certification bottlenecks extending installation timelines for residential retrofits.
United States HVAC Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with premium inverter platforms and commodity fixed-speed systems occupying distinct competitive tiers. The market structure consolidates around integrated manufacturers with captive compressor supply and controls engineering capabilities against fragmented regional assemblers dependent on outsourced components. Three archetypes dominate: vertically integrated full-line manufacturers, specialist heat pump technology developers, and regional contract assemblers serving price-sensitive replacement cycles. Competitive intensity centers on M&A activity consolidating dealer networks and strategic partnerships securing alternative refrigerant supply chains ahead of phasedown deadlines.
Among the integrated manufacturer tier, Carrier Global Corporation, Trane Technologies, and Daikin Industries exemplify archetypes combining captive component production with extensive service infrastructure. These entities anchor competitive positioning through technician training capacity and aftermarket parts availability rather than equipment pricing alone. Their geographic footprints concentrate specification influence in residential retrofit channels where contractor relationships determine brand selection.
| Leading Market Players |
|---|
| Carrier Global Corporation |
| Trane Technologies |
| Daikin Industries |
| Lennox International |
| Johnson Controls |
| Rheem Manufacturing Company |
| Mitsubishi Electric |
| Nortek Air Solutions |
| AAON |
| Others |
Value Network & Pricing Analysis
Long-term capacity reservation agreements between major manufacturers and Asian compressor suppliers lock in both component access and price visibility across the 2026-2035 window. These contracts insulate Tier 1 OEMs from spot-market volatility while forcing smaller regional assemblers into higher-cost procurement channels.
Pricing Analysis
Configured-to-order pricing for precision cooling systems commands 35-50% premiums over standard packaged rooftop units. Three-tier pricing structure across premium inverter platforms, mid-grade heat pumps, and economy fixed-speed systems reflects SEER rating thresholds and smart control integration levels. Cost compression in the economy tier is intensifying because of commodity metal volatility and tariff exposure on coil assemblies. Residential homeowners in emergency replacement scenarios exhibit highest price sensitivity, while data center operators prioritize thermal performance over capital expenditure.
Supply Chain Analysis
Scroll compressor manufacturing concentration in Thailand, China, and South Korea creates single-source vulnerability for US equipment assemblers. Coil fabrication draws from copper cathode supplies anchored in Chile and Peru, plus aluminum sheet from domestic smelters. Tariff exposure on Chinese aluminum extrusions and Southeast Asian compressor imports threatens margin stability. Distribution runs through manufacturer-authorized dealer networks for residential retrofits, while commercial projects engage integrated mechanical-electrical contractors directly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States HVAC Equipment Market sits in early-cycle recovery following the post-pandemic installation backlog and refrigerant transition disruption. Replacement demand from aging installed base and regulatory compliance deadlines sustains volume visibility through the forecast window.
For Market Incumbents: Fortify technician training capacity ahead of EPA Section 608 certification bottlenecks that constrain installation throughput. Deepen backward integration into low-GWP refrigerant supply chains before AIM Act phasedown deadlines eliminate legacy chemistry options. Carrier, Trane, and Daikin dealer network density provides defensive moats against emerging heat pump specialists.
For New Entrants and Emerging Players: Anchor in cold-climate heat pump retrofits across the Upper Midwest, where natural gas infrastructure previously blocked penetration and contractor relationships remain unconsolidated. Target multi-family residential VRF installations in coastal Florida counties where salt-air corrosion accelerates replacement cycles. Pursue design-build contracting relationships with hospitality REITs seeking single-source accountability.
For Investors and Strategic Acquirers: Regional contract assemblers with EPA certification capacity and established utility rebate program navigation represent priority acquisition targets. Long-term viability hinges on refrigerant platform transition execution and IoT-enabled service revenue scaling. Watch DOE enforcement timing on SEER rating escalations as the inflection indicator for equipment replacement surge.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Training Academy Expansion | Carrier's dealer network investments address EPA Section 608 certification scarcity constraining Southeast installation capacity. |
| Low-GWP Refrigerant Supply Partnership | R-454B and R-32 procurement agreements with Chemours and Honeywell secure chemistry access ahead of AIM Act phasedown. |
| Cold-Climate Heat Pump Platform Launch | Daikin's inverter-driven systems below 5°F performance thresholds expand addressable market into legacy gas heating territories. |
| Grid-Interactive Thermal Storage Integration | Trane's utility demand response contracts monetize commercial building thermal mass through FERC-regulated frequency regulation markets. |
| VRF System Design-Build Capability | Mitsubishi Electric's multi-zone configurations capture hospitality renovation projects where ductwork replacement proves cost-prohibitive. |
Research Methodology
Operator-level perspectives from HVAC contractor owners, facility management directors, equipment manufacturer sales executives, and utility demand-side management officers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against EPA AIM Act regulatory filings, DOE appliance standards databases, EIA cooling-degree-day statistics, and utility rebate program disclosures. Bottom-up shipment modeling by equipment category and state triangulated against top-down market sizing from manufacturer revenue disclosures.
Sensitivity analysis across copper price scenarios, refrigerant supply disruption events, and technician training capacity constraints shaped the forecast envelope. Segmentation dimensions modeled include product architecture, inverter technology tier, building application, and end-user procurement channel. CAGRs derived from equipment replacement cycle analysis and regulatory compliance deadline clustering. Cold-climate heat pump performance threshold improvements and data center cooling load growth served as key demand-side inputs.
Material uncertainties — EPA enforcement timing on HFC phasedown, DOE SEER rating escalation schedules, and state-level electrification mandate adoption — sit outside the modeled envelope. Forecasts reflect assumptions regarding refrigerant supply chain maturation and contractor certification pipeline expansion. Practitioners should keep alternative scenarios live as utility rebate program funding levels and ASHRAE 90.1 code adoption timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
GCC Kitchen Hood Market
HVAC Equipment
US HVAC Field Device Market
HVAC Equipment
Global Portable Air Conditioner Market
HVAC Equipment
Global Air-To-Air Heat Pumps Market
HVAC Equipment
Global HVAC Packaged Unit Market
HVAC Equipment
France HVAC Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
Air-Cooled Heat Exchangers Market
HVAC Equipment
Wall Hung Boilers Market
HVAC Equipment
Industrial Blowers Market
HVAC Equipment
Europe Ventilation Equipment Market
HVAC Equipment
Underfloor Heating Market
HVAC Equipment
Europe Industrial Heat Pump Market
HVAC Equipment
Global Industrial Fans and Blowers Market
HVAC Equipment
Global HVAC Linesets Market