
 Asia-Pacific Heating Equipment Market | 2026-2036
Asia-Pacific Heating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Heating Equipment Market Outlook
Multi-source procurement among original equipment manufacturers is consolidating around fewer qualified component suppliers across the Asia-Pacific heating equipment supply base. Daikin Industries Limited leverages its inverter compressor technology to anchor premium heat pump positions in Japan and Southeast Asia. Mitsubishi Electric Corporation competes through deep manufacturing scale in chiller and air-source heat pump platforms across East Asian markets. LG Electronics Inc. differentiates via smart-home integration and connected thermostat ecosystems that extend its residential furnace and boiler offerings in South Korea and beyond.
Asia-Pacific heating equipment encompasses furnaces, boilers, heat pumps, and radiators designed to generate and distribute thermal energy for space conditioning and process applications, typically operating at efficiency ratings governed by regional minimum performance standards and refrigerant phase-down protocols. Heat pumps now command the fastest expansion trajectory within product type segments, driven by building electrification mandates and gas-grid restrictions in urban China and Korea. Electric and hybrid technology segments absorb disproportionate capital allocation as gas infrastructure expansion slows across Pacific Rim metropolitan clusters, while the residential end-user category sustains the largest installed base though commercial retrofit installations yield higher per-unit margins.
China's MEE enforces dual carbon compliance timelines that force boiler efficiency upgrades and refrigerant transitions across domestic manufacturing. Japan's METI Top Runner program and South Korea's KEMCO standards create tiered product certification barriers that filter market access for imported equipment. India's BIS energy labeling rules and Australia's MEPS alignment with IEC test methods add further compliance layers for pan-Asia distribution strategies. Stakeholders must monitor refrigerant quota allocations and carbon-border adjustment negotiations as these will determine which technology platforms receive preferential financing and project approval velocity across the region's divergent regulatory timelines.
Market Dynamics
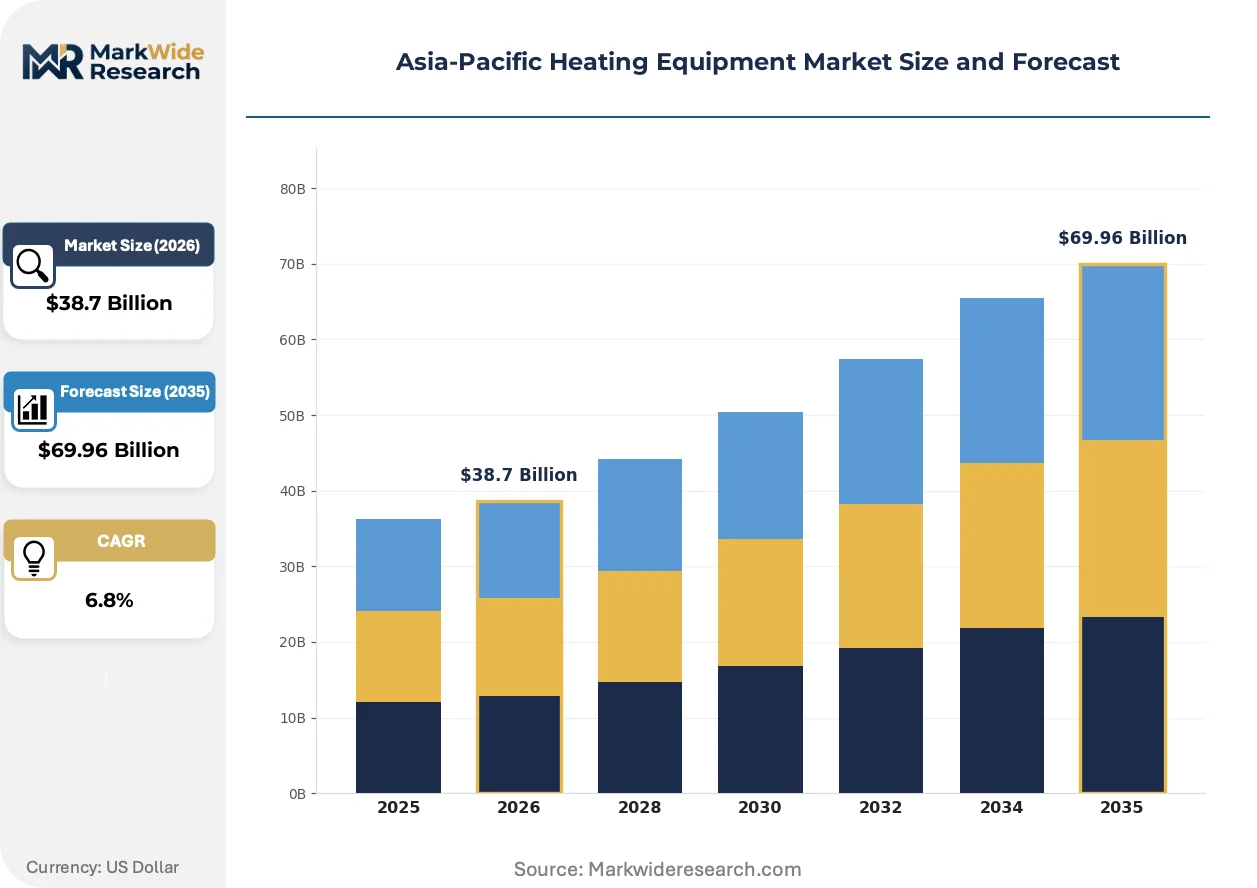
Japan's METI Top Runner program and China's MEE dual carbon mandates are compressing equipment replacement cycles across the Asia-Pacific heating equipment market, forcing manufacturers to accelerate refrigerant transitions and efficiency tier upgrades ahead of regulatory deadlines.
Growth Catalysts
- Building electrification mandates:China's northern provinces enforce district heating retrofits that absorb heat pump and high-efficiency boiler volumes. Seoul, Tokyo, and Singapore commercial developers expand procurement of air-source systems.
- KEMCO certification tiers:South Korea's energy efficiency standards create product differentiation pathways that reward inverter-driven heat pumps with preferential financing and building code credits.
- Refrigerant phase-down protocols:Regional alignment with IEC test methods and F-gas quota allocations accelerates R-32 and R-290 adoption in new equipment platforms.
Market Restraints
- Copper and rare-earth input volatility:Compressor motor laminations and heat exchanger tubing face price swings that compress OEM margins on fixed-price municipal contracts.
- Qualified supplier concentration:Inverter compressor and electronic expansion valve sourcing narrows to a handful of Japanese and Korean component specialists, creating single-source vulnerability.
- Gas infrastructure lock-in:Existing piped natural gas networks in China's established districts slow hybrid system penetration despite efficiency advantages.
Strategic Opportunities
- India's BIS labeling expansion:Mandatory energy performance disclosure for commercial boilers opens premium positioning for imported equipment meeting stricter test protocols.
- Smart-home convergence:Integration of heat pump controls with connected thermostat ecosystems creates recurring revenue streams through predictive maintenance subscriptions.
- Australia's MEPS alignment:Harmonized efficiency thresholds with IEC methods reduce certification duplication costs for pan-Asia product platforms.
Industry Challenges
- Refrigerant handling certification gaps:Installation networks across Southeast Asia lack sufficient technicians trained on flammable A2L and A3 refrigerant safety protocols.
- Legacy control integration:District heating operators in China's northern provinces struggle to interface modern variable-speed heat pumps with existing centralized SCADA architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Heating Equipment Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furnaces, Boilers, Heat Pumps, Radiators Technology: Electric, Gas, Solar, Hybrid End User: Residential, Commercial, Industrial, Institutional Installation: New, Retrofit, Replacement, Maintenance |
| Companies Covered | LG Electronics Inc., Whirlpool Corp., Daikin Industries Limited, ROBERT Bosch GmbH, Danfoss A/S, Mitsubishi Electric Corporation, Johnson Controls-Hitachi Air Conditioning, Emerson Electric Co., Panasonic Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Heating Equipment Market Strategic Shifts
Electrification mandates and refrigerant chemistry shifts are restructuring product development priorities across Asia-Pacific heating equipment, compressing the viable technology window for conventional combustion systems while expanding the addressable market for integrated thermal platforms.
Variable refrigerant flow heat pumps with dedicated outdoor air handling are expanding into high-rise residential towers across Seoul and Tokyo. Property developers specify these systems to meet local building energy codes while eliminating rooftop mechanical room requirements. The technology is expanding into mid-rise commercial retrofits previously served by centralized chillers, compressing the addressable market for water-cooled equipment in urban clusters.
China's MEE enforces dual carbon compliance timelines that force simultaneous boiler efficiency upgrades and refrigerant transitions across domestic manufacturing. Equipment producers must certify products under both GB energy efficiency standards and evolving refrigerant quota allocations. The commercial retrofit segment absorbs the bulk of compliance-driven procurement as building operators face mandatory replacement deadlines.
Buyer preference is consolidating around outcome-based thermal service contracts rather than equipment ownership. Japanese commercial real estate funds and Singaporean REITs now procure heating capacity through energy-as-a-service agreements that transfer operational risk to OEM-affiliated providers. This model is most visible in Tokyo's central business district, where district cooling and heating operators unbundle equipment capex from utility billing.
Asia-Pacific Heating Equipment Market Segmentation
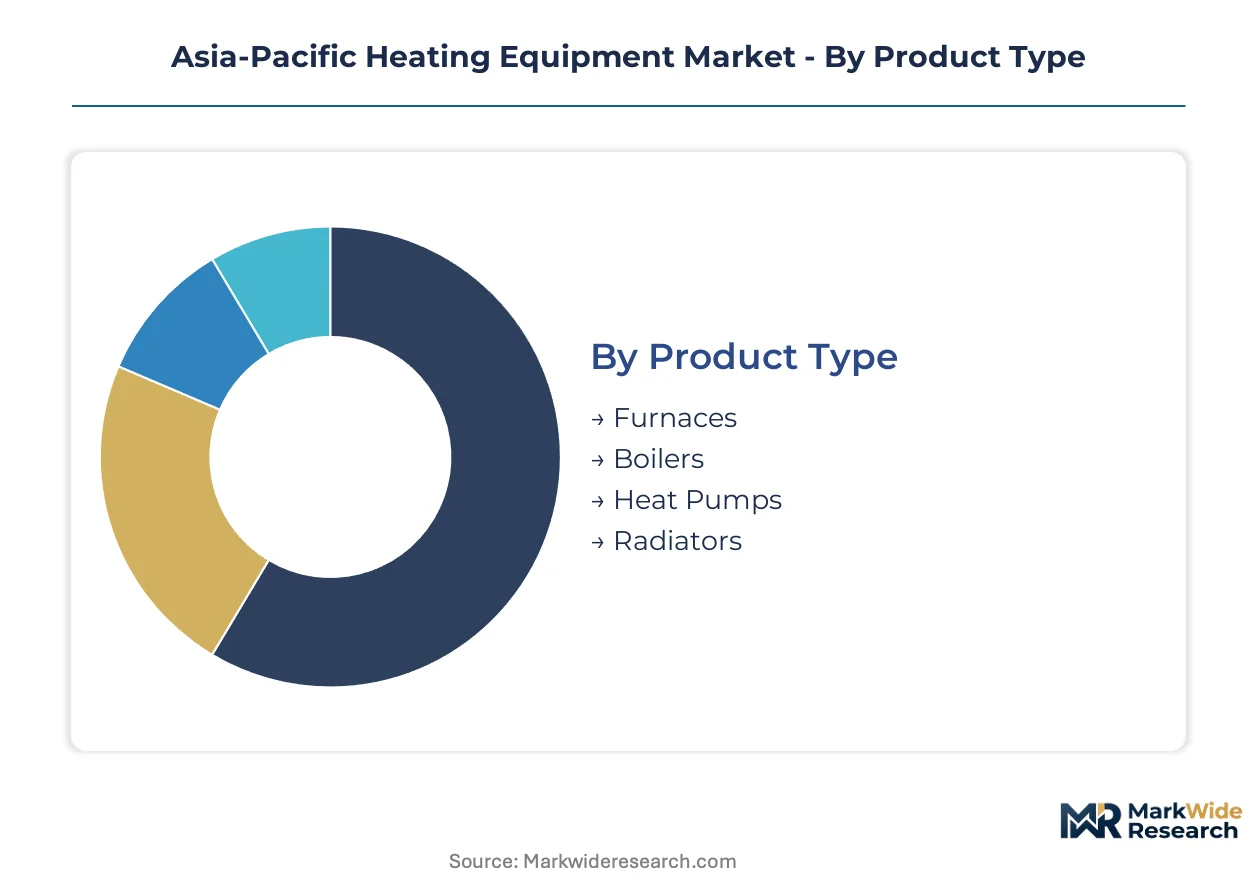
Segmentation across the Asia-Pacific heating equipment market reveals how regulatory pressure and infrastructure age dictate procurement patterns. Equipment replacement cycles vary dramatically by product maturity and local energy transition timelines.
Product Type:
Upgrade urgency separates segments with compressed replacement windows from those with extended service intervals.
- Heat Pumps:Inverter-driven air-source and water-source systems operate at coefficient of performance ratings exceeding 3.0 under IEC test protocols. China's northern provinces absorb the bulk of district heating retrofits as MEE dual carbon mandates force boiler displacement in Beijing, Tianjin, and Hebei municipalities.
- Boilers:Condensing gas and biomass-fired units remain entrenched in legacy building stock across Japan and South Korea. Seoul's commercial developers specify hybrid boiler-heat pump combinations to satisfy KEMCO certification tiers while maintaining backup thermal capacity.
- Furnaces:Forced-air combustion systems dominate Australian residential construction and Southeast Asian industrial process heating.
- Radiators:Panel and underfloor distribution equipment pairs with low-temperature heat pump circuits in Tokyo high-rise retrofits.
Volume placements concentrate in Boilers; the faster expansion belongs to Heat Pumps.
Technology:
Cost tier stratification separates premium electrified platforms from economy combustion alternatives.
- Electric:Resistance and vapor-compression systems eliminate on-site emissions. Australia's MEPS alignment with IEC methods reduces certification costs for pan-Asia electric platform distribution.
- Hybrid:Dual-fuel configurations combine electric heat pumps with gas boiler backup. Singaporean REITs procure these systems through energy-as-a-service contracts that transfer operational risk to OEM-affiliated providers.
- Gas:Natural gas and LPG combustion equipment faces grid lock-in constraints across China's established urban districts.
- Solar:Thermal collectors and photovoltaic-thermal hybrids serve niche applications in India's commercial sector under BIS labeling requirements.
Customer procurement concentrates in Gas; the steepest expansion trajectory belongs to Hybrid.
End User:
Application urgency varies by sector exposure to efficiency mandates and financing availability.
- Commercial:Office towers, retail complexes, and hospitality facilities face mandatory replacement deadlines under Japan's METI Top Runner program. Tokyo central business district operators unbundle equipment capex from utility billing through thermal service agreements.
- Residential:Single-family and multi-family dwellings sustain the largest installed base across the region. South Korean apartment complexes specify connected thermostat ecosystems that integrate with smart-home platforms.
- Industrial:Process heating and manufacturing facilities require high-temperature thermal output exceeding standard heat pump capabilities.
- Institutional:Schools, hospitals, and government buildings procure through municipal tender processes with fixed-price contract structures.
Volume placements concentrate in Residential; the fastest margin expansion belongs to Commercial.
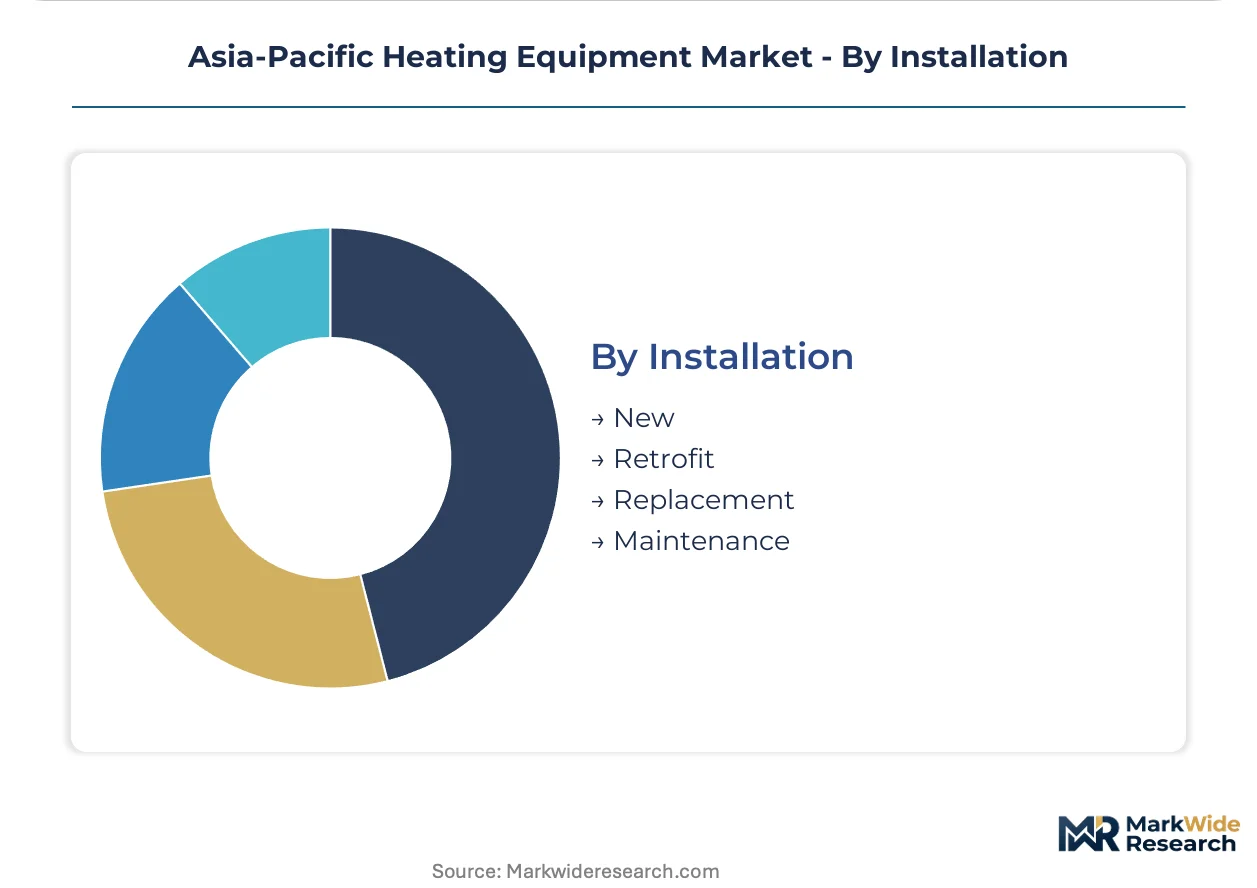
Installation:
Customer type distinguishes capex-heavy new construction from opex-driven service relationships.
- Retrofit:Equipment replacement in existing building envelopes demands compatibility with legacy distribution infrastructure. China's district heating operators struggle to interface modern variable-speed heat pumps with centralized SCADA architectures.
- Replacement:End-of-life equipment swaps follow compressed cycles under refrigerant phase-down protocols. F-gas quota allocations accelerate R-32 and R-290 adoption in equipment platforms across the region.
- New:Greenfield construction incorporates heat pump-ready specifications in Seoul and Tokyo high-rise developments.
- Maintenance:Service contracts and predictive maintenance subscriptions generate recurring revenue through connected equipment monitoring.
Procurement volume concentrates in Replacement; the expanding service opportunity belongs to Maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper concentrate flows from Chile and Indonesia anchor compressor manufacturing supply chains across East Asia. Rare-earth processing clusters in Jiangxi and Inner Mongolia feed permanent magnet motor production for inverter-driven heat pumps. These material geographies shape equipment cost structures and regional procurement priorities.
China
District heating retrofits in Beijing, Tianjin, and Hebei municipalities absorb the bulk of heat pump and high-efficiency boiler volumes. MEE dual carbon mandates enforce simultaneous efficiency upgrades and refrigerant transitions under GB standards. Manufacturing concentrates in the Yangtze River Delta and Pearl River Delta where OEMs face compressed certification deadlines.
Japan
Tokyo commercial real estate funds procure heating capacity through energy-as-a-service agreements that transfer operational risk to providers. METI Top Runner program tiers create product certification barriers filtering market access for imported equipment. Kanto and Kansai industrial corridors house inverter compressor specialists supplying regional OEM networks.
South Korea
Seoul apartment complexes specify connected thermostat ecosystems integrating with smart-home platforms. KEMCO certification tiers reward inverter-driven heat pumps with preferential financing and building code credits. Busan-Ulsan manufacturing bases anchor chiller and air-source heat pump production for domestic and export markets.
Australia
Forced-air combustion systems dominate residential construction across New South Wales and Victoria. MEPS alignment with IEC test methods reduces certification duplication costs for pan-Asia electric platform distribution. Queensland and Western Australia mining corridors sustain industrial process heating demand.
India
Mandatory BIS energy performance disclosure for commercial boilers opens premium positioning for imported equipment meeting stricter test protocols. Maharashtra and Gujarat industrial zones drive process heating procurement through municipal tender structures. Delhi-NCR commercial retrofits face efficiency disclosure requirements accelerating equipment replacement cycles.
Asia-Pacific Heating Equipment Market Competitive Environment
Global majors compete with regional champions across technology licensing and component supply relationships. Market structure shows moderate consolidation around Japanese and Korean OEMs controlling inverter compressor sourcing, with European specialists holding positions in control systems and hydronic distribution. Three archetypes dominate: integrated conglomerates with captive component production, specialized heat pump platform developers, and controls-focused subsystem suppliers. Competitive moves center on strategic partnerships for refrigerant transition readiness and capacity expansion in Southeast Asian assembly locations.
Among Korea-based conglomerates, LG Electronics Inc. occupies a position emphasizing connected ecosystem integration. Japanese integrated manufacturers exemplified by Daikin Industries Limited and Mitsubishi Electric Corporation anchor premium-tier heat pump positions through captive compressor technology. These three represent the dominant competitive archetypes shaping procurement relationships with Seoul, Tokyo, and Singapore commercial developers.
| Leading Market Players |
|---|
| LG Electronics Inc. |
| Whirlpool Corp. |
| Daikin Industries Limited |
| ROBERT Bosch GmbH |
| Danfoss A/S |
| Mitsubishi Electric Corporation |
| Johnson Controls-Hitachi Air Conditioning |
| Emerson Electric Co. |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
Sovereign-backed producers across China and South Korea anchor compressor manufacturing, translating state-supported capacity expansion into disciplined pricing power that resists margin erosion despite copper and rare-earth volatility. Their captive access to Jiangxi rare-earth processing and Yangtze River Delta assembly infrastructure lets these entities absorb input cost swings without passing full burden to municipal tender winners.
Pricing Analysis
Warranty bundling separates premium Japanese OEMs from Korean and Chinese competitors, with Tokyo-based manufacturers including predictive maintenance subscriptions while Seoul and Shanghai rivals price equipment-only for retrofit tenders. Three-tier pricing structure across premium, standard, and economy levels maps to KEMCO certification tiers and METI Top Runner bands, with inverter-driven heat pumps commanding financing advantages. Cost compression in economy condensing boilers is intensifying because fixed-price municipal contracts in China's northern provinces lock in margins. Institutional buyers through district heating operators show highest price sensitivity; Singaporean REITs procuring through energy-as-a-service agreements demonstrate lowest.
Supply Chain Analysis
Container freight rates from Busan-Ulsan manufacturing bases to Southeast Asian project sites dictate landed cost competitiveness for Korean OEMs serving Indonesian and Vietnamese retrofit demand. Component sourcing draws from Japan for inverter compressors, South Korea for electronic expansion valves, and China for heat exchanger tubing. Single-source vulnerability concentrates in Japanese and Korean inverter motor laminations. Distribution runs through OEM-affiliated service networks for commercial retrofits and wholesale channels for residential replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MEE dual carbon mandates erect a compliance moat that favors incumbents with certified R-32 and R-290 platforms while screening out undercapitalized entrants lacking refrigerant transition readiness.
For Market Incumbents: Lock in component supply through captive or long-term agreements with Jiangxi rare-earth processors and Japanese inverter specialists before quota allocations tighten. Accelerate certification investment under Australia's MEPS alignment to reduce pan-Asia platform duplication costs. Defend against emerging Chinese OEMs by controlling electronic expansion valve sourcing channels. For New Entrants and Emerging Players: Begin with India's BIS labeling expansion for commercial boilers, where mandatory energy disclosure creates positioning space for imported equipment meeting stricter IEC test protocols. Target Southeast Asian maintenance service contracts as the most penetrable segment given refrigerant handling certification gaps. Pursue OEM partnership routes rather than direct manufacturing to bypass compressor supply concentration. For Investors and Strategic Acquirers: METI Top Runner tier advancement announcements from Japanese manufacturers are the leading indicator that premium heat pump positioning is consolidating. Five-to-ten year viability favors controls-focused subsystem suppliers with software-defined thermal service capabilities. Acquisition targets should show integrated thermostat ecosystem development and recurring revenue from predictive maintenance subscriptions.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Transition | R-32 and R-290 adoption ahead of F-gas quotas secures MEE compliance in Beijing-Tianjin-Hebei clusters. |
| Inverter Compressor Supply Agreement | Long-term contracts with Kanto and Kansai specialists reduce single-source vulnerability for Korean OEMs. |
| Energy-as-a-Service Launch | Thermal service contracts transfer operational risk to OEM-affiliated providers serving Singaporean REITs. |
| Smart-Home Control Integration | Connected thermostat ecosystems generate recurring revenue through predictive maintenance subscriptions in Seoul apartments. |
| Southeast Asian Assembly Expansion | Busan-Ulsan manufacturers establish Vietnamese and Indonesian production to shorten freight legs for retrofit demand. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with OEM procurement directors, district heating operators in Beijing and Tianjin, KEMCO certification specialists, and commercial real estate fund managers in Tokyo and Singapore. KEMCO efficiency databases, China's MEE dual carbon compliance disclosures, Japan's METI Top Runner product registries, and Australia's MEPS alignment documentation provided segmentation benchmarks. Bottom-up equipment shipment analysis triangulated against top-down construction spend and energy efficiency retrofit allocations.
Reconciliation of import-export statistics with OEM production disclosures and municipal tender awards generated volume baselines across product type, technology, and end-user dimensions. Modeled segmentation captured heat pump versus boiler displacement rates, electric-hybrid-gas technology mix shifts, and residential-commercial-industrial procurement splits. CAGRs derived from regression against regulatory deadline schedules and building stock turnover rates. Forecast inputs included refrigerant quota allocation trajectories and copper concentrate price indices from Chilean and Indonesian supply sources.
Underlying measurement precision varies by segment; heat pump and district heating retrofit volumes carry tighter precision than industrial furnace and Southeast Asian maintenance service estimates. Forecasts reflect assumptions about MEE enforcement consistency, KEMCO tier advancement timing, and F-gas quota implementation. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
Middle East and Africa Commercial HVAC Market
HVAC Equipment
Equipment Fan Filter Unit (EFU) Market
HVAC Equipment
ASEAN Heat Exchanger Market
HVAC Equipment
Global Submerged Coil Heat Exchanger Market
HVAC Equipment
Centrifugal Fan Wheels Market
HVAC Equipment
United Kingdom District Heating Market
HVAC Equipment
US Residential HVAC Systems Market
HVAC Equipment
Air Volume Controllers Market
HVAC Equipment
Industrial Insulation Testers Market
HVAC Equipment
Desert Air Cooler Market
HVAC Equipment
North America HVAC Filter Change Service Market
HVAC Equipment
China Commercial HVAC Market
HVAC Equipment
Canada Commercial HVAC Market
HVAC Equipment
Compressor Controllers Market
HVAC Equipment
North America Commercial HVAC Market
HVAC Equipment
Duct Fans Market