
 Europe Commercial HVAC Market | 2026-2036
Europe Commercial HVAC Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial HVAC Market Insights
The split between premium and commodity tiers in Europe commercial HVAC is hardening around refrigerant transition readiness and digital control integration. Daikin Industries leverages its VRF technology leadership to command premium positioning across Nordic and DACH markets. Bosch Thermotechnology anchors its competitiveness through deep manufacturing integration in German heat pump production. Carrier Corporation differentiates via extensive service networks that lock in long-term maintenance contracts across French and Italian installations.
Europe commercial HVAC encompasses climate control systems designed for non-residential buildings, typically operating at capacities from 5 kW to over 5,000 kW and utilizing vapor-compression or absorption cycles to regulate temperature, humidity, and air quality for occupant comfort and equipment protection. These systems integrate chillers, rooftop units, heat pumps, and variable refrigerant flow configurations to serve diverse building footprints and load profiles across office, retail, healthcare, and education facilities. Heat pumps are capturing disproportionate investment as building decarbonization targets elevate electrification over fossil-fuel heating across Northern European markets. Smart HVAC technology is expanding fastest where EU building performance standards mandate automated energy monitoring and demand-responsive control systems. Rooftop units remain structurally mature in Southern European climates but face replacement pressure from modular heat pump alternatives.
The EU F-Gas Regulation and Ecodesign Directive are restricting refrigerant selections and minimum efficiency thresholds, compelling manufacturers to redesign core platforms and certify new product lines for market access. EMA guidelines on indoor air quality in healthcare settings and national transpositions of the Energy Performance of Buildings Directive are layering additional compliance requirements onto hospital and educational procurement specifications. Stakeholders must monitor how the EU AI Act intersects with autonomous building management algorithms, as compliance costs for smart HVAC control systems could reshape vendor competitive dynamics before the next product replacement cycle peaks.
Market Dynamics
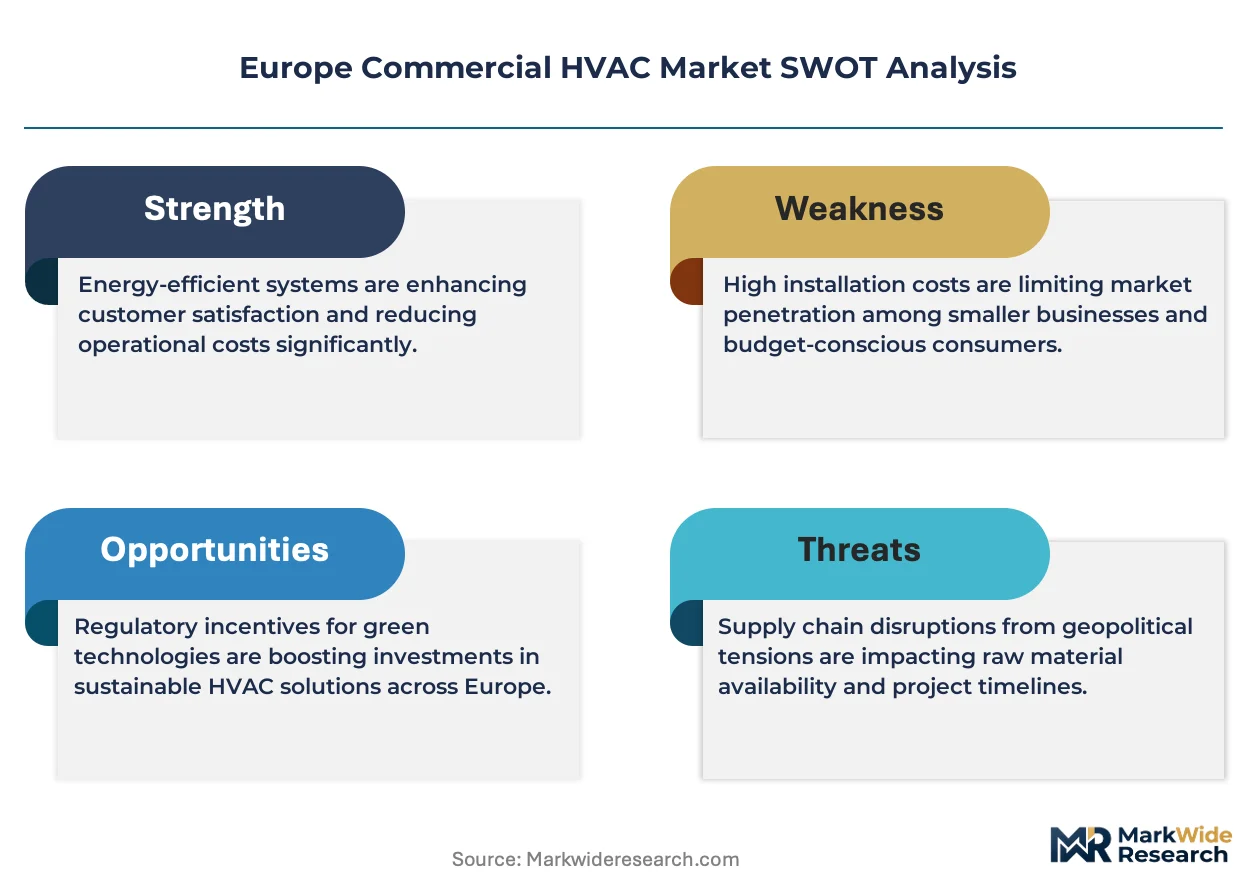
The EU F-Gas Regulation is compressing refrigerant choices across European commercial HVAC, forcing manufacturers to redesign chiller platforms and recertify product lines for market access before replacement cycles peak in Germany, France, and the Netherlands.
Growth Catalysts
- Building Energy Renovation Mandates:Germany's tightening enforcement timelines for commercial real estate energy upgrades are accelerating chiller replacement cycles in office corridors across Berlin, Frankfurt, and Munich.
- Heat Pump Electrification:Northern European building decarbonization targets are elevating electrified heating over fossil-fuel systems, concentrating investment in vapor-compression heat pump configurations.
- Indoor Air Quality Standards:EMA guidelines on healthcare ventilation are layering procurement specifications onto hospital HVAC systems in France, Italy, and Spain.
Market Restraints
- Refrigerant Supply Concentration:Lower-GWP alternative production capacity concentrates among specialized chemical suppliers, creating input bottlenecks for chiller manufacturers retooling product lines.
- Copper and Aluminum Volatility:Heat exchanger material costs fluctuate with commodity markets, compressing margins on standardized rooftop units and modular heat pump systems.
- F-Gas Phase-Down Friction:The EU F-Gas Regulation's quota system creates compliance timeline mismatches between refrigerant availability and equipment certification deadlines.
Strategic Opportunities
- Smart Building Integration:The EU AI Act intersects with autonomous building management algorithms, creating first-mover advantage for vendors with pre-certified control system architectures.
- Healthcare Vertical Expansion:EMA air quality mandates and national EPBD transpositions are expanding specification-driven procurement in hospital and educational facilities across Italy and Spain.
- Service Network Unbundling:Long-term maintenance contract structures in French and Italian installations create channel innovation space for predictive analytics platforms.
Industry Challenges
- Refrigerant Technician Certification:Lower-GWP system handling requires specialized training programs that lag behind equipment deployment timelines in the Netherlands and Belgium.
- Legacy Control Integration:Automated energy monitoring mandates under EU building performance standards create friction when interfacing with existing building management systems in aging French office stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial HVAC Market |
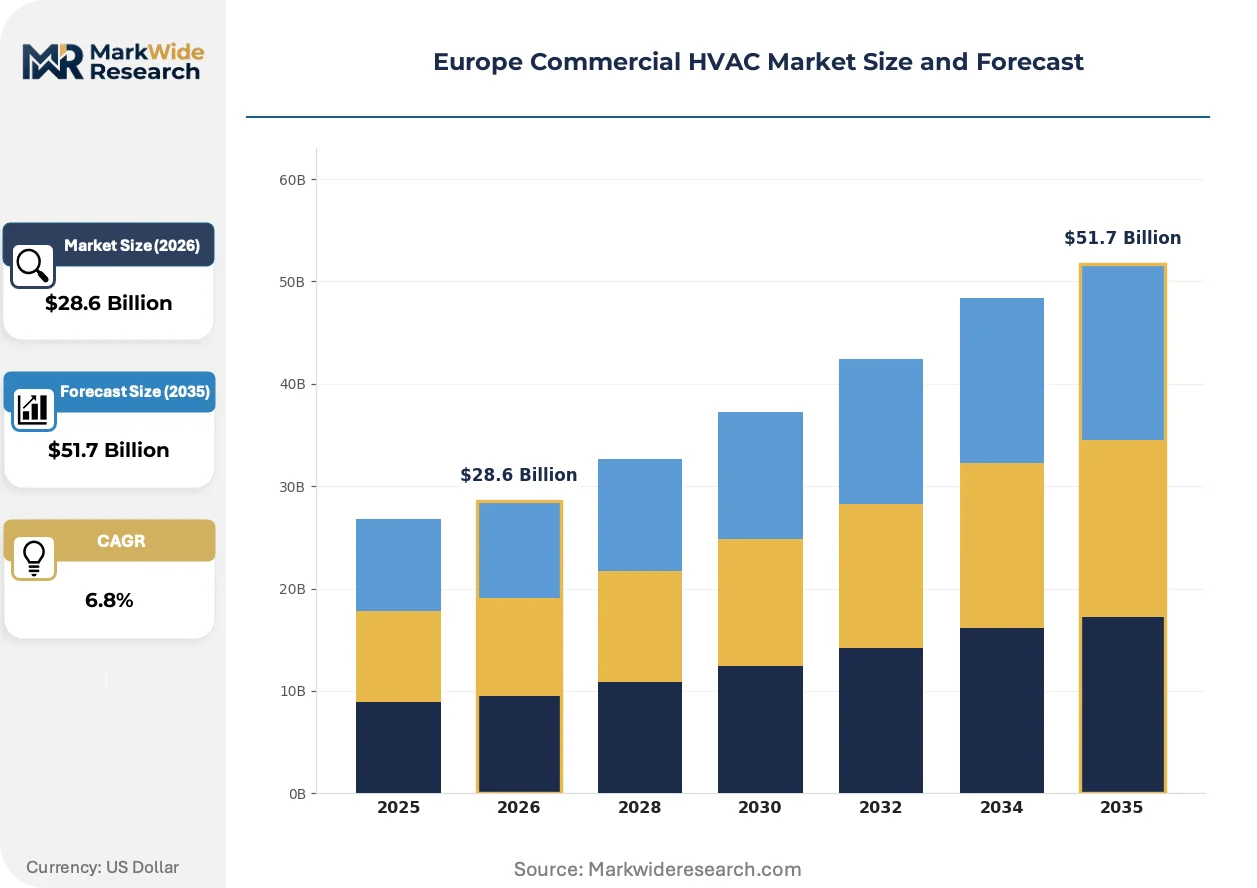
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chillers, Rooftop Units, Heat Pumps, Variable Refrigerant Flow Installation Type: New Construction, Renovation, Replacement, Retrofits End User: Office Buildings, Retail Spaces, Educational Institutions, Hospitals Technology: Smart HVAC, Traditional HVAC, Renewable Energy, Hybrid Systems |
| Companies Covered | Daikin Industries Ltd., Bosch Thermotechnology GmbH, Vaillant Group, Johnson Controls, Carrier Corporation, Mitsubishi Electric Corporation, Systemair AB, Aermec SpA, Danfoss A/S, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial HVAC Market Trends and Innovations
Electrification and digitalization are converging to reshape equipment specifications, refrigerant chemistry, and procurement structures across European commercial HVAC installations.
Heat pump technology is electrifying commercial heating infrastructure across Northern European markets. These systems extract thermal energy from ambient air, water, or ground sources to deliver space heating and domestic hot water at efficiencies exceeding conventional combustion equipment. Office developers in Germany, the Netherlands, and Denmark are specifying heat pumps for new construction and deep renovation projects at accelerating rates. This transition is electrifying building thermal loads and compressing demand for gas-fired boilers and direct electric resistance heating in commercial segments.
The EU F-Gas Regulation is mandating refrigerant transitions with cascading industrial consequences. This framework quotas hydrofluorocarbon production and bans specific high-GWP refrigerants in new equipment categories on fixed timelines. Chiller and rooftop unit manufacturers must redesign compressor architectures, heat exchanger sizing, and safety systems to accommodate mildly flammable lower-GWP alternatives. Southern European markets with mature rooftop unit installed bases face the steepest reconfiguration requirements as replacement cycles compress against regulatory deadlines.
Facility managers are consolidating vendor relationships around full-service energy performance contracts. This procurement evolution displaces transactional equipment purchasing with multi-year agreements bundling installation, monitoring, optimization, and maintenance. French and Italian commercial real estate portfolios are leading this transition, driven by EPBD compliance cost certainty requirements and internal carbon accounting pressures. The shift concentrates specification authority among energy service companies and dilutes traditional equipment distributor influence in project origination.
Europe Commercial HVAC Market Segmentation
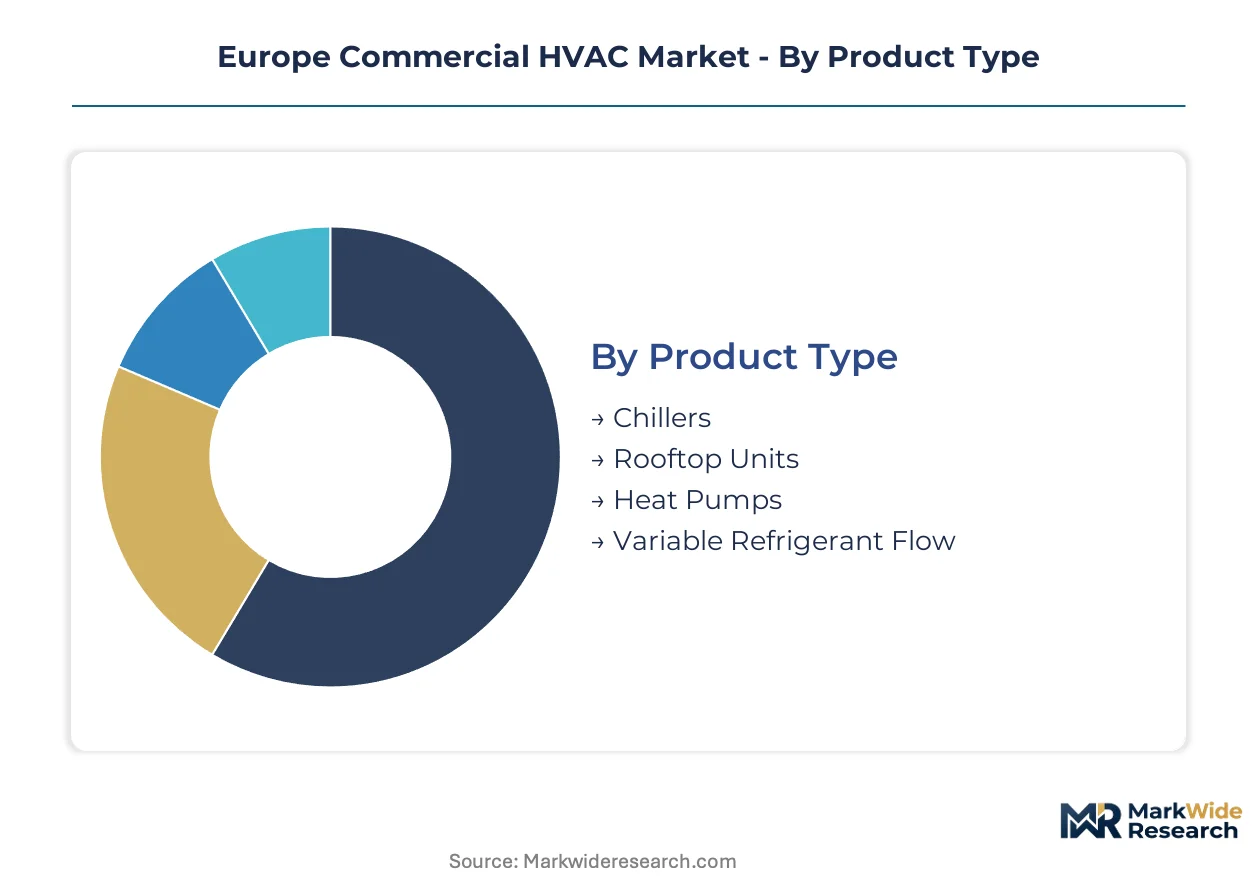
Equipment specifications diverge sharply across European commercial HVAC segments as refrigerant transitions and electrification mandates reshape procurement priorities. Capital allocation patterns now favor platforms with lower-GWP refrigerant compatibility and integrated digital controls over legacy infrastructure.
Product Type:
Chillers demand the highest upfront capital deployment given their centralized architecture and custom engineering requirements for large commercial footprints.
- Chillers:Centralized vapor-compression or absorption systems operating above 500 kW capacity serve district cooling networks and large office complexes. German and French developers are accelerating replacement timelines for aging centrifugal and screw chiller fleets ahead of F-Gas quota reductions.
- Heat Pumps:Vapor-compression equipment extracting thermal energy from air, water, or ground sources delivers space heating at coefficients of performance exceeding conventional combustion. Northern European markets in Denmark, Sweden, and the Netherlands are specifying these for new construction and deep renovation at accelerating rates.
- Rooftop Units:Packaged systems combining heating, cooling, and ventilation in weather-resistant enclosures dominate Southern European commercial stock.
- Variable Refrigerant Flow:Modular refrigerant-based systems enable zoned temperature control across disparate building loads without ductwork infrastructure.
Most installed capacity flows through chillers. Expansion is steepest in heat pumps.
Installation Type:
Replacement projects concentrate investment volume as regulatory deadlines compress decision timelines for aging equipment.
- Replacement:Direct equipment swaps addressing end-of-life chillers and rooftop units dominate procurement in Germany's commercial corridors. Berlin, Frankfurt, and Munich office portfolios face tightening enforcement of building energy renovation mandates.
- Renovation:Deep building upgrades integrating HVAC with envelope improvements and controls modernization capture public subsidy flows. French and Dutch commercial real estate operators are bundling electrification with facade and glazing improvements.
- New Construction:Greenfield installations specify heat pump and VRF configurations from design phase.
- Retrofits:Control system and refrigerant upgrades without full equipment replacement address interim compliance needs.
Replacement commands the largest project value per site. Renovation is climbing the fastest as subsidy programs deepen.
End User:
Healthcare and education facilities impose the most stringent specification requirements due to indoor air quality mandates and occupancy-critical operations.
- Hospitals:Ventilation systems for operating theaters, patient wards, and pharmaceutical storage demand continuous operation with filtration and humidity control. EMA guidelines on healthcare indoor air quality are layering procurement specifications onto French, Italian, and Spanish hospital HVAC tenders.
- Office Buildings:Climate control for open-plan and cellular workspaces prioritizes energy efficiency and demand-responsive operation. Germany's commercial corridors in Berlin, Frankfurt, and Munich are driving chiller replacement volume.
- Educational Institutions:Schools and universities balance capital constraints against tightening EPBD compliance deadlines.
- Retail Spaces:Shopping centers and big-box formats emphasize rapid installation and modular capacity scaling.
Hospitals anchor premium pricing tiers. Office buildings generate the highest equipment volume.
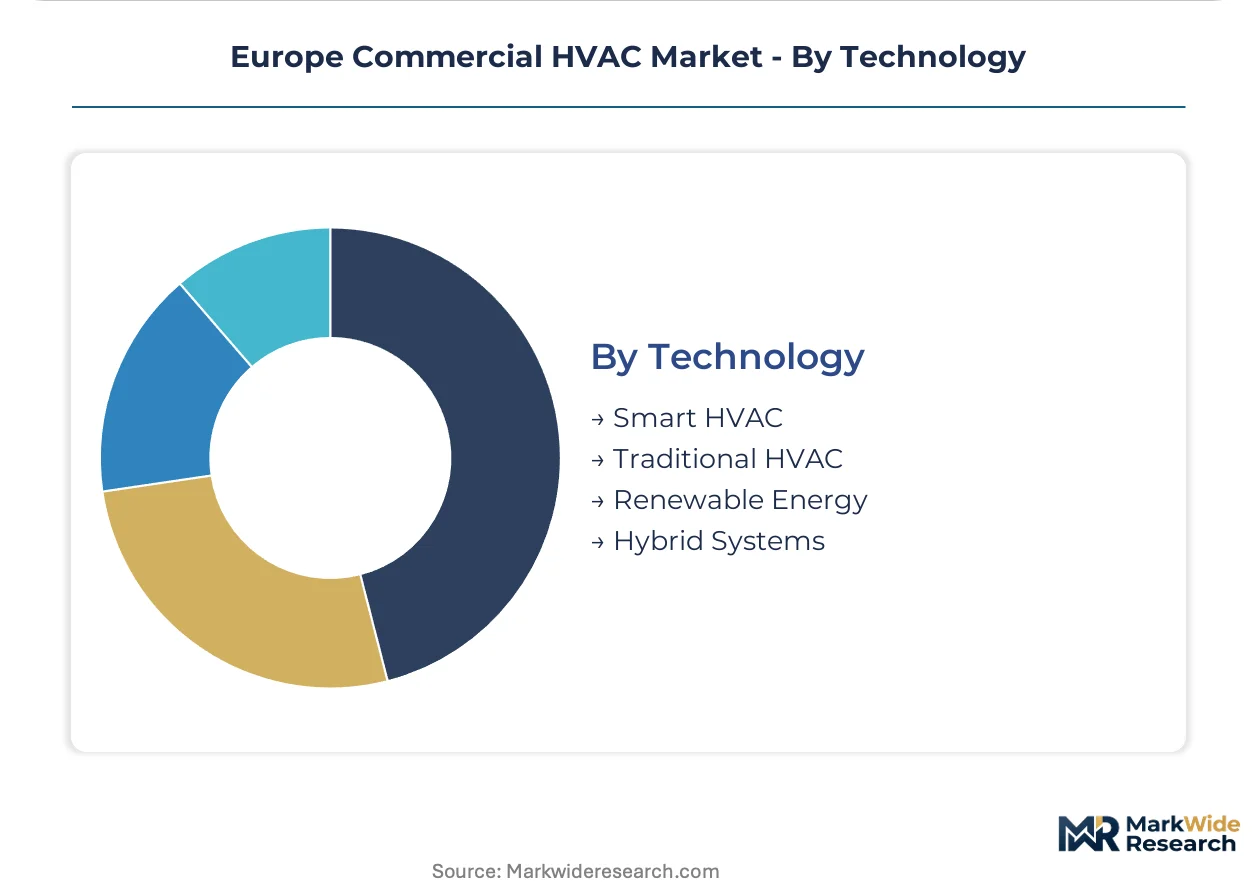
Technology:
Smart control architectures command margin premiums through energy monitoring compliance and predictive maintenance capabilities.
- Smart HVAC:Automated systems with IoT sensors, machine learning optimization, and cloud-based analytics enable demand-responsive operation and fault detection. The EU AI Act is creating certification requirements for autonomous building management algorithms that vendors must address.
- Hybrid Systems:Configurations combining heat pumps with thermal storage and auxiliary combustion balance electrification with peak-load resilience.
- Traditional HVAC:Conventional electromechanical controls without networked intelligence dominate aging installed base.
- Renewable Energy:Solar thermal and geothermal integration reduces operational carbon intensity for on-site generation.
Smart HVAC is gaining specification share fastest. Traditional systems retain the largest installed base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany outpaces France in commercial HVAC replacement volume, while the Netherlands compresses project timelines more aggressively than Belgium. National enforcement of EU directives varies sharply, fragmenting procurement rhythms across the region.
Germany
Berlin, Frankfurt, and Munich office corridors drive chiller replacement demand as building energy renovation mandates tighten enforcement timelines. The Federal Building Energy Act transposes EPBD requirements into binding municipal compliance schedules. Bavaria's commercial real estate clusters face accelerated equipment swap decisions ahead of F-Gas quota reductions.
France
Healthcare ventilation upgrades dominate procurement as EMA indoor air quality guidelines layer specifications onto hospital tenders. The national transposition of the Energy Performance of Buildings Directive binds educational and public facilities to renovation deadlines. Île-de-France commercial portfolios concentrate energy service company contracting for bundled HVAC modernization.
Netherlands
Heat pump electrification accelerates fastest here as gas grid phase-out policies harden building decarbonization targets. The national F-Gas implementation tightens refrigerant handling certification requirements ahead of equipment deployment waves. Randstad urban corridors concentrate deep renovation projects integrating envelope improvements with HVAC replacement.
Italy
Hospital and educational facility procurement expands under EMA air quality mandates and regional EPBD enforcement. The national recovery plan channels subsidy flows toward building energy upgrades in public infrastructure. Northern industrial districts around Milan and Turin anchor premium equipment specification for manufacturing facility climate control.
Spain
Rooftop unit replacement pressure intensifies as mature Southern European installed bases face F-Gas regulatory deadlines. The national climate law transposes EU building performance standards into commercial renovation requirements. Madrid and Barcelona commercial corridors concentrate service network competition for long-term maintenance contract structures.
Europe Commercial HVAC Market Competitive Landscape
Top-tier vendors anchor premium positioning through refrigerant transition readiness, while mid-tier fabricators compete on retrofit compatibility and regional service density. The vendor base stratifies across three functional tiers: full-system integrators with captive control technology, heat pump specialists with manufacturing depth in electrified platforms, and modular equipment suppliers serving standardized replacement cycles. Consolidation pressure concentrates among mid-scale European fabricators lacking lower-GWP refrigerant certification timelines. Strategic moves cluster on vertical integration into compressor manufacturing and predictive analytics platform licensing.
Within the full-system integrator tier, Daikin Industries Ltd. and Carrier Corporation exemplify archetypes built on control technology and service network scale respectively. Bosch Thermotechnology GmbH anchors the heat pump specialist vector with manufacturing integration depth. These three occupy positions that illustrate how refrigerant transition readiness and digital platform maturity stratify competitive positioning across German, French, and Dutch procurement channels.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Bosch Thermotechnology GmbH |
| Vaillant Group |
| Johnson Controls |
| Carrier Corporation |
| Mitsubishi Electric Corporation |
| Systemair AB |
| Aermec SpA |
| Danfoss A/S |
| Others |
Pricing and Supply Chain Analysis
Refrigerant technician certification concentration in the Netherlands and Belgium compresses labor-cost differentials between premium and commodity HVAC tiers, widening pricing spreads as F-Gas handling requirements layer specialized skill premiums onto lower-GWP system deployments.
Pricing Analysis
The bundled-vs-unbundled service split stratifies European commercial HVAC procurement, with full-service energy performance contracts commanding premiums over transactional equipment sales. Pricing separates refrigerant-transition-ready platforms with integrated digital controls from legacy rooftop configurations, with German office developers showing lowest price sensitivity on compliance-certain bundles. Cost compression in standardized rooftop units intensifies as copper and aluminum volatility squeezes heat exchanger margins. French and Italian healthcare facilities exhibit least price sensitivity due to EMA air quality mandate enforcement and occupancy-critical operations.
Supply Chain Analysis
Reverse-logistics flows for chiller refurbishment and compressor remanufacturing concentrate in Germany and France, extending equipment lifecycles while cannibalizing new-unit demand in aging installed bases. Manufacturing draws from German compressor fabrication, Chinese electronics components, and Italian heat exchanger production. Single-source vulnerability concentrates in lower-GWP refrigerant supply among specialized chemical producers. Distribution runs through energy service companies consolidating specification authority in French and Dutch commercial portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe commercial HVAC functions as a geographic-arbitrage play, with Netherlands gas grid phase-out policies accelerating heat pump electrification timelines faster than Spanish rooftop replacement cycles, compressing margin capture windows in Southern European markets.
For Market Incumbents: Anchor premium positioning through captive lower-GWP refrigerant certification programs ahead of quota reductions. Defensive consolidation should target predictive analytics platforms serving French and Italian long-term maintenance contract structures. Compressor manufacturing backward integration secures supply continuity against chemical supplier bottlenecks.
For New Entrants and Emerging Players: Smart HVAC control architectures with pre-certified EU AI Act compliance offer technology-first entry into specification-driven German and Dutch procurement channels. White-space concentrates in predictive maintenance platforms unbundling service networks in French commercial real estate and EMA-mandated healthcare ventilation upgrades in Italy and Spain. Channel partnership with energy service companies bypasses distributor gatekeeping.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European fabricators lacking lower-GWP refrigerant certification timelines. Long-term viability centers on refrigerant transition readiness and digital platform maturity rather than manufacturing scale alone. Monitor F-Gas quota enforcement acceleration as inflection signal for consolidation urgency.
| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Platform Redesign | EU F-Gas Regulation mandates lower-GWP chemistry transitions before replacement cycle peaks. |
| Smart Control Certification | EU AI Act creates first-mover advantage for pre-certified autonomous building management algorithms. |
| Service Network Expansion | French and Italian long-term maintenance contracts lock in recurring revenue streams. |
| Heat Pump Manufacturing Scale-Up | Netherlands gas grid phase-out accelerates electrified heating specification in Northern Europe. |
| Predictive Analytics Licensing | Energy service company consolidation creates channel for fault-detection platform deployment. |
Research Methodology
Coverage spans Germany, France, the Netherlands, Italy, and Spain, with primary inputs from each national market. The approach combines interviews with HVAC manufacturer product managers, commercial real estate facility directors, energy service company procurement leads, and refrigerant supply specialists with secondary validation from EU F-Gas Regulation filings, national EPBD transposition documents, EMA indoor air quality guidelines, and trade data on compressor and heat exchanger flows. Bottom-up equipment shipment analysis triangulates against top-down building stock renovation projections.
Granularity extends to product type, installation category, end-user vertical, and technology tier across the projection horizon. The analytical framework models chiller, heat pump, rooftop unit, and VRF configurations separately, with heat pump electrification and smart HVAC adoption as industry-specific demand drivers. CAGRs derive from replacement cycle compression against regulatory deadlines and subsidy program deployment.
The model holds under steady EU F-Gas quota enforcement and EPBD compliance timelines; deviation in refrigerant availability or national subsidy suspension would shift equipment mix assumptions. Practitioners should monitor EMA air quality guideline expansion and EU AI Act certification requirements for early signals of specification-driven procurement acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Equipment
HVAC Systems Market
HVAC Equipment
Global Snow Making System Market
HVAC Equipment
Refrigeration and Air Conditioning Compressors Market
HVAC Equipment
Europe HVAC Market
HVAC Equipment
Modular Refrigeration Unit Market
HVAC Equipment
Japan HVAC Market
HVAC Equipment
Air Conditioner Quilt Market
HVAC Equipment
HVAC Air Quality Monitoring Market
HVAC Equipment
GCC Water Heater Market
HVAC Equipment
Heating Equipment Market
HVAC Equipment
Steam Operated Condensate Pump Market
HVAC Equipment
Reciprocating Chiller Market
HVAC Equipment
Europe Bus HVAC Market
HVAC Equipment
United States Residential Heating Equipment Market
HVAC Equipment
Heavy Duty Heat Pump Market
HVAC Equipment
Hydro Chillers Market