
 Remote Magnetic Catheter Systems Market | 2026-2036
Remote Magnetic Catheter Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Magnetic Catheter Systems Market Analytics
MDR Article 10.4 is broadening the cost-of-entry calculus for robotic catheter platforms in Europe. Stereotaxis leverages its installed base of Niobe systems to sustain recurring revenue from disposable catheters. Boston Scientific competes through integrated electrophysiology workflows that combine mapping with magnetic steering capabilities.
Remote magnetic catheter systems employ external magnetic fields to steer magnetically-tipped catheters through cardiac chambers with sub-millimeter precision, typically operating at field strengths between 0.08 and 0.10 Tesla. The technology enables electrophysiologists to perform complex ablations while seated at a radiation-shielded workstation, reducing fluoroscopy exposure during prolonged procedures. Magnetic navigation systems occupy the highest capital-investment tier among product categories, while software modules represent the fastest-expanding margin pool as vendors shift toward subscription-based platform ecosystems. Hospitals dominate end-user demand, though ambulatory surgical centers are gaining traction as same-day ablation protocols standardize across health systems.
FDA premarket notification pathways and EU MDR conformity assessments shape product development timelines for magnetic navigation platforms, with both agencies scrutinizing robotic safety interlocks and electromagnetic compatibility. The EPA and OSHA indirectly influence system design through requirements for lead shielding and operator radiation monitoring in interventional suites. Stakeholders must monitor evolving reimbursement codes for robotic-assisted electrophysiology across CMS and national health technology assessment bodies, as coverage decisions will determine site-of-service economics for capital-intensive magnetic catheter installations.
Market Dynamics
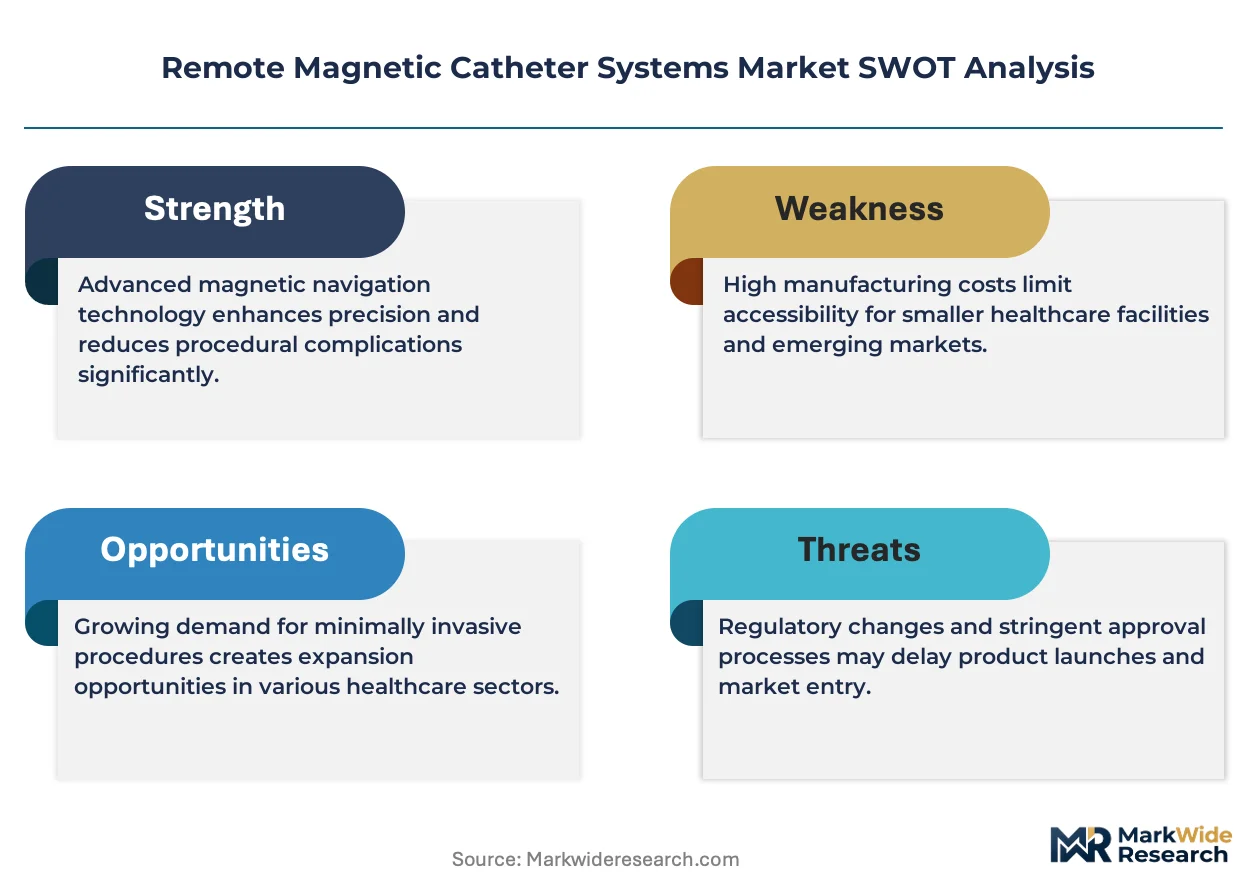
Capital intensity and regulatory compliance burden are compressing vendor margins while simultaneously erecting barriers to new entrants in magnetic navigation platforms. Electrophysiology labs demand proof of clinical utility before committing to seven-figure system investments.
Growth Catalysts
- EU MDR Article 10.4:Stricter clinical evidence requirements favor established platforms with robust safety databases, accelerating replacement cycles for aging systems in European hospital networks.
- Ambulatory surgical centers:Same-day discharge protocols for atrial fibrillation ablation are expanding addressable procedure volume beyond traditional inpatient settings.
- Fluoroscopy reduction mandates:OSHA radiation exposure limits and EPA lead shielding standards drive demand for workstation-based navigation that minimizes operator dose.
Market Restraints
- Superconducting magnet supply concentration:Cryogenic cooling systems and niobium-titanium wire sourcing depend on a limited supplier base in Germany and Japan.
- Proprietary catheter lock-in:Magnetic navigation platforms require vendor-specific disposable catheters, creating lifetime cost escalation that procurement committees resist.
- Substitution by contact-force sensing:Mechanical catheter technologies with integrated pressure feedback capture simpler ablation cases at lower capital cost.
Strategic Opportunities
- Japan's aging cardiac population:METI reimbursement incentives for minimally invasive arrhythmia treatment create favorable economics for magnetic system adoption in Tokyo and Osaka hospital clusters.
- Pediatric electrophysiology:Magnetic steering enables access to delicate cardiac structures in congenital ablation cases where manual catheter manipulation carries higher perforation risk.
- Subscription-based software ecosystems:Recurring revenue from mapping algorithm updates and cloud-based procedure analytics shifts vendor economics toward platform stickiness.
Industry Challenges
- Electrophysiologist training bottlenecks:Magnetic navigation requires distinct motor skills and spatial reasoning that extend fellowship programs and limit immediate productivity post-installation.
- EMC certification complexity:FDA electromagnetic compatibility validation and EU MDR electrical safety testing add months to product release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Magnetic Catheter Systems Market |
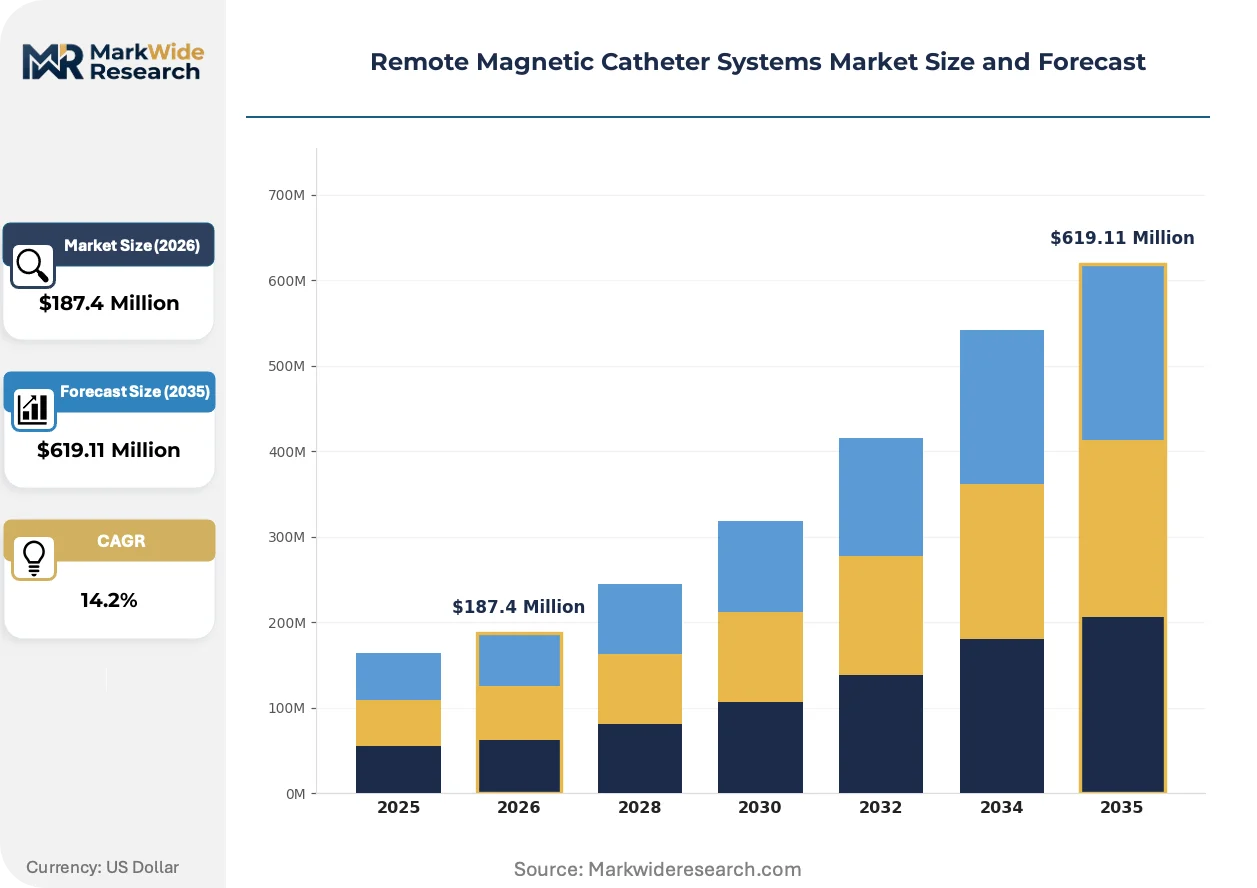
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Navigation Systems, Catheters, Accessories, Software Application: Cardiology, Electrophysiology, Neurology, Vascular Intervention End User: Hospitals, Ambulatory Surgical Centers, Cardiac Clinics, Research Institutes Technology: 3D Visualization, Real-time Tracking, Robotics, Imaging Integration |
| Companies Covered | Stereotaxis, Medtronic, Boston Scientific, Abbott Laboratories, St. Jude Medical, Siemens Healthineers, Philips Healthcare, Johnson & Johnson, Cardinal Health, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Magnetic Catheter Systems Market Evolving Landscape
Real-time imaging fusion and artificial intelligence guidance are transforming procedure workflow efficiency in cardiac ablation suites. Vendors compete on software intelligence rather than hardware specifications alone.
Magnetic navigation systems are integrating advanced imaging modalities including intracardiac echocardiography and pre-procedural CT/MRI overlay to create unified visualization environments. Academic medical centers in the United States and Germany deploy these fused platforms for complex substrate mapping in ventricular tachycardia cases. The convergence is integrating anatomical precision with functional data, compressing procedure duration and reducing repeat ablation rates.
EU MDR clinical evaluation requirements are forcing manufacturers to generate prospective registry data for robotic catheter platforms rather than relying on predicate device equivalence. The regulation demands post-market surveillance systems that track patient outcomes across multiple sites. Small platform developers face capital exhaustion from this evidentiary burden while Stereotaxis and Boston Scientific leverage installed bases to absorb compliance costs.
Hospital procurement committees now bundle magnetic navigation capital requests with multi-year disposable catheter supply agreements, shifting vendor relationships toward total-cost-of-ownership frameworks. This purchasing consolidation favors suppliers with integrated mapping and steering portfolios. The pattern concentrates in United States integrated delivery networks where CFOs scrutinize robotics utilization rates against amortization schedules.
Remote Magnetic Catheter Systems Market Segmentation
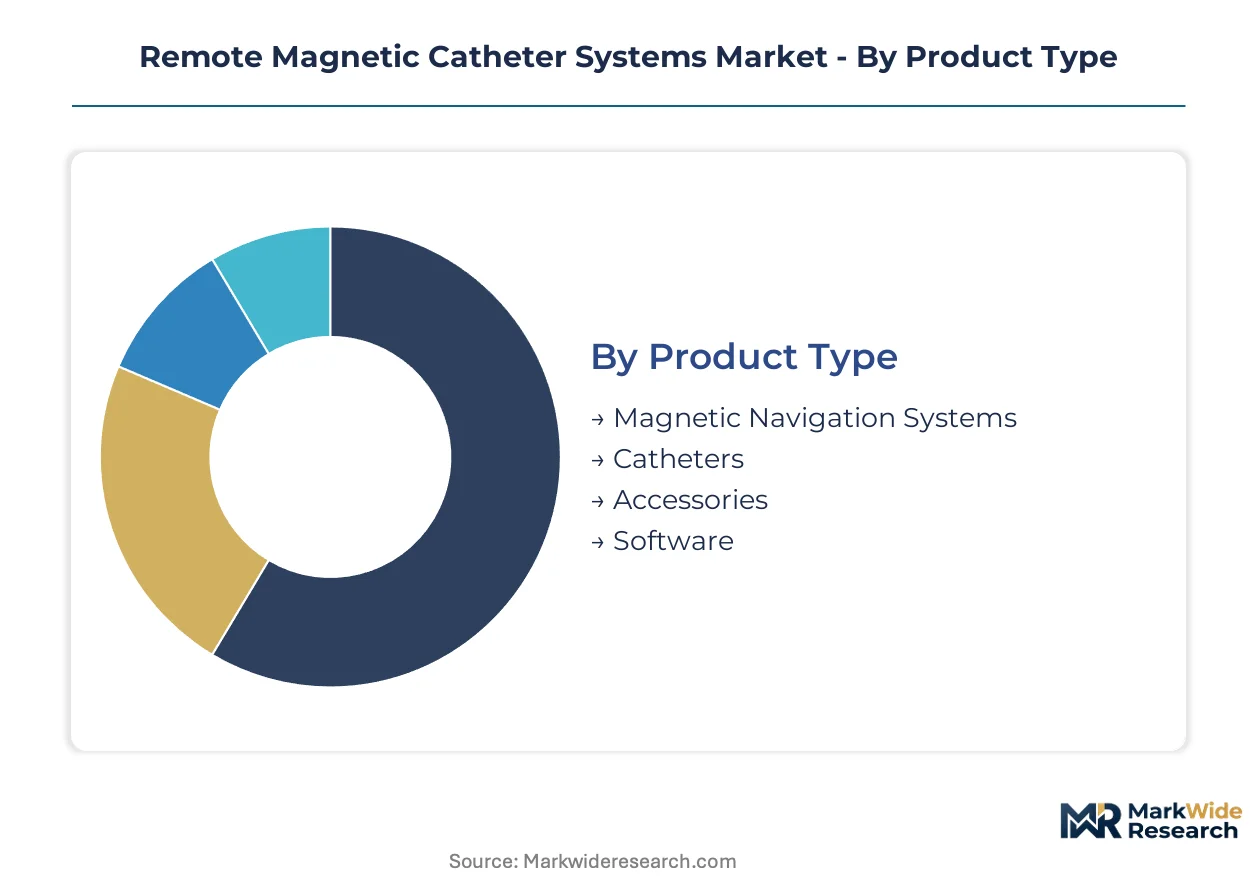
Segmentation in remote magnetic catheter systems reveals distinct procurement patterns across capital equipment, consumables, and software layers. Hospital CFOs evaluate each tier through different investment horizons, with navigation platforms requiring decade-long amortization against disposable catheter recurring costs.
Product Type:
Capital intensity separates buyers into those prioritizing upfront platform ownership versus recurring consumable expenditure.
- Magnetic Navigation Systems:External magnetic field generators operating at 0.08-0.10 Tesla with cryogenic cooling infrastructure. Demand concentrates in United States academic medical centers where seven-figure capital approvals require proof of fluoroscopy reduction. FDA electromagnetic compatibility validation extends procurement timelines by months.
- Catheters:Magnetically-tipped steerable devices with proprietary connector interfaces locking into vendor-specific platforms. German hospital networks resist lifetime cost escalation from disposable lock-in, driving procurement committee scrutiny of total-cost-of-ownership frameworks.
- Accessories:Patient synchronization hardware, magnetic field sensors, and procedure-specific attachment kits.
- Software:Subscription-based mapping algorithms and cloud-based procedure analytics with recurring license structures.
Magnetic Navigation Systems lead volumes today; Software is gaining share fastest.
Application:
Clinical complexity determines reimbursement pathways and thus site-of-service economics for magnetic platform deployment.
- Electrophysiology:Atrial fibrillation and ventricular tachycardia ablation workflows demanding sub-millimeter catheter precision. United States integrated delivery networks expand same-day discharge protocols, shifting volume toward ambulatory settings. CMS reimbursement codes for robotic-assisted electrophysiology shape adoption velocity.
- Cardiology:Structural heart interventions and coronary navigation procedures. Japanese hospital clusters in Tokyo and Osaka leverage METI incentives for minimally invasive cardiac treatment.
- Neurology:Magnetically-guided interventions for intracranial vascular access.
- Vascular Intervention:Peripheral artery disease treatments utilizing magnetic steering for tortuous anatomy navigation.
Electrophysiology commands installed base concentration; Cardiology is expanding most quickly.
End User:
Facility type dictates capital access, procedure volume thresholds, and regulatory compliance burden.
- Hospitals:Inpatient electrophysiology labs with dedicated interventional suites and radiation shielding infrastructure. German hospital networks face EU MDR Article 10.4 compliance costs accelerating replacement cycles for aging magnetic platforms.
- Ambulatory Surgical Centers:Same-day discharge facilities capturing simpler ablation cases at lower overhead. United States site-of-service economics favor ASC expansion as CMS reimbursement differentials narrow against hospital outpatient departments.
- Cardiac Clinics:Specialized arrhythmia treatment centers without full surgical backup.
- Research Institutes:Academic centers generating prospective registry data for EU MDR clinical evaluation requirements.
Hospitals retain dominant installed base; Ambulatory Surgical Centers show steepest expansion trajectory.
Technology:
Software-hardware integration depth separates vendors competing on workflow efficiency versus standalone device specifications.
- Imaging Integration:Pre-procedural CT/MRI overlay fused with intracardiac echocardiography for unified visualization. German academic medical centers deploy these platforms for complex ventricular tachycardia substrate mapping. Procedure duration compression drives procurement preference.
- Robotics:Automated catheter steering with safety interlocks and electromagnetic compatibility certification. FDA and EU MDR scrutiny of robotic safety systems extends development timelines.
- 3D Visualization:Anatomical mapping displays with cardiac chamber reconstruction.
- Real-time Tracking:Catheter position sensing with latency-minimized feedback loops.
Imaging Integration leads clinical preference; Robotics is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Remote magnetic catheter systems originated in United States academic medical centers during the early commercialization of robotic electrophysiology platforms. The technology subsequently diffused through German hospital networks and Japanese metropolitan clusters as regulatory frameworks matured for minimally invasive cardiac interventions.
United States
Integrated delivery networks in the United States drive capital deployment for magnetic navigation platforms as CFOs scrutinize robotics utilization against amortization schedules. FDA electromagnetic compatibility validation extends procurement timelines for new system installations. The Cleveland Clinic and Mayo Clinic anchor adoption clusters where same-day discharge protocols expand addressable procedure volumes.
Germany
German hospital networks resist lifetime cost escalation from proprietary catheter lock-in, driving procurement committee scrutiny of total-cost-of-ownership frameworks. EU MDR Article 10.4 compliance costs accelerate replacement cycles for aging magnetic platforms in Berlin and Munich academic centers. The country's national pharmaceutical regulator demands robust post-market surveillance for robotic interventional systems.
Japan
Japan's aging cardiac population creates favorable economics for magnetic system adoption in Tokyo and Osaka hospital clusters. METI reimbursement incentives for minimally invasive arrhythmia treatment reduce capital recovery periods for seven-figure platform investments. Nagoya medical centers generate prospective registry data supporting regulatory submissions across Asia-Pacific markets.
United Kingdom
United Kingdom electrophysiology labs prioritize fluoroscopy reduction mandates in procurement decisions for radiation-shielded workstation systems. The country's national pharmaceutical regulator aligns with EU MDR clinical evidence requirements for robotic catheter platforms. London teaching hospitals and Manchester cardiac centers concentrate installed base expansion for complex ventricular tachycardia workflows.
Remote Magnetic Catheter Systems Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with integrated electrophysiology portfolios. Capital intensity and regulatory compliance burden compress vendor margins while erecting barriers to new entrants. Three strategic archetypes dominate: pure-play magnetic navigation specialists, diversified cardiac rhythm management conglomerates, and imaging-system integrators. M&A activity concentrates on mapping technology acquisitions and strategic partnerships for software ecosystem expansion.
Among diversified cardiac rhythm management conglomerates, Medtronic, Boston Scientific, and Abbott Laboratories exemplify the integrated portfolio archetype. Stereotaxis occupies a position as the pure-play magnetic navigation specialist with historical installed base concentration. Siemens Healthineers and Philips Healthcare represent the imaging-system integrator tier, leveraging pre-procedural visualization platforms to compete on workflow convergence rather than standalone catheter steering specifications.
| Leading Market Players |
|---|
| Stereotaxis |
| Medtronic |
| Boston Scientific |
| Abbott Laboratories |
| St. Jude Medical |
| Siemens Healthineers |
| Philips Healthcare |
| Johnson & Johnson |
| Cardinal Health |
| Others |
Value Network & Pricing Analysis
EPA lead shielding and OSHA radiation exposure mandates gate qualified supply for workstation-based navigation systems, reserving premium-tier pricing access to vendors with validated fluoroscopy reduction portfolios. Magnetic navigation platforms face procurement committee scrutiny that ties capital approval to proof of operator dose minimization, compressing margins for non-compliant suppliers while elevating pricing power for certified systems.
Pricing Analysis
Subscription-based platform ecosystems with recurring software license structures dominate vendor economics, separating premium-tier mapping algorithm suites from standard visualization packages. Price differentiation hinges on FDA electromagnetic compatibility validation tier and integrated imaging fusion depth, with academic medical centers absorbing premium positioning for complex substrate mapping workflows. Cost compression in standard-tier hardware stems from contact-force sensing substitution in simpler ablation cases. Ambulatory surgical centers exhibit highest price sensitivity due to same-day discharge protocol economics, while United States integrated delivery networks prioritize total-cost-of-ownership frameworks over unit pricing.
Supply Chain Analysis
CE marking and FDA electromagnetic compatibility certification requirements concentrate qualified manufacturing in Germany, Japan, and the United States, excluding lower-cost jurisdictions from magnetic navigation platform supply. Superconducting magnet production draws from niobium-titanium wire sourcing anchored in German and Japanese specialty metal suppliers, with cryogenic cooling system assembly tethered to these same geographies. Single-source vulnerability runs through superconducting coil winding capabilities concentrated among three European suppliers. Distribution runs through hospital procurement committees and integrated delivery network capital committees rather than open market channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Magnetic catheter systems present a margin-expansion story as subscription-based software ecosystems displace transactional hardware revenue, with cloud-based procedure analytics commanding recurring license premiums that amortize platform development costs across expanding installed bases.
For Market Incumbents: Lock in disposable catheter supply agreements through multi-year procurement contracts that resist German hospital network total-cost-of-ownership scrutiny. Deepen backward integration into superconducting magnet manufacturing to mitigate niobium-titanium wire supply concentration risk. Prioritize software companion development for imaging fusion algorithms that compress procedure duration in ventricular tachycardia workflows. For New Entrants and Emerging Players: The price-point gap between seven-figure magnetic navigation platforms and contact-force sensing systems creates white-space for mid-tier robotic steering modules. Target pediatric electrophysiology applications where magnetic access to delicate cardiac structures commands procedure-specific premiums. Pursue strategic partnerships with imaging-system integrators to bypass standalone platform certification timelines. For Investors and Strategic Acquirers: Roll-up economics work for mapping technology specialists because EU MDR Article 10.4 compliance costs exhaust small platform developers while concentrating value in installed base data assets. Platform-rollup viability extends across a five-to-ten year window as hospital procurement consolidation favors integrated portfolio vendors. Monitor CMS reimbursement code decisions for robotic-assisted electrophysiology as the signal for site-of-service economics inflection.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10.4 compliance accelerates replacement cycles for aging European installed bases. |
| Hospital System Partnership | Integrated delivery network CFOs scrutinize robotics utilization against amortization schedules. |
| Software Companion Development | Cloud-based procedure analytics shift vendor economics toward recurring revenue stickiness. |
| Reimbursement Strategy | CMS coverage decisions determine capital recovery periods for seven-figure platform investments. |
| Backward Integration | Captive supply of superconducting magnets mitigates niobium-titanium wire sourcing concentration. |
Research Methodology
Multiple input streams — electrophysiologist interviews, hospital procurement committee discussions, biomedical engineer consultations, and GPO contracts manager surveys — were reconciled against FDA 510(k) filings, EU MDR technical documentation, CMS reimbursement databases, and hospital capital expenditure records. Bottom-up procedure volume modeling and top-down platform shipment triangulation anchored market sizing across the analysis window.
Data-stream reconciliation applied segmentation dimensions spanning magnetic navigation system tier, catheter disposable category, software deployment model, and end-user facility type. CAGRs derived from installed base expansion rates, replacement cycle timing, and same-day discharge protocol adoption curves. Forecast inputs incorporated METI reimbursement incentive trajectories and fluoroscopy reduction mandate enforcement patterns.
Caveats apply where EU MDR clinical evidence requirement evolution or superconducting magnet supply disruption could materially shift the outlook. Forecasts reflect assumptions about ambulatory surgical center site-of-service economics and contact-force sensing substitution velocity. A model refresh is warranted upon material change in CMS robotic-assisted electrophysiology coverage determinations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Smart Infusion Pump Market
Medical Devices
Interventional Cardiology and Peripheral Vascular Devices Market
Medical Devices
Occlusion Balloon Catheter Market
Medical Devices
Infant Radiant Warmer Market
Medical Devices
Bone Anchored Hearing Aids Market
Medical Devices
External Pacemakers Market
Medical Devices
Lancing Devices and Lancets Market
Medical Devices
United Kingdom Aesthetic Devices Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Intracranial Pressure (ICP) Monitoring Devices Market
Medical Devices
United States Small Bone and Joint Devices Market
Medical Devices
Continuous Passive Motion Devices Market
Medical Devices
United States Insulin Pumps Market
Medical Devices
Bronchial Blocker Devices Market
Medical Devices
Testicular Implants (Prosthesis) Market