
 Automotive TCU Market | 2026-2036
Automotive TCU Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive TCU Market Analysis
5G-ready specification tiers are rotating toward the center of OEM procurement decisions, displacing basic 4G-Legacy configurations from flagship vehicle programs. Continental AG leverages captive semiconductor partnerships to secure module supply for integrated cockpit domains. ZF Friedrichshafen anchors its position through transmission-control integration, embedding TCU logic within powertrain electronics. Bosch differentiates via end-to-end cybersecurity certification, a requirement that Tier-1 suppliers now treat as non-negotiable.
An automotive TCU is an embedded telematics control unit that manages wireless data exchange between vehicles and external networks, typically integrating cellular modems operating at sub-6 GHz and mmWave bands alongside GNSS receivers and CAN-FD gateway processors. Its primary commercial purpose is to enable real-time remote diagnostics, over-the-air software updates, and cloud-connected safety services for passenger and commercial vehicles. Integrated Modules command the dominant share of value given their consolidation of antenna, modem, and application processor into single enclosures, while Software Solutions represent the fastest-expanding margin pool as automakers pursue subscription-based feature monetization. V2X technology segments are gaining traction fastest where municipal infrastructure investments support direct vehicle-to-vehicle and vehicle-to-infrastructure communication protocols.
NHTSA crash-notification mandates in the United States, ETSI standards under European Commission delegated acts, and China's MIIT dual carbon goals collectively shape TCU hardware requirements and certification pathways for connected vehicle platforms. The European Union's F-Gas Regulation and CE marking directives additionally constrain thermal management material selections in module design. Stakeholders must monitor which regulatory jurisdiction sets the most stringent cybersecurity and data-localization benchmarks, as this will determine the reference architecture that scales across export programs.
Market Dynamics
Cellular module procurement is rotating toward 5G-ready specifications as OEMs sunset 4G-only architectures ahead of regulatory deadlines, compressing supplier qualification timelines and fragmenting legacy supply pools.
Growth Catalysts
- V2X Communication Mandates:The EU AI Act and Intelligent Transport Systems directives compel hardware upgrades across European fleets, forcing module replacements in commercial logistics vehicles.
- Commercial Fleet Digitization:Fleet operators accelerate connected platform procurement to enable real-time diagnostics and predictive maintenance across long-haul trucking networks.
- Subscription Monetization:Automakers pursue recurring revenue from over-the-air feature activation, embedding higher-margin application processors within TCU enclosures.
Market Restraints
- Semiconductor Supply Concentration:Modem chipset fabrication concentrates among a handful of foundry operators, exposing module assemblers to allocation volatility.
- F-Gas Thermal Constraints:The European Union's F-Gas Regulation restricts phase-change materials in module thermal management, complicating high-temperature automotive grade certification.
- 4G Inventory Stranding:Legacy cellular module stockpiles face accelerated obsolescence as 5G-native vehicle programs dominate OEM roadmaps.
Strategic Opportunities
- India Fleet Telematics:Commercial vehicle mandates under the country's national automotive regulator create first-mover advantage for localized module production.
- Cybersecurity Certification Services:End-to-end security validation emerges as a billable service layer as OEMs require Tier-1 suppliers to demonstrate ISO/SAE 21434 compliance.
- Edge-AI Convergence:Onboard inference engines merge with TCU processors to enable latency-critical safety functions without cloud round-trips.
Industry Challenges
- Embedded Systems Talent Scarcity:Automotive-grade firmware engineering for CAN-FD gateway integration outpaces available specialized labor pools.
- Multi-Jurisdiction Certification:Simultaneous NHTSA, ETSI, and MIIT homologation timelines strain validation resources and compress program schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive TCU Market |
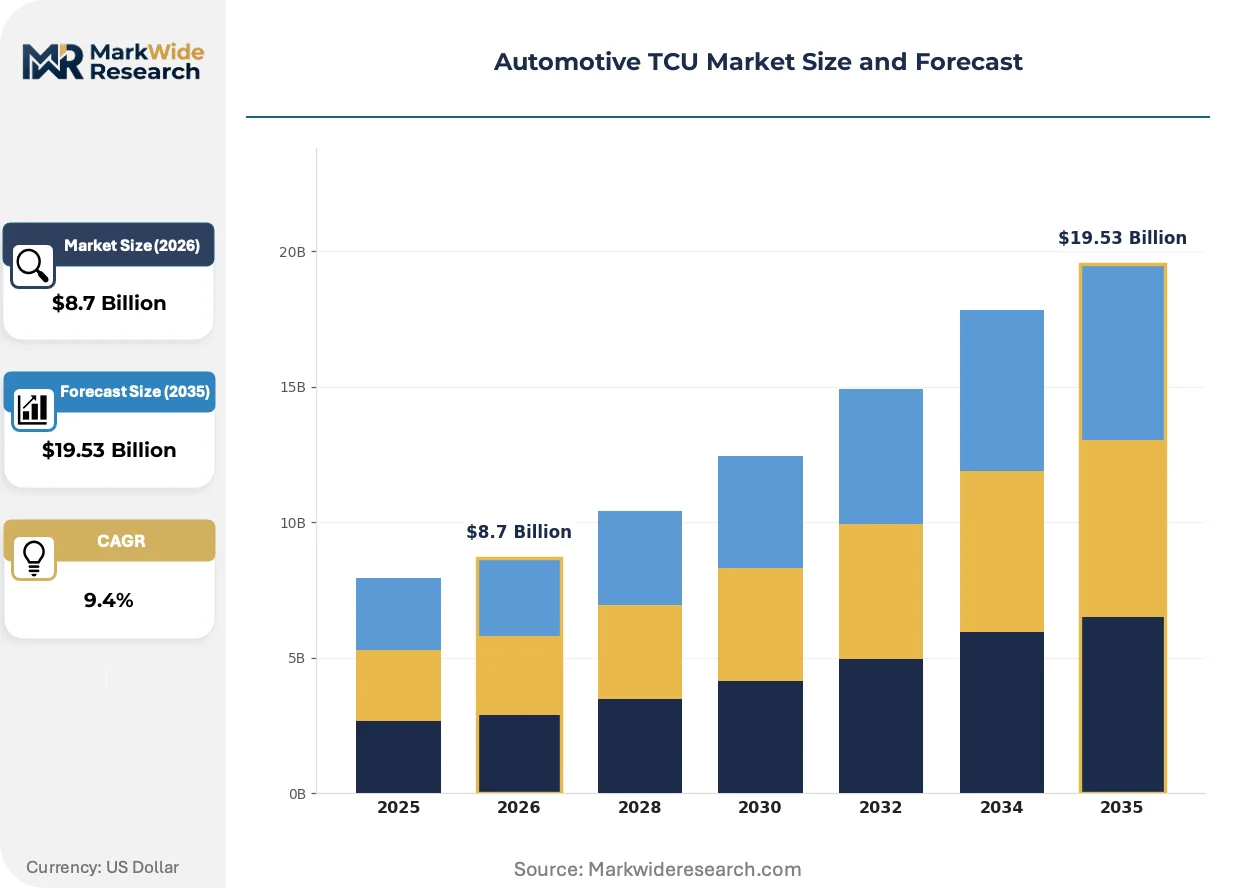
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Modules, Standalone Units, Software Solutions, Hybrid Systems Technology: Cellular, V2X, Wi-Fi, Bluetooth Application: Telematics, Vehicle Tracking, Fleet Management, Emergency Services End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Dealerships |
| Companies Covered | Continental AG, ZF Friedrichshafen AG, LG Electronics, Hyundai Mobis, Hitachi Astemo, Harman, Denso, Marelli, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive TCU Market Emerging Trajectories
Module architectures are splitting between integrated cockpit domains and standalone telematics units as OEMs debate electronics consolidation strategies.
Integrated TCU enclosures are bifurcating from discrete modem assemblies as Volkswagen Group and Stellantis pursue zonal electronics consolidation. Tier-1 suppliers must qualify dual architectures simultaneously. This split is compressing development budgets toward the integrated variant while stranding discrete module R&D.
ETSI standards under European Commission delegated acts now mandate direct vehicle-to-infrastructure communication protocols for type approval. Module vendors must embed dual-radio 5G-V2X chipsets. German OEMs have accelerated their supplier qualification timelines by eight months to secure 2026 model-year compliance.
Automotive buyers now specify outcome-based connectivity contracts rather than hardware-procurement agreements. Fleet operators in North America negotiate guaranteed uptime SLAs with penalties. This shift transfers operational risk to module suppliers and compresses their service margin assumptions.
Automotive TCU Market Segmentation
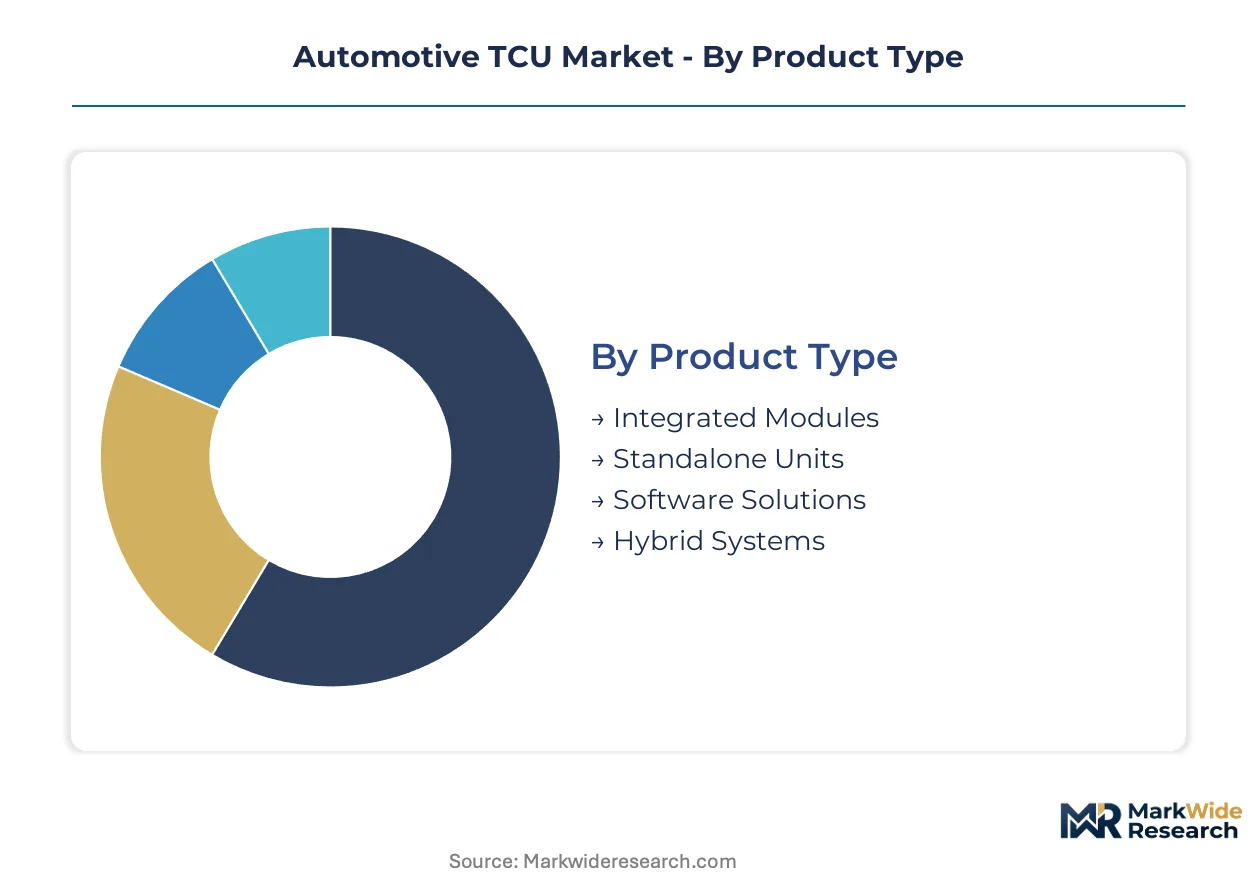
Segmentation in automotive TCU markets reveals how value migrates between hardware enclosures and software monetization layers. Procurement patterns diverge sharply between integrated cockpit domains and discrete telematics units as OEMs debate electronics consolidation strategies.
Product Type:
Margin pools concentrate in consolidated enclosures that merge antenna, modem, and application processor into single assemblies, while software layers capture expanding recurring revenue streams.
- Integrated Modules:Single-enclosure designs consolidate cellular modems, GNSS receivers, and CAN-FD gateway processors. German OEM headquarters in Stuttgart and Munich drive specification-setting for these architectures across European flagship programs. Integrated Modules hold installed capacity. Software Solutions is rotating up the share rankings.
- Standalone Units:Discrete modem assemblies persist in commercial fleet retrofits where legacy vehicle architectures resist electronics consolidation. Long-haul trucking operators in North America specify these for aftermarket telematics deployments.
- Software Solutions:Subscription-based feature activation and over-the-air update platforms represent the steepest expansion trajectory as automakers pursue recurring revenue from connected services.
- Hybrid Systems:Partitioned architectures separate safety-critical V2X functions from infotainment connectivity, satisfying ISO/SAE 21434 cybersecurity requirements without full integration costs.
Integrated Modules command procurement volume in new vehicle programs. Software Solutions is climbing the fastest in margin contribution.
Technology:
Certification complexity varies dramatically across radio protocols, with dual-mode 5G-V2X chipsets requiring simultaneous ETSI and NHTSA homologation.
- Cellular:Sub-6 GHz and mmWave modems form the backbone of cloud-connected diagnostics and over-the-air updates. 5G-ready specifications are displacing 4G-Legacy configurations from flagship vehicle programs as regulatory deadlines approach.
- V2X:Direct vehicle-to-vehicle and vehicle-to-infrastructure communication protocols gain traction where municipal infrastructure investments support deployment. EU Intelligent Transport Systems directives now mandate these chipsets for type approval.
- Wi-Fi:Local area connectivity for in-vehicle device pairing and dealership service bay diagnostics. Wi-Fi modules face pricing pressure as smartphone tethering reduces dedicated hardware demand.
- Bluetooth:Low-energy protocols for key fob authentication and sensor cluster communication. Bluetooth represents mature technology with stable cost curves.
Cellular dominates unit economics. V2X is expanding most quickly in regulatory-mandated applications.
Application:
Commercial fleet operators negotiate outcome-based connectivity contracts rather than hardware-procurement agreements, transferring operational risk to module suppliers.
- Telematics:Real-time remote diagnostics and cloud-connected safety services form the core commercial purpose of TCU deployments. Passenger vehicle OEMs embed these for automatic crash notification mandated by NHTSA.
- Vehicle Tracking:GNSS-receiver-based location services for stolen vehicle recovery and usage-based insurance pricing. Insurance underwriters in Germany specify certified tracking modules for premium discounts.
- Fleet Management:Predictive maintenance algorithms and route optimization for commercial logistics networks. Fleet operators accelerate procurement to enable real-time diagnostics across long-haul trucking.
- Emergency Services:E-call mandates under European Commission delegated acts require automatic crash notification hardware. These modules face stringent reliability certification.
Fleet Management captures commercial procurement volume. Telematics is gaining share fastest in passenger vehicle integration.
End User:
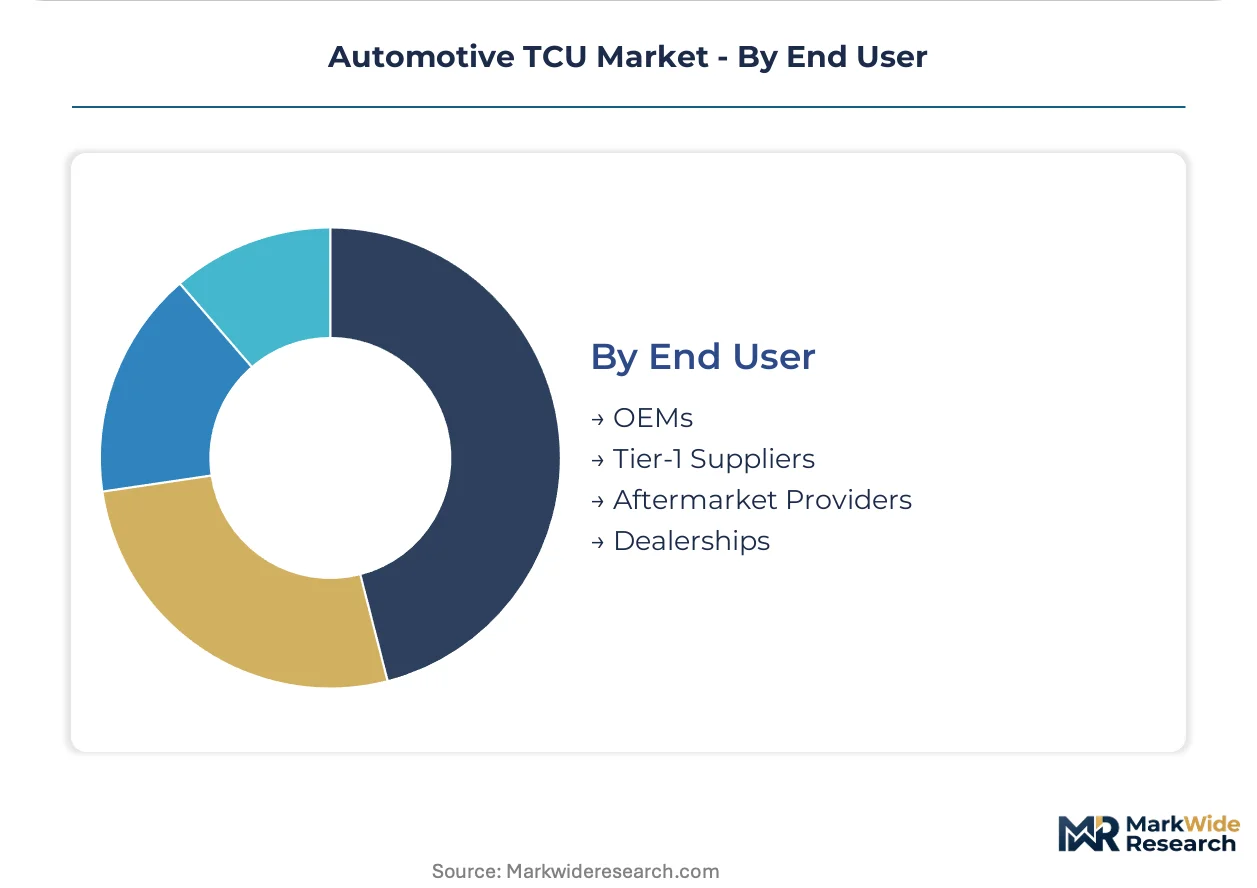
Specification authority concentrates with automotive OEM headquarters, though aftermarket channels retain relevance in fleet retrofit cycles.
- OEMs:Volkswagen Group and Stellantis pursue zonal electronics consolidation strategies that favor integrated TCU architectures. OEM procurement decisions determine reference designs that cascade through supply chains.
- Tier-1 Suppliers:Continental AG, ZF Friedrichshafen, and Bosch qualify dual architectures simultaneously as module vendors. These suppliers must demonstrate ISO/SAE 21434 cybersecurity compliance.
- Aftermarket Providers:Commercial fleet retrofits and vehicle tracking installations for used vehicle segments. Aftermarket channels face compressed margins from outcome-based contract expectations.
- Dealerships:Service bay diagnostics and connected feature activation for subscription monetization. Dealerships function as software distribution points rather than hardware resellers.
OEMs control specification authority. Tier-1 Suppliers is rotating up the share rankings through cybersecurity certification services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in automotive TCU hardware concentrate where OEM headquarters and tier-1 supplier clusters sit in close geographic proximity. Module fabrication capacity concentrates in Germany, China, South Korea, and the United States, with each market shaping distinct regulatory compliance requirements that cascade through supply chains.
Germany
Stuttgart and Munich host Volkswagen Group and BMW headquarters that set reference architectures for integrated TCU designs. ETSI standards under EU Intelligent Transport Systems directives mandate dual-radio 5G-V2X chipsets for type approval by 2026. The Baden-Württemberg supplier corridor anchors Continental AG and Bosch qualification programs for zonal electronics consolidation.
China
Domestic EV manufacturers accelerate procurement of connected vehicle platforms to satisfy MIIT dual carbon goals and smart city infrastructure mandates. GB standards for vehicle networking establish certification pathways that differ from Western regulatory frameworks. The Yangtze River Delta cluster around Shanghai concentrates module assembly capacity for both local OEMs and export programs.
United States
NHTSA automatic crash notification mandates drive baseline telematics hardware penetration across passenger vehicle fleets. Detroit-based OEM procurement offices specify outcome-based connectivity contracts with guaranteed uptime SLAs. The Southeast manufacturing corridor attracts module assembly investments seeking proximity to vehicle assembly plants.
South Korea
Hyundai Motor Group and Kia headquarters in Seoul anchor specification authority for integrated cockpit domain architectures. The country's national automotive regulator enforces cybersecurity certification requirements that anticipate ISO/SAE 21434 adoption. Gyeonggi Province hosts LG Electronics and Hyundai Mobis module production facilities serving regional OEM programs.
Japan
Denso and Hitachi Astemo headquarters in Aichi Prefecture drive transmission-control integration strategies that embed TCU logic within powertrain electronics. METI standards for connected vehicle security shape supplier qualification timelines. The Kanto region around Tokyo concentrates R&D investment for edge-AI convergence with telematics processors.
Automotive TCU Market Vendor Landscape
Listed leaders compete with private specialists across module architecture strategies, creating a tiered structure where scale-driven conglomerates face focused component vendors. The vendor base splits between integrated cockpit domain suppliers and standalone telematics unit providers. Three archetypes dominate: diversified automotive electronics conglomerates, captive semiconductor-integrated module vendors, and cybersecurity-specialized certification services. Competitive moves concentrate on strategic partnerships for 5G chipset supply and portfolio diversification into software monetization layers.
Within the diversified conglomerate tier, Continental AG and Bosch exemplify archetypes that span multiple automotive electronics domains. ZF Friedrichshafen occupies a position representing transmission-control integration strategies. These German-based entities anchor the European supply base through qualification programs that cascade specifications to tier-2 component vendors across export markets.
| Leading Market Players |
|---|
| Continental AG |
| ZF Friedrichshafen AG |
| LG Electronics |
| Hyundai Mobis |
| Hitachi Astemo |
| Harman |
| Denso |
| Marelli |
| Bosch |
| Others |
Supply Flow & Price Mechanics
5G modem chipset substitution for 4G-Legacy silicon is redrawing procurement geography toward Taiwan and South Korea foundry clusters while compressing module assembler margins through allocation premiums and accelerated qualification costs.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with ISO/SAE 21434 cybersecurity certification and 5G-V2X dual-radio capability as primary price differentiation drivers. Cost compression in economy-tier discrete modules is intensifying because stranded 4G inventory forces distressed liquidation. Fleet operators exhibit the highest price sensitivity, while German flagship vehicle programs demonstrate inelastic demand for integrated cockpit domain architectures.
Supply Chain Analysis
Strategic stockpiling of cellular modem chipsets has displaced just-in-time preferences as module vendors buffer against foundry allocation volatility and eight-month qualification timeline compressions. Module fabrication draws from Germany, China, and South Korea, with mmWave RF front-end components and automotive-grade ceramic substrates as critical dependencies. Single-source vulnerability in sub-6 GHz baseband silicon concentrates risk. Distribution runs through captive Tier-1 supplier channels directly into OEM platform engineering teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive TCU demand follows a cyclical recovery pattern tied to vehicle production restocking and regulatory mandate deadlines across major automotive markets.
For Market Incumbents: Fortify cybersecurity certification service capabilities to capture ISO/SAE 21434 compliance revenue as OEMs offload validation burden. Deepen captive semiconductor partnerships with Taiwan and South Korea foundries to secure 5G chipset allocation priority. These moves counter margin erosion from outcome-based connectivity contracts transferring operational risk.
For New Entrants and Emerging Players: Anchor in India's commercial fleet telematics segment where national automotive regulator mandates create first-mover advantage for localized module production. Target aftermarket retrofit channels for long-haul trucking operators in North America with standalone discrete modem assemblies. Pursue direct partnerships with fleet management software platforms rather than OEM qualification programs.
For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors cybersecurity-specialized certification services and edge-AI convergence capabilities. Over a five-to-ten-year horizon, acquisition targets with demonstrated ETSI and NHTSA dual-homologation expertise command structural scarcity premiums. Watch for inflection when municipal V2X infrastructure deployment rates cross threshold densities in EU urban corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| 5G-V2X Chipset Supply Agreement | Secures allocation priority from Taiwan foundries for dual-radio module production. |
| Cybersecurity Certification Service Launch | Captures ISO/SAE 21434 validation revenue from Tier-1 suppliers under OEM pressure. |
| India Manufacturing Footprint Establishment | Positions for commercial fleet mandates under national automotive regulator directives. |
| Edge-AI Processor Integration | Enables latency-critical safety functions without cloud dependency for premium vehicle programs. |
| Outcome-Based Connectivity Contract Portfolio | Transfers operational risk from fleet operators to module suppliers with uptime SLA penalties. |
Methodological Framework
A standing panel of OEM platform engineers, Tier-1 supplier procurement directors, aftermarket fleet telematics operators, and semiconductor foundry account managers provided ongoing calibration across the study period. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, ETSI standards documentation, and NHTSA regulatory filings. Bottom-up module shipment estimates triangulated against top-down OEM connected vehicle platform announcements.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derived from fitted growth curves applied to baseline penetration rates, with inputs including 5G network rollout timelines, V2X infrastructure investment pipelines, and regulatory mandate enforcement schedules.
Material uncertainties — semiconductor allocation volatility, regulatory deadline shifts, and fleet operator contract restructuring — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding OEM electronics consolidation strategies and foundry capacity expansion trajectories. Revision becomes warranted when 5G-native vehicle program share crosses threshold penetration in German flagship lineups.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Drivetrain Vibration and Condition Monitoring Sensor Systems Market
Powertrain
Transmission Repair Market
Powertrain
Asia Pacific Automotive Engine Market
Powertrain
Automotive Transmission Repair Market
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
EV Powertrain-in-the-Loop (P-HIL) Test Benches Market
Powertrain
Crankshaft Oil Market
Powertrain
Transmission Control System Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
North America Precision Gearbox Market
Powertrain
Industrial Diesel Turbocharger Market
Powertrain
Gear Oil Market
Powertrain
Automotive Vacuum Pump Market
Powertrain
Automotive Active Purge Pump Market
Powertrain
North America Electro Hydraulic Power Steering Market
Powertrain
Mechanical Reciprocating Engine Market