
 Automotive Fuel Pulsation Damper Market | 2026-2036
Automotive Fuel Pulsation Damper Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fuel Pulsation Damper Market Analysis
Precision machining talent scarcity is bifurcating the supplier base between in-house capability holders and outsourced assemblers. Bosch leverages captive production of electronic damping modules to secure OEM contracts. Continental anchors European supply through specialized fluid reservoir manufacturing. Aisin Seiki dominates Asian sourcing with integrated spring-and-chamber fabrication.
An automotive fuel pulsation damper is a pressure-attenuating device installed in fuel delivery systems, typically incorporating elastomeric diaphragms, metal bellows, or spring-loaded pistons within sealed chambers to absorb injector-induced pressure waves and prevent rail resonance. It maintains stable fuel pressure at injectors across varying engine speeds and load conditions. Lightweight damper configurations are gaining share as OEMs pursue gram-level mass reduction targets, while electronic technology variants command premium positioning due to real-time adaptive damping capability. Mechanical dampers retain volume leadership in aftermarket channels where cost sensitivity prevails over precision control.
EPA tailpipe standards and Euro 7 emissions protocols are tightening permissible fuel system leakage rates, directly elevating sealing element specifications across OEM supply chains. Japan's METI enforces JIS fuel system integrity benchmarks that constrain market entry for non-compliant suppliers. Stakeholders must monitor evolving EPA and EMA regulatory timelines to align R&D allocation between hydraulic refinement and electronic control architectures.
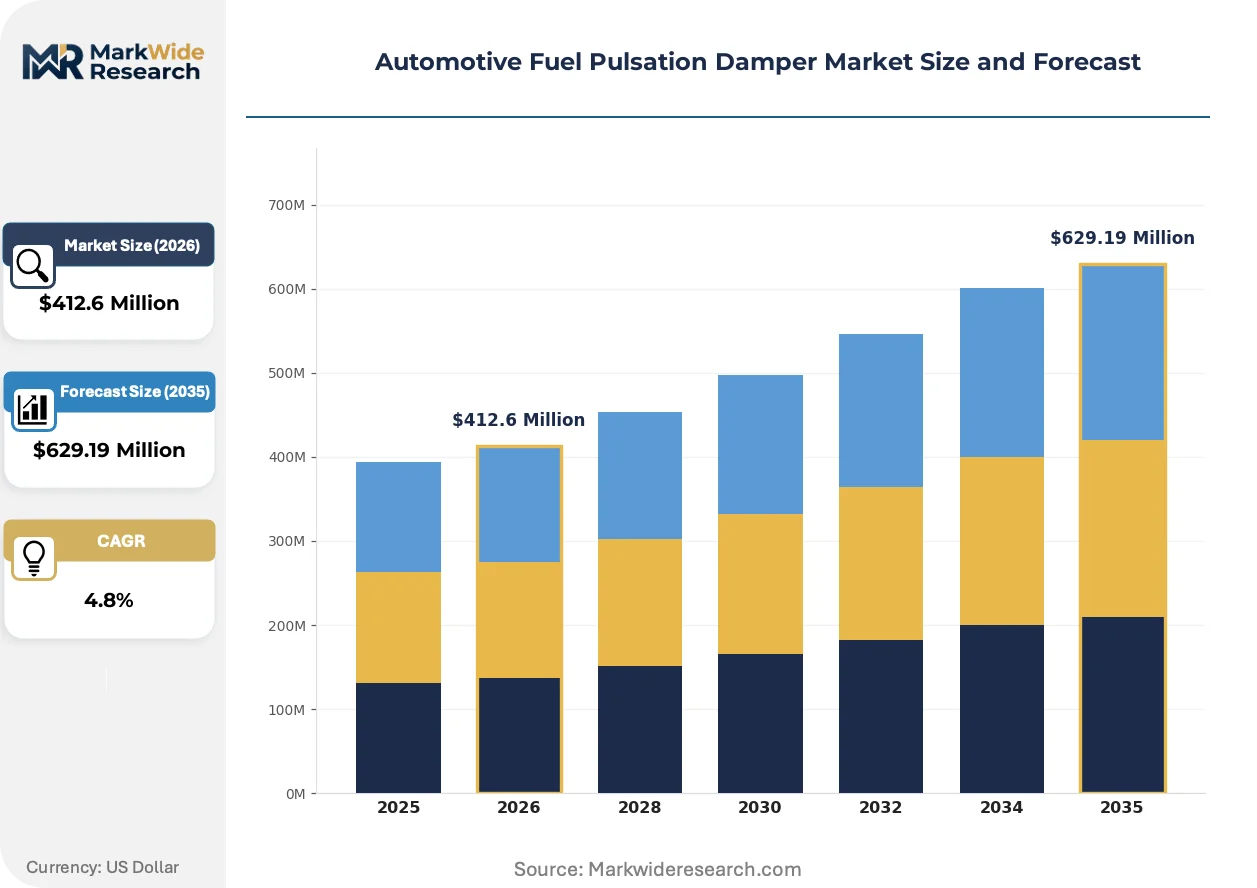
Market Dynamics
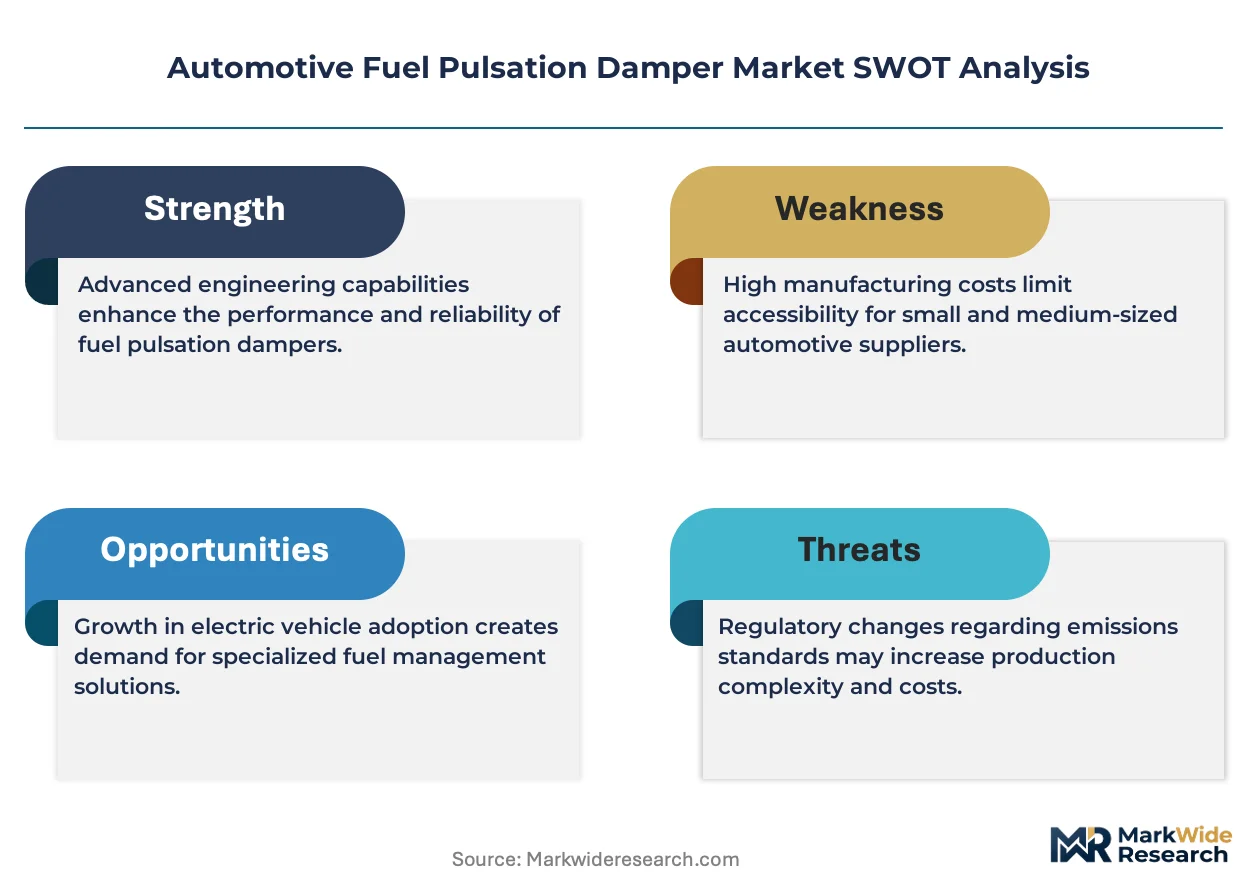
Electronic damping architectures are forcing a bifurcation between precision-capable suppliers and commodity assemblers, as Euro 7 and EPA emissions protocols mandate real-time fuel pressure control that mechanical dampers cannot deliver. This technology shift concentrates procurement power among OEMs with captive electronic module production.
Growth Catalysts
- Euro 7 emissions protocols:European OEMs are accelerating electronic damper adoption to meet stringent fuel system leakage benchmarks. The regulation mandates sub-gram evaporation rates that require adaptive pressure control.
- Lightweight material substitution:Aluminum and polymer composite dampers are displacing steel configurations in Germany, Japan, and South Korea as automakers pursue fleet efficiency targets.
- Precision machining specialization:In-house capability holders are securing long-term supply contracts through certified micro-finishing processes that outsourced assemblers cannot replicate.
Market Restraints
- Specialized elastomer supply concentration:Fluorocarbon diaphragm material sourcing clusters in Japanese and German chemical suppliers, creating input cost volatility for tier-two damper manufacturers.
- Electronic module capex thresholds:Real-time sensor integration and control firmware development require capital commitments that exclude sub-scale entrants from OEM qualification programs.
- Mechanical damper substitution ceiling:Cost-sensitive aftermarket channels retain demand for spring-loaded piston configurations, limiting electronic variant volume expansion in replacement segments.
Strategic Opportunities
- India commercial vehicle electrification:Compressed natural gas and hydrogen fuel cell bus programs under the PLI scheme create demand for high-pressure damping solutions in nascent alternative fuel infrastructure.
- Sensor-actuator convergence:Integration of piezoelectric pressure sensing with electromagnetic valve control enables predictive damping algorithms that differentiate premium electronic modules.
- Direct OEM contracting:Bypassing traditional tier-one system integrators through dedicated damper supply agreements allows margin capture from precision-certified specialists.
Industry Challenges
- Micro-finishing talent scarcity:CNC programming for sub-10-micron tolerance chambers requires specialized machinist training that vocational pipelines in manufacturing regions have not scaled to match demand.
- Multi-protocol certification timelines:Simultaneous EPA, EMA, and JIS fuel system integrity testing extends product validation cycles, compressing window for design iteration before model-year lock.
- Legacy rail interface compatibility:Electronic dampers must maintain mechanical interchangeability with existing fuel rail architectures while adding electrical connectors, complicating packaging engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fuel Pulsation Damper Market |
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Damper, Lightweight Damper, Heavy-Duty Damper, Custom Damper Component: Spring, Chamber, Fluid Reservoir, Sealing Element End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Technology: Pneumatic, Hydraulic, Mechanical, Electronic |
| Companies Covered | Continental, Bosch, Delphi Technologies, Magna International, Aisin Seiki, Schaeffler Group, Zhejiang Jincheng Auto, Parker Hannifin, Tenneco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fuel Pulsation Damper Market Emerging Trajectories
Adaptive control architectures and material substitution are reshaping competitive positioning in fuel pulsation damping. Real-time pressure modulation and gram-level mass reduction now separate qualified suppliers from commodity competitors.
Metal bellows configurations incorporating cobalt-nickel alloy membranes are decomposing traditional elastomeric diaphragm dominance in high-pressure direct injection applications. German and Japanese OEMs are specifying these variants for next-generation gasoline engines operating above 350 bar rail pressure. The technology is decomposing the historical cost-performance tradeoff that constrained metal bellows to racing and aerospace derivatives.
EPA Tier 4 and Euro 7 tailpipe standards are tightening permissible evaporative emissions from fuel system components to sub-0.5-gram-per-day leakage rates. These protocols mandate hermetic sealing architectures that accelerate electronic damper adoption over mechanical spring-piston alternatives. Passenger vehicle OEMs in Germany and South Korea are responding with dedicated fluid reservoir integration programs that consolidate damping and pressure regulation functions.
Consolidated procurement of damping modules alongside fuel rails and injectors is displacing discrete component sourcing at major OEM technical centers. Tier-one system integrators in Stuttgart, Nagoya, and Detroit are absorbing damper specification into complete delivery system contracts. South Korean automakers exhibit the most advanced integration, with Hyundai and Kia technical centers mandating single-supplier accountability for rail resonance performance.
Automotive Fuel Pulsation Damper Market Segmentation
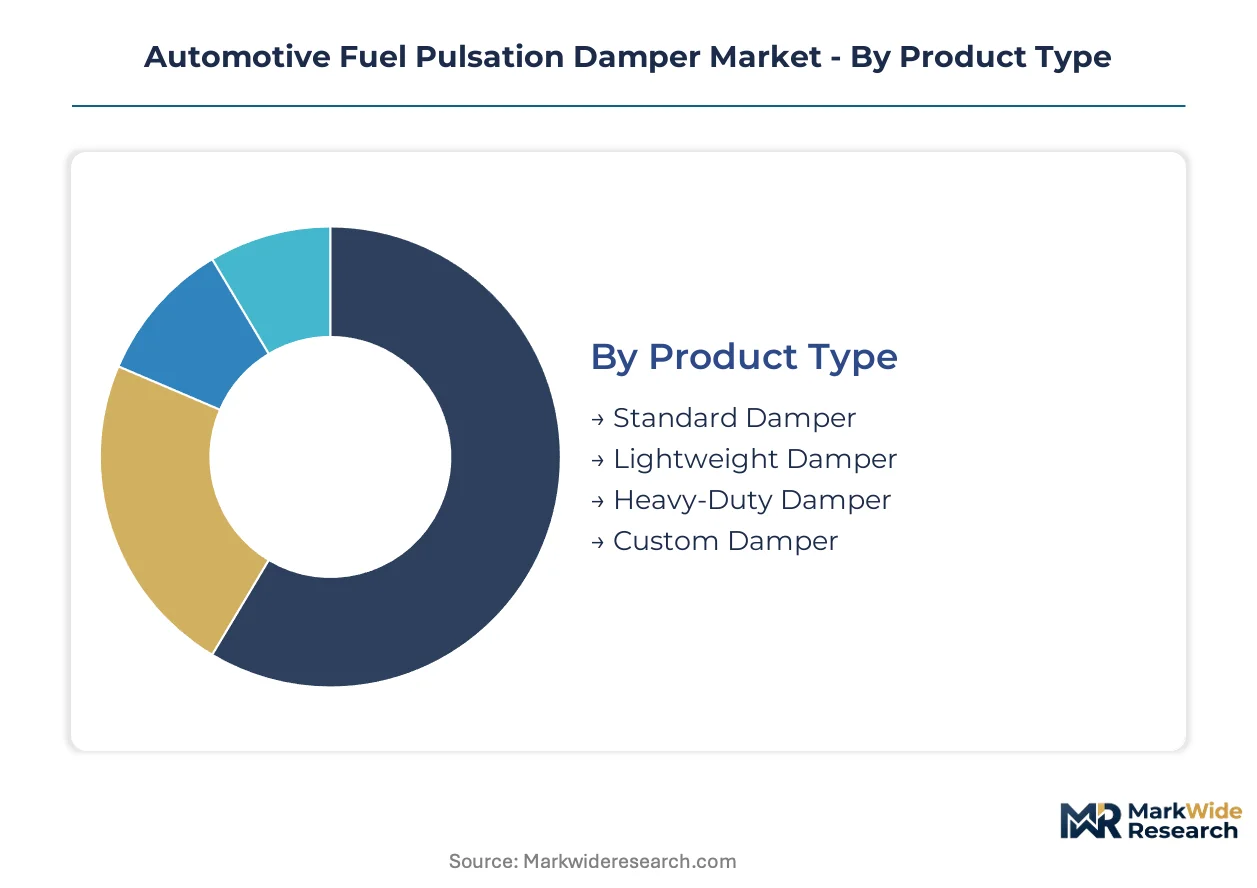
Fuel pulsation damper segmentation reveals distinct procurement channels for each product tier. OEMs source precision-certified variants through captive supply agreements, while aftermarket channels favor standardized mechanical configurations.
Product Type:
Lightweight dampers flow through direct OEM contracting channels, while heavy-duty variants concentrate in fleet procurement programs. Standard dampers dominate distributor networks serving independent repair facilities.
- Standard Damper:Steel-spring configurations with elastomeric diaphragms serve cost-sensitive replacement markets. Demand clusters in North American aftermarket channels where EPA compliance tolerances permit mechanical architectures.
- Lightweight Damper:Aluminum and polymer composite constructions achieve gram-level mass reduction for passenger vehicle OEMs. Procurement concentrates in Germany, Japan, and South Korea as automakers pursue fleet efficiency benchmarks.
- Heavy-Duty Damper:Reinforced chamber designs withstand commercial vehicle duty cycles.
- Custom Damper:Application-specific geometries for racing and specialty vehicle programs.
By volume, Standard Damper leads. By growth pace, Lightweight Damper is expanding most quickly.
Component:
Margin distribution across component tiers follows precision machining intensity. Fluid reservoirs and sealing elements command premium positioning due to hermetic integrity requirements.
- Spring:Coil and torsion configurations provide mechanical compliance in piston-based architectures. Demand concentrates in aftermarket channels where cost sensitivity favors replaceable spring elements over integrated modules.
- Chamber:CNC-machined aluminum housings with sub-10-micron tolerances form the pressure boundary. Procurement clusters with in-house capability holders in Stuttgart and Nagoya technical centers.
- Fluid Reservoir:Integrated damping-pressure regulation combinations.
- Sealing Element:Fluorocarbon diaphragms and metal bellows membranes.
By revenue contribution, Chamber leads. By certification complexity, Sealing Element faces the steepest expansion trajectory.
End User:
Customer type determines specification authority and contract structure. OEMs retain direct damper sourcing for electronic variants, while tier-one integrators control mechanical damper procurement.
- OEMs:Passenger vehicle manufacturers specify electronic damping modules for Euro 7 compliance. Sourcing concentrates at German, South Korean, and Japanese technical centers with captive electronic production.
- Aftermarket Providers:Independent distributors and service chains procure mechanical spring-piston configurations. Demand clusters in North American replacement markets where installation simplicity outweighs adaptive control benefits.
- Tier-1 Suppliers:System integrators consolidate rail-injector-damper procurement.
- Vehicle Assemblers:Contract manufacturers without captive fuel system design.
By contract value, OEMs lead. By transaction frequency, Aftermarket Providers dominate.
Technology:
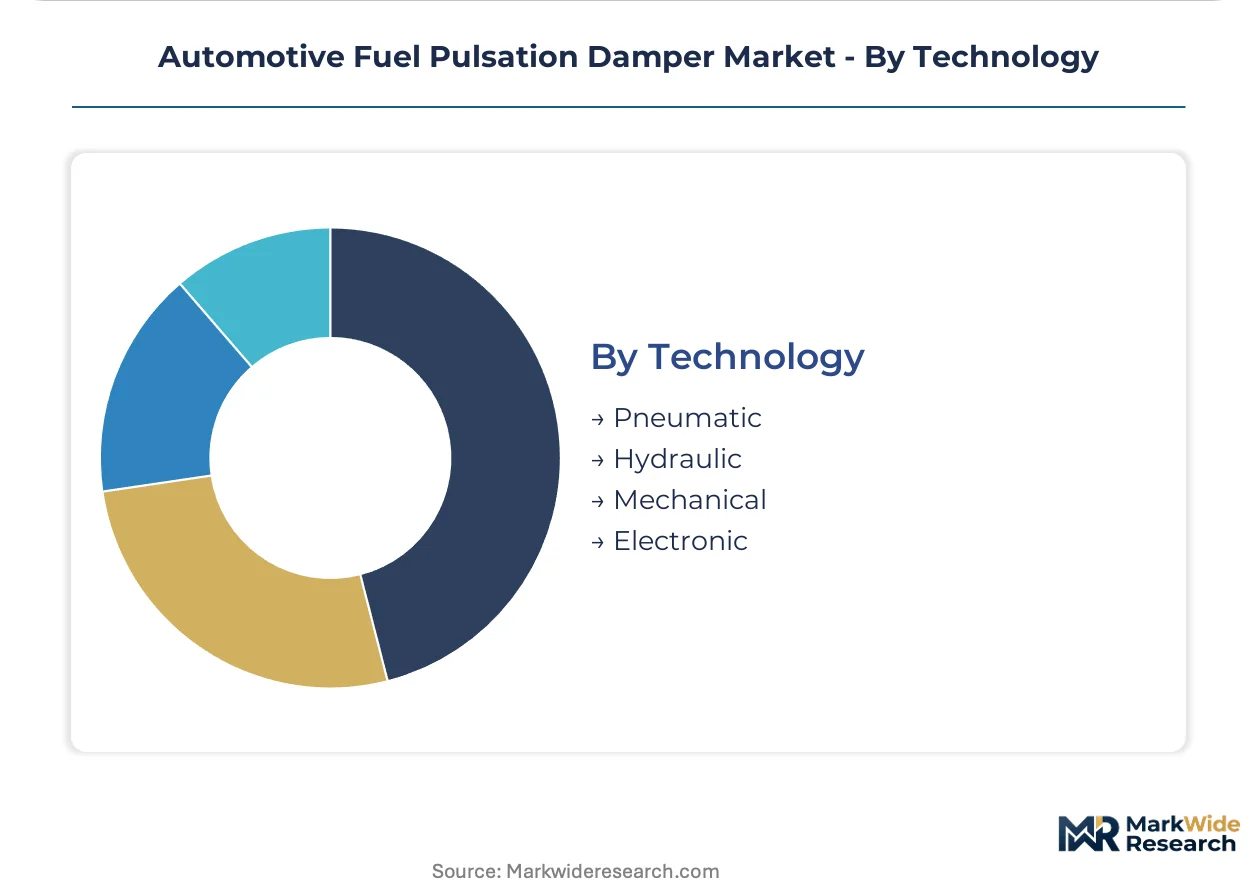
Technology tier aligns with regulatory intensity and price realization. Electronic architectures require firmware development capabilities that exclude sub-scale entrants.
- Electronic:Real-time sensor-actuator modules with adaptive pressure algorithms. Adoption concentrates in European and South Korean OEM programs responding to EPA and Euro 7 evaporation limits.
- Hydraulic:Fluid-based damping with fixed orifice configurations. Demand persists in commercial vehicle applications where cost constraints limit electronic module penetration.
- Mechanical:Spring-loaded piston architectures.
- Pneumatic:Air-spring or gas-charged configurations.
By installed base, Mechanical leads. By specification momentum, Electronic is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys electronic dampers at scale for Euro 7 compliance, while India and Brazil retain mechanical configurations for cost-sensitive commercial fleets. This consumption-mix differential reflects regulatory stringency gradients across development tiers.
Germany
Passenger vehicle OEMs source lightweight aluminum dampers through Stuttgart and Munich technical centers. KBA enforces type approval protocols that mandate hermetic sealing above 350 bar rail pressure. Bosch and Continental anchor supply through captive production facilities in Baden-Württemberg and Lower Saxony.
Japan
Integrated spring-and-chamber fabrication dominates procurement for gasoline direct injection platforms. METI administers JIS fuel system integrity benchmarks that constrain import competition. Nagoya-based technical clusters coordinate damping module specification with Toyota and Honda powertrain divisions.
South Korea
Hyundai and Kia technical centers mandate single-supplier accountability for rail resonance performance. MFDS oversees component certification timelines that compress design iteration windows. Seoul Capital Area procurement offices consolidate damping-injector-rail contracts under tier-one system integrators.
United States
Aftermarket channels absorb mechanical spring-piston configurations for legacy fleet maintenance. EPA Tier 4 tailpipe standards tighten evaporative emissions limits to sub-0.5-gram-per-day leakage rates. Detroit technical centers specify electronic modules for light-duty OEM programs while distributor networks serve independent repair facilities.
India
Compressed natural gas bus programs under the PLI scheme generate demand for high-pressure damping solutions. BIS certification requirements extend validation cycles for alternative fuel system components. Maharashtra and Gujarat manufacturing corridors host tier-two assemblers serving domestic commercial vehicle electrification.
Automotive Fuel Pulsation Damper Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive electronic module production separating qualified suppliers from commodity assemblers. Precision machining capability and firmware development resources concentrate procurement power among OEM-aligned fabricators. Two strategic archetypes dominate: diversified automotive component conglomerates with in-house damping divisions, and specialized fluid power manufacturers with certified micro-finishing processes. Competitive moves center on backward integration into fluorocarbon diaphragm supply and geographic expansion into Indian commercial vehicle electrification programs.
Among diversified automotive suppliers, Continental and Bosch exemplify the integrated archetype through European technical center anchoring. Aisin Seiki occupies a position within the Asian sourcing tier, representing specialized spring-and-chamber fabrication capabilities. These three names illustrate how geographic clustering around Stuttgart, Nagoya, and Seoul shapes competitive positioning without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Continental |
| Bosch |
| Delphi Technologies |
| Magna International |
| Aisin Seiki |
| Schaeffler Group |
| Zhejiang Jincheng Auto |
| Parker Hannifin |
| Tenneco |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day fluorocarbon diaphragm lead times from Japanese and German chemical suppliers concentrate input pricing power among tier-one damper manufacturers, while OEMs with captive electronic module production capture margin through long-term offtake structures that exclude spot-market participants from premium tier access.
Pricing Analysis
Long-term offtake agreements dominate OEM procurement of electronic damping modules, locking in volume commitments that insulate qualified suppliers from spot-price volatility in fluorocarbon elastomer feedstocks. Three-tier pricing structure across premium, standard, and economy levels separates precision-certified electronic variants from mechanical spring-piston configurations and unbranded aftermarket replacements. Pricing pressure stems from electronic module capex thresholds that compress margins for sub-scale entrants attempting tier-two qualification. Aftermarket distributors exhibit highest price sensitivity, favoring standardized steel-spring dampers over adaptive electronic architectures despite evaporative emissions compliance gaps.
Supply Chain Analysis
Japan and Germany anchor fluorocarbon diaphragm and precision-machined chamber production, while South Korea concentrates integrated damping-injector-rail module assembly for Hyundai and Kia programs. Raw material dependencies center on cobalt-nickel alloys for metal bellows membranes, aluminum billet for lightweight housings, and specialty fluorocarbon polymers for hermetic sealing elements. Single-source vulnerability runs through Japanese chemical suppliers controlling high-performance elastomer formulations. Distribution runs through tier-one system integrators in Stuttgart, Nagoya, and Seoul technical centers that consolidate component procurement under complete fuel delivery system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat, where Euro 7 and EPA certification timelines create switching costs that lock OEMs into qualified supplier relationships across multiple model-year cycles.
For Market Incumbents: Fortify backward integration into fluorocarbon diaphragm supply to neutralize Japanese chemical supplier pricing leverage, while expanding certified micro-finishing capacity in Baden-Württemberg and Lower Saxony to capture incremental OEM contracting. Electronic damper firmware development represents the priority capability barrier against emerging Asian module assemblers.
For New Entrants and Emerging Players: JIS fuel system integrity fast-track certification opens procurement access to Nagoya-based Toyota and Honda technical centers that remain underpenetrated by non-Japanese suppliers. India's PLI-funded CNG bus electrification programs offer the most penetrable white-space for high-pressure damping solutions, with BIS certification timelines compressing competitive response windows for established players.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive conglomerates seeking to divest non-core fluid power divisions lacking electronic module development resources. Precision-certified specialists with captive CNC micro-finishing and hermetic sealing capabilities represent the highest-conviction acquisition archetype. The signal to monitor is Euro 7 implementation delays that would temporarily extend mechanical damper demand and depress electronic variant valuation multiples.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorocarbon Diaphragm Supply | Neutralizes input cost volatility from Japanese and German chemical suppliers. |
| Electronic Module Firmware Development | Secures OEM qualification for Euro 7 adaptive pressure control mandates. |
| India Commercial Vehicle Electrification Expansion | Captures PLI-funded CNG and hydrogen fuel cell bus damping demand. |
| Precision Micro-Finishing Capacity Addition | Enables sub-10-micron tolerance chamber production for 350+ bar rail pressure. |
| Direct OEM Contracting Bypass | Eliminates tier-one integrator margin extraction from damper specification. |
Methodological Framework
Cross-validation between OEM platform engineering interviews and tier-one supplier procurement disclosures anchors the qualitative findings, with secondary validation from KBA type approval records, EPA Tier 4 certification databases, and METI JIS standard filings. Primary fieldwork encompassed fuel system engineers at Stuttgart, Nagoya, and Seoul technical centers, aftermarket distribution managers in North American replacement channels, and fluorocarbon material specialists at Japanese chemical suppliers. Bottom-up triangulation across vehicle production volumes, content-per-vehicle assumptions, and regional regulatory adoption curves reconciles with top-down market sizing from automotive component trade flows and SEC 10-K segment disclosures.
Sensitivity analysis around Euro 7 implementation timelines and electronic damper penetration rates stress-tests base-case assumptions across the projection horizon. Segmentation modeling spans product type, technology tier, end-user channel, and regional production cluster, with vehicle class and propulsion architecture as automotive-specific dimensions. CAGRs derive from regression analysis of historical adoption patterns against regulatory milestone dates, incorporating OEM platform lifecycle cadence and tier-two supplier qualification velocity as forecast inputs.
Decision-makers should treat outputs as directional under sustained EPA and Euro 7 regulatory stringency; material deviation in emissions protocol enforcement timelines would warrant model refresh. Recalibration cycles align with material shifts in OEM electronic module procurement decisions and alternative fuel infrastructure deployment under India's PLI scheme.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Fuel Pressure Regulator Market
Powertrain
Global Driveline Market
Powertrain
Automotive Fan Clutch Market
Powertrain
Motor Vehicle Carburetors Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Automotive Engine Degreasers Market
Powertrain
Automotive Clutch Actuator Market
Powertrain
Car Oil Filter Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Diesel Particulate Filter (DPF) Market
Powertrain
Automatic Transmission Market
Powertrain
Global Automotive Engine and Engine Mounts Market
Powertrain
Automotive Transmission System Market
Powertrain
United States Electro Hydraulic Power Steering Market
Powertrain
Automotive Fuel Feed Pumps Market
Powertrain
Mexico Electrically Powered Hydraulic Steering Market