
 Automotive Conversion Kit Market | 2026-2036
Automotive Conversion Kit Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Conversion Kit Market Outlook
ISO 6469 electric vehicle safety certification is rotating supplier eligibility toward firms with dedicated battery-system testing infrastructure. EV West leverages its California manufacturing base to dominate West Coast classic-car electrification projects. Electric Classic Cars anchors the premium heritage-vehicle segment with proprietary motor-mounting solutions for pre-1980 chassis architectures. Zelectric Motors competes through specialized Porsche and Volkswagen air-cooled platform expertise.
An automotive conversion kit constitutes an integrated hardware package enabling propulsion-system transformation of existing vehicle architectures, typically encompassing electric motor assemblies, battery modules with thermal management, power electronics, and adapted drivetrain couplers rated for specific torque outputs. The primary industrial purpose centers on extending vehicle service life while achieving regulatory compliance or operational cost reduction without full platform replacement. EV Conversion Kits capture the dominant margin pool as battery pack costs decline and fleet operators seek to defer capital expenditure on new commercial vehicle procurement. Classic Cars represent a high-attachment-rate application where emotional value justifies premium pricing for bespoke electrification builds. Fuel System Kits face structural pressure as CNG and LPG infrastructure investment stalls in key European markets.
EPA emission certification under 40 CFR Part 86 governs aftermarket engine conversions in the United States, while the EU Green Deal and Euro 7 standards accelerate ICE phase-out timelines that directly expand addressable kit demand. CARB executive orders for zero-emission commercial vehicles in California create a template other state regulators evaluate for adoption. Fleet procurement officers and workshop network managers must monitor regulatory harmonization between federal and state-level conversion standards to avoid stranded inventory in multi-jurisdiction operations.
Market Dynamics
Fleet procurement officers face compressed compliance windows as EPA tailpipe standards and Euro 7 emission norms tighten simultaneously, forcing rapid propulsion-system decisions on medium-duty commercial vehicles without full platform replacement.
Growth Catalysts
- EPA 40 CFR Part 86 certification pathways:Aftermarket engine conversions gain regulatory clarity in the United States, reducing compliance uncertainty for workshop networks serving commercial fleets.
- Battery pack cost trajectories:Declining lithium-ion cell prices improve total cost of ownership calculations for fleet operators evaluating retrofit versus replacement strategies.
- California CARB zero-emission mandates:Commercial fleet retrofit obligations create immediate demand concentration in the United States' largest state vehicle market.
Market Restraints
- Specialized technician scarcity:High-voltage battery system installation and ISO 6469 safety certification require skills absent in traditional internal combustion service networks.
- Legacy chassis compatibility limits:Pre-1990 vehicle architectures lack standardized mounting points, forcing costly custom fabrication for each conversion project.
- CNG and LPG infrastructure investment stalls:Fuel system kit demand faces structural pressure as European refueling network expansion pauses in key markets.
Strategic Opportunities
- Heritage-vehicle electrification:Classic car collectors in Germany and the United Kingdom demonstrate willingness to pay premium pricing for bespoke propulsion builds.
- Workshop certification programs:Authorized installer networks create captive distribution channels and recurring service revenue streams for kit suppliers.
- Modular battery swapping architectures:Commercial fleet operators in Japan pilot standardized pack formats that reduce vehicle downtime during energy replenishment.
Industry Challenges
- ISO 6469 testing infrastructure requirements:Battery-system safety certification demands capital-intensive laboratory facilities that exclude smaller suppliers from eligibility.
- Multi-jurisdiction regulatory harmonization gaps:Fleet operators managing cross-border routes face conflicting federal and state-level conversion standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Conversion Kit Market |
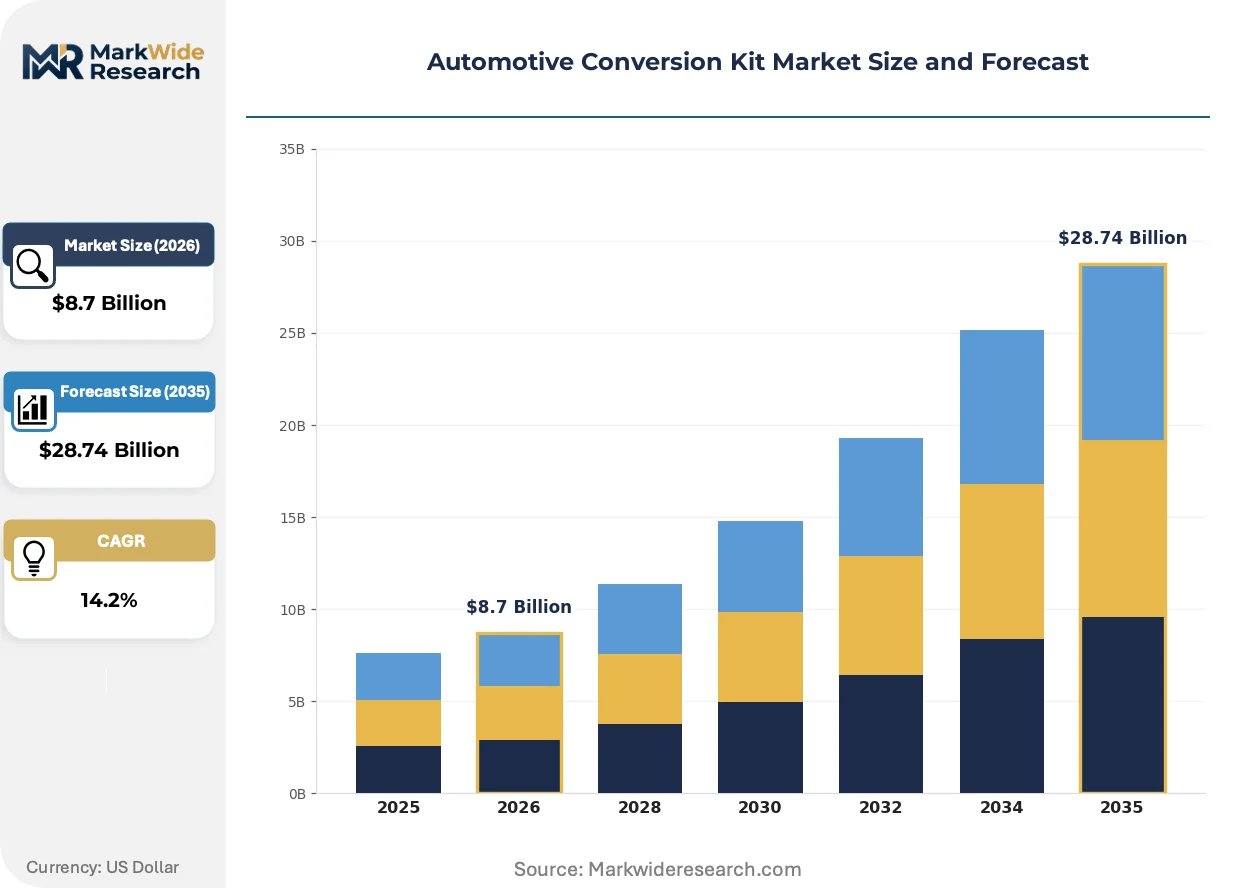
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: EV Conversion Kits, Engine Swap Kits, Fuel System Kits, Suspension Kits Application: Commercial Vehicles, Recreational Vehicles, Classic Cars, Motorcycles Technology: Hybrid Systems, Electric Drive Systems, Turbocharging, Fuel Injection End User: DIY Enthusiasts, Automotive Workshops, Fleet Operators, Manufacturers |
| Companies Covered | Electric Classic Cars, EV West, Electric GT, ZEV, Zelectric Motors, EV-propulsion, Revolt Systems, Stark Automotive, SkyCNG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Conversion Kit Market Strategic Shifts
Silicon carbide power electronics and modular thermal management architectures are compressing conversion timelines while expanding addressable vehicle age ranges. Three developments dominate supplier R&D roadmaps.
Integrated motor-inverter units with silicon carbide switching elements are miniaturizing power electronics packaging, enabling retrofit installations in engine bays originally designed for compact internal combustion blocks. Fleet operators in California adopt these compact drivetrains for medium-duty delivery vans. The reduced spatial footprint is compressing installation labor hours and expanding workshop throughput capacity.
The EU Green Deal and Euro 7 standards are accelerating internal combustion phase-out timelines across European Union member states. Commercial vehicle registration authorities in Germany and France now prioritize zero-emission retrofit certifications in permit processing queues. Medium-duty logistics fleets operating across the Benelux corridor face the most immediate compliance pressure.
Direct-to-fleet contracting models are displacing traditional parts-distribution channels for high-volume commercial operators. Tier-one suppliers in the United States now bypass regional distributors to negotiate enterprise service agreements with national fleet managers. California-based logistics operators pioneered this procurement shift, with similar patterns emerging in Texas and Illinois commercial vehicle markets.
Automotive Conversion Kit Market Segmentation
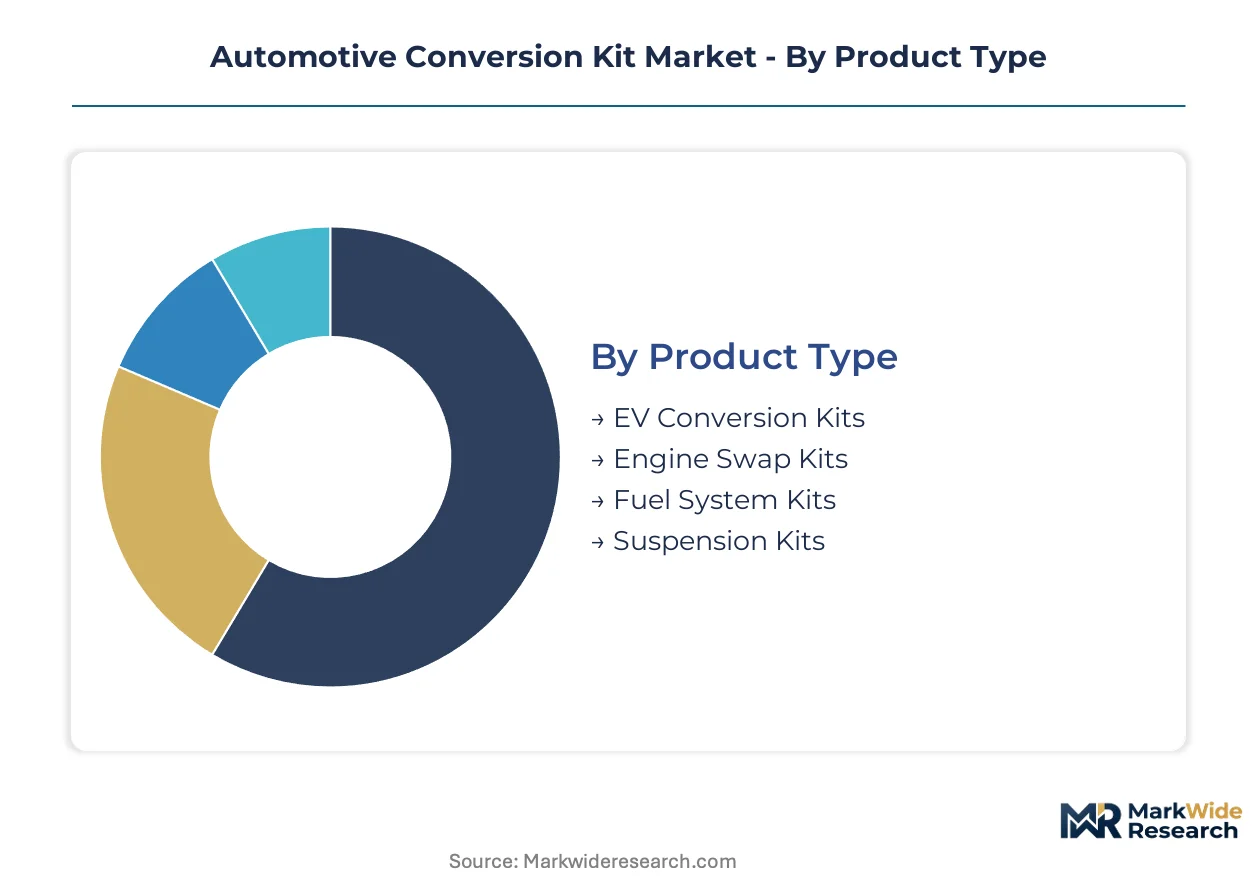
Segmentation in the automotive conversion kit market determines which supplier capabilities align with distinct procurement channels. Fleet operators, classic car collectors, and commercial workshops each trigger different kit specifications and certification requirements.
Product Type:
Direct-to-fleet contracting now bypasses traditional distribution for EV Conversion Kits and Engine Swap Kits, while Fuel System Kits and Suspension Kits still flow through regional parts networks.
- EV Conversion Kits:Integrated hardware packages encompassing electric motor assemblies, battery modules with thermal management, and adapted drivetrain couplers. Fleet operators in California concentrate procurement here as CARB zero-emission mandates compress compliance windows for medium-duty commercial vehicles.
- Engine Swap Kits:Complete propulsion system replacements including engine blocks, transmission adapters, and EPA 40 CFR Part 86 certification documentation. Classic car workshops in Germany and the United Kingdom drive demand where heritage-vehicle electrification faces owner resistance.
- Fuel System Kits:CNG and LPG conversion hardware for existing internal combustion platforms.
- Suspension Kits:Chassis modification components enabling weight distribution changes from battery pack installation.
EV Conversion Kits dominate installed base. Engine Swap Kits is where expansion concentrates.
Application:
Cost tier stratification separates Commercial Vehicles at enterprise contract pricing from Classic Cars at premium bespoke rates.
- Commercial Vehicles:Medium-duty delivery vans and logistics trucks requiring ISO 6469 safety certification. Fleet procurement officers across North American and European corridors prioritize these applications where total cost of ownership advantages offset retrofit capital expenditure.
- Classic Cars:Pre-1980 chassis architectures demanding proprietary motor-mounting solutions and custom fabrication. Collectors in Germany and the United Kingdom justify premium pricing through emotional attachment to heritage vehicles.
- Recreational Vehicles:Camper vans and motorhomes seeking range extension or emission compliance.
- Motorcycles:Two-wheel platforms with severe space constraints for battery packaging.
Commercial Vehicles anchor volume throughput. Classic Cars is climbing the fastest.
Technology:
Volume concentration favors Electric Drive Systems in fleet procurement, while Hybrid Systems retain niche positioning for range-anxious operators.
- Electric Drive Systems:Silicon carbide power electronics with integrated motor-inverter units miniaturizing packaging for compact engine bay retrofit. California-based logistics operators adopt these for medium-duty delivery vans where reduced spatial footprint compresses installation labor.
- Hybrid Systems:Dual-powertrain architectures preserving internal combustion range backup. Fleet operators across the Benelux corridor evaluate these where charging infrastructure gaps persist on cross-border routes.
- Turbocharging:Forced induction upgrades for retained internal combustion platforms.
- Fuel Injection:Precision fuel delivery optimization for emission compliance.
Electric Drive Systems dominates supplier R&D allocation. Hybrid Systems retains defensive positioning.
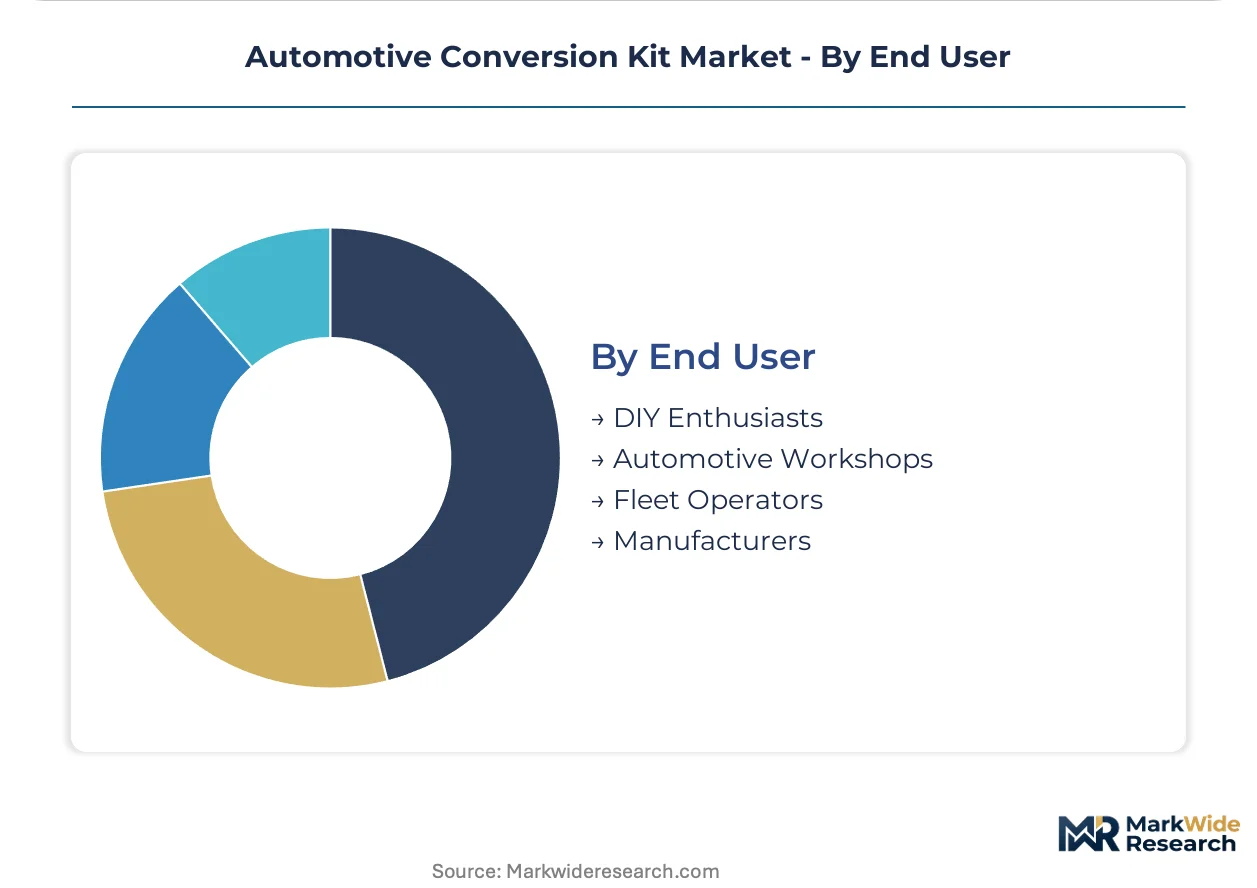
End User:
Customer type determines margin structure — Fleet Operators negotiate enterprise service agreements while DIY Enthusiasts absorb full retail markup.
- Fleet Operators:National logistics and delivery companies procuring through direct-to-fleet contracting models. Tier-one suppliers in the United States bypass regional distributors to negotiate enterprise service agreements with these high-volume commercial operators.
- Automotive Workshops:Authorized installer networks requiring ISO 6469 certification and high-voltage technician training. Workshop certification programs create captive distribution channels and recurring service revenue streams for kit suppliers.
- DIY Enthusiasts:Individual builders purchasing through retail channels with self-installation risk.
- Manufacturers:Vehicle OEMs integrating conversion capabilities into new platform design.
Fleet Operators command pricing leverage. Automotive Workshops is where supplier investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Subsidy programs and regulatory mandates are redrawing procurement maps for fleet operators and conversion workshops. National incentive structures now determine where capital flows fastest.
United States
California's CARB zero-emission mandates for commercial fleets generate immediate retrofit demand in the country's largest state vehicle market. EPA 40 CFR Part 86 certification pathways provide regulatory clarity for aftermarket engine conversions nationwide. Los Angeles and San Francisco logistics corridors concentrate procurement activity where medium-duty delivery operators face compressed compliance windows.
Germany
Commercial vehicle registration authorities prioritize zero-emission retrofit certifications in permit processing queues under EU Green Deal timelines. KBA type-approval requirements for modified propulsion systems shape supplier technical documentation standards. The Benelux corridor logistics operators face immediate compliance pressure, with conversion activity concentrating around Stuttgart and Munich industrial zones.
United Kingdom
Heritage-vehicle collectors demonstrate willingness to pay premium pricing for bespoke electrification builds of pre-1980 chassis architectures. DVSA safety certification requirements for modified vehicles establish compliance benchmarks for workshop networks. Classic car conversion specialists cluster in the Midlands and Home Counties where restoration infrastructure already exists.
Japan
Commercial fleet operators pilot standardized battery pack formats that reduce vehicle downtime during energy replenishment. METI technology roadmaps for electrification retrofits influence supplier R&D allocation decisions. Nagoya and Osaka manufacturing belts host workshop certification programs for high-voltage technician training.
France
Medium-duty logistics fleets operating across trans-Alpine routes evaluate hybrid system retrofits where charging infrastructure gaps persist. ANSM vehicle modification oversight aligns with EU Green Deal implementation timelines. Lyon and Marseille commercial vehicle corridors show rising conversion kit procurement as Euro 7 standards approach.
Automotive Conversion Kit Market Competitive Environment
Player mix skews toward regional specialists with certified installation networks rather than integrated manufacturing conglomerates. The vendor base separates into three functional tiers: heritage-vehicle boutiques, fleet-focused system integrators, and component subsystem suppliers. Consolidation pressure remains limited as technical certification requirements create defensible local positions. Geographic expansion and workshop certification programs constitute the dominant competitive moves as suppliers seek captive distribution channels.
Within the heritage-vehicle specialist tier, Electric Classic Cars and Zelectric Motors exemplify archetypes pursuing premium pricing through proprietary mounting solutions for air-cooled platforms. EV West occupies a position representing the regional system integrator model with concentrated West Coast presence. These three anchors illustrate how technical specialization and geographic focus combine to defend margin structure against broader industrial competitors.
| Leading Market Players |
|---|
| Electric Classic Cars |
| EV West |
| Electric GT |
| ZEV |
| Zelectric Motors |
| EV-propulsion |
| Revolt Systems |
| Stark Automotive |
| SkyCNG |
| Others |
Value Chain & Pricing Dynamics
Long-term enterprise service agreements lock in both lithium-ion cell supply access and price visibility for fleet procurement officers negotiating direct-to-fleet contracts with tier-one system integrators. California-based logistics operators pioneered this structure, with similar contracting patterns now emerging in Texas and Illinois commercial vehicle markets.
Pricing Analysis
Certification level creates the primary spread between ISO 6469-compliant premium tiers and uncertified economy offerings. Three-tier pricing structure across premium, standard, and economy levels dominates the market, with ISO 6469 battery-system testing infrastructure and CARB executive order documentation commanding substantial premiums. Cost compression in the economy tier is intensifying because smaller suppliers lack capital-intensive laboratory facilities. Fleet operators exhibit the lowest price sensitivity due to total cost of ownership calculations, while DIY enthusiasts absorb full retail markup without volume leverage.
Supply Chain Analysis
Container availability constraints on the Shanghai-Long Beach trade lane have elevated inbound logistics costs for battery module imports. Supply concentrates in China for lithium-ion cell manufacturing, South Korea for power electronics, and Germany for precision drivetrain couplers. The conversion kit ecosystem draws from silicon carbide substrates, thermal management fluids, and high-voltage cabling as critical inputs. Single-source vulnerability in battery cell supply creates structural exposure for Western kit assemblers. Distribution runs through authorized installer networks rather than traditional aftermarket parts distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks the commercial vehicle replacement cycle, with fleet operators deferring new platform procurement during capital expenditure contraction phases and accelerating retrofit adoption as compliance windows compress.
For Market Incumbents: Compound workshop certification coverage to create captive distribution channels before emerging battery-swapping specialists capture fleet service relationships. Prioritize backward integration into silicon carbide power electronics to defend margin position against component cost volatility. ISO 6469 testing infrastructure investments will exclude smaller competitors from regulatory eligibility pools. For New Entrants and Emerging Players: CARB fast-track certification for zero-emission commercial vehicles offers the most penetrable regulatory pathway for California market entry. Target the heritage-vehicle segment in Germany and the United Kingdom where emotional value justifies premium pricing and incumbent presence remains sparse. Pursue direct-to-collector digital marketing channels rather than traditional workshop networks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among workshop certification program operators with captive service agreements. Five-to-ten year viability favors suppliers with demonstrated ISO 6469 compliance and established fleet operator relationships. Watch for EPA 40 CFR Part 86 certification pathway expansions beyond California as the signal for demand inflection outside the current regulatory corridor.| Strategic Initiative | Industry Significance |
|---|---|
| Workshop Certification Program Expansion | Creates captive distribution channels and recurring service revenue streams for kit suppliers. |
| Silicon Carbide Power Electronics Integration | Compresses installation labor hours and expands workshop throughput capacity for fleet operators. |
| Direct-to-Fleet Contracting Model | Bypasses regional distributors to negotiate enterprise service agreements with national fleet managers. |
| Modular Battery Swapping Architecture | Reduces vehicle downtime during energy replenishment for commercial fleet operators in Japan. |
| Heritage-Vehicle Electrification Capability | Captures premium pricing from collectors in Germany and the United Kingdom for bespoke builds. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with fleet procurement officers, workshop network managers, high-voltage technician trainers, and battery system engineers; and secondary validation through EPA certification databases, CARB executive order filings, IHS Markit vehicle registration data, and EU Green Deal implementation trackers. Bottom-up triangulation across kit supplier production disclosures and top-down reconciliation against fleet operator procurement surveys anchored volume estimates.
Across the analysis window, the forecasting framework modeled segmentation by propulsion architecture, vehicle class, certification tier, and regional regulatory cluster. CAGRs were derived from regression analysis of historical fleet procurement patterns and projected compliance deadline impacts. Industry-specific inputs included lithium-ion cell price trajectories and ISO 6469 certification adoption curves.
Decision-makers should treat outputs as directional under sustained EPA and Euro 7 enforcement timelines; material deviation in regulatory implementation would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Gear Oil Market
Powertrain
Automotive Balance Shaft Market
Powertrain
South America Automotive Market
Powertrain
Automotive Power Steering Cooler Market
Powertrain
South Korea Automotive Engine Oils Market
Powertrain
Automotive Driveline Market
Powertrain
Asia Pacific Electrically Powered Hydraulic Steering Market
Powertrain
Test Automation Systems for Powertrain Dynamometer Market
Powertrain
Automotive Haptic Accelerator Pedal Market
Powertrain
Automotive Clutch Slave Cylinder Market
Powertrain
Diesel Engine Market
Powertrain
Fuel Pumps Market
Powertrain
South America Internal Combustion Engines Market
Powertrain
Turbocharger Actuators Market
Powertrain
Automotive Fuel Injection Pump Market
Powertrain
Global Automotive Exhaust Gas Turbochargers Market