
 Smart Heater Market | 2026-2036
Smart Heater Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Heater Market Insights
Residential retrofit demand is recalibrating how manufacturers allocate capacity across product lines. Rheem Manufacturing Company leverages its North American distribution network to dominate gas-to-electric conversion projects. Panasonic Corporation anchors its position through deep R&D intensity in heat pump integration. Haier Electronics Group Co. Ltd. competes on manufacturing scale, extending cost advantages into European markets.
A smart heater is an electrically or fuel-powered thermal device incorporating embedded sensors, connectivity modules, and algorithmic controls to modulate output based on occupancy, weather, or grid signals, typically operating between 1 kW and 15 kW for residential units. Its primary purpose is to deliver conditioned thermal energy while minimizing waste through predictive scheduling and demand-response compatibility. Wi-Fi Enabled technology leads volume shipments as utility rebate programs favor interoperable devices, though Voice-Controlled systems capture premium positioning through Amazon Alexa and Google Home ecosystem integration. Electric product types hold the broadest addressable base, while Infrared variants concentrate margin pools in commercial outdoor installations where rapid radiant response justifies higher unit economics.
The EU Green Deal, F-Gas Regulation, and CE marking framework collectively mandate minimum seasonal efficiency thresholds and refrigerant phase-down schedules that reshape product development roadmaps. The EPA in the United States enforces parallel efficiency standards through ENERGY STAR certification, narrowing market access for non-compliant imports. Stakeholders must monitor how building electrification mandates in Germany, France, and the United Kingdom interact with grid capacity constraints to determine whether infrastructure investment or product efficiency yields the tighter bottleneck for volume expansion.
Market Dynamics
The electrification of residential heating under the EU Green Deal is compressing product development cycles and forcing manufacturers to reconfigure supply chains around heat pump-compatible components.
Growth Catalysts
- F-Gas Regulation phase-down:The European Union's refrigerant restrictions are accelerating R&D investment in natural refrigerant systems and driving replacement demand for legacy gas-fired units.
- Building renovation wave:Germany, France, and the United Kingdom are deploying national retrofit subsidies that concentrate demand for connected thermal devices in multi-family housing.
- Wi-Fi module cost collapse:Semiconductor commoditization is embedding connectivity into mid-range residential units, expanding the addressable base for utility demand-response programs.
Market Restraints
- Copper and rare earth price volatility:Heat pump compressor manufacturing depends on concentrated Chilean copper supply and Chinese rare earth processing, creating margin compression during commodity spikes.
- Grid capacity constraints:Distribution infrastructure in rural Germany and northern England cannot support simultaneous mass electrification of heating without substantial utility capex.
- Natural gas price anchoring:Persistently low wholesale gas prices in North America delay consumer payback calculations for electric conversion projects.
Strategic Opportunities
- Polish and Romanian residential stock:These markets exhibit low heat pump penetration rates and rising building efficiency standards under EU cohesion funding.
- Commercial outdoor infrared:Hospitality and municipal sectors in Mediterranean climates are adopting rapid-response radiant systems for terrace heating.
- Voice-control ecosystem integration:Amazon Alexa and Google Home certification programs create premium positioning and recurring service revenue streams.
Industry Challenges
- Heat pump installer certification backlog:F-gas handling licenses and electrical competency requirements create bottlenecks for deployment velocity in the United Kingdom and Germany.
- Legacy hydronic system incompatibility:Existing radiator sizing and pipework configurations in 1970s European housing stock resist low-temperature heat pump optimization without full renovation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Heater Market |
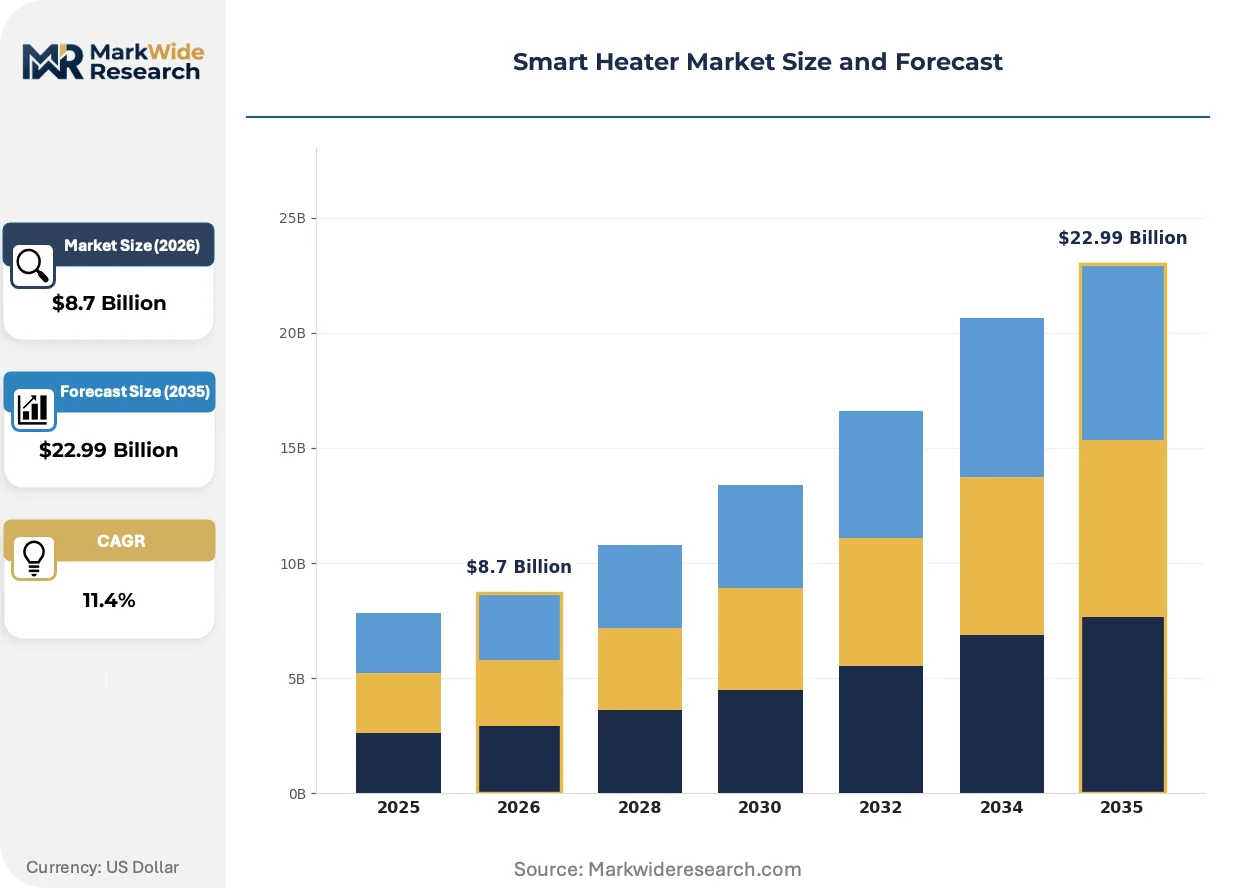
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas, Infrared, Oil-filled Technology: Wi-Fi Enabled, Bluetooth, Smart Thermostat, Voice-Controlled Application: Residential, Commercial, Industrial, Outdoor End User: Homeowners, Tenants, Businesses, Contractors |
| Companies Covered | Honeywell International Inc., Carrier Global Corporation, Panasonic Corporation, Rheem Manufacturing Company, Electrolux AB, LG Corporation, Haier Electronics Group Co. Ltd., Dyson Ltd., Mitsubishi Electric Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Heater Market Trends and Innovations
Algorithmic control systems are displacing static thermostatic regulation across residential and light commercial installations, compressing the value capture toward software and data layers.
Heat pump inverter architecture is modularizing around standardized refrigerant circuits and detachable communication modules. Residential installers in Germany and the Netherlands are specifying field-replaceable control boards to reduce service call duration. This modularity is compressing manufacturer service revenue while expanding third-party maintenance market entry.
The EPA's ENERGY STAR 5.0 certification requirements for connected thermal devices are narrowing market access for non-compliant imports. Test procedure updates now mandate verified performance under partial-load conditions. Electric resistance manufacturers serving the US market are responding by integrating predictive occupancy algorithms to maintain certification eligibility.
Utility rebate program administrators are consolidating procurement specifications around interoperable OpenADR protocols. Large multi-family developers in California and New York now require pre-certified demand-response compatibility as a bid precondition. This specification tightening is displacing proprietary communication stacks and concentrating volume among chipset vendors with pre-integrated certification.
Smart Heater Market Segmentation
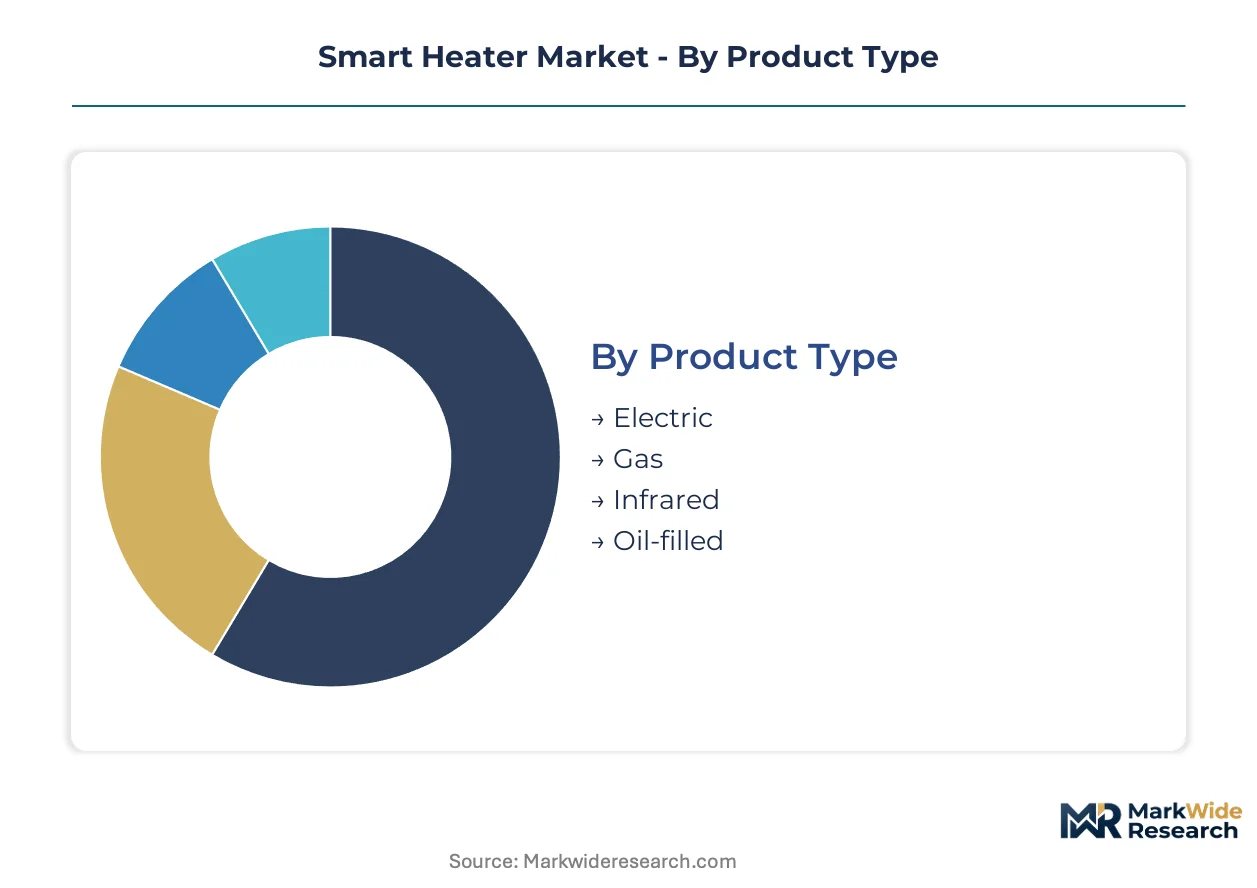
Smart heater procurement patterns diverge sharply across installation contexts and buyer sophistication levels. Segment boundaries determine which connectivity protocols, control interfaces, and thermal output ranges manufacturers must prioritize in regional product roadmaps.
Product Type:
Buyer cost tiers and retrofit complexity separate the four product categories.
- Electric:Resistance-element or heat-pump architectures dominate residential retrofits where grid capacity permits. German and French multi-family housing subsidies concentrate demand for 3-6 kW wall-mounted units with OpenADR compatibility.
- Gas:Condensing boilers and hybrid systems retain share in North American single-family construction where natural gas distribution density supports payback calculations. Low wholesale gas prices in the United States delay electrification timelines.
- Infrared:Rapid-response radiant panels command premium positioning in Mediterranean hospitality terraces and municipal outdoor installations.
- Oil-filled:Legacy convection technology persists in rural Eastern European markets with intermittent grid reliability.
Electric configurations lead volumes today; Infrared variants are gaining share fastest in commercial outdoor applications.
Technology:
Control interface sophistication determines utility rebate eligibility and ecosystem integration depth.
- Wi-Fi Enabled:TCP/IP connectivity modules enable remote scheduling, firmware updates, and demand-response signaling through utility backhaul networks. California and New York multi-family developers now mandate OpenADR pre-certification as a bid precondition.
- Voice-Controlled:Amazon Alexa and Google Home certification programs create premium positioning and recurring service revenue streams through ecosystem lock-in.
- Smart Thermostat:Integrated sensor arrays with predictive occupancy algorithms maintain ENERGY STAR 5.0 eligibility under EPA partial-load test procedures.
- Bluetooth:Short-range protocols serve price-sensitive segments where cloud connectivity adds unacceptable hardware cost.
Wi-Fi Enabled systems dominate shipment volumes; Voice-Controlled installations show the steepest expansion trajectory in premium residential retrofits.
Application:
Installation environment dictates thermal output range, weatherproofing requirements, and control granularity.
- Residential:Single-family and multi-family installations drive the bulk of connected device shipments, with EU Green Deal renovation subsidies concentrating demand in Germany, France, and the United Kingdom.
- Commercial:Office, retail, and hospitality applications require zone-level control and centralized building management system integration.
- Industrial:Process heating and warehouse applications prioritize thermal output density over connectivity sophistication.
- Outdoor:Terrace, patio, and municipal plaza installations favor rapid-response infrared radiant systems with IP65 weatherproofing ratings.
Residential applications anchor volume; Outdoor segments are climbing the fastest as Mediterranean hospitality operators expand heated terrace capacity.
End User:
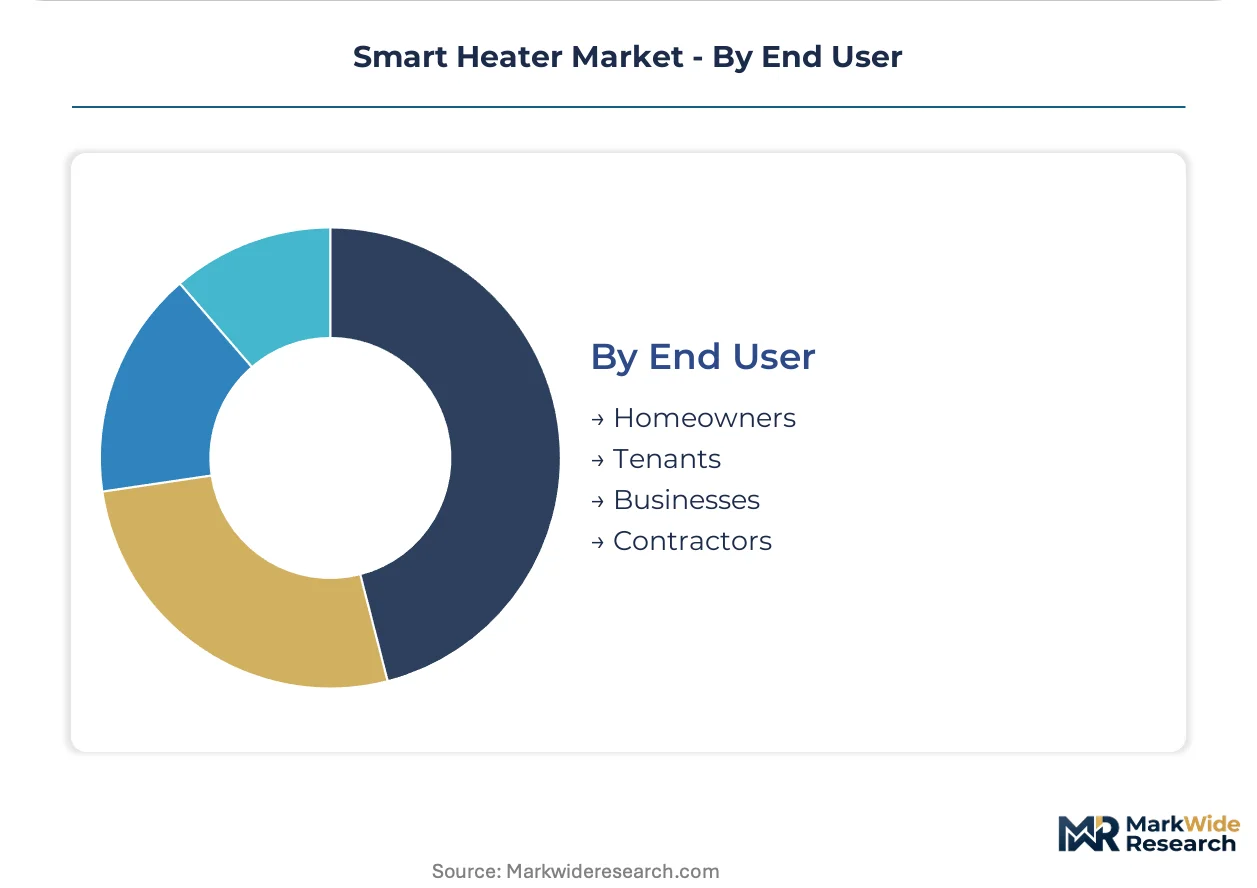
Decision-making authority and financing mechanisms split procurement behavior across four buyer types.
- Homeowners:Direct purchasers in single-family detached housing prioritize payback period and utility rebate capture, with German KfW subsidies influencing technology selection.
- Contractors:Installation firms serving renovation markets specify field-replaceable control boards to compress service call duration and expand maintenance revenue.
- Businesses:Corporate facility managers demand enterprise-grade fleet management dashboards and centralized demand-response aggregation.
- Tenants:Rental housing occupants lack capital authority and rely on landlord-installed infrastructure, creating split-incentive friction for efficiency upgrades.
Homeowners represent the largest addressable base; Contractors are expanding most quickly as installer certification backlogs create service market entry opportunities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ruhr industrial corridor concentrates heat pump manufacturing capacity as German electrification mandates reshape procurement patterns across the European Union. National retrofit subsidy programs and grid infrastructure constraints create divergent deployment velocities across major markets.
Germany
The KfW renovation subsidy program drives multi-family housing conversions toward heat pump-compatible electric systems. The F-Gas Regulation accelerates natural refrigerant R&D investment across Bavarian and North Rhine-Westphalian manufacturing clusters. Berlin-Brandenburg hosts installer certification bottlenecks that constrain deployment velocity despite subsidy availability.
France
MaPrimeRénov subsidy tiers concentrate demand for connected thermal devices in Île-de-France and Auvergne-Rhône-Alpes housing stock. The EU Green Deal efficiency mandates interact with the country's nuclear baseload capacity to support electrification economics. Lyon-Grenoble industrial clusters specialize in inverter compressor production for residential heat pumps.
United Kingdom
The Boiler Upgrade Scheme faces installer certification backlogs that delay heat pump deployment in northern England and Scotland. Ofgem grid capacity constraints in rural distribution networks limit simultaneous mass electrification. The Midlands manufacturing corridor supplies control module components to domestic and export markets.
United States
EPA ENERGY STAR 5.0 certification requirements narrow market access for non-compliant imports serving California and New York multi-family developers. Low wholesale natural gas prices in Texas and the Southeast delay consumer payback calculations for electric conversion projects. The Pacific Northwest concentrates utility demand-response program administration.
China
Dual carbon goals and building efficiency standards under MIIT guidance expand heat pump production capacity in the Yangtze River Delta. GB standards for connected appliances create domestic certification requirements that parallel export market specifications. Shandong Province hosts compressor manufacturing clusters serving European and North American OEM contracts.
Smart Heater Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers reconfigure supply chains around heat pump-compatible components. The vendor base stratifies across three tiers: diversified industrial conglomerates with captive distribution networks, specialized thermal equipment fabricators with regional installer relationships, and technology licensors supplying control algorithms and connectivity modules. Strategic archetypes include scale-driven cost competitors, R&D-intensive system integrators, and ecosystem platform operators. M&A activity and geographic licensing agreements represent the dominant competitive moves as firms secure refrigerant handling certifications and installer training capacity.
Among Asia-Pacific-based conglomerates, Panasonic Corporation, Haier Electronics Group Co. Ltd., and LG Corporation exemplify divergent strategic positioning. Panasonic anchors the R&D-intensive system integrator archetype through deep investment in heat pump inverter architecture. Haier occupies the scale-driven manufacturing position, extending cost advantages into European retrofit markets. LG sits within the ecosystem platform tier, leveraging connectivity module integration to capture utility demand-response program specifications. North American and European incumbents including Rheem Manufacturing Company and Carrier Global Corporation defend position through installer network density and field-replaceable control board specifications.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Carrier Global Corporation |
| Panasonic Corporation |
| Rheem Manufacturing Company |
| Electrolux AB |
| LG Corporation |
| Haier Electronics Group Co. Ltd. |
| Dyson Ltd. |
| Mitsubishi Electric Corporation |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up installer networks in the United Kingdom and Germany are consolidating purchasing power and compressing distributor margins while amplifying price transparency across heat pump-compatible equipment tiers.
Pricing Analysis
Distributor margin layers absorb the steepest compression as European multi-family developers consolidate procurement around OpenADR-certified units. Three-tier pricing structure across premium voice-controlled, standard Wi-Fi-enabled, and economy Bluetooth-only levels segments buyer access to utility rebate programs. Cost compression in mid-range electric units is intensifying because semiconductor commoditization embeds connectivity at marginal hardware cost. Contractor-led renovation projects exhibit the highest price sensitivity, while hospitality operators specifying outdoor infrared systems demonstrate minimal elasticity.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from German and French national retrofit programs, bypassing traditional distribution layers for multi-family housing contracts. Manufacturing concentrates in China, Germany, and Japan, with compressor production anchored in Shandong Province and Bavarian industrial clusters. Rare earth processing from Chinese refineries and Chilean copper cathode supply feed heat pump inverter assembly. Single-source vulnerability in refrigerant-grade copper tubing creates exposure during commodity spikes. Distribution runs through certified installer networks rather than retail channels in European electrification markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
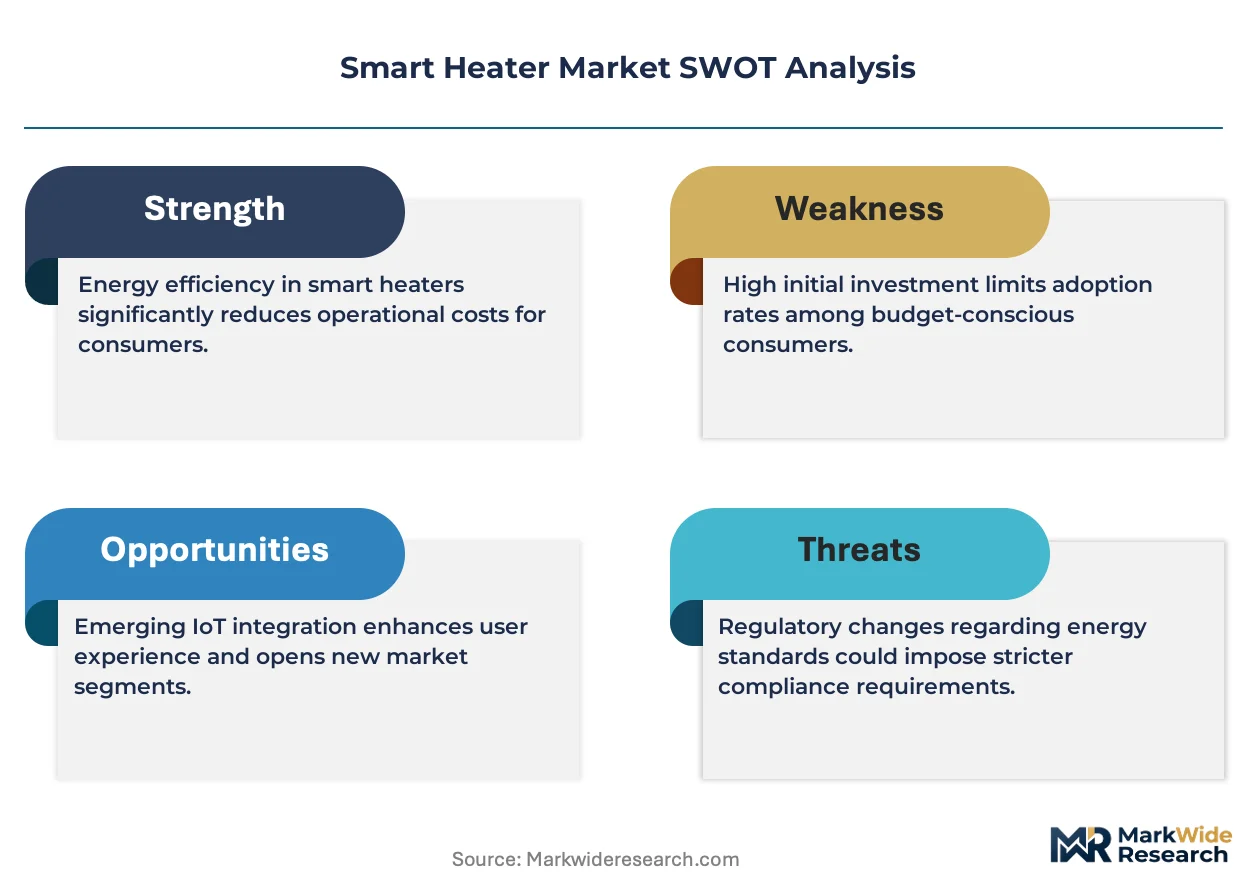
The Smart Heater Market functions as a regulatory compounder where EU Green Deal efficiency mandates and F-Gas Regulation phase-down schedules mechanically expand replacement demand regardless of consumer sentiment cycles.
For Market Incumbents: Acquire installer certification capacity to lock out emerging competitors facing F-gas handling license backlogs in the United Kingdom and Germany. Secure captive supply of natural refrigerant compressors before 2025 regulatory deadlines tighten. Vertical integration into field-replaceable control board manufacturing defends service revenue against third-party maintenance entrants. For New Entrants and Emerging Players: The EU Green Deal in Poland and Romania opens a window for low-cost electric resistance units ahead of building efficiency standard enforcement. Polish residential stock exhibits minimal heat pump penetration and rising subsidy eligibility under cohesion funding. Voice-control ecosystem certification creates premium positioning without manufacturing scale requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized thermal equipment fabricators with regional installer relationships but without captive connectivity module production. Five-to-ten-year viability hinges on refrigerant handling certification portability across national regulatory regimes. Monitor German grid capacity investment announcements as the inflection signal for electrification velocity ceilings.| Strategic Initiative | Industry Significance |
|---|---|
| Natural Refrigerant R&D Investment | EU F-Gas Regulation phase-down mandates accelerate compressor architecture redesign in Bavarian manufacturing clusters. |
| Installer Certification Acquisition | F-gas handling license backlogs in Berlin-Brandenburg constrain deployment velocity and create defensive moats. |
| OpenADR Protocol Integration | California and New York utility rebate programs now mandate pre-certified demand-response compatibility as bid precondition. |
| Voice-Control Ecosystem Partnership | Amazon Alexa and Google Home certification programs generate recurring service revenue through platform lock-in. |
| Field-Replaceable Control Board Specification | German and Dutch installers prioritize modular designs to compress service call duration and expand maintenance market entry. |
Research Methodology
Bottom-up residential retrofit modeling reconciled against top-down heat pump component production tracking forms the analytical core of this study. Primary interviews with HVAC contractor procurement leads, utility demand-response program administrators, F-gas certification body officials, and multi-family housing developers combined with secondary validation from EU Green Deal implementation reports, EPA ENERGY STAR certification databases, and national customs trade records. Top-down supply-side analysis triangulates against bottom-up demand segmentation across technology tiers and installation contexts.
Input-output matrices map heat pump inverter production capacity, rare earth magnet supply, and copper cathode availability against electrification subsidy deployment rates and grid infrastructure investment schedules across the analysis window. Segmentation dimensions include product architecture, control interface sophistication, installation environment, and buyer decision-making authority. CAGRs derive from regression analysis of historical efficiency mandate adoption curves and retrofit subsidy penetration rates, stress-tested against copper price volatility scenarios and installer certification velocity constraints.
Revisions become necessary when grid capacity constraints in rural Germany or northern England trigger electrification moratoria, or when natural refrigerant patent thickets delay compressor commercialization. Forecasts reflect documented assumptions about subsidy program continuity and F-Gas Regulation enforcement intensity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electrical Equipment
Axial Fans Market
Electrical Equipment
High Voltage Electric Capacitor Market
Electrical Equipment
Global Busbar Trunking Market
Electrical Equipment
Circuit Breaker and Fuses Market
Electrical Equipment
North America Commercial Lighting Control Market
Electrical Equipment
US Electric Enclosure Market
Electrical Equipment
North America Low Voltage Induction Motors Market
Electrical Equipment
High Voltage Switchboard Market
Electrical Equipment
Global Panelboards Market
Electrical Equipment
Saudi Arabia Electric Motor Market
Electrical Equipment
China DC Motor Market
Electrical Equipment
High Voltage Electric Heater Market
Electrical Equipment
Terminal Block Market
Electrical Equipment
Global Digital Panel Meter Market
Electrical Equipment
Vacuum Interrupter Market
Electrical Equipment
Global Electrical Steel Market