
 Germany Electric Vehicle Battery Manufacturing Equipment Market | 2026-2036
Germany Electric Vehicle Battery Manufacturing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Electric Vehicle Battery Manufacturing Equipment Market Insights
Market Dynamics
High-precision coating and drying specifications is bifurcating the competitive landscape into premium and mid-tier equipment tiers. Dürr AG leverages its paint-line heritage to dominate vacuum drying systems for electrode production. Schuler AG anchors its position through deep specialization in high-speed stacking and winding machines. Robert Bosch Manufacturing Solutions GmbH differentiates via integrated process control software that spans assembly through quality verification.
Technology and Segmentation
Germany Electric Vehicle Battery Manufacturing Equipment encompasses machinery for electrode preparation, cell assembly, formation, and testing, with coating uniformity tolerances below 2% and drying temperatures exceeding 120°C serving as critical performance thresholds. Assembly Machines and Testing Equipment capture the deepest margin pools, as OEMs and Tier-1 Suppliers prioritize in-line quality verification and traceability. Lithium-ion technology sustains near-term volume leadership, while Solid State equipment represents the fastest-growing technology segment as pilot lines scale toward commercial readiness.
Regulatory Environment
The EU Battery Regulation and CE marking requirements shape equipment standards, mandating carbon-footprint disclosure and recycled-material traceability that forces manufacturers to retool for compliance. KBA type-approval protocols and Germany's national implementation of the EU Green Deal accelerate demand for energy-efficient drying and solvent-recovery systems. Stakeholders must monitor how delegated acts under the Battery Regulation tighten performance benchmarks before committing to long-dated equipment contracts.
Market Dynamics
The EU Battery Regulation's recycled-content mandates and carbon-footprint disclosure requirements are forcing equipment manufacturers to redesign coating, drying, and formation systems for traceability compliance, compressing procurement timelines as OEMs race to secure qualified suppliers before delegated acts tighten.
Growth Catalysts
- EU Green Deal implementation:Germany's national climate targets accelerate investment in energy-efficient drying and solvent-recovery systems that reduce operational emissions at cell factories.
- Solid-state pilot scaling:Bavarian research clusters and industrial consortia are pulling specialized formation and dry-room equipment into commercial production lines ahead of mass manufacturing.
- Automotive OEM captive production:Volkswagen Group and BMW Group's direct investment in cell manufacturing is creating dedicated demand for high-speed stacking and winding machinery with integrated quality verification.
Market Restraints
- Specialized steel and precision component supply:Dependence on Japanese and South Korean suppliers for ultra-high-precision bearings and vacuum chamber materials creates input cost volatility and extended lead times.
- CE marking and KBA type-approval complexity:Divergent certification timelines between EU harmonized standards and Germany's national implementation create regulatory friction that delays equipment commissioning.
- Technical limitation in dry electrode coating:Current binder dispersion and calendering equipment cannot yet achieve the throughput and uniformity tolerances required for solid-state cell formats at commercial scale.
Strategic Opportunities
- North Rhine-Westphalia industrial corridor:Underdeveloped compared to Bavaria, this region offers greenfield sites with access to renewable energy infrastructure and chemical industry feedstocks for cathode active material processing equipment.
- Battery passport compliance services:The EU Battery Regulation's digital tracking mandate creates white space for equipment-integrated data architecture and blockchain-enabled traceability modules.
- Second-life battery disassembly automation:Emerging regulatory obligations for end-of-life processing are pulling robotic dismantling and diagnostic equipment into new application areas beyond cell manufacturing.
Industry Challenges
- Electrochemical engineering and automation software integration:Scarcity of professionals who bridge cell chemistry expertise with programmable logic controller and machine vision system deployment slows commissioning timelines.
- Cleanroom and dry-room infrastructure capex:Dew point requirements below minus 40 degrees Celsius for solid-state electrode handling demand substantial upfront investment in facility conditioning systems that strain project financing.
- Legacy automotive quality system integration:Equipment suppliers must reconcile semiconductor-grade traceability protocols with existing automotive IATF 16949 audit structures, creating documentation burden and timeline extension.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Electric Vehicle Battery Manufacturing Equipment Market |
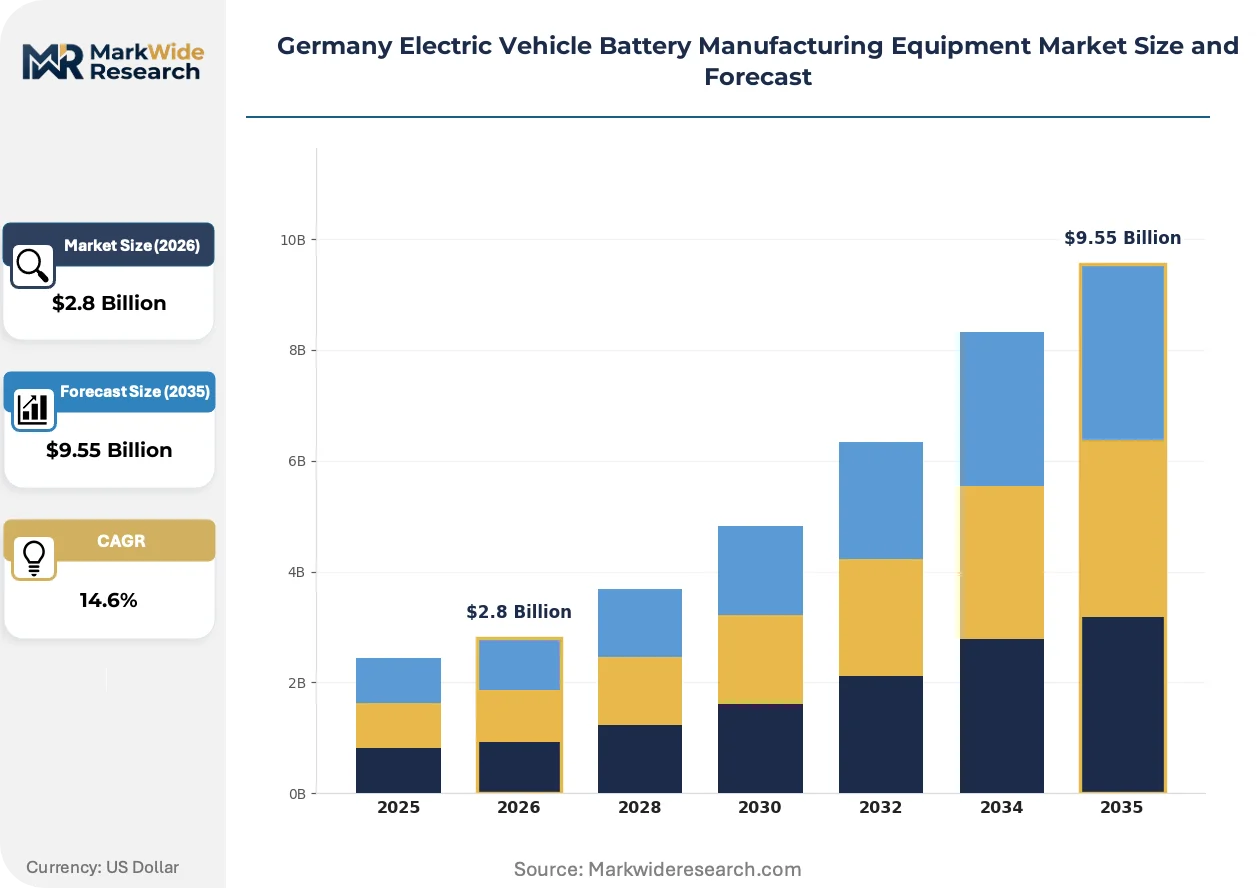
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assembly Machines, Testing Equipment, Automation Solutions, Charging Stations Technology: Lithium-ion, Solid State, Flow Batteries, Nickel Metal Hydride End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Research Institutions Size: Large-Scale, Mid-Scale, Small-Scale, Compact |
| Companies Covered | Dürr AG, Schuler AG, Hitachi Ltd, Xiamen Tmax Battery Equipments Limited, ACEY New Energy Technology, IPG Photonics Corporation, Wuxi Lead Intelligent Equipment Co Ltd, Robert Bosch Manufacturing Solutions GmbH, Targray Technology International Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Electric Vehicle Battery Manufacturing Equipment Market Trends and Innovations
Equipment architecture is pivoting from standalone machines toward integrated process islands where coating, drying, calendering, and slitting operations share control systems and environmental envelopes, compressing factory footprints and energy intensity.
Electrode manufacturing is fragmenting as dry electrode coating technology eliminates solvent-based slurry processing and the associated drying energy load. Cell producers in Bavaria and Baden-Württemberg are piloting this transition at limited scale. The structural consequence is compressing the competitive advantage of incumbent wet-coating equipment specialists who must now develop parallel dry-process capabilities or cede early solid-state contracts.
Delegated acts under the EU Battery Regulation are mandating carbon-footprint thresholds for battery cells placed on the European market. Equipment manufacturers must now certify energy consumption per unit output and solvent recovery rates as part of CE conformity assessment. German cell factories are responding by specifying heat pump-based drying systems and closed-loop N-methyl-2-pyrrolidone recovery in new procurement tenders.
Buyer concentration among three major automotive OEMs running captive cell production is compressing negotiation leverage for equipment vendors. Tier-1 suppliers and independent cell producers are being displaced from early equipment allocation as OEMs prioritize direct supplier relationships for strategic assembly and formation lines. This pattern is most visible in Saxony, where a single OEM's gigafactory absorbs regional engineering capacity.
Germany Electric Vehicle Battery Manufacturing Equipment Market Segmentation
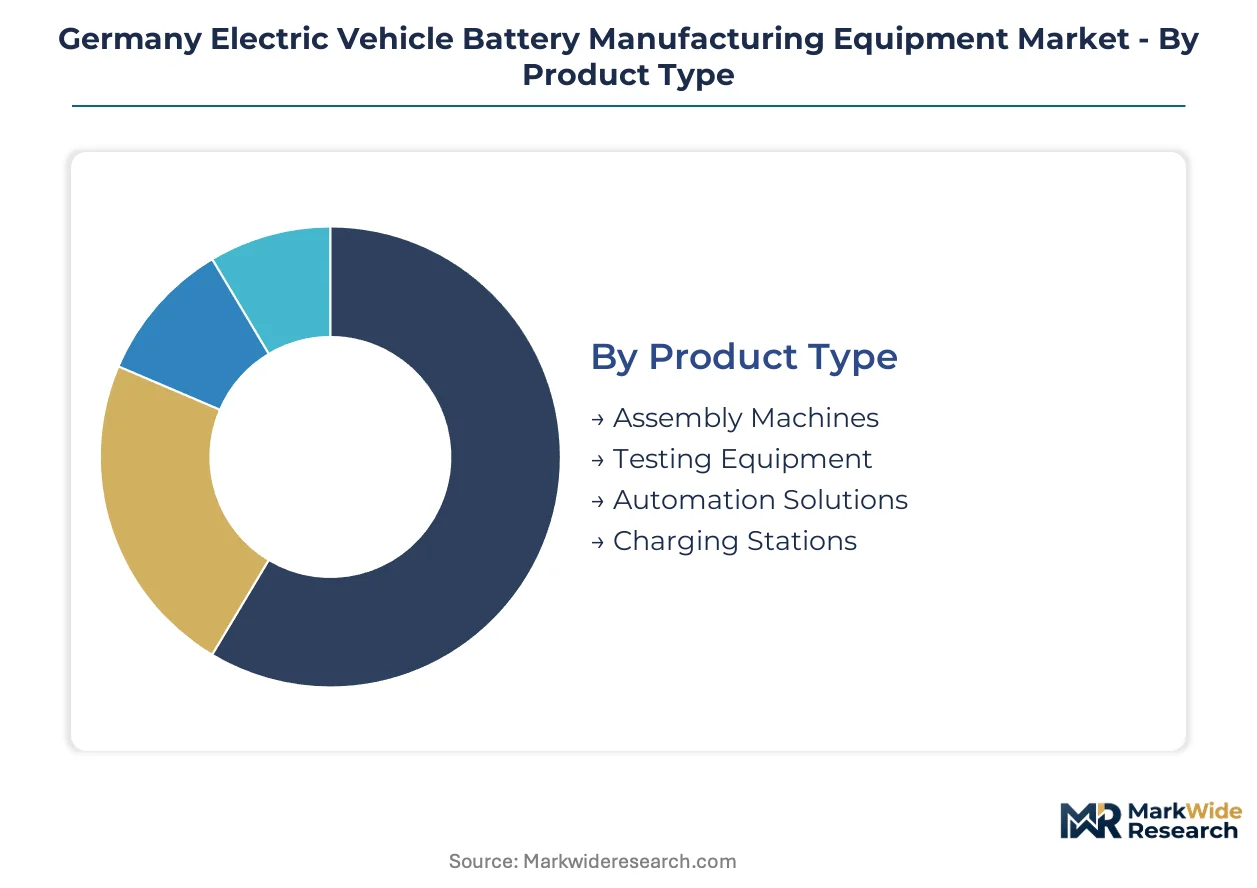
Segmentation in Germany's battery equipment market reveals how procurement channels split between captive OEM lines and independent supplier facilities. Equipment specifications diverge sharply across these channels, with traceability and throughput requirements driving vendor selection.
Product Type:
Assembly Machines and Testing Equipment flow predominantly through direct OEM procurement channels, while Automation Solutions and Charging Stations distribute more evenly across Tier-1 suppliers and aftermarket channels.
- Assembly Machines:High-speed stacking and winding systems form the core of electrode-to-cell conversion. Volkswagen Group's Salzgitter facility and BMW's Leipzig operations anchor demand for machinery exceeding 200 cells per minute with integrated vision inspection.
- Testing Equipment:Formation and aging cabinets with electrochemical impedance spectroscopy capabilities command premium positioning. Bavarian cell factories prioritize in-line quality verification modules that feed data directly into battery passport architectures.
- Automation Solutions:Robotic material handling and AGV fleet management systems span dry-room logistics.
- Charging Stations:Formation cycling infrastructure for pilot-line validation.
Assembly Machines dominate installed base. Testing Equipment is where expansion concentrates.
Technology:
Cost tier stratification separates mature lithium-ion equipment from emerging solid-state systems, with price premiums of 40-60% for dry-room compatible machinery.
- Lithium-ion:Wet coating and solvent-based electrode processing equipment represents the mature volume base. Dürr AG and Schuler AG anchor supply for conventional pouch and cylindrical cell formats across Baden-Württemberg production corridors.
- Solid State:Dry electrode coating and sulfide electrolyte handling systems demand dew point controls below minus 40 degrees Celsius. Bavarian research consortia at Ulm and Munich pull specialized formation equipment into pre-commercial lines.
- Flow Batteries:Redox cell stack assembly systems for stationary storage pilot projects.
- Nickel Metal Hydride:Legacy hybrid vehicle battery refurbishment equipment.
Lithium-ion equipment commands current revenue concentration. Solid State systems are climbing the fastest adoption trajectory.
End User:
Customer type determines specification intensity, with OEMs demanding full process integration while Tier-1 suppliers prioritize modular, reconfigurable platforms.
- OEMs:Volkswagen Group, BMW Group, and Mercedes-Benz Group operate captive cell factories requiring turnkey electrode-to-module lines with unified control architectures. Their direct procurement bypasses traditional equipment distributors.
- Tier-1 Suppliers:Cell producers supplying multiple automotive customers favor flexible equipment configurations that accommodate format changes between pouch, prismatic, and cylindrical designs.
- Aftermarket Providers:Diagnostic and refurbishment equipment for second-life battery processing.
- Research Institutions:Fraunhofer and university pilot lines drive demand for small-batch formation and characterization systems.
OEMs dominate capital deployment. Tier-1 Suppliers represent the most contested expansion segment.
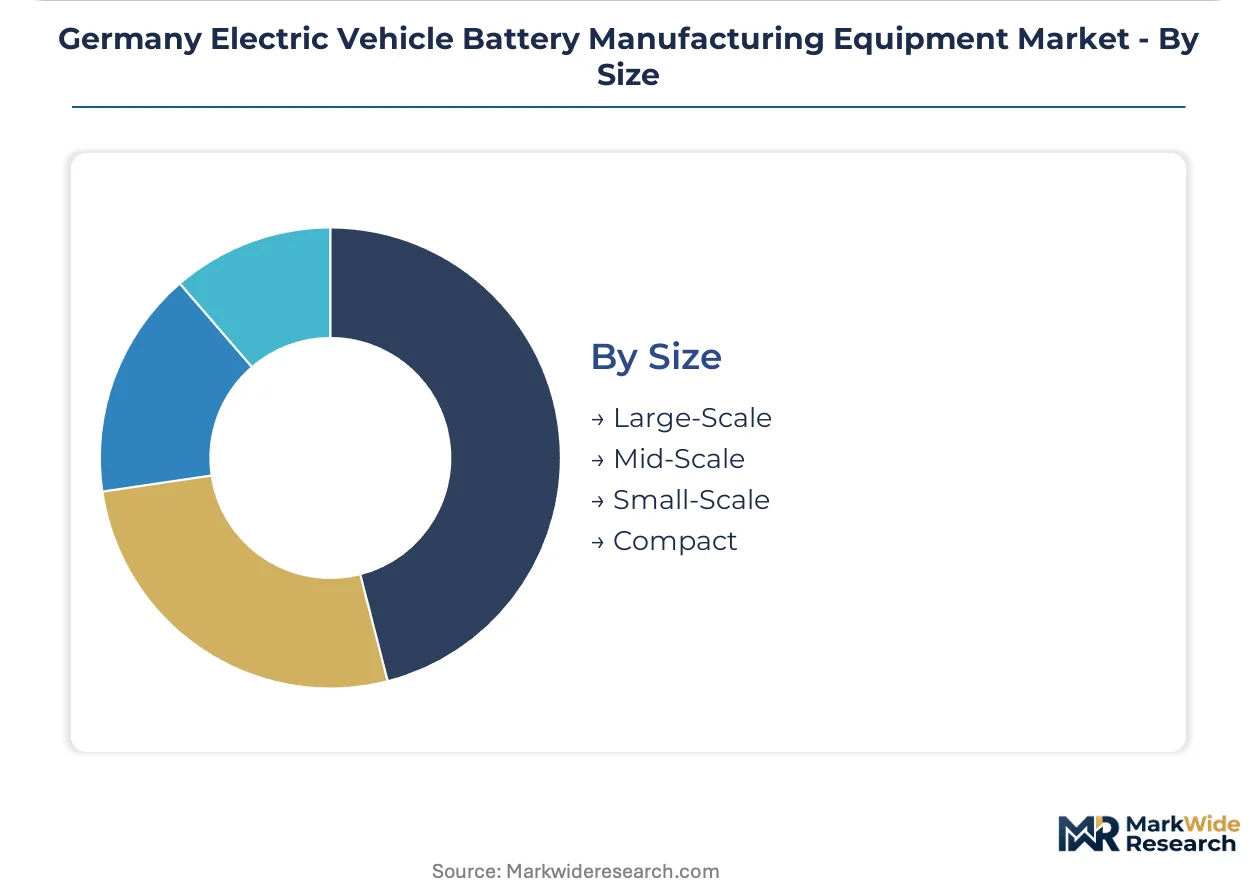
Size:
Volume scale correlates with facility vintage, with greenfield sites specifying Large-Scale systems while brownfield retrofits favor Compact and Mid-Scale modules.
- Large-Scale:Continuous coating lines exceeding 80 meters in length with annual throughput above 10 GWh. New gigafactories in Saxony and Lower Saxony specify these systems for electrode production halls.
- Mid-Scale:Semi-continuous equipment suites for 2-5 GWh annual capacity. North Rhine-Westphalia's emerging industrial corridor favors this scale for cathode active material integration projects.
- Small-Scale:Batch processing equipment for pilot and validation lines.
- Compact:Benchtop systems for R&D and quality control laboratories.
Large-Scale systems anchor new facility investments. Mid-Scale equipment is gaining share fastest in regional expansion corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment fabrication clusters tightly around automotive OEM headquarters and research consortia. Bavaria absorbs the deepest capital deployment. Regulatory pressure from the EU Battery Regulation and KBA protocols shapes facility specifications across federal states.
Bavaria
Volkswagen Group and BMW Group operate captive cell factories near Munich and Ingolstadt. The Bavarian state government funds battery research clusters at Technical University of Munich. Ulm and Munich host pre-commercial solid-state pilot lines pulling specialized formation equipment.
North Rhine-Westphalia
Cathode active material processing equipment concentrates near Leverkusen and Düsseldorf chemical corridors. The state offers greenfield sites with renewable energy infrastructure. Thyssenkrupp and chemical industry feedstock access attract mid-scale electrode production investments.
Baden-Württemberg
Porsche and Mercedes-Benz Group headquarters drive demand for high-speed winding machinery around Stuttgart. Fraunhofer institutes pilot dry electrode coating technology. The region balances automotive heritage with semiconductor-grade cleanroom expertise.
Lower Saxony
Volkswagen's Salzgitter battery factory anchors large-scale coating line demand. The federal state provides grid infrastructure for energy-intensive drying systems. Wolfsburg and Braunschweig form a procurement corridor for turnkey electrode-to-module lines.
Saxony
A single OEM gigafactory near Dresden absorbs regional engineering capacity for formation and aging cabinets. Silicon Saxony semiconductor ecosystem supplies automation components. The area faces talent competition from Bavarian battery clusters.
Germany Electric Vehicle Battery Manufacturing Equipment Market Competitive Landscape
Concentration sits with diversified industrial conglomerates and specialized machinery fabricators. Premium-tier positioning separates paint-line heritage players from emerging automation specialists. Three archetypes dominate: legacy automotive suppliers leveraging process control software, precision engineering specialists from metal-forming backgrounds, and Asian equipment exporters scaling through cost-advantaged modular platforms. Competitive moves center on strategic partnerships for solid-state pilot line development and geographic expansion into underpenetrated North Rhine-Westphalia corridors.
Among Germany-based industrial groups, Dürr AG and Schuler AG exemplify heritage-driven positioning, while Robert Bosch Manufacturing Solutions GmbH represents the integrated software-control archetype. These three anchor the premium equipment tier where coating uniformity tolerances and vacuum drying specifications determine vendor selection. Chinese fabricators including Xiamen Tmax Battery Equipments Limited and Wuxi Lead Intelligent Equipment Co Ltd occupy the scale-driven export segment, supplying modular platforms to independent cell producers and Tier-1 suppliers seeking flexible format reconfiguration.
| Leading Market Players |
|---|
| Dürr AG |
| Schuler AG |
| Hitachi Ltd |
| Xiamen Tmax Battery Equipments Limited |
| ACEY New Energy Technology |
| IPG Photonics Corporation |
| Wuxi Lead Intelligent Equipment Co Ltd |
| Robert Bosch Manufacturing Solutions GmbH |
| Targray Technology International Inc |
| Others |
Pricing and Supply Chain Analysis
Extended lead times of 18-24 months for ultra-high-precision bearings and vacuum chamber materials compress procurement flexibility for German equipment fabricators, concentrating pricing power with Japanese and South Korean suppliers while forcing OEMs to absorb cost volatility through long-dated contracts.
Pricing Analysis
The EU Battery Regulation dictates the pricing tier structure across German battery equipment procurement, with carbon-footprint disclosure mandates and recycled-content traceability requirements separating premium-certified systems from standard-tier alternatives. Price differentiation hinges on CE marking tier and energy efficiency certification, with heat pump-based drying systems commanding substantial premiums over conventional thermal designs. Cost compression in mid-tier assembly machinery is intensifying because Chinese fabricators are scaling modular platforms with faster delivery cycles. Tier-1 suppliers exhibit the highest price sensitivity as they compete for OEM subcontracting volumes, while captive automotive cell factories prioritize specification compliance over unit cost.
Supply Chain Analysis
Inventory buffers for specialized steel alloys and precision motion components rarely exceed 60 days, exposing German fabricators to disruption cascades when Asian suppliers face capacity constraints. Component sourcing draws from Japan, South Korea, and China for ultra-high-precision bearings, vacuum chamber materials, and machine vision systems. Raw material dependencies center on nickel-alloy steels, ceramic coatings, and rare-earth magnetic components. Single-source vulnerability concentrates in vacuum drying system subassemblies where Schuler AG and Dürr AG maintain proprietary designs. Distribution runs through direct OEM procurement channels for large-scale systems, with modular equipment reaching Tier-1 suppliers via specialized industrial distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment incumbents face substitution pressure from Asian modular platforms that undercut on delivery speed and reconfiguration flexibility, requiring defensive repositioning around regulatory compliance integration and solid-state pilot line exclusivity.
For Market Incumbents: Shield core revenue streams by embedding battery passport compliance architecture directly into formation and testing equipment, locking in OEM dependency as delegated acts tighten. Deepen backward integration into vacuum drying subsystem production to reduce exposure to Japanese supplier lead time volatility. Prioritize exclusive partnerships with Bavarian solid-state research consortia to secure early-mover positioning before dry electrode coating achieves commercial scale. For New Entrants and Emerging Players: Battery passport data integration services represent an under-served layer where incumbents lack software-native capabilities, offering white-space entry for automation specialists with blockchain and machine vision expertise. North Rhine-Westphalia's cathode active material processing corridor offers the most penetrable geography, with greenfield sites seeking mid-scale electrode production equipment absent established vendor relationships. A compliance-as-a-service go-to-market model, bundling equipment with ongoing regulatory update subscriptions, bypasses capital-intensive hardware competition. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded battery equipment divisions lacking strategic prioritization, particularly metal-forming heritage players without integrated software control capabilities. Long-term viability favors specialists with demonstrated dry-room equipment execution as solid-state transitions from pilot to mass manufacturing. The signal to watch is delegation act publication timelines tightening carbon-footprint thresholds, which will force accelerated replacement cycles in installed base equipment and favor vendors with pre-certified energy-efficient designs.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Electrode Coating Scale-Up | Eliminates solvent recovery infrastructure and reduces energy intensity for solid-state cell formats. |
| Battery Passport Compliance Integration | Embeds traceability modules into formation equipment to meet EU Battery Regulation delegated acts. |
| Heat Pump Drying System Certification | Positions vendors for premium procurement as KBA protocols tighten energy efficiency benchmarks. |
| North Rhine-Westphalia Geographic Expansion | Captures cathode active material processing demand near Leverkusen chemical corridors. |
| Solid-State Pilot Line Partnership | Locks in early reference installations with Bavarian research clusters at Technical University of Munich. |
Research Methodology
The analysis maps electrode preparation, cell assembly, formation, and testing equipment segments, each validated through equipment procurement directors, plant engineers at captive OEM facilities, and aftermarket service heads. Primary fieldwork combined structured interviews with secondary validation against KBA type-approval databases, EU Battery Regulation delegated act drafts, and industrial trade flow records. Bottom-up installed base estimates triangulated with top-down capital expenditure projections from automotive OEM disclosure filings.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user category, and equipment scale class. CAGRs derived from equipment replacement cycle analysis, capacity expansion announcements, and regulatory compliance-driven upgrade timelines. Forecast inputs incorporated solid-state pilot line scaling trajectories and delegated act implementation schedules.
Material uncertainties — accelerated solid-state commercialization, Asian supplier capacity constraints, and EU Battery Regulation enforcement variance — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding technology transition pacing and regulatory timeline adherence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Canada Electric Vehicle Battery Separator Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Italy Electric Vehicle Battery Separator Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Battery Maintenance Service Market
Battery Infrastructure
Smart Battery Swap Station Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
ASEAN Countries Electric Vehicle Battery Separator Market
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
Automotive Battery Plate Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
Battery Enclosure Market
Battery Infrastructure
Lithium-Ion Battery Filling Machine Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
Battery Raw Materials Market