
 Battery Enclosure Market | 2026-2036
Battery Enclosure Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Enclosure Market Outlook
Automotive OEM demand for battery enclosures is collapsing toward integrated cell-to-pack designs that eliminate modular housings. Tier-one suppliers like Magna International leverages its stamping and assembly scale to capture platform contracts from EV-native manufacturers. Constellium anchors European supply through its dedicated automotive aluminum rolling capacity in Belgium and France. Alcoa Corporation competes on upstream bauxite-to-sheet integration, sustaining cost positions as primary aluminum prices fluctuate.
A battery enclosure is a protective structural housing that contains electrochemical cells, manages thermal loads through engineered cooling channels, and maintains ingress protection ratings up to IP67 for automotive applications. Its primary purpose is to prevent thermal runaway propagation while providing mechanical integrity during crash events. Metal enclosures, particularly aluminum extrusions and stampings, dominate value pools in electric vehicle applications where crashworthiness and lightweighting converge. Composite solutions represent the fastest-growing type segment as fiber-reinforced thermoplastics enable complex geometries that integrate cooling and electrical isolation in single molded parts. Small and medium sizes still occupy the volume base in portable devices and industrial equipment, though custom large-format enclosures carry premium pricing for grid-scale renewable energy installations.
The US NHTSA crashworthiness standards and China's GB/T battery safety protocols are forcing redesign cycles that prioritize flame-retardant materials and multi-layer thermal barriers. The EU's CE marking and REACH chemical restrictions further constrain polymer formulation choices for enclosures sold in European markets. Stakeholders must monitor how cell chemistry shifts toward solid-state architectures reshape enclosure thermal management requirements and structural load paths before committing to long tooling investments.
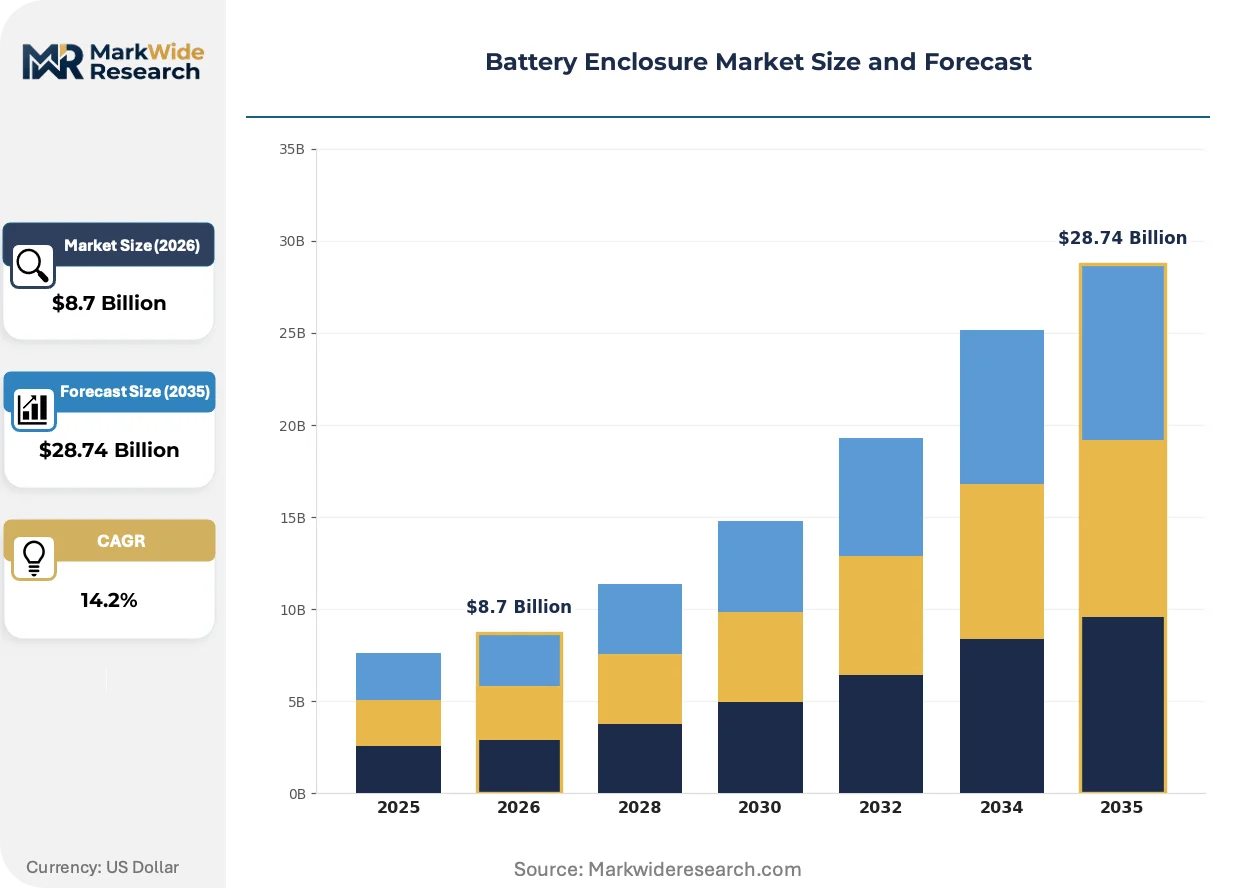
Market Dynamics
Cell-to-pack architecture adoption by electric vehicle OEMs is compressing enclosure volumes while simultaneously demanding higher structural performance per unit, forcing material suppliers to recalibrate density-to-strength ratios in aluminum and composite formulations.
Growth Catalysts
- China GB/T battery safety protocols:Mandatory thermal runaway containment testing is accelerating enclosure redesign cycles toward multi-layer barrier systems in domestic EV production.
- Grid-scale energy storage deployment:Utility-scale lithium-ion installations require custom large-format enclosures with integrated liquid cooling, opening premium fabrication contracts for specialized metalworkers.
- Solid-state cell chemistry maturation:Higher operating temperatures in next-generation batteries are pulling demand toward ceramic-composite thermal interfaces within enclosure assemblies.
Market Restraints
- Primary aluminum price volatility:London Metal Exchange pricing swings directly compress margins for extrusion-dependent enclosure manufacturers locked into annual automotive supply contracts.
- China rare earth magnet concentration:Thermal management system suppliers face single-source risk for neodymium-doped cooling pump motors essential to active enclosure designs.
- EU F-Gas Regulation phase-down:Restrictions on hydrofluorocarbon-based dielectric cooling fluids are forcing premature obsolescence of existing thermal management tooling investments.
Strategic Opportunities
- India PLI scheme for battery manufacturing:Production-linked incentives for cell and pack assembly are attracting enclosure suppliers to establish localized stamping and welding capacity near Tamil Nadu cell plants.
- Second-life stationary storage repurposing:Retired automotive enclosures are finding refurbishment demand in behind-the-meter commercial battery installations with relaxed ingress protection requirements.
- Digital twin-enabled predictive maintenance:Sensor-integrated smart enclosures are creating recurring software revenue streams through thermal performance monitoring subscriptions sold to fleet operators.
Industry Challenges
- Multi-physics simulation talent scarcity:Coupled thermal-structural-crash modeling expertise remains concentrated among a handful of specialized engineering consultancies, elongating OEM validation timelines.
- IP friction around composite fiber layup automation:Patent thickets held by aerospace manufacturers are complicating licensing for automotive-grade continuous fiber thermoplastic enclosure production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Enclosure Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Polymer, Metal, Composite, Aluminum Application: Electric Vehicles, Portable Devices, Renewable Energy Systems, Industrial Equipment Size: Small, Medium, Large, Custom Size End User: Manufacturers, OEMs, Suppliers, Distributors |
| Companies Covered | Grevol, Alcoa Corporation, Linamar Corp, Constellium, UFP Technologies, Magna International, Dura-Shiloh, ArcelorMittal, Novelis Inc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Enclosure Market Strategic Shifts
Active thermal management integration is blurring the boundary between structural housing and functional cooling system, requiring enclosure designers to master fluid dynamics and electrical isolation simultaneously.
Continuous fiber-reinforced thermoplastic (CFRTP) overmolding is miniaturizing cooling channel geometries to sub-millimeter tolerances while maintaining dielectric strength. European premium EV platforms are adopting these hybrid metal-polymer enclosures for cell-to-pack architectures. The technology is miniaturizing thermal propagation pathways that previously required separate cooling plates and structural trays.
EU F-Gas Regulation restrictions on synthetic refrigerants are redirecting thermal management fluid selection toward natural hydrocarbon and CO2-based alternatives. Enclosure suppliers must redesign sealing systems and pressure ratings to accommodate higher-vapor-pressure coolants. German automotive OEMs are accelerating validation programs for propane-dielectric immersion cooling in performance battery packs.
Automotive OEMs are consolidating enclosure procurement under platform-level contracts rather than sourcing modular housings separately from cooling hardware. Tier-one integrators with combined stamping and thermal system capabilities are displacing specialized enclosure fabricators in supplier selection processes. South Korean battery cell producers are driving this consolidation through vertical specification of complete pack assemblies to European vehicle manufacturers.
Battery Enclosure Market Segmentation
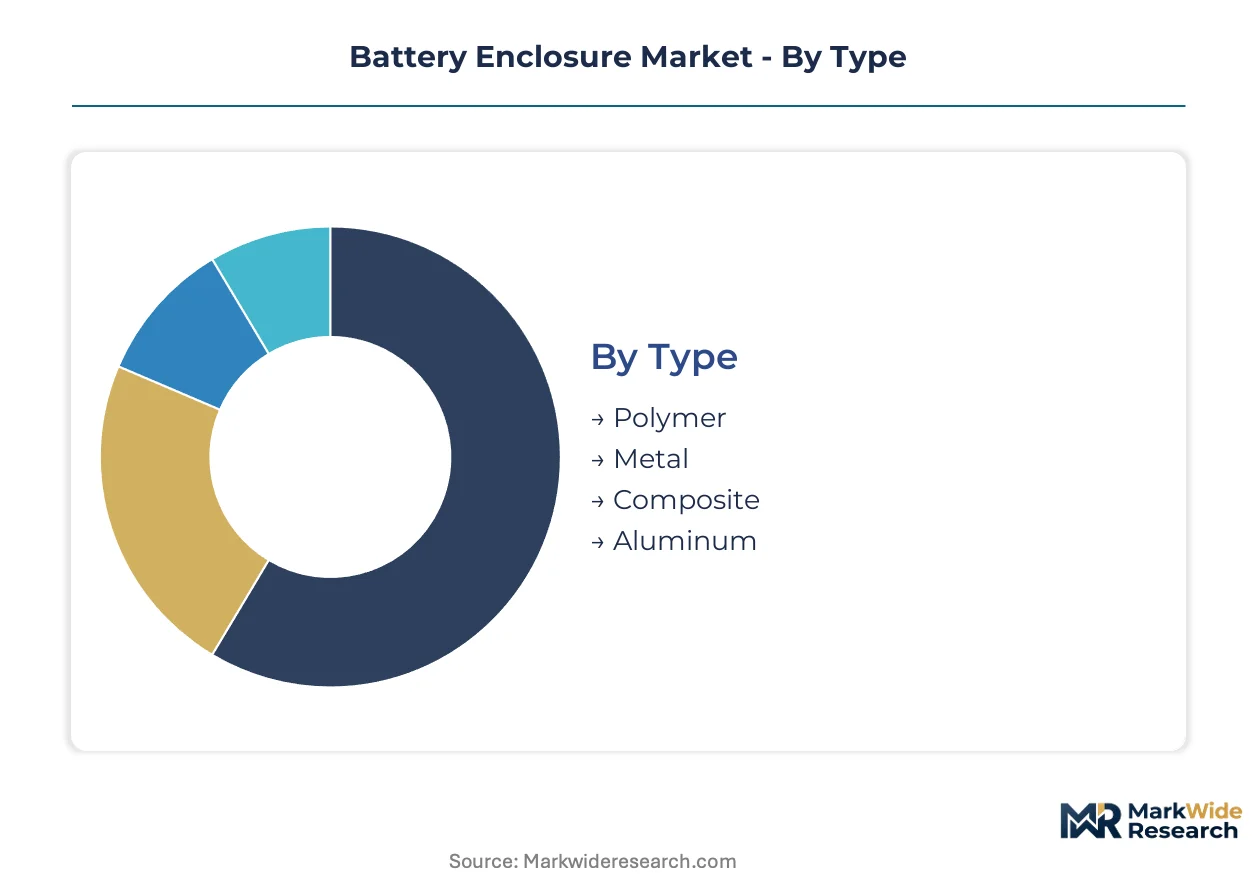
Material selection and dimensional specifications in battery enclosures are increasingly governed by thermal runaway containment mandates from China's GB standards and the EU's F-Gas Regulation. These regulatory frameworks create divergent compliance pathways that reshape procurement priorities across automotive, industrial, and energy storage applications.
Type:
REACH chemical restrictions and GB/T battery safety protocols impose distinct material certification burdens that segment supplier capabilities and customer eligibility.
- Metal:Aluminum extrusions and high-strength steel stampings deliver crashworthiness ratings required by NHTSA protocols. Automotive OEMs in Germany's manufacturing corridor specify these for cell-to-pack architectures where structural load-bearing integrates with thermal management.
- Composite:Fiber-reinforced thermoplastics enable sub-millimeter cooling channel tolerances through overmolding processes. European premium EV platforms favor these for weight reduction targets, though ECHA substance scrutiny complicates polymer formulation choices.
- Aluminum:Rolled sheet and cast alloys offer the most mature recycling infrastructure and LME price transparency. Constellium's Belgian and French rolling capacity anchors European supply for this segment.
- Polymer:Injection-molded engineering plastics serve cost-sensitive portable device applications with lower thermal loads. BIS certification requirements in India constrain import sourcing for domestic electronics manufacturers.
Established volume favors Metal; emerging adoption favors Composite.
Application:
End-use thermal profiles and duty cycles determine enclosure complexity tiers and corresponding margin structures.
- Electric Vehicles:Active liquid cooling integration and IP67 ingress protection dominate specifications. South Korean cell producers specify complete pack assemblies that compress modular housing procurement into platform-level contracts.
- Renewable Energy Systems:Grid-scale lithium-ion installations demand custom large-format fabrications with multi-layer thermal barriers. Utility procurement cycles favor specialized metalworkers capable of ASME pressure vessel compliance.
- Industrial Equipment:Forklift and material handling applications balance durability against moderate thermal loads. China's domestic EV transition diverts aluminum extrusion capacity from this segment toward automotive.
- Portable Devices:Consumer electronics enclosures prioritize miniaturization and surface finish over thermal management sophistication. India's PLI scheme for electronics manufacturing is attracting localized molding capacity near Tamil Nadu assembly plants.
Electric Vehicles command premium engineering resources; Renewable Energy Systems are climbing the fastest as utility deployment accelerates.
Size:
Dimensional categories correlate directly with cooling architecture complexity and fabrication method constraints.
- Custom Size:Bespoke dimensions for grid-scale and marine applications require project-specific engineering and extended validation timelines. German automotive OEMs are accelerating propane-dielectric immersion cooling programs that demand non-standard pressure vessel geometries.
- Large:Standardized utility-scale formats balance economies of scale against transportation logistics limits. Second-life stationary storage repurposing is creating refurbishment demand with relaxed ingress protection specifications.
- Medium:Industrial and commercial battery formats occupy the volume base with established stamping and welding automation. China's GB standards for thermal runaway containment are forcing redesign investments across this tier.
- Small:Portable electronics and power tool applications favor high-volume injection molding with minimal thermal integration. MFDS medical device regulations in South Korea constrain polymer biocompatibility choices for healthcare applications.
Medium formats sustain manufacturing scale; Custom Size commands the steepest expansion trajectory as energy storage deployment diversifies.
End User:
Procurement authority and technical specification control vary sharply across the value chain, determining supplier relationship structures.
- OEMs:Vehicle and energy system manufacturers consolidate enclosure sourcing under platform contracts that bundle structural housing with thermal management hardware. Tier-one integrators with combined stamping and fluid system capabilities are displacing specialized fabricators.
- Manufacturers:Cell producers in South Korea and China specify complete pack assemblies, pushing enclosure design decisions upstream. Vertical integration into housing production is emerging as a competitive differentiator for these firms.
- Suppliers:Tier-two component vendors face margin compression as OEMs consolidate procurement. Alcoa's upstream bauxite-to-sheet integration sustains cost positions for aluminum-dependent suppliers locked into annual contracts.
- Distributors:Aftermarket and replacement channels serve second-life storage and industrial refurbishment markets with reduced certification burdens. India's battery manufacturing incentives are attracting distributor investment in localized warehousing near cell production zones.
OEMs concentrate specification authority; Manufacturers are gaining procurement influence as cell-to-pack architectures mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg's container throughput underwrites Germany's automotive export corridor for battery enclosure shipments to European OEMs. China's Ningbo-Zhoushan port anchors Pacific Rim raw material flows for aluminum extrusion feedstock. South Korea's Busan Newport handles cell component logistics for battery pack integrators supplying global vehicle manufacturers.
China
GB/T battery safety protocols mandate thermal runaway containment testing for all domestic EV production. MIIT production quotas for new energy vehicles compress enclosure redesign cycles toward multi-layer barrier systems. The Yangtze River Delta cluster around Shanghai concentrates stamping and welding capacity for cell-to-pack architectures.
Germany
NHTSA-equivalent UNECE crashworthiness ratings drive aluminum-intensive structural housing specifications for premium EV platforms. The EU F-Gas Regulation phase-down forces thermal management fluid transitions toward propane-dielectric alternatives. Baden-Württemberg's Stuttgart region hosts concentrated OEM platform engineering centers specifying integrated enclosure-cooling assemblies.
United States
IRA domestic content bonuses reshape procurement geography toward North American aluminum rolling capacity. NHTSA Federal Motor Vehicle Safety Standards govern crash-propagation resistance in battery pack housings. Michigan's automotive manufacturing corridor attracts Tier-one integrators consolidating stamping and thermal system capabilities.
South Korea
MFDS medical-grade polymer certifications constrain biocompatibility pathways for healthcare-adjacent battery applications. METI-aligned industrial policy supports cell producer vertical integration into pack assembly. The Busan-Ulsan industrial zone concentrates battery cell output that specifies complete enclosure assemblies for export.
India
BIS certification requirements for electronics manufacturing constrain import sourcing for domestic battery enclosure production. The PLI scheme for advanced chemistry cell manufacturing attracts localized stamping capacity near Tamil Nadu cell plants. Gujarat's Mundra Port infrastructure supports raw material ingress for aluminum-dependent automotive suppliers.
Battery Enclosure Market Competitive Environment
Listed leaders compete with private specialists across capital access and tooling flexibility dimensions. The vendor base organizes around three tiers: multinational Tier-one integrators with combined stamping and thermal capabilities, upstream metal producers with rolling and casting integration, and specialized fabricators focused on custom large-format energy storage housings. Dominant competitive moves include capacity expansion near cell production zones and strategic partnerships for composite fiber layup automation licensing.
Within the aluminum value chain tier, Alcoa Corporation and Constellium exemplify upstream integration strategies that sustain cost positions through LME price cycles. Magna International occupies a position among Tier-one integrators consolidating platform-level contracts. Among specialized composite fabricators, UFP Technologies represents the niche engineering segment serving non-automotive thermal management applications.
| Leading Market Players |
|---|
| Grevol |
| Alcoa Corporation |
| Linamar Corp |
| Constellium |
| UFP Technologies |
| Magna International |
| Dura-Shiloh |
| ArcelorMittal |
| Novelis Inc |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day aluminum extrusion lead times concentrate pricing power with rolling mills in Belgium and France, compressing margin buffers for stampers locked into annual automotive contracts while GB/T certification costs widen spreads between qualified and unqualified suppliers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ASME-certified large-format fabricators from medium-volume industrial stampers and injection-molded portable device suppliers. Price differentiation hinges on thermal runaway certification grade and volume scale, with OEM platform contracts commanding 40-60% discounts off list. Cost compression in the medium tier is intensifying because China's domestic EV transition diverts aluminum capacity toward automotive. Cell producers exhibit the lowest price sensitivity; aftermarket distributors face the highest.
Supply Chain Analysis
Strait of Malacca transit underwrites bauxite flows from Guinea and Australia to Chinese smelters, creating a logistics chokepoint for primary aluminum feedstock. Supply concentrates in China, Germany, and South Korea for extrusion and stamping capacity. The chain draws from bauxite, rare earth magnets for cooling pumps, and fiber-reinforced thermoplastic resins. Single-source vulnerability for neodymium-doped pump motors threatens active enclosure designs. Distribution runs through Tier-one integrators consolidating platform-level contracts rather than specialized fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-physics simulation expertise for coupled thermal-structural-crash modeling remains lodged with a handful of specialized engineering consultancies, elongating OEM validation timelines and creating scarcity rents for qualified talent pools.
For Market Incumbents: Fortify backward integration into aluminum rolling capacity to offset LME price volatility, and lock in multi-year platform contracts with South Korean cell producers before composite fiber layup automation matures. The threat of CFRTP overmolding displacing metal stampings accelerates as European premium EV platforms adopt hybrid enclosures. Certification investment in China's GB/T thermal runaway protocols serves as the critical lever for domestic market access. For New Entrants and Emerging Players: Lead with second-life stationary storage refurbishment as the most penetrable white-space target, where retired automotive enclosures face relaxed ingress protection requirements and simplified validation. India's PLI scheme for Tamil Nadu cell plants offers geographic entry with production-linked incentives. A go-to-market angle anchored in digital twin-enabled predictive maintenance subscriptions creates recurring revenue distinct from capital equipment sales. For Investors and Strategic Acquirers: Long-term, this sits as a materials-scarcity play because ceramic-composite thermal interface capacity for solid-state cell architectures will constrain enclosure supplier margins before demand peaks. Acquisition targets should cluster around specialized metalworkers with ASME pressure vessel compliance and established utility procurement relationships. The signal to watch is propane-dielectric immersion cooling validation progress among German automotive OEMs, which would obsolete existing thermal management tooling investments and reshape competitive positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Rolling | Constellium's Belgian and French capacity anchors cost positions through LME cycles. |
| GB/T Thermal Runaway Certification Investment | MIIT production quotas compress redesign cycles toward multi-layer barrier systems. |
| CFRTP Overmolding Automation Licensing | Patent thickets from aerospace manufacturers complicate automotive-grade fiber layup production. |
| Digital Twin Platform Development | Sensor-integrated smart enclosures create recurring software revenue from fleet operators. |
| India PLI-Aligned Capacity Buildout | Tamil Nadu cell plants attract localized stamping and welding infrastructure. |
Study Parameters
Cross-validation between OEM platform engineering interviews and SEC 10-K filings from aluminum producers anchors the qualitative findings. Primary fieldwork engaged Tier 1 supplier procurement leads, OEM thermal management directors, composite fabrication engineers, and utility-scale EPC contractors. Secondary sources incorporated NHTSA Federal Motor Vehicle Safety Standards documentation, EU F-Gas Regulation impact assessments, China MIIT production quota disclosures, and IHS Markit vehicle production databases. Bottom-up enclosure content-per-vehicle estimates triangulate against top-down aluminum consumption forecasts.
Sensitivity analysis around solid-state cell chemistry maturation timelines and primary aluminum price volatility bands shapes the projection framework. Segmentation dimensions span material type, application end-use, dimensional category, and procurement authority tier across the analysis window. CAGRs derive from weighted average of historical capacity expansion announcements and regulatory-mandated redesign cycle frequencies. Industry-specific inputs include thermal runaway containment testing adoption curves and F-Gas Regulation phase-down compliance cost estimates.
The analysis sits within stated boundaries; outcomes outside sustained electric vehicle production scaling or abrupt solid-state commercialization would require recalibration. Forecasts reflect assumptions around GB/T protocol enforcement intensity and EU F-Gas refrigerant substitution timelines. Practitioners should keep alternative scenarios live as cell-to-pack architecture adoption rates and rare earth magnet supply diversification evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Battery Infrastructure
Electric Vehicle Battery Swapping Market
Battery Infrastructure
Global Automotive 48 Volt Battery System Market
Battery Infrastructure
China Electric Vehicle Battery Electrolyte Market
Battery Infrastructure
Automotive Battery Plate Market
Battery Infrastructure
Carbon Battery Bank Market
Battery Infrastructure
Battery Lug Market
Battery Infrastructure
Battery-As-A-Service Market
Battery Infrastructure
Europe Lithium Foil Market
Battery Infrastructure
Battery Tray Market
Battery Infrastructure
South America Electric Vehicle Battery Separator Market
Battery Infrastructure
Battery Swap-Ready Pack Systems for Urban Fleets Market
Battery Infrastructure
Global Battery Packaging Market
Battery Infrastructure
Asia Pacific Electric Vehicle Battery Separator Market
Battery Infrastructure
Solar Containers Market
Battery Infrastructure
Battery Production Machine Market
Battery Infrastructure
Germany Electric Vehicle Battery Separator Market