
 Mexico Diabetes Care Devices Market | 2026-2036
Mexico Diabetes Care Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Diabetes Care Devices Market Foresight
Homecare settings is decoupling from hospital-centric distribution as patients adopt self-monitoring technologies. Abbott Diabetes Care leverages its FreeStyle platform to anchor direct-to-consumer channels across Mexican urban centers. Medtronic competes through its integrated pump-sensor ecosystem, while Roche Diabetes Care sustains laboratory and pharmacy partnerships with its Accu-Chek portfolio.
Mexico Diabetes Care Devices encompass instruments for glucose measurement, insulin delivery, and metabolic monitoring, typically incorporating electrochemical sensors, microfluidic cartridges, or Bluetooth-enabled transmitters operating at specified analytical sensitivities. Continuous glucose monitors and insulin pumps command premium positioning due to algorithm-driven closed-loop functionality, whereas blood glucose meters occupy a mature, price-sensitive tier within retail pharmacy networks. Smart monitoring and wireless connectivity segments attract R&D investment as software integration enables remote clinician oversight and reimbursement differentiation.
COFEPRIS regulates medical device registration and post-market vigilance, while NOM standards specify electromagnetic compatibility and biocompatibility testing protocols for electronic diabetes devices. These frameworks elevate compliance costs for importers but simultaneously protect domestic patients from substandard products and create barriers for unapproved entrants. Stakeholders must monitor evolving software-as-medical-device classifications and telehealth reimbursement rulings that will determine which technology configurations achieve sustainable commercial traction.
Market Dynamics
COFEPRIS post-market surveillance tightening is forcing importers to restructure quality assurance operations, while tertiary care networks in Mexico City and Jalisco consolidate procurement leverage for continuous glucose monitoring systems.
Growth Catalysts
- NOM electromagnetic compatibility mandates:Domestic manufacturers gain competitive positioning against importers facing extended certification timelines.
- Diabetes clinic clustering around tertiary networks:Concentrated demand pools enable volume-based contracting for insulin pump-sensor ecosystems.
- Bluetooth-enabled transmitter integration:Remote clinician oversight capabilities expand addressable patient populations beyond metropolitan centers.
Market Restraints
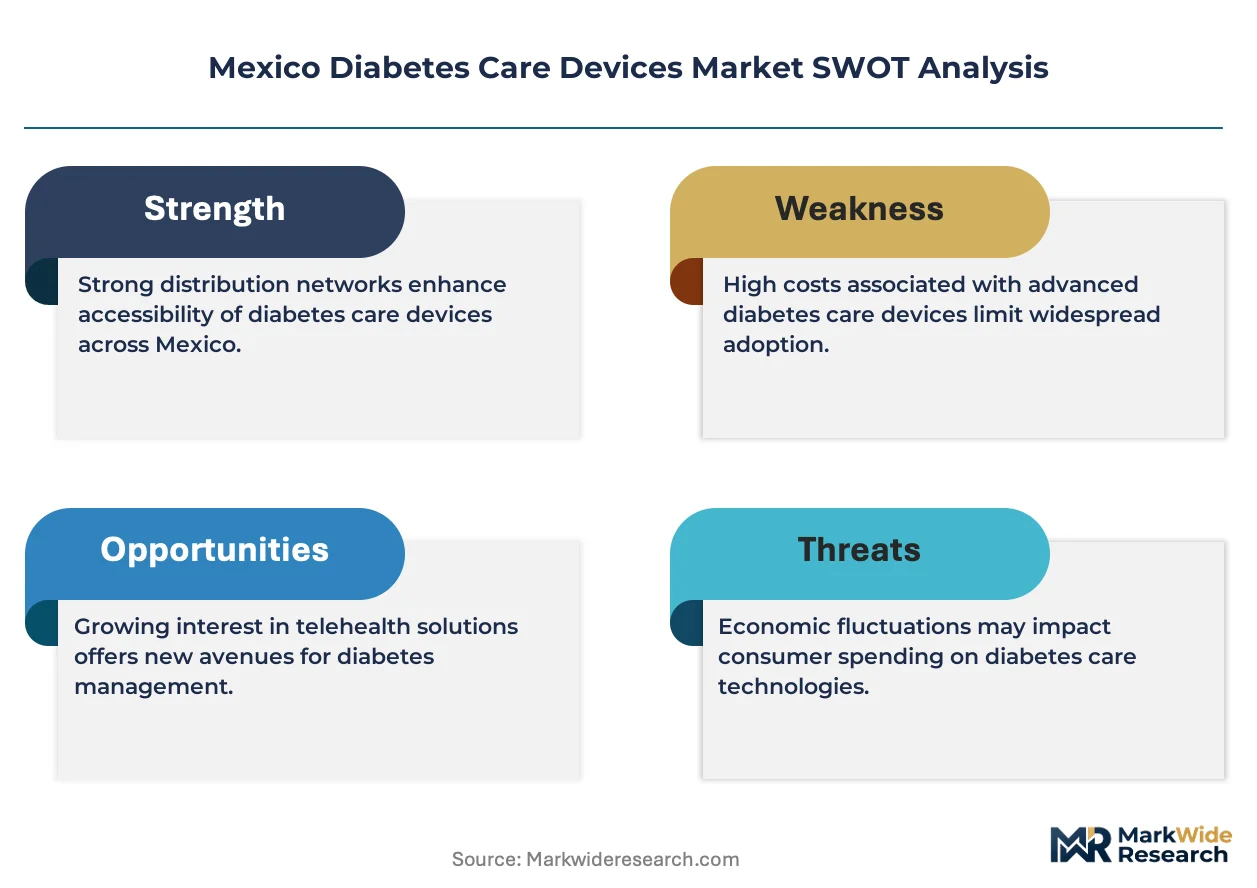
- Biocompatibility testing cost escalation:COFEPRIS NOM compliance requirements elevate entry barriers for mid-tier device manufacturers.
- Electrochemical sensor supply concentration:Import dependency for specialized glucose-sensitive membranes creates input vulnerability.
- Software-as-medical-device classification uncertainty:Pending telehealth reimbursement rulings delay closed-loop algorithm commercialization timelines.
Strategic Opportunities
- Direct-to-consumer channel expansion:Urban pharmacy networks in Monterrey and Guadalajara enable bypass of hospital-centric distribution.
- Algorithm-driven closed-loop functionality:Premium positioning for integrated pump-sensor systems creates margin differentiation from blood glucose meters.
- Microfluidic cartridge miniaturization:Convergence with smartphone connectivity opens self-monitoring segments in underpenetrated states.
Industry Challenges
- Post-market vigilance workforce scarcity:COFEPRIS adverse event reporting requirements outpace trained regulatory affairs specialist supply.
- Legacy hospital procurement system integration:Electronic health record interoperability gaps complicate continuous glucose data workflow adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Diabetes Care Devices Market |
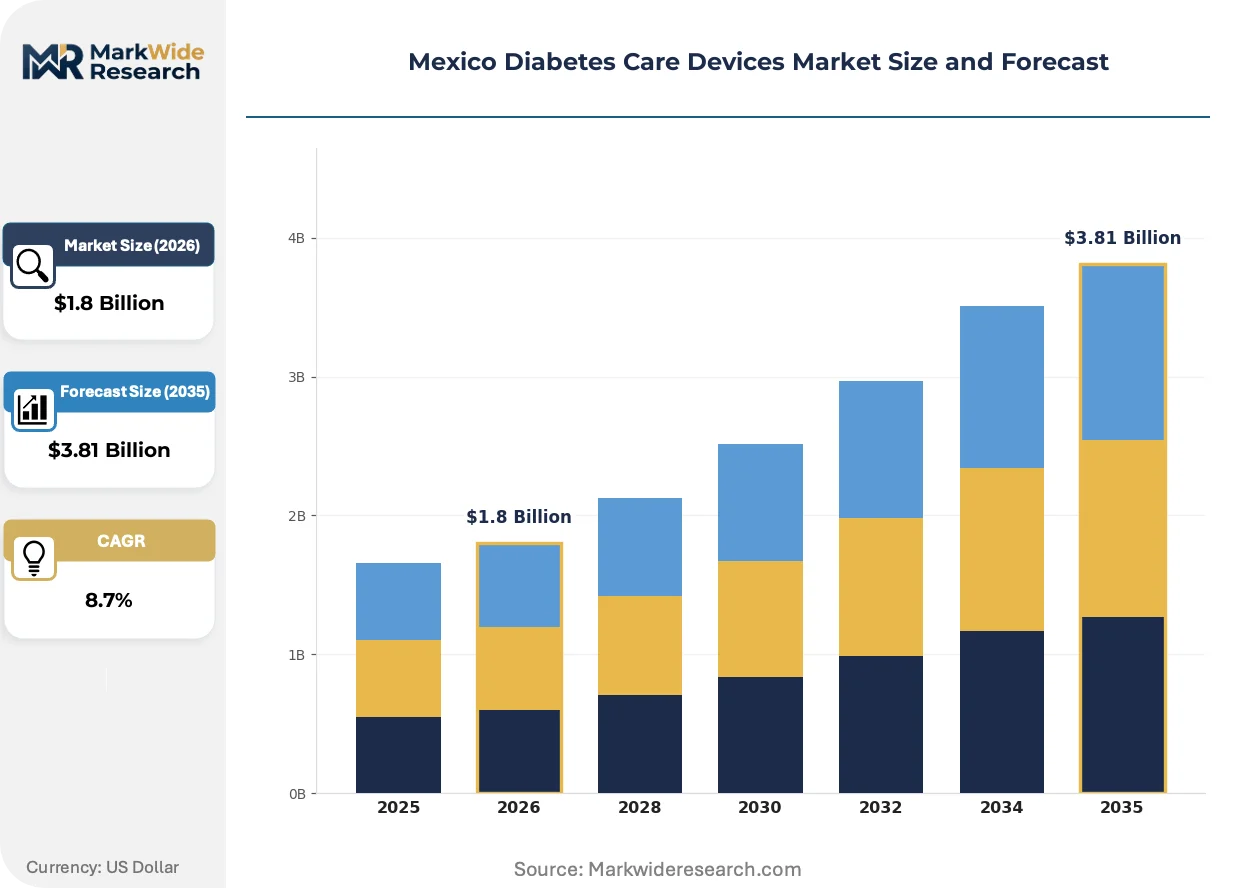
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blood Glucose Meters, Insulin Pumps, Continuous Glucose Monitors, Pen Injectors End User: Hospitals, Homecare Settings, Diabetes Clinics, Retail Pharmacies Technology: Smart Monitoring, Wireless Connectivity, Software Integration, Mobile Applications Application: Type 1 Diabetes, Type 2 Diabetes, Gestational Diabetes, Diabetes Management |
| Companies Covered | Abbott Diabetes Care, Medtronic, Roche Diabetes Care, Novo Nordisk, Eli Lilly and Company, Lifescan, Ascensia Diabetes Care, Insulet Corporation, Tandem Diabetes Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Diabetes Care Devices Market Shifts & Advancements
Software integration is absorbing capital allocation across the Mexico diabetes device landscape, reshaping how manufacturers differentiate hardware platforms through algorithmic performance rather than sensor precision alone.
Closed-loop insulin delivery systems are absorbing development resources from major device manufacturers, with specialized diabetes clinics in Mexico City piloting automated basal rate adjustment protocols. Hospital procurement committees now evaluate algorithm stability metrics alongside traditional accuracy specifications. This technology is absorbing premium pricing power from conventional pump-sensor combinations.
COFEPRIS software-as-medical-device draft guidance is elevating documentation requirements for Bluetooth-enabled glucose transmitters. Manufacturers must submit clinical validation data for cloud-based analytics features previously exempt from device classification. The Jalisco tertiary care network is responding by consolidating vendor qualification processes to reduce supplier audit burden.
Patient self-monitoring preferences are fragmenting traditional pharmacy channel dominance, with urban consumers in Monterrey and Puebla purchasing direct-to-consumer continuous glucose monitors through e-commerce platforms. Hospital-based diabetes educators now compete with manufacturer telehealth support programs for patient onboarding. This behavioral shift is most visible among Type 1 patients under 35 in metropolitan zones with reliable cellular coverage.
Mexico Diabetes Care Devices Market Segmentation
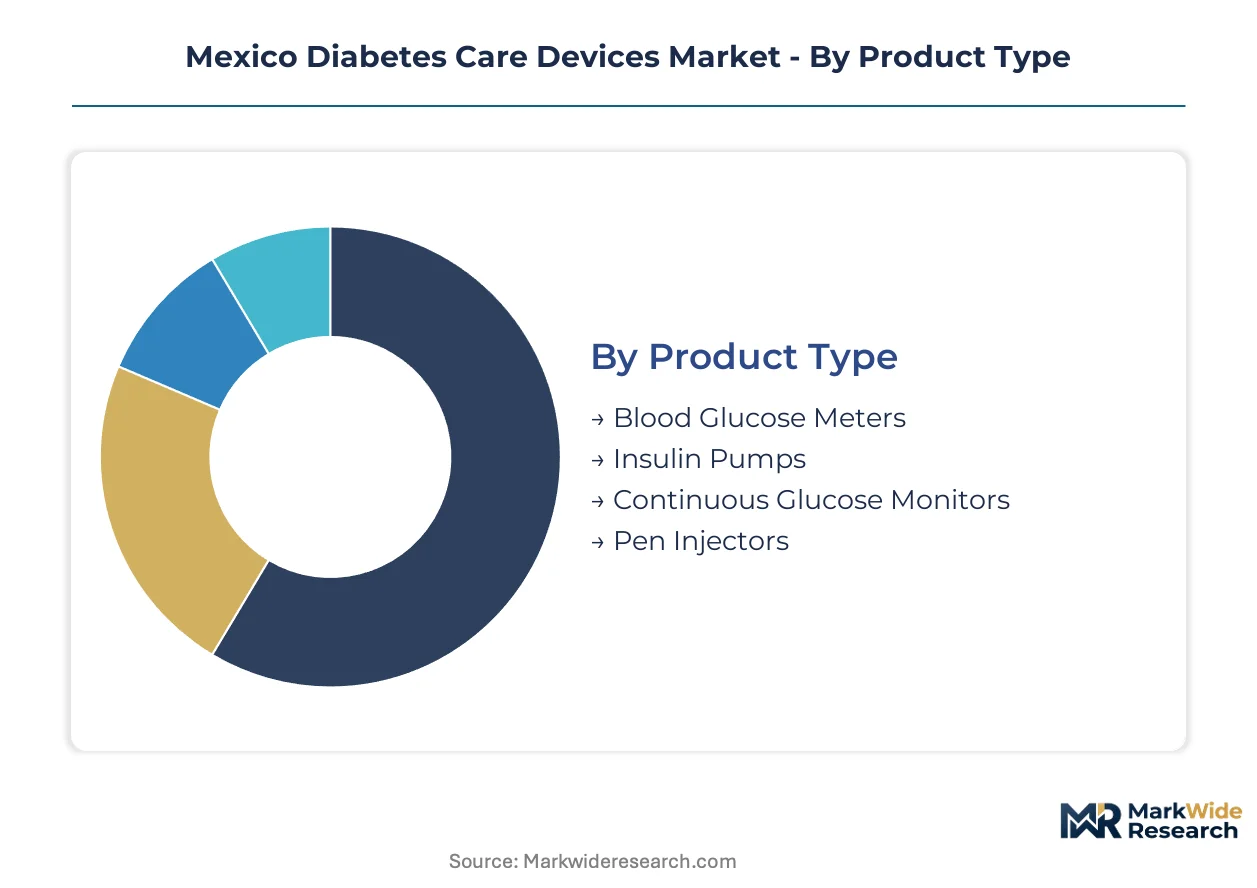
Device configuration in Mexico diabetes care hinges on reimbursement pathway and patient access infrastructure. Procurement committees at tertiary networks evaluate closed-loop functionality against cost-per-patient metrics, while self-monitoring adoption fragments traditional channel structures.
Product Type:
Hospital procurement committees weigh algorithmic performance against capital expenditure limits when selecting device categories.
- Continuous Glucose Monitors:Electrochemical sensors paired with Bluetooth-enabled transmitters enable real-time glucose trending. Mexico City tertiary networks concentrate demand for closed-loop systems as COFEPRIS post-market surveillance tightens import quality requirements.
- Insulin Pumps:Microprocessor-controlled basal-bolus delivery systems integrate with sensor data for automated adjustment. Jalisco diabetes clinics drive volume contracting for pump-sensor ecosystems amid concentrated specialist availability.
- Blood Glucose Meters:Handheld electrochemical analyzers with disposable test strips dominate retail pharmacy networks across Monterrey and Guadalajara.
- Pen Injectors:Disposable and reusable cartridge-based delivery devices serve price-sensitive patient segments in underpenetrated states.
Blood glucose meters lead on scale; continuous glucose monitors lead on momentum.
End User:
Channel selection determines reimbursement eligibility and patient onboarding protocols for device manufacturers.
- Diabetes Clinics:Specialized outpatient facilities cluster around tertiary care networks in Mexico City and Jalisco, enabling volume-based contracting for advanced monitoring systems. These centers concentrate endocrinologist expertise and drive adoption of algorithm-driven closed-loop functionality.
- Homecare Settings:Self-monitoring patients bypass hospital procurement through direct-to-consumer channels. Urban consumers in Puebla and Monterrey purchase Bluetooth-enabled transmitters via e-commerce platforms, fragmenting traditional pharmacy dominance.
- Hospitals:Tertiary inpatient facilities manage acute glycemic episodes and initiate patients on pump-sensor ecosystems.
- Retail Pharmacies:Community dispensaries serve blood glucose meter replenishment and over-the-counter pen injector sales.
Diabetes clinics lead on scale; homecare settings lead on momentum.
Technology:
Software classification under COFEPRIS draft guidance reshapes development roadmaps for connected device features.
- Software Integration:Cloud-based analytics platforms aggregate glucose data for remote clinician oversight. COFEPRIS software-as-medical-device documentation requirements elevate compliance costs for manufacturers deploying algorithmic features.
- Smart Monitoring:Predictive glucose trending and automated alert systems differentiate premium device tiers. Hospital procurement committees in Mexico City now evaluate algorithm stability metrics alongside traditional accuracy specifications.
- Wireless Connectivity:Bluetooth and cellular transmitters enable real-time data streaming to clinician dashboards.
- Mobile Applications:Smartphone interfaces for patient-facing glucose visualization and insulin dosing support.
Software integration leads on scale; smart monitoring leads on momentum.
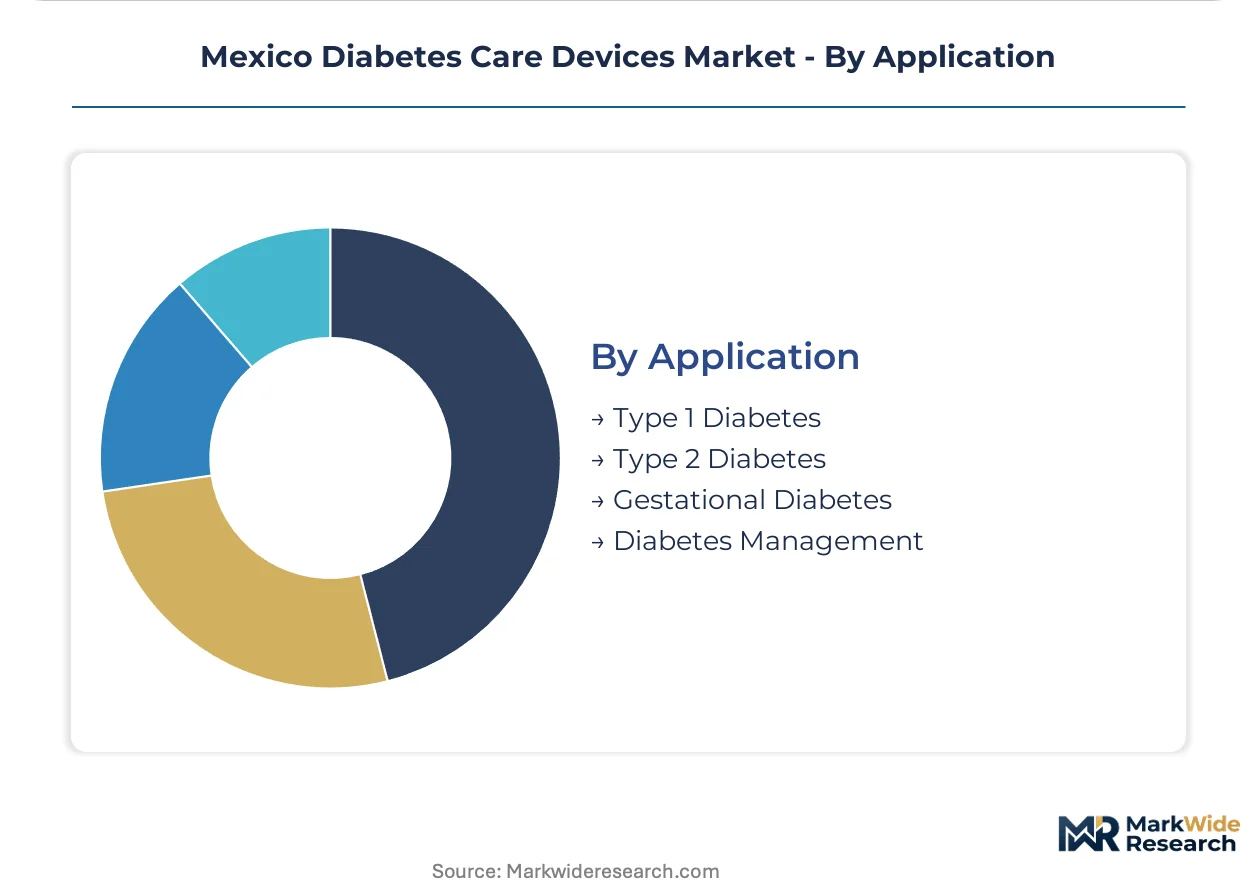
Application:
Disease severity and treatment intensity dictate device complexity and reimbursement tier.
- Type 1 Diabetes:Absolute insulin deficiency requires intensive monitoring and automated delivery systems. Patients under 35 in metropolitan zones with reliable cellular coverage drive adoption of closed-loop pump-sensor combinations through direct-to-consumer channels.
- Type 2 Diabetes:Progressive insulin resistance creates heterogeneous monitoring needs across disease stages. Pharmacy networks in Guadalajara and Monterrey serve this larger patient population with blood glucose meters and pen injectors.
- Gestational Diabetes:Temporary hyperglycemia during pregnancy demands short-term monitoring solutions.
- Diabetes Management:Comprehensive care protocols spanning prevention, monitoring, and complication screening.
Type 2 diabetes leads on scale; Type 1 diabetes leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where diabetes device manufacturers concentrate quality-assurance operations, with cost-of-compliance gaps between federal enforcement zones driving operational migration toward states with streamlined COFEPRIS liaison offices.
Mexico City Metro
Specialized diabetes clinics cluster around tertiary care networks in Cuajimalpa and Tlalpan, creating concentrated demand pools for continuous glucose monitoring systems. COFEPRIS headquarters proximity enables faster adverse-event reporting turnaround for importers maintaining local regulatory affairs teams. Hospital procurement committees at Instituto Nacional de Ciencias Médicas y Nutrición Salvador Zubirán anchor volume contracting for insulin pump-sensor ecosystems.
Nuevo León
Monterrey's urban consumers drive direct-to-consumer channel fragmentation through e-commerce penetration of Bluetooth-enabled glucose transmitters. The state's medical device distributor network benefits from customs infrastructure at Colombia-Solidarity International Bridge reducing import clearance times. Pharmacy chains in San Pedro Garza García serve self-monitoring patient segments with blood glucose meter replenishment.
Jalisco
Guadalajara hosts the highest density of endocrinology specialists outside Mexico City, enabling concentrated adoption of algorithm-driven closed-loop functionality. COFEPRIS regional office jurisdiction covers post-market surveillance for Pacific coast imports through Manzanillo port. Hospital Civil de Guadalajara anchors tertiary network procurement leverage for integrated pump-sensor systems.
Bajío Region
Querétaro and Guanajuato manufacturing corridors attract electrochemical sensor assembly operations seeking NOM electromagnetic compatibility certification proximity. The region's automotive electronics supplier base provides workforce transferability for microfluidic cartridge production. León's pharmaceutical distribution hub serves pen injector replenishment across central Mexico.
Northern Border States
Baja California and Chihuahua leverage maquiladora infrastructure for medical device component assembly serving US FDA-registered parent facilities. Tijuana's contract manufacturing ecosystem produces glucose test strip substrates under ISO 13485 quality systems. Cross-border patient populations in Ciudad Juárez access dual-market device procurement through binational pharmacy networks.
Mexico Diabetes Care Devices Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with hospital procurement committees favoring integrated pump-sensor ecosystems while retail pharmacy networks fragment among test-strip suppliers. The market structure concentrates around three strategic tiers: multinational device platforms with closed-loop algorithms, regional distributors with COFEPRIS registration expertise, and domestic assemblers leveraging NOM compliance proximity. Dominant competitive moves include vertical integration into electrochemical sensor substrate production and strategic partnerships with tertiary care network procurement committees.
Among US-based device manufacturers, Abbott Diabetes Care and Medtronic occupy positions anchoring the premium-tier vector through integrated hardware-software platforms, while Roche Diabetes Care represents the European multinational archetype sustaining laboratory and pharmacy channel partnerships. These three exemplify contrasting strategic postures: direct-to-consumer channel expansion versus hospital-centric distribution consolidation versus retail network maintenance.
| Leading Market Players |
|---|
| Abbott Diabetes Care |
| Medtronic |
| Roche Diabetes Care |
| Novo Nordisk |
| Eli Lilly and Company |
| Lifescan |
| Ascensia Diabetes Care |
| Insulet Corporation |
| Tandem Diabetes Care |
| Others |
Supply & Pricing Matrix
COFEPRIS electromagnetic compatibility certification mandates gate qualified supply access and premium-tier pricing power for diabetes device manufacturers seeking hospital procurement contracts in Mexico City tertiary networks. Importers facing extended NOM testing timelines absorb compliance cost premiums that domestic assemblers in Bajío manufacturing corridors bypass, creating a bifurcated pricing landscape where certification proximity determines margin capture.
Pricing Analysis
Hospital procurement committee discounts anchor the dominant pricing structure, with volume-based contracting for insulin pump-sensor ecosystems commanding premium positioning against retail pharmacy transactional models for blood glucose meters. Price differentiation rests on COFEPRIS registration tier and algorithmic feature depth, with closed-loop systems capturing margin separation from electrochemical sensor-only devices. Cost compression in the pen injector segment intensifies as domestic cartridge assemblers exploit NOM compliance proximity. Retail pharmacy networks in Monterrey and Guadalajara exhibit highest price sensitivity, while tertiary care procurement committees prioritize algorithm stability over unit cost.
Supply Chain Analysis
NOM domestic-content testing requirements reshape sourcing toward electrochemical sensor substrate producers with certified electromagnetic compatibility laboratories in Querétaro and Guanajuato. Manufacturing concentration draws from Taiwan and South Korea for glucose-sensitive membrane components, with US and German suppliers dominating microprocessor-controlled pump assemblies. Raw material dependencies center on palladium-based electrode substrates, medical-grade silicone for insulin reservoirs, and lithium polymer cells for transmitter power. Single-source vulnerability runs through specialized glucose oxidase enzyme suppliers. Distribution runs through COFEPRIS-registered medical device distributors with regional warehouse infrastructure in Mexico City, Monterrey, and Guadalajara.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mexico diabetes device market compounds as COFEPRIS software-as-medical-device draft guidance elevates documentation requirements, forcing algorithmic feature investments that deepen competitive moats for prepared manufacturers.
For Market Incumbents: Extend closed-loop algorithm development roadmaps ahead of pending telehealth reimbursement rulings that will determine sustainable commercial traction for automated basal rate adjustment protocols. Consolidate vendor qualification processes with Jalisco tertiary care networks to reduce supplier audit burden amid post-market surveillance tightening. Backward integration into electrochemical sensor substrate production defends margin position against import dependency for specialized glucose-sensitive membranes.
For New Entrants and Emerging Players: Capture direct-to-consumer channel fragmentation in Puebla and Monterrey where urban consumers under 35 purchase Bluetooth-enabled transmitters through e-commerce platforms, bypassing hospital-centric distribution entirely. Target underpenetrated states with microfluidic cartridge miniaturization converging with smartphone connectivity, opening self-monitoring segments beyond metropolitan cellular coverage zones. Anchor go-to-market execution through manufacturer telehealth support programs competing with hospital-based diabetes educators for patient onboarding.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with COFEPRIS registration expertise and established tertiary care network procurement relationships, positioned for acquisition by multinational device platforms seeking algorithmic capabilities. Long-term viability centers on software integration differentiation rather than hardware sensor precision alone. Watch for inflection signals in COFEPRIS adverse event reporting system modernization that would accelerate post-market vigilance workforce scarcity premiums for regulatory affairs specialists.
| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Software-as-Medical-Device Submission | Clinical validation data for cloud-based analytics features secures premium reimbursement tier ahead of competitors. |
| Hospital System Partnership Consolidation | Volume-based contracting with Instituto Nacional de Ciencias Médicas anchors pump-sensor ecosystem adoption. |
| Electrochemical Sensor Substrate Integration | In-house production of glucose-sensitive membranes reduces import dependency and NOM certification timeline exposure. |
| Direct-to-Consumer Channel Expansion | E-commerce penetration in Monterrey and Guadalajara fragments pharmacy dominance among Type 1 patients under 35. |
| Telehealth Reimbursement Strategy | Remote clinician oversight capabilities expand addressable populations beyond Mexico City metropolitan coverage zones. |
Research Methodology
Multiple input streams — primary interviews with hospital procurement committee members, biomedical engineers at tertiary care networks, and COFEPRIS regulatory affairs specialists; secondary validation through COFEPRIS medical device registration databases, hospital procurement contract disclosures, and NOM electromagnetic compatibility certification records; plus customs import data for electrochemical sensor components — were reconciled through bottom-up and top-down triangulation. The analytical framework combined demand-side patient population modeling with supply-side manufacturing capacity assessment across Bajío assembly operations and cross-border maquiladora facilities.
Cross-referencing historical adoption curves for continuous glucose monitoring systems against panel input from diabetes clinic administrators and GPO contracts managers anchored the projection framework across the analysis window. Segmentation dimensions modeled include device configuration tier, end-user channel structure, software integration depth, and disease severity application. CAGRs were derived from algorithmic adoption elasticity coefficients and reimbursement pathway probability weightings, with specific inputs from Bluetooth-enabled transmitter penetration rates and closed-loop system pilot program outcomes.
Regulatory classification delays, telehealth reimbursement ruling timing, and electrochemical sensor supply concentration are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented assumptions regarding COFEPRIS enforcement intensity and tertiary care network consolidation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
China Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Global Glucose Monitoring Devices Market
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
Brazil Oral Anti-Diabetic Drug Market
Diabetes Care
Insulin Resistance Market
Diabetes Care
Malaysia Insulin Infusion Pump Market
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Latin America Insulin Infusion Pump Market
Diabetes Care
Insulin Pen Needles Market
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
South Africa Oral Antidiabetic Drug Market
Diabetes Care
Internet of Things for Diabetes Market
Diabetes Care
Disposable Insulin-Delivery Device Market