
 India Oral Anti-Diabetic Drug Market | 2026-2036
India Oral Anti-Diabetic Drug Market Size, Share, and Industry Trends Forecast 2026-2036
India Oral Anti-Diabetic Drug Market Outlook
Private hospital chains and corporate pharmacy networks is reorganizing procurement priorities toward SGLT2 inhibitors and DPP-4 inhibitor combinations, displacing the traditional dominance of standalone metformin prescribing in government dispensaries. Sanofi leverages its insulin-to-oral portfolio continuity to anchor physician relationships across tier-two cities. Sun Pharma competes aggressively on metformin-sitagliptin fixed-dose pricing, while AstraZeneca differentiates through cardiovascular outcome trial data integration into promotional messaging.
Oral anti-diabetic drugs comprise systemically administered pharmaceutical agents that lower blood glucose through mechanisms including hepatic glucose suppression, pancreatic insulin secretion enhancement, renal glucose excretion inhibition, or intestinal incretin pathway modulation; these agents typically achieve therapeutic plasma concentrations within hours and require chronic daily administration for glycemic control in type 2 diabetes mellitus. Biguanides and sulfonylureas occupy the mature volume base where intense generic competition compresses margins, while SGLT2 inhibitors represent the fastest-expanding margin pool driven by nephroprotective and cardioprotective label expansions. DPP-4 inhibitors sustain intermediate growth through favorable hypoglycemia profiles that appeal to elderly polypharmacy patients.
CDSCO regulates new drug approvals and fixed-dose combination standards, while the NPPA governs price controls on essential formulations including several sulfonylureas and biguanides, creating a dual-track market where innovator molecules face pricing ceilings and branded generics operate under competitive market forces. State-level FDA authorities enforce manufacturing quality compliance through facility inspections that determine market access eligibility for domestic producers. Stakeholders must monitor evolving PLI scheme pharmaceutical incentives and patent cliff timing for originator SGLT2 molecules to calibrate generic entry strategies.
Market Dynamics
CDSCO's accelerated approval pathways for fixed-dose combinations are compressing development timelines and forcing incumbents to defend physician relationships through outcome data rather than legacy prescribing habits.
Growth Catalysts
- Maharashtra Outpatient Expansion:State-level health insurance schemes in Maharashtra, Karnataka, and Tamil Nadu deepen pharmaceutical access for chronic disease management.
- PLI Pharmaceutical Incentives:India's Production Linked Incentive scheme for active pharmaceutical ingredients reduces import dependency for key oral hypoglycemic intermediates.
- SGLT2 Cardiorenal Labeling:Nephroprotective and cardioprotective indications expand addressable patient pools beyond glycemic control alone.
Market Restraints
- NPPA Price Controls:India's National Pharmaceutical Pricing Authority imposes ceilings on essential biguanides and sulfonylureas, compressing margin pools for volume-base molecules.
- API Import Concentration:Domestic formulators remain dependent on Chinese intermediate suppliers for DPP-4 inhibitor precursors, exposing cost volatility to geopolitical friction.
- Generic Substitution Mandates:Government dispensary procurement rules prioritize lowest-cost metformin and glimepiride, locking out differentiated formulations.
Strategic Opportunities
- Tier-Three Hospital Formulary Access:Corporate pharmacy networks in Rajasthan and Madhya Pradesh expand chronic disease outpatient clinics requiring oral hypoglycemic stocking.
- Fixed-Dose Combination Streamlining:CDSCO's harmonized bioequivalence standards for metformin-SGLT2 and metformin-DPP-4 combinations reduce regulatory burden for novel pairings.
- Renal Dosing Differentiation:SGLT2 inhibitors with reduced eGFR thresholds capture diabetic kidney disease patients previously excluded from therapy.
Industry Challenges
- State FDA Inspection Backlogs:Manufacturing facility clearance delays in Uttar Pradesh and Gujarat block market access for domestic producers awaiting compliance certification.
- Physician Education Requirements:Cardiometabolic outcome trial data integration demands specialized medical liaison deployment that strains field force economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Oral Anti-Diabetic Drug Market |
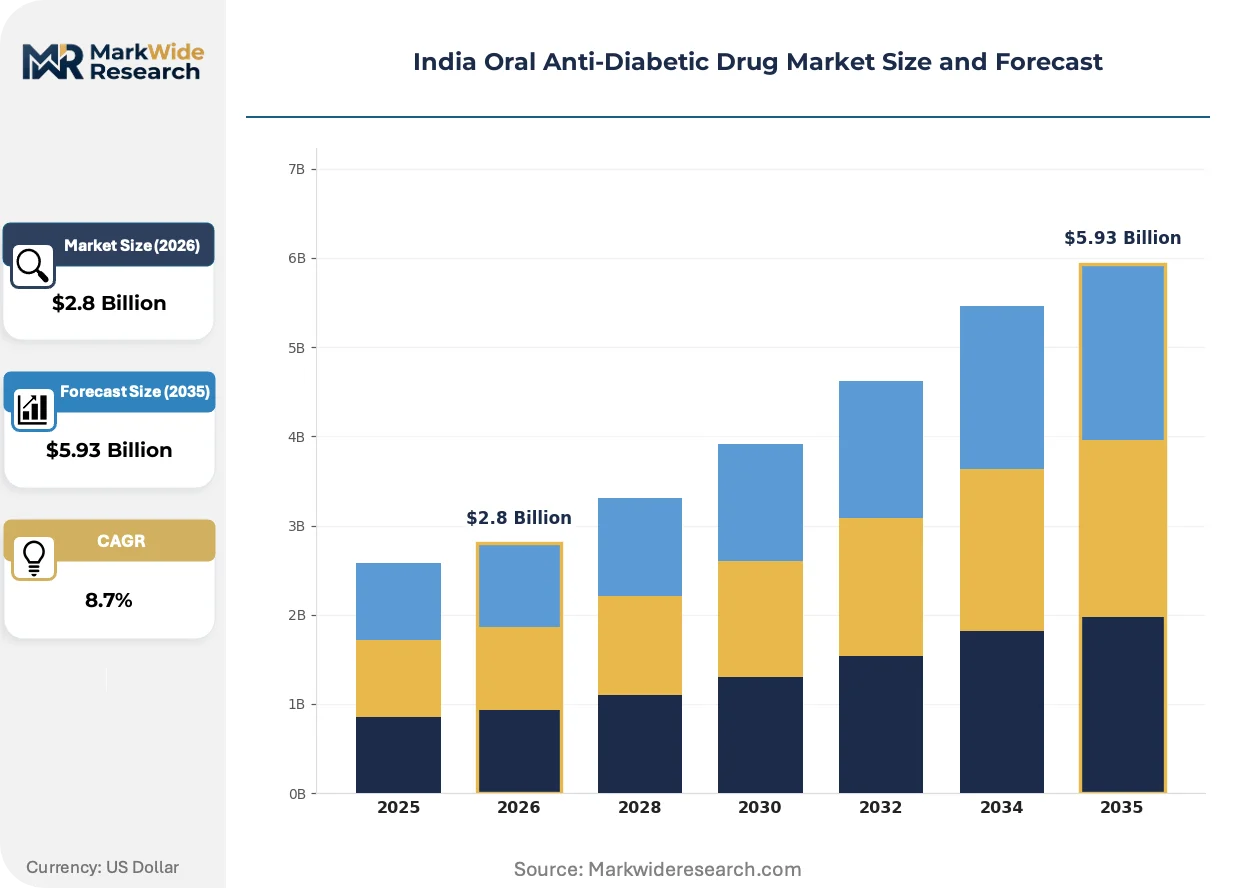
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Drug Class: Biguanides, Sulfonylureas, DPP-4 Inhibitors, SGLT2 Inhibitors Formulation Type: Tablet, Capsule, Oral Suspension, Injectable End User: Hospitals, Clinics, Pharmacies, Home Care Prescription Type: Prescription, Over-the-Counter, Generic, Brand |
| Companies Covered | Sanofi, Eli Lilly, Novo Nordisk, AstraZeneca, Merck, Boehringer Ingelheim, Johnson & Johnson, Novartis, Takeda Pharmaceuticals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Oral Anti-Diabetic Drug Market Strategic Shifts
Prescribing patterns are bifurcating between government dispensary cost minimization and private channel outcome-based differentiation, with technology and regulatory forces accelerating this divergence.
Continuous glucose monitoring integration with oral therapy titration is fragmenting the traditional endocrinologist-pharmacist-patient relationship. Private hospital chains in Bengaluru and Hyderabad deploy CGM-linked dosing algorithms that adjust SGLT2 and DPP-4 inhibitor regimens in real time. This data-driven approach compresses reliance on standalone HbA1c monitoring and enables outcome-based contracting with payers.
CDSCO's 2023 guidance on fixed-dose combination bioequivalence studies tightens pharmacokinetic standards for metformin-based pairings. Domestic manufacturers in Andhra Pradesh and Telangana reconfigure stability testing protocols to meet accelerated dissolution specifications. The regulation most impacts sulfonylurea-metformin combinations, where legacy formulations face reformulation costs or withdrawal.
Corporate pharmacy networks consolidate procurement authority previously dispersed across individual hospital formularies. Apollo Pharmacy and MedPlus centralize therapeutic class negotiations, demanding cardiovascular outcome data packages that smaller regional chains cannot match. This concentration is most visible in Tamil Nadu, where pharmacy network density enables volume-based contracting for SGLT2 inhibitor portfolios.
India Oral Anti-Diabetic Drug Market Segmentation
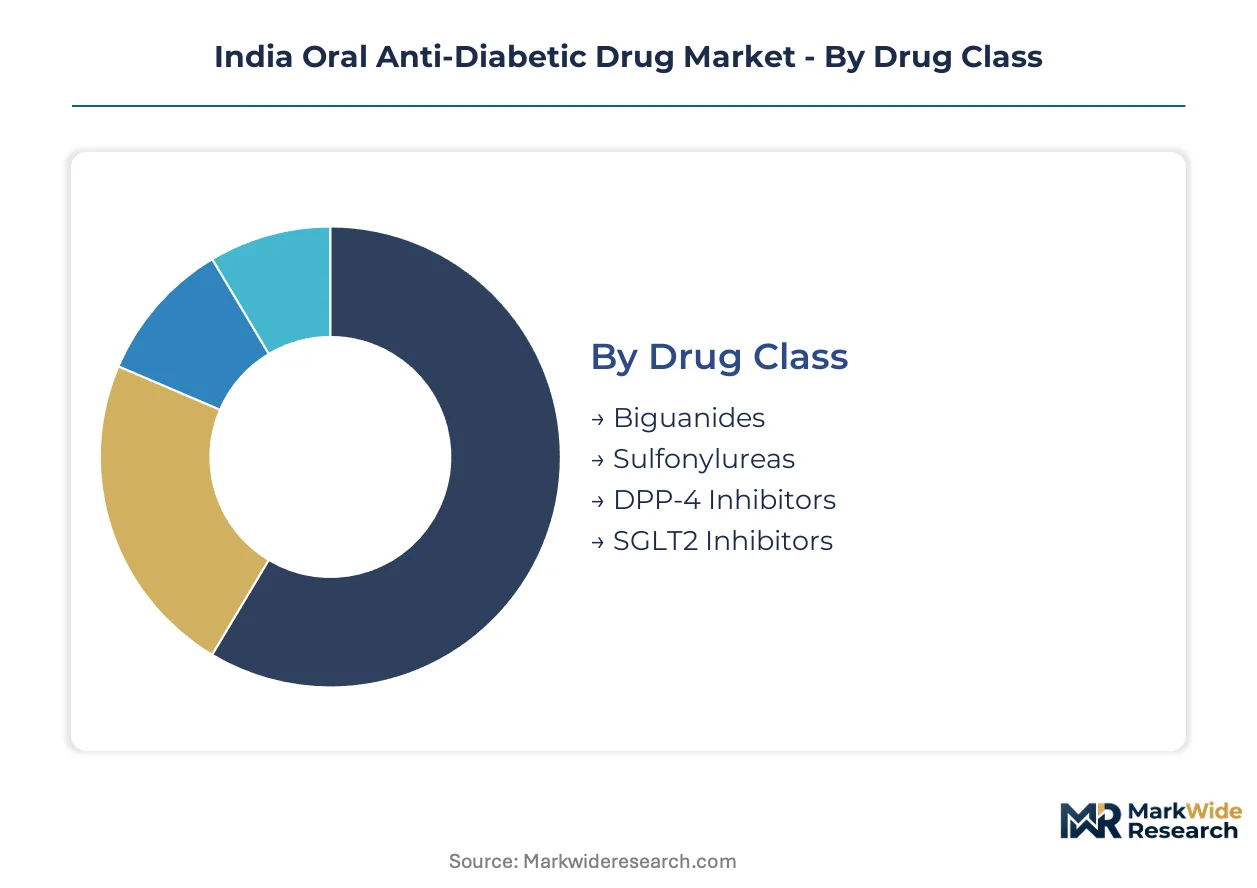
Oral anti-diabetic drug procurement in India fragments across institutional and retail channels with divergent formulary logic. Drug class selection varies sharply between government cost-minimization protocols and private outcome-based contracting.
Drug Class:
Maharashtra and Karnataka hospitals drive domestic consumption of newer agents, while export-oriented API production concentrates in Andhra Pradesh and Telangana.
- Biguanides:Metformin formulations constitute the volume foundation of Indian diabetes therapy, with immediate-release and extended-release variants dominating government dispensary procurement. Demand clusters in Tamil Nadu's state insurance networks where lowest-cost sourcing mandates exclude premium formulations.
- Sulfonylureas:Glimepiride and gliclazide molecules face NPPA price ceilings that compress branded margins to generic levels. Prescribing persists in tier-three cities where physician familiarity outweighs hypoglycemia risk concerns.
- DPP-4 Inhibitors:Sitagliptin and tenelipitin combinations appeal to elderly polypharmacy populations in Bengaluru and Hyderabad private chains.
- SGLT2 Inhibitors:Dapagliflozin and empagliflozin command premium positioning through cardiorenal outcome data integration into Apollo and MedPlus formularies.
Biguanides hold the largest share; momentum sits with SGLT2 inhibitors.
Formulation Type:
Cost tier stratification separates mass-market solid dosages from specialty delivery systems requiring cold chain infrastructure.
- Tablet:Compressed solid dosage forms dominate manufacturing economics across Gujarat and Maharashtra facilities. CDSCO's accelerated dissolution standards for metformin-based fixed-dose combinations favor tablet reformulation over legacy capsule production.
- Capsule:Gelatin-shell delivery systems retain niche positioning for modified-release sulfonylurea formulations targeting gastric tolerance segments.
- Oral Suspension:Liquid formulations serve pediatric and geriatric populations with swallowing difficulties in Kerala's home care networks.
- Injectable:GLP-1 receptor agonist pens and pre-filled syringes occupy hospital outpatient clinics in Delhi NCR corporate chains despite requiring cold storage.
Tablets capture the volume base; oral suspension sees steepest expansion trajectory in geriatric applications.
End User:
Customer type determines procurement authority concentration versus fragmentation across India's healthcare hierarchy.
- Hospitals:Institutional formularies in Maharashtra and Karnataka corporate chains centralize therapeutic class negotiations. SGLT2 inhibitor adoption accelerates where cardiology and nephrology departments influence endocrinology prescribing.
- Clinics:Individual practitioner offices in Madhya Pradesh and Rajasthan tier-two cities maintain sulfonylurea and biguanide dominance through legacy relationships.
- Pharmacies:Apollo and MedPlus networks in Tamil Nadu deploy centralized procurement algorithms that prioritize outcome data packages.
- Home Care:Direct-to-patient delivery models expand in Bengaluru and Hyderabad where CGM integration enables remote titration monitoring.
Hospitals command the highest value per patient; home care is gaining share fastest through chronic disease management programs.
Prescription Type:
Regulatory pathway and intellectual property status create four distinct commercial tracks with divergent margin profiles.
- Prescription:Physician-mandated dispensing governs all SGLT2 and DPP-4 inhibitor categories under CDSCO's scheduled drug classification. Private hospital chains require specialist authorization for initiations.
- Over-the-Counter:Limited to specific metformin strengths in select state jurisdictions where pharmacy board regulations permit self-selection.
- Generic:Post-patent biguanides and sulfonylureas face mandatory substitution in government dispensaries under lowest-tender procurement rules.
- Brand:Differentiated formulations with bioequivalence certifications command shelf-space premiums in corporate pharmacy networks.
Generic substitution dominates volume; branded SGLT2 molecules retain pricing power in private channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API synthesis clusters in Gujarat and Maharashtra while formulation manufacturing spreads across Telangana and Karnataka. CDSCO regional offices in Mumbai and Hyderabad process the bulk of new drug approvals. State-level health insurance penetration varies sharply, creating demand pockets in western and southern India.
Maharashtra
Mumbai and Pune hospital chains drive SGLT2 inhibitor adoption through cardiology-nephrology collaboration. The state government's Mahatma Jyotiba Phule Jan Arogya Yojana expands outpatient pharmaceutical coverage for chronic diseases. Baddi-Nalagarh industrial corridor suppliers feed raw materials to Maharashtra formulation facilities.
Gujarat
Ahmedabad and Vadodara host concentrated API manufacturing for biguanide and sulfonylurea intermediates. CDSCO zonal office in Ahmedabad accelerates generic approval timelines for domestic exporters. Ankleshwar chemical complexes supply DPP-4 inhibitor precursors to formulation plants across India.
Karnataka
Bengaluru corporate hospital chains deploy CGM-integrated oral therapy protocols for affluent patient segments. The state's Arogya Karnataka scheme deepens access to newer oral hypoglycemics in district hospitals. Mysuru and Mangaluru manufacturing zones specialize in extended-release metformin formulations.
Tamil Nadu
Chennai and Coimbatore pharmacy network density enables volume-based SGLT2 contracting. The Chief Minister's Comprehensive Health Insurance Scheme prioritizes lowest-cost procurement, limiting premium formulation access. Tirupur and Salem industrial estates concentrate on solid dosage manufacturing for domestic distribution.
Telangana
Hyderabad's bulk drug and formulation corridor attracts PLI scheme investments for oral hypoglycemic APIs. The state FDA enforces stringent manufacturing compliance standards that filter substandard producers. Genome Valley biotech clusters increasingly support clinical trial infrastructure for cardiorenal outcome studies.
India Oral Anti-Diabetic Drug Market Competitive Environment
Concentration sits with multinational originators holding SGLT2 and DPP-4 portfolios alongside domestic generic giants commanding biguanide and sulfonylurea volumes. The market structures into three tiers: patented molecule specialists, branded generic formulators, and institutional tender suppliers. Competitive moves center on fixed-dose combination portfolio expansion and outcome data integration into hospital formulary negotiations.
Among multinational originators, Sanofi leverages insulin-to-oral continuity across tier-two physician relationships. AstraZeneca anchors the SGLT2 premium tier through cardiovascular outcome trial positioning. Sun Pharma occupies the branded generic intersection with aggressive metformin-sitagliptin fixed-dose pricing. These three represent distinct strategic archetypes: portfolio continuity, outcome differentiation, and cost-engineered combination therapy.
| Leading Market Players |
|---|
| Sanofi |
| Eli Lilly |
| Novo Nordisk |
| AstraZeneca |
| Merck |
| Boehringer Ingelheim |
| Johnson & Johnson |
| Novartis |
| Takeda Pharmaceuticals |
| Others |
Value Chain & Pricing Dynamics
CDSCO bioequivalence certification gates both manufacturing qualification and price tier access simultaneously, as facilities lacking accelerated dissolution compliance for metformin-based fixed-dose combinations forfeit entry into Apollo and MedPlus premium formularies while defaulting to NPPA-controlled government tender pricing.
Pricing Analysis
NPPA price ceilings dictate the pricing tier structure for essential biguanides and sulfonylureas, compressing these volume-base molecules toward commodity levels while SGLT2 inhibitors command premium positioning through cardiorenal outcome data. Three-tier pricing separates outcome-certified hospital formularies from branded generic retail channels from lowest-tender government procurement. Cost compression in the sulfonylurea tier intensifies because of mandatory generic substitution in state insurance schemes. Government dispensaries exhibit extreme price sensitivity, whereas private corporate chains prioritize clinical data packages over unit cost.
Supply Chain Analysis
China and India anchor API production for oral hypoglycemic intermediates, with Ankleshwar and Hyderabad chemical complexes supplying biguanide precursors while Chinese manufacturers dominate DPP-4 inhibitor starting materials. Domestic formulators draw from concentrated import channels for SGLT2 inhibitor active pharmaceutical ingredients. Single-source vulnerability runs through Chinese intermediate suppliers, exposing margin volatility to geopolitical friction. Distribution runs through corporate pharmacy network centralization in Tamil Nadu and Maharashtra, displacing fragmented hospital formulary procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cardiorenal outcome trial capability scarcity defines competitive positioning, as only originators and select domestic partners possess the clinical infrastructure to generate differentiated hospital formulary data.
For Market Incumbents: Compound physician relationship density in tier-two cities through insulin-to-oral portfolio continuity, while securing backward integration into DPP-4 inhibitor precursor production to offset API import concentration. Defend against Sun Pharma's aggressive metformin-sitagliptin pricing by embedding CGM-integrated dosing algorithms into hospital protocols. For New Entrants and Emerging Players: Differentiate on renal dosing specialization for SGLT2 inhibitors targeting diabetic kidney disease populations previously excluded from therapy. White-space sits with tier-three hospital outpatient clinics in Rajasthan and Madhya Pradesh where corporate pharmacy networks expand chronic disease stocking. Deploy medical liaison teams focused on cardiology-nephrology collaboration rather than traditional endocrinology detailing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed domestic formulators possessing CDSCO-approved facilities but lacking outcome trial infrastructure for SGLT2 portfolio elevation. Long-term viability hinges on capturing cardiorenal label expansion timing before patent cliff acceleration. Watch CDSCO accelerated approval pathway volume as the inflection signal for generic entry strategy calibration.| Strategic Initiative | Industry Significance |
|---|---|
| Fixed-Dose Combination Portfolio Expansion | CDSCO streamlined bioequivalence standards reduce regulatory burden for novel metformin-SGLT2 pairings. |
| Cardiorenal Outcome Trial Investment | AstraZeneca's cardiovascular data integration into Apollo formulary negotiations establishes premium positioning precedent. |
| API Backward Integration | PLI scheme incentives for oral hypoglycemic intermediates reduce Chinese import dependency exposure. |
| CGM-Integrated Therapy Protocols | Bengaluru hospital chains deploy real-time dosing algorithms that compress traditional HbA1c monitoring reliance. |
| Tier-Three Hospital Formulary Access | MedPlus network expansion into Madhya Pradesh creates outpatient chronic disease clinic stocking requirements. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads, formulary directors, and hospital procurement managers; and secondary validation through CDSCO approval databases, NPPA pricing notifications, ClinicalTrials.gov cardiorenal outcome studies, and state health insurance scheme procurement records. Bottom-up patient-volume modeling triangulated against top-down pharmaceutical expenditure tracking.
Across the projection horizon, the analytical framework segmented by drug class, formulation type, end user channel, and prescription regulatory status. CAGRs derived from patient population growth, therapy line shift assumptions, and formulary access expansion trajectories. Forecast inputs incorporated PLI scheme incentive uptake rates and patent expiration sequencing for originator SGLT2 molecules.
The analysis sits within stated boundaries; outcomes outside sustained CDSCO accelerated approval pathway volume or abrupt API import restriction would require recalibration. Forecasts reflect documented assumptions regarding state insurance scheme penetration and physician prescribing pattern evolution. Recalibration cycles align with material shifts in regulatory approval timelines and PLI scheme pharmaceutical incentive revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
BRIC Diabetes Care Devices Market
Diabetes Care
Asia-Pacific Oral Anti-Diabetic Drug Market
Diabetes Care
Australia Blood Glucose Monitoring Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
Middle East and Africa Diabetes Pen Market
Diabetes Care
Self-Monitoring Blood Glucose Devices Market
Diabetes Care
Middle East and Africa Insulin Pens Market
Diabetes Care
South Africa Continuous Glucose Monitoring Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Oman Diabetes Care Devices Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Continuous Glucose Monitoring Device Market
Diabetes Care
Artificial Intelligence in Diabetes Management Market
Diabetes Care
Germany Insulin Infusion Pump Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market