
 Spain Self-Monitoring Blood Glucose Devices Market | 2026-2036
Spain Self-Monitoring Blood Glucose Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Self-Monitoring Blood Glucose Devices Market Insights
Market Dynamics
A shortage of specialized diabetes nurse educators is unwinding traditional clinic-dependent care models and pushing patients toward self-directed monitoring protocols. Roche Diabetes Care leverages its established hospital formulary relationships to sustain institutional channel dominance across Spanish endocrinology departments. Abbott Diabetes Care competes through FreeStyle Libre portfolio breadth, while Menarini anchors its position via localized manufacturing and pharmacy distribution networks that cover provincial territories outside major metropolitan hubs.
Technology and Segmentation
Self-monitoring blood glucose devices comprise electrochemical biosensor systems that quantify capillary glucose concentration through enzymatic reaction with glucose oxidase, producing current signals proportional to blood sugar levels for real-time metabolic assessment. Strip-based meters occupy the mature volume tier with compressed margins, whereas continuous glucose monitoring systems capture the fastest-expanding patient cohort as sensor accuracy and calibration-free designs improve reimbursement eligibility. Smart glucometers with Bluetooth connectivity and app integration concentrate emerging margin pools by enabling remote clinician oversight and data-driven insulin dosing adjustments.
Regulatory Environment
Spain's national health system reimbursement criteria, coordinated through the Ministry of Health and regional autonomous community health services, determine patient co-payment obligations and eligible device categories for glucose monitoring. The Spanish Agency for Medicines and Health Products enforces CE marking compliance under EU Medical Device Regulation transitioned frameworks, while ISO 15197 accuracy standards govern meter performance validation for market authorization. Stakeholders must monitor evolving autonomous community procurement centralization initiatives that threaten to consolidate purchasing power and reshape competitive access across Spain's seventeen regional health systems.
Market Dynamics
Decentralized diabetes management protocols are dismantling clinic-dependent care models across Spain's autonomous communities, with regional health services accelerating reimbursement approvals for patient-operated monitoring systems.
Growth Catalysts
- Autonomous community reimbursement expansion:Regional health services in Madrid, Catalonia, and Andalusia have broadened glucose monitoring supply coverage, reducing patient co-payment burdens and expanding eligible device categories.
- Continuous glucose monitoring sensor accuracy improvements:Calibration-free designs and extended wear durations now satisfy Spain's national health system technical criteria, unlocking institutional procurement channels previously reserved for strip-based systems.
- Bluetooth-enabled smart glucometers:These devices integrate with mobile applications to enable real-time data sharing with endocrinology departments, satisfying remote patient monitoring mandates.
Market Restraints
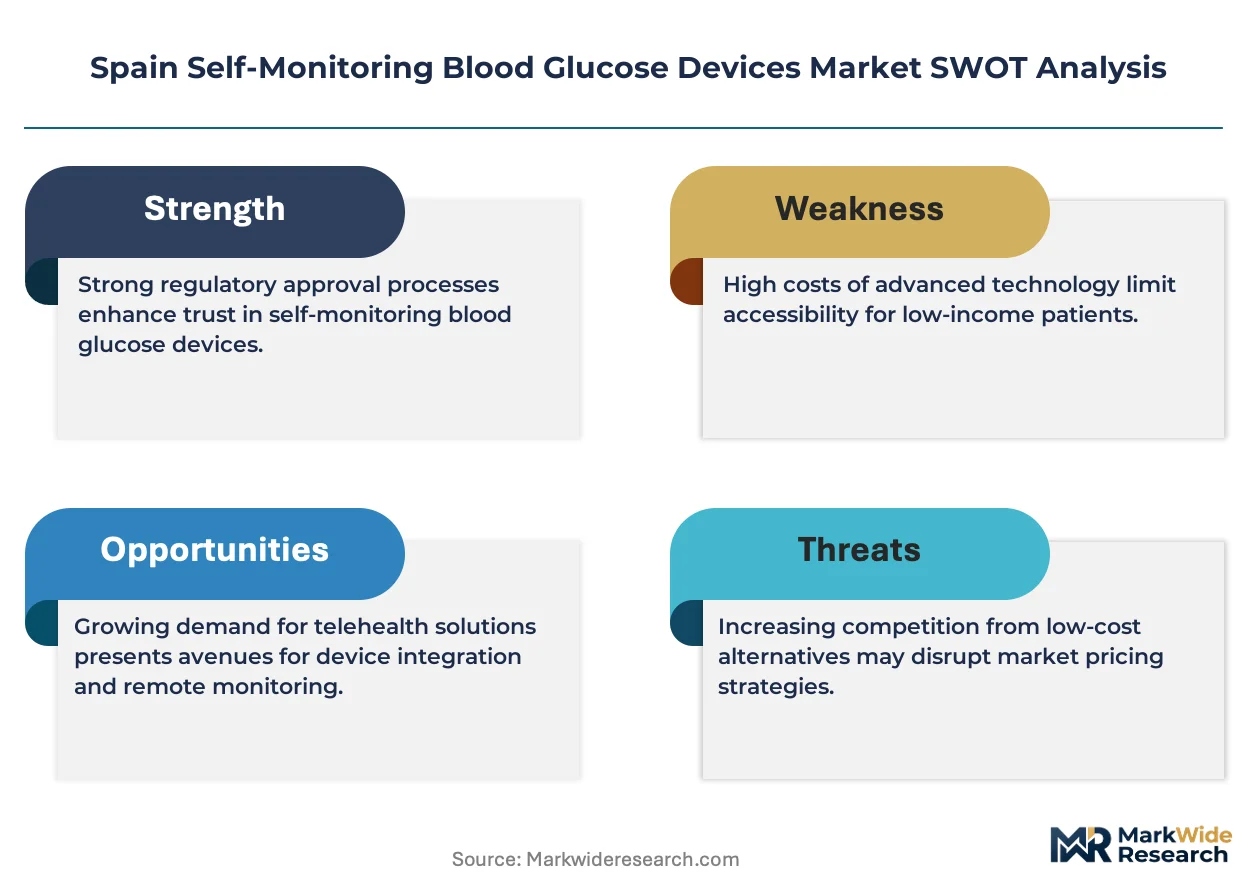
- Specialized diabetes nurse educator shortage:Spain's healthcare workforce gaps limit patient training capacity, constraining adoption rates for complex self-monitoring protocols outside major metropolitan hubs.
- Strip-based meter margin compression:Mature electrochemical biosensor technology faces pricing pressure from regional procurement centralization initiatives consolidating purchasing power.
- EU Medical Device Regulation compliance costs:Transitioned CE marking requirements under MDR frameworks impose validation burdens on manufacturers seeking market authorization.
Strategic Opportunities
- Provincial pharmacy network penetration:Distribution infrastructure outside Madrid, Barcelona, and Seville remains fragmented, creating whitespace for localized manufacturing and direct-to-patient supply models.
- Sensor-platform convergence with insulin delivery systems:Integration of continuous glucose monitoring data with automated insulin dosing algorithms opens closed-loop therapy positioning.
- Data monetization through clinician oversight platforms:Aggregated glucose trend analytics enable population health management contracts with regional health services.
Industry Challenges
- ISO 15197 accuracy validation timelines:Meter performance certification requirements delay product launches and require sustained R&D investment.
- Interoperability with legacy hospital information systems:Integration of patient-generated glucose data into existing electronic health record architectures demands customized middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Self-Monitoring Blood Glucose Devices Market |
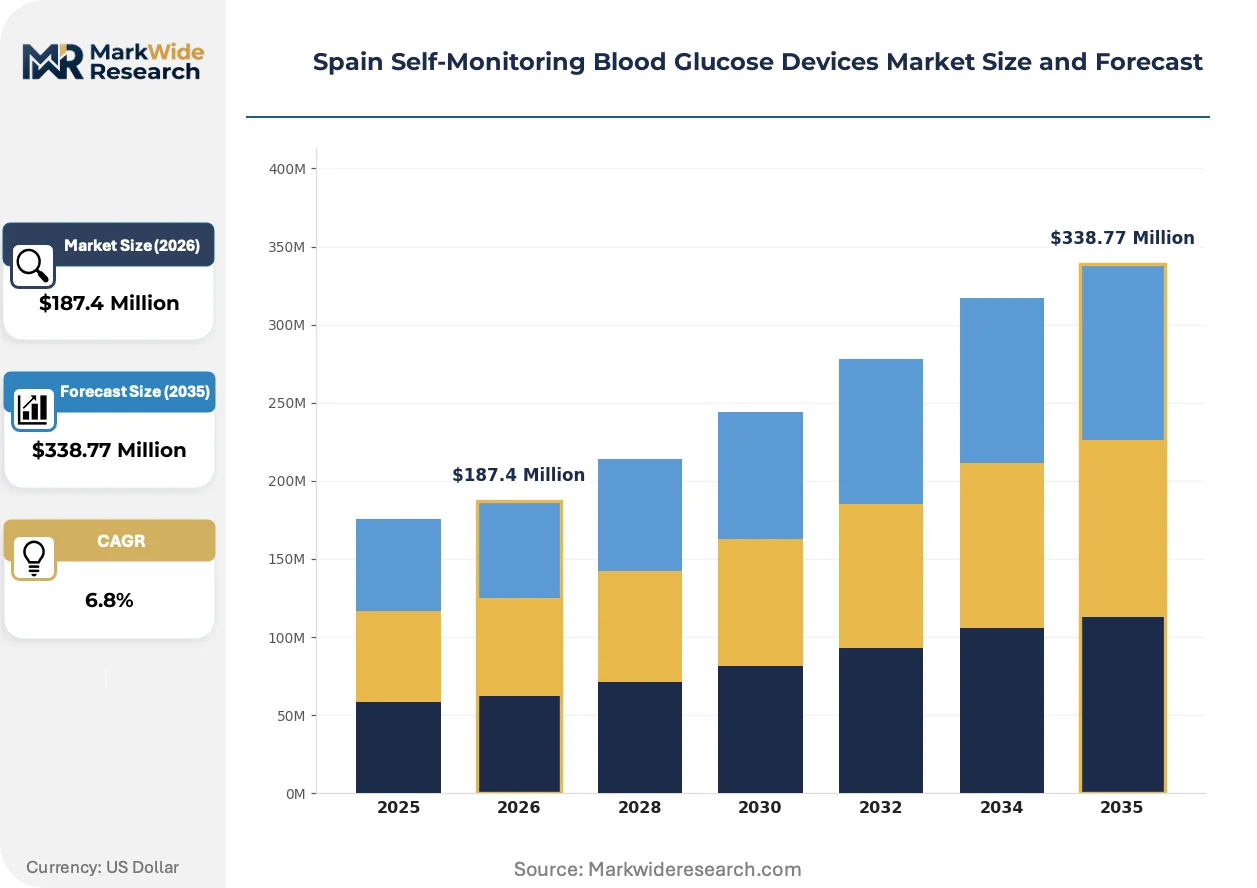
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strip-Based, Continuous Glucose Monitoring, Smart Glucometers, Portable Meters End User: Diabetics, Healthcare Professionals, Home Care Patients, Clinical Laboratories Technology: Electrochemical, Optical, Enzymatic, Non-Invasive Application: Diabetes Management, Health Monitoring, Clinical Research, Drug Development |
| Companies Covered | LifeScan, Rossmax International Ltd, Roche Diabetes Care, Bionime Corporation, Arkray Inc, Abbott Diabetes Care, Sinocare, Menarini, Ascensia Diabetes Care, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Self-Monitoring Blood Glucose Devices Market Trends and Innovations
Sensor miniaturization and wireless connectivity standards are redefining device form factors and patient adherence patterns across Spain's diabetes care pathways.
Continuous glucose monitoring sensor technology is miniaturizing through advances in flexible substrate materials and microelectrode arrays, enabling 14-day wear durations with factory calibration. Home care patients in Catalonia and Madrid are adopting these systems at rates exceeding traditional strip-based protocols. This miniaturization is compressing the installed base of legacy capillary blood draw devices while expanding reimbursement-eligible patient populations.
Spain's Ministry of Health coordinates glucose monitoring reimbursement criteria through regional autonomous community health services, with procurement centralization initiatives consolidating purchasing authority across seventeen regional systems. Industrial consequence includes standardized tender specifications favoring multi-parameter data connectivity. Hospital formulary committees are responding by prioritizing devices with integrated Bluetooth transmission and cloud-based clinician dashboards.
Patient-operated monitoring is displacing clinic-based glucose assessment as the primary diabetes management modality, with autonomous community nurses delegating routine metabolic oversight to remote data review platforms. Community pharmacy channels are capturing device dispensing volume previously controlled by hospital endocrinology departments. This behavioral shift is most visible in Andalusia, where rural healthcare access gaps accelerate adoption of self-directed monitoring with telemedicine backup.
Spain Self-Monitoring Blood Glucose Devices Market Segmentation
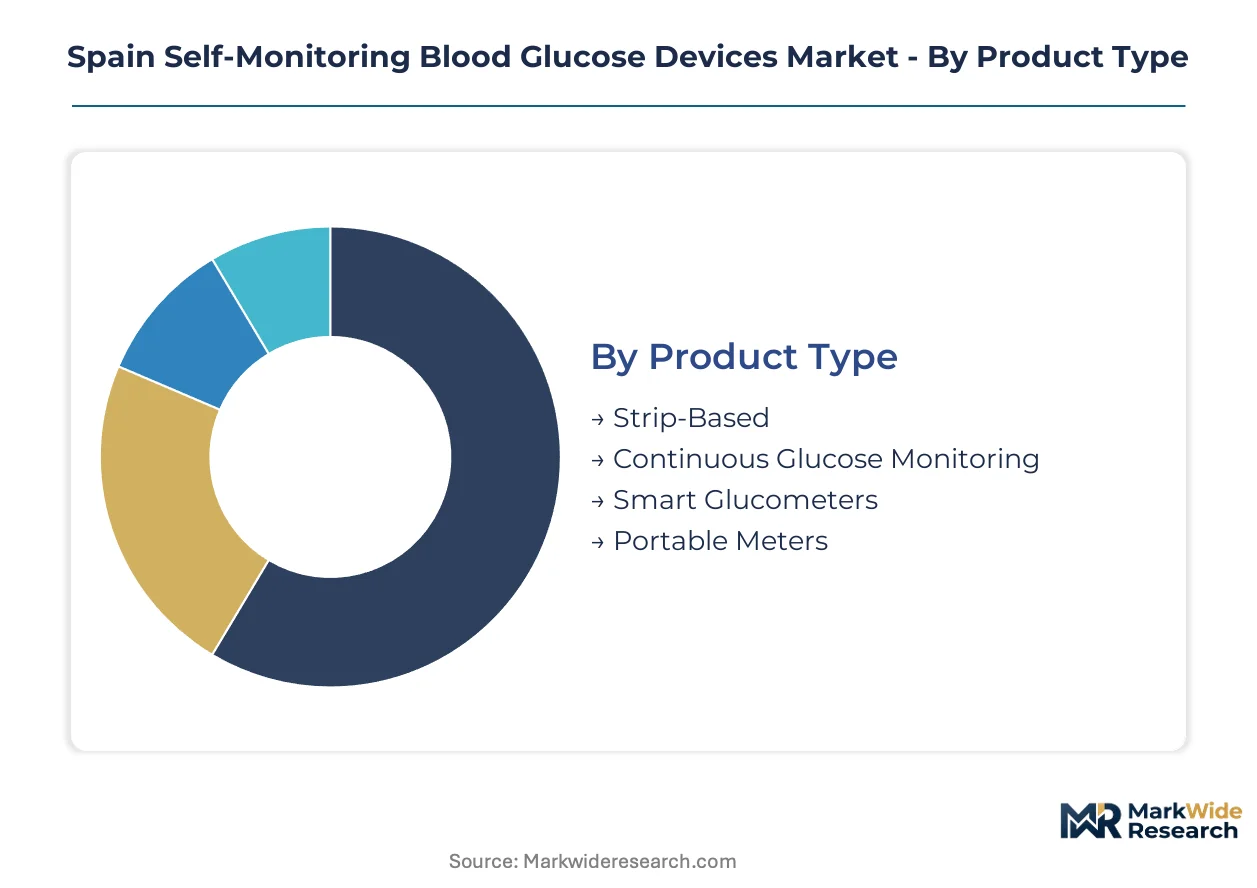
Segmentation in Spain's self-monitoring blood glucose devices market reveals distinct channel affinities and reimbursement pathways. Each category maps to specific procurement hierarchies within the national health system and autonomous community frameworks.
Product Type:
Hospital formularies, community pharmacies, and direct-to-patient subscription channels each favor different device formats based on reimbursement eligibility and technical specifications.
- Strip-Based:Electrochemical biosensor strips with glucose oxidase enzyme coating generate current signals proportional to capillary glucose concentration. Demand concentrates in Andalusian provincial pharmacies where regional procurement centralization has compressed unit economics for legacy meter systems.
- Continuous Glucose Monitoring:Factory-calibrated sensors with 14-day wear duration and flexible substrate microelectrode arrays transmit data wirelessly to receiver devices. Madrid and Catalonia autonomous health services have accelerated reimbursement approvals, shifting procurement volume from hospital endocrinology departments to home care channels.
- Smart Glucometers:Bluetooth-enabled meters with mobile app integration and cloud-based clinician dashboards.
- Portable Meters:Compact battery-operated devices for point-of-care testing outside clinical settings.
By volume, Strip-Based leads. By growth pace, Continuous Glucose Monitoring is ahead.
End User:
Patient training capacity and reimbursement authorization tiers create divergent adoption curves across user categories.
- Diabetics:Individual patients managing Type 1 or Type 2 diabetes through self-directed monitoring protocols with varying degrees of clinical oversight.
- Healthcare Professionals:Endocrinologists, diabetes nurse educators, and primary care physicians prescribing and interpreting glucose monitoring data.
- Home Care Patients:Catalonia and Madrid lead autonomous community adoption as decentralized care models displace clinic-dependent protocols for rural and mobility-limited populations.
- Clinical Laboratories:Hospital-based reference labs processing centralized glucose testing with ISO 15197 accuracy validation requirements.
Home Care Patients capture the steepest expansion trajectory as telemedicine infrastructure matures.
Technology:
Measurement accuracy standards and calibration requirements determine reimbursement eligibility across Spain's seventeen regional health systems.
- Electrochemical:Enzymatic glucose oxidase reaction producing quantifiable current signals dominates strip-based meter architectures with established CE marking pathways under EU MDR frameworks.
- Optical:Spectroscopic or photometric detection methods for transdermal glucose assessment.
- Enzymatic:Bio-catalytic reaction systems with glucose oxidase or glucose dehydrogenase cofactors.
- Non-Invasive:Optical or thermal sensing technologies eliminating capillary blood draw requirements.
Electrochemical commands installed base dominance. Non-Invasive holds the most speculative upside pending clinical validation.
Application:
Reimbursement codes and procurement specifications align device categories to distinct use cases within Spain's national health system.
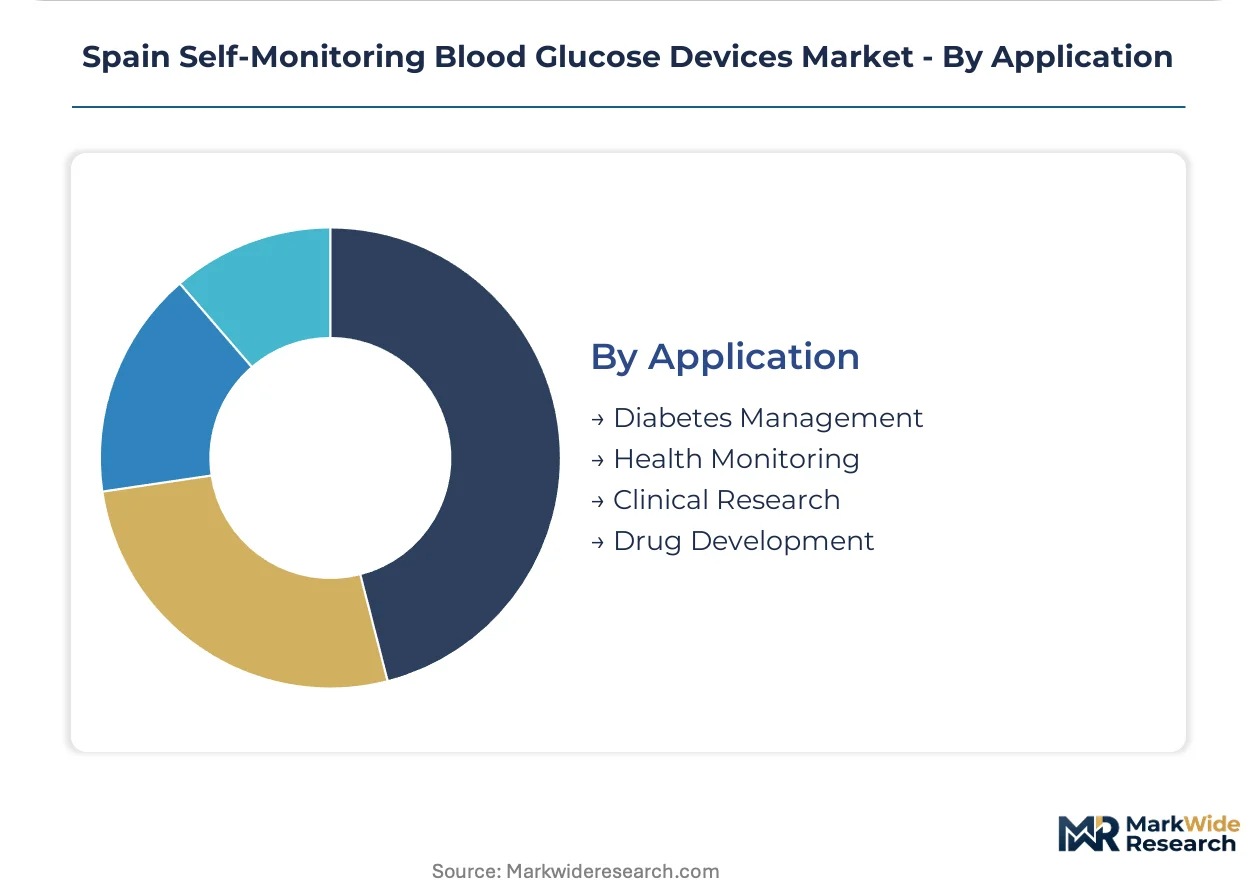
- Diabetes Management:Routine metabolic monitoring for insulin dosing and glycemic control in diagnosed patient populations.
- Health Monitoring:Preventive glucose screening for prediabetes and wellness applications outside formal diabetes diagnosis.
- Clinical Research:Academic medical centers in Barcelona and Madrid deploy continuous glucose monitoring for pharmacokinetic studies and device validation trials.
- Drug Development:Pharmaceutical sponsors contract with Spanish CROs for glucose endpoint monitoring in diabetes therapeutic pipelines.
Diabetes Management generates absolute volume. Clinical Research offers the highest per-unit margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Autonomous communities in northern Spain command pricing premiums over southern counterparts, reflecting divergent reimbursement generosity and healthcare infrastructure density. Madrid and Catalonia concentrate procurement authority while Andalusia operates under tighter budget constraints. This asymmetry shapes manufacturer channel strategies across the seventeen regional health systems.
Madrid
Hospital endocrinology departments in the capital region drive demand for continuous glucose monitoring systems with integrated data platforms. The Ministry of Health coordinates reimbursement criteria that favor Bluetooth-enabled devices with cloud connectivity. The Madrid metropolitan cluster anchors institutional procurement volume for sensor-based monitoring protocols.
Catalonia
Barcelona's medical technology ecosystem accelerates adoption of factory-calibrated sensors among home care patients managing Type 1 diabetes. Regional health services have expanded coverage for fourteen-day wear duration devices, reducing patient co-payment obligations. The Barcelona-Tarragona corridor concentrates pharmacy dispensing networks for smart glucometer distribution.
Andalusia
Provincial pharmacies in Seville, Málaga, and Granada dominate strip-based meter volume as rural healthcare access gaps persist. Regional procurement centralization has compressed unit economics for legacy electrochemical systems. The Andalusian autonomous health service maintains stricter eligibility criteria for continuous monitoring reimbursement compared to northern regions.
Basque Country
Industrial manufacturing heritage in Bilbao and San Sebastián supports localized production of glucose monitoring components for export markets. The regional health service pursues aggressive standardization of tender specifications favoring multi-parameter data connectivity. Basque medical device clusters supply sensor substrates to multinational diabetes care manufacturers.
Valencia
Mid-sized metropolitan hubs including Alicante and Valencia city exhibit growing home care patient populations seeking telemedicine-integrated monitoring solutions. Regional reimbursement policies lag Madrid and Catalonia but show accelerating alignment with EU MDR compliance requirements. The Valencia biotechnology corridor hosts clinical validation trials for non-invasive glucose sensing technologies.
Spain Self-Monitoring Blood Glucose Devices Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure across Spain's autonomous communities. Hospital formulary committees favor established manufacturers with validated accuracy profiles under ISO 15197 standards, while provincial pharmacies prioritize unit economics for high-frequency strip purchases. Three archetypes dominate: multinational diabetes care divisions with institutional channel dominance, regional manufacturers leveraging localized distribution networks, and Asian exporters competing on strip-based meter cost structures. Competitive moves center on sensor-platform convergence with insulin delivery systems and backward integration into enzyme coating production for biosensor strips.
Among multinational diabetes care divisions, Roche Diabetes Care and Abbott Diabetes Care occupy positions exemplifying divergent strategic archetypes. Roche anchors institutional channel relationships through established hospital formulary presence across Spanish endocrinology departments. Abbott represents the sensor-platform convergence vector with its FreeStyle Libre portfolio breadth. Menarini, as an Italy-based pharmaceutical and device manufacturer, sits within the regional manufacturing archetype through localized production and pharmacy distribution networks penetrating provincial territories outside major metropolitan hubs.
| Leading Market Players |
|---|
| LifeScan |
| Rossmax International Ltd |
| Roche Diabetes Care |
| Bionime Corporation |
| Arkray Inc |
| Abbott Diabetes Care |
| Sinocare |
| Menarini |
| Ascensia Diabetes Care |
| Others |
Pricing and Supply Chain Analysis
Regional procurement centralization contracts lock in multi-year glucose monitoring supply commitments across Spain's autonomous communities, anchoring price visibility for hospital formulary committees while compressing margins for strip-based meter suppliers competing on standardized tender specifications.
Pricing Analysis
Customization-premium spreads separate Bluetooth-enabled smart glucometers with cloud connectivity from basic electrochemical strip meters. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 15197 certification grade, factory-calibrated sensor accuracy, and bundled clinician oversight services. Pricing pressure stems from Andalusian regional procurement consolidation favoring lowest-compliant-bid awards for high-volume strip purchases. Home care patients in Madrid and Catalonia exhibit lowest price sensitivity due to generous reimbursement coverage, while provincial pharmacies in southern Spain face acute cost compression.
Supply Chain Analysis
Germany and Ireland anchor enzyme coating production for glucose oxidase biosensor strips, while China and South Korea supply flexible substrate microelectrode arrays for continuous monitoring sensors. Spain's domestic manufacturing concentrates in Basque Country sensor substrate fabrication and Menarini's localized device assembly. Single-source vulnerability in glucose oxidase enzyme supply creates exposure to EMA regulatory inspections. Distribution runs through hospital procurement consortia in Madrid and Catalonia, provincial pharmacy networks in Andalusia, and direct-to-patient subscription channels for sensor-based systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's self-monitoring blood glucose devices market sits in early-cycle expansion as decentralized diabetes management protocols displace clinic-dependent care models and unlock reimbursement for patient-operated monitoring systems.
For Market Incumbents: Compound formulary lock-in through sensor-platform convergence with automated insulin delivery algorithms, defending against Abbott's FreeStyle Libre portfolio breadth. Deepen backward integration into glucose oxidase enzyme production to offset margin compression from regional procurement centralization. Prioritize CE marking pathway acceleration under EU MDR transitioned frameworks to maintain hospital channel access. For New Entrants and Emerging Players: Differentiate on telemedicine-integrated data platforms targeting Valencia and Andalusia home care patients underserved by incumbent distribution networks. Penetrate provincial pharmacy whitespace outside Madrid-Barcelona-Seville metropolitan clusters through localized manufacturing partnerships. Pursue autonomous community nurse educator shortage as entry wedge, offering remote patient training bundled with device subscriptions. For Investors and Strategic Acquirers: Sensor substrate specialists with ISO 13485 certification and existing relationships to Basque Country medical device clusters represent priority acquisition archetypes. Long-term viability hinges on convergence toward closed-loop therapy systems integrating continuous glucose monitoring with automated insulin dosing. Watch for inflection signals in Menarini's manufacturing capacity expansion announcements and Basque regional health service tender specification shifts favoring multi-parameter data connectivity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance unlocks institutional procurement channels across seventeen autonomous community health systems. |
| Hospital System Partnership | Formulary relationships with Madrid endocrinology departments anchor sensor-based monitoring volume. |
| Software Companion Development | Bluetooth-enabled mobile apps satisfy remote patient monitoring mandates from Spain's Ministry of Health. |
| Reimbursement Strategy | Autonomous community coverage expansion in Catalonia reduces patient co-payment burdens for factory-calibrated sensors. |
| Backward Integration | In-house glucose oxidase enzyme production defends margin position against strip-based meter pricing compression. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, diabetes nurse educators, biomedical engineers, and GPO contracts managers, and refined through secondary validation against Spanish Agency for Medicines and Health Products CE marking databases, autonomous community procurement registries, CMS Medicare cross-reference data, and ISO 15197 accuracy certification records. Bottom-up patient population estimates triangulated with top-down healthcare expenditure flows.
Variance-decomposition across product type, end user category, technology platform, and autonomous community geography shaped the analytical framework. CAGRs were derived from segmented adoption curves calibrated to reimbursement policy trajectories and sensor accuracy improvement timelines. Continuous glucose monitoring penetration rates and smart glucometer connectivity integration served as industry-specific forecast anchors throughout the projection horizon.
Material uncertainties — autonomous community procurement centralization pace, EU MDR enforcement stringency, diabetes nurse educator workforce expansion — sit outside the modeled envelope. Forecasts reflect assumptions about reimbursement generosity continuity and sensor-platform convergence adoption. Recalibration cycles align with material shifts in Spain's national health system technology assessment criteria and regional tender specification standardization initiatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diabetes Care
South Africa Blood Glucose Monitoring Market
Diabetes Care
Oman Diabetes Drugs Market
Diabetes Care
Continuous Glucose Monitoring in Philippines Market
Diabetes Care
South Korea Oral Anti-Diabetic Drug Market
Diabetes Care
Point of Care Glucose Testing Market
Diabetes Care
Oman Insulin Drugs and Delivery Devices Market
Diabetes Care
Disposable Insulin-Delivery Device Market
Diabetes Care
Thailand Oral Antidiabetic Drug Market
Diabetes Care
Japan Insulin Drugs and Delivery Devices Market
Diabetes Care
Global Blood Glucose Monitoring Systems Market
Diabetes Care
Sensor Based Glucose Measuring Systems Market
Diabetes Care
Latin America Oral Anti-Diabetic Drug Market
Diabetes Care
Latin America Diabetes Care Devices Market
Diabetes Care
Mexico Oral Anti-Diabetic Drug Market
Diabetes Care
Vietnam Insulin Drug and Delivery Device Market
Diabetes Care
Asia Pacific Continuous Glucose Monitoring (CGM) Market