
 UK Food Enzymes Market | 2026-2036
UK Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
UK Food Enzymes Market Analytics
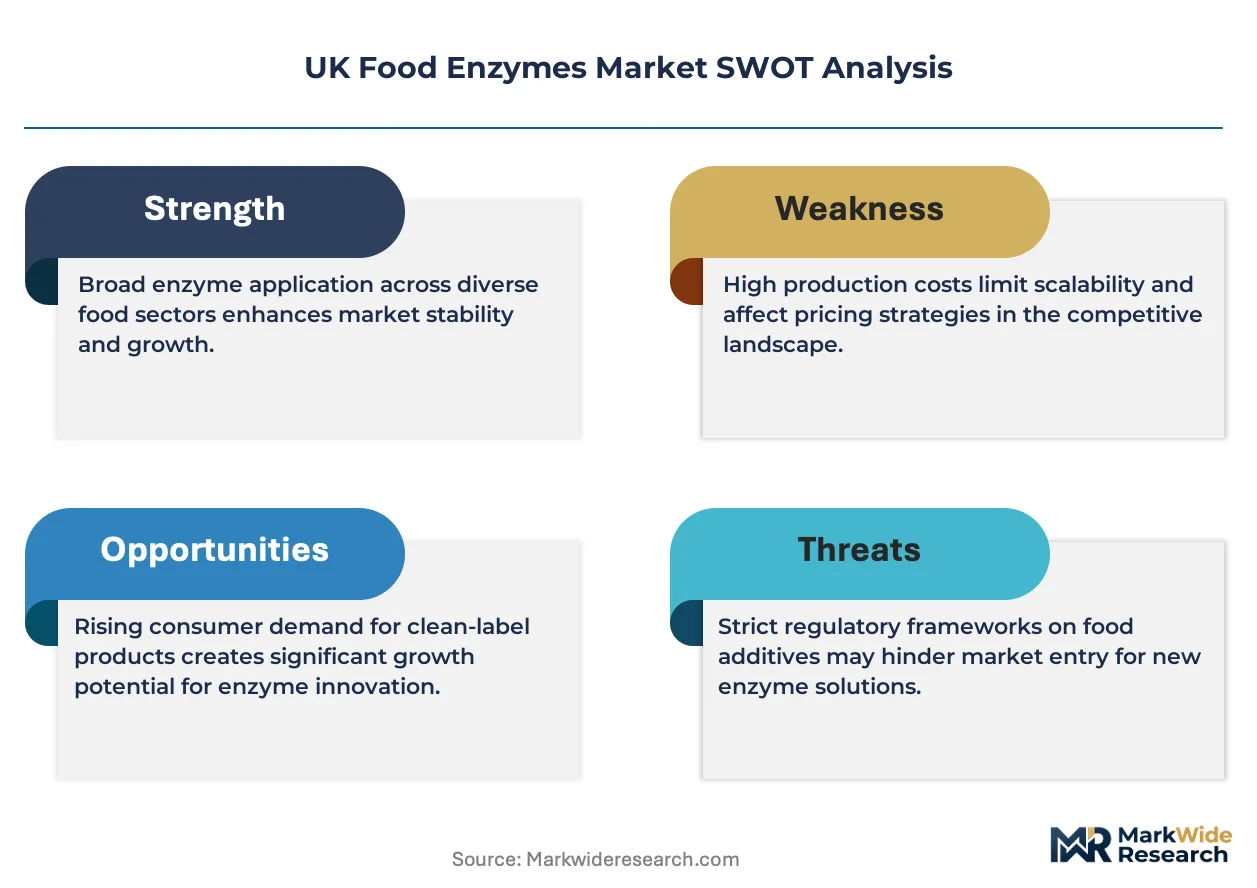
Biochemist recruitment bottlenecks across British food technology is redrawing competitive boundaries for enzyme suppliers. Kerry Group plc leverages its integrated ingredient platforms to sustain formulation partnerships with UK bakery manufacturers. Associated British Foods plc anchors domestic supply through captive enzyme development and in-house production of specialty baking solutions. Novonesis Group competes on fermentation scale, positioning its biocatalyst portfolio for dairy processing expansion across British co-operatives.
Food enzymes comprise protein-based biocatalysts, typically operating at 30–70°C and pH 4.0–8.0, that accelerate hydrolysis, oxidation, and isomerization reactions without entering the final product composition. These catalysts serve industrial food processing by reducing maturation time, improving yield extraction, and enabling consistent product texture across batch production. Proteases command the largest share of product type demand due to their ubiquity in meat tenderization and dairy coagulation, while lipases generate premium margin pools from specialized fat-modification contracts. Application concentration tilts toward baking, where amylase blends optimize dough rheology and extend shelf stability for industrial bread lines.
The Food Standards Agency enforces novel food authorizations under retained EU Regulation 2015/2283, while Health and Safety Executive protocols govern occupational enzyme exposure limits in manufacturing facilities. British Standards Institution certification and EU REACH-aligned substance registrations create dual compliance tracks for imported biocatalyst formulations. Stakeholders must monitor divergence between UK-specific enzyme approval pathways and continuing EU regulatory alignment as the post-Brexit chemicals framework crystallizes.
Market Dynamics
Post-Brexit divergence between UK and EU enzyme approval pathways is fragmenting supplier compliance architectures. British manufacturers now navigate parallel substance registration tracks while FSSAI-aligned import scrutiny intensifies at ports.
Growth Catalysts
- Clean-label bakery reformulation:Amylase blends replace chemical conditioners in industrial bread lines as retailers mandate ingredient transparency. British supermarkets now enforce shorter additive panels.
- Retained EU Regulation 2015/2283:Novel food authorization pathways provide regulatory certainty for enzyme innovators seeking UK market entry ahead of divergence.
- Midlands processing cluster concentration:Proximity between enzyme formulators and baked goods manufacturers reduces logistics friction and enables just-in-time biocatalyst delivery.
Market Restraints
- Fermentation feedstock volatility:Molasses and grain-derived substrates face price pressure from biofuel competition, squeezing lipase production economics.
- Single-source dependency:Specialty protease supply concentrates among Danish and Dutch fermentation houses, exposing British meat processors to disruption risk.
- Thermostability ceiling:Current amylase variants degrade above 75°C, limiting deployment in high-temperature extrusion applications for snack manufacturing.
Strategic Opportunities
- Northern Irish dairy expansion:Cross-border milk pooling creates scale for chymosin and lipase deployment in cheese processing cooperatives.
- EU REACH-UK REACH divergence:Dual registration requirements favor suppliers with existing EU dossiers seeking first-mover advantage in British biocatalyst niches.
- Enzyme-sensor integration:Real-time activity monitoring systems converge with immobilized biocatalyst platforms to enable predictive process control in continuous baking lines.
Industry Challenges
- Biochemist recruitment scarcity:British food technology programs graduate insufficient fermentation specialists to staff Midlands enzyme development labs.
- Novel food authorization timelines:Food Standards Agency review cycles extend 18-24 months, delaying revenue recognition for innovative enzyme submissions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Food Enzymes Market |
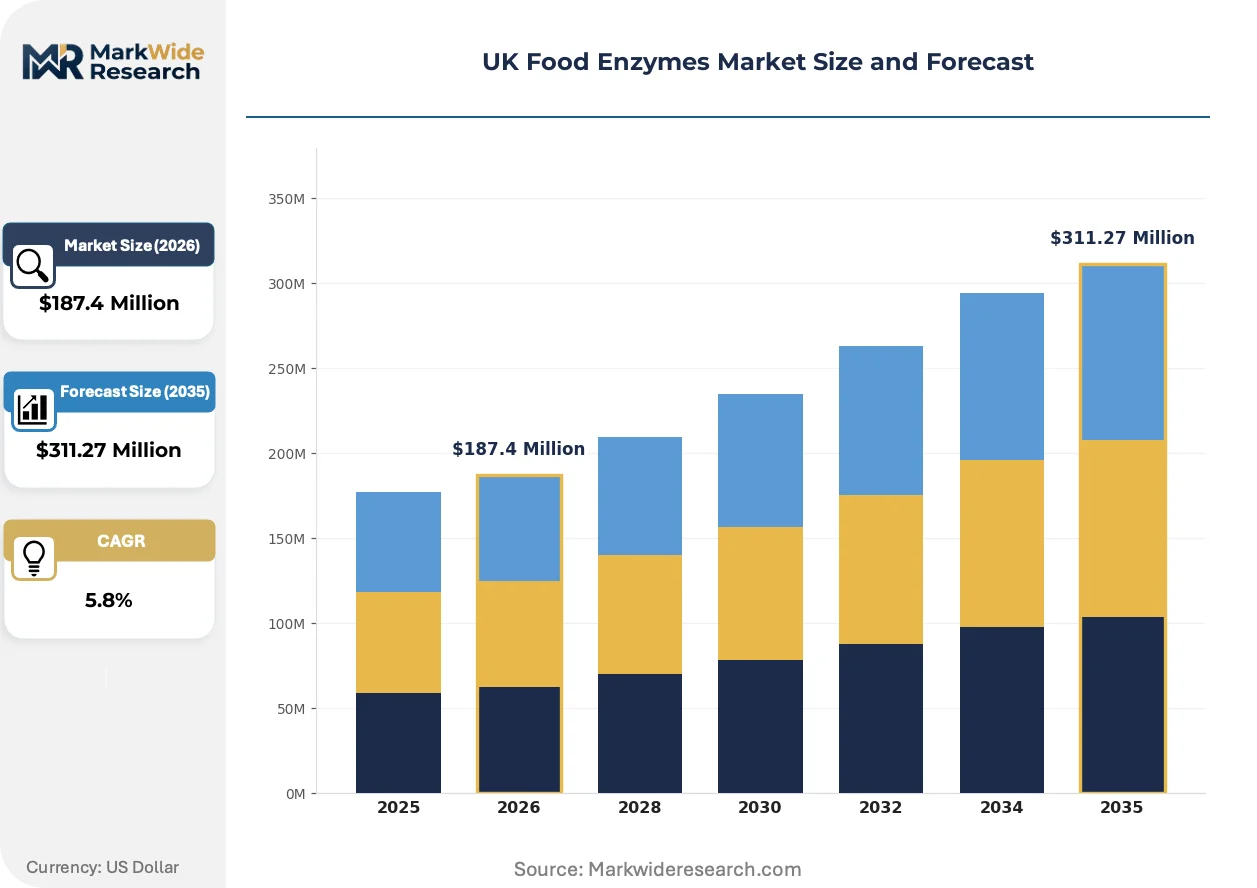
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases Application: Baking, Brewing, Dairy, Meat Processing End User: Food Manufacturers, Beverage Producers, Bakery, Dairy Producers Form: Liquid, Powder, Granular, Tablets |
| Companies Covered | Associated British Foods plc, Kerry Group plc, DuPont de Nemours Inc., Koninklijke DSM N.V., Novonesis Group, Chr. Hansen Holding A/S, Amano Enzyme Inc., International Flavors & Fragrances Inc., AB Enzymes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Food Enzymes Market Evolving Landscape
Biocatalyst engineering is accelerating beyond traditional fermentation optimization toward precision-designed enzyme variants. British manufacturers now demand performance specifications tailored to specific flour matrices and processing conditions.
Immobilized enzyme systems is bifurcating the biocatalyst supply landscape. Continuous baking lines at Warburtons and Hovis deploy fixed-bed amylase reactors to reduce enzyme consumption by half. This technology is compressing batch-based enzyme sales volumes while expanding recurring substrate and reactor maintenance contracts.
Retained EU Regulation 2015/2283 divergence protocols are forcing dual-track safety dossier preparation. British suppliers now maintain parallel toxicology submissions for UK REACH and continuing EU compliance. Dairy enzyme categories face the steepest documentation burden as novel protein modifications trigger extended evaluation windows.
Specification-driven procurement now dominates large bakery group purchasing. Technical teams at Associated British Foods and Premier Foods issue enzyme performance mandates rather than brand nominations. This pattern concentrates supplier relationships around three to four formulation partners capable of co-developing bespoke amylase-lipase blends for specific flour profiles.
UK Food Enzymes Market Segmentation
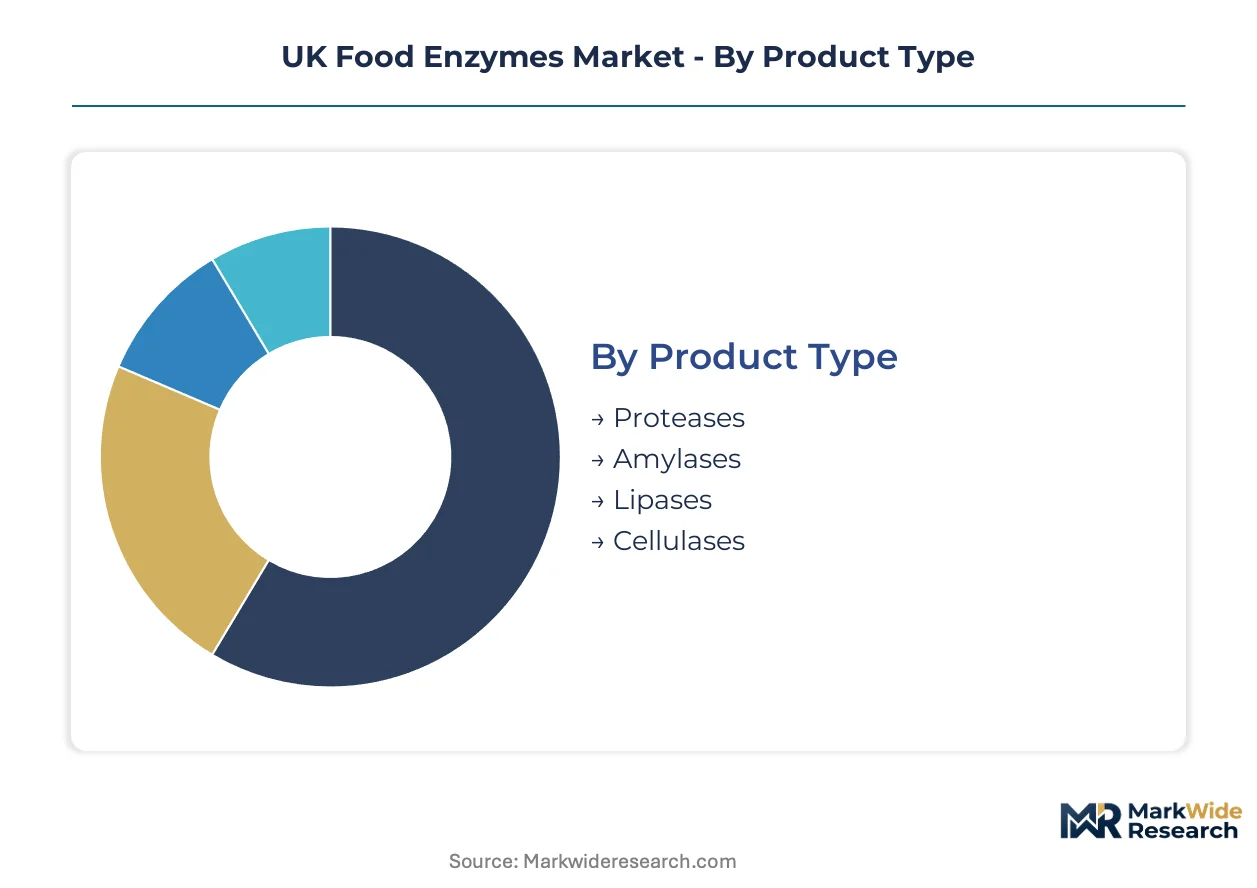
Enzyme procurement patterns across British food manufacturing diverge sharply between commodity bulk buyers and specialty formulators seeking bespoke biocatalyst solutions. Understanding these segment boundaries clarifies where supplier relationships consolidate versus where technical differentiation commands premium positioning.
Product Type:
Domestic fermentation capacity concentrates protease and amylase supply, while lipase and cellulase production relies more heavily on imported biocatalysts from continental European facilities.
- Proteases:These protein-hydrolyzing enzymes operate optimally at 45–60°C with broad pH tolerance from 5.5 to 8.0. British meat processors and dairy cooperatives in Yorkshire and the Midlands anchor demand, driven by clean-label tenderization protocols that displace chemical phosphates.
- Amylases:Starch-modifying biocatalysts with temperature stability up to 75°C enable dough conditioning and anti-staling in industrial bread production. Warburtons and Hovis production lines in the English Midlands specify fungal-derived variants for consistent flour performance across variable wheat harvests.
- Lipases:Fat-modifying enzymes from controlled fermentation generate diacetyl and ester compounds for flavor enhancement. Specialty contracts with artisan cheese producers in Somerset and Cheddar command premium formulation fees.
- Cellulases:Cellulose-degrading biocatalysts improve juice extraction efficiency and texture modification. Scottish fruit processing cooperatives and English cider houses in Herefordshire represent the primary domestic uptake.
Proteases command the established base. The steepest expansion runs through lipases.
Application:
Cost tier stratification separates high-volume commodity enzyme users from premium specialty processors willing to fund co-development partnerships with biocatalyst suppliers.
- Baking:Industrial bread manufacturers deploy amylase blends to optimize dough rheology and extend shelf stability without chemical preservatives. Premier Foods and Associated British Foods technical teams issue performance specifications rather than brand nominations, concentrating supplier relationships.
- Brewing:Mashing enzymes from fungal and bacterial sources accelerate starch conversion and improve wort fermentability. Scottish craft breweries and major lager producers in Burton-upon-Trent differentiate through enzyme-assisted adjunct processing for cost-optimized grain bills.
- Dairy:Chymosin and lipase biocatalysts enable coagulation control and flavor development in cheese manufacturing. Northern Irish cross-border milk pooling creates scale for cooperative enzyme deployment across cheddar and specialty cheese production.
- Meat Processing:Protease marinades and tenderization systems reduce mechanical processing requirements. British sausage and prepared meat manufacturers face retailer pressure to eliminate phosphate additives, redirecting formulation spend toward enzyme-based alternatives.
Baking absorbs the highest absolute enzyme volumes. Dairy applications are climbing the fastest as British cheese exports expand.
End User:
Customer type determines procurement sophistication, with multinational food manufacturers demanding integrated supply contracts while regional dairies prioritize technical service responsiveness.
- Food Manufacturers:Large-scale processors of prepared meals, sauces, and convenience foods require consistent enzyme activity across batch production. These buyers negotiate annual supply agreements with formulation guarantees and regulatory documentation packages.
- Beverage Producers:Brewers and distillers utilize glucoamylase and pullulanase variants for attenuation control and filtration efficiency. English malt whisky distilleries in Speyside and grain ethanol facilities represent distinct specification requirements.
- Bakery:Industrial bread and pastry manufacturers constitute the most concentrated demand pool. Midlands-based production clusters enable just-in-time liquid enzyme delivery from nearby formulation plants.
- Dairy Producers:Cheese makers and yogurt processors specify chymosin purity grades and lipase activity levels. Organic certification requirements segment this category into conventional and premium biocatalyst tiers.
Food manufacturers anchor procurement volume. Dairy producers are gaining share fastest through specialty cheese export growth.
Form:
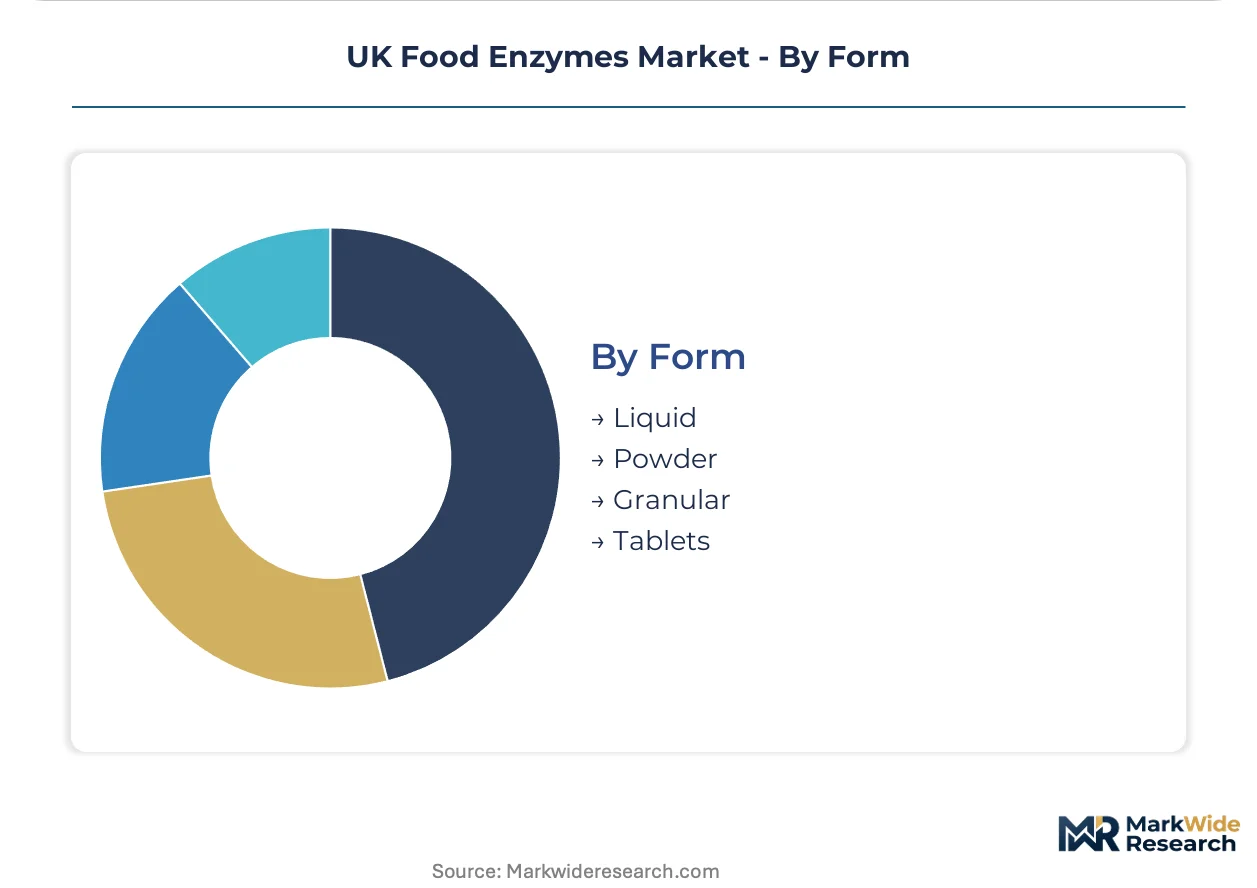
Supply concentration favors liquid formulations for high-throughput continuous processing, while powder and granular forms serve batch manufacturers with intermittent enzyme requirements.
- Liquid:Pumpable enzyme concentrates enable automated dosing in continuous baking and brewing lines. British industrial bakeries favor liquid amylase systems for integration with existing CIP infrastructure.
- Powder:Free-flowing enzyme preparations suit dry blending operations in flour milling and premix manufacturing. Northern English flour millers specify powder proteases for protein modification prior to dough mixing.
- Granular:Dust-free enzyme carriers improve handling safety in meat processing environments. British sausage manufacturers adopt granular lipase formulations for controlled fat modification.
- Tablets:Pre-measured enzyme units serve small-batch artisan producers lacking liquid dosing equipment. Microbreweries and farmhouse cheese operations in Wales and the Southwest represent the primary uptake.
Liquid formulations dominate established industrial demand. Granular forms are expanding most quickly through meat processing safety upgrades.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Food Standards Agency anchors enzyme regulation across British manufacturing corridors. Post-Brexit divergence from EU REACH protocols fragments compliance architectures for cross-border suppliers. Regional concentration patterns reflect proximity between fermentation capacity and end-use processing clusters.
England
Industrial bread manufacturers in the Midlands drive amylase demand through specification-driven procurement. Retained EU Regulation 2015/2283 governs novel food authorizations while UK REACH registration requirements tighten for imported biocatalysts. Birmingham and Nottingham processing corridors host just-in-time liquid enzyme delivery systems serving Warburtons and Hovis production lines.
Scotland
Speyside malt whisky distilleries utilize glucoamylase variants for attenuation control in grain ethanol conversion. The Scottish Environment Protection Agency monitors industrial effluent from fermentation facilities under devolved environmental permitting. Edinburgh and Glasgow anchor biocatalyst distribution networks for Highland beverage cooperatives.
Wales
Artisan cheese producers in Pembrokeshire and Ceredigion specify chymosin purity grades for specialty export contracts. Rural Development Programme Wales funding supports dairy processing modernization in agricultural cooperatives. Swansea and Cardiff serve as logistics nodes for enzyme delivery to farmhouse operations lacking liquid dosing infrastructure.
Northern Ireland
Cross-border milk pooling with the Republic creates scale for lipase deployment in cheddar manufacturing cooperatives. DAERA enforces dual compliance with UK REACH and continuing EU substance registration for biocatalyst imports. Armagh and Tyrone dairy clusters benefit from integrated enzyme supply chains spanning the island.
UK Food Enzymes Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in British enzyme supply. Consolidation pressure intensifies as specification-driven procurement concentrates relationships around formulation partners with co-development capabilities. Three archetypes dominate: diversified ingredient platforms, captive fermentation houses, and precision biocatalyst specialists. Capacity expansion and strategic partnerships represent the primary competitive vectors as suppliers defend position in bakery and dairy verticals.
Within the integrated platform tier, Kerry Group plc and Associated British Foods plc exemplify formulation-forward positioning. Kerry leverages its ingredient portfolio to sustain technical partnerships with Midlands manufacturers. Associated British Foods anchors domestic supply through in-house specialty development. Novonesis Group occupies the fermentation scale tier, competing on biocatalyst volume for dairy processing expansion across British cooperatives.
| Leading Market Players |
|---|
| Associated British Foods plc |
| Kerry Group plc |
| DuPont de Nemours Inc. |
| Koninklijke DSM N.V. |
| Novonesis Group |
| Chr. Hansen Holding A/S |
| Amano Enzyme Inc. |
| International Flavors & Fragrances Inc. |
| AB Enzymes |
| Others |
Value Network & Pricing Analysis
Fourteen-to-eighteen-day liquid enzyme lead times from Midlands formulation plants to Birmingham baking corridors concentrate pricing power with integrated suppliers possessing captive fermentation capacity. This inventory compression tightens cost discipline among British manufacturers while rewarding biocatalyst formulators with regional production footprints.
Pricing Analysis
Continental European lipase imports command 15-25% premia over domestically fermented protease and amylase equivalents, reflecting Danish and Dutch supplier concentration in specialty fat-modification biocatalysts. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and volume commitment, with FSA novel food authorization status commanding formulation premiums. Cost compression in standard-grade amylase blends is intensifying because Warburtons and Hovis procurement teams consolidate supplier panels. Small-scale artisan cheese producers in Somerset exhibit highest price sensitivity, while Midlands industrial bakeries prioritize performance guarantees over unit cost.
Supply Chain Analysis
Strait of Dover transit chokepoints expose British enzyme importers to customs inspection delays as FSSAI-aligned scrutiny intensifies at UK ports. Domestic fermentation capacity concentrates protease and amylase supply, while lipase and cellulase production draws from Danish, Dutch, and German facilities. Raw material dependencies on molasses substrates, grain-derived media, and pharmaceutical-grade filtration membranes create feedstock volatility exposure. Single-source vulnerability runs through specialty protease supply chains. Distribution runs through just-in-time liquid delivery networks serving Midlands processing clusters, supplemented by powder and granular shipments to Northern English flour millers and Welsh farmhouse operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
UK food enzymes sit in early-cycle expansion as clean-label bakery reformulation accelerates biocatalyst displacement of chemical conditioners across British supermarket supply chains.
For Market Incumbents: Consolidate formulation partnerships through captive Midlands production capacity and exclusive supply agreements with Warburtons-scale baking groups. Threats from Novonesis Group fermentation scale and Kerry Group integrated ingredient platforms intensify competitive pressure. Certification investment in parallel UK REACH and retained EU dossier preparation defends positioning against post-Brexit regulatory divergence. For New Entrants and Emerging Players: Differentiate on immobilized enzyme system integration for continuous baking line retrofits, where technical service responsiveness gaps exist among established suppliers. White-space targets include Northern Irish dairy cooperatives leveraging cross-border milk pooling scale and Welsh artisan cheese producers lacking liquid dosing infrastructure. Go-to-market through predictive maintenance contracts bundling biocatalyst supply with reactor monitoring systems. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underexploited food-grade fermentation assets and stranded capacity in pharmaceutical enzyme production. Long-term viability hinges on regulatory compliance infrastructure and co-development relationships with specification-driven bakery technical teams. Watch FSA novel food authorization timeline compression as signal of competitive access improvement.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstock | Molasses and grain substrate sourcing control insulates margin structures from biofuel competition pressure. |
| Immobilized Enzyme Platform Deployment | Fixed-bed reactor installations at Hovis and Warburtons compress batch sales volumes while expanding recurring service contracts. |
| Dual-Track Regulatory Dossier Preparation | Parallel UK REACH and retained EU submissions position suppliers for first-mover advantage in post-Brexit divergence scenarios. |
| Midlands Formulation Capacity Expansion | Proximity to Birmingham and Nottingham baking corridors reduces logistics friction and enables just-in-time liquid delivery. |
| Predictive Process Control Partnerships | Enzyme-sensor integration with continuous baking lines creates technical switching costs and deepens customer relationships. |
Research Methodology
A standing panel of fermentation plant managers, bakery technical directors, dairy cooperative procurement leads, and FSA regulatory affairs specialists provided ongoing calibration across primary fieldwork and secondary validation. Primary interviews with Midlands enzyme formulators, Yorkshire meat processors, and Northern Irish dairy operators combined with customs trade data, British Standards Institution certification records, Food Standards Agency submission databases, and SEC filings from listed ingredient suppliers. Bottom-up volume modeling across product type, application, and form segments triangulated against top-down market sizing from production capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled enzyme demand by product type, application concentration, end-user procurement sophistication, and geographic processing cluster. CAGRs derived from segment-level growth rate reconciliation with macro food manufacturing output trends. Forecast inputs incorporated flour matrix variability specifications, clean-label reformulation adoption curves, and regulatory authorization pipeline visibility.
The analysis sits within stated boundaries; outcomes outside retained EU Regulation alignment or UK REACH implementation timelines would require recalibration. Forecasts reflect assumptions regarding biochemist labor supply, fermentation feedstock cost trajectories, and bakery procurement consolidation patterns. Practitioners should keep alternative scenarios live as FSA novel food authorization protocols and Brexit-adjusted chemical registration frameworks evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Excipients Market
Food Additives and Ingredients
Starch-Based Texturizing Agents Market
Food Additives and Ingredients
Bulking Agents Market
Food Additives and Ingredients
Russia Food Emulsifiers Market
Food Additives and Ingredients
North America Food Emulsifiers Market
Food Additives and Ingredients
Liquid Caramel Color Market
Food Additives and Ingredients
Japan Feed Additives Market
Food Additives and Ingredients
Food Enzymes Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Scrambled Egg Mix Market
Food Additives and Ingredients
Cetyl Palmitate Market
Food Additives and Ingredients
Instant Fat Powder Market
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Food Phosphate Market
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
Global Integrated Food Ingredient Market