
 United States Anti-Caking Market | 2026-2036
United States Anti-Caking Market Size, Share, and Industry Trends Forecast 2026-2036
United States Anti-Caking Market Analytics
Food manufacturers is rotating toward pharmaceutical-grade anti-caking specifications as nutraceutical powder formulations proliferate. Cargill, Incorporated leverages its grain-processing backbone to supply silicon dioxide variants across multiple end-use tiers. Evonik Industries AG sustains R&D intensity in precipitated silica technologies for moisture-sensitive applications. Cabot Corporation anchors its position through fumed silica production scale serving industrial salt and fertilizer blenders.
Anti-caking agents are powdered or granular additives, typically comprising silica-based compounds, carbonates, or silicates, engineered to maintain free-flow properties in hygroscopic materials by absorbing moisture or creating physical separation between particles. These substances prevent clumping in salt, sugar, fertilizers, and pharmaceutical powders during storage and transport under variable humidity conditions. Sodium silicate and calcium carbonate occupy mature volume positions in agricultural and industrial applications where cost efficiency outweighs premium performance requirements. Pharmaceutical-grade and food-grade specifications command margin concentration due to FDA purity certifications and lot-traceability demands that technical-grade suppliers cannot readily satisfy.
The FDA, EPA, and USDA collectively govern anti-caking agent approval, environmental discharge from manufacturing facilities, and residue limits in food-contact applications across the United States. FSMA-mandated hazard analysis pushes food manufacturers toward pre-qualified supplier lists, tightening market access for uncertified producers. Stakeholders must monitor evolving EPA air-quality standards for silica particulate emissions as enforcement intensifies in production-heavy states.
Market Dynamics
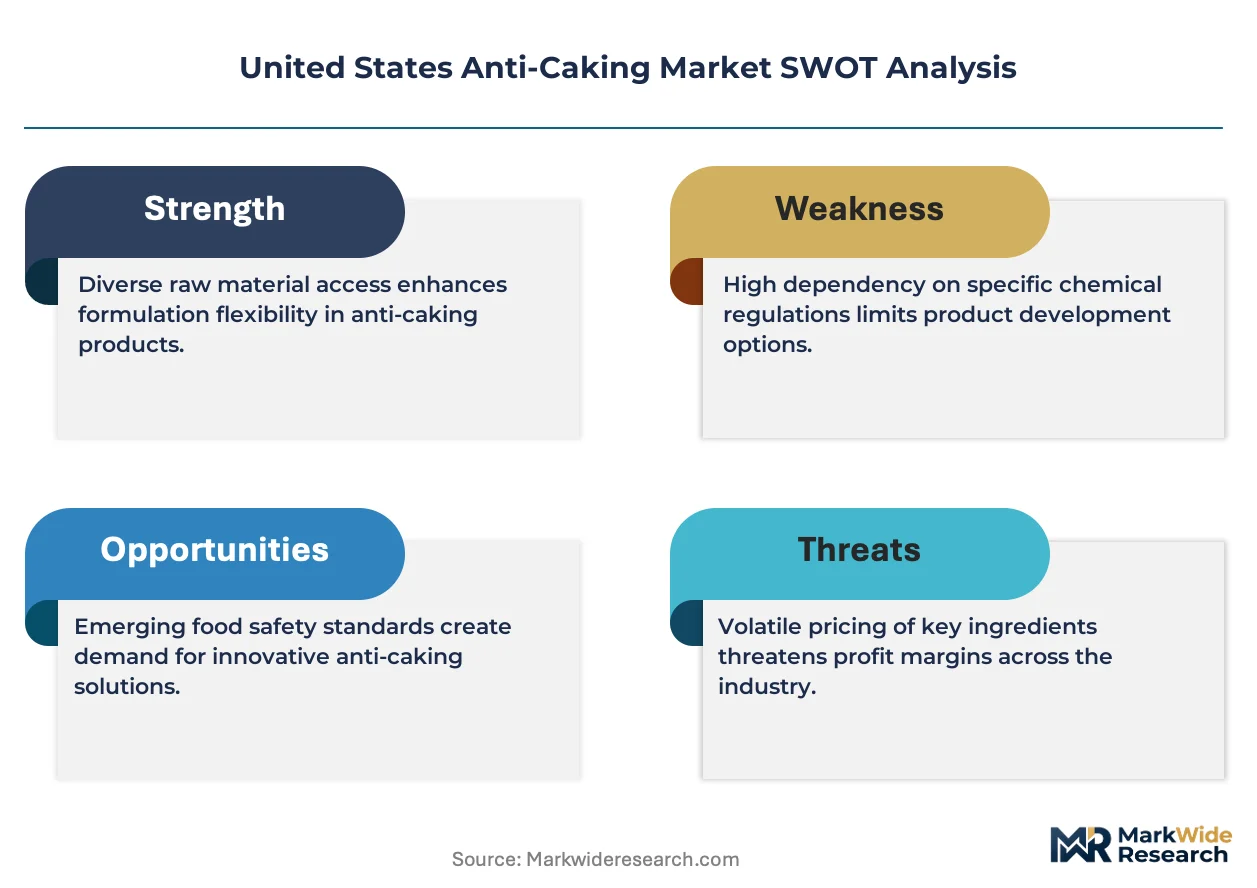
Clean-label formulation mandates from food manufacturers are compressing the addressable market for synthetic anti-caking agents while expanding specification premiums for mineral-derived alternatives that satisfy FDA GRAS self-affirmation pathways.
Growth Catalysts
- FSMA-mandated supplier qualification:Food Safety Modernization Act requirements force manufacturers toward pre-certified anti-caking additive sources, consolidating procurement around compliant producers with validated hazard controls.
- Midwest agricultural processing concentration:Iowa-Illinois-Nebraska grain and fertilizer corridors generate sustained bulk demand for technical-grade silicates and carbonates in salt conditioning and blend flowability.
- Pharmaceutical powder proliferation:Nutraceutical tablet and capsule formulations require pharmaceutical-grade silicon dioxide with lot-traceability documentation, creating margin-rich specification tiers.
Market Restraints
- Silica feedstock cost volatility:Precipitated and fumed silica production depends on sodium silicate and energy inputs subject to natural gas price swings in Gulf Coast manufacturing clusters.
- EPA air-quality enforcement intensification:Stricter particulate emission standards for crystalline silica in production-heavy states raise compliance capital requirements and operational scrutiny.
- Organic salt substitution threat:Unprocessed sea salt and mineral salt products marketed without anti-caking additives capture shelf-space in premium retail channels.
Strategic Opportunities
- Southeast food manufacturing expansion:Georgia and North Carolina poultry and snack processing growth creates demand for clean-label flow agents with regional supply proximity.
- USDA Organic certification pathway:Approved mineral-derived anti-caking agents qualify for organic food contact, opening premium pricing in certified product lines.
- Direct-to-blender distribution models:Bypassing traditional chemical distributor networks, producers establish captive supply relationships with large fertilizer and salt compounders.
Industry Challenges
- Analytical chemist scarcity:FDA lot-release testing and purity verification require specialized personnel in short supply across Midwest and Southeast production zones.
- GRAS notification timeline compression:Novel anti-caking substance approvals face extended FDA review cycles, delaying market entry for reformulated mineral variants.
- Legacy batch record system integration:Electronic batch documentation upgrades for FSMA compliance strain capital budgets at mid-tier technical-grade producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Anti-Caking Market |
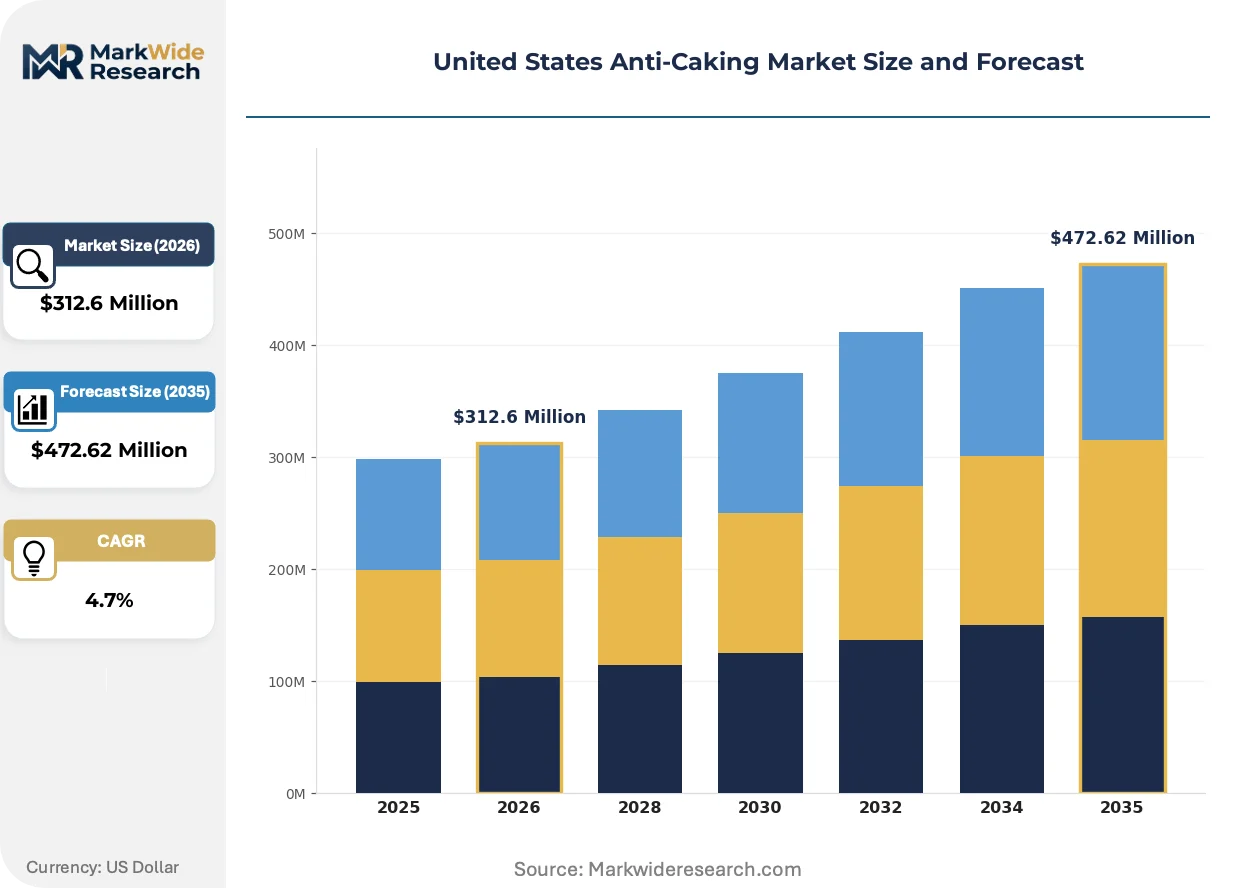
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $472.62 Million |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Silicate, Calcium Carbonate, Magnesium Carbonate, Talc Application: Food Industry, Pharmaceutical Industry, Agriculture, Chemicals End User: Food Manufacturers, Cosmetic Companies, Agricultural Suppliers, Industrial Manufacturers Grade: Food Grade, Technical Grade, Pharmaceutical Grade, Industrial Grade |
| Companies Covered | Cargill, Incorporated, Tate & Lyle, The Archer Daniels Midland Company, Agropur Ingredients, DuPont de Nemours, Inc., Evonik Industries AG, Cabot Corporation, Solvay S.A., PPG Industries, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Anti-Caking Market Evolving Landscape
Anti-caking agent development is pivoting from commodity volume toward performance-differentiated specifications, with particle engineering and surface modification technologies enabling targeted moisture management in hygroscopic formulations.
Nano-structured precipitated silica variants with controlled pore distribution are miniaturizing particle architectures to sub-micron scales. Pharmaceutical manufacturers adopt these grades for high-humidity tablet formulations where standard silicon dioxide fails. This particle engineering is miniaturizing the functional dosage required per unit mass, compressing additive volumes while maintaining flow performance.
FDA's updated Food Safety Modernization Act supplier verification rules now mandate documented hazard analysis for all anti-caking inputs. Food manufacturers must maintain approved supplier lists with validated foreign supplier compliance programs. Salt and sugar processors in the Midwest and Southeast are consolidating procurement around domestic producers with established FSMA preventive controls.
Compounders are unbundling anti-caking specification from bulk chemical procurement, establishing dedicated technical service relationships for formulation troubleshooting. Large agricultural blenders now contract directly with silica producers for custom particle size distributions. This specification-driven purchasing is most visible in Nebraska and Iowa fertilizer operations where flowability failures carry field-application penalties.
United States Anti-Caking Market Segmentation
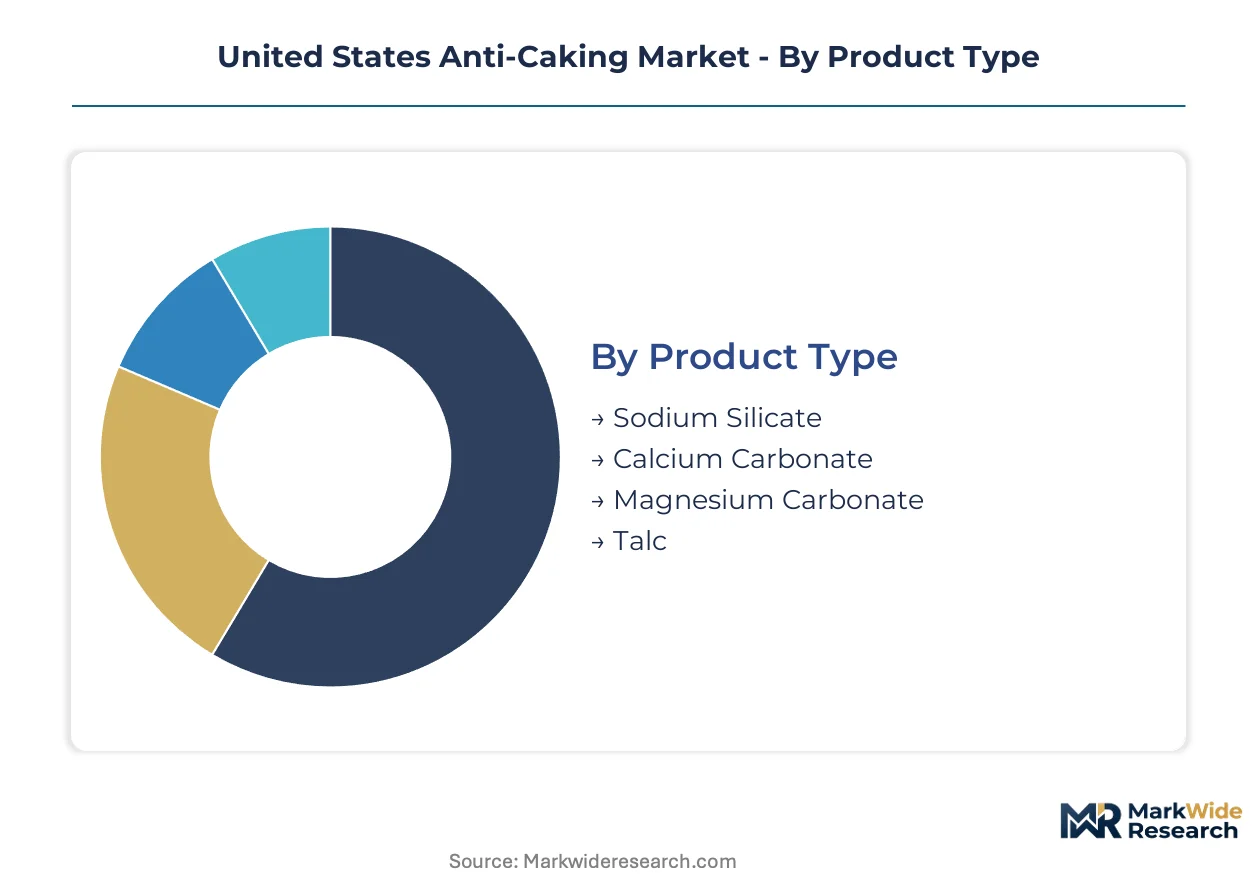
Anti-caking agent procurement patterns diverge sharply across specification tiers and end-use requirements. Food-grade and pharmaceutical-grade segments command premium positioning through FDA certification barriers, while technical-grade volumes concentrate in bulk agricultural applications where cost efficiency dominates supplier selection.
Product Type:
Sodium silicate and calcium carbonate face the strongest substitution pressure from mineral-derived alternatives in clean-label food formulations, while magnesium carbonate and talc retain defensive positions in moisture-sensitive pharmaceutical and cosmetic applications.
- Sodium Silicate:Alkaline silicate compound manufactured from sand and soda ash, forming glassy coatings that physically separate hygroscopic particles. Iowa-Illinois-Nebraska fertilizer blenders and salt compounders drive bulk procurement volumes, though EPA crystalline silica emission scrutiny elevates production compliance costs.
- Calcium Carbonate:Naturally occurring mineral carbonate with moderate moisture absorption capacity and neutral pH profile. Midwest agricultural processing corridors sustain technical-grade demand, yet organic salt substitution trends in premium retail channels erode growth potential in food-contact applications.
- Magnesium Carbonate:Lightweight basic carbonate with superior hygroscopic binding affinity for high-moisture pharmaceutical powders. Nutraceutical tablet manufacturers in Georgia and North Carolina specify pharmaceutical-grade variants for humidity-stable formulations.
- Talc:Hydrated magnesium silicate with lamellar particle structure providing physical barrier separation. Cosmetic powder compounders and select food applications utilize purified grades meeting USP purity specifications.
Sodium silicate anchors the volume base while magnesium carbonate gains share at the steepest rate.
Application:
Application demand concentrates in food and agricultural channels where flowability failures carry immediate operational penalties, with pharmaceutical applications generating the highest margin concentration per kilogram.
- Food Industry:Salt, sugar, baking powder, and powdered beverage formulations requiring FDA GRAS-certified flow agents. FSMA-mandated supplier qualification pushes processors toward domestic producers with validated preventive controls.
- Pharmaceutical Industry:Tablet disintegration aids, capsule lubricants, and powder flow enhancers demanding USP-grade silicon dioxide with lot-traceability documentation. Moisture-sensitive formulations in high-humidity climates drive specification premiums.
- Agriculture:Fertilizer blend conditioning and animal feed premix flowability. Nebraska and Iowa compounders contract directly with silica producers for custom particle size distributions bypassing distributor markups.
- Chemicals:Industrial salt conditioning and detergent powder free-flow maintenance. Technical-grade sodium silicate and carbonates dominate procurement where purity certifications remain secondary to unit cost.
Agriculture anchors the volume base while pharmaceutical applications climb the fastest on value terms.
End User:
End-user procurement sophistication varies dramatically, with food manufacturers maintaining the most stringent supplier qualification protocols while agricultural suppliers prioritize volume pricing and logistics reliability.
- Food Manufacturers:Salt processors, sugar refiners, and baking ingredient compounders requiring GRAS self-affirmation documentation and FSMA-compliant hazard analysis records. Clean-label mandates compress synthetic additive demand.
- Cosmetic Companies:Powder foundation, blush, and talcum product manufacturers specifying purified mineral grades with heavy metal testing certification. Southeast manufacturing expansion elevates regional supply requirements.
- Agricultural Suppliers:Fertilizer blenders and feed premix compounders in Midwest corridors sourcing technical-grade silicates and carbonates in bulk railcar quantities.
- Industrial Manufacturers:Detergent producers, chemical processors, and non-food salt compounders accepting industrial-grade specifications with relaxed purity tolerances.
Agricultural suppliers anchor the volume base while food manufacturers gain specification influence fastest.
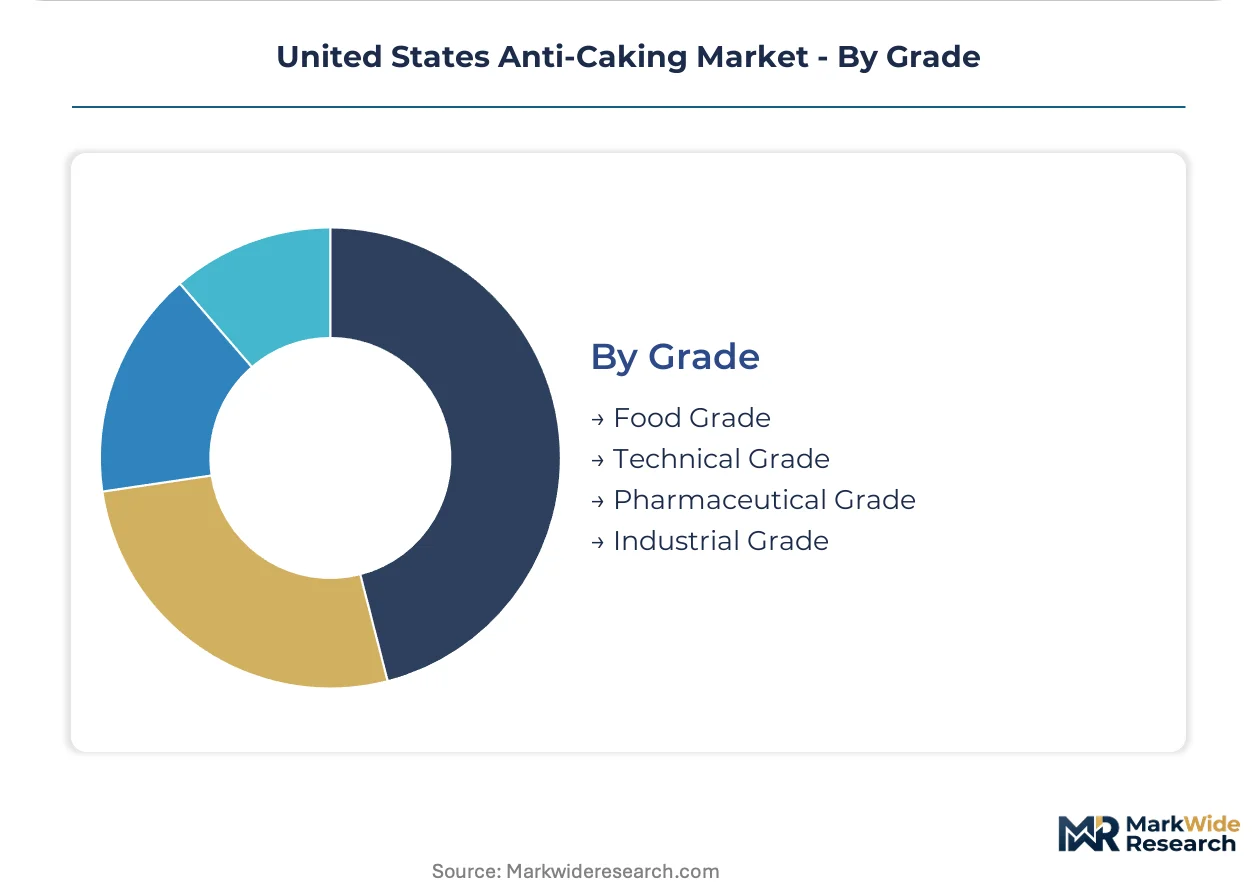
Grade:
Grade stratification reflects regulatory burden differentiation, with pharmaceutical and food grades carrying certification costs that technical and industrial grades avoid entirely.
- Food Grade:FDA GRAS-listed additives with purity specifications for direct food contact. Lot-release testing and foreign supplier verification programs elevate procurement complexity.
- Technical Grade:Moderate purity silicates and carbonates for agricultural and non-food industrial applications. Cost efficiency outweighs certification requirements.
- Pharmaceutical Grade:USP-compliant silicon dioxide and mineral carbonates with documented particle size distribution and microbial testing. Analytical chemist scarcity constrains production expansion.
- Industrial Grade:Unpurified or minimally processed variants for chemical manufacturing and non-contact applications. Price sensitivity drives commodity procurement behavior.
Technical grade anchors the volume base while pharmaceutical grade expands most quickly on margin contribution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food manufacturers and agricultural compounders dominate procurement, with Midwest fertilizer blenders and Southeast snack processors driving specification divergence across state-level regulatory enforcement zones.
Midwest Agricultural Processing Corridor
Iowa-Illinois-Nebraska fertilizer blenders and salt compounders generate sustained bulk demand for technical-grade sodium silicate and calcium carbonate. EPA crystalline silica emission standards intensify compliance scrutiny at production facilities across this corridor. Omaha and Des Moines anchor direct-to-blender distribution relationships that bypass traditional chemical distributor markups.
Southeast Food Manufacturing Belt
Georgia and North Carolina poultry processors and snack manufacturers require clean-label flow agents with regional supply proximity. FSMA-mandated supplier qualification pushes processors toward domestic producers with validated preventive controls. Atlanta and Charlotte concentrate procurement consolidation as food safety documentation requirements tighten.
Gulf Coast Chemical Production Hub
Louisiana and Texas host precipitated silica manufacturing clusters dependent on natural gas feedstock pricing. EPA air-quality enforcement for particulate emissions elevates capital requirements at production facilities. Houston and Lake Charles sustain technical-grade output for industrial salt conditioning despite feedstock cost volatility.
California Nutraceutical Manufacturing
Southern California tablet and capsule formulators demand pharmaceutical-grade silicon dioxide with lot-traceability documentation. FDA purity certifications and analytical testing requirements constrain supplier qualification timelines. Los Angeles and San Diego concentrate moisture-sensitive formulation expertise for high-humidity climate applications.
United States Anti-Caking Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with agricultural processing backbones. Market structure concentrates around producers with validated FSMA preventive controls and GRAS self-affirmation capabilities. Three archetypes dominate: grain-processing integrated suppliers, specialty silica technology developers, and industrial chemical scale producers. Competitive moves center on direct-to-blender distribution bypasses and pharmaceutical-grade certification investments.
Among diversified agribusiness conglomerates, Cargill, Incorporated and The Archer Daniels Midland Company occupy positions leveraging grain-processing infrastructure for multi-tier supply. Evonik Industries AG represents the specialty silica technology archetype with precipitated and fumed production expertise. Cabot Corporation anchors the industrial chemical scale segment through manufacturing breadth serving salt and fertilizer blenders.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Tate & Lyle |
| The Archer Daniels Midland Company |
| Agropur Ingredients |
| DuPont de Nemours, Inc. |
| Evonik Industries AG |
| Cabot Corporation |
| Solvay S.A. |
| PPG Industries, Inc. |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day lot-release testing cycles for pharmaceutical-grade silicon dioxide concentrate supply power among FDA-validated domestic producers while compressing procurement flexibility for Midwest fertilizer blenders. This lead-time architecture rewards producers with captive analytical capabilities and GRAS-affirmed mineral portfolios, while penalizing technical-grade suppliers lacking electronic batch documentation systems.
Pricing Analysis
Commodity-grade sodium silicate and calcium carbonate trade on spot-indexed contracts, while pharmaceutical-grade silicon dioxide and magnesium carbonate command three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on FDA purity certification tier and lot-traceability documentation depth, with FSMA-compliant suppliers capturing margin premiums. Cost compression in technical-grade tiers intensifies because organic salt substitution erodes addressable volume. Agricultural suppliers in Iowa-Nebraska corridors exhibit highest price sensitivity; California nutraceutical formulators show least.
Supply Chain Analysis
Gulf Coast natural gas feedstock availability functions as the primary chokepoint for precipitated silica manufacturing, with Louisiana and Texas production clusters tethered to Henry Hub pricing volatility. Geographic supply concentration centers on domestic sodium silicate production, Chinese precipitated silica imports, and German specialty silica technology. Raw material dependencies include soda ash, sand, and natural gas. Single-source vulnerability runs through Gulf Coast energy infrastructure. Distribution runs through direct-to-blender contracts bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Anti-Caking Market operates as a regulatory-moat defensive structure where FSMA-mandated supplier qualification creates switching costs that entrench validated incumbents. This entrenchment intensifies as food manufacturers consolidate procurement around domestic producers with electronic batch documentation and preventive control protocols.
For Market Incumbents: Shield market position by deepening captive analytical testing capabilities to offset chemist scarcity constraints in Midwest production zones. Extend backward integration into mineral feedstock sourcing to neutralize silica cost volatility from Gulf Coast energy markets. Prioritize pharmaceutical-grade certification investments in Georgia and North Carolina to capture nutraceutical powder proliferation.
For New Entrants and Emerging Players: Lead with USDA Organic certification pathways for mineral-derived anti-caking agents targeting Southeast poultry and snack processors. Target direct-to-blender distribution relationships with Nebraska-Iowa fertilizer compounders seeking custom particle size distributions. Penetrate through technical service bundling that unbundles specification from commodity procurement.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized anti-caking divisions lacking FSMA preventive control infrastructure. Long-term viability favors producers with validated GRAS portfolios and regional supply proximity to Midwest agricultural corridors. Monitor EPA crystalline silica enforcement intensity as inflection signal for compliance capital requirements.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Feedstock | Captive soda ash and sand sourcing neutralizes Gulf Coast energy price transmission. |
| Pharmaceutical-Grade Certification Investment | USP-compliant silicon dioxide production captures Georgia-North Carolina nutraceutical expansion. |
| Direct-to-Blender Distribution Model | Bypassing chemical distributors secures Nebraska-Iowa fertilizer compounder relationships. |
| FSMA Preventive Controls Implementation | FDA-validated hazard analysis qualifies suppliers for consolidated food manufacturer procurement. |
| USDA Organic Certification Pathway | Approved mineral-derived additives access premium pricing in certified product lines. |
Research Methodology
A spread of perspectives from plant managers at silica production facilities, procurement leads at Midwest fertilizer compounders, technical R&D directors at specialty chemical firms, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from FDA GRAS notices, EPA air-quality enforcement records, USDA organic certification databases, and SEC filings of diversified chemical conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across grade tier, end-use industry, and regional production hub dimensions.
Segmentation dimensions modeled include product type, application channel, end-user sophistication, and grade certification tier across the analysis window. CAGRs derived from regression analysis of historical volume trajectories adjusted for regulatory enforcement intensity and feedstock cost volatility. Industry-specific forecast inputs incorporated FSMA compliance penetration rates and organic salt substitution trends in premium retail channels.
Forecasts assume regulatory continuity in FDA FSMA implementation and EPA crystalline silica standards; material policy shifts would require re-modeling supplier qualification timelines and production facility capital requirements. Practitioners should keep alternative scenarios live as EPA enforcement intensity and natural gas feedstock pricing evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
North America Clean Label Ingredient Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Lecithin Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
Monosodium Glutamate Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
Bread Preservatives Market
Food Additives and Ingredients
Tara Gum Market
Food Additives and Ingredients
Global Integrated Food Ingredient Market
Food Additives and Ingredients
Agar Agar Gum Market