
 Microencapsulated Food Ingredient Market | 2026-2036
Microencapsulated Food Ingredient Market Size, Share, and Industry Trends Forecast 2026-2036
Microencapsulated Food Ingredient Market Outlook
REACH compliance is pivoting the cost-of-entry calculus for European suppliers of shell-material chemistries. BASF SE leverages its polymer science heritage to sustain integrated supply from raw alginates to finished beadlets. Kerry Group plc anchors beverage application development through dedicated encapsulation facilities in Ireland and Wisconsin. DSM-Firmenich AG differentiates via fermentation-derived coating technologies that compete on thermal stability benchmarks.
Microencapsulated food ingredients are active compounds enclosed within protective matrices of lipids, proteins, or carbohydrates, typically ranging from 1 to 1000 micrometers in diameter, designed to mask off-flavors, extend shelf life, or enable controlled release in specific pH environments. Spray drying dominates volume production for flavors and vitamins due to capital efficiency and scale, while liposome encapsulation commands premium positioning in dairy alternatives where bioavailability claims justify higher unit economics. Coacervation remains specialized for high-value enzymes in sauces where heat-triggered release determines functional performance.
The FDA governs novel encapsulant safety through GRAS self-affirmation and food additive petitions, while EFSA reviews health claim substantiation for encapsulated bioactives marketed in Europe. BIS certification requirements in India constrain import flows of unvalidated shell materials, redirecting regional procurement toward domestic gelatin and gum arabic suppliers. Stakeholders must monitor divergence between FDA process-analytical-technology guidance and EFSA's evolving nano-definition thresholds, as jurisdictional asymmetry in particle-size classification threatens cross-border formulation strategies.
Market Dynamics
Sports nutrition brands are compressing formulation cycles to deliver stable probiotics and omega-3 in ready-to-drink formats, forcing encapsulation suppliers to validate thermal release profiles against accelerated shelf-life protocols.
Growth Catalysts
- Clean-label bakery demand in Germany:German consumers absorb significant volumes of encapsulated vitamins and enzymes as reformulated breads and pastries eliminate artificial preservatives.
- FDA GRAS pathway evolution:The agency's expanding notification framework for novel shell materials accelerates commercialization timelines for fermentation-derived coatings.
- Spray drying scale economics:Capital-efficient production platforms enable flavor and vitamin suppliers to serve commodity beverage markets without unit-cost penalties.
Market Restraints
- Alginate supply concentration:Seaweed harvesting constraints in specific coastal regions create input volatility for marine-derived shell materials.
- REACH compliance cost escalation:ECHA registration requirements for novel polymer chemistries pivot European supplier economics toward larger integrated players.
- Conventional emulsion limits:Standard lipid encapsulation struggles to protect heat-sensitive bioactives above 80°C processing temperatures.
Strategic Opportunities
- India BIS certification gap:Domestic gelatin and gum arabic suppliers capture redirected import flows as unvalidated shell materials face entry barriers.
- Dairy alternative bioavailability claims:Liposome encapsulation commands premium positioning in oat and almond milk formulations where absorption benchmarks justify higher unit economics.
- Coacervation-enzyme convergence:Heat-triggered release systems enable functional performance in high-value sauce applications where thermal activation determines end-product quality.
Industry Challenges
- Particle-size classification asymmetry:Divergent FDA process-analytical-technology guidance and EFSA nano-definition thresholds threaten cross-border formulation strategies.
- Encapsulation technologist scarcity:Specialized expertise in controlled-release engineering and shell-matrix optimization outpaces academic program output.
- Legacy equipment retrofit costs:Fluidized bed and spray drying installations require significant capital to accommodate novel coating chemistries and in-line monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microencapsulated Food Ingredient Market |
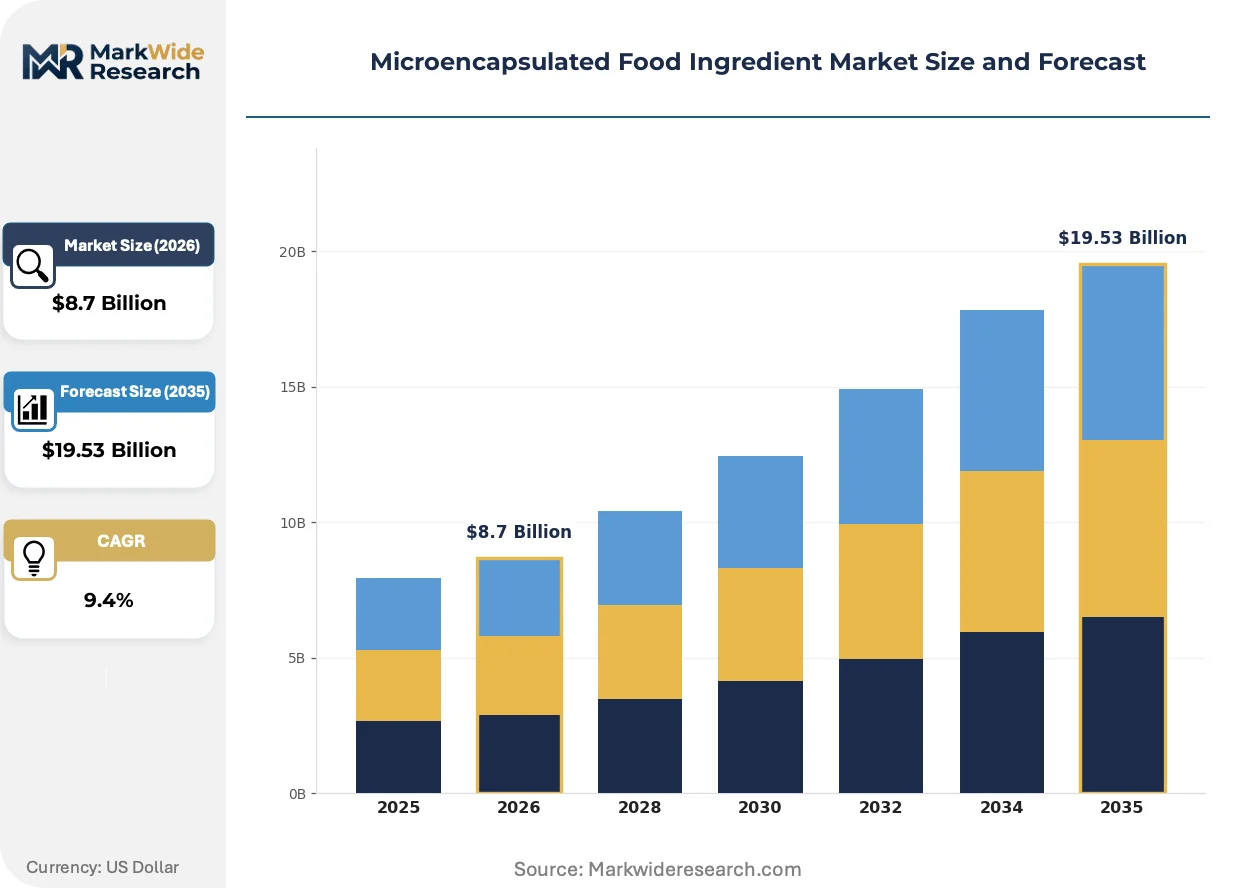
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flavors, Vitamins, Enzymes, Preservatives Encapsulation Technology: Spray Drying, Coacervation, Liposome, Extrusion Application: Beverages, Bakery Products, Dairy Alternatives, Sauces Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales |
| Companies Covered | BASF SE, DSM-Firmenich AG, Cargill, Incorporated, Ingredion Incorporated, International Flavors & Fragrances Inc., Givaudan SA, Kerry Group plc, Balchem Corporation, Symrise AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microencapsulated Food Ingredient Market Strategic Shifts
Encapsulation architecture is fragmenting into application-specific platforms as end-users reject one-size-fits-all delivery systems. Suppliers now compete on release-kinetics precision rather than shell-material novelty alone.
Electrohydrodynamic spraying is modularizing micron-scale particle production for heat-sensitive bioactives. Nutraceutical contract manufacturers in Switzerland and the Netherlands adopt these platforms to serve pharmaceutical-grade probiotic specifications. The technology is compressing minimum viable batch sizes from metric tons to kilogram scales, enabling personalized nutrition formulations.
EFSA's evolving nano-definition thresholds are forcing reformulation of sub-1000 nanometer lipid carriers marketed in Europe. Encapsulation houses must now document dissolution behavior and cellular uptake kinetics beyond traditional safety dossiers. Dairy alternative brands face the steepest compliance burden as their bioavailability claims rely on particle-size-dependent absorption mechanisms.
Ingredient buyers are consolidating supplier relationships around vertically integrated partners who control shell-material supply from raw biomass through finished beadlet. Procurement teams at North American beverage multinationals now require captive alginate or protein supply as a qualification criterion. This concentration is visible in Wisconsin and Ireland where dedicated encapsulation facilities anchor regional procurement gravity.
Microencapsulated Food Ingredient Market Segmentation
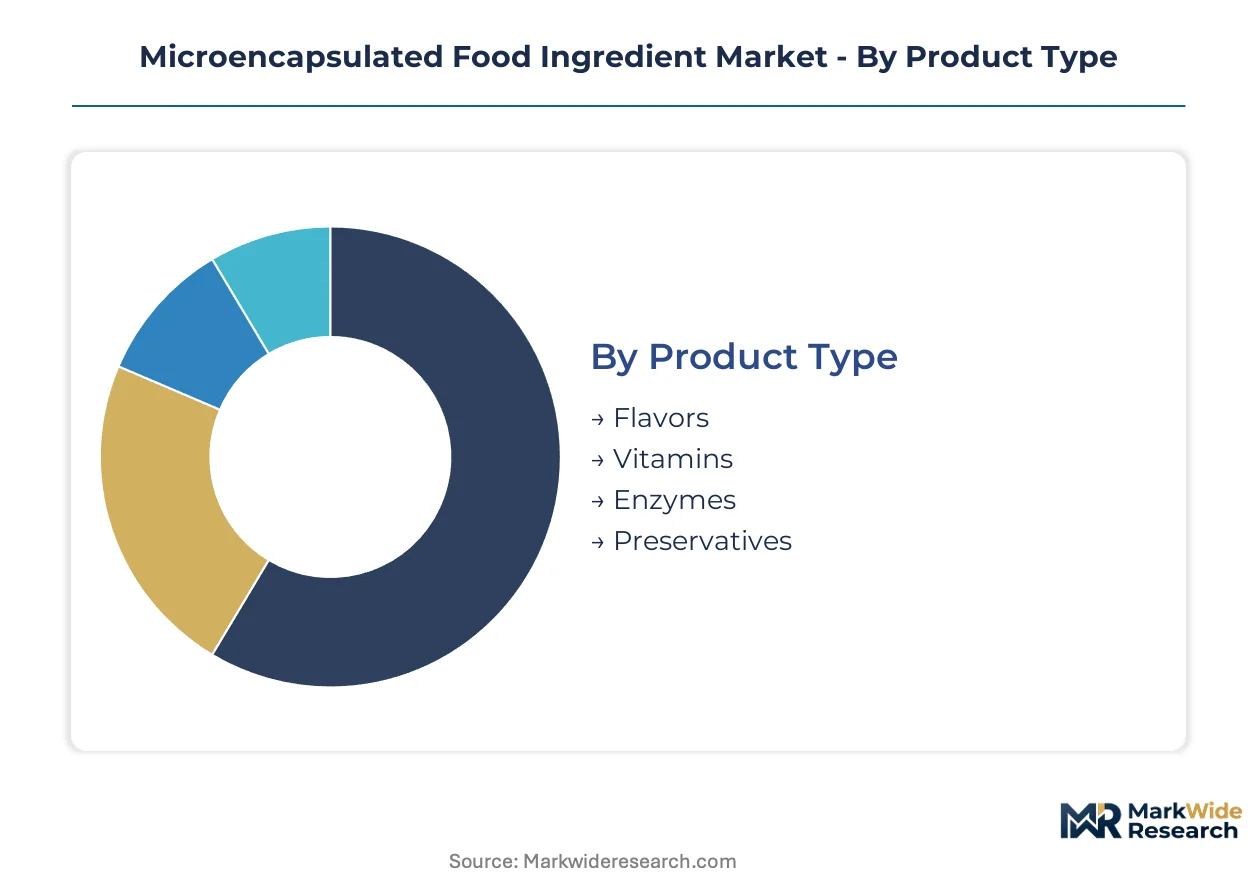
Microencapsulated food ingredients fragment into distinct commercial tiers based on payload sensitivity, release-kinetics requirements, and end-use processing conditions. Segmentation discipline separates commodity volume plays from premium positioning opportunities.
Product Type:
Reformulation cycles in clean-label applications drive upgrade demand across payload categories as brands replace synthetic additives with protected natural actives.
- Flavors:Volatile aromatic compounds immobilized in carbohydrate or lipid matrices prevent oxidation and evaporative losses during thermal processing. Beverage manufacturers in Germany absorb significant volumes for shelf-stable ready-to-drink formats.
- Vitamins:Heat-sensitive micronutrients including ascorbic acid and B-complexes require protein or modified starch shells to survive pasteurization and baking temperatures. Clean-label bakery reformulations in Western Europe concentrate demand for stabilized vitamin beadlets.
- Enzymes:Proteases and amylases encapsulated via coacervation enable heat-triggered release in high-temperature sauce applications.
- Preservatives:Natural antimicrobial actives including nisin and rosemary extract require barrier protection against premature depletion.
Volume placements concentrate in Flavors; the faster expansion belongs to Vitamins.
Encapsulation Technology:
Technology selection pivots on capital intensity versus performance specifications, with cost tiers separating commodity platforms from precision-engineered systems.
- Spray Drying:Atomization of active-laden emulsions into hot air streams yields 10-100 micrometer particles with capital-efficient throughput. Flavor and vitamin suppliers leverage this platform for commodity beverage markets without unit-cost penalties.
- Coacervation:Phase separation of hydrocolloid complexes around oil droplets creates 20-500 micrometer beads with tunable release triggers. High-value enzyme applications in sauces command premium positioning where thermal activation determines functional performance.
- Liposome:Phospholipid bilayer vesicles 50-1000 nanometers in diameter protect bioactives in dairy alternatives where bioavailability claims justify higher unit economics.
- Extrusion:Melt-based matrix embedding of actives within carbohydrate or lipid carriers suits heat-stable payloads in confectionery and cereal applications.
Capital deployment concentrates in Spray Drying; the steepest expansion trajectory belongs to Liposome platforms serving nutraceutical specifications.
Application:
End-use processing severity dictates shell-material selection, with thermal stress thresholds separating application tiers.
- Beverages:Acid-stable encapsulation protects probiotics and vitamins through low-pH shelf environments. Sports nutrition brands compress formulation cycles to deliver stable actives in ready-to-drink formats.
- Bakery Products:Yeast-raised and chemically leavened systems demand thermal protection above 180°C for enzymes and vitamins. German clean-label reformulations absorb significant encapsulated volumes.
- Dairy Alternatives:Oat and almond milk formulations leverage liposome encapsulation to substantiate bioavailability claims against dairy nutritional benchmarks.
- Sauces:Heat-triggered release systems enable functional enzyme performance in retort and aseptic processing conditions.
Procurement gravity centers on Beverages; Dairy Alternatives gain share fastest on plant-based positioning.
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with direct relationships dominating formulation-intensive segments.
- Online Retail:E-commerce platforms serve small-scale nutraceutical formulators and regional ingredient traders with standardized beadlet specifications.
- Supermarkets:Mass-market retail channels move commodity encapsulated flavors and colors for home baking and beverage preparation.
- Specialty Stores:Technical ingredient distributors cater to artisanal producers and clean-label startups requiring application guidance.
- Direct Sales:Multinational beverage and bakery manufacturers negotiate captive supply agreements with integrated encapsulation houses.
Relationship value concentrates in Direct Sales; Specialty Stores expand most quickly on startup ecosystem growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German clean-label bakery reformulations concentrate significant encapsulated vitamin and enzyme demand, while sports nutrition brands in the United States and India compress formulation cycles for stable probiotic delivery.
United States
Sports nutrition manufacturers in Wisconsin and California absorb substantial encapsulated omega-3 and probiotic volumes for ready-to-drink applications. FDA GRAS notification pathways for novel fermentation-derived shell materials accelerate commercialization timelines for domestic suppliers. Chicago anchors procurement gravity for beverage multinationals requiring captive alginate supply agreements.
Germany
Clean-label bakery reformulations eliminate artificial preservatives across Bavaria and North Rhine-Westphalia, driving encapsulated vitamin and enzyme uptake. ECHA REACH registration requirements for novel polymer chemistries pivot supplier economics toward integrated players with captive raw material supply. Hamburg concentrates technical service capabilities for beverage encapsulation development.
India
BIS certification constraints redirect regional procurement toward domestic gelatin and gum arabic suppliers in Maharashtra and Gujarat. FSSAI enforcement of shell material validation requirements blocks unvalidated import flows from European sources. Karnataka's nutraceutical contract manufacturers expand liposome production for pharmaceutical-grade probiotic specifications.
Switzerland
Swissmedic-aligned nutraceutical manufacturers in Basel and Zurich adopt electrohydrodynamic spraying platforms for personalized nutrition formulations. Swiss fermentation-derived coating technologies compete on thermal stability benchmarks against conventional lipid systems. Geneva anchors precision encapsulation R&D serving pharmaceutical-grade specifications.
Netherlands
Dairy alternative brands in Randstad leverage liposome encapsulation to substantiate bioavailability claims against dairy nutritional benchmarks. EFSA nano-definition thresholds force reformulation of sub-1000 nanometer lipid carriers for oat and almond milk applications. Eindhoven's food technology cluster hosts modular electrohydrodynamic spraying installations for heat-sensitive bioactives.
Microencapsulated Food Ingredient Market Competitive Environment
German chemical conglomerates anchor one tier; Irish and Dutch specialists hold formulation-intensive positions. The vendor base separates into integrated polymer-science players, fermentation-technology houses, and application-focused contract manufacturers. Three strategic archetypes dominate: backward-integrated shell-material suppliers, precision-release engineering specialists, and beverage-dedicated encapsulation facilities. Competitive moves concentrate on captive raw material supply agreements and modular production platform licensing.
Within the integrated chemical tier, BASF SE represents backward control from raw alginates through finished beadlets. DSM-Firmenich AG exemplifies fermentation-derived coating differentiation competing on thermal stability benchmarks. Kerry Group plc anchors beverage application development through dedicated encapsulation facilities in Ireland and Wisconsin. These three occupy positions spanning polymer science, biotechnology, and application engineering archetypes.
| Leading Market Players |
|---|
| BASF SE |
| DSM-Firmenich AG |
| Cargill, Incorporated |
| Ingredion Incorporated |
| International Flavors & Fragrances Inc. |
| Givaudan SA |
| Kerry Group plc |
| Balchem Corporation |
| Symrise AG |
| Others |
Value Chain & Pricing Dynamics
Sports nutrition procurement teams demanding captive alginate supply agreements are forcing encapsulation houses to secure upstream seaweed harvesting contracts, compressing margin structures for non-integrated suppliers while rewarding backward-integrated players with pricing power in thermal-stable probiotic formulations.
Pricing Analysis
Volume placements in spray-dried flavors and vitamins run on commodity unit economics with thin margins, while liposome platforms for dairy alternatives capture premium positioning through bioavailability substantiation. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels separates contract manufacturers from commodity suppliers. Pricing pressure stems from REACH registration cost escalation for novel polymer chemistries, which advantages integrated chemical conglomerates with existing ECHA dossiers. Beverage multinationals exhibit lowest price sensitivity due to captive supply requirements, while regional bakery reformulators face acute cost compression.
Supply Chain Analysis
Marine alginate supply rests on coastal harvesting operations in Norway, France, and Chile, with seasonal variability constraining input planning for hydrocolloid shell materials. Phospholipid feedstock for liposome production draws from soybean and sunflower processing in the Netherlands and Ukraine, while fermentation-derived coating technologies hinge on dextrose supply from corn wet-milling in the United States. Single-source vulnerability in pharmaceutical-grade gelatin from specific European abattoirs creates qualification bottlenecks for probiotic encapsulation. Distribution runs through technical ingredient distributors for artisanal accounts and direct sales agreements for multinational beverage and bakery manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EFSA's evolving nano-definition thresholds and REACH registration requirements erect regulatory moats that favor incumbents with existing dossiers and dedicated regulatory affairs infrastructure.
For Market Incumbents: To counter emerging electrohydrodynamic spraying specialists in Switzerland and the Netherlands, BASF SE and DSM-Firmenich AG should deepen backward integration into fermentation-derived coating feedstocks and expand dedicated encapsulation capacity in Ireland and Wisconsin to anchor beverage procurement gravity. Certification investment in pharmaceutical-grade probiotic specifications represents the critical defensive lever against modular platform competitors. For New Entrants and Emerging Players: E-commerce platforms serving small-scale nutraceutical formulators offer the most penetrable route, with online retail channels for personalized nutrition formulations presenting white-space opportunity beyond integrated chemical conglomerates. Specialty stores catering to clean-label startups in Germany provide secondary entry angle through technical service differentiation. Target India BIS certification gaps by partnering with domestic gelatin suppliers in Maharashtra and Gujarat to bypass import barriers. For Investors and Strategic Acquirers: The window for entry favors fermentation-technology houses with thermal stability benchmarks and modular electrohydrodynamic spraying capabilities. Long-term viability centers on platforms serving pharmaceutical-grade probiotic specifications with documented release-kinetics precision. Watch EFSA nano-definition threshold finalization as the signal for compliance-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seaweed Harvesting | Norwegian and Chilean alginate supply agreements secure shell-material cost stability for integrated players. |
| Pharmaceutical-Grade Certification Investment | Swissmedic-aligned specifications in Basel unlock premium pricing in probiotic contract manufacturing. |
| Modular Electrohydrodynamic Platform Licensing | Eindhoven and Zurich installations enable kilogram-scale production for personalized nutrition formulations. |
| Captive Supply Agreement Expansion | Wisconsin and Ireland facilities anchor procurement gravity for North American beverage multinationals. |
| REACH Dossier Pre-Registration | ECHA compliance for novel polymer chemistries creates barrier-to-entry moats against non-integrated competitors. |
Study Parameters
Independent corroboration across encapsulation technology suppliers, sports nutrition formulators, and regulatory affairs consultants underwrites the qualitative findings in this study. Primary interviews with plant managers at spray drying facilities, procurement leads at German bakery reformulators, technical R&D directors at flavor houses, and regulatory specialists at EFSA-notified bodies combined with secondary validation from FDA GRAS notification databases, ECHA registration filings, FSSAI shell material guidelines, and customs trade data for alginate and phospholipid imports. Bottom-up capacity estimates and top-down demand modeling triangulate volume and value outputs.
Rate-of-change decomposition across payload sensitivity tiers, release-kinetics specifications, and end-use processing severity anchors the analytical framework over the projection horizon. Segmentation dimensions modeled include encapsulation technology capital intensity, application thermal stress thresholds, and regional regulatory cluster divergence between FDA process-analytical-technology guidance and EFSA nano-definition thresholds. CAGRs derive from installed capacity expansion schedules, reformulation cycle compression in sports nutrition, and clean-label bakery upgrade demand trajectories.
Inputs from ECHA registration databases and FSSAI enforcement records were available through the study window; gaps in proprietary release-kinetics benchmarking data from liposome manufacturers introduce uncertainty bands around dairy alternative bioavailability claim substantiation. Forecasts reflect assumptions on regulatory timeline adherence, seaweed harvesting yield stability, and fermentation-derived coating technology adoption curves. A small set of triggers—EFSA nano-definition finalization, India BIS certification enforcement intensity, and electrohydrodynamic spraying platform cost curves—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Polyglycerol Esters of Fatty Acids Market
Food Additives and Ingredients
Phytogenic Feed Additives Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
Food Emulsifiers Market
Food Additives and Ingredients
Food Texturing Agents Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
China Anti-Caking Market
Food Additives and Ingredients
Asia-Pacific Anti-Caking Market
Food Additives and Ingredients
Seitan Powder Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Asia- Pacific Food Micronized Salt Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Anti-Caking Market