
 South Africa Food Colorants Market | 2026-2036
South Africa Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Food Colorants Market Analytics
Synthetic azo dyes is decoupling from premium food applications as carmine and anthocyanin extracts capture margin-rich positions. Chr. Hansen Holding leverages its fermentation-derived pigment portfolio to dominate natural colorant supply to dairy processors. BASF SE anchors synthetic colorant availability through its established technical service network serving beverage formulators. Sensient Technologies specializes in custom color blends that help confectionery manufacturers navigate clean-label transitions.
Food colorants comprise chromophoric molecules—whether porphyrin-based, carotenoid, or azo compounds—that impart visual identity to edible products at concentrations typically measured in parts per million. These substances function primarily to correct color loss during processing, enhance naturally occurring hues, or provide visual differentiation that influences consumer purchase decisions at shelf. Natural colorants lead value generation as anthocyanin and curcumin extracts command price premiums over synthetic alternatives, while liquid formulations capture growing share from powders in automated dosing systems. Beverage applications exhibit the fastest structural expansion as carbonated and functional drink producers accelerate reformulation timelines.
South Africa's Department of Health enforces colorant safety through amendments to the Foodstuffs, Cosmetics and Disinfectants Act, while the National Regulator for Compulsory Specifications certifies product integrity under mandatory standards. BIS alignment pressures importers to demonstrate equivalence testing for synthetic dyes crossing from Asian supply corridors. Stakeholders must monitor pending regulatory consultations on maximum permissible limits for aluminum-containing lakes, as these specifications will determine reformulation costs and supplier qualification timelines across the value chain.
Market Dynamics
South Africa's Foodstuffs, Cosmetics and Disinfectants Act amendments are forcing beverage and dairy processors to accelerate reformulation timelines, compressing supplier qualification windows and redrawing procurement relationships across Gauteng's dense manufacturing corridor.
Growth Catalysts
- Clean-label mandates:South Africa's Department of Health updates to maximum permissible limits for synthetic additives drive reformulation toward plant-derived anthocyanin and curcumin extracts in premium beverage lines.
- Johannesburg processing cluster:Gauteng province concentrates national food manufacturing, creating localized demand density that rewards suppliers with technical service capabilities and rapid response logistics.
- Automated dosing systems:Liquid colorant formulations displace powder handling in high-volume carbonated drink production, reducing batch-to-batch variation and labor contamination risks.
Market Restraints
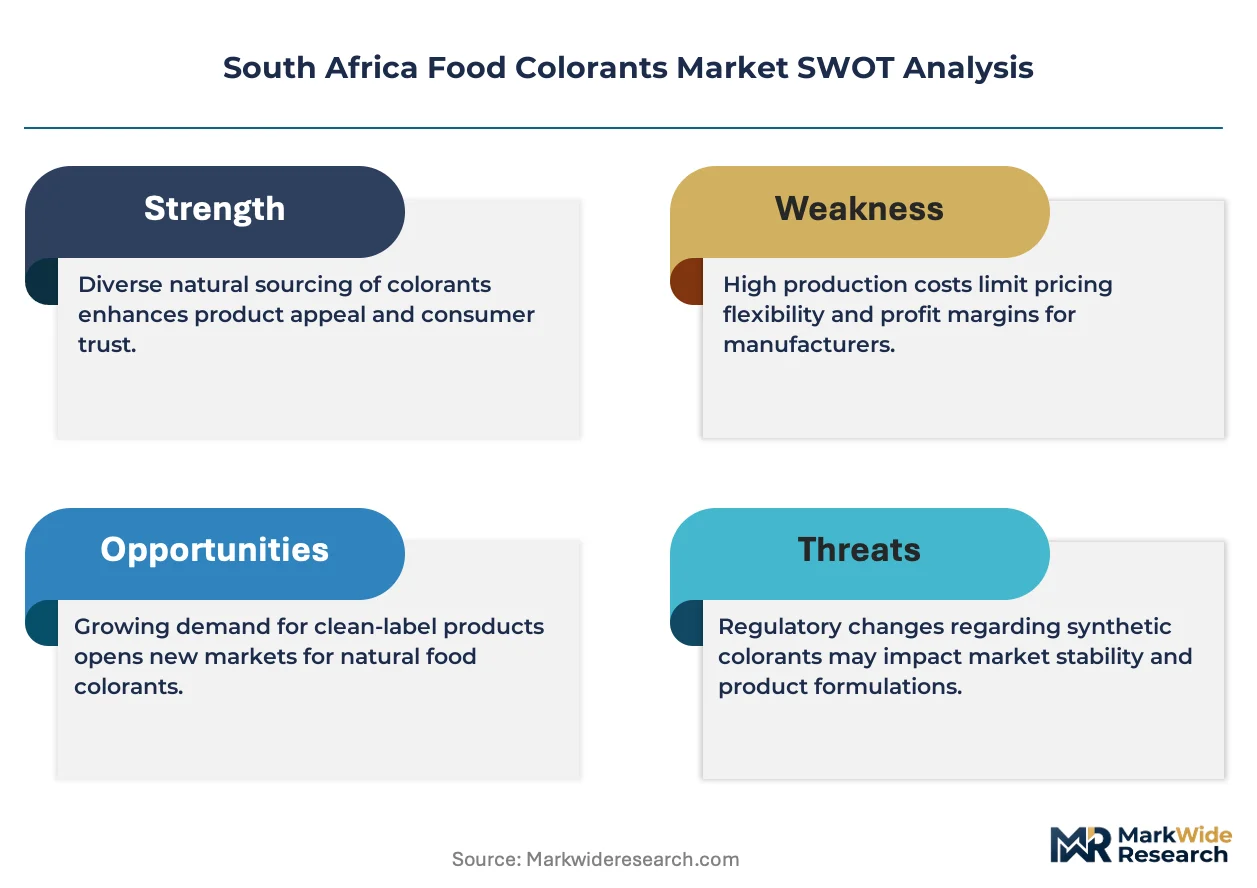
- Natural pigment cost premiums:Carmine and spirulina extracts command substantially higher input costs than synthetic azo alternatives, squeezing margin recovery in mid-tier confectionery and bakery segments.
- Import dependency for specialty extracts:Concentrated supply corridors from Asian fermentation-derived pigment producers expose South African formulators to currency volatility and extended lead times.
- Aluminum lake regulatory uncertainty:Pending consultations on maximum permissible limits for aluminum-containing colorant lakes create reformulation cost ambiguity and freeze long-term supply contracts.
Strategic Opportunities
- Western Cape wine and juice processing:Underpenetrated natural colorant adoption in grape-derived beverage applications offers expansion beyond Gauteng's saturated dairy and carbonated drink markets.
- KwaZulu-Natal confectionery corridor:Durban's sugar processing and candy manufacturing cluster presents white space for custom color blend technical services supporting clean-label transitions.
- BIS alignment certification:Bureau of Indian Standards equivalence recognition for imported synthetic dyes creates competitive differentiation for suppliers demonstrating third-party testing protocols.
Industry Challenges
- Specialized food chemist scarcity:Formulation expertise spanning both synthetic dye stability and natural pigment pH sensitivity remains concentrated among a narrow technical workforce, constraining R&D velocity.
- Dual certification timelines:Simultaneous compliance with South Africa's National Regulator for Compulsory Specifications and pending aluminum lake amendments extends product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Food Colorants Market |
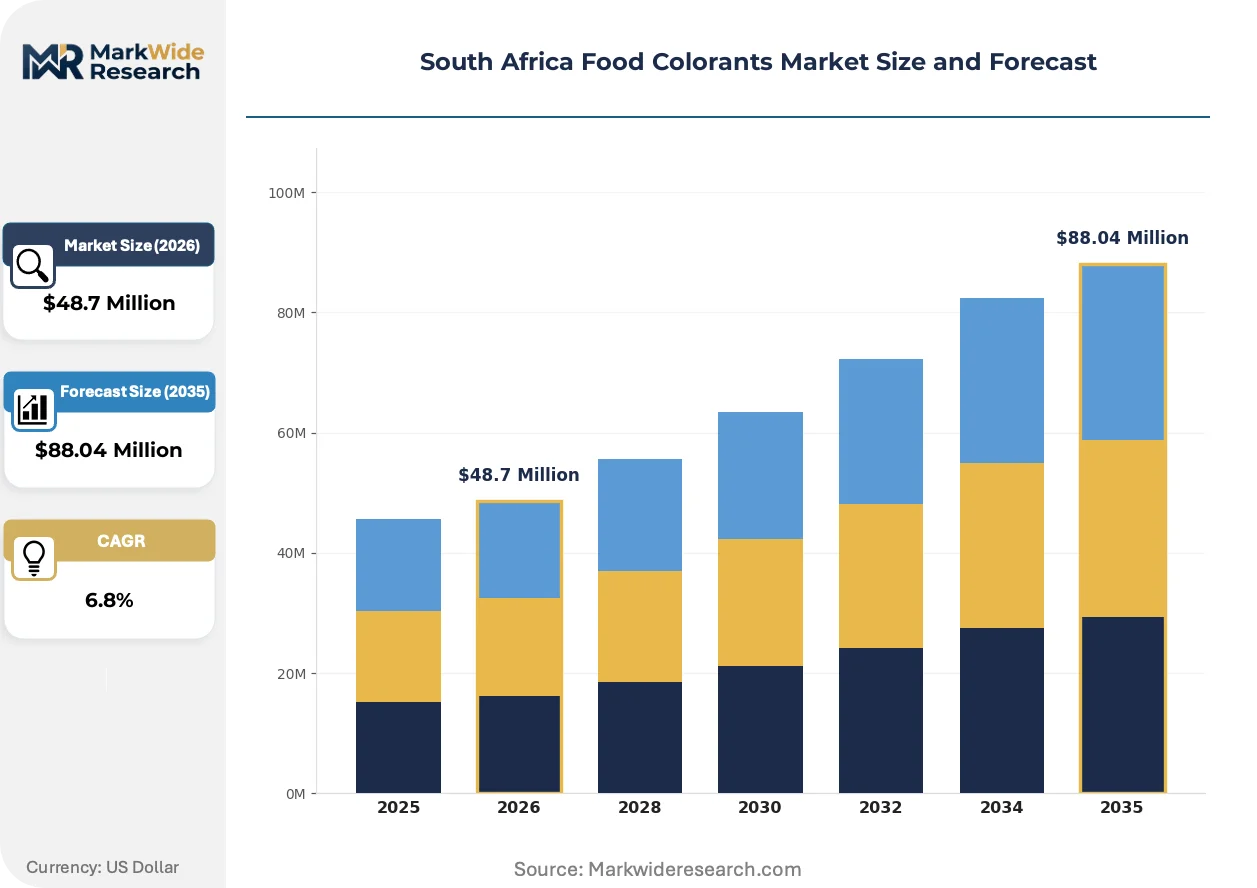
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Organic, Inorganic Application: Beverages, Confectionery, Bakery, Dairy Form: Liquid, Powder, Paste, Granular End User: Food Manufacturers, Catering Services, Retailers, Restaurants |
| Companies Covered | Sensient Technologies, BASF SE, Chr. Hansen Holding, Cargill Inc., Archer Daniels Midland, Givaudan SA, Chemical Services Ltd., Parshwanath Colour Chem, Quantum Colors SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Food Colorants Market Evolving Landscape
Reformulation chemistry is compressing development cycles as beverage processors pivot from synthetic azo dyes toward fermentation-derived and plant-extracted alternatives, while regulatory pressure on aluminum-containing additives accelerates specification changes across the value chain.
Microencapsulation technology for natural pigments is consolidating supplier capabilities around pH-stable anthocyanin delivery systems. Beverage formulators in Johannesburg's processing corridor are adopting these systems at compressed timelines to maintain color intensity across acidic carbonated matrices. The technology is consolidating competitive positioning around technical service depth rather than commodity pigment supply.
South Africa's Department of Health amendments to the Foodstuffs, Cosmetics and Disinfectants Act are tightening maximum permissible limits for synthetic additives. Industrial consequence includes mandatory reformulation documentation and accelerated supplier requalification for aluminum lake-containing products. Dairy processors face the most acute compliance pressure, driving partnerships with fermentation-derived pigment specialists.
Buyer concentration among Gauteng's beverage and dairy giants is compressing supplier negotiation cycles and unbundling after-sales technical support from base pigment contracts. Regional distributors are being displaced by direct procurement relationships with manufacturers possessing in-house color laboratories. This pattern is most visible in carbonated and functional drink segments, where formulation speed determines shelf positioning.
South Africa Food Colorants Market Segmentation
Food colorant procurement in South Africa fragments across technical specifications, regulatory compliance tiers, and automation readiness. Manufacturers optimize formulation costs by matching pigment chemistry to processing infrastructure and end-use shelf stability requirements.
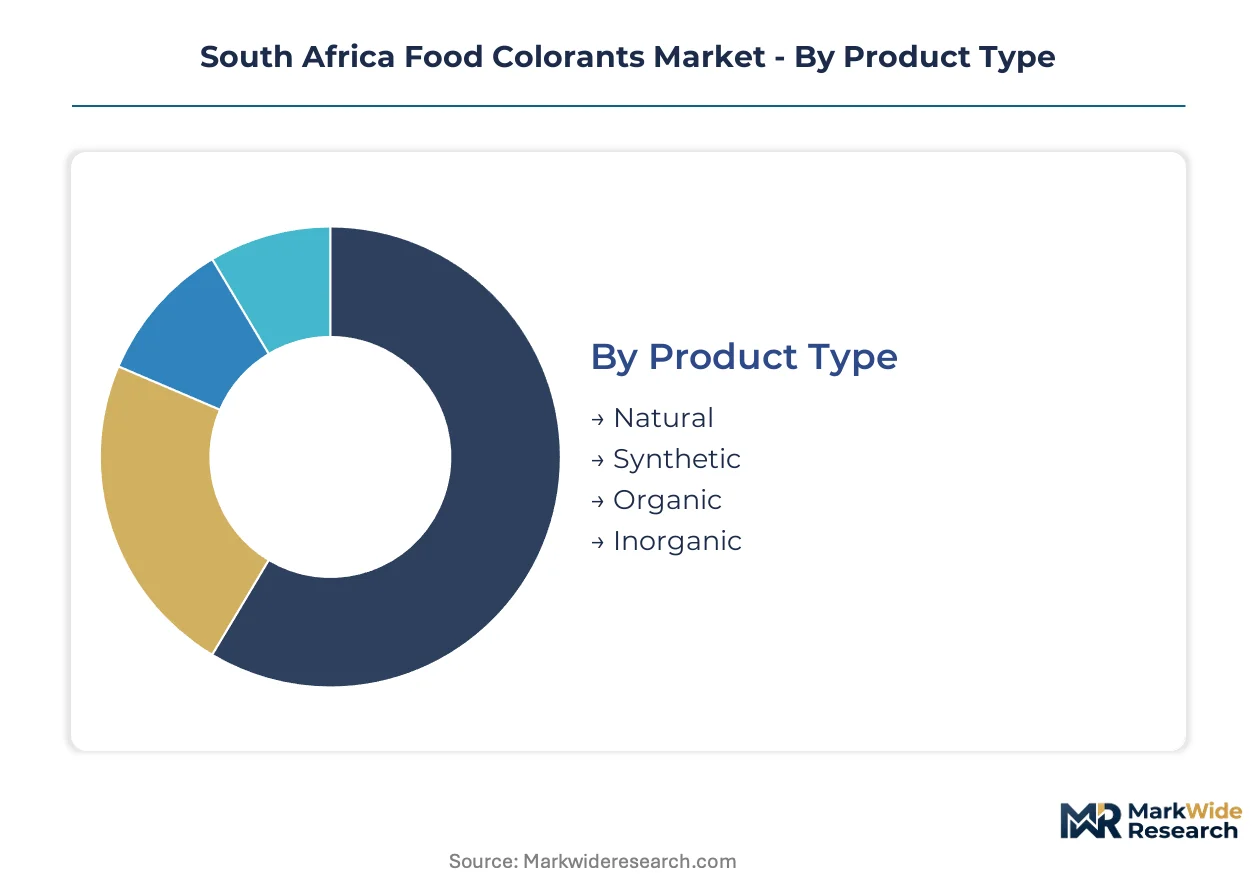
Product Type:
Reformulation cycles are shortening as processors replace legacy synthetic systems with plant-derived alternatives that satisfy clean-label positioning and amended Department of Health limits.
- Natural:Anthocyanin, curcumin, and carmine extracts dominate premium beverage and dairy applications where consumers scrutinize ingredient declarations. Gauteng's carbonated drink manufacturers absorb disproportionate volumes as they phase out azo dyes ahead of regulatory deadlines.
- Synthetic:Azo compounds and aluminum lakes retain cost-critical positions in mass-market confectionery despite mounting compliance pressure. Reformulation cost ambiguity around pending aluminum lake limits has frozen long-term procurement contracts across mid-tier bakery segments.
- Organic:Carbon-based pigments including caramel color serve brewing and sauce applications requiring heat stability. Durban's sugar processing corridor sources these for consistent browning in caramelized confectionery.
- Inorganic:Titanium dioxide and iron oxides provide opacity and mineral-based hues in decorative coatings. Import dependency from Asian suppliers exposes Western Cape wine processors to currency volatility.
Synthetic colorants sit at the top of the volume ranking, with natural extracts climbing the fastest.
Application:
Demand concentration tracks Gauteng's manufacturing density, with each application exhibiting distinct technical service requirements and specification sensitivity.
- Beverages:Carbonated and functional drink producers drive liquid colorant adoption for automated dosing precision. Johannesburg's processing cluster consumes the largest share as brands accelerate reformulation to plant-derived anthocyanin systems.
- Confectionery:Hard candy and chocolate coatings require pH-stable pigments across acidic and alkaline matrices. KwaZulu-Natal's sugar corridor demands custom blend technical services that smaller distributors cannot supply.
- Bakery:Heat-stable carotenoids and caramel colors withstand oven temperatures in bread and pastry applications. Mid-tier producers face margin compression from natural pigment premiums.
- Dairy:Fermentation-derived pigments from Chr. Hansen dominate yogurt and cheese coloring where clean-label positioning commands retail price recovery. Compliance pressure under Foodstuffs, Cosmetics and Disinfectants Act amendments is most acute here.
Beverages command the steepest expansion trajectory, while dairy maintains the highest specification barriers.
Form:
Physical state selection depends on dosing automation level, batch size, and contamination risk tolerance across processing environments.
- Liquid:Pump-dispersed systems eliminate dust exposure and reduce batch-to-batch variation in high-volume production. Gauteng's automated carbonated drink lines are displacing powder handling at compressed timelines.
- Powder:Dry blends serve smaller bakeries and confectioners with manual scaling operations. Labor contamination risks persist in under-automated facilities.
- Paste:High-concentration formats reduce storage footprint for specialized applications requiring intense color saturation. Decorative icing manufacturers in Johannesburg favor these for transport efficiency.
- Granular:Free-flowing particles suit dry-mix applications where dispersion uniformity is critical. Instant beverage premix producers specify these for shelf-stable distribution.
Liquid formulations hold volume leadership, with paste formats gaining share fastest in premium decorative segments.
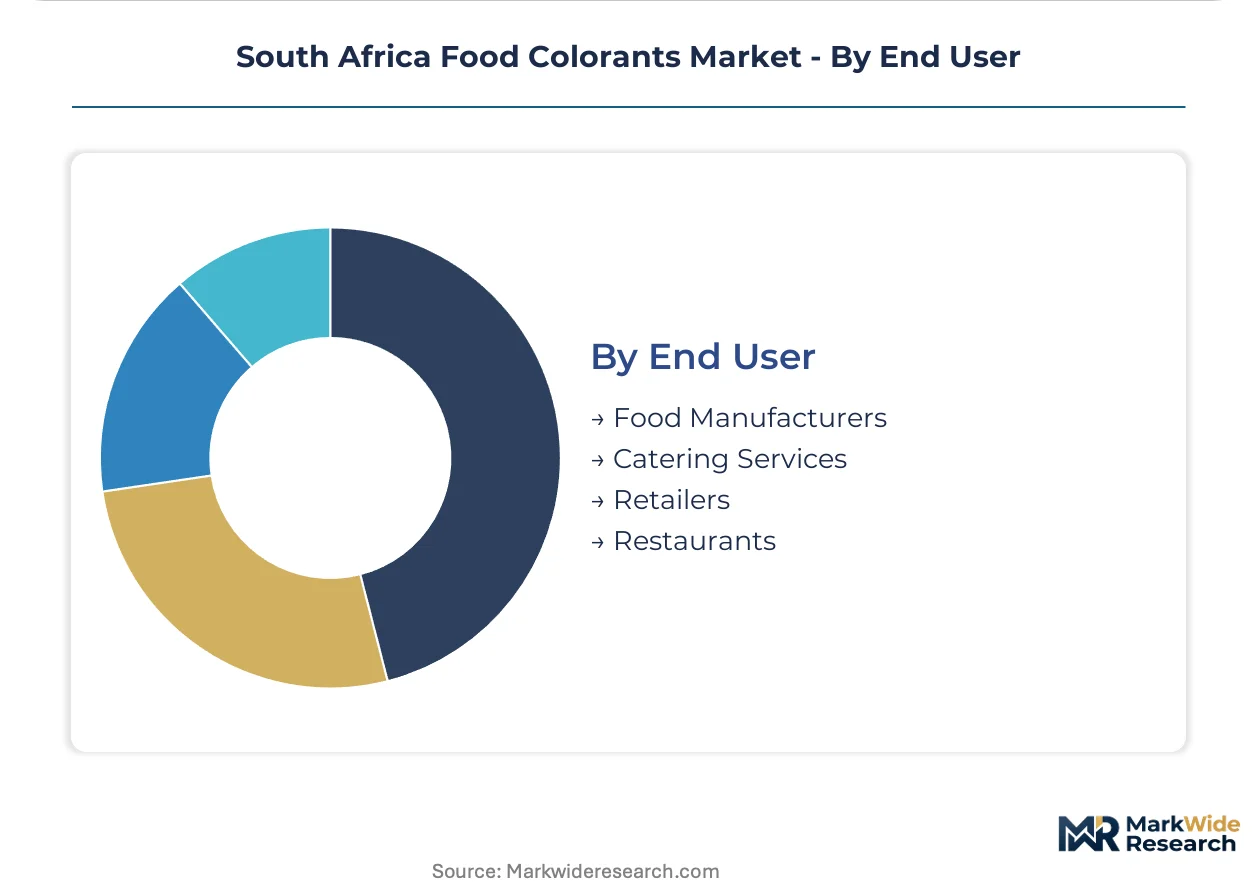
End User:
Procurement sophistication varies sharply between large-scale manufacturers with in-house color laboratories and fragmented food service operators.
- Food Manufacturers:Integrated processors in Gauteng and KwaZulu-Natal negotiate direct supplier relationships, unbundling technical service from pigment supply. These buyers drive specification changes across the value chain.
- Catering Services:Institutional kitchens prioritize cost-stable synthetic options where visual presentation supports menu differentiation. Volume concentration remains dispersed.
- Retailers:Private-label brands impose clean-label requirements on contract manufacturers, transmitting natural pigment premiums to shelf pricing. Western Cape wine and juice retailers are expanding specification influence.
- Restaurants:Independent operators source through regional distributors with limited technical support capabilities. This segment lags in natural colorant adoption.
Food manufacturers dominate procurement volume, with retailers expanding specification influence most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gauteng province anchors South African food colorant demand through Johannesburg's dense beverage and dairy processing corridor, where reformulation timelines compress supplier relationships. Provincial concentration creates localized procurement intensity that rewards technical service capabilities and rapid-response logistics networks.
Gauteng
Carbonated drink manufacturers and dairy processors drive anthocyanin and curcumin extract consumption as they phase out azo dyes ahead of Department of Health regulatory deadlines. The Foodstuffs, Cosmetics and Disinfectants Act amendments mandate accelerated supplier requalification for aluminum lake-containing formulations. Johannesburg's automated production lines displace powder handling with liquid colorant dosing systems at compressed implementation schedules.
Western Cape
Grape-derived beverage applications present underpenetrated natural colorant adoption beyond Gauteng's saturated dairy markets. Wine and juice processors face import dependency exposure to Asian titanium dioxide suppliers through currency volatility channels. Cape Town's retail private-label expansion transmits clean-label requirements to contract manufacturers, amplifying specification influence downstream.
KwaZulu-Natal
Durban's sugar processing and candy manufacturing cluster demands custom color blend technical services that smaller distributors cannot supply. Hard candy producers require pH-stable pigments across acidic and alkaline matrices where formulation expertise concentrates among narrow technical workforces. The National Regulator for Compulsory Specifications certification timelines extend product launch cycles for regional confectionery exporters.
Eastern Cape
Mid-tier bakery segments face margin compression from natural pigment premiums as they navigate pending aluminum lake regulatory uncertainty. Port Elizabeth's food service operators lag in natural colorant adoption, sourcing through regional distributors with limited technical support capabilities. Institutional kitchens prioritize cost-stable synthetic options where visual presentation supports menu differentiation.
South Africa Food Colorants Market Competitive Landscape
Portfolio diversification dominates the current landscape as suppliers unbundle after-sales technical support from base pigment contracts to secure direct procurement relationships with Gauteng's integrated processors. The vendor base stratifies across fermentation-derived pigment specialists, synthetic dye incumbents with established technical service networks, and custom blend providers serving clean-label transitions. Three archetypes define competitive positioning: natural extract specialists commanding premium pricing, synthetic colorant anchors leveraging regulatory compliance expertise, and regional distributors facing displacement from manufacturer-direct relationships. M&A activity and backward integration into captive supply of fermentation-derived pigments represent the dominant competitive vectors reshaping supplier qualification timelines.
Within the natural extract specialist tier, Chr. Hansen Holding and Sensient Technologies occupy positions exemplifying technical service depth over commodity supply. BASF SE anchors the synthetic colorant incumbent archetype through compliance-focused relationships with beverage formulators. Among regional fabricators, Chemical Services Ltd. and Quantum Colors SA represent distributors adapting to direct procurement compression from Gauteng's manufacturing giants.
| Leading Market Players |
|---|
| Sensient Technologies |
| BASF SE |
| Chr. Hansen Holding |
| Cargill Inc. |
| Archer Daniels Midland |
| Givaudan SA |
| Chemical Services Ltd. |
| Parshwanath Colour Chem |
| Quantum Colors SA |
| Others |
Value Network & Pricing Analysis
Gauteng's beverage and dairy processors are compressing supplier qualification timelines under Foodstuffs, Cosmetics and Disinfectants Act amendments, forcing pigment suppliers to absorb reformulation costs and accelerate technical service deployment to maintain contract positions.
Pricing Analysis
Input-cost pass-through from spirulina and carmine extracts runs through anthocyanin-based formulations at substantial premiums over synthetic azo alternatives. Three-tier pricing structure across fermentation-derived premium, plant-extracted standard, and synthetic economy levels separates Chr. Hansen's dairy positioning from BASF's beverage anchor contracts. Cost compression in mid-tier confectionery is intensifying because natural pigment premiums outpace retail price recovery. Mid-tier bakery segments exhibit highest price sensitivity; integrated Gauteng beverage giants show least.
Supply Chain Analysis
Direct-to-manufacturer channels handle Gauteng's hyperscale processor demand, displacing regional distributors from pigment procurement relationships. Supply concentrates in India for spirulina fermentation, China for synthetic dye intermediates, and Peru for carmine cochineal harvests. Raw material dependencies span cochineal insects, grape pomace anthocyanins, and petroleum-derived azo precursors. Single-source vulnerability from Asian fermentation corridors exposes South African formulators to currency volatility. Distribution runs through Johannesburg's technical service hubs with captive color laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's food colorants market functions as a stable compounder anchored by regulatory-mandated reformulation cycles that perpetually refresh demand for compliant pigment systems.
For Market Incumbents: Acquire fermentation-derived pigment capabilities to defend against Chr. Hansen's dairy dominance and Sensient's custom blend technical services. Secure backward integration into captive anthocyanin supply from Western Cape grape processors. Expand in-house color laboratory capacity across Gauteng to match compressed buyer qualification timelines. For New Entrants and Emerging Players: Mid-tier Durban confectioners lacking pH-stable formulation support represent the most penetrable buyer archetype in South Africa's colorants landscape. Target white-space demand in KwaZulu-Natal's sugar corridor with technical service partnerships that incumbent distributors cannot replicate. Lead with custom blend development capabilities rather than commodity pigment supply. For Investors and Strategic Acquirers: Asymmetric upside sits with fermentation-derived pigment specialists possessing Bureau of Indian Standards equivalence certification for synthetic dye import substitution. Long-term viability hinges on regulatory compliance depth rather than volume scale. Watch pending aluminum lake maximum permissible limit consultations as the critical inflection signal for reformulation cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anthocyanin Supply | Captive grape pomace extraction from Western Cape wine processors secures pH-stable pigment feedstock. |
| Technical Service Laboratory Expansion | In-house color formulation capabilities in Johannesburg match Gauteng processor compressed timelines. |
| BIS Equivalence Certification Investment | Third-party testing protocols differentiate imported synthetic dye suppliers under National Regulator standards. |
| Microencapsulation Capability Buildout | pH-stable delivery systems consolidate competitive positioning in carbonated beverage reformulation. |
| Direct Procurement Relationship Development | Manufacturer-direct contracts displace regional distributors from Gauteng's concentrated buyer base. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade flow reconciliation, and primary stakeholder engagement — were reconciled to construct South Africa's food colorants market baseline. Interviews with beverage formulation chemists, dairy procurement leads, confectionery technical directors, and National Regulator compliance officers were cross-validated against customs records, Department of Health amendment documentation, and Bureau of Indian Standards certification databases. Bottom-up pigment volume estimates and top-down manufacturing output triangulation anchored demand sizing.
Data-stream reconciliation across product type, application, form, and end-user segmentation dimensions generated value projections over the projection horizon. CAGRs were derived from regression analysis of historical reformulation cycle timing and regulatory compliance cost trajectories. Modeled inputs included aluminum lake regulatory uncertainty timelines, automated dosing system adoption curves in Gauteng carbonated drink facilities, and natural pigment premium elasticity across bakery and confectionery tiers.
Underlying measurement precision varies by segment; beverage and dairy applications carry tighter precision than dispersed food service channels due to concentrated buyer visibility. Forecasts reflect assumptions around Department of Health amendment implementation timing and BIS equivalence recognition pathways for imported synthetic dyes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
North America Food Stabilizers Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Blueberry Ingredient Market
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Mexico Food Preservatives Market
Food Additives and Ingredients
North America Food Acidulants Market
Food Additives and Ingredients
Potassium Propionate Market
Food Additives and Ingredients
Food Grade Phosphates Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
South America Feed Additives Market
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
France Food Emulsifiers Market