
 Food Grade Phosphates Market | 2026-2036
Food Grade Phosphates Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Phosphates Market Intelligence
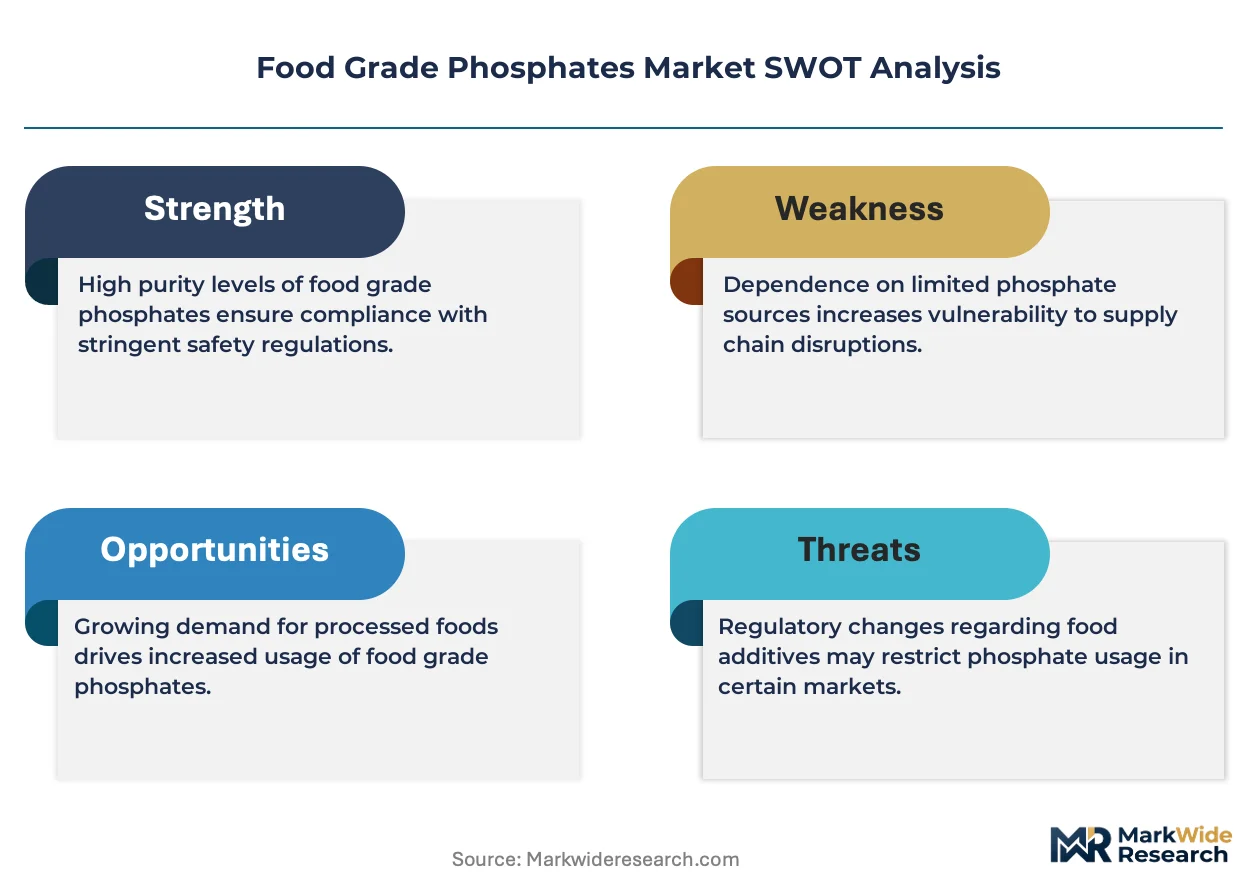
A divergence in purity grades and functional specialization is rebalancing the food grade phosphates market between high-value additives and commodity ingredients. This split separates specialty phosphates for nutraceuticals from standard grades used in bulk food processing. ICL Group leverages its vertically integrated phosphate rock supply to compete on scale. Budenheim specializes in high-purity formulations for complex food systems, while Prayon S.A. focuses on purified phosphoric acid as a key intermediate.
Food grade phosphates are mineral salts derived from phosphoric acid, essential for their functional properties in food production. These additives act as leavening agents, emulsifiers, sequestrants, and pH control agents. Within product types, sodium phosphates dominate due to their versatility and cost-effectiveness, particularly in bakery applications. Potassium phosphates represent a growing segment, valued for their use in low-sodium formulations for processed meats and dairy products, where health-conscious consumer trends are influential.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) dictate purity, usage levels, and labeling requirements. In China, compliance with national GB standards is mandatory for market access, influencing ingredient sourcing. Navigating these disparate international standards for heavy metal limits and approved applications remains a critical competency for suppliers aiming for broad geographic reach.
Market Dynamics
The market's central dynamic is the growing bifurcation between commodity and specialty phosphates. This split is driven by divergent end-market requirements, separating bulk-use grades for meat processing from high-purity, functional formulations for nutraceuticals and complex food systems.
Growth Catalysts
- Processed Food Expansion:Demand for convenience foods and processed meats in Asian and Latin American economies is a primary catalyst, increasing the use of phosphates for moisture retention, texture, and shelf-life extension in large-scale food manufacturing.
- Low-Sodium Formulations:Public health initiatives targeting sodium reduction are boosting the adoption of potassium phosphates as a functional substitute for sodium phosphates, particularly in processed meats, cheeses, and baked goods in Europe and North America.
- Bakery Sector Growth:The expansion of industrial bakeries and the popularity of ready-to-bake products rely on chemical leavening systems, where sodium and calcium phosphates are essential for controlling dough aeration and final product volume.
Market Restraints
- Phosphate Rock Volatility:The price and supply of phosphate rock, the primary raw material, are subject to significant geopolitical and market volatility, directly impacting production costs and margin stability for phosphate manufacturers.
- Clean Label Substitution:The consumer-driven "clean label" movement pressures food manufacturers to reduce or replace phosphates with alternatives like starches, hydrocolloids, or plant-based proteins, posing a direct substitution threat.
- Regulatory Divergence:Navigating disparate heavy metal limits and usage guidelines between jurisdictions, such as the US FDA and Europe's EFSA, complicates global product development and increases compliance costs for suppliers.
Strategic Opportunities
- Nutraceutical Fortification:The growing nutraceuticals market presents an opportunity for high-purity calcium and magnesium phosphates as sources for mineral fortification in dietary supplements, functional beverages, and fortified foods.
- Plant-Based Foods:Formulating plant-based meat and dairy alternatives requires sophisticated texturizing and emulsifying systems, creating a new application space for specialized phosphate blends to improve mouthfeel and stability.
- Emerging Market Standards:As food safety regulations tighten in markets like India and Brazil, local producers are upgrading from industrial-grade to food-grade ingredients, opening new channels for certified phosphate suppliers.
Industry Challenges
- Supply Chain Complexity:Managing distinct supply chains for different purity grades and ensuring traceability to comply with regulations like China's GB standards and the US Food Safety Modernization Act is a major operational burden.
- Capital Intensive Production:The construction of facilities capable of producing purified phosphoric acid and high-purity specialty phosphates is capital-intensive and involves long lead times, creating a high barrier to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Phosphates Market |
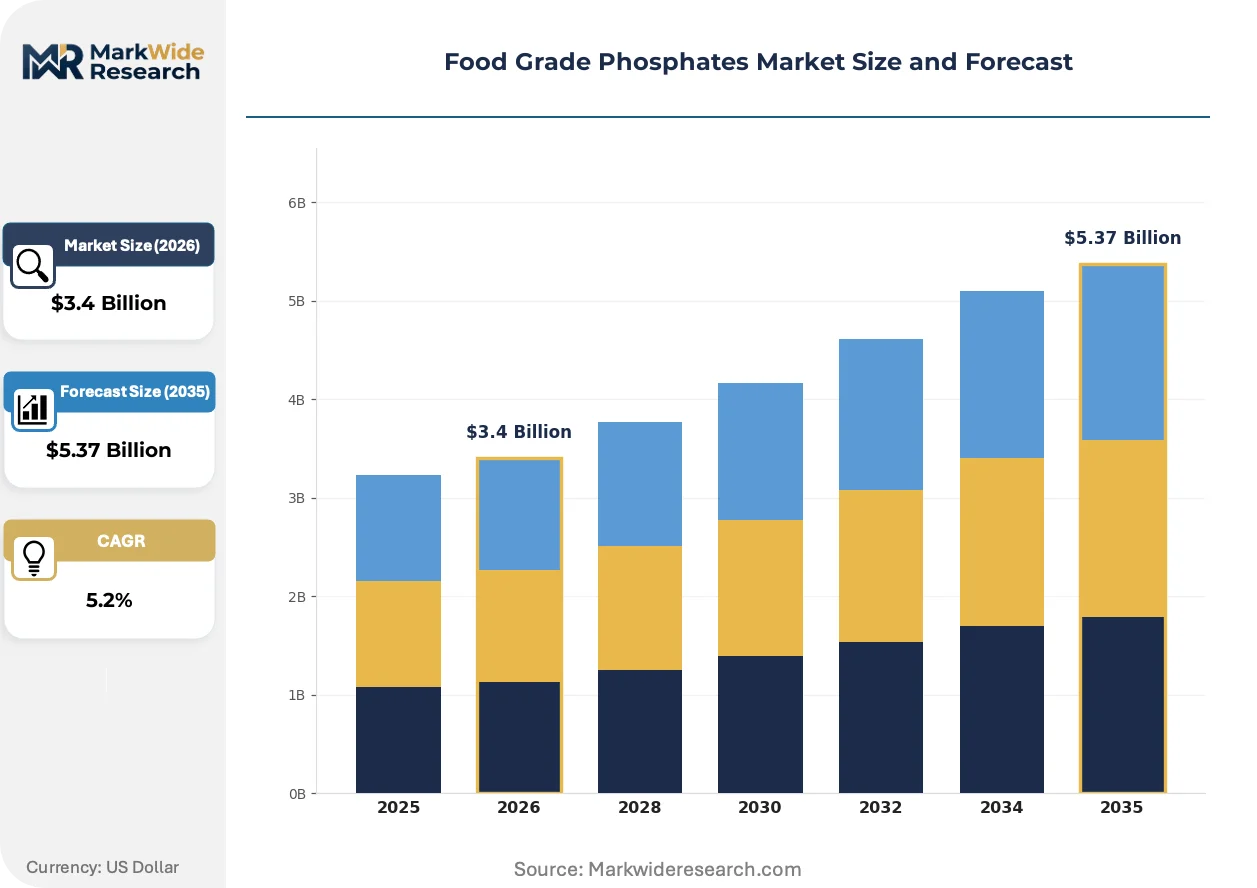
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $5.37 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocalcium Phosphate, Dicalcium Phosphate, Tricalcium Phosphate, Sodium Phosphate, Potassium Phosphate Application: Meat Processing, Dairy Products, Bakery, Beverage, Confectionery End User: Food Manufacturers, Food Service Providers, Ingredient Suppliers, Nutraceutical Producers Packaging Type: Bulk Bags, Drums, Sachets, Cartons, Flexible Intermediate Bulk Containers |
| Companies Covered | Budenheim, OCP S.A., Innophos Holdings, Nutrien Ltd, ICL Group, Prayon S.A., Aditya Birla Chemicals, Haifa Group, FOSFA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Phosphates Market Strategic Shifts & Innovations
Functional specialization is intensifying as suppliers develop phosphate blends tailored for specific outcomes, such as freeze-thaw stability or controlled leavening. This shift moves beyond basic pH control toward performance-driven solutions addressing complex formulation challenges in the food industry.
Microencapsulation technology provides a protective barrier around individual phosphate particles, enabling controlled, triggered release. It is increasingly adopted by industrial bakeries and processed meat producers to optimize leavening reactions and curing processes. This technology is automating the timed delivery of functional ingredients within a food matrix, improving consistency and reducing processing complexity.
Regulatory scrutiny from bodies like the European Food Safety Authority (EFSA) on the aggregate dietary intake of phosphates is a significant trend. This pressure compels food manufacturers to optimize formulations and justify the technological need for every additive. The processed cheese and cured meat segments are most affected, responding by investing in high-efficacy phosphate blends that achieve functional goals at lower concentrations.
A clear behavioral shift is visible in ingredient sourcing, driven by the clean label movement. Food product developers are now reformulating to minimize the number of additives on ingredient statements, favoring multifunctional phosphates that can replace several other ingredients. This trend is most advanced in the North American and European plant-based food and premium beverage sectors.
Food Grade Phosphates Market Segmentation
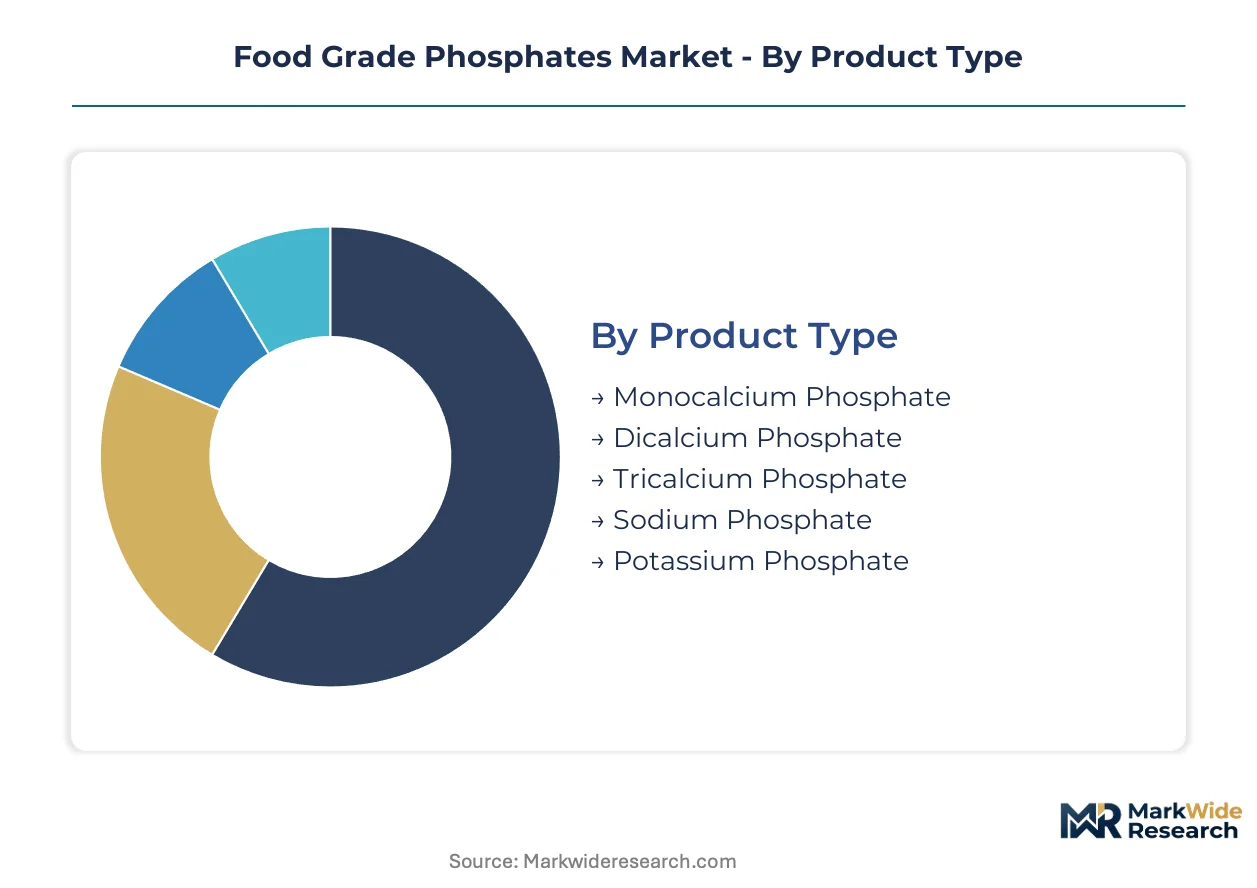
Understanding the Food Grade Phosphates Market requires a granular examination of its diverse segments, reflecting varied functional requirements and end-use applications. This segmentation highlights the distinct value propositions across different product types, applications, end-users, and packaging formats. Distinct purity grades and functional specializations drive market dynamics.
Product Type:
Production of high-purity food grade phosphates, particularly those requiring advanced purification, demands significant capital investment in specialized chemical processing facilities. The initial investment in phosphoric acid purification and subsequent salt crystallization dictates entry barriers for new manufacturers.
- Sodium Phosphate:These versatile salts are widely used as emulsifiers, leavening agents, and pH buffers. Their cost-effectiveness and broad functionality concentrate demand in large-scale bakery and processed meat applications across Asia.
- Potassium Phosphate:Valued for low-sodium formulations, these phosphates serve as functional substitutes. Public health initiatives in Europe and North America drive their use in processed meats and dairy products.
- Monocalcium Phosphate:This calcium salt functions as a leavening agent in baked goods and a mineral fortifier. It controls dough rise in industrial bakeries.
- Dicalcium Phosphate:Used as a dietary supplement for calcium and phosphorus, it also conditions dough. Demand for mineral fortification supports this segment.
- Tricalcium Phosphate:This insoluble salt serves as an anti-caking agent, mineral supplement, and buffer in powders. Its use in fortified beverages is growing.
Most installed capacity flows through Sodium Phosphate. Expansion is steepest in Potassium Phosphate.
Application:
The volume of food grade phosphates consumed varies significantly across different food processing applications, directly correlating with the scale of production in each segment. High-volume processed food sectors drive the largest demand for functional additives.
- Meat Processing:Phosphates enhance moisture retention, improve texture, and extend the shelf life of processed meats. Large-scale manufacturing in China relies on these additives for ham, sausages, and poultry.
- Bakery:Essential as leavening agents, phosphates control dough aeration and crumb structure. Industrial bakeries in Europe utilize sodium and calcium phosphates for consistent product quality.
- Dairy Products:Phosphates act as emulsifiers, stabilizers, and protein precipitants in cheese and yogurt. Their role in processed cheese manufacturing is critical for texture.
- Beverage:Used as pH regulators and mineral fortifiers in soft drinks and functional beverages. Demand for fortified drinks supports this application.
- Confectionery:Phosphates provide texture modification and pH control in candies and gums. Their use in gelled confectionery is notable.
Volume concentration remains highest in Meat Processing. The Bakery application is expanding most quickly.
End User:
Profitability for phosphate suppliers can vary significantly depending on the end-user segment, driven by differing requirements for purity, formulation complexity, and volume. Nutraceutical producers typically command higher-margin specialty products.
- Food Manufacturers:These large-scale industrial players integrate phosphates into a wide array of processed foods. Their high-volume procurement drives significant market share.
- Nutraceutical Producers:Requiring high-purity calcium and magnesium phosphates for mineral fortification, this segment focuses on dietary supplements. Stringent quality standards define their sourcing.
- Food Service Providers:Restaurants and institutional kitchens use phosphates in prepared mixes for texture and stability. Their demand often involves pre-blended solutions.
- Ingredient Suppliers:These entities purchase bulk phosphates for blending into custom formulations or reselling. They act as intermediaries in the supply chain.
Food Manufacturers contribute the largest revenue. Nutraceutical Producers show the strongest commercial traction.
Packaging Type:
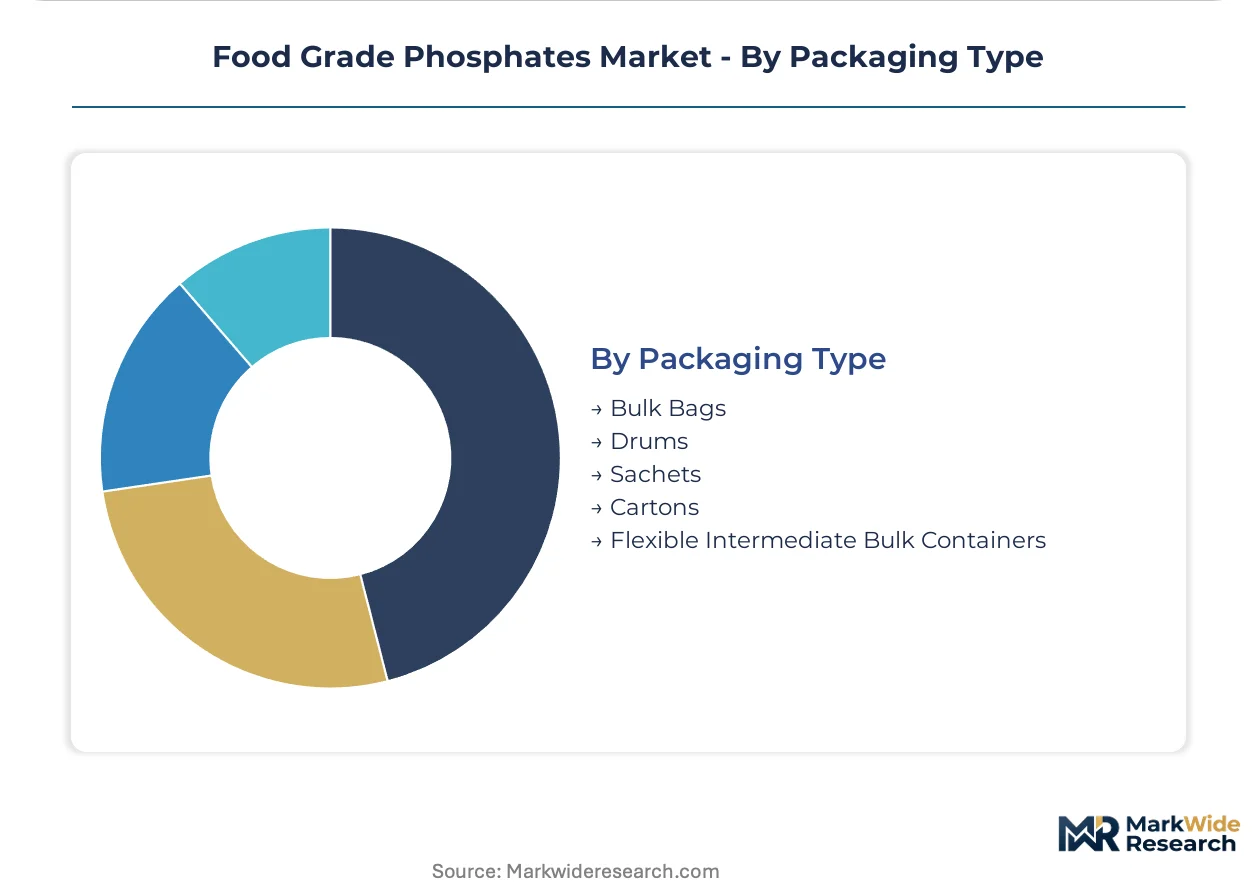
The supply chain configuration for food grade phosphates is influenced by packaging type, with bulk formats concentrating distribution channels for large industrial users. Specialized packaging serves niche or high-value applications requiring precise delivery.
- Bulk Bags:Large industrial users in meat processing and bakery sectors procure phosphates in bulk bags for cost efficiency. These formats facilitate high-volume material handling.
- Flexible Intermediate Bulk Containers:Offering a balance between bulk and smaller packaging, FIBCs are used for medium to large-scale industrial applications. Their ease of handling supports various food manufacturing processes.
- Drums:Typically used for specialty phosphates or smaller industrial batches where contamination control is critical. This format serves diverse food producers.
- Sachets:Small, pre-portioned sachets cater to food service and household use. They offer convenience and precise dosage for smaller operations.
- Cartons:Used for consumer-facing products or specific ingredient blends requiring retail-friendly packaging. This format targets premium food segments.
The dominant packaging format is Bulk Bags. Flexible Intermediate Bulk Containers are gaining share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled food scientists and processing engineers anchor innovation across key global markets, driving demand for specialized food grade phosphates. These professionals develop new applications and optimize existing formulations, particularly in high-growth convenience food segments. Regulatory compliance teams ensure products meet diverse national and international food safety standards, influencing ingredient selection.
United States
Strong demand for processed foods and low-sodium formulations drives phosphate consumption in the United States. The US FDA mandates strict purity standards and usage limits for food additives, impacting product development. Food processing hubs in the Midwest, particularly around Chicago and Minneapolis, are actively integrating advanced phosphate blends for texture and shelf-life extension.
China
China's large-scale meat processing and convenience food sectors generate substantial demand for food grade phosphates. National GB standards dictate mandatory purity levels and approved applications for all food additives. Eastern coastal manufacturing zones, including the Yangtze River Delta, are rapidly expanding their use of phosphates in packaged foods.
India
The expanding bakery sector and growing nutraceutical market in India fuel the need for various food grade phosphates. The FSSAI issues comprehensive guidelines for food safety and additive usage, influencing local sourcing. Western India, particularly the Maharashtra region, sees increased adoption of calcium and sodium phosphates in fortified products.
Germany
Germany's sophisticated industrial bakeries and dairy product manufacturers require high-quality food grade phosphates. The European Food Safety Authority (EFSA) sets stringent maximum usage levels and purity specifications for food additives across the EU. Bavaria's specialized food ingredient manufacturers are developing innovative phosphate solutions for premium convenience foods.
Brazil
Processed meats and beverage fortification applications are significant demand drivers for food grade phosphates in Brazil. ANVISA, the national health surveillance agency, regulates the use and labeling of food additives. São Paulo's large-scale food production facilities are integrating phosphates to improve product stability and texture.
Food Grade Phosphates Market Key Industry Players
Top-tier vendors anchor scale-driven commodity phosphate production, while specialized formulators focus on high-purity applications for niche markets. The market structure exhibits a tiered consolidation, with a few large players controlling raw material supply. Strategic archetypes include integrated raw material suppliers, niche high-purity specialists, and broad-portfolio chemical producers. Capacity expansion and portfolio diversification are common competitive moves.
ICL Group, a vertically integrated entity, exemplifies raw material control and broad market reach. Budenheim, a German-based company, represents high-purity formulation expertise for complex food systems and specialty applications. Prayon S.A. anchors the purified phosphoric acid intermediate market, supplying critical raw materials to other food phosphate manufacturers.
| Leading Market Players |
|---|
| Budenheim |
| OCP S.A. |
| Innophos Holdings |
| Nutrien Ltd |
| ICL Group |
| Prayon S.A. |
| Aditya Birla Chemicals |
| Haifa Group |
| FOSFA |
| Others |
Cost & Logistics Intelligence
Phosphate rock prices, influenced by geopolitical factors, cascade through the food grade phosphates supply chain, directly affecting production costs and end-product pricing tiers. This volatility shapes manufacturers' procurement strategies and margin stability.
Pricing Analysis
The bundled-versus-unbundled service split significantly influences pricing for food grade phosphates. Contract-based long-term offtake agreements dominate for commodity grades, with specialty formulations commanding value-based pricing based on purity, vertical integration, and volume scale. Pricing pressure stems from raw material volatility and the clean label movement, primarily affecting high-volume food manufacturers. Nutraceutical producers, however, exhibit lower price sensitivity for their high-purity product requirements.
Supply Chain Analysis
Dual-sourcing requirements, where buyers mandate multi-supplier qualification, are becoming critical in the food grade phosphates supply chain. Geographic supply concentrates in China for bulk products and Morocco for phosphate rock extraction, with purified phosphoric acid being a key dependency. Geopolitical volatility impacting phosphate rock represents a significant structural risk. Distribution runs through direct sales to large food manufacturers and ingredient suppliers for smaller, specialized players.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Food Grade Phosphates Market is transitioning into a late-cycle quality story, driven by a demand shift towards high-purity formulations for nutraceuticals and complex food systems. This evolution necessitates strategic adjustments across the value chain.
For Market Incumbents: To counter the clean label substitution threat, market incumbents must invest in advanced R&D for multifunctional phosphate blends. Deepen backward integration into phosphoric acid production to stabilize costs and ensure purity. Capacity additions in specialized facilities for high-purity grades will reinforce competitive positioning.
For New Entrants and Emerging Players: Microencapsulation technology provides a compelling wedge for new entrants to optimize leavening reactions and curing processes. Target underpenetrated emerging markets like India and Brazil, where local producers are upgrading to certified food-grade ingredients. Focus on specialized, high-purity formulations for plant-based food alternatives as a go-to-market angle.
For Investors and Strategic Acquirers: Asymmetric upside sits with niche high-purity specialists and technology providers offering performance-driven solutions over the long term. The market's essential functional role ensures viability across the next five to ten years. Identify acquisition targets with strong intellectual property in microencapsulation or specialized phosphate blends. A signal to watch is regulatory tightening on aggregate phosphate intake, driving demand for high-efficacy solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for High-Purity Grades | Ensures supply for growing nutraceutical and complex food system demands. |
| R&D in Multifunctional Blends | Develops performance-driven solutions to address clean label pressures and formulation challenges. |
| Backward Integration into Phosphoric Acid | Stabilizes raw material costs and ensures consistent purity for critical inputs. |
| Strategic Partnerships for Plant-Based Applications | Accelerates development of specialized texturizing and emulsifying systems. |
| Investment in Microencapsulation Technology | Automates timed delivery of functional ingredients, improving product consistency. |
Research Approach
Multiple input streams — primary interviews, secondary research, and proprietary databases — were reconciled to construct a robust market view. Primary engagement included food scientists, procurement leads, regulatory affairs specialists, and R&D directors across key regions. Secondary validation drew from industry association reports, government food safety guidelines from the US FDA and Europe's EFSA, company financial filings, and specialized trade publications. Bottom-up and top-down triangulation ensured data integrity.
Data-stream reconciliation established the analytical framework for market projections across the analysis window. Segmentation dimensions included product type, application, end-user, packaging format, and purity grade. Compound Annual Growth Rates were derived through a weighted average of historical trends and projected future demand. Processed food consumption trends and anticipated regulatory changes for additives served as key forecast inputs.
The model holds under current macroeconomic conditions and regulatory frameworks; deviation in raw material price volatility or clean label movement acceleration would shift the outlook materially. Forecasts reflect assumptions documented through stakeholder consultations. Stricter global regulations on aggregate phosphate intake represent a specific risk factor.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Brazil Food Acidulants Market
Food Additives and Ingredients
AKD Emulsifier Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Food Binders Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Oxidized Starch Market
Food Additives and Ingredients
United Kingdom Food Additives Market
Food Additives and Ingredients
Quillaja Saponaria Ingredient Market
Food Additives and Ingredients
Global Wood-Derived Food Additives Market
Food Additives and Ingredients
Non-PHO Emulsifiers Market
Food Additives and Ingredients
Africa Food Enzymes Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
France Food Additives Market
Food Additives and Ingredients
Global Natamycin Market
Food Additives and Ingredients
Mexico Anti Caking Market