

Bakery Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Bakery Stabilizers Market Insights
European hydrocolloid producers is rebalancing capacity toward bakery-grade gum arabic and pectin derivatives after weather disruptions in Sub-Saharan sourcing regions. Cargill leverages its integrated starch-to-stabilizer pipeline to secure supply continuity for industrial bread manufacturers. Kerry Group anchors its position through specialized emulsifier blends tailored for clean-label cake applications. Palsgaard competes on precision-dosing technology that reduces over-formulation waste in high-throughput pastry lines.
Bakery stabilizers comprise functional ingredient systems—typically emulsifiers, hydrocolloids, enzymes, and gums—that control water mobility, gas retention, and crumb structure in wheat-based doughs and batters, with dosage precision often measured in parts per thousand to prevent texture collapse or staling acceleration. Their primary commercial purpose is to extend shelf-stable freshness in packaged baked goods while accommodating reduced-fat or egg-free reformulations. Hydrocolloids dominate volume demand in bread applications where moisture retention governs consumer acceptability over multi-day distribution cycles. Enzymes represent the fastest-expanding product category as amylase and lipase systems displace chemical preservatives in premium positioning strategies. Emulsifiers concentrate margin pools within cake and pastry segments where aeration stability commands formulation premiums.
The FDA's GRAS notification pathway and the EPA's bio-based manufacturing incentives jointly shape stabilizer innovation priorities in the United States, while the EU's EFSA-driven additive re-evaluations and REACH compliance obligations constrain emulsifier chemistry options for exporters. India's FSSAI fortification mandates and China's GB standards for food-grade gums add layer complexity for multinational formulation houses seeking cross-border product registration harmonization. Stakeholders must monitor evolving enzyme labeling thresholds and bioengineered ingredient disclosure requirements that threaten to fragment formulation standards across North American and European retail channels.
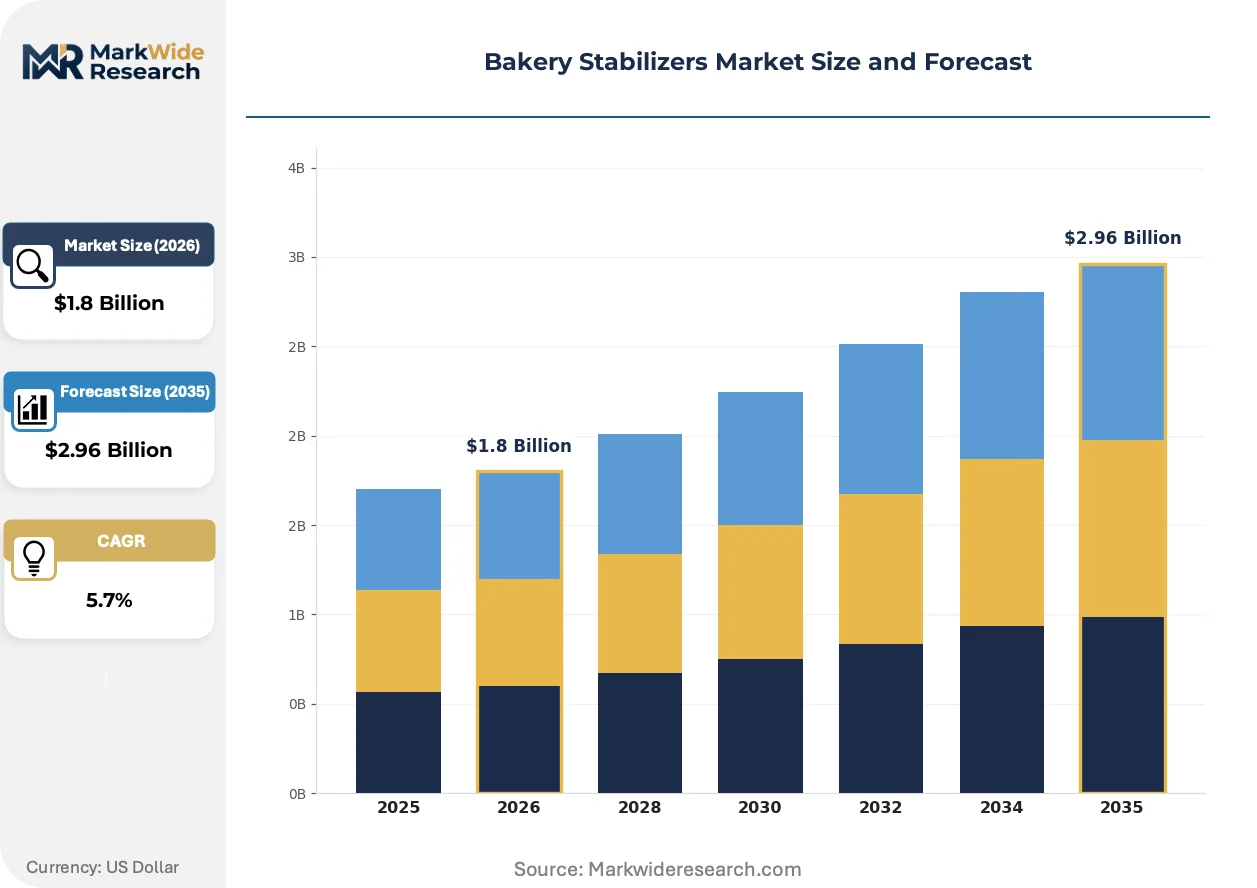
Market Dynamics
The EU's updated Food Additives Regulation is forcing commercial bakeries into accelerated emulsifier substitution programs, compressing formulation cycles from multi-year to quarterly review intervals.
Growth Catalysts
- Clean-label mandates:EFSA-driven additive re-evaluations in Europe are pulling enzymatic systems into premium bread positioning, displacing chemical preservatives in packaged goods.
- Industrial bakery clustering:Germany's Rhineland and Bavaria regions concentrate procurement scale, creating pull-through demand for integrated stabilizer systems in high-throughput lines.
- Bio-based manufacturing incentives:The EPA's bio-preferred program in the United States is accelerating fermentation-derived hydrocolloid capacity expansion for egg-free reformulations.
Market Restraints
- Gum arabic supply volatility:Weather disruptions across Sub-Saharan sourcing regions are creating raw material intermittency for European hydrocolloid producers.
- REACH compliance costs:ECHA registration obligations for novel emulsifier chemistries are extending time-to-market for reformulated systems by 18-24 months.
- Enzyme price premiums:Lipase and amylase systems command 3-4x the per-kilogram cost of conventional chemical stabilizers, constraining adoption in economy-tier bakery segments.
Strategic Opportunities
- India fortification mandates:FSSAI micronutrient requirements in packaged bread are creating formulation service opportunities for stabilizer houses with integrated mineral-delivery expertise.
- Precision-dosing technology:Automated dosing systems that reduce over-formulation waste are expanding into mid-tier pastry operations previously served by manual batch processes.
- China GB standard alignment:Harmonization opportunities exist for multinational suppliers navigating SAMR food-grade gum specifications against EU and US regulatory frameworks.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in enzyme-starch interactions is concentrating at top-tier suppliers, creating talent acquisition friction for regional stabilizer blenders.
- Clean-label certification timelines:Third-party non-GMO and organic verification for hydrocolloid sources is extending supplier qualification cycles by 8-12 months.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakery Stabilizers Market Trends and Innovations
Enzymatic stabilizer systems are compressing the competitive landscape by enabling chemical-free shelf-life extension, while regulatory divergence between FDA GRAS pathways and EFSA re-evaluation cycles is fragmenting formulation standardization.
Fermentation-derived hydrocolloids are expanding into industrial bread manufacturing as drop-in replacements for modified starches in clean-label applications. Mid-sized commercial bakeries in the United States and Germany are adopting these systems at quarterly reformulation intervals. The technology is expanding into previously price-sensitive segments by matching the cost structure of conventional emulsifiers at scale.
REACH compliance obligations for food-contact substances are constraining emulsifier chemistry options for exporters serving European industrial bakeries. ECHA registration dossiers now require extended toxicological data packages for novel surfactants. Cake and pastry segments are responding by accelerating enzyme-based aeration systems that fall outside REACH substance evaluation scope.
Direct procurement relationships between industrial bakeries and stabilizer manufacturers are disintermediating traditional ingredient distributors in high-volume bread applications. German bakery clusters are negotiating multi-year supply agreements with integrated producers that bypass regional wholesalers. This pattern is most visible in the Rhineland region, where three industrial bakery cooperatives have established captive supply arrangements for hydrocolloid systems.
Bakery Stabilizers Market Segmentation
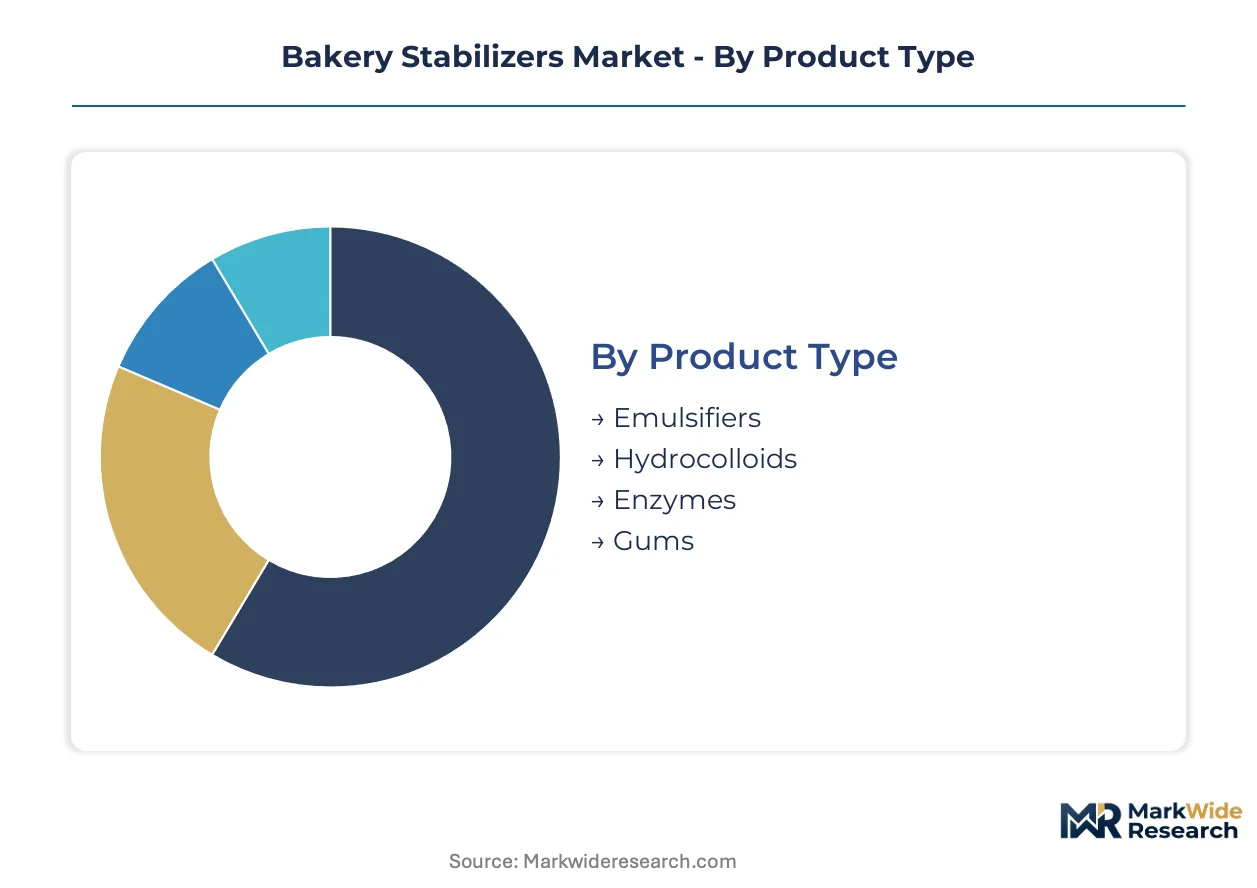
Bakery stabilizer procurement splits along functional performance requirements and shelf-life specifications. Industrial buyers prioritize hydrocolloid systems for moisture retention in extended distribution cycles, while artisanal operators favor enzymatic solutions for clean-label positioning.
Product Type:
Formulation chemists select stabilizer categories based on dough system compatibility and regulatory acceptance thresholds in target markets.
- Hydrocolloids:Cellulose derivatives, pectin, and gum arabic systems govern water mobility in high-hydration bread formulations. German industrial bakery clusters in Rhineland source these at scale for multi-day freshness extension in packaged sliced bread.
- Enzymes:Amylase and lipase systems enable chemical-free shelf-life extension through starch modification and lipid interaction control. Clean-label mandates from EFSA-driven additive re-evaluations are accelerating adoption in premium European bread positioning.
- Emulsifiers:Mono- and diglycerides, lecithin, and DATEM variants stabilize gas-cell structures in cake batters.
- Gums:Xanthan, guar, and locust bean derivatives provide viscosity control in gluten-free and egg-free reformulations.
Hydrocolloids lead on scale; enzymes lead on momentum.
Application:
End-use determines dosage precision requirements, with bread demanding moisture retention and cakes requiring aeration stability.
- Bread:Industrial pan bread and artisanal loaves require hydrocolloid systems at parts-per-thousand precision to prevent crumb firming during distribution. German bakery cooperatives negotiate multi-year supply agreements for integrated stabilizer systems.
- Cakes:Aerated batters depend on emulsifier blends for gas-cell stabilization through baking and cooling cycles. Kerry Group anchors supply relationships through specialized formulations for clean-label cake applications.
- Pastries:Laminated doughs utilize enzyme systems to control fat distribution and layer integrity.
- Biscuits:Low-moiture applications favor gum systems for texture modulation and breakage resistance.
Bread dominates volume throughput; cakes concentrate margin extraction.
End User:
Procurement scale and technical service requirements separate industrial buyers from artisanal operators.
- Food Processing Units:High-throughput manufacturing lines demand precision-dosing compatibility and batch-to-batch consistency. Palsgaard competes on automated dosing technology that reduces over-formulation waste in these installations.
- Bakeries:Mid-sized commercial operations balance reformulation flexibility with cost control, adopting fermentation-derived hydrocolloids at quarterly intervals.
- Confectioneries:Specialized applications require custom stabilizer blends for texture and shelf stability.
- Retail Chains:Private-label programs drive specification standardization across supplier bases.
Food processing units lead on procurement scale; bakeries lead on reformulation frequency.
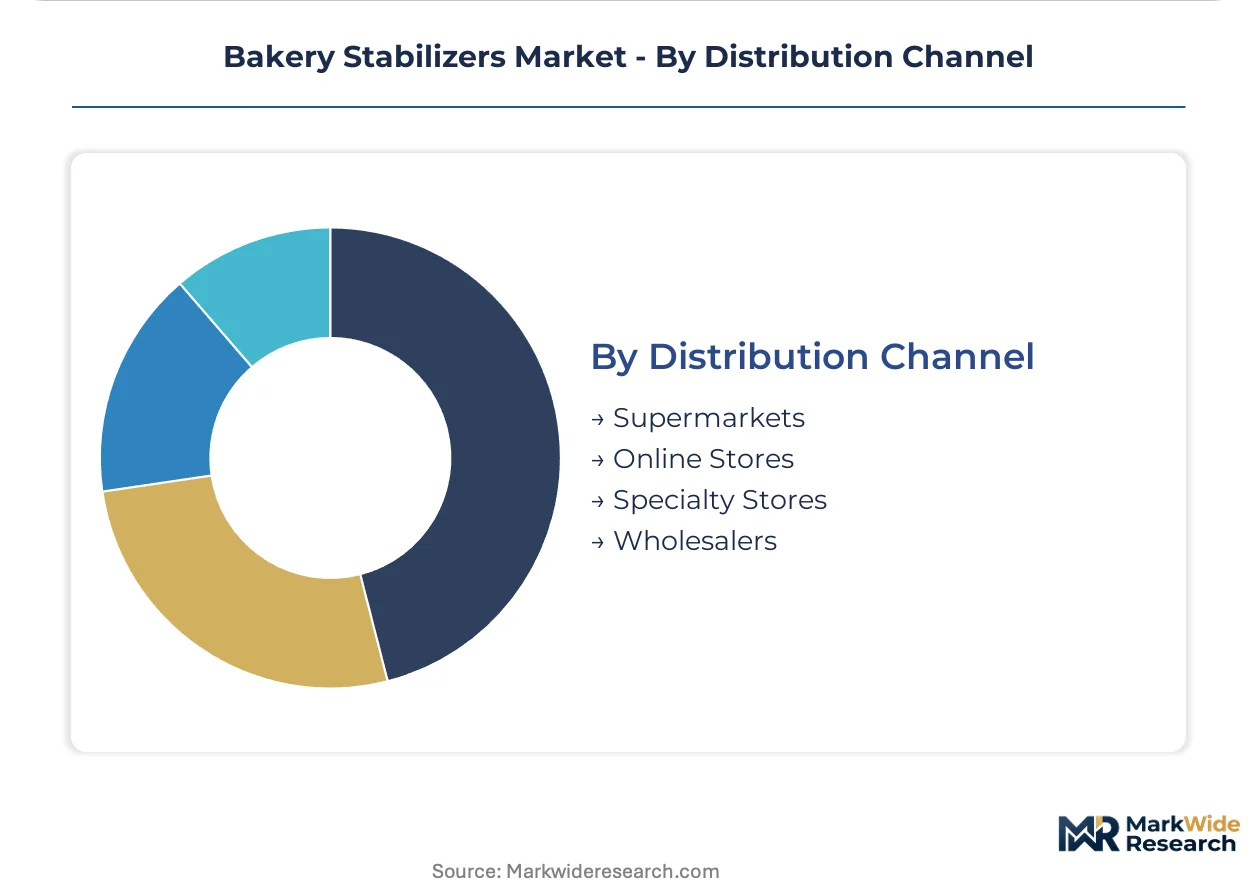
Distribution Channel:
Channel selection reflects order size, technical service needs, and inventory velocity requirements.
- Wholesalers:Bulk hydrocolloid systems move through distributor networks serving mid-tier bakeries without direct manufacturer relationships. German industrial clusters are disintermediating this channel through captive supply arrangements.
- Supermarkets:Retail stabilizer SKUs for home baking segments concentrate in conventional emulsifier and gum offerings.
- Specialty Stores:Artisanal bakeries source enzyme systems and clean-label hydrocolloids through technical ingredient suppliers.
- Online Stores:E-commerce penetration remains limited to small-volume specialty formulations and sample procurement.
Wholesalers retain volume leadership; specialty stores capture premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting hydrocolloid production toward jurisdictions with streamlined food-additive approval pathways, as REACH compliance costs in Europe extend time-to-market by 18-24 months for novel emulsifier chemistries. Manufacturers are relocating fermentation-derived capacity to markets offering bio-based manufacturing incentives and faster regulatory clearance.
United States
The EPA's bio-preferred program accelerates fermentation-derived hydrocolloid capacity expansion for egg-free reformulations. FDA GRAS notification pathways enable faster market entry for enzymatic stabilizer systems compared to EFSA timelines. Industrial bakeries in the Midwest and Southeast are adopting precision-dosing technology at quarterly reformulation intervals.
Germany
Rhineland and Bavaria industrial bakery clusters concentrate procurement scale for integrated stabilizer systems in high-throughput lines. EFSA-driven additive re-evaluations force quarterly formulation review cycles, compressing multi-year development windows. German cooperatives negotiate multi-year supply agreements that bypass traditional distributor networks for hydrocolloid systems.
China
GB standards for food-grade gums create harmonization complexity for multinational formulation houses seeking cross-border product registration. SAMR specifications govern hydrocolloid purity thresholds in industrial bread manufacturing. Yangtze River Delta bakery equipment manufacturers source stabilizer systems through direct procurement relationships.
India
FSSAI fortification mandates in packaged bread create formulation service opportunities for stabilizer houses with mineral-delivery expertise. Central food safety regulations require micronutrient integration in commercial bakery products. Maharashtra and Gujarat industrial bakeries adopt enzyme systems for clean-label positioning in premium segments.
Brazil
ANVISA registration requirements for imported hydrocolloids extend supplier qualification timelines for European exporters. Domestic gum arabic sourcing from Sub-Saharan trade partners faces weather-driven intermittency. São Paulo industrial bakery clusters increasingly specify enzymatic stabilizers for extended shelf-life in tropical distribution conditions.
Bakery Stabilizers Market Competitive Landscape
North American producers anchor the scale-driven tier; European specialists hold the premium formulation segment. The vendor base separates into integrated agribusiness conglomerates with starch-to-stabilizer pipelines and focused ingredient houses with precision-dosing capabilities. Three archetypes dominate: fermentation-technology leaders, hydrocolloid sourcing specialists, and emulsifier blend engineers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as direct procurement relationships disintermediate traditional distribution channels.
Among integrated agribusiness operators, Cargill and Archer Daniels Midland occupy positions exemplifying captive supply chain control from raw material through finished stabilizer systems. Kerry Group and Palsgaard sit within the specialized formulation tier, representing archetypes of precision-application engineering and clean-label emulsifier development. Tate & Lyle anchors the European hydrocolloid sourcing specialist position.
| Leading Market Players |
|---|
| Cargill |
| Tate & Lyle |
| Kerry Group |
| Archer Daniels Midland Company |
| Ingredion |
| CP Kelco |
| Palsgaard |
| BASF |
| Hydrosol |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up hydrocolloid specialists have consolidated Sub-Saharan gum arabic sourcing networks, tightening working-capital discipline and compressing distributor margins across European bakery supply chains. This ownership concentration feeds directly into pricing power for moisture-retention systems while forcing mid-tier blenders toward spot-market exposure for pectin derivatives.
Pricing Analysis
Distributor margin layers in industrial hydrocolloid supply typically capture 12-18 points before bakery procurement teams, though direct-to-cooperative arrangements in Germany's Rhineland clusters bypass this structure entirely. Three-tier pricing structure across premium, standard, and economy levels separates enzyme-based clean-label systems from conventional emulsifier blends and commodity gum offerings. Pricing pressure stems from fermentation-derived hydrocolloid scale economics matching modified starch cost structures. Economy-tier bread manufacturers exhibit acute price sensitivity, while premium cake specialists absorb enzyme premiums for EFSA-compliant positioning.
Supply Chain Analysis
Domestic-content mandates in India's FSSAI fortification programs are reshaping sourcing toward local mineral-delivery stabilizer production for packaged bread applications. Raw material supply concentrates in Sudan and Chad for gum arabic, Germany and Denmark for fermentation-derived hydrocolloids, and China for xanthan and guar processing. Critical dependencies include Sub-Saharan acacia harvests, European corn-starch feedstocks, and Asian seaweed-derived hydrocolloids. Single-source vulnerability runs through Sudanese gum arabic corridors disrupted by climate volatility. Distribution runs through integrated manufacturer-direct relationships disintermediating traditional wholesale networks in high-volume bread applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bakery stabilizers function as a regulatory compounder where EFSA-driven additive re-evaluations and India's FSSAI fortification mandates continuously generate reformulation service demand across commercial bakery clusters.
For Market Incumbents: Deploy precision-dosing technology partnerships to lock in high-throughput pastry line installations before mid-tier competitors achieve automated formulation capability. Cargill and Kerry Group should extend backward integration into fermentation-derived hydrocolloid capacity to offset gum arabic supply intermittency from Sub-Saharan sourcing disruptions. Channel control through multi-year cooperative supply agreements in Germany's industrial bakery clusters defends margin position against distributor disintermediation. For New Entrants and Emerging Players: Mid-sized commercial bakeries in the United States Midwest represent the most penetrable buyer archetype, operating at quarterly reformulation intervals without captive supplier relationships. White-space targets include egg-free reformulation services for EPA bio-preferred program participants and enzyme-based aeration systems for cake manufacturers escaping REACH substance evaluation scope. Go-to-market execution should anchor on technical service partnerships with regional bakery equipment distributors. For Investors and Strategic Acquirers: Valuations sit cheapest among fermentation-technology specialists with scalable hydrocolloid platforms and clean-label certification pipelines. Long-term viability over a five-to-ten year window favors integrated producers controlling starch-to-stabilizer pipelines rather than formulation blenders exposed to raw material volatility. The signal to watch is accelerated direct procurement relationship formation between industrial bakery cooperatives and hydrocolloid manufacturers, indicating distributor displacement velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Capacity | Cargill's captive bio-based hydrocolloid production secures supply continuity against Sub-Saharan gum arabic disruptions. |
| Precision-Dosing Technology Deployment | Palsgaard's automated systems reduce over-formulation waste in high-throughput German pastry operations. |
| Clean-Label Certification Investment | Third-party non-GMO and organic verification extends supplier qualification cycles by 8-12 months for premium positioning. |
| Direct Procurement Relationship Formation | Rhineland bakery cooperatives bypass traditional distributors through multi-year hydrocolloid supply agreements. |
| Regulatory Harmonization Capability Buildout | Multinational formulation houses navigate FDA GRAS, EFSA re-evaluations, and China GB standards for cross-border registration. |
Research Methodology
Bottom-up bakery application modeling reconciled against top-down hydrocolloid capacity tracking forms the analytical core of this study. Primary interviews with formulation chemists, industrial bakery procurement directors, and hydrocolloid plant managers combined with secondary validation from EFSA additive re-evaluation dossiers, FSSAI fortification circulars, and customs trade data for gum arabic imports. Triangulation across these sources calibrated enzyme adoption rates and emulsifier substitution timelines.
Input-output matrices mapped hydrocolloid consumption against bread, cake, pastry, and biscuit production volumes across the projection horizon. Segmentation dimensions modeled include product type, application, end-user scale, and distribution channel, with regulatory framework clusters treated as a cross-cutting variable. CAGRs were derived from elasticity-adjusted demand curves incorporating clean-label mandate penetration and bio-based manufacturing incentive uptake. Industry-specific forecast inputs included quarterly reformulation interval acceleration and REACH compliance cost pass-through assumptions.
Underlying measurement precision varies by segment; enzyme systems and hydrocolloid volumes in industrial bread applications carry tighter precision than artisanal bakery penetration estimates. Forecasts reflect documented assumptions about regulatory timeline adherence and raw material supply continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.