
 Ecommerce Inventory Management Software Market | 2026-2036
Ecommerce Inventory Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Ecommerce Inventory Management Software Market Insights
The EU Green Deal is decoupling supply chain transparency from traditional inventory opacity, compelling ecommerce operators to embed carbon tracking into stock management workflows. Shopify leverages its merchant ecosystem to anchor cloud-native inventory tools across North America. SAP competes through deep ERP integration that sustains enterprise-grade demand forecasting for large wholesalers. Zoho Inventory specializes in modular APIs that extend inventory visibility to emerging marketplace sellers in South Asia.
Ecommerce inventory management software comprises digital platforms that automate stock tracking, order orchestration, and multi-warehouse synchronization through real-time data pipelines, typically processing SKU-level updates within sub-second latency to prevent overselling and stockouts. Cloud-based deployment dominates current installations, though hybrid architectures are capturing margin pools from enterprises with legacy on-premise ERP commitments. The end-user split reveals SMEs driving volume expansion while large enterprises concentrate value through multi-tenant private cloud deployments with direct EDI integrations to supplier networks.
FDA traceability rules for food and supplement ecommerce, EPA packaging waste directives in California, and EU GDPR data residency requirements collectively shape platform architecture decisions and cross-border deployment constraints. The SEC's climate disclosure mandates for public retailers further tighten the link between inventory systems and emissions reporting. Stakeholders must monitor how fragmented national data-localization laws reshape multi-tenant cloud economics before committing to centralized platform architectures.
Market Dynamics
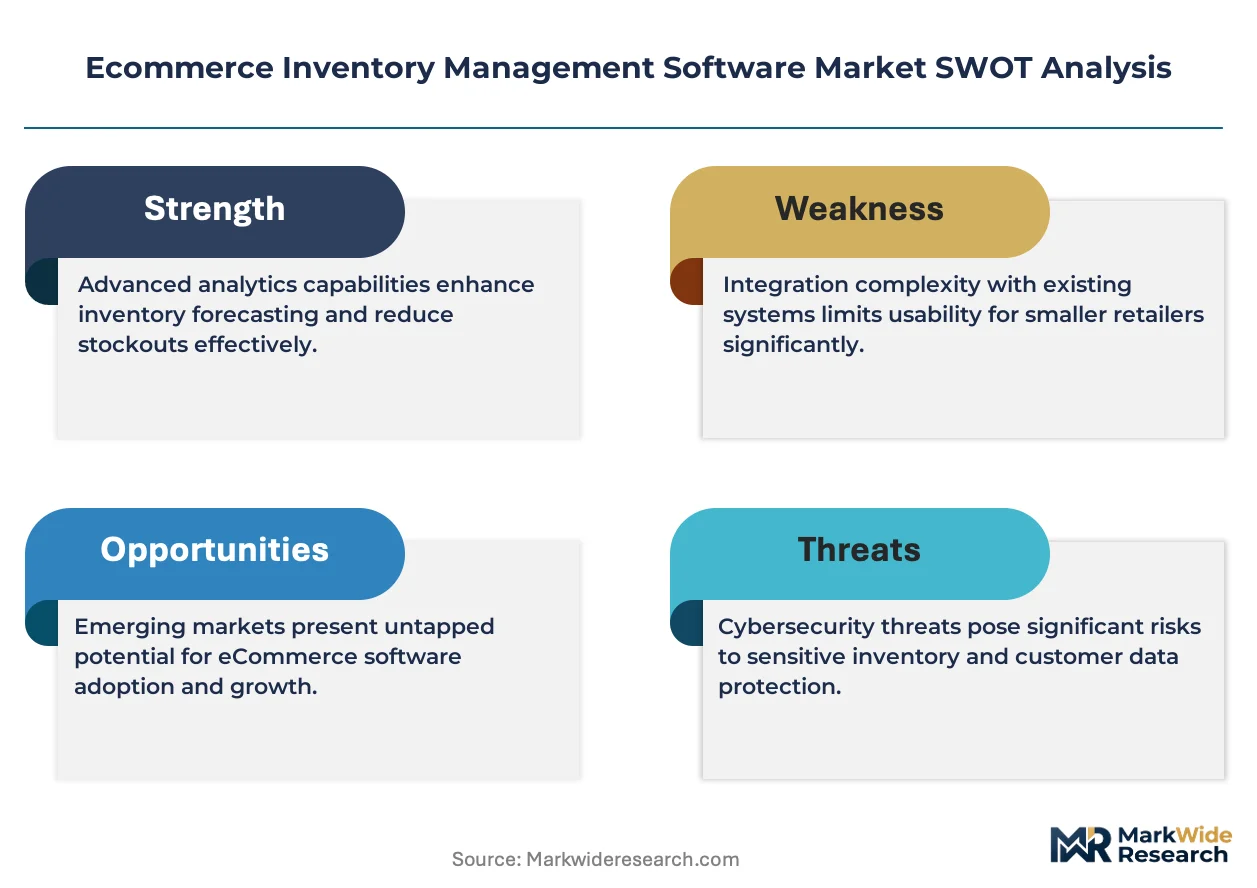
Cloud-native inventory platforms are compressing the technical moat between mid-market merchants and enterprise-grade fulfillment capabilities, forcing incumbent vendors to reprice API access and warehouse orchestration modules.
Growth Catalysts
- EU Digital Product Passport:The EU Green Deal mandates granular lifecycle tracking for electronics and textiles sold online, compelling retailers to deploy real-time SKU serialization.
- Multi-channel fulfillment:Direct-to-consumer brands operating across Amazon, Shopify, and TikTok Shop require unified stock visibility to prevent channel-specific stockouts.
- California packaging waste directives:The state's Extended Producer Responsibility laws embed inventory data into compliance reporting, accelerating cloud migration among West Coast ecommerce clusters.
Market Restraints
- Data localization friction:Fragmented national data-residency laws in Germany, France, and India force redundant infrastructure spend, eroding multi-tenant cloud economics.
- Legacy ERP entrenchment:Wholesale distributors with SAP or Oracle on-premise commitments face seven-figure migration costs to API-native inventory stacks.
- Real-time latency thresholds:Sub-second inventory synchronization across distributed warehouses demands edge computing investments that exceed SME capital budgets.
Strategic Opportunities
- Carbon-accounting convergence:The SEC's climate disclosure mandates for public retailers create demand for inventory systems that auto-generate Scope 3 emissions reports from stock movement data.
- India marketplace penetration:Emerging sellers on Flipkart and Meesho lack integrated warehouse management, presenting modular API openings for cloud-native entrants.
- AI-driven demand sensing:Machine learning models that ingest social media sentiment and weather patterns are compressing forecast error rates for seasonal apparel categories.
Industry Challenges
- EDI integration complexity:Large wholesalers demand direct electronic data interchange with supplier networks, requiring months of custom mapping for each trading partner.
- Cybersecurity certification timelines:SOC 2 Type II and ISO 27001 audits delay go-live dates for vendors serving enterprise accounts by six to nine months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ecommerce Inventory Management Software Market |
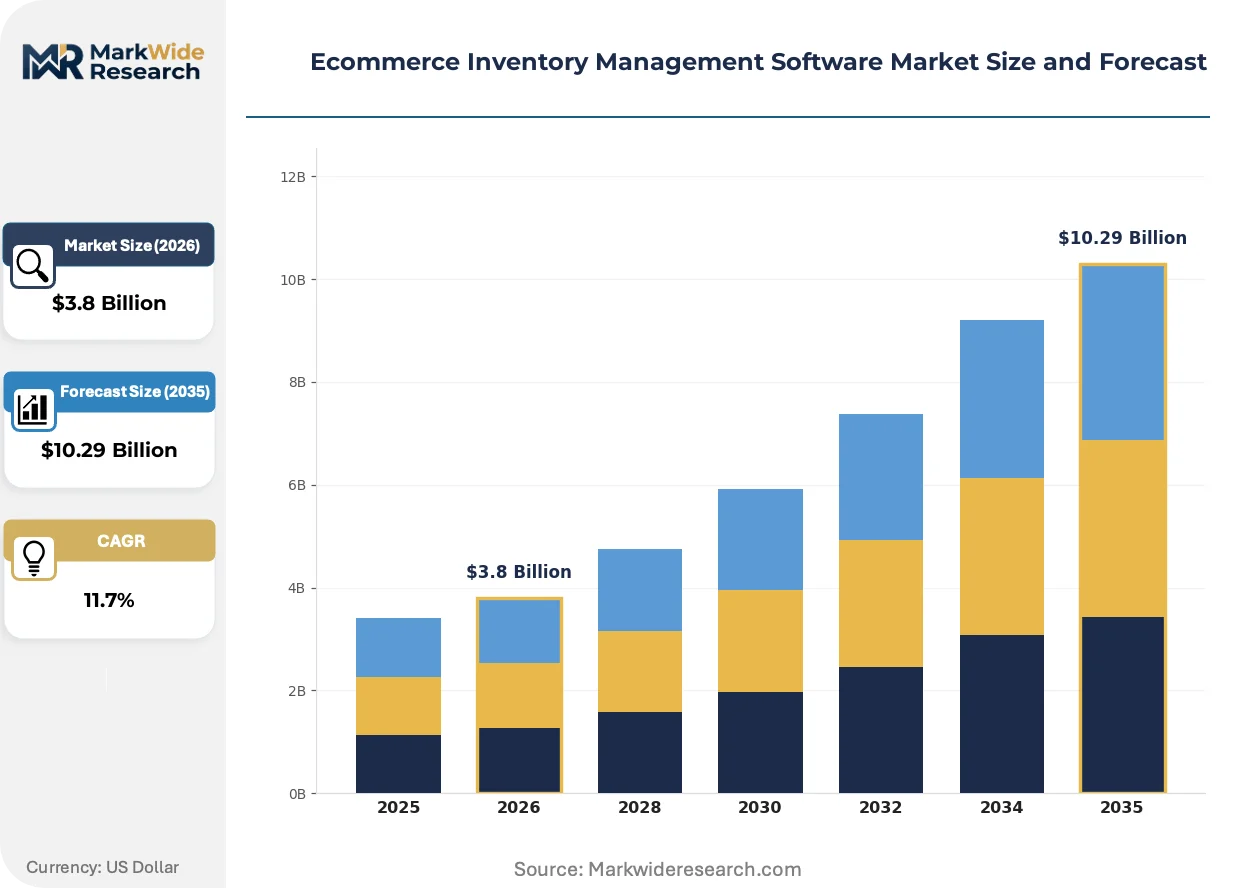
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.29 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cloud-Based, On-Premise, Hybrid, Mobile Integration Level: APIs, Plugins, EDI, Direct Integrations End User: SMEs, Large Enterprises, Marketplaces, Wholesalers Deployment: Single Tenant, Multi-Tenant, Private Cloud, Public Cloud |
| Companies Covered | Shopify, Zoho Inventory, Cin7, Fishbowl, Oracle, SAP, Linnworks, Veeqo, Skubana, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ecommerce Inventory Management Software Market Trends and Innovations
Real-time data pipelines and predictive analytics are redefining competitive advantage in inventory orchestration, compressing the gap between demand signal and warehouse response.
Embedded machine learning for demand forecasting is consolidating vendor differentiation in the mid-market segment. Third-party logistics providers and direct-to-consumer brands are deploying these tools within eighteen-month refresh cycles. The technology is consolidating pricing power around platforms that pre-integrate forecasting with warehouse execution.
The FDA's traceability rules for dietary supplements and packaged foods mandate lot-level tracking from manufacturer to consumer. Ecommerce operators must now embed serialization into pick-pack-ship workflows. Food and supplement pure-play retailers face the steepest compliance curves, with many pursuing hybrid cloud architectures to isolate sensitive traceability data.
Merchant procurement of inventory software now favors outcome-based contracts tied to stockout reduction and carrying-cost savings. Enterprise buyers are displacing perpetual licenses with annual recurring models that bundle implementation support. This shift is most visible among California-based ecommerce clusters where venture-backed brands prioritize operational flexibility over capital ownership.
Ecommerce Inventory Management Software Market Segmentation
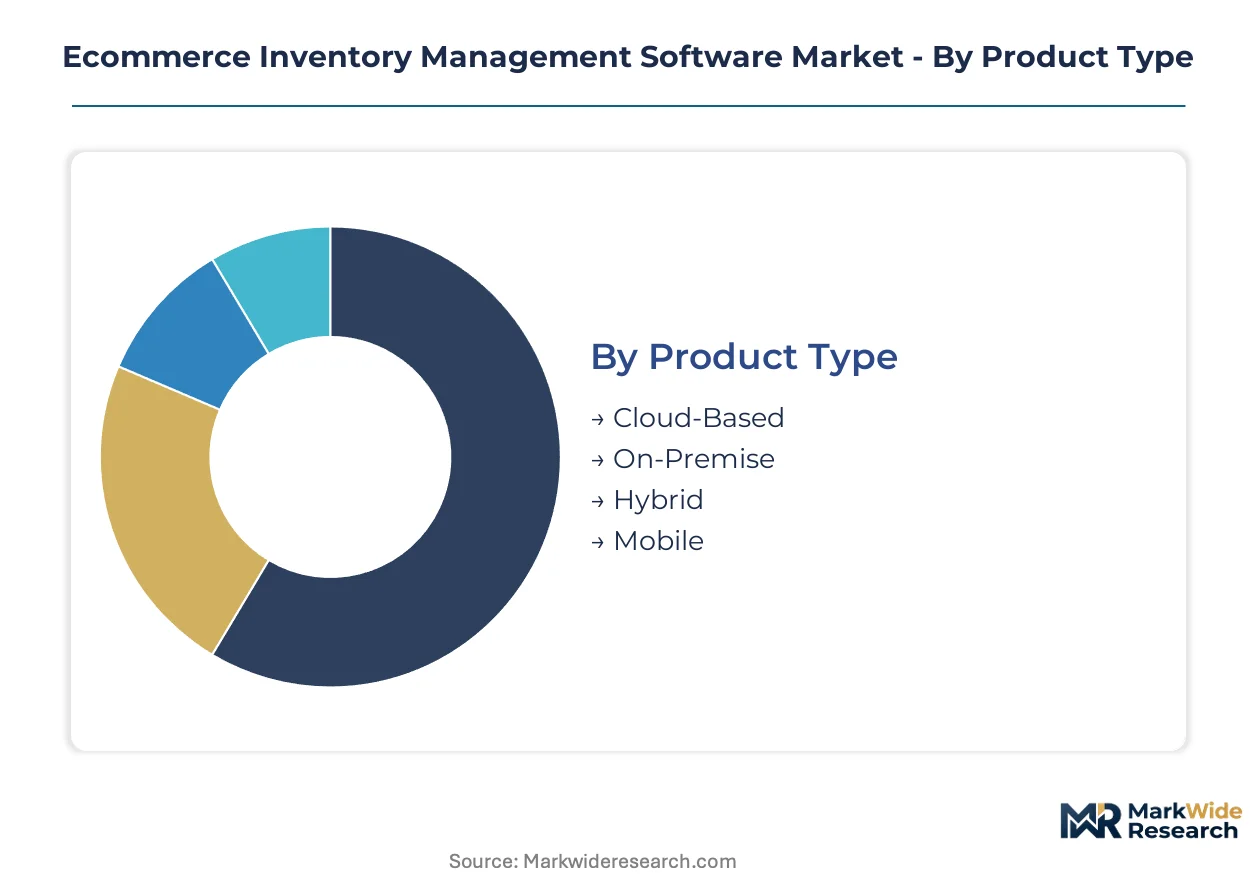
Inventory management software segments diverge sharply by technical architecture and buyer sophistication. Cloud-native configurations dominate new procurement cycles while legacy on-premise estates persist among wholesale distributors with deep ERP entrenchment. Understanding these fault lines reveals where platform vendors can extract pricing power versus where commoditization pressures concentrate.
Product Type:
Customization-to-standardization tension runs deepest here — cloud platforms offer configurable workflows while on-premise solutions demand bespoke infrastructure engineering.
- Cloud-Based:These platforms deliver real-time SKU synchronization through distributed data pipelines with sub-second latency thresholds. Demand concentrates among California-based direct-to-consumer brands and multi-channel retailers operating across Amazon, Shopify, and TikTok Shop, driven by the need to prevent channel-specific stockouts without capital-intensive infrastructure.
- On-Premise:Legacy deployments run on client-owned servers with direct database access for custom reporting and compliance isolation. Large wholesale distributors with SAP or Oracle commitments in Germany and the United States sustain this segment, constrained by seven-figure migration costs and data residency requirements under GDPR and fragmented national localization laws.
- Hybrid:Split architectures isolate sensitive traceability data on private infrastructure while leveraging public cloud for scalability.
- Mobile:Native iOS and Android applications extend warehouse floor visibility through barcode scanning and voice-picking interfaces.
Most installed capacity flows through Cloud-Based platforms. Expansion is steepest in Hybrid configurations as FDA traceability rules and EU Digital Product Passport mandates force compliance-driven architecture splits.
Integration Level:
Cost tier stratification separates lightweight API connections from capital-intensive EDI implementations requiring months of custom mapping.
- APIs:REST and GraphQL endpoints enable rapid connectivity between inventory systems and storefronts, marketplaces, and logistics providers. Zoho Inventory and similar modular platforms target emerging marketplace sellers in India through standardized API tiers that reduce implementation timelines from quarters to weeks.
- EDI:Electronic data interchange protocols demand AS2 or AS4 transport layers with rigorous trading partner certification. Large North American wholesalers serving big-box retailers require this integration depth, with each supplier network connection consuming substantial professional services capacity and extending sales cycles.
- Plugins:Pre-built connectors for dominant ecommerce platforms accelerate time-to-value for mid-market merchants.
- Direct Integrations:Native coupling with ERP systems bypasses middleware latency for enterprises with unified technology estates.
APIs capture the broadest merchant base. EDI commands the highest contract values and longest customer retention.
End User:
Customer type maturity separates venture-backed brands prioritizing operational flexibility from institutional procurement functions demanding SLA-backed uptime guarantees.
- SMEs:Small and medium enterprises drive volume expansion through subscription-based access to capabilities previously reserved for enterprises. These buyers cluster in India on Flipkart and Meesho, and in California's venture-backed ecommerce ecosystem, where annual recurring models displace perpetual licenses.
- Large Enterprises:Multi-tenant private cloud deployments with direct EDI integrations to supplier networks concentrate value in this segment. Public retailers facing SEC climate disclosure mandates require inventory systems that auto-generate Scope 3 emissions reports from stock movement data.
- Marketplaces:Platform operators managing third-party seller inventory need unified visibility across fragmented merchant bases.
- Wholesalers:B2B distributors with complex channel hierarchies demand lot-level tracking and customer-specific pricing automation.
SMEs generate the highest new-logo velocity. Large Enterprises contribute disproportionate expansion revenue through module upsells.
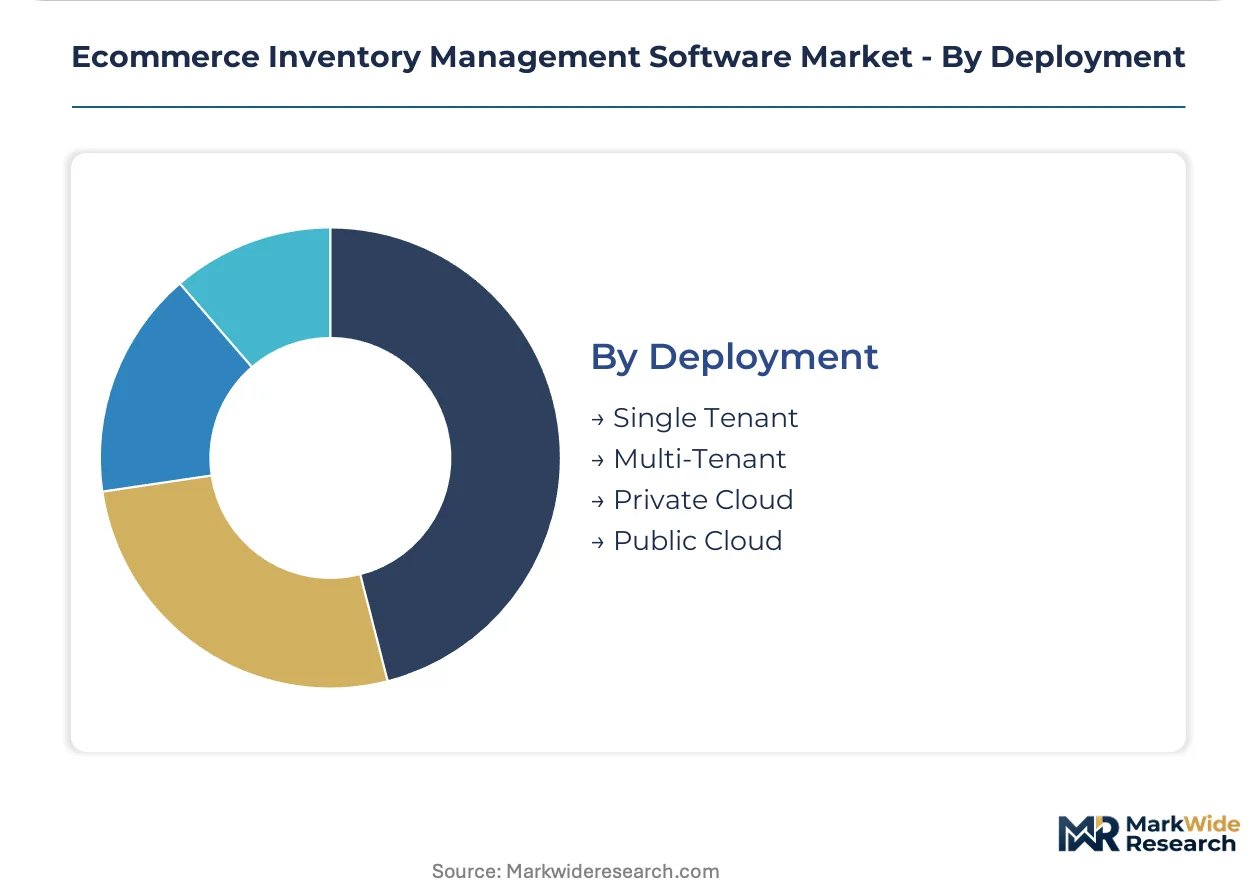
Deployment:
Supply concentration in hyperscale infrastructure shapes margin pools — public cloud leverages economies of scale while private deployments capture compliance premiums.
- Multi-Tenant:Shared infrastructure architectures spread compute costs across merchant bases, enabling aggressive price points for mid-market penetration. These deployments face margin pressure from redundant infrastructure spend forced by data localization friction in Germany, France, and India.
- Private Cloud:Dedicated single-tenant environments isolate sensitive data for FDA-regulated food and supplement operators, with hybrid architectures capturing margin pools from enterprises balancing legacy on-premise ERP commitments against cloud scalability requirements.
- Single Tenant:Fully isolated deployments serve regulated industries with strict audit trail requirements.
- Public Cloud:Pure hyperscale consumption models maximize elasticity for seasonal demand spikes in apparel and consumer electronics.
Multi-Tenant configurations dominate current installations. Private Cloud is gaining share fastest as cybersecurity certification timelines and regulatory data isolation requirements harden.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud inventory management originated in Silicon Valley's venture-backed ecommerce ecosystem during the late 2000s, with early platforms scaling through merchant marketplaces before diffusing to enterprise wholesalers and international direct-to-consumer brands.
United States
California's venture-backed ecommerce clusters and Texas fulfillment hubs drive cloud-native procurement cycles. The SEC's climate disclosure mandates compel public retailers to embed carbon tracking into stock management workflows. Los Angeles and Austin host the densest concentrations of multi-channel merchants replacing legacy ERP systems with API-first platforms.
Germany
Automotive parts distributors and industrial wholesalers sustain demand for hybrid cloud architectures. GDPR data residency requirements and fragmented national localization laws force redundant infrastructure spend across Frankfurt and Munich data centers. Bavaria-based machinery exporters are migrating from SAP on-premise commitments to private cloud deployments with direct EDI integrations.
United Kingdom
London's direct-to-consumer fashion brands and Manchester-based third-party logistics providers accelerate multi-tenant adoption. The UK's post-Brexit customs complexity increases demand for real-time SKU synchronization across EU and domestic warehouses. Southeast England hosts the highest density of merchants operating across Amazon, Shopify, and TikTok Shop simultaneously.
India
Flipkart and Meesho marketplace sellers in Maharashtra and Karnataka lack integrated warehouse management, creating modular API openings. The country's PLI scheme for electronics manufacturing extends to supply chain software localization. Bangalore and Mumbai clusters show the steepest growth in SME subscription adoption for inventory visibility tools.
China
Cross-border ecommerce operators in the Yangtze River Delta and Pearl River Delta demand real-time synchronization with international fulfillment networks. The country's dual carbon goals and MIIT data localization rules reshape platform architecture decisions. Shenzhen and Hangzhou host the most advanced deployments of AI-driven demand sensing for seasonal apparel categories.
Ecommerce Inventory Management Software Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light platform designers for merchant relationships across deployment tiers. The vendor base concentrates around three strategic archetypes: cloud-native challengers with API-first architectures, incumbent ERP vendors defending through deep integration moats, and vertical specialists targeting regulated industries with compliance-isolated deployments. Consolidation pressures intensify as mid-market merchants demand enterprise-grade fulfillment capabilities without proportional price increases. Dominant competitive moves include strategic partnerships between platform vendors and third-party logistics networks, plus geographic expansion through localized data residency compliance.
Within the cloud-native tier, Shopify and Zoho Inventory exemplify divergent geographic strategies. Shopify anchors North American merchant ecosystems through pre-integrated storefront and inventory capabilities. Zoho Inventory occupies a position serving emerging marketplace sellers in South Asia through modular API tiers. SAP represents the incumbent defense archetype, sustaining enterprise relationships through ERP integration depth that complicates displacement by challengers.
| Leading Market Players |
|---|
| Shopify |
| Zoho Inventory |
| Cin7 |
| Fishbowl |
| Oracle |
| SAP |
| Linnworks |
| Veeqo |
| Skubana |
| Others |
Pricing and Supply Chain Analysis
EU Digital Product Passport mandates gate qualified supply and premium-tier pricing access for inventory platforms serving electronics and textile retailers. California's Extended Producer Responsibility laws embed compliance reporting into stock management workflows, compressing margins for vendors lacking carbon-tracking modules while rewarding certified architectures with pricing power.
Pricing Analysis
Annual recurring revenue models with tiered feature access dominate procurement cycles across mid-market and enterprise segments. Price differentiation rests on API call volume thresholds and EDI integration depth, with SOC 2 Type II certification commanding substantial premiums. Cost compression in the SME tier intensifies as hyperscale infrastructure spreads compute expenses across merchant bases. Venture-backed direct-to-consumer brands in California exhibit lowest price sensitivity, prioritizing operational flexibility over license ownership, while emerging marketplace sellers in India drive aggressive discounting for standardized API tiers.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscale providers concentrated in the United States, Germany, and India, with edge computing hardware sourcing from Taiwan and South Korea. Software development draws from engineering talent pools in Bangalore, Berlin, and Austin, while data center construction depends on specialized cooling systems and renewable energy contracts. Single-source vulnerability concentrates in ASIC-based edge devices for sub-second latency synchronization. Distribution runs through direct sales teams for enterprise accounts and self-service portals for SME acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Inventory management software functions as a geographic-arbitrage play where data localization costs in Germany and India exceed California cloud economics by substantial margins. Regulatory fragmentation creates tiered deployment strategies that reward multi-region infrastructure investment.
For Market Incumbents: Lock in enterprise relationships through deep ERP integration moats that complicate displacement by API-native challengers. Extend private cloud certifications for FDA-regulated food operators facing traceability mandates. Fortify EDI professional services capacity to capture big-box retail supplier network contracts with twelve-month switching costs.
For New Entrants and Emerging Players: Emerging marketplace sellers on Flipkart and Meesho represent the most penetrable buyer archetype for modular API platforms with rapid implementation timelines. Target Maharashtra and Karnataka clusters with pre-built connectors for dominant Indian marketplaces. Pursue outcome-based contracts tied to stockout reduction metrics rather than perpetual license displacement.
For Investors and Strategic Acquirers: Roll-up economics work for vertical specialists with compliance-isolated deployments because regulatory data residency requirements fragment addressable markets and sustain niche pricing power. Prioritize platforms with ISO 27001 and SOC 2 Type II certifications already completed. Watch for EU Digital Product Passport enforcement acceleration as the inflection signal for serialization-capable inventory stacks.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Pre-built ERP connectors reduce SAP and Oracle displacement timelines from quarters to weeks for wholesale distributors. |
| Geographic Expansion | Localized data residency compliance in Frankfurt and Mumbai captures GDPR and PLI scheme procurement requirements. |
| Strategic Partnership | Third-party logistics network alliances embed inventory tools into fulfillment workflows for direct-to-consumer brands. |
| Acquisition of Specialist Firm | Carbon-accounting modules auto-generate SEC-mandated Scope 3 emissions reports from stock movement data. |
| Product Launch | AI-driven demand sensing ingests social media sentiment to compress forecast error rates for seasonal apparel. |
Research Methodology
Multiple input streams — primary interviews with CTOs and IT procurement officers at multi-channel retailers, technical validation with platform engineers and integration specialists, and secondary synthesis from SEC filings and hyperscaler capex disclosures — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned direct-to-consumer brand operators in California, wholesale distributors in Germany, and emerging marketplace sellers in India. Secondary sources included customs records for cloud infrastructure trade flows, EDI protocol documentation, and regulatory filings with the SEC and EU Green Deal implementation bodies.
Data-stream reconciliation anchored the forecast framework across the analysis window. Segmentation dimensions modeled encompass deployment architecture, organization size tier, vertical industry, integration complexity level, and regional adoption pattern. CAGRs were derived from revenue trajectory analysis and capacity expansion announcements. Industry-specific inputs included API call volume growth curves, EDI implementation pipeline data, and carbon-tracking module attach rates.
Inputs from hyperscaler infrastructure providers and regulatory implementation timelines were available through the study window; gaps in private cloud pricing transparency and SME churn rates introduce uncertainty bands around segment-level projections. Forecasts reflect documented assumptions about multi-tenant cloud economics and data localization friction persistence. Regulatory enforcement acceleration, cybersecurity certification timeline compression, and AI inference cost curves constitute the trigger set warranting ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Retail Core Banking Solution Market
Software & Services
Automation Test Software Market
Software & Services
PCB CAD Software Market
Software & Services
Global Managed Application Services Market
Software & Services
Global Decision Support Software Market
Software & Services
Video Management Software (VMS) Market
Software & Services
Recruitment Software Market
Software & Services
RIP Software Market
Software & Services
France Digital Marketing Software Market
Software & Services
Camp Management Software Market
Software & Services
Global Invoice Automation Software Market
Software & Services
Payroll and HR Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
Japan HR Payroll Software Market
Software & Services
Software License Management (SLM) Market
Software & Services
Global Automation Software Market