
 Russian IT Software and Services Market | 2026-2036
Russian IT Software and Services Market Size, Share, and Industry Trends Forecast 2026-2036
Russian IT Software and Services Market Analytics
Subscription-based licensing for enterprise resource planning modules is shifting how Russian vendors monetize long-term client relationships. Yandex leverages its cloud infrastructure stack to anchor public sector contracts requiring data sovereignty compliance. VK Company competes across social, gaming, and enterprise communication layers, extending its platform footprint into government-approved software directories. РЕЛЭКС specializes in high-assurance database systems, dominating security-critical installations in defense and nuclear energy facilities.
Russian IT software and services encompass enterprise application development, systems integration, managed infrastructure, and technical support delivered across on-premises, cloud-based, hybrid, and SaaS architectures. These offerings typically incorporate domestic cryptographic modules, comply with FSTEC certification requirements, and process data within Russian Federation jurisdictional boundaries to serve regulated industries. ERP and CRM product types retain the largest installed base among legacy state enterprises modernizing Soviet-era accounting and customer management workflows. Cloud-based and SaaS installations represent the fastest-expanding deployment mode as Rostelecom and regional data center operators expand certified facility capacity. Government customer type segments command premium pricing due to mandatory security clearance requirements and localized development obligations.
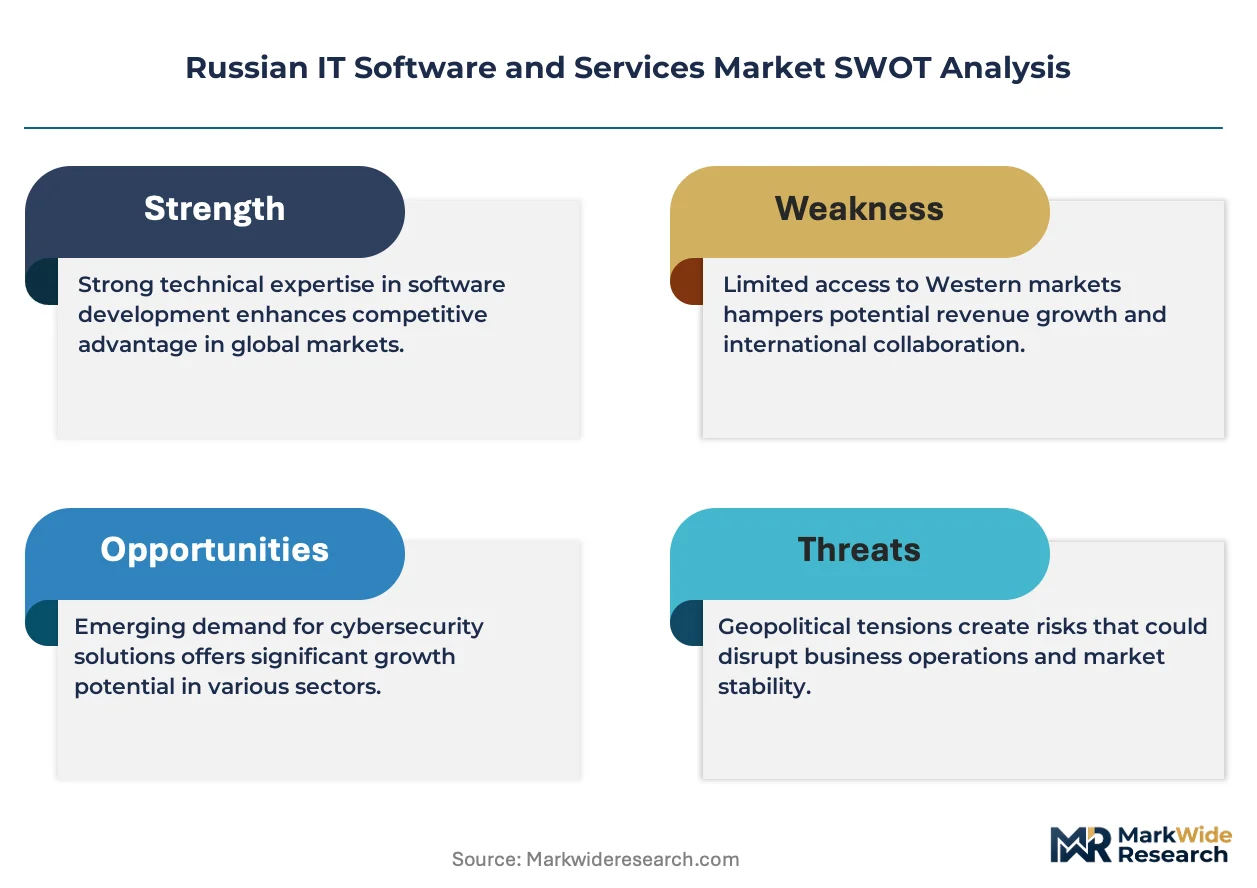
FSTEC certification requirements and the Russian Data Localization Law shape vendor eligibility for public procurement, forcing foreign suppliers to establish domestic legal entities and technical infrastructure. The Central Bank of Russia's cybersecurity mandates for financial institutions dictate software procurement standards across payment processing, risk management, and customer authentication systems. Industry participants must monitor evolving procurement quota requirements for domestic software in state contracts and assess technical debt migration paths from deprecated Western platforms.
Market Dynamics
FSTEC certification mandates and data localization statutes are forcing procurement rewrites across Russia's banking, defense, and energy verticals. Domestic vendors capture state contracts through compliance-first positioning, while foreign suppliers retreat or restructure through local legal entities.
Growth Catalysts
- Import Substitution Quotas:Public sector procurement rules mandate minimum domestic software shares in state contracts, redirecting budget flows toward certified local developers.
- Core Banking Modernization:Russian financial institutions replace legacy Soviet-era platforms with domestically developed core systems to meet Central Bank cybersecurity mandates.
- Cloud Infrastructure Expansion:Rostelecom and regional operators build certified data center capacity, enabling SaaS deployment for security-sensitive government clients.
Market Restraints
- Semiconductor Access Constraints:Advanced chip procurement restrictions limit hardware performance for encryption-intensive database and security applications.
- Technical Debt Burden:Legacy COBOL and mainframe systems in state enterprises require costly parallel-run migrations that stretch implementation timelines.
- Localization Compliance Costs:FSTEC certification processes impose multi-quarter approval cycles and mandatory domestic code audits that inflate vendor operating expenses.
Strategic Opportunities
- Siberian Data Center Cluster:Cold climate and stranded energy assets in Irkutsk and Krasnoyarsk regions attract hyperscale facility investment for compute-intensive workloads.
- Quantum-Resistant Cryptography:Post-quantum algorithm development creates first-mover positioning for vendors serving defense and nuclear energy certification requirements.
- Edge Computing Integration:Distributed processing architectures address latency constraints in Far Eastern and Arctic territories with limited backbone connectivity.
Industry Challenges
- Systems Integration Talent Scarcity:Shortage of engineers certified in both legacy Soviet protocols and modern container orchestration platforms delays enterprise deployments.
- Interoperability Friction:Proprietary domestic cryptographic modules create integration barriers with remaining Western hardware and software components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russian IT Software and Services Market |
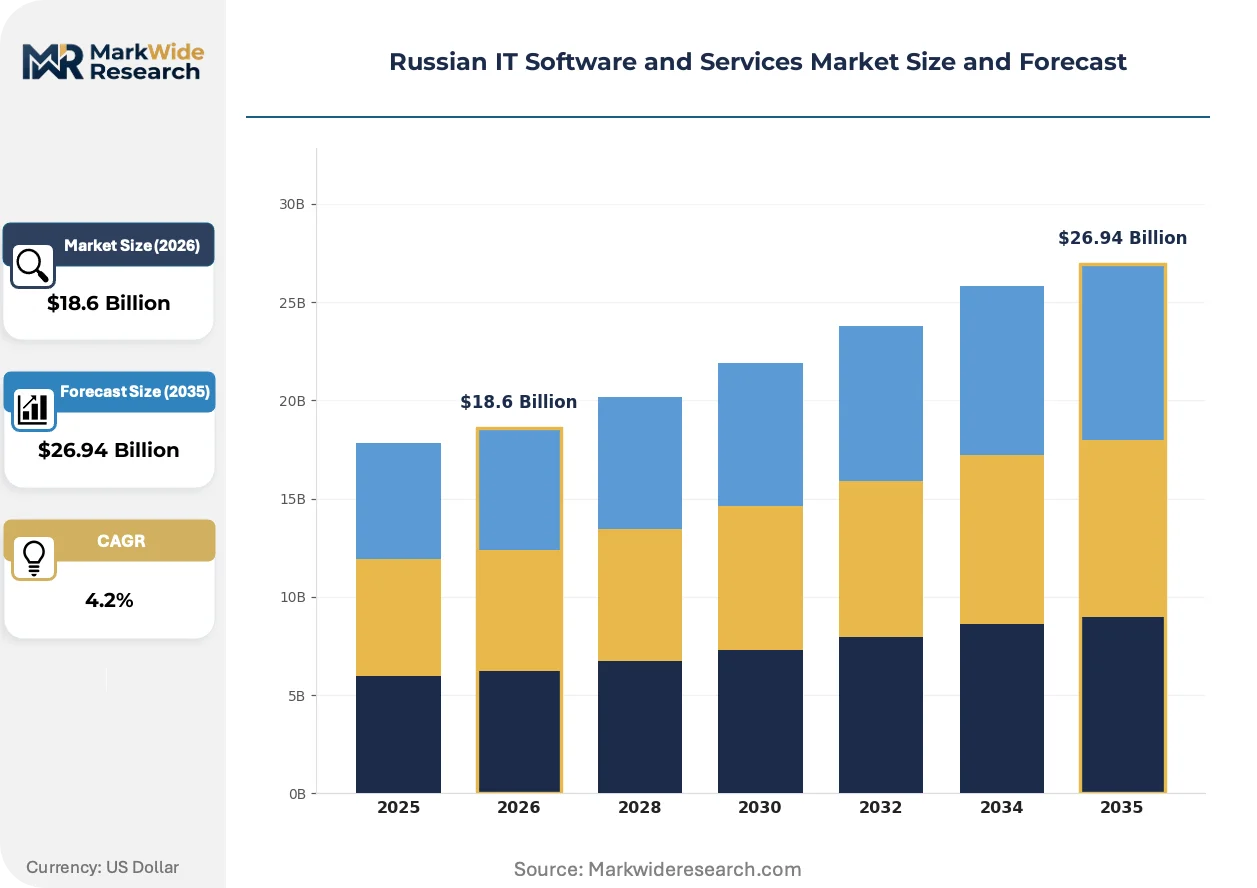
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ERP, CRM, SCM, HCM Installation: On-Premises, Cloud-Based, Hybrid, SaaS Customer Type: SMEs, Large Enterprises, Government, Startups Service Type: Consulting, Support, Development, Training |
| Companies Covered | РЕЛЭКС, Notamedia, Yandex, Heads and Hands, Plavno, VK Company, Infomatika, INOSTUDIO, Digital Design, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russian IT Software and Services Market Evolving Landscape
Deployment architectures and vendor business models are transforming as state buyers demand sovereign control over data and processing infrastructure. Three interconnected developments are compressing traditional procurement cycles.
Confidential computing enclaves are electrifying security architecture design across defense and financial services deployments. State-owned enterprises pilot trusted execution environments for multi-tenant cloud workloads. This hardware-based isolation is compressing vendor qualification timelines by satisfying FSTEC requirements without full infrastructure audits.
The Central Bank's cybersecurity mandates for payment systems are rewriting software procurement standards across retail banking and fintech segments. Technical specifications now require domestic cryptographic modules and source code escrow arrangements. Tier-one banks respond by consolidating vendor relationships around certified platform providers with established FSTEC track records.
Subscription licensing for enterprise resource planning modules is displacing perpetual license sales in state-owned enterprise procurement. Annual recurring revenue models align vendor incentives with long-term implementation success rather than upfront delivery. This shift is most visible in Moscow and St. Petersburg municipal administration contracts, where total-cost-of-ownership calculations now dominate vendor selection criteria.
Russian IT Software and Services Market Segmentation
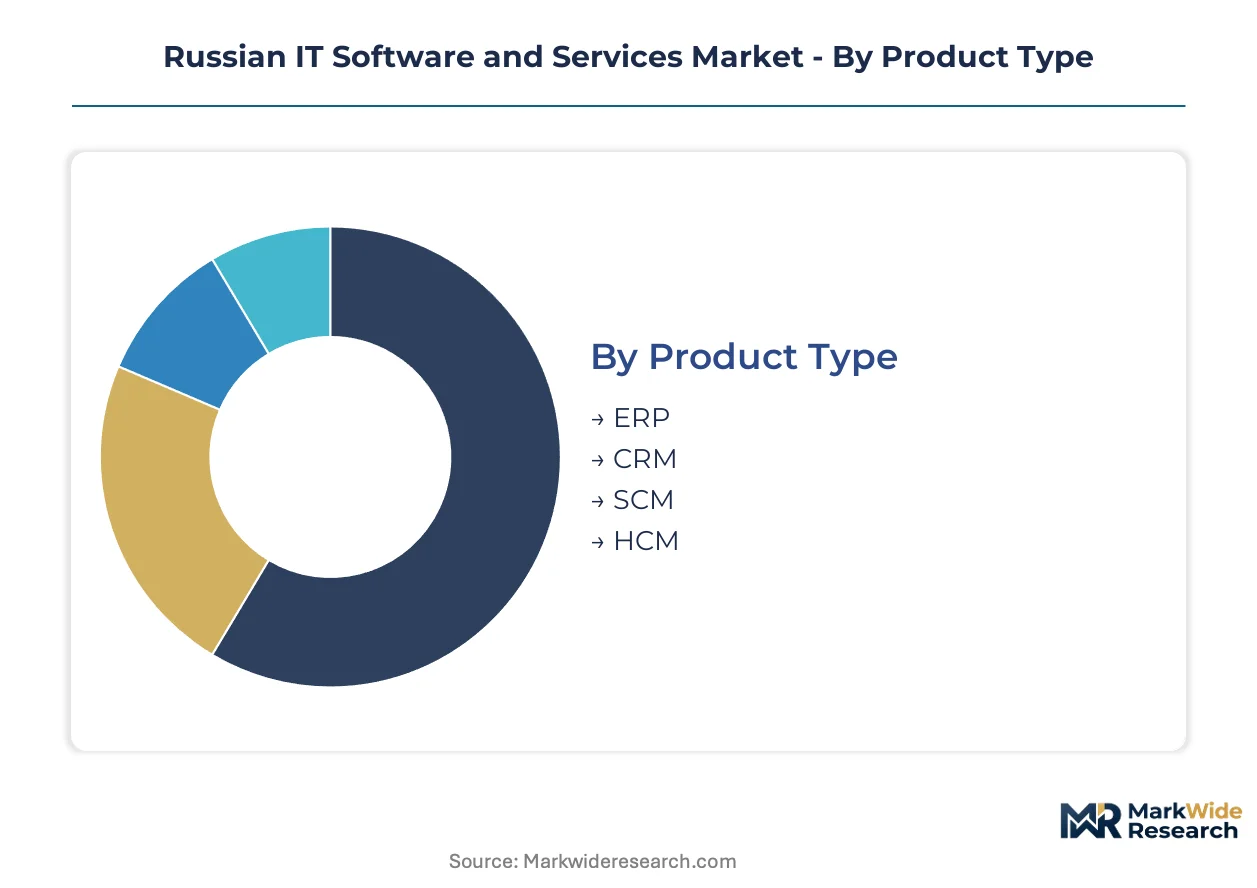
Segmentation in the Russian IT software and services market reveals how procurement rules and technical requirements fragment demand across compliance tiers. FSTEC certification obligations and data localization mandates create distinct purchasing behaviors that vendors must address through specialized positioning.
Product Type:
Standalone enterprise platforms dominate procurement budgets while embedded modules integrate into broader system architectures.
- ERP:Enterprise resource planning platforms consolidate financial, supply chain, and human capital workflows into unified databases. State-owned enterprises in Moscow and St. Petersburg drive replacement demand as Soviet-era accounting systems reach end-of-life. Core banking modernization at Sberbank and VTB accelerates procurement of domestic ERP stacks with FSTEC-certified cryptographic modules.
- CRM:Customer relationship management systems manage sales pipelines, service tickets, and marketing automation for regulated industries. Russian retail banks prioritize CRM replacements to comply with Central Bank data localization mandates for customer records. Yandex and VK Company capture municipal administration contracts through sovereign cloud deployment options.
- SCM:Supply chain management software optimizes procurement, logistics, and inventory coordination across distributed operations.
- HCM:Human capital management platforms automate payroll, recruitment, and workforce analytics for compliance-heavy employers.
ERP leads volumes today; CRM is gaining share fastest.
Installation:
Deployment architecture selection hinges on data sovereignty requirements and latency sensitivity across Russia's vast territory.
- On-Premises:Self-managed infrastructure within organizational facilities maintains complete operational control over sensitive data. Defense contractors and nuclear energy facilities mandate on-premises deployment to satisfy air-gapped security requirements. РЕЛЭКС database installations at Rosatom facilities exemplify this pattern.
- Cloud-Based:Third-party hosted infrastructure delivers elastic compute and storage without capital expenditure. Rostelecom's certified data centers in Moscow, Kazan, and Novosibirsk enable government clients to meet data localization law while accessing scalable resources. State-owned enterprises pilot confidential computing enclaves to compress FSTEC qualification timelines.
- Hybrid:Mixed deployment combines on-premises control for sensitive workloads with cloud burst capacity for variable demand.
- SaaS:Software-as-a-service subscriptions deliver fully managed applications through browser interfaces with minimal IT overhead.
On-Premises retains the largest installed base; Cloud-Based is expanding most quickly.
Customer Type:
Budget scale and compliance burden create four distinct purchasing profiles with divergent vendor selection criteria.
- SMEs:Small and medium enterprises prioritize cost efficiency and rapid deployment over deep customization. Regional banks and retail chains outside Moscow adopt SaaS CRM and HCM modules to avoid infrastructure investment. Subscription licensing aligns vendor incentives with implementation success.
- Large Enterprises:Major corporations demand extensive integration with legacy systems and dedicated support relationships. Industrial conglomerates in the Urals and Volga regions modernize Soviet-era COBOL platforms through phased ERP migrations. Technical debt burdens stretch implementation timelines across multi-year contracts.
- Government:Public sector procurement operates under mandatory domestic software quotas and security clearance requirements.
- Startups:Early-stage technology companies favor agile development tools and consumption-based pricing models.
Large Enterprises command the highest contract values; Government segments show the steepest expansion trajectory.
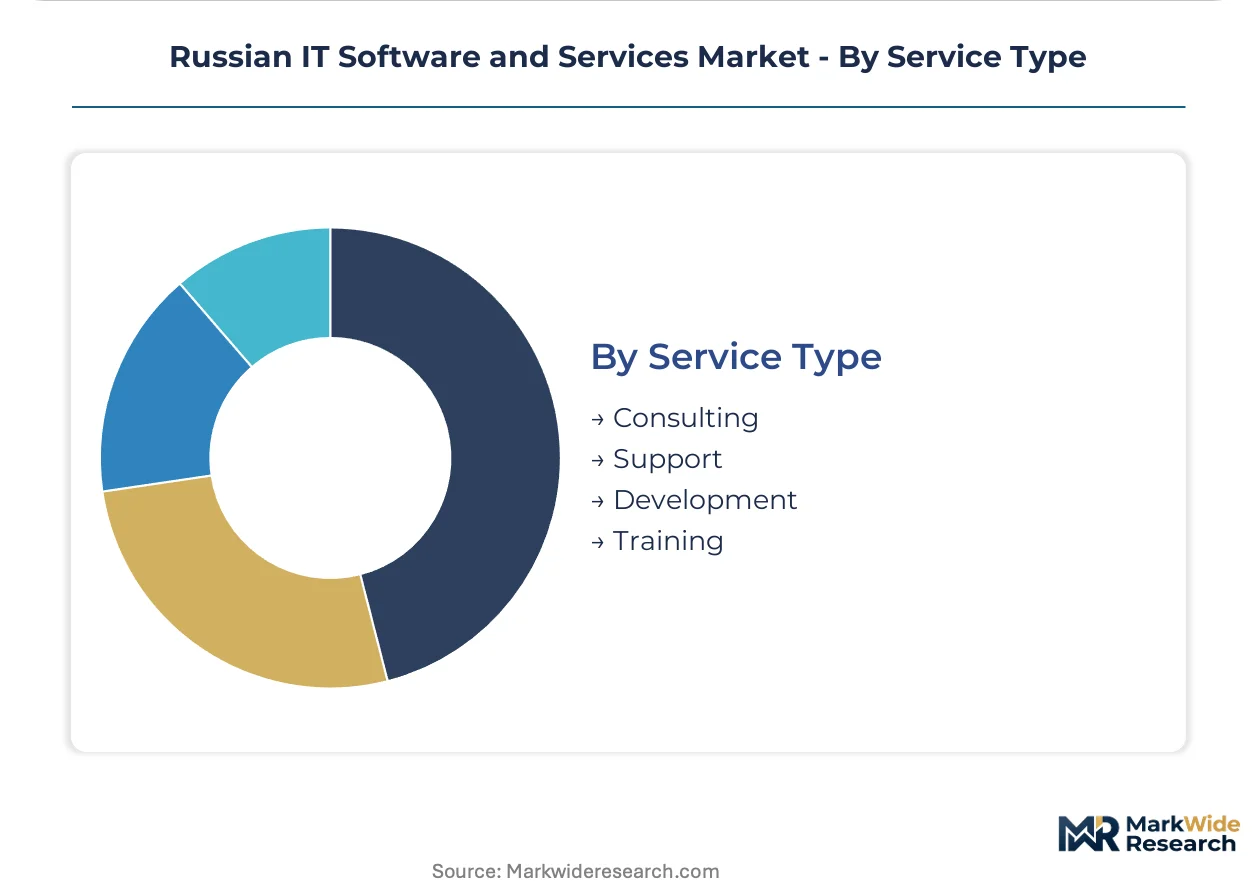
Service Type:
Value capture shifts from perpetual licenses toward ongoing operational support as subscription models mature.
- Consulting:Advisory services guide system selection, process redesign, and change management for complex transformations. Systems integration talent scarcity in container orchestration and legacy Soviet protocols delays enterprise deployments. Moscow-based consultancies recruit certified engineers at premium rates.
- Support:Technical assistance, patch management, and incident resolution ensure operational continuity. Tier-one banks consolidate vendor relationships around certified platform providers with established FSTEC track records. Annual recurring revenue models align incentives with long-term success.
- Development:Custom application engineering addresses gaps between standard products and specialized requirements.
- Training:Knowledge transfer programs build internal capability for system administration and user adoption.
Support generates the most predictable revenue streams; Consulting commands the highest margins.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's enterprise software procurement dwarfs Poland's public sector IT budgets, yet both operate under distinct regulatory frameworks that shape vendor eligibility and contract structures.
Moscow
Sberbank and VTB drive core banking platform replacements under Central Bank cybersecurity mandates. The capital's municipal administration contracts prioritize FSTEC-certified vendors with sovereign cloud deployment options. Yandex anchors public sector deals through data sovereignty-compliant infrastructure.
St. Petersburg
Industrial conglomerates modernize Soviet-era COBOL systems through phased ERP migrations. The Northwestern Federal District hosts defense contractors requiring air-gapped installations. VK Company captures municipal CRM contracts through government-approved software directories.
Novosibirsk
Rostelecom's certified data center enables SaaS deployment for Siberian government clients. The Akademgorodok technology cluster supplies systems integration talent for container orchestration platforms. Regional banks adopt cloud-based HCM modules to avoid infrastructure capital expenditure.
Kazan
The Tatarstan republic's IT park attracts hyperscale facility investment for compute-intensive workloads. Local developers serve state-owned enterprises with hybrid deployment architectures. Confidential computing enclaves pilot here to compress FSTEC qualification timelines.
Irkutsk
Cold climate and stranded hydroelectric assets position the region for energy-efficient data center clusters. Nuclear energy facilities mandate РЕЛЭКС database installations with high-assurance security protocols. Edge computing architectures address latency constraints in Far Eastern territories.
Russian IT Software and Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with compliance-first domestic vendors capturing state contracts while foreign suppliers retreat or restructure through local legal entities. The vendor base concentrates around three tiers: platform providers with FSTEC certification track records, systems integrators bridging legacy Soviet protocols and modern architectures, and niche specialists serving security-critical installations. Consolidation pressures favor vendors with established relationships at Sberbank, VTB, and Rostelecom. Strategic moves center on M&A to acquire scarce container orchestration talent and partnerships with regional data center operators to expand certified facility footprint.
Within the platform provider tier, Yandex exemplifies infrastructure-anchored positioning through its cloud stack, while VK Company occupies a diversified role across social, gaming, and enterprise communication layers. РЕЛЭКС represents the high-assurance specialist archetype, with its database systems dominating defense and nuclear energy certification requirements. These three anchors illustrate how compliance capabilities, infrastructure control, and vertical specialization determine contract access under Russia's procurement rules.
| Leading Market Players |
|---|
| РЕЛЭКС |
| Notamedia |
| Yandex |
| Heads and Hands |
| Plavno |
| VK Company |
| Infomatika |
| INOSTUDIO |
| Digital Design |
| Others |
Value Network & Pricing Analysis
FSTEC certification requirements gate both qualified vendor supply and premium-tier pricing access in Russia's IT software market, forcing procurement officers to pay compliance premiums for security-cleared solutions while restricting contract eligibility to domestic developers with approved cryptographic modules. State-owned enterprises and defense contractors absorb these cost premiums as mandatory operational expenditures, creating a bifurcated market where certified vendors capture government margins while uncertified competitors compete on price for commercial segments.
Pricing Analysis
Capacity additions in Moscow and Kazan are reshaping price floors for cloud-based ERP and CRM deployments as Rostelecom and regional operators expand certified data center footprint. Subscription-based SaaS licensing dominates state procurement, with pricing stratifying across FSTEC certification tiers, customization depth, and sovereign cloud deployment options. Cost compression in the SME segment intensifies as Yandex and VK Company compete for municipal administration contracts through standardized subscription tiers. Government buyers show lowest price sensitivity due to mandatory security requirements, while regional banks and retail chains outside major metros drive hardest bargain negotiations.
Supply Chain Analysis
Direct-to-government channels handle hyperscale procurement demand from Sberbank, VTB, and Rostelecom, bypassing traditional systems integrators for core platform acquisitions. Software development capacity concentrates in Russia, with limited spillover to Belarus and Armenia for engineering talent augmentation. Critical dependencies include domestic cryptographic module suppliers, FSTEC-certified code audit firms, and regional data center operators with sovereign facility status. Single-source vulnerability runs through the narrow base of FSTEC-accredited certification bodies, where multi-quarter approval queues create procurement bottlenecks for security-critical installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's IT software market offers margin expansion potential as import substitution mandates compress competitive intensity for certified vendors while subscription models lengthen customer lifetime value. Technical debt migration from Soviet-era platforms sustains implementation demand across state-owned enterprises regardless of macroeconomic conditions.
For Market Incumbents: To counter semiconductor access constraints limiting encryption performance, anchor defensive positioning through backward integration into domestic cryptographic module development and exclusive partnerships with Rostelecom for certified cloud capacity. Deepen FSTEC certification track records at Sberbank and VTB to create switching costs that lock out emerging competitors from core banking modernization cycles.
For New Entrants and Emerging Players: Enter via municipal administration SaaS contracts in secondary cities where Yandex and VK Company maintain lighter presence, targeting Irkutsk and Krasnoyarsk regions with edge-computing architectures that address Far Eastern latency constraints. White-space opportunity concentrates in quantum-resistant cryptography development for defense and nuclear energy certification requirements, where first-mover positioning remains unclaimed.
For Investors and Strategic Acquirers: Roll-up economics work for container orchestration specialists because systems integration talent scarcity in legacy Soviet protocols and modern Kubernetes platforms stretches enterprise deployment timelines and inflates billable rates. Target acquisition archetypes include mid-tier consultancies with FSTEC-certified engineering benches and regional data center operators with sovereign facility status. Monitor Central Bank cybersecurity mandate expansion into retail banking segments as inflection signal for core banking platform replacement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates vendor relationships around FSTEC-certified providers with established Sberbank track records. |
| Acquisition of Specialist Firm | Captures scarce container orchestration talent to bridge legacy COBOL systems and modern cloud architectures. |
| Strategic Partnership | Aligns with Rostelecom's certified data center expansion to secure sovereign cloud deployment eligibility. |
| Product Launch | Introduces quantum-resistant cryptography modules targeting Rosatom and defense certification requirements. |
| Geographic Expansion | Establishes Siberian engineering presence to serve Irkutsk and Krasnoyarsk data center clusters. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with CTOs at tier-one banks, IT procurement officers at state-owned enterprises, platform engineers at Yandex and VK Company, FSTEC certification consultants, and regional data center operators with secondary validation against SEC filings, Rostelecom capex disclosures, Central Bank regulatory circulars, and customs data on semiconductor imports. Bottom-up deployment forecasts triangulated against top-down IT spending projections from public sector budget disclosures.
Historical reference periods anchored the projection horizon through verified installation data across on-premises, cloud-based, hybrid, and SaaS deployment modes, with segmentation modeling covering product type, installation architecture, customer scale tier, and service delivery model. CAGRs derived from curve-fitting verified contract values against procurement pipeline visibility, incorporating import substitution quota enforcement timelines and core banking modernization cycle phasing at Sberbank and VTB as industry-specific forecast inputs.
Inputs from Central Bank regulatory filings and regional procurement databases were available through the study window; gaps in classified defense sector contract values introduce uncertainty bands around security-critical installation estimates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Real-Time Voice Changing Software Market
Software & Services
Global Church Management Software Market
Software & Services
Disk Space Analyzer Software Market
Software & Services
Global HMI Software Market
Software & Services
Global Knowledge Management Software Market
Software & Services
Global Idea Management Software Market
Software & Services
Custom Software Development Market
Software & Services
Global MSP Software Market
Software & Services
Digital Customer Onboarding Software Market
Software & Services
Global Document Control Software Market
Software & Services
Deck Software Market
Software & Services
Electronic Batch Records Market
Software & Services
Europe Application Modernization Services Market
Software & Services
Lab Automation Software Market
Software & Services
Enterprise Capture Software Market
Software & Services
Global App Store Optimization Tools Software Market