
 Remote Desktop Software Market | 2026-2036
Remote Desktop Software Market Size, Share, and Industry Trends Forecast 2026-2036
Remote Desktop Software Market Analysis
Channel partnerships between remote desktop vendors and managed service providers is fragmenting as direct-to-enterprise sales gain share. TeamViewer anchors its position through deep integration with industrial IoT platforms and OEM licensing. Splashtop competes aggressively on price-performance for media and creative workstation access. LogMeIn sustains brand recognition in North America through its legacy remote support heritage and channel density.
Remote desktop software enables real-time screen sharing, input redirection, and session management across geographically separated computing devices, typically operating over encrypted transport protocols with latency thresholds below 150 milliseconds for interactive usability. Cloud-based deployment leads volume adoption as SMEs abandon on-premises gateway maintenance, while hybrid architectures capture margin pools from enterprises requiring air-gapped failover. Subscription business models dominate recurring revenue, though pay-per-use structures are expanding among seasonal and project-based users.
FCC guidelines on broadband quality and net neutrality shape last-mile performance expectations for remote desktop sessions across the United States. GDPR and the EU AI Act impose data residency, breach notification, and automated decision-making transparency requirements on European deployments. NIS2 expands incident reporting obligations for critical infrastructure operators using remote access tools. Stakeholders must evaluate zero-trust architecture mandates and quantum-resistant encryption timelines when selecting platform vendors and deployment configurations.
Market Dynamics
Zero-trust security mandates are compressing deployment timelines as enterprises replace legacy VPN gateways with session-based remote access architectures that enforce continuous authentication and least-privilege access controls.
Growth Catalysts
- EU NIS2 Directive:Critical infrastructure operators across Germany, France, and Italy must upgrade remote access tooling to meet mandatory incident reporting and supply chain security requirements, forcing replacement cycles.
- Healthcare telemedicine infrastructure:Hospital IT departments are provisioning persistent remote desktop capacity for distributed clinical staff and specialist consultations, creating sustained procurement demand.
- GPU virtualization:Media production houses and architecture firms are deploying high-fidelity remote workstation access to centralize render farms and reduce endpoint hardware expenditure.
Market Restraints
- Latency physics:Interactive desktop sessions require sub-150 millisecond round-trip times, excluding satellite-dependent and rural broadband markets from viable deployment.
- Certificate authority concentration:Browser vendors and operating system maintainers control root certificate trust stores, creating gatekeeper risk for niche remote desktop protocol implementations.
- Quantum decryption timeline:NIST post-quantum cryptography migration deadlines are compressing encryption refresh cycles and straining R&D budgets for smaller protocol vendors.
Strategic Opportunities
- India manufacturing digitization:PLI scheme beneficiaries are modernizing shop-floor access for equipment vendors and quality auditors, opening greenfield remote maintenance deployments.
- Edge-to-cloud session brokering:Converging 5G network slicing with containerized remote desktop brokers enables sub-50 millisecond latency for autonomous vehicle teleoperation and surgical robotics.
- GDPR Article 32 compliance services:Managed security providers are bundling data residency verification and breach notification automation as premium remote desktop add-ons.
Industry Challenges
- Zero-trust architecture skill scarcity:Enterprise security teams lack sufficient identity engineering and microsegmentation expertise to configure modern remote access policies correctly.
- Legacy Active Directory entanglement:Decades-old group policy and Kerberos configurations resist migration to cloud-native identity platforms, prolonging hybrid complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Remote Desktop Software Market |
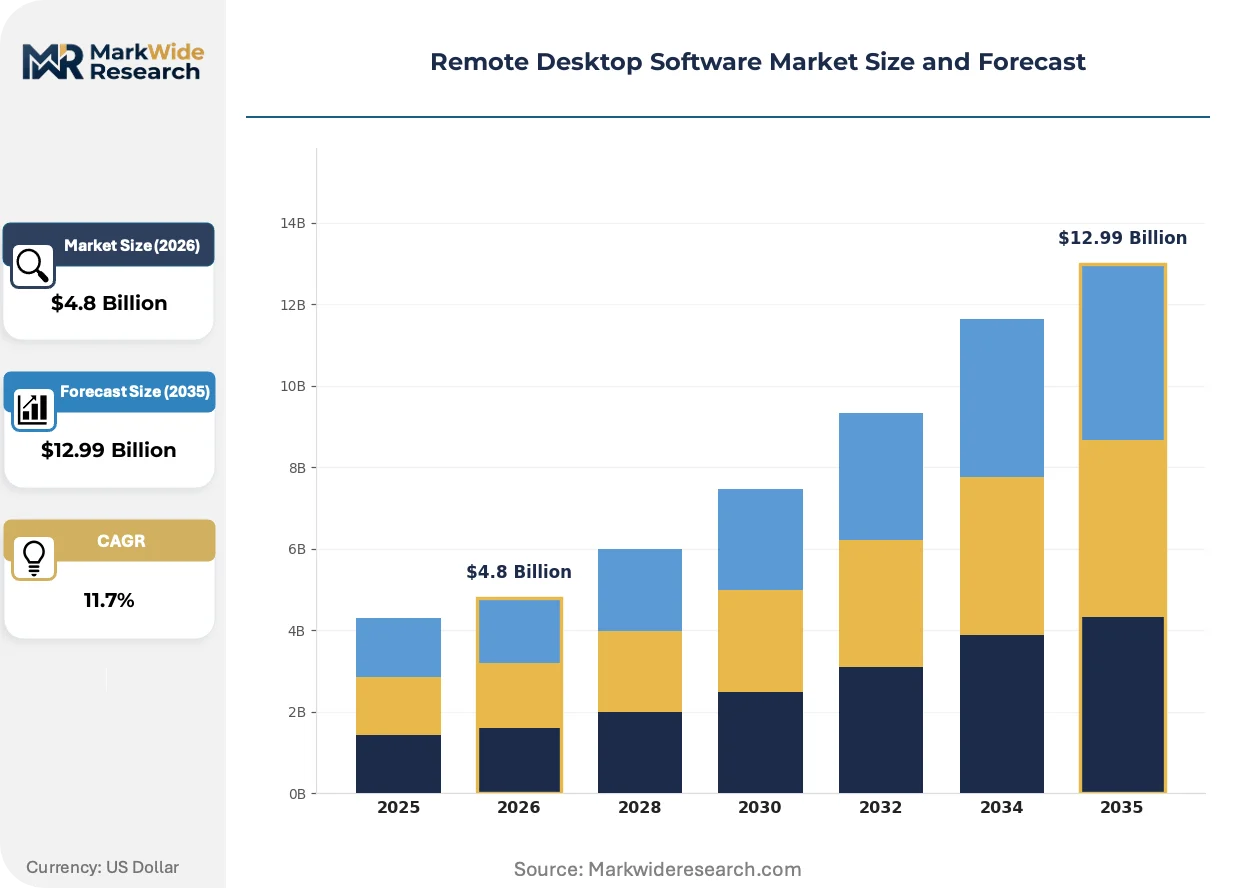
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-Based, On-Premises, Hybrid, Managed Services End User: SMEs, Enterprises, Government Agencies, Educational Institutions Features: File Transfer, Multi-Platform Support, Remote Printing, Session Recording Business Model: Subscription, One-Time License, Freemium, Pay-Per-Use |
| Companies Covered | LogMeIn, GoTo Resolve, Splashtop, NinjaOne, Freshdesk, RemotePC, Zoho Assist, RemoteToPC, TeamViewer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Remote Desktop Software Market Emerging Trajectories
Remote desktop platforms are absorbing adjacent security and collaboration functions as vendors compete to own the complete distributed workforce infrastructure stack rather than remain point solutions.
GPU virtualization is virtualizing workstation-class graphics pipelines by encoding framebuffer deltas at the host and streaming compressed video streams to thin clients. Engineering firms and visual effects studios are adopting this architecture aggressively to consolidate hardware spend. The technology is virtualizing the traditional one-to-one workstation assignment model, compressing capital intensity for compute-heavy verticals.
EU AI Act algorithmic transparency requirements are mandating documentation of automated decision-making in remote session monitoring and anomaly detection systems. Vendors serving European enterprises must now maintain technical files explaining how AI-driven access scoring functions. Healthcare and financial services deployments face the steepest compliance burden, with German operators already engaging notified bodies for conformity assessment.
Consumption-based licensing is displacing seat-count subscriptions among project-based creative agencies and seasonal tax preparation firms. Channel partners are unbundling implementation and support services from software fees to capture margin from this flexibility. The shift is most visible in North American professional services verticals where headcount fluctuates by forty percent across quarterly cycles.
Remote Desktop Software Market Segmentation
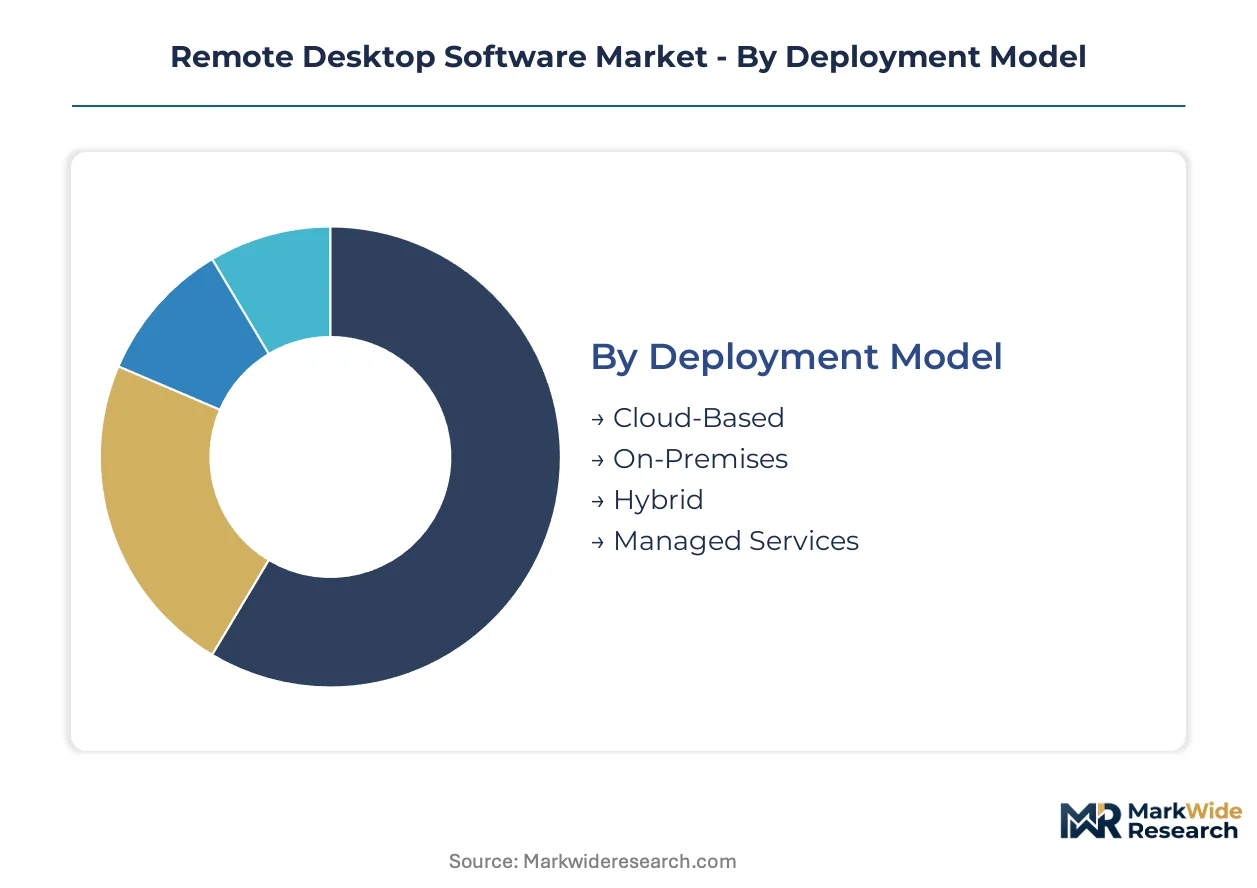
Remote desktop software vendors structure product portfolios around deployment complexity, organizational scale, and consumption economics. Each segmentation dimension carries distinct margin profiles and competitive dynamics that shape vendor resource allocation.
Deployment Model:
Use-case spectrum spans from fully managed cloud consumption to air-gapped industrial installations with strict data sovereignty requirements.
- Cloud-Based:Browser-delivered sessions eliminate gateway infrastructure maintenance. Healthcare networks in Germany and France are migrating clinical workstation access to cloud brokers to satisfy GDPR data residency through EU-zone hosting.
- On-Premises:Self-hosted session brokers run inside organizational firewalls with direct control over encryption key management. Defense contractors and German Mittelstand manufacturers retain this architecture for operational technology segmentation.
- Hybrid:Split configurations route internal sessions through on-premises gateways while external access traverses cloud relays. Enterprises with legacy Active Directory entanglements deploy hybrid stacks to phase cloud identity migration.
- Managed Services:Third-party providers assume full infrastructure responsibility including patch management and certificate rotation. Channel partners in North America bundle managed services with consumption-based licensing for seasonal professional services firms.
The dominant share belongs to Cloud-Based deployment, while Hybrid is closing the gap fastest among enterprises navigating zero-trust transitions.
End User:
Customer type determines feature depth, security certification requirements, and procurement cycle length.
- SMEs:Organizations under 500 employees favor subscription simplicity over customization. Cloud-native vendors capture this segment through self-service provisioning and per-seat pricing without minimum commitments.
- Enterprises:Complex identity federation and session audit requirements demand dedicated customer success engineering. German automotive suppliers and US financial institutions drive enterprise RFP volume with mandatory SOC 2 Type II and ISO 27001 attestations.
- Government Agencies:FedRAMP, ITAR, and national encryption standards constrain vendor eligibility. US federal deployments require US-person data handling and domestic cloud regions exclusively.
- Educational Institutions:Semester-based demand patterns and stretched IT budgets favor site licensing and seasonal suspension options. University systems in India and Brazil are expanding remote lab access for distributed student populations.
Enterprises command the largest revenue pool per account, though SMEs collectively generate higher absolute subscription volume through broader vendor penetration.
Features:
Capability bundling separates commodity remote access from premium workforce infrastructure platforms.
- File Transfer:Drag-and-drop and clipboard synchronization enable workflow continuity across separated devices. Media production houses in Los Angeles and London demand high-bandwidth transfer pipelines for uncompressed video assets.
- Multi-Platform Support:Native clients for Windows, macOS, Linux, iOS, and Android maximize endpoint flexibility. Bring-your-own-device policies in Indian IT services firms require comprehensive mobile support.
- Remote Printing:Local printer redirection preserves document workflow without file staging. German legal and accounting partnerships maintain remote printing for confidential client matter handling.
- Session Recording:Full motion capture with searchable metadata supports compliance audit and security investigation. Financial services regulators in Singapore and Hong Kong mandate session recording for trader surveillance.
Multi-Platform Support has become table stakes, while Session Recording carries the steepest premium pricing due to storage and indexing infrastructure costs.
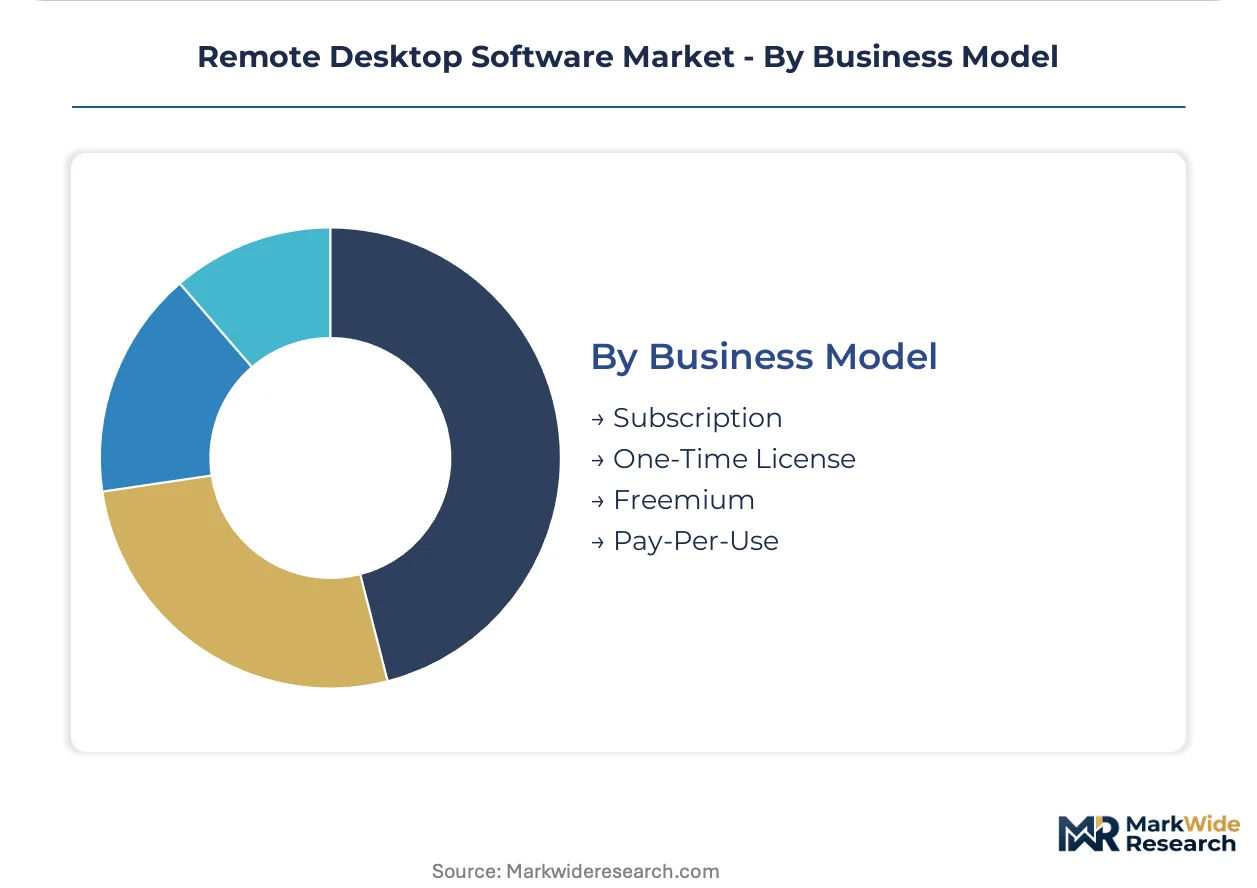
Business Model:
Revenue structure alignment with customer cash flow patterns determines contract closure rates and churn exposure.
- Subscription:Monthly or annual recurring fees dominate vendor economics with predictable renewal streams. Annual prepay discounts of fifteen to twenty percent are standard across North American and European markets.
- One-Time License:Perpetual purchase with maintenance add-ons persists in air-gapped environments without internet connectivity. Russian and Chinese industrial operators favor perpetual models to isolate from vendor payment infrastructure.
- Freemium:Limited-session or single-connection tiers convert individual professionals to paid personal licenses. Freelance developers and independent consultants in Eastern European markets drive freemium-to-paid conversion pipelines.
- Pay-Per-Use:Metered consumption by session duration or data volume serves project-based organizations with volatile headcount. US tax preparation firms and Indian election campaign technology teams activate pay-per-use during peak seasonal windows.
Subscription retains structural dominance, though Pay-Per-Use is expanding most quickly among professional services verticals with forty-plus percent quarterly headcount fluctuation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The DE-CIX internet exchange in Frankfurt anchors European data traffic routing, enabling sub-50 millisecond latency benchmarks that underpin Germany's dominance in industrial remote access deployments.
United States
FCC broadband quality guidelines and net neutrality frameworks shape performance expectations for cross-country remote desktop sessions. Healthcare networks in Boston and financial services clusters in New York deploy zero-trust session brokers to satisfy HIPAA and SEC cybersecurity mandates. Silicon Valley SaaS vendors drive cloud-native remote access innovation through direct enterprise sales channels.
Germany
The EU NIS2 Directive and AI Act impose mandatory incident reporting and algorithmic transparency obligations on critical infrastructure operators. Mittelstand manufacturing networks in Baden-Württemberg and Bavaria require secure remote maintenance capabilities for industrial automation equipment. Stuttgart automotive suppliers anchor demand for air-gapped hybrid deployments with strict operational technology segmentation.
India
PLI scheme beneficiaries modernizing shop-floor access create greenfield demand for equipment vendor connectivity and quality auditor remote presence. Mumbai and Bengaluru IT services firms enforce bring-your-own-device policies requiring comprehensive multi-platform endpoint support. TRAI broadband expansion targets reduce latency barriers for tier-2 city deployments.
United Kingdom
GDPR data residency requirements and post-Brexit regulatory divergence shape cloud hosting location strategies for financial services firms. London trading floors mandate session recording for FCA compliance surveillance, driving premium feature adoption. Cambridge technology clusters incubate specialized remote workstation virtualization for media production workflows.
Japan
METI digital transformation subsidies accelerate SME cloud migration away from legacy on-premises gateway maintenance. Tokyo and Osaka manufacturing headquarters require low-latency access to Nagoya industrial equipment for remote troubleshooting. JIS standards alignment pressures vendors to certify encryption implementations for government eligibility.
Remote Desktop Software Market Vendor Landscape
On the supply side, the industry is consolidating around three distinct strategic tiers as direct-to-enterprise sales displace traditional channel intermediaries. Pure-play remote access vendors compete with converged security platforms absorbing adjacent collaboration functions. Dominant competitive moves include OEM licensing partnerships with industrial IoT platforms and consumption-based pricing unbundling to capture seasonal professional services demand.
Among established remote desktop specialists, TeamViewer anchors the industrial integration archetype through deep OEM relationships, while Splashtop occupies the price-performance position for media workstation virtualization. LogMeIn exemplifies the legacy channel density model sustaining North American brand recognition through managed service provider networks. These three representations illustrate how vendor archetypes map to distinct customer procurement patterns and margin pool capture strategies.
| Leading Market Players |
|---|
| LogMeIn |
| GoTo Resolve |
| Splashtop |
| NinjaOne |
| Freshdesk |
| RemotePC |
| Zoho Assist |
| RemoteToPC |
| TeamViewer |
| Others |
Supply Flow & Price Mechanics
DE-CIX Frankfurt traffic exchange costs compress margins for cloud-hosted session brokers serving German Mittelstand manufacturers, concentrating pricing power among vendors with captive EU-zone data centers while forcing tiered differentiation downstream.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by compliance certification and session fidelity. SOC 2 Type II attestation and ISO 27001 certification drive premium positioning for US financial institutions and German automotive suppliers, while uncertified cloud tiers compete on per-seat economics for Indian IT services firms. Pricing pressure stems from Splashtop's aggressive price-performance positioning in media workstation virtualization. SMEs exhibit highest price sensitivity, whereas government agencies accept substantial premiums for FedRAMP authorization.
Supply Chain Analysis
Contract manufacturing concentration rests with Foxconn, Quanta, and Wistron for thin client hardware supporting remote desktop endpoints. Taiwan and China anchor display panel and SoC supply, while Mexico and Vietnam expand final assembly capacity for North American delivery. Semiconductor feedstock dependencies center on TSMC-fabricated GPUs for virtualization workloads and Samsung NAND for session recording storage. Single-source vulnerability concentrates in GPU virtualization chipsets. Distribution runs through direct enterprise sales displacing managed service provider intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Managed security services bundling GDPR Article 32 compliance tools expands faster than core remote desktop licensing, creating service-attach margin pools that reshape vendor economics.
For Market Incumbents: Build switching-cost moats through deep Active Directory integration and legacy group policy entrenchment. Defensive moves center on OEM licensing partnerships with Siemens and Bosch industrial IoT platforms to lock out challenger protocols. Threat from cloud-native zero-trust alternatives demands rapid certificate authority trust store consolidation. Channel control through exclusive MSP tiering programs anchors retention. For New Entrants and Emerging Players: India's PLI scheme manufacturing digitization presents the most penetrable geographic white space, with greenfield shop-floor access deployments lacking incumbent entrenchment. Target equipment vendor remote maintenance contracts in Bengaluru and Pune automotive clusters. Consumption-based licensing for seasonal tax preparation firms offers lowest-friction go-to-market entry. For Investors and Strategic Acquirers: Specialist session recording vendors with financial services regulatory compliance DNA represent priority acquisition targets. Long-term viability hinges on quantum-resistant cryptography migration capability ahead of NIST deadlines. Watch hyperscaler remote desktop product announcements as inflection signal threatening independent vendor economics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Deep OEM partnerships with Siemens MindSphere and Bosch IoT Suite lock in industrial automation workflows. |
| Geographic Expansion | EU-zone data center buildout satisfies GDPR Article 44 transfer restrictions for German healthcare networks. |
| Product Launch | Edge-to-cloud session brokers leveraging 5G network slicing enable sub-50ms latency for surgical robotics. |
| Strategic Partnership | Managed security provider alliances bundle zero-trust architecture consulting with remote access deployment. |
| Acquisition of Specialist Firm | Session recording vendors with FCA and MAS compliance heritage capture financial services premium pricing. |
Methodological Framework
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings in observable deployment patterns. CTOs, IT procurement officers at German automotive suppliers, channel partners, and integration specialists provided operational perspective. Secondary sources include SEC 10-K disclosures, EU NIS2 implementation guidance, TRAI broadband quality reports, and hyperscaler capex announcements. Bottom-up session volume estimates triangulate against top-down enterprise software spending benchmarks.
Calibration against historical cloud migration velocity and zero-trust architecture adoption curves shapes the projection framework. Segmentation dimensions span deployment model, organization size, vertical industry, integration complexity, and regional regulatory cluster. CAGRs derive from logistic diffusion modeling of enterprise technology replacement cycles. GPU virtualization penetration rates and 5G network slicing deployment timelines constitute key forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperscaler platform entrants or quantum-resistant cryptography specialists would shift outcomes. Regulatory acceleration under EU AI Act enforcement or NIS2 penalty structures may compress upgrade timelines. Quarterly review of hyperscaler product roadmaps and notified body conformity assessment queues is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Application Performance Management (APM) Software Market
Software & Services
Global Employee Recognition Software Market
Software & Services
Global Church Management Software Market
Software & Services
Global Travel and Expense Management Software Market
Software & Services
Objectives & Key Results (OKR) Software Market
Software & Services
Terminal Emulator Software Market
Software & Services
Library Management Software Market
Software & Services
Global Journal App Market
Software & Services
Global Digital Rights Management Software Market
Software & Services
Real Estate Software Market
Software & Services
Global DevOps Software Market
Software & Services
Europe Workforce Management Software Market
Software & Services
Hadoop Market
Software & Services
Simulation Software Market
Software & Services
Cursor Reviewer Market
Software & Services
North America Workforce Management Software Market