
 Programmable Automation Controller Software Market | 2026-2036
Programmable Automation Controller Software Market Size, Share, and Industry Trends Forecast 2026-2036
Programmable Automation Controller Software Market Analytics
Small-to-mid-sized food and beverage processors is collapsing into cloud-based deployment models as legacy DCS maintenance costs spiral. Siemens AG leverages its SIMATIC portfolio to anchor European process automation accounts. Rockwell Automation, Inc. competes through FactoryTalk integrations that dominate North American automotive lines. Schneider Electric SE specializes in EcoStruxure architectures that extend its energy-management dominance into hybrid control environments.
Programmable automation controller software comprises runtime environments, engineering tools, and communication protocols that execute deterministic control logic on industrial hardware with cycle times typically below 10 milliseconds. These platforms coordinate sensors, actuators, and enterprise systems across discrete and continuous manufacturing operations. Configuration software and control software command the largest revenue pools due to entrenched replacement cycles and safety-certification lock-in. Cloud-based and edge deployment models represent the fastest-expanding segments as latency-sensitive applications migrate compute closer to physical assets.
IEC 61508 and ISA/IEC 62443 shape functional safety and cybersecurity requirements for PAC software in process industries, forcing vendors to maintain dual-certification pipelines. The EPA's Clean Air Act enforcement and OSHA process safety management standards in the United States compel oil and gas operators to upgrade legacy control systems with auditable software platforms. Stakeholders must weigh the capital efficiency of cloud-native architectures against the regulatory burden of validating safety-critical code across distributed edge nodes.
Market Dynamics
Edge-native runtime architectures are fragmenting traditional centralized control hierarchies as discrete manufacturers push deterministic logic closer to physical assets, compressing cycle times below 5 milliseconds while forcing vendors to recertify safety stacks for distributed topologies.
Growth Catalysts
- Automotive Flexible Production:German automotive OEMs around Munich and Stuttgart are procuring PAC software for reconfigurable assembly lines that switch between electric and combustion powertrains within single shifts.
- IEC 61508 Functional Safety Mandates:European and North American process industries must recertify control systems to SIL 3 standards, locking in replacement cycles for certified software platforms.
- Edge Computing Convergence:Time-sensitive networking protocols are enabling deterministic control over standard Ethernet, collapsing the hardware boundary between PLCs and industrial PCs.
Market Restraints
- Semiconductor Supply Concentration:Industrial-grade ARM and x86 processors for PAC hardware concentrate in Taiwanese and South Korean foundries, exposing lead times to geopolitical friction.
- Dual-Certification Cost Burden:Vendors must maintain parallel development pipelines for IEC 61508 safety certification and ISA/IEC 62443 cybersecurity validation, doubling engineering overhead.
- Legacy DCS Lock-in:Oil and gas operators face stranded asset risk from decades-old distributed control systems with proprietary communication protocols that resist migration.
Strategic Opportunities
- Cloud-Native Deployment White Space:Small-to-mid-sized food and beverage processors in the US Midwest are abandoning on-premise maintenance contracts for subscription-based runtime environments.
- EU Green Deal Process Optimization:Energy-intensive chemical manufacturers must install auditable control platforms to track Scope 1 emissions, creating demand for EcoStruxure-integrated PAC stacks.
- Digital Twin Convergence:Real-time physics engines from gaming and simulation software are merging with industrial control runtimes to enable virtual commissioning of production lines.
Industry Challenges
- Safety-Critical Code Validation:Distributed edge architectures complicate deterministic behavior verification across hundreds of nodes, stretching IEC 61508 audit timelines.
- OT-IT Skill Convergence:Control engineers must now secure Ethernet networks and containerized deployments, creating talent scarcity in traditional automation departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Programmable Automation Controller Software Market |
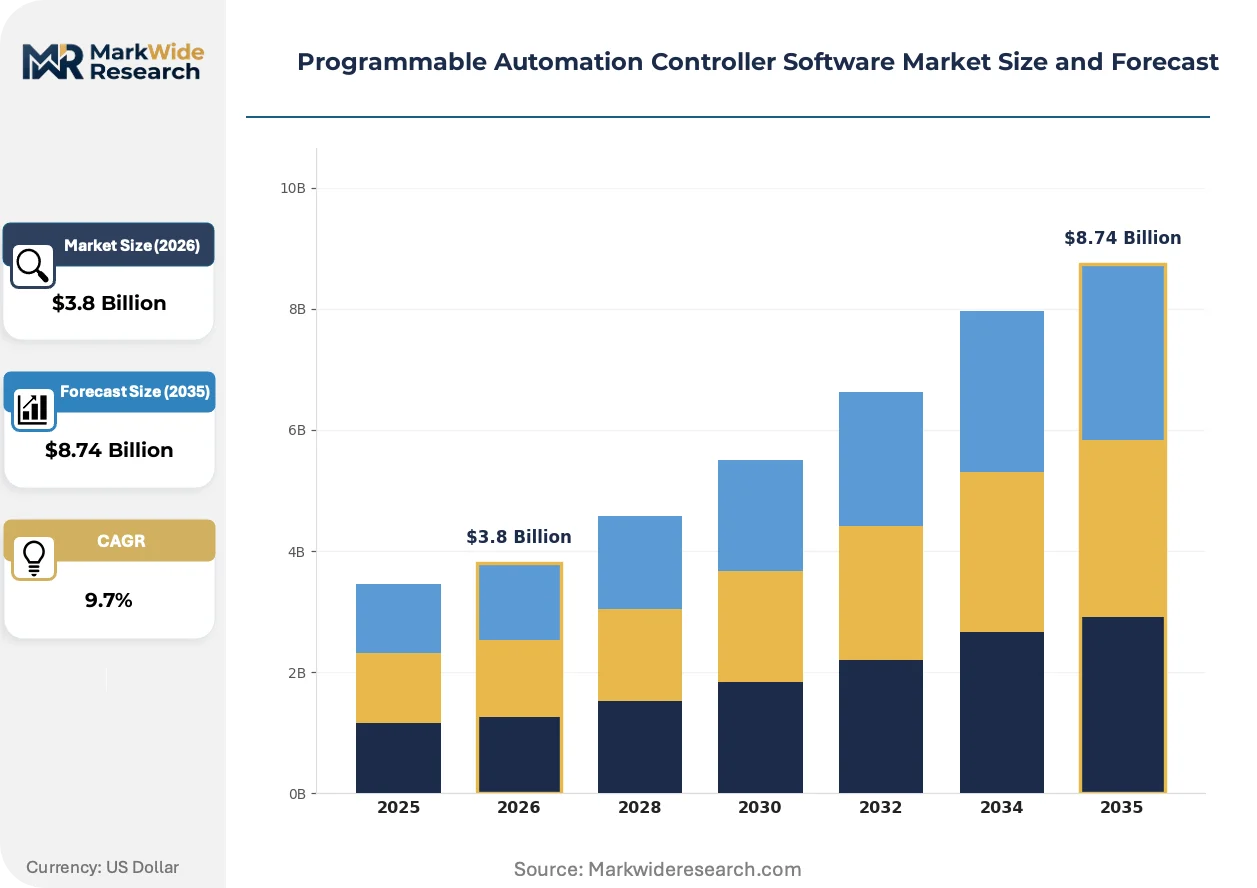
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Configuration Software, Monitoring Software, Control Software, Simulation Software Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge End User: Manufacturing, Oil & Gas, Food & Beverage, Pharmaceuticals Technology: PLC-Based, PC-Based, IPC-Based, Distributed Control Systems |
| Companies Covered | Rockwell Automation, Inc., Siemens AG, Schneider Electric SE, Mitsubishi Electric Corporation, Emerson Electric Co., ABB Ltd., Honeywell International Inc., Advantech Co., Ltd., Opto22, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Programmable Automation Controller Software Market Evolving Landscape
Deterministic control software is fragmenting into specialized runtime environments optimized for specific latency tiers, with sub-millisecond motion control separating from 10-millisecond process loops and cloud-synced supervisory layers.
Containerized control runtimes are fragmenting hardware-software coupling in discrete manufacturing. Automotive tier-one suppliers in Stuttgart are deploying Kubernetes-orchestrated control pods that migrate between edge nodes during equipment maintenance. This topology is fragmenting vendor lock-in by enabling multi-supplier software stacks on standardized industrial PCs.
REACH chemical substance restrictions and the EU AI Act are reshaping software material declarations and algorithmic transparency requirements for European process industries. PAC vendors must now document training data provenance for AI-assisted control loops. German chemical clusters are responding by demanding open-model architectures that permit regulator audit of decision logic.
Food and beverage processors are unbundling engineering tool licenses from runtime software, favoring pay-per-project configuration environments over perpetual seat agreements. Equipment OEMs in Denmark and the Netherlands are responding with token-based access models for their proprietary programming suites. This shift is most visible in dairy and brewing applications where seasonal production cycles favor variable cost structures.
Programmable Automation Controller Software Market Segmentation
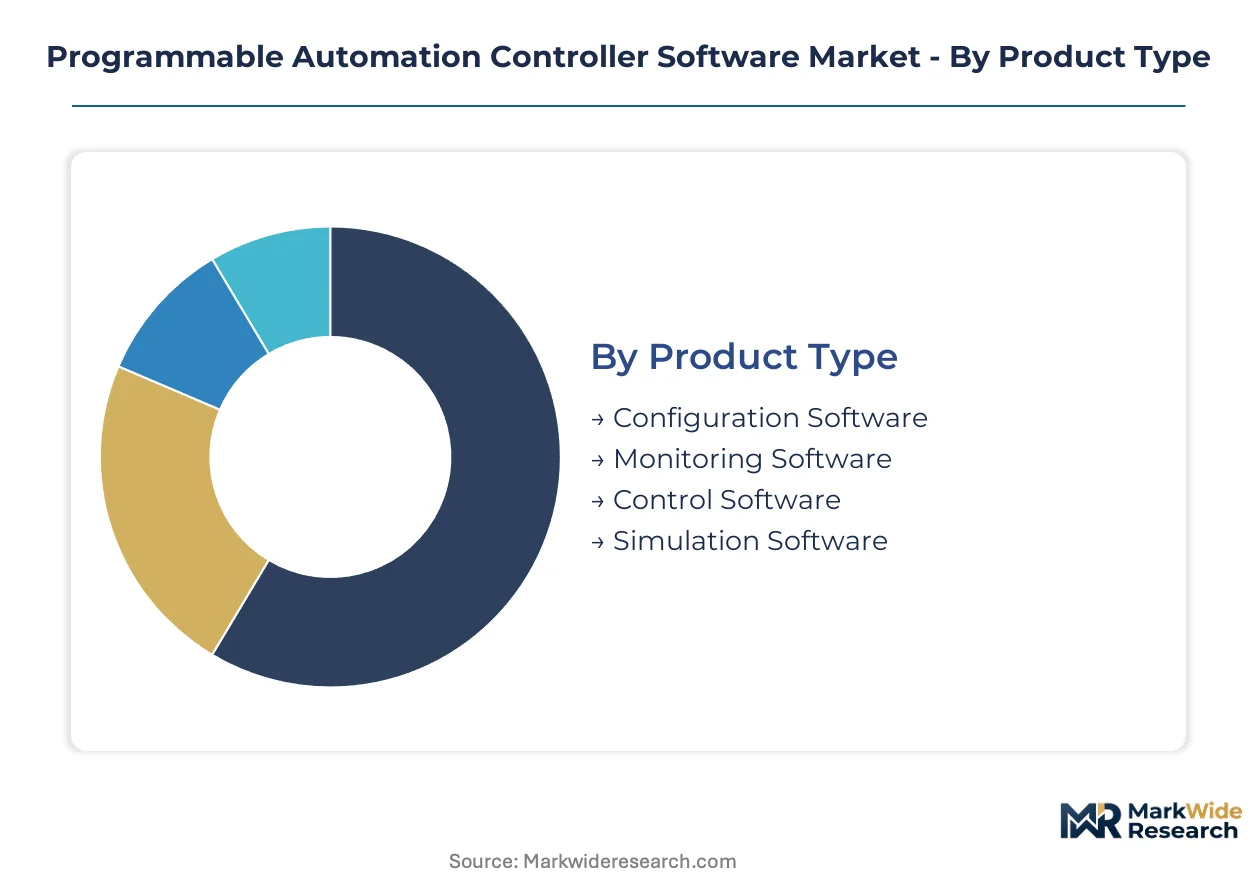
PAC software segmentation reveals distinct procurement patterns across product tiers and deployment architectures. German automotive OEMs and US Gulf Coast petrochemical operators drive divergent purchasing behaviors that reshape vendor go-to-market strategies.
Product Type:
Configuration and control software concentrate demand in domestic European accounts, while monitoring and simulation tools attract export-led procurement from Asian system integrators.
- Configuration Software:Engineering environments for logic programming and hardware commissioning dominate seat license revenue. Munich automotive suppliers consume perpetual licenses for safety-certified toolchains under IEC 61508 mandates.
- Control Software:Runtime environments executing deterministic logic with sub-10-millisecond cycle times anchor replacement cycles. Oil and gas operators on the US Gulf Coast recertify these platforms to SIL 3 standards, locking in vendor relationships.
- Monitoring Software:Visualization and alarm management layers for supervisory control.
- Simulation Software:Virtual commissioning environments for offline logic validation.
Control software holds the largest share; momentum sits with simulation software.
Deployment Model:
Edge and hybrid architectures command premium pricing from discrete manufacturers, while cloud-based deployments penetrate cost-sensitive process industries through subscription economics.
- Edge:Containerized runtimes deploy deterministic control on industrial PCs with sub-5-millisecond latency. Stuttgart automotive tier-one suppliers orchestrate these via Kubernetes for flexible production lines.
- Hybrid:Split architectures run critical loops locally while syncing analytics to cloud layers. German chemical clusters adopt these for EU Green Deal emissions tracking without sacrificing deterministic guarantees.
- On-Premises:Traditional server-based installations for air-gapped safety systems.
- Cloud-Based:Subscription runtime environments for small-to-mid-sized food processors.
On-premises retains the largest installed base; edge deployments are climbing the fastest.
End User:
Manufacturing and oil and gas sectors concentrate procurement in developed economies, while food and beverage and pharmaceuticals show geographic diffusion across emerging markets.
- Manufacturing:Discrete automation spanning automotive, electronics, and machinery production. German OEMs around Stuttgart and Munich drive flexible line reconfigurations requiring rapid software redeployment.
- Oil & Gas:Upstream and downstream process control with stringent safety requirements. US operators face EPA Clean Air Act enforcement compelling control system upgrades.
- Food & Beverage:Batch and continuous processing with seasonal demand volatility.
- Pharmaceuticals:GMP-validated control with audit trail requirements for FDA and EMA compliance.
Manufacturing commands the largest revenue pool; food and beverage shows the steepest expansion trajectory.
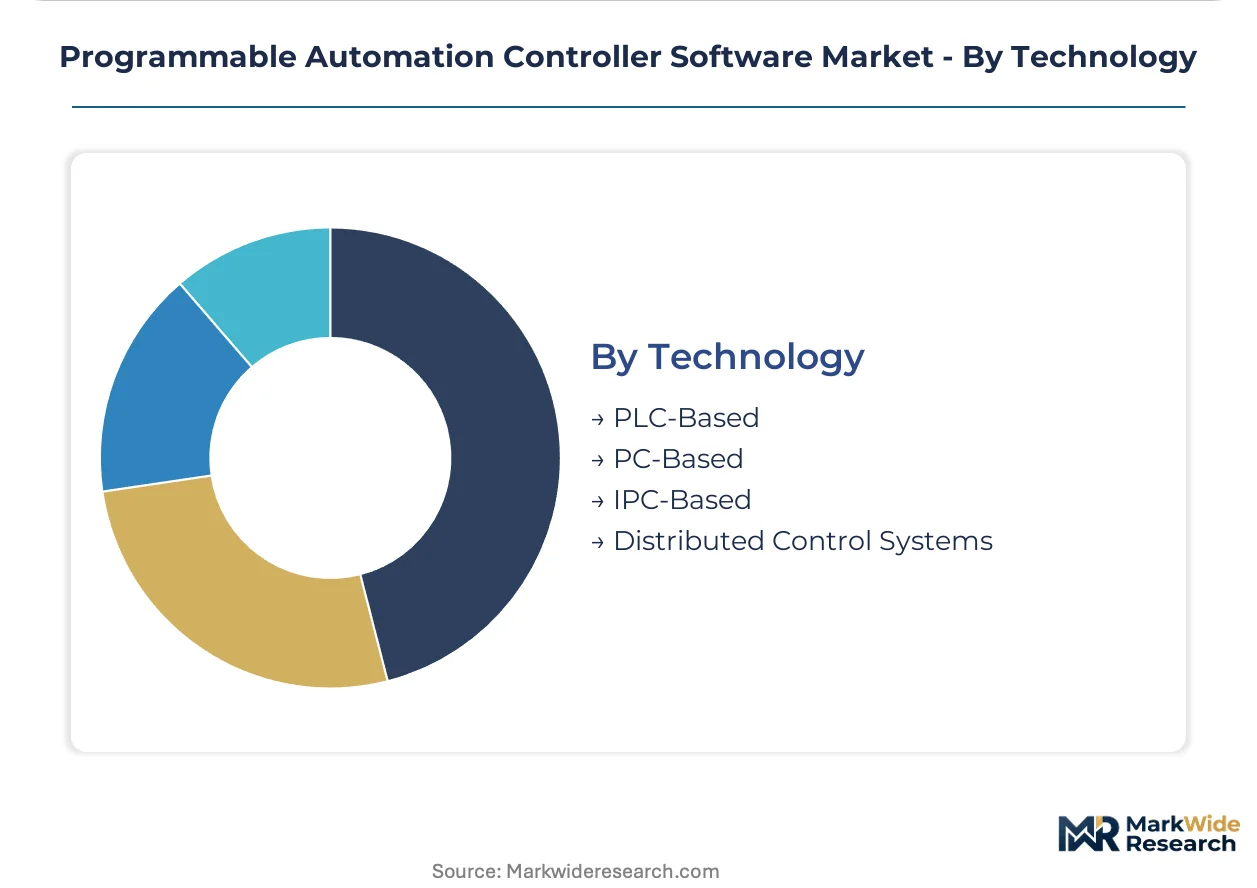
Technology:
PC-based and IPC-based platforms fragment traditional PLC strongholds, while distributed control systems retain process industry incumbency despite migration pressures.
- PLC-Based:Proprietary hardware-software stacks with embedded runtime environments. These dominate legacy automotive lines but face displacement from open industrial PC architectures.
- IPC-Based:Industrial PCs running standardized operating systems with real-time extensions. Stuttgart suppliers deploy these for Kubernetes-orchestrated control pods enabling multi-vendor software stacks.
- PC-Based:Commercial computing hardware with industrial I/O interfaces.
- Distributed Control Systems:Centralized architectures for large-scale continuous processes.
PLC-based systems retain the largest installed base; IPC-based platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's industrial corridor anchors European PAC software procurement for chemical and petrochemical automation. Germany's Rhine-Main rail freight network enables just-in-time component delivery to Stuttgart and Munich automotive clusters. The US Gulf Coast pipeline infrastructure supports petrochemical control system upgrades driven by EPA enforcement.
United States
Gulf Coast petrochemical operators and Midwest automotive manufacturers drive PAC software demand for emissions-compliant control systems. EPA Clean Air Act enforcement compels control system recertification to auditable software platforms. Houston's Energy Corridor hosts migration projects from legacy DCS architectures to hybrid edge-cloud deployments.
Germany
Automotive OEMs and chemical manufacturers procure PAC software for flexible production lines and EU Green Deal emissions tracking. IEC 61508 SIL 3 certification mandates lock in replacement cycles for safety-critical runtime environments. Stuttgart's automotive cluster deploys Kubernetes-orchestrated control pods for reconfigurable assembly lines switching between powertrain types.
China
Electric vehicle battery manufacturing and semiconductor fabrication expand demand for sub-millisecond deterministic control. MIIT industrial internet policies accelerate edge-native runtime adoption in smart factories. Yangtze River Delta electronics manufacturers integrate time-sensitive networking protocols for precision motion control.
Japan
Robotics integration and precision machinery manufacturing sustain demand for deterministic control software with sub-5-millisecond cycle times. METI Society 5.0 initiatives promote digital twin convergence for virtual commissioning. Nagoya's automotive and aerospace cluster adopts containerized control runtimes for flexible production scheduling.
South Korea
Memory chip fabrication and display panel manufacturing require ultra-precise environmental control systems. MFDS pharmaceutical validation standards and KOSHA industrial safety regulations shape software certification requirements. Seoul Capital Area semiconductor foundries deploy edge-native architectures for real-time process optimization.
Programmable Automation Controller Software Market Competitive Landscape
Concentration sits with diversified industrial conglomerates that bundle PAC software within broader automation portfolios. Siemens AG and Rockwell Automation, Inc. anchor the premium tier through entrenched relationships with automotive and process industry accounts. Mid-tier specialists compete on deployment flexibility and subscription economics for small-to-mid-sized manufacturers. Strategic moves center on edge-native runtime certification and cloud-native licensing transitions that unbundle perpetual seat agreements.
Among European-headquartered conglomerates, Siemens AG and Schneider Electric SE exemplify the diversified automation archetype that leverages energy management and process control synergies. Rockwell Automation, Inc. represents the North American-centric player with FactoryTalk-anchored automotive line dominance. These three companies illustrate how certification lock-in and vertical industry specialization create defensible positions against cloud-native challengers.
| Leading Market Players |
|---|
| Rockwell Automation, Inc. |
| Siemens AG |
| Schneider Electric SE |
| Mitsubishi Electric Corporation |
| Emerson Electric Co. |
| ABB Ltd. |
| Honeywell International Inc. |
| Advantech Co., Ltd. |
| Opto22 |
| Others |
Value Network & Pricing Analysis
Perpetual seat licenses for IEC 61508-certified toolchains lock in German automotive suppliers around Stuttgart and Munich to multi-year vendor relationships with visible replacement-cycle pricing. These contracts tether software procurement to hardware commissioning schedules, compressing negotiation leverage for buyers while securing margin stability for certified-platform vendors.
Pricing Analysis
Volume-discount tiering structures separate safety-critical runtime environments from standard configuration tools across the PAC software landscape. Three-tier pricing stratifies across SIL 3-certified premium stacks, standard industrial-grade licenses, and economy-tier monitoring suites. Price differentiation hinges on certification grade and after-sales engineering support bundling. Cost compression in the economy tier intensifies as cloud-native challengers unbundle perpetual agreements into subscription models. Small-to-mid-sized food processors in the US Midwest exhibit highest price sensitivity, while Gulf Coast petrochemical operators accept premium positioning for auditable safety platforms.
Supply Chain Analysis
Inbound logistics costs from Taiwanese and South Korean semiconductor foundries fluctuate with container availability on Asia-Pacific trade lanes, exposing industrial-grade ARM and x86 processor delivery timelines. Hardware-software coupling draws from Taiwan, South Korea, and Germany for processor fabrication, industrial PC assembly, and automation component integration. The supply chain rests on industrial-grade memory modules, real-time operating system licenses, and safety-certified compiler toolchains. Single-source vulnerability concentrates in Taiwanese foundry capacity for automotive-grade silicon. Distribution runs through system integrator channels in Stuttgart, Houston, and Nagoya that bundle software with commissioning services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
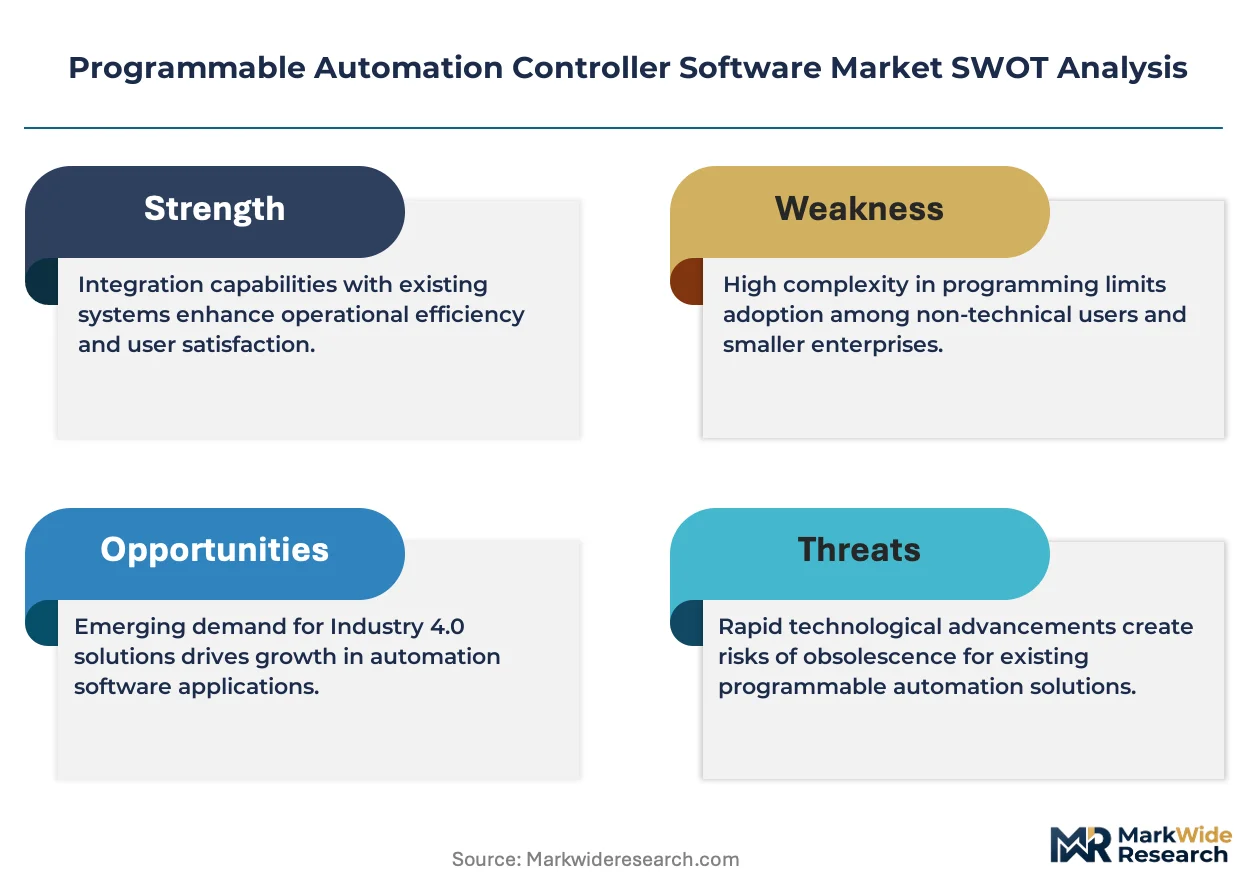
This market presents a defensive moat rooted in regulatory entrenchment. IEC 61508 SIL 3 certification requirements and ISA/IEC 62443 cybersecurity mandates create switching costs that lock buyers into validated vendor relationships across replacement cycles.
For Market Incumbents: Fortify certification pipelines by maintaining parallel IEC 61508 and ISA/IEC 62443 validation tracks, insulating against cloud-native challengers attempting to bypass safety-critical code audits. Deepen channel control through system integrator exclusivity arrangements in German automotive clusters. Prioritize R&D investment in containerized runtime architectures that preserve deterministic guarantees while enabling Kubernetes orchestration for flexible production lines. For New Entrants and Emerging Players: Differentiate on subscription economics for small-to-mid-sized food and beverage processors in the US Midwest, where legacy DCS maintenance cost spirals create white-space vulnerability. Target cloud-native deployment models with pay-per-project token-based access that unbundles engineering tools from runtime licenses. Penetrate through equipment OEM partnerships in Denmark and Netherlands dairy automation, leveraging seasonal production volatility to displace perpetual seat agreements. For Investors and Strategic Acquirers: Edge-native runtime specialists with dual-certification capabilities represent the most defensible acquisition archetype in this landscape. Long-term viability hinges on regulatory compliance moats deepening across the projection horizon, with containerized control platforms enabling multi-vendor software stacks on standardized industrial PCs. Watch for inflection signals in German chemical cluster procurement patterns, where EU Green Deal emissions tracking requirements accelerate hybrid edge-cloud adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Runtime Certification | Enables sub-5-millisecond deterministic control for Stuttgart automotive reconfigurable assembly lines. |
| Cloud-Native Licensing Transition | Unbundles perpetual seat agreements into subscription models for Midwest food processor accounts. |
| Dual-Certification Pipeline Investment | Maintains parallel IEC 61508 SIL 3 and ISA/IEC 62443 validation for process industry lock-in. |
| Digital Twin Platform Integration | Merges real-time physics engines with industrial control runtimes for virtual commissioning. |
| Kubernetes Orchestration Capability | Enables containerized control pods migrating between edge nodes during equipment maintenance. |
Research Methodology
A standing panel of control systems engineers, plant automation managers, OEM procurement leads, and system integrator technical directors provided ongoing calibration throughout the study. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, IEC certification registries, and trade data from German mechanical engineering associations. Bottom-up segment sizing triangulated against top-down industry expenditure estimates from automation trade publications.
Consistency checks validated volume and value outputs against external benchmarks from industrial software trade associations and regional automation expenditure surveys. The analytical framework modeled deployment architecture, end-user vertical, certification tier, and geographic adoption pattern across the projection horizon. CAGRs derived from segment-level growth trajectory analysis incorporating replacement cycle timing, regulatory mandate enforcement schedules, and edge-computing infrastructure deployment curves.
The analysis sits within stated boundaries; outcomes outside sustained EPA Clean Air Act enforcement, stable Taiwanese semiconductor foundry output, or continued German automotive capital expenditure would require recalibration. Forecasts reflect documented assumptions regarding certification timeline stability and cloud-native adoption elasticity in process industries. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Adaptive Learning Software Market
Software & Services
Lending Software Market
Software & Services
Bank Reconciliation Software Market
Software & Services
Application Development and Deployment Software Market
Software & Services
Global Server Management Software Market
Software & Services
Europe Database Management Software Market
Software & Services
Transient Analysis Software Market
Software & Services
Integration Brokerage Software Market
Software & Services
Global Construction Management Software Market
Software & Services
HR Tech Market
Software & Services
Europe Pharmacy POS Software Market
Software & Services
Global Local SEO Software Market
Software & Services
Admission Management Software Market
Software & Services
Denmark Software As a Service (Saas) Market
Software & Services
Document Capture Software Market