
 Global Custom Software Development Services Market | 2026-2036
Global Custom Software Development Services Market Size, Share, and Industry Trends Forecast 2026-2036
Global Custom Software Development Services Market Foresight
The divergence between premium and commodity tiers is hardening as enterprise clients demand specialized AI/ML engineering while cost-sensitive buyers offshore routine maintenance. Accenture leverages its consulting heritage to command premium pricing for complex transformation programs. Infosys sustains margin advantage through in-house platform products that reduce project-specific labor intensity. Tata Consultancy Services anchors volume leadership by operating one of the world's largest trained technical workforces.
Custom software development services encompass the end-to-end design, coding, testing, and deployment of proprietary applications built to client specifications rather than licensed as packaged products, typically delivered through agile sprints with continuous integration pipelines and automated quality gates. Enterprise software development commands the largest revenue pool as Fortune 500 firms replace legacy ERP modules, while cloud-based deployment is accelerating fastest as Kubernetes-orchestrated containerization slashes infrastructure provisioning cycles. Mobile application development remains structurally fragmented with compressed timelines, whereas API integration services capture expanding margins from real-time data interoperability mandates.
FDA validation requirements for software-as-medical-device constrain development practices for healthcare clients, while GDPR and the EU AI Act impose cross-border data handling and algorithmic accountability standards on European deliverables. India's BIS certification and SEZ policies shape competitive cost structures for export-oriented delivery centers. Stakeholders must weigh sovereign data residency laws against talent access when selecting delivery geography.
Market Dynamics
Enterprise procurement of AI-enabled custom platforms is concentrating vendor selection around demonstrable compliance credentials, bifurcating the competitive landscape between certified specialists and undifferentiated implementers.
Growth Catalysts
- EU AI Act algorithmic accountability mandates:Healthcare and financial services buyers in Europe now require documented explainability pipelines, creating dedicated procurement budgets for compliance-first development partners.
- Kubernetes-orchestrated containerization:Infrastructure provisioning cycles have compressed from weeks to hours, enabling faster iteration contracts and expanding addressable project scope for mid-market clients.
- India's SEZ policy framework:Export-oriented delivery centers in Bangalore and Hyderabad operate under favorable cost structures that sustain margin-competitive bidding for Fortune 500 maintenance contracts.
Market Restraints
- Specialized AI/ML engineering talent scarcity:Deep learning pipeline architects command premium compensation that erodes project margins for fixed-bid engagements.
- Cross-border data residency enforcement:GDPR and HIPAA fragmentation forces redundant infrastructure deployment, inflating delivery costs for multi-territory clients.
- Low-code platform substitution:Salesforce and ServiceNow configurability absorbs routine workflow automation demand that previously required custom builds.
Strategic Opportunities
- Saudi Arabia's digital transformation mandates:Government-led smart city investments in NEOM and Riyadh are generating greenfield procurement for sovereign cloud-compliant development.
- Software-as-medical-device FDA validation services:Specialized regulatory engineering for SaMD classification represents uncaptured margin pool as healthcare OEMs outsource compliance documentation.
- Edge-AI and 5G convergence:Real-time inference on distributed devices demands co-developed firmware-software stacks that bypass traditional cloud-native delivery models.
Industry Challenges
- DevSecOps skill integration:Security-by-design competency gaps in legacy development teams delay automated compliance pipeline deployment.
- Legacy ERP integration complexity:SAP and Oracle module replacement projects face data migration risks that extend warranty periods and compress realized margins.
- ISO 27001 certification timeline:Six-to-twelve-month audit cycles constrain smaller vendors from bidding on enterprise security-sensitive procurements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Custom Software Development Services Market |
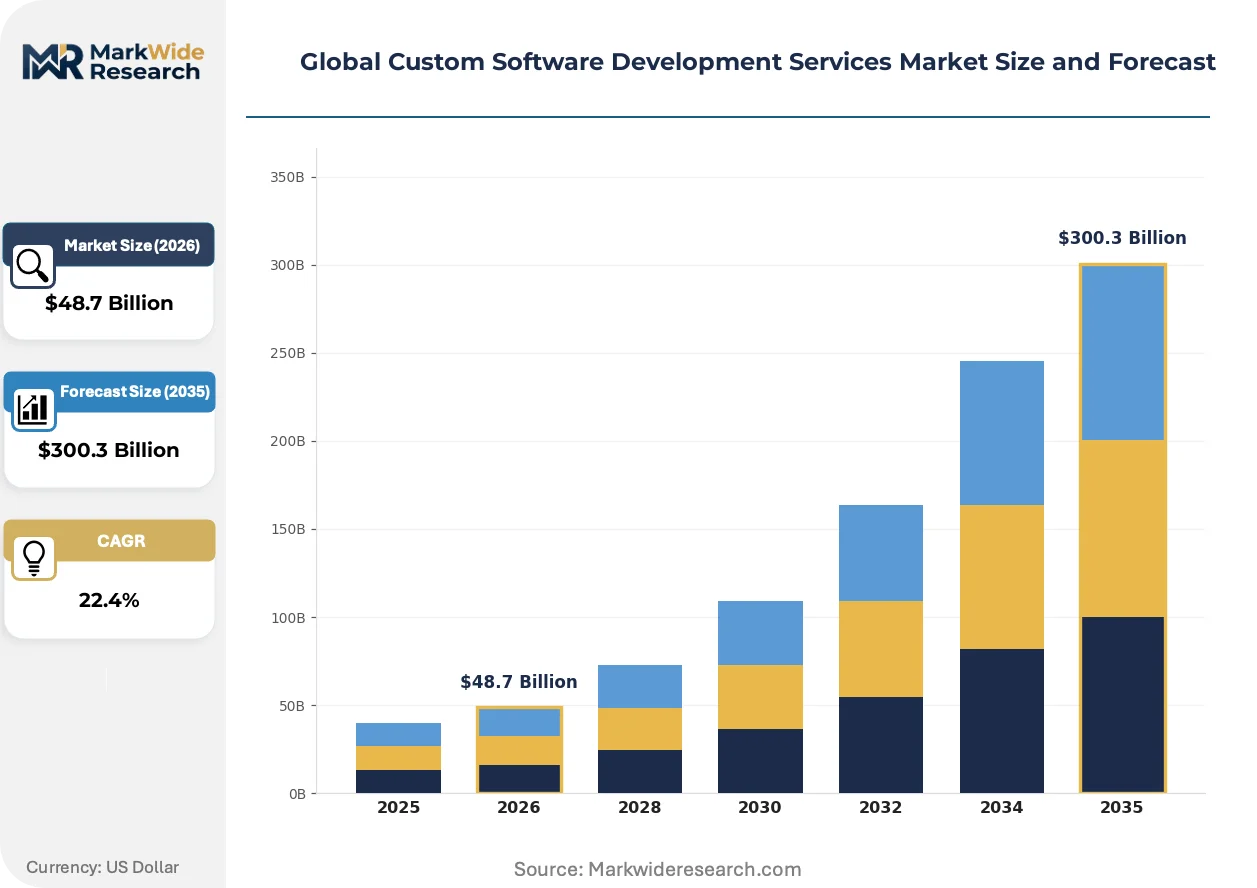
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $300.3 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Web Application Development, Mobile Application Development, Enterprise Software Development, API Integration, Software Maintenance Programming Language: Java, Python, JavaScript, Ruby, PHP, C# Deployment Model: On-Premise, Cloud-Based, Hybrid, Multi-Cloud, Containerized End User Industry: Banking, Telecommunications, Manufacturing, Education, Transportation, Hospitality |
| Companies Covered | HCLTech, Intellias, Infosys, Chetu, 3Pillar Global, Tata Consultancy Services (TCS), ScienceSoft, TatvaSoft, Accenture, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Custom Software Development Services Market Shifts & Advancements
Generative AI coding assistants are restructuring team composition ratios, while regulatory fragmentation forces geographic specialization that rewards compliance-native delivery architectures over generic scale.
Large language model pair-programming tools are automating boilerplate generation and test scaffolding. Mid-sized development shops in Poland and Vietnam are adopting GitHub Copilot and Amazon CodeWhisperer to maintain output velocity with leaner headcounts. This tooling compression is integrating junior developer workflows into senior-led review cycles, flattening traditional hierarchy-dependent quality gates.
The EU AI Act's risk classification framework entered enforcement phase for high-risk system providers. Developers must now maintain technical documentation, human oversight protocols, and accuracy metrics for biometric and credit-scoring applications. Financial services procurement in Germany and France now mandates CE-marking equivalent conformity assessments that disqualify non-EU vendors lacking established legal representation.
Buyers are unbundling maintenance from initial development, awarding separate multi-year operational contracts to specialized managed service providers. This disintermediation fragments vendor relationships and compresses switching costs. Healthcare systems in the United States exhibit this pattern most acutely, separating EMR platform builds from ongoing HIPAA-compliant hosting arrangements.
Global Custom Software Development Services Market Segmentation
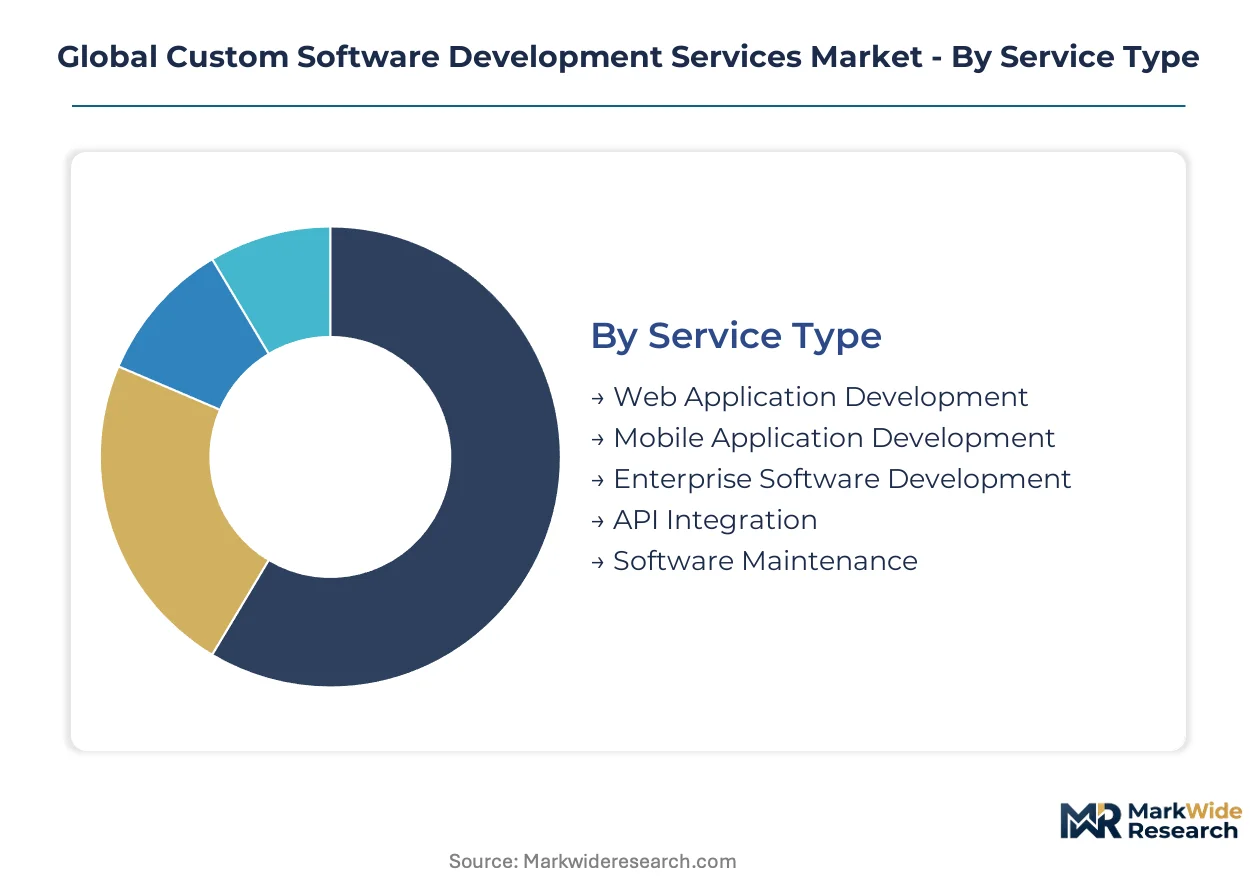
Procurement patterns across custom software development diverge sharply by technical architecture and compliance exposure. Buyers segment vendor selection around deployment sovereignty requirements and end-use regulatory intensity rather than generic capability claims.
Service Type:
Replacement cycles vary dramatically across service categories, with legacy ERP module upgrades driving the longest sales cycles and mobile refreshes compressing delivery timelines.
- Enterprise Software Development:Fortune 500 ERP module replacement and SAP S/4HANA migration projects dominate contract values. Banking and manufacturing clients in Germany and the United States anchor demand as regulatory deadlines force modernization decisions.
- Web Application Development:Patient-facing healthcare portals and digital banking interfaces require HIPAA and GDPR-compliant architecture. Delivery centers in Bangalore and Hyderabad capture volume from cost-sensitive mid-market buyers seeking certified development partners.
- Mobile Application Development:Compressed six-month refresh cycles dominate consumer-facing deployments.
- API Integration:Real-time data interoperability mandates from open banking regulations expand procurement scope.
- Software Maintenance:Multi-year operational contracts now unbundle from initial builds, fragmenting vendor relationships.
Volume placements concentrate in Enterprise Software Development; the faster expansion belongs to API Integration.
Programming Language:
Language selection tracks directly to application performance requirements and available talent pool depth in delivery geographies.
- Java:Dominates enterprise backend systems requiring long-term support commitments. Financial services institutions in Frankfurt and Singapore standardize on Java Spring Boot for core banking platform builds.
- Python:Powers machine learning pipelines and data engineering workloads. Healthcare AI diagnostic tools in the United States and algorithmic trading systems in London drive specialized recruitment for TensorFlow and PyTorch expertise.
- JavaScript:Full-stack Node.js and React development spans consumer web and cross-platform mobile.
- C#:Microsoft Azure-native enterprise applications favor this stack for Windows ecosystem integration.
- PHP:Content management and e-commerce backends retain share in cost-optimized engagements.
- Ruby:Startup ecosystem preference persists for rapid prototyping despite enterprise procurement avoidance.
Java anchors the largest committed headcount; Python climbs fastest on AI/ML project proliferation.
Deployment Model:
Sovereign data residency laws and latency requirements are fragmenting infrastructure choices across regulated industries.
- Cloud-Based:Kubernetes-orchestrated containerization has compressed provisioning from weeks to hours. Mid-market clients in Poland and Vietnam adopt managed AWS and Azure services to bypass capital expenditure constraints.
- Containerized:Microservices architecture enables independent scaling of application components. Telcos in South Korea and logistics operators in the Netherlands deploy edge-distributed containers for real-time processing.
- Hybrid:Split workloads between on-premise sensitive data and cloud burst capacity satisfy banking regulators.
- Multi-Cloud:Risk distribution across AWS, Azure, and GCP gains traction in Fortune 500 procurement.
- On-Premise:Defense and classified government systems retain this model for air-gapped security.
Cloud-Based deployments command the widest vendor participation; Containerized architectures gain share fastest among latency-sensitive applications.
End User Industry:
Regulatory complexity and digital maturity gaps create divergent procurement patterns across verticals.
- Banking:Open banking APIs and core system modernization absorb the largest custom development budgets. EU PSD2 compliance and US FedNow integration timelines compress vendor selection cycles in London and New York.
- Telecommunications:5G network slicing and edge computing infrastructure require co-developed firmware-software stacks. Operators in Saudi Arabia and South Korea lead procurement for sovereign cloud-compliant deployments.
- Manufacturing:Industrial IoT platform builds and predictive maintenance systems drive shop-floor digitization.
- Transportation:Fleet management and autonomous vehicle validation platforms expand regulatory engineering demand.
- Education:Learning management system customization follows hybrid instruction model adoption.
- Hospitality:Guest experience platforms and revenue management integrations concentrate in premium hotel chains.
Banking generates the deepest project backlogs; Telecommunications shows the steepest expansion trajectory on infrastructure buildouts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangalore and Hyderabad anchor the largest delivery center concentration for enterprise software development, while regulatory fragmentation across major economies reshapes vendor selection criteria.
United States
FDA validation requirements for software-as-medical-device and HIPAA compliance mandates drive specialized procurement in healthcare technology. Enterprise buyers in New York and San Francisco prioritize vendors with documented FedRAMP authorization for federal cloud deployments. The Boston corridor concentrates healthcare AI development shops serving academic medical centers.
Germany
Open banking APIs under PSD2 and core banking modernization absorb substantial custom development budgets in Frankfurt and Munich. The EU AI Act's algorithmic accountability requirements now disqualify non-EU vendors lacking established legal representation for high-risk system procurement. Berlin hosts emerging compliance-native development shops specializing in CE-marking equivalent conformity assessments.
India
Bangalore's SEZ policy framework sustains margin-competitive bidding for Fortune 500 maintenance contracts through favorable cost structures. BIS certification requirements and export-oriented delivery center policies shape competitive positioning for technical workforce scale. Hyderabad's HITEC City corridor concentrates Kubernetes-orchestrated containerization expertise for mid-market cloud migrations.
United Kingdom
Financial services procurement in London mandates demonstrable compliance credentials for AI-enabled platform builds under emerging algorithmic accountability standards. The UK Information Commissioner's Office enforcement of GDPR cross-border data handling creates vendor selection friction for non-UK legal entities. Manchester and Edinburgh delivery centers capture mid-market fintech development demand.
Saudi Arabia
NEOM and Riyadh smart city investments generate greenfield procurement for sovereign cloud-compliant development under SFDA and national data residency mandates. Government-led digital transformation programs prioritize vendors with established local legal presence and Arabic-language delivery capabilities. The Eastern Province concentrates energy sector digitalization projects requiring specialized regulatory engineering.
Global Custom Software Development Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across compliance certification depth and AI/ML engineering specialization. The vendor base stratifies into three tiers: global consultancies commanding transformation program pricing, Indian IT majors leveraging workforce scale for maintenance contracts, and boutique specialists capturing regulatory engineering premiums. Strategic archetypes include compliance-first specialists, platform-product hybrids, and pure-play labor arbitrage operators. Dominant competitive moves encompass geographic certification expansion and in-house platform development to reduce project-specific labor intensity.
Within the global consultancy tier, Accenture occupies a position exemplifying premium pricing for complex transformation programs. Among Indian IT majors, Tata Consultancy Services and Infosys represent scale-driven and platform-hybrid archetypes respectively, with the former anchoring volume leadership through workforce scale and the latter sustaining margin advantage through in-house platform products.
| Leading Market Players |
|---|
| HCLTech |
| Intellias |
| Infosys |
| Chetu |
| 3Pillar Global |
| Tata Consultancy Services (TCS) |
| ScienceSoft |
| TatvaSoft |
| Accenture |
| Others |
Supply & Pricing Matrix
Specialized AI/ML engineering talent compensation flows through project-based pricing tiers, with Bangalore and Hyderabad delivery centers compressing routine maintenance rates while Frankfurt and Boston specialists command premiums for FDA-validated healthcare builds.
Pricing Analysis
Outcome-based pricing anchored to delivered functionality and compliance certification separates premium transformation contracts from commodity maintenance engagements. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth—FedRAMP-authorized vendors in the United States and EU AI Act-compliant shops in Germany occupy the premium band, while SEZ-based Indian operators capture volume at compressed margins. Price differentiation hinges on regulatory engineering specialization and workforce geography, with cost compression in routine web application development intensifying as generative AI coding assistants flatten junior-senior productivity gaps. Healthcare systems in the United States exhibit the least price sensitivity due to HIPAA liability exposure, whereas mid-market Polish and Vietnamese buyers drive the hardest rate negotiations for cloud migration projects.
Supply Chain Analysis
Freight costs for hardware-dependent edge-AI deployments add geographic constraints to talent-sourcing decisions, favoring distributed delivery models over centralized offshore hubs. Technical workforce supply concentrates in India, Poland, and Vietnam, with Bangalore and Hyderabad anchoring the largest certified developer pools for enterprise clients. Project delivery draws from cloud infrastructure subscriptions, proprietary platform licenses, and compliance documentation services as core inputs. Single-source vulnerability in Kubernetes-orchestrated containerization expertise—concentrated among South Korean telco operators and Dutch logistics specialists—creates bidding friction for latency-sensitive applications. Distribution runs through direct enterprise procurement teams, systems integrator partnerships, and managed service provider intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generative AI coding assistants are displacing traditional team hierarchy models, forcing vendors to restructure pricing and talent deployment around augmented developer productivity rather than headcount scale.
For Market Incumbents: To counter margin erosion from low-code platform substitution, Accenture and TCS should deepen in-house platform development to reduce project-specific labor intensity while expanding FedRAMP and EU AI Act certification coverage to defend premium pricing for regulated verticals. For New Entrants and Emerging Players: The gap between premium transformation pricing and economy-tier maintenance rates offers entry space for compliance-native boutiques in Berlin and Boston specializing in FDA-validated software-as-medical-device documentation, with hospital system direct sales as the preferred go-to-market path. For Investors and Strategic Acquirers: ISO 27001 certification timeline compression among mid-sized vendors is the leading indicator that security-sensitive procurement eligibility is consolidating around audit-ready players, suggesting five-to-ten-year viability favors acquisition targets with established certification pipelines and healthcare or financial services vertical depth.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | CE-marking equivalent assessments unlock high-risk system procurement in Germany and France. |
| In-House Platform Development | Proprietary tools reduce labor intensity and sustain margin advantage against pure-play competitors. |
| Geographic Certification Expansion | FedRAMP authorization opens federal cloud deployment contracts in the United States market. |
| Acquisition of Regulatory Engineering Specialists | FDA validation expertise captures uncapped margin pools in healthcare software-as-medical-device. |
| Strategic Partnership with Hyperscalers | AWS and Azure co-sell arrangements accelerate Kubernetes-orchestrated containerization adoption. |
Research Methodology
Multi-period observation of vendor pricing disclosures, certification timelines, and procurement award patterns anchored the trend analysis, supplemented by interviews with CTOs at Fortune 500 enterprises, IT procurement officers in healthcare systems, platform engineers at Indian IT majors, and integration specialists at systems integrators. Secondary validation drew from SEC 10-K filings, hyperscaler capex disclosures, EU AI Act implementation guidance, and hospital procurement databases. Bottom-up project pipeline aggregation and top-down market sizing triangulated volume and value estimates.
Input-output matrices mapped deployment model, organization size, vertical regulatory intensity, integration complexity, and regional adoption pattern against projected demand across the analysis window. CAGRs were derived from segment-level growth rate reconciliation with macroeconomic indicators and technology diffusion curves. Kubernetes penetration rates and AI/ML engineering wage inflation served as software-specific forecast inputs.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time procurement contract values introduce uncertainty bands around vendor market share estimates. Forecasts reflect documented assumptions about compliance timeline enforcement and generative AI productivity adoption curves. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Data Integration Software Market
Software & Services
Global Cloud Accounting Technology Market
Software & Services
Global Applicant Tracking Software Market
Software & Services
Software Defined Broadcasting Market
Software & Services
Time and Attendance Software Market
Software & Services
Account-Based Advertising Software Market
Software & Services
Yacht Management Software Market
Software & Services
Global Data Quality Software Market
Software & Services
Content Moderation Software Market
Software & Services
Construction Jobsite Management Software Market
Software & Services
Configure Price and Quote (CPQ) Market
Software & Services
Talent Management Software Market
Software & Services
Asia Pacific Human Capital Management Software (HCM) Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Procurement Software Market
Software & Services
Europe Digital Signage Software Market