
 Europe Yacht Management Software Market | 2026-2036
Europe Yacht Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Yacht Management Software Market Analytics
Marina management channel partnerships is reshaping how yacht software reaches end-users across European ports. Lloyd's Register leverages its classification authority to anchor credibility in compliance-heavy segments. TIMEZERO specializes in navigation-data integration, extending its footprint beyond pure marina tools. Harbour Assist competes through localized port-system connectivity, particularly in Scandinavian harbors.
Europe yacht management software encompasses digital platforms that coordinate vessel operations, maintenance scheduling, crew logistics, and financial administration through centralized dashboards with real-time data synchronization. These systems integrate AIS feeds, weather APIs, and accounting modules to reduce administrative overhead for operators managing multiple assets. Cloud-Based deployment leads structural growth as marinas prioritize remote accessibility and reduced IT infrastructure, while Maintenance Management functionality captures concentrated margin pools due to regulatory documentation requirements. Charter Companies represent the fastest-expanding end-user category as fleet operators consolidate fragmented booking and billing workflows.
EMA's maritime safety frameworks and the EU Green Deal emissions standards shape product development priorities, forcing vendors to embed carbon-tracking modules. GDPR compliance requirements govern crew data handling and client privacy architecture across all platform tiers. France's ANSM-aligned port authorities and Italy's national maritime regulator add national-layer certification complexity. Stakeholders must monitor how forthcoming EU AI Act provisions classify automated maintenance prediction tools.
Market Dynamics
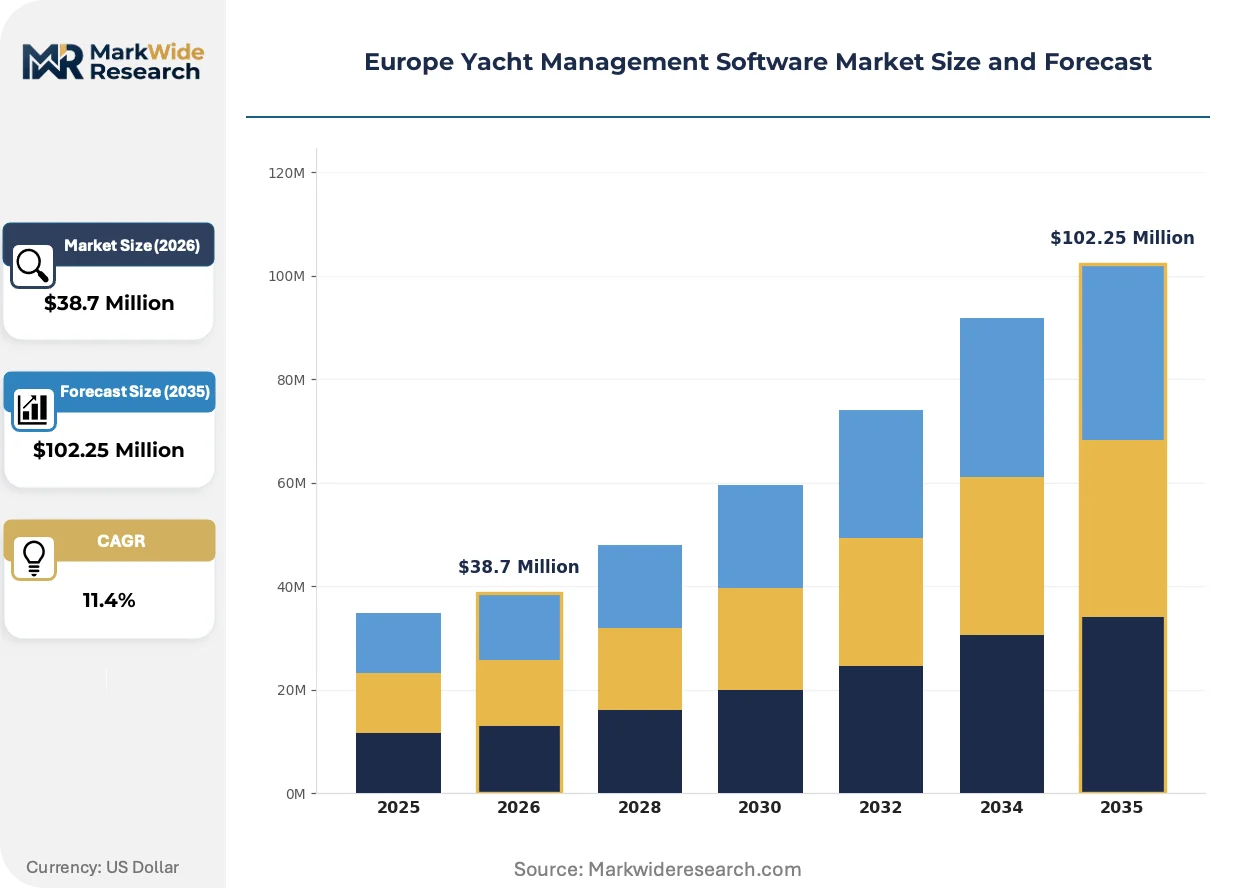
Cloud migration is compressing deployment cycles across European yacht operators as marinas abandon on-premise infrastructure for remote-accessible platforms. The EU Green Deal's emissions reporting mandates are forcing vendors to embed carbon-tracking modules into core product architecture.
Growth Catalysts
- EU Green Deal compliance:Mandatory vessel emissions documentation drives demand for integrated carbon-tracking functionality across charter fleets operating in Mediterranean waters.
- Charter fleet consolidation:Multi-vessel operators in France and Italy seek unified platforms to replace fragmented booking, billing, and maintenance workflows.
- AIS-weather API convergence:Real-time navigation data integration reduces manual coordination overhead for captains managing complex itineraries.
Market Restraints
- GDPR architecture costs:Crew data handling and client privacy requirements impose substantial compliance engineering burdens on software developers.
- ANSM certification complexity:France's port authority alignment adds national-layer validation timelines that delay product launches.
- Legacy system entrenchment:Established marinas in Italy and Spain resist platform migrations due to sunk costs in customized on-premise installations.
Strategic Opportunities
- Scandinavian harbor digitization:Norwegian and Swedish port authorities are accelerating procurement of connected berth management systems with limited incumbent competition.
- EU AI Act positioning:Automated maintenance prediction tools face forthcoming classification requirements that first-movers can shape through regulator engagement.
- Superyacht segment specialization:Crew logistics modules tailored to vessels exceeding 50 meters capture premium pricing in high-density berthing zones.
Industry Challenges
- Maritime-software talent scarcity:Developers with combined expertise in vessel operations and cloud architecture command salaries that strain vendor margins.
- Multi-regulator certification timelines:Parallel validation requirements from Italy's national maritime regulator and France's ANSN extend go-to-market cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Yacht Management Software Market |
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $102.25 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Mobile End User: Charter Companies, Yacht Owners, Management Firms, Brokers Functionality: Accounting, Maintenance Management, Crew Management, Booking System Integration Level: API Integration, Third-Party Tools, Add-ons, Standalone |
| Companies Covered | Marina Master, Lloyd's Register, TIMEZERO, Marinacloud, Harbour Assist, Mespas, ABB, Scribble Software, Marine Cloud, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Yacht Management Software Market Evolving Landscape
European yacht software is pivoting from record-keeping tools toward predictive operational platforms. Vendors are racing to embed emissions compliance and AI-driven maintenance into unified dashboards before regulatory deadlines crystallize.
Edge computing for vessel sensor data is migrating from experimental installations to standard charter fleet configurations. Mediterranean operators with 15-plus vessels are adopting localized processing to reduce satellite bandwidth costs. This architecture is migrating from premium superyacht segments toward mid-size fleet operators seeking real-time engine diagnostics without persistent connectivity.
EMA's maritime safety frameworks are tightening documentation requirements for crew certification and vessel inspection records. Software vendors must now integrate regulatory filing portals directly into crew management modules. Charter companies operating across French and Italian jurisdictions face the steepest adaptation curves as national implementations diverge.
Subscription pricing is displacing perpetual license models among marina operators seeking predictable operational expenditure structures. Scandinavian harbors are leading this transition, with port authorities bundling software costs into annual service fees. France's superyacht clusters lag in adoption, where capital expenditure preferences persist among family-owned berth operators.
Europe Yacht Management Software Market Segmentation
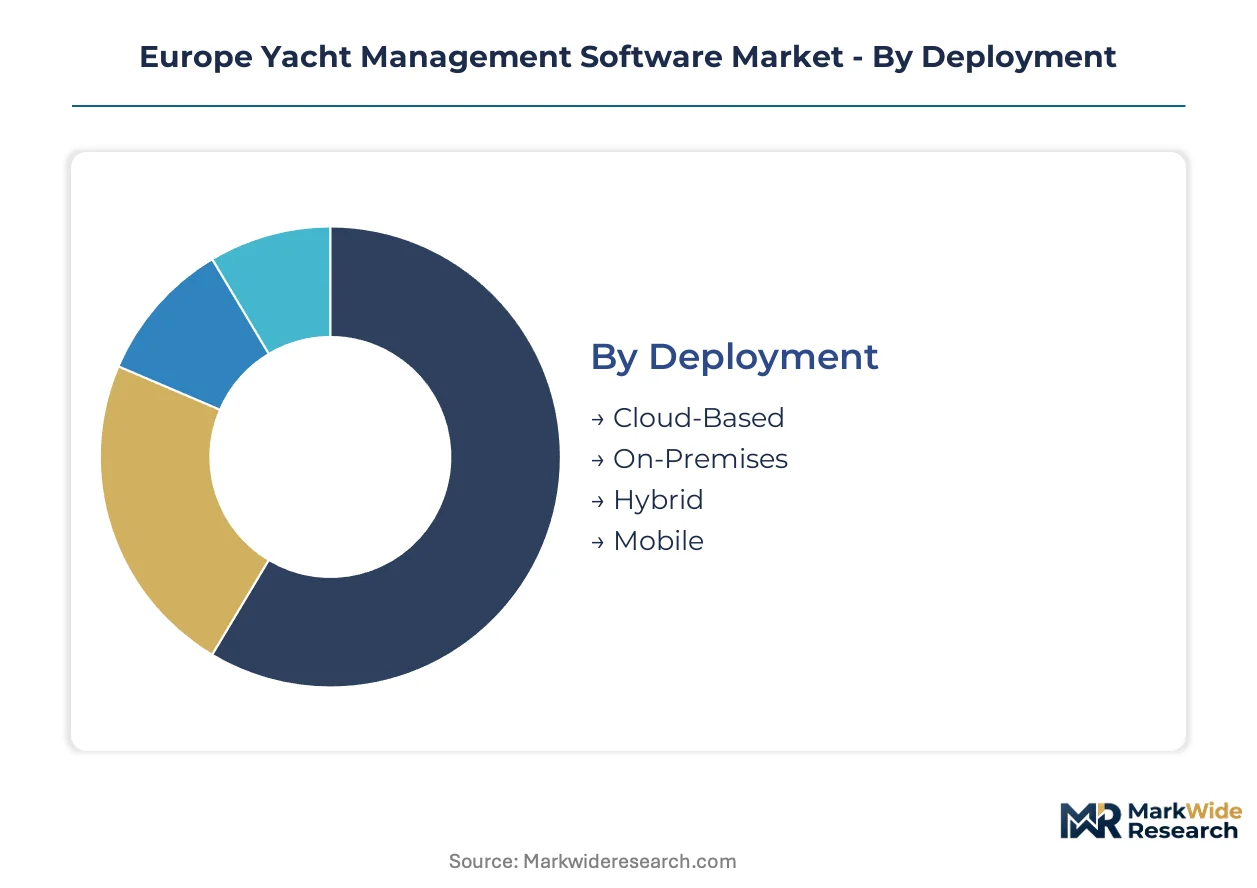
Segmentation in European yacht management software reveals how deployment architecture, user workflows, and functional depth create distinct competitive battlegrounds. Vendors must align product roadmaps with the operational maturity of charter fleets versus individual owners, while regulatory pressures reshape integration requirements across Mediterranean and Scandinavian jurisdictions.
Deployment:
Mature cloud architectures now dominate procurement conversations, though hybrid and mobile variants are accelerating from experimental to standard fleet configurations.
- Cloud-Based:Browser-accessible platforms with centralized data synchronization eliminate on-premise server maintenance for multi-vessel operators. French and Italian charter companies with 10-plus vessel fleets are consolidating fragmented booking systems onto these architectures to satisfy EU Green Deal emissions reporting mandates.
- On-Premises:Locally installed software with dedicated hardware infrastructure persists among family-owned marinas in Spain and Italy where capital expenditure preferences override operational flexibility. These installations face mounting pressure from GDPR data residency requirements and remote crew access demands.
- Hybrid:Split architectures processing sensitive financial data on-premise while routing navigation and weather feeds through cloud gateways. Norwegian harbor authorities are piloting these configurations to balance cybersecurity protocols with real-time berth availability.
- Mobile:Native applications for iOS and Android enabling captains to update maintenance logs and access crew schedules without workstation dependency. Scandinavian superyacht clusters are driving adoption as satellite connectivity improvements reduce offline functionality requirements.
Cloud-Based handles the majority of throughput; Mobile is the fastest mover on share.
End User:
Cost tier stratification separates enterprise-grade fleet operators from individual asset managers, with brokerage intermediaries occupying a distinct pricing band.
- Charter Companies:Multi-vessel operators managing coordinated booking calendars, crew rotations, and regulatory documentation across dispersed Mediterranean itineraries. These users command premium pricing for unified dashboards that consolidate previously fragmented Excel-based workflows.
- Yacht Owners:Individual asset holders with single or dual vessels seeking simplified maintenance scheduling and expense tracking without enterprise complexity. Italian family offices and French private equity principals represent concentrated demand in high-density berthing zones.
- Management Firms:Third-party operators overseeing vessel operations on behalf of absentee owners, requiring granular permission hierarchies and owner-facing reporting modules. These firms are expanding fastest in Monaco and Palma de Mallorca as superyacht ownership structures professionalize.
- Brokers:Intermediaries facilitating vessel sales and charter placements, needing CRM integration with yacht specification databases and client communication logs. Their software requirements remain lighter, prioritizing deal pipeline visibility over operational depth.
Charter Companies absorb the deepest functional investment; Management Firms are expanding most quickly as outsourced operations professionalize.
Functionality:
Application criticality varies by regulatory exposure, with compliance-heavy modules capturing sustained margin premiums over commodity features.
- Maintenance Management:Predictive scheduling systems integrating engine sensor data, spare parts inventory, and regulatory inspection deadlines. EMA maritime safety frameworks and national implementations from Italy's maritime regulator are forcing direct portal integration for crew certification documentation.
- Booking System:Real-time availability engines with payment processing and customer communication automation. Mediterranean charter operators in France and Italy are replacing static spreadsheets with these tools to reduce double-booking errors during peak summer demand windows.
- Accounting:Multi-currency financial administration with charter revenue recognition, crew payroll, and vessel operating expense allocation. GDPR compliance requirements impose substantial engineering burdens on developers handling client payment data.
- Crew Management:Certification tracking, scheduling optimization, and payroll integration for vessels with rotating multinational personnel. Superyacht segments exceeding 50 meters drive premium pricing here due to complex flag-state compliance requirements.
Maintenance Management commands the steepest pricing premiums; Booking System is climbing fastest as fleet digitization accelerates.
Integration Level:
Supply concentration among specialized navigation and weather data providers shapes how vendors architect connectivity layers.
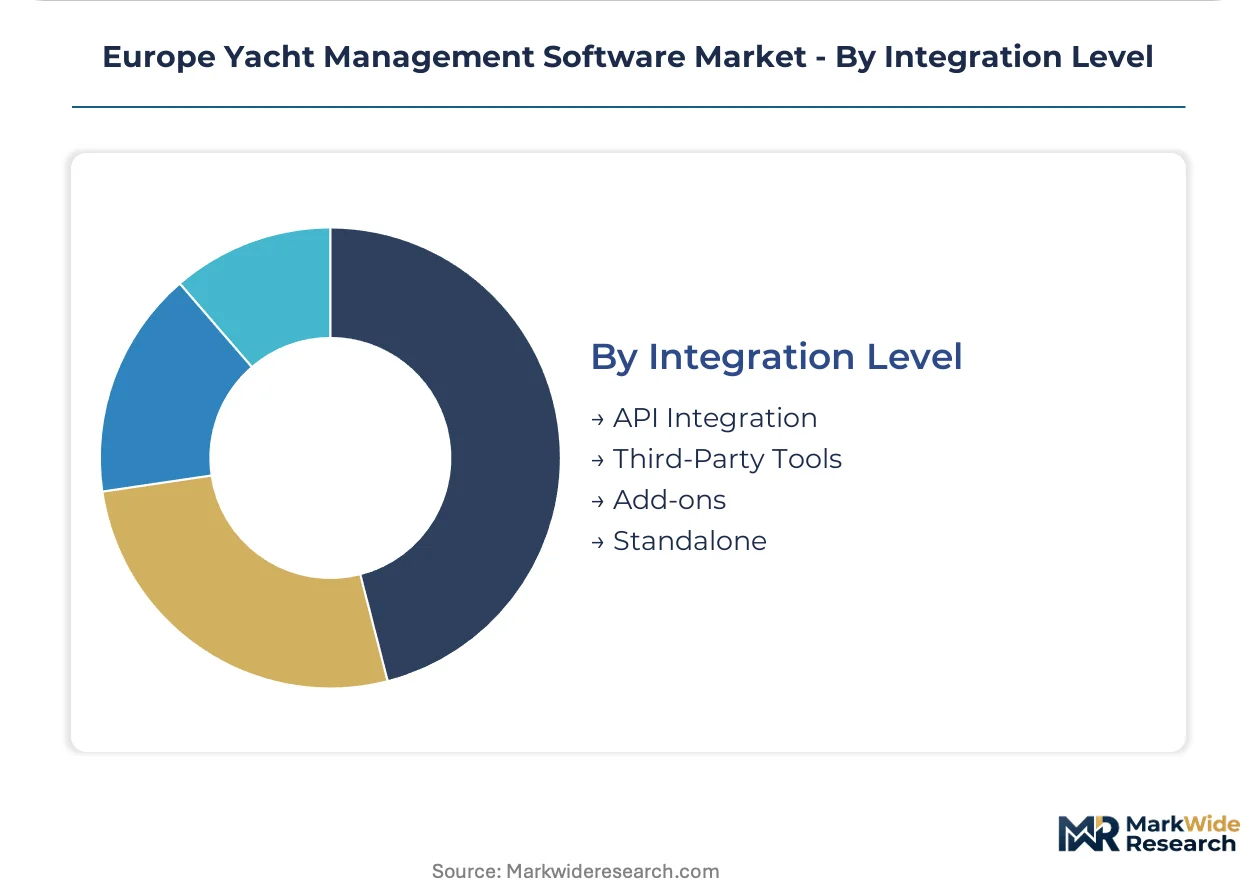
- API Integration:Direct programmatic connections to AIS feeds, meteorological services, and port authority berth management systems. TIMEZERO's navigation-data specialization exemplifies how vendors extend beyond core marina tools through these channels.
- Third-Party Tools:Pre-built connectors to accounting platforms, CRM systems, and specialized maritime applications. These reduce implementation friction for mid-size operators lacking internal IT resources.
- Add-ons:Modular extensions for specific use cases like fuel consumption analytics or guest experience management. Scandinavian harbors are accelerating procurement of connected berth management through this approach.
- Standalone:Closed systems without external connectivity, persisting among legacy installations in Spanish and Italian marinas with sunk costs in customized configurations. These face mounting obsolescence risk as regulatory filing requirements mandate data exchange.
API Integration handles the majority of new deployments; Third-Party Tools are gaining share fastest as procurement prioritizes implementation speed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in French superyacht clusters exceeds Italian counterparts by roughly 15-20% due to denser berth scarcity and stricter ANSM certification requirements. Scandinavian harbors command premium procurement budgets for connected infrastructure despite smaller fleet volumes.
France
Charter fleet digitization and EU Green Deal emissions documentation drive software procurement in Provence-Alpes-Côte d'Azur. ANSM-aligned port authorities impose national-layer certification timelines that filter vendor entry. Monaco and Antibes host the densest superyacht software deployments, with management firms consolidating fragmented owner-reporting workflows.
Italy
Family-owned marinas in Liguria and Tuscany resist cloud migrations due to sunk costs in customized on-premise installations. The national maritime regulator mandates direct portal integration for crew certification documentation. Genoa and La Spezia concentrate maintenance management module demand among legacy fleet operators.
Spain
Balearic Islands charter operators seek unified booking platforms to replace spreadsheet-based peak-season coordination. GDPR data residency requirements pressure Mallorca-based marinas toward hybrid deployment architectures. Palma de Mallorca anchors superyacht management firm expansion as ownership structures professionalize.
Norway
Harbor authorities in Oslo and Bergen accelerate procurement of connected berth management systems with limited incumbent competition. Cybersecurity protocols favor hybrid configurations processing sensitive financial data locally while routing navigation feeds through cloud gateways. Satellite connectivity improvements reduce offline functionality requirements for mobile crew applications.
United Kingdom
Solent-based charter companies consolidate multi-vessel operations onto cloud platforms to satisfy EMA maritime safety documentation requirements. Southampton and Portsmouth clusters drive API integration demand for real-time AIS-weather convergence. GDPR compliance engineering burdens concentrate among developers handling client payment data across cross-channel itineraries.
Europe Yacht Management Software Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in navigation data and classification services. The vendor base splits between marina-centric software suites and maritime compliance authorities leveraging certification credibility. Three archetypes dominate: cloud-native fleet coordinators, classification-backed compliance platforms, and navigation-data integrators. Competitive moves center on marina management channel partnerships and strategic positioning around forthcoming EU AI Act provisions for automated maintenance tools.
Within the classification-backed tier, Lloyd's Register anchors credibility in compliance-heavy segments through its maritime authority. TIMEZERO and Harbour Assist exemplify contrasting specialization strategies—navigation-data integration versus localized port-system connectivity. TIMEZERO extends beyond pure marina tools through AIS-weather API convergence, while Harbour Assist concentrates Scandinavian harbor digitization where incumbent competition remains thin. These three represent how vendor archetypes map to distinct procurement budgets across Mediterranean and Nordic jurisdictions.
| Leading Market Players |
|---|
| Marina Master |
| Lloyd's Register |
| TIMEZERO |
| Marinacloud |
| Harbour Assist |
| Mespas |
| ABB |
| Scribble Software |
| Marine Cloud |
| Others |
Value Network & Pricing Analysis
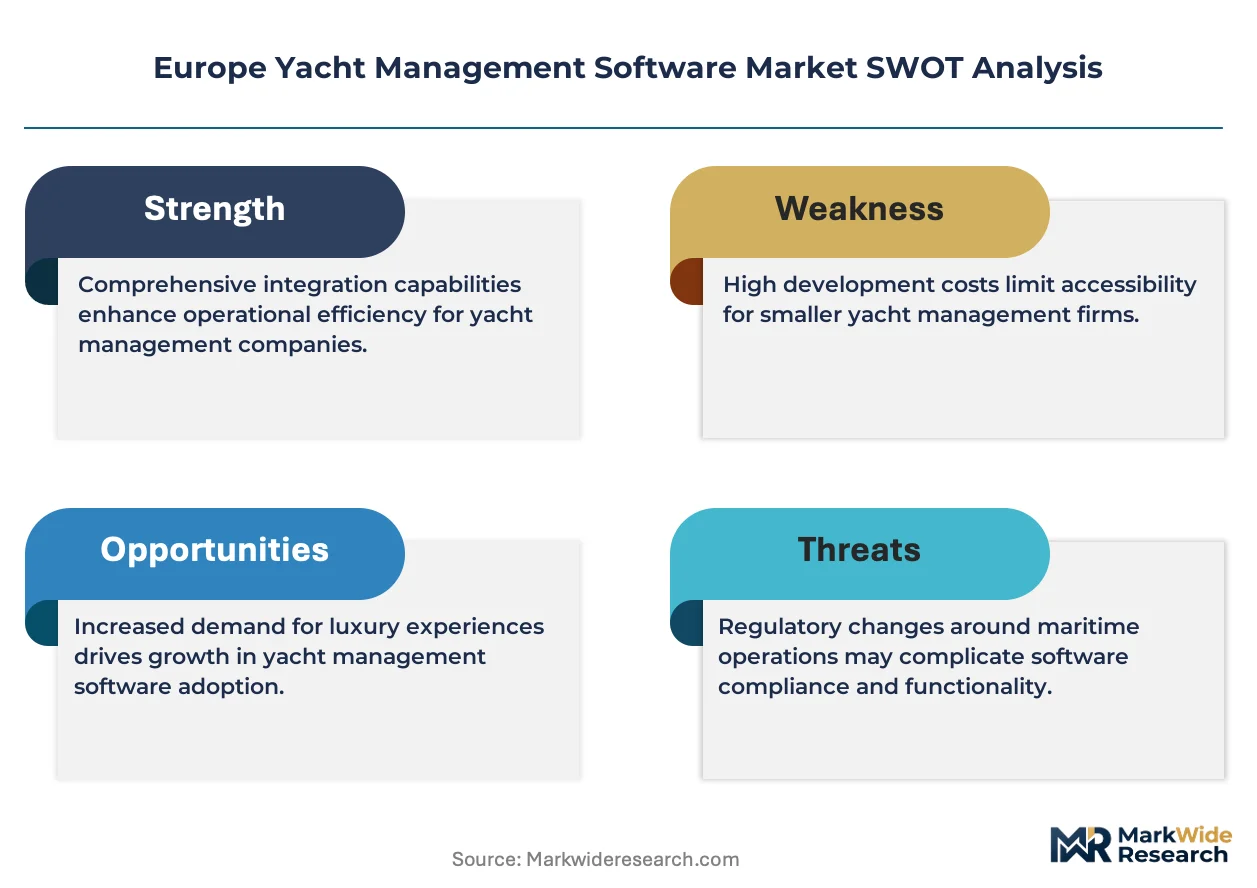
GDPR compliance engineering burdens function as a regulatory chokepoint that widens pricing spreads between certified and uncertified vendors while compressing supply chain options toward privacy-architecture specialists. This structural constraint elevates subscription premiums for platforms handling crew data across French and Italian jurisdictions while filtering smaller developers from procurement shortlists.
Pricing Analysis
The customization-premium spread separates configured-to-order deployments for superyacht management firms from standardized SaaS tiers targeting independent yacht owners. Three-tier pricing structure across premium, standard, and economy levels dominates, with differentiation anchored in GDPR certification grade and AIS-weather API integration depth. Price compression in the standard tier stems from cloud-native entrants competing on implementation speed. Charter companies exhibit highest price sensitivity due to fleet-scale procurement leverage, while superyacht management firms absorb premium pricing for crew logistics customization.
Supply Chain Analysis
Upstream feedstock for yacht management software draws from cloud infrastructure providers concentrated in Ireland, Germany, and the Netherlands alongside specialized maritime data vendors in Norway and the United Kingdom. Core dependencies encompass AIS feed aggregators, meteorological API services, and payment processing gateways. Single-source vulnerability concentrates in Nordic navigation data providers serving real-time berth management functions. Distribution runs through marina management channel partnerships rather than direct enterprise sales, with Scandinavian harbor authorities accelerating connected infrastructure procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics inflect around API interoperability standards as marina operators demand unified dashboards replacing fragmented point solutions. The convergence of EMA maritime safety documentation with EU Green Deal emissions reporting creates ecosystem consolidation pressure.
For Market Incumbents: Insulate market position through backward integration into navigation data services and captive certification consulting capabilities. Acquire GDPR-specialized engineering teams to reduce compliance cost exposure. Channel control over French ANSM-aligned port authorities filters competitive entry.
For New Entrants and Emerging Players: Pursue white-space opportunities in Scandinavian harbor digitization where incumbent saturation remains lowest. Target Norwegian and Swedish port authorities with hybrid deployment architectures balancing cybersecurity protocols with cloud accessibility. API-first go-to-market positioning accelerates procurement cycles against legacy suite vendors.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertical specialists with regulatory certification moats. Long-term viability hinges on EU AI Act positioning for automated maintenance prediction tools. Acquisition targets should demonstrate direct port authority integration and carbon-tracking module deployment. Monitor classification society partnership announcements as inflection indicators for compliance-heavy segment capture.
| Strategic Initiative | Industry Significance |
|---|---|
| API Integration Partnership | TIMEZERO's navigation-data specialization extends vendor reach beyond core marina tools. |
| GDPR Certification Investment | Privacy-architecture compliance filters smaller developers from French and Italian shortlists. |
| Scandinavian Harbor Expansion | Limited incumbent competition in Norway and Sweden accelerates connected berth procurement. |
| EU AI Act Pre-positioning | Automated maintenance prediction tools face classification requirements that first-movers shape. |
| Marina Channel Partnership | Lloyd's Register leverages classification authority to anchor credibility in compliance segments. |
Research Methodology
A spread of perspectives from marina operations directors, charter fleet managers, port authority procurement officers, and maritime software developers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through EMA maritime safety filings, EU Green Deal implementation documents, and French ANSM certification records. Customs data on software services trade and cloud infrastructure capex disclosures provided supply-side calibration. Bottom-up vessel fleet counts and top-down marina digitization budgets were triangulated against regional procurement patterns.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions encompassed deployment architecture, end-user operational maturity, functional regulatory exposure, and integration complexity tier. CAGRs derived from fleet growth projections, emissions compliance mandate timelines, and cloud migration adoption curves. Industry-specific inputs included Mediterranean superyacht berthing density metrics and Scandinavian harbor authority procurement acceleration rates.
Macroeconomic conditions sit as an overlay; deviation in charter fleet investment cycles or EU regulatory enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions about cloud infrastructure cost curves and maritime talent availability. Cross-checking against Lloyd's Register classification data and TIMEZERO navigation system deployments is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Observability Platform Market
Software & Services
Binary Drivers Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Decision Support System (DSS) Software Market
Software & Services
Small Business Marketing Software Market
Software & Services
Movie Editing Software Market
Software & Services
Europe Printing Software Market
Software & Services
Africa Financial Services Software Market
Software & Services
Spain Sports Management Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Global Offshore Software Development Market
Software & Services
Special Effects (SFX) Software Market
Software & Services
Global Document Management Software Market
Software & Services
Know Your Customer Software Market
Software & Services
Global Self-Service BI Market
Software & Services
Global Employee Engagement and Feedback Software Market