
 Automotive Operating Systems Market | 2026-2036
Automotive Operating Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Operating Systems Market Analysis
The rift between premium safety-critical stacks and commodity infotainment layers is hardening across automotive software procurement. BlackBerry QNX anchors the high-integrity segment through its ISO 26262-certified microkernel architecture deployed in ADAS controllers. Wind River Systems leverages its aerospace heritage to dominate aerospace-grade reliability benchmarks in autonomous driving compute. Elektrobit competes aggressively on middleware integration speed for European OEM digital cockpit programs.
Automotive operating systems constitute the foundational software layer governing real-time task scheduling, hardware abstraction, and inter-process communication within vehicle electronic control units, typically executing on microcontrollers with sub-50-microsecond interrupt latency requirements to ensure deterministic brake-by-wire and steer-by-wire responses. The application dimension shows infotainment frameworks commanding current volume while ADAS runtime environments capture expanding margin pools as Level 2+ autonomy proliferates. Linux-based technology stacks lead installation counts through Android Automotive adoption, though RTOS architectures sustain premium pricing in chassis and powertrain domains where functional safety certification remains mandatory.
The EU's Cyber Resilience Act and UN ECE R155/R156 vehicle cybersecurity regulations are reshaping software validation requirements, forcing OEMs to demonstrate over-the-air update integrity and intrusion detection capabilities across all ECU operating environments. The US NHTSA and China's MIIT are advancing parallel mandates on software bill of materials disclosure and fail-operational system behavior. Stakeholders must monitor how hypervisor consolidation strategies reconcile mixed-criticality workloads while preserving supplier liability boundaries between OEMs and Tier-1 integrators.
Market Dynamics
Hypervisor consolidation is forcing OEMs to reconcile mixed-criticality workloads on single compute platforms, collapsing the historical separation between infotainment and safety-critical domains while preserving supplier liability boundaries.
Growth Catalysts
- EU Cyber Resilience Act:Mandates standardized security protocols for connected vehicle software, compelling OEMs to upgrade ECU operating environments with intrusion detection and over-the-air update integrity capabilities.
- Electric vehicle platforms:Accelerate adoption of real-time operating systems through zonal E/E architectures that demand deterministic task scheduling across battery management and thermal control systems.
- Germany's automotive engineering corridor:Concentrates demand around Stuttgart and Munich, where Tier-1 suppliers and OEM engineering centers drive procurement of ISO 26262-certified software stacks.
Market Restraints
- Functional safety certification costs:ISO 26262 ASIL-D qualification requires 18-36 month validation cycles, creating capital intensity barriers for new entrants targeting chassis and powertrain domains.
- RTOS talent scarcity:Embedded systems engineers with microkernel optimization expertise concentrate at established vendors, constraining supply-side expansion.
- Linux substitution threat:Android Automotive and Automotive Grade Linux capture infotainment volume through royalty-free models, compressing pricing power in non-safety-critical segments.
Strategic Opportunities
- India's automotive software ecosystem:Underpenetrated relative to engineering talent base, presenting white space for offshore development centers serving European OEM digital cockpit programs.
- Software-defined vehicle architectures:Enable recurring revenue models through feature-on-demand operating system modules, shifting value capture from hardware to subscription-enabled software layers.
- UN ECE R155/R156 harmonization:Creates regulatory tailwind for cybersecurity-certified OS vendors as type-approval requirements spread beyond EU to Japan and South Korea.
Industry Challenges
- Hypervisor integration complexity:OEMs struggle to preserve deterministic latency guarantees for brake-by-wire functions while hosting infotainment workloads on shared silicon, requiring extensive supplier coordination.
- Software bill of materials disclosure:NHTSA and MIIT mandates force granular open-source component tracking, exposing licensing contamination risks and extending compliance timelines.
- Legacy ECU refresh cycles:7-10 year automotive platform lifecycles delay adoption of modern OS architectures, fragmenting supplier support obligations across multiple kernel generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Operating Systems Market |
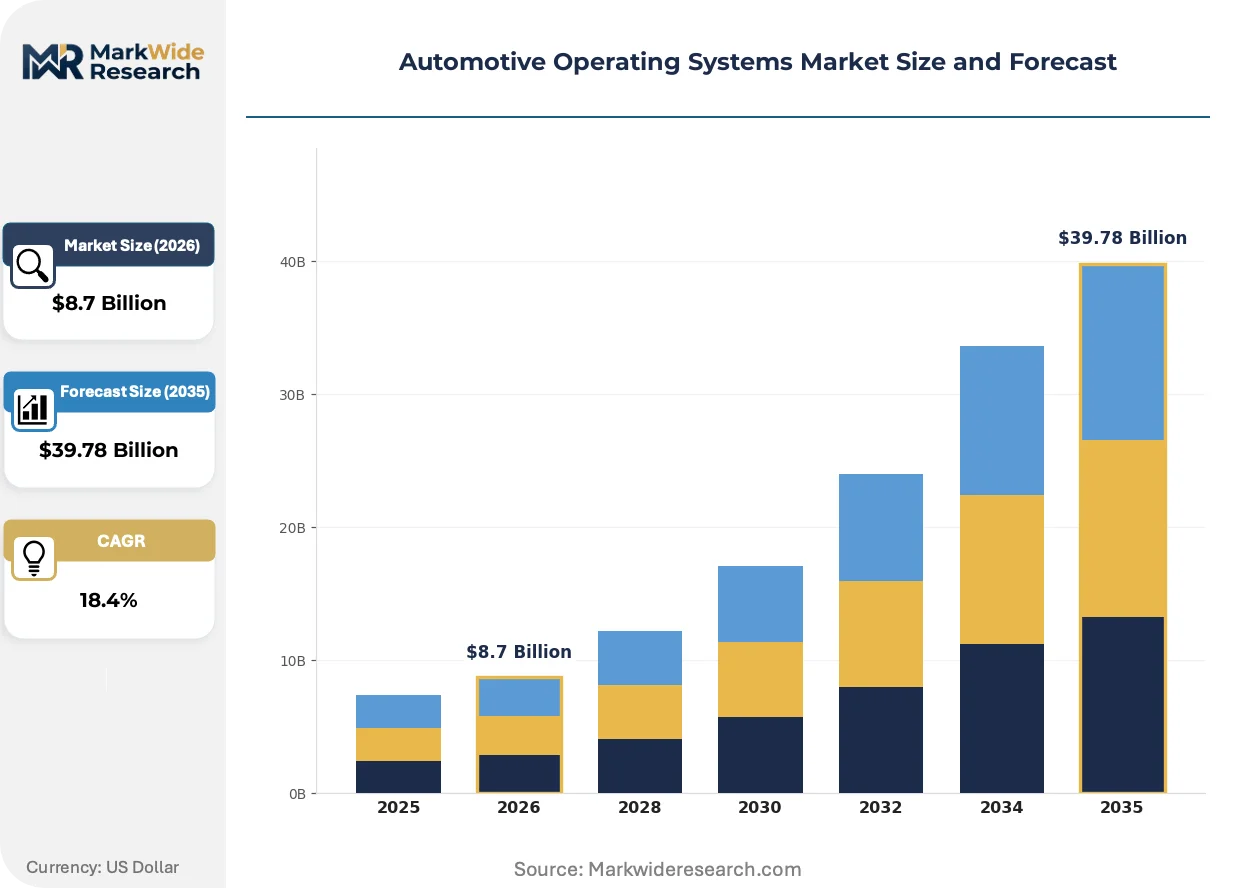
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embedded Systems, Middleware, Application Frameworks, Runtime Environments Technology: RTOS, Linux-Based, Automotive Open System Architecture, Hypervisor End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, System Integrators Application: Infotainment, ADAS, Telematics, Vehicle Control |
| Companies Covered | Green Hills Software, Elektrobit, Continental AG, Intellias, Vector Informatik, Cerence, Wind River Systems, DXC Technology, BlackBerry QNX, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Operating Systems Market Emerging Trajectories
Containerized middleware deployment is collapsing the traditional boundary between vehicle domains, enabling software updates that traverse previously isolated ECU networks without hardware replacement.
Microkernel-based separation architectures are decentralizing safety-critical function isolation across zonal compute nodes. Tier-1 suppliers adopt these architectures for domain controller consolidation, replacing monolithic ECU fleets with fewer, more powerful compute units. This decentralization compresses hardware bill-of-materials while elevating software complexity management to a core OEM competency.
REACH and RoHS substance restrictions are reshaping semiconductor packaging requirements for automotive-grade processors, indirectly affecting OS vendor hardware abstraction layer designs. The industrial consequence extends validation matrices to cover alternative substrate materials and thermal profiles. Powertrain ECU suppliers face the steepest compliance ramps as electrification multiplies silicon content per vehicle.
Buyer concentration among megaplatform OEMs is compressing supplier negotiation cycles and favoring long-term framework agreements over program-by-program procurement. Tier-2 OS licensors lose pricing leverage as Volkswagen Group, Toyota, and Hyundai-Kia consolidate purchasing through captive software subsidiaries. This concentration is most visible in Germany and Japan, where domestic supplier hierarchies reinforce incumbent positioning.
Automotive Operating Systems Market Segmentation
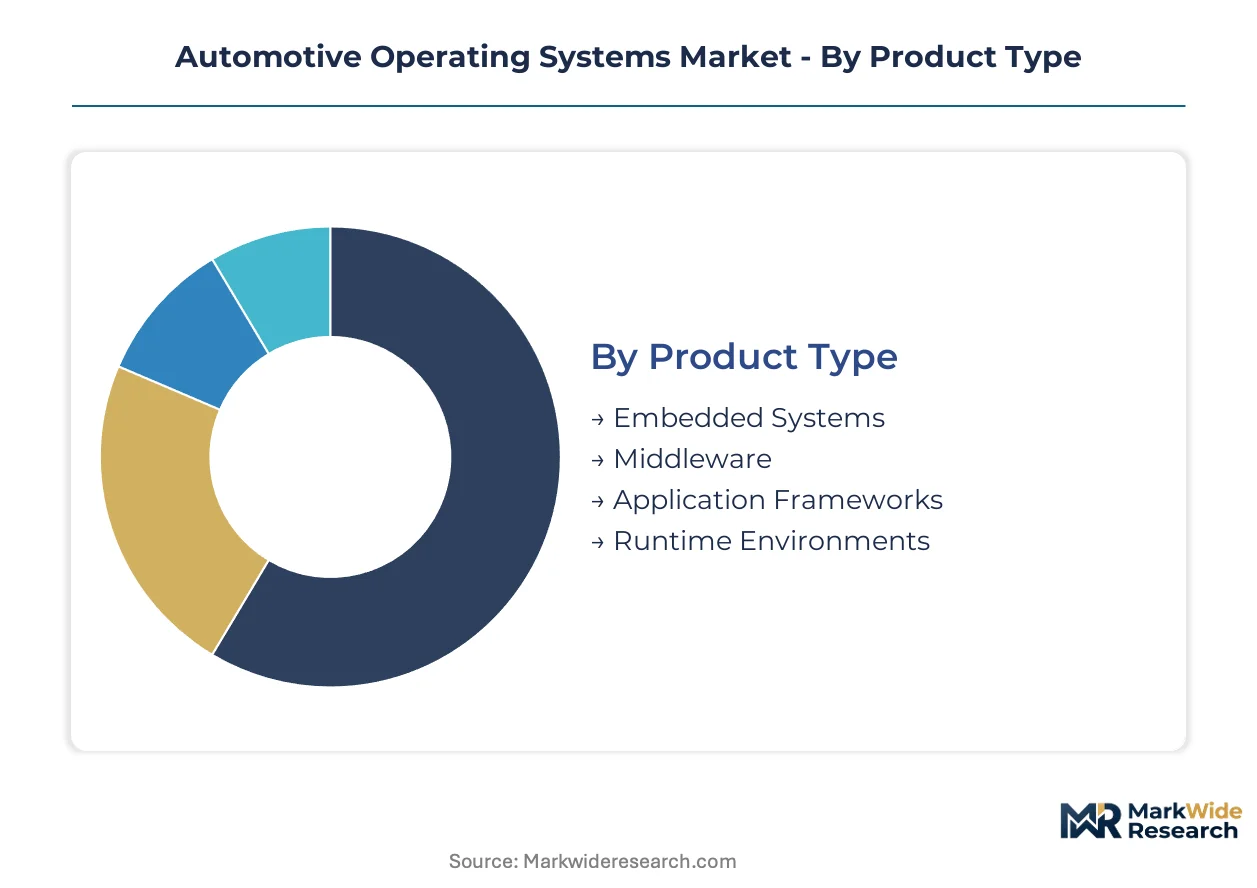
Automotive operating systems fragment across hardware abstraction layers, virtualization technologies, and functional safety domains. Procurement patterns diverge sharply between chassis-critical stacks demanding ISO 26262 certification and infotainment layers prioritizing developer ecosystem breadth.
Product Type:
Technology specification determines integration depth and margin capture across the software stack.
- Embedded Systems:Bare-metal firmware and board support packages execute deterministic control loops on microcontrollers with sub-50-microsecond interrupt latency. Demand clusters in Germany's Stuttgart-Munich corridor where Bosch and Continental engineering centers specify ASIL-D certified stacks for brake-by-wire modules.
- Middleware:Inter-process communication frameworks and data distribution services bridge heterogeneous ECU networks. Deployment is accelerating in software-defined vehicle programs where zonal architectures require standardized publish-subscribe protocols across previously isolated domains.
- Application Frameworks:Software development kits and API layers abstract hardware complexity for third-party developers.
- Runtime Environments:Virtual machines and container orchestration layers enable over-the-air feature deployment.
Mature deployment sits with Embedded Systems. Newer deployment is concentrated in Runtime Environments.
Technology:
Kernel architecture selection locks in long-term supplier relationships and certification investment recovery.
- RTOS:Microkernel architectures deliver deterministic task scheduling with formal verification for safety-critical functions. Procurement concentrates in powertrain and chassis domains where UN ECE regulations mandate fail-operational behavior.
- Linux-Based:Android Automotive and Automotive Grade Linux dominate infotainment through royalty-free distribution and consumer-app ecosystem compatibility. Volume leadership here compresses pricing power even as installation counts expand fastest.
- Automotive Open System Architecture:Standardized software component frameworks enable OEM-Tier-1 interoperability.
- Hypervisor:Type-1 virtualization layers consolidate mixed-criticality workloads on single compute platforms.
RTOS maintains the steepest expansion trajectory in ADAS compute. Linux-Based stacks capture the broadest installation base.
End User:
Buyer sophistication and liability exposure shape procurement sophistication and contract structure.
- OEMs:Volkswagen Group, Toyota, and Hyundai-Kia consolidate purchasing through captive software subsidiaries, compressing Tier-2 vendor pricing leverage. Direct procurement of foundational OS layers is climbing as vertical integration strategies deepen.
- Tier-1 Suppliers:Continental, Bosch, and Denso intermediate safety-critical stack integration for OEMs lacking embedded systems expertise. These suppliers command premium margins on ASIL-certified configurations.
- Aftermarket Providers:Telematics retrofit and infotainment upgrade specialists source commodity Linux distributions.
- System Integrators:Engineering services firms customize hypervisor configurations for zonal architecture migrations.
Established relationships sit with Tier-1 Suppliers. Direct engagement is climbing fastest among OEMs.
Application:
Functional domain determines real-time requirements, certification burden, and update frequency.
- Infotainment:Graphical user interface frameworks and media processing pipelines execute on application processors without hard real-time constraints. India's underpenetrated engineering talent base presents white space for offshore development centers serving European OEM digital cockpit programs.
- ADAS:Sensor fusion and path planning algorithms demand POSIX-compliant real-time extensions on heterogeneous compute. EU Cyber Resilience Act mandates are forcing intrusion detection integration into previously isolated perception stacks.
- Telematics:Cellular connectivity modules and cloud gateway functions manage over-the-air update distribution.
- Vehicle Control:Powertrain management and thermal regulation systems require deterministic closed-loop control.
Volume concentration sits with Infotainment. Margin expansion is concentrating in ADAS.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors automotive operating systems procurement through its dense concentration of Tier-1 engineering centers and OEM headquarters. The city's supplier ecosystem drives ISO 26262 certification demand across safety-critical software stacks. This German corridor sets technical specifications that cascade through European and Asian supply chains.
Germany
Bosch and Continental engineering centers in Stuttgart and Munich specify ASIL-D certified RTOS architectures for brake-by-wire and steer-by-wire modules. The EU Cyber Resilience Act mandates intrusion detection capabilities across all ECU operating environments, compelling Tier-1 suppliers to upgrade middleware stacks. The Baden-Württemberg automotive corridor concentrates procurement decisions for Volkswagen Group and Mercedes-Benz programs.
United States
NHTSA software bill of materials disclosure requirements are forcing granular open-source component tracking across supplier networks. Silicon Valley autonomous driving programs demand POSIX-compliant real-time extensions for sensor fusion compute. Michigan's Detroit-Toledo corridor hosts engineering centers where Ford and General Motors consolidate operating system procurement through captive software subsidiaries.
China
MIIT cybersecurity mandates parallel UN ECE R155/R156 type-approval requirements for connected vehicle software. Domestic EV platforms accelerate zonal E/E architecture adoption requiring deterministic task scheduling across battery management systems. Shanghai's Pudong district clusters autonomous driving R&D centers where Baidu and Huawei develop proprietary OS layers for Level 2+ programs.
Japan
METI industrial policy supports domestic software stack development to reduce dependence on foreign RTOS vendors. Toyota and Denso engineering centers in Nagoya specify microkernel architectures for fail-operational autonomous driving systems. The Kansai region's supplier hierarchy reinforces incumbent positioning through long-term framework agreements with captive software subsidiaries.
India
PLI scheme incentives for automotive electronics manufacturing attract offshore development centers serving European OEM digital cockpit programs. Embedded systems engineering talent concentrates in Bangalore and Hyderabad despite RTOS expertise scarcity. Domestic EV startups source commodity Linux distributions for infotainment while importing certified safety stacks from German suppliers.
Automotive Operating Systems Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification grade and functional safety domain. The vendor base stratifies between aerospace-grade reliability specialists and middleware integration speed competitors. Three archetypes dominate: microkernel RTOS vendors with ISO 26262 heritage, Linux-based infotainment stack providers, and hypervisor consolidation specialists. Competitive moves concentrate on strategic partnerships for zonal architecture programs and technology licensing to captive OEM software subsidiaries.
Within the microkernel RTOS tier, BlackBerry QNX and Green Hills Software exemplify safety-critical specialization through their certification heritage. Wind River Systems occupies a position bridging aerospace reliability benchmarks with automotive autonomous driving compute. Elektrobit anchors the middleware integration segment for European OEM digital cockpit programs. These three vendors represent distinct competitive vectors: formal verification depth, cross-industry reliability transfer, and European Tier-1 supplier proximity.
| Leading Market Players |
|---|
| Green Hills Software |
| Elektrobit |
| Continental AG |
| Intellias |
| Vector Informatik |
| Cerence |
| Wind River Systems |
| DXC Technology |
| BlackBerry QNX |
| Others |
Supply Flow & Price Mechanics
REACH and RoHS substance restrictions gate qualified supply for automotive-grade processors, compelling Tier-1 suppliers to absorb elevated validation costs that transmit into premium-tier pricing for ISO 26262-certified stacks. Battery management and thermal control systems demand alternative substrate materials, compressing margins on non-compliant commodity layers while elevating certified RTOS pricing power.
Pricing Analysis
Value-based pricing anchored to functional safety outcomes dominates procurement for brake-by-wire and steer-by-wire modules. Certification grade and volume scale drive price differentiation, with ASIL-D stacks commanding substantial premiums over ASIL-B configurations. Cost compression in infotainment Linux layers intensifies because Android Automotive's royalty-free model erodes licensing leverage. Aftermarket providers exhibit highest price sensitivity, while OEMs captive software subsidiaries show lowest sensitivity for safety-critical procurement.
Supply Chain Analysis
India's PLI scheme domestic-content mandates are reshaping sourcing patterns for offshore development centers serving European OEM programs. Semiconductor fabrication concentrates in Taiwan, South Korea, and Germany, with automotive-grade packaging drawing from specialized foundry capacity. Raw material dependencies span silicon wafers, rare earth substrates, and RoHS-compliant thermal interface materials. Single-source vulnerability around advanced node automotive processors elevates supply chain risk. Distribution runs through Tier-1 integrator channels rather than direct OEM relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
RTOS talent scarcity props pricing for certified embedded systems engineers, constraining supply-side expansion and sustaining margin pools for incumbents with established expertise concentration.
For Market Incumbents: Deploy certification investment leverage by deepening ASIL-D coverage across zonal architecture migrations before Linux-based stacks encroach on chassis domains. Prioritize backward integration into hypervisor layer development to preserve supplier liability boundaries against emerging captive OEM software subsidiaries. Channel control over Stuttgart-Munich engineering corridors remains critical. For New Entrants and Emerging Players: The mid-tier pricing gap between BlackBerry QNX premium positioning and commodity Android Automotive distributions offers white-space entry. India's underpenetrated engineering talent base presents the most penetrable geography for offshore development centers serving European digital cockpit programs. Pursue middleware integration speed as the primary go-to-market angle against established RTOS vendors. For Investors and Strategic Acquirers: Tier-1 supplier consolidation of operating system procurement through captive subsidiaries is the leading indicator that vertical integration trends will accelerate. Long-term viability favors aerospace-grade reliability specialists with cross-industry certification heritage over pure-play automotive middleware vendors. Target acquisition archetype: microkernel RTOS vendors with formal verification depth. Watch for MIIT cybersecurity mandate harmonization with UN ECE R155 as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Volkswagen Group's consolidation through captive software subsidiaries compresses Tier-2 vendor pricing leverage. |
| Software-Defined Vehicle Investment | Recurring revenue models through feature-on-demand modules shift value capture from hardware to subscription layers. |
| Battery Supply Agreement | Zonal E/E architectures for EV platforms demand deterministic RTOS scheduling across thermal management systems. |
| Geographic Manufacturing Footprint | India's PLI incentives attract offshore development centers serving Stuttgart-Munich engineering corridors. |
| Charging Infrastructure Partnership | Telematics gateway functions require cybersecurity-certified OS layers under EU Cyber Resilience Act mandates. |
Methodological Framework
SEC filings, IHS Markit vehicle production databases, and UN ECE regulatory submissions formed the secondary backbone, cross-referenced with primary interviews spanning OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and embedded systems R&D directors. Bottom-up and top-down triangulation validated installation counts and pricing trajectories across kernel architecture segments.
Bottom-up modeling aggregated content-per-vehicle assumptions across propulsion architectures and vehicle classes, while top-down approaches calibrated aggregate market evolution against OEM software spending disclosures. Segmentation dimensions spanned product type, kernel technology, end-user procurement sophistication, and application domain criticality. CAGRs derived from regression against electrification penetration curves and regulatory mandate implementation timelines, with zonal E/E architecture adoption rates and ADAS compute proliferation as key automotive-specific inputs.
Inputs from OEM software subsidiary disclosures and Tier-1 supplier annual reports were available through the study window; gaps in proprietary hypervisor licensing terms introduce uncertainty bands around consolidation scenario outcomes. Forecasts reflect documented assumptions on electrification pace and cybersecurity regulatory harmonization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Waterway Transportation Software Solutions Market
Software & Services
North America IT Services Market
Software & Services
Supply Chain Visibility (SCV) Software Market
Software & Services
Gym Management Software Market
Software & Services
Survey and Feedback Management Software Market
Software & Services
IT Service Management Tools Market
Software & Services
Reporter Systems Market
Software & Services
Ecommerce Software and Platform Market
Software & Services
Automotive Dealer Management Systems (DMS) Market
Software & Services
Terminal Emulator Software Market
Software & Services
Construction and Design Software Market
Software & Services
Global App Store Optimization Tools Software Market
Software & Services
Balance Sheet Management Software Market
Software & Services
K8s Market
Software & Services
Germany HR Payroll Software Market
Software & Services
Global AR Game Engine Software Market