
 Deck Design Software Market | 2026-2036
Deck Design Software Market Size, Share, and Industry Trends Forecast 2026-2036
Deck Design Software Market Outlook
Subscription-based feature modules is decoupling perpetual license revenue from core CAD engine sales in the deck design sector. Autodesk Inc. leverages its construction cloud ecosystem to extend tool interoperability across residential and commercial project workflows. Chief Architect, Inc. anchors its position through deep specialization in North American building code libraries and framing automation. Cedreo competes aggressively on browser-native rendering speed, reducing hardware barriers for contractor adoption.
Deck design software encompasses computer-aided design applications engineered to generate structural plans, material takeoffs, and photorealistic visualizations for outdoor platform construction, typically incorporating load-bearing calculations, joist spacing algorithms, and compliance checking against local building ordinances. Residential Software dominates current revenue as renovation-driven homeowners prioritize visualization fidelity over engineering depth, while Cloud-based deployment records the fastest expansion by eliminating installation friction for distributed contractor teams. Augmented Reality features command premium positioning by collapsing the sell-cycle between designer presentation and homeowner approval.
US municipalities enforce deck construction standards through ICC (International Code Council) adopted regulations, while OSHA governs fall protection protocols that influence railing height and baluster spacing parameters embedded in design algorithms. The National Building Code of Canada and Australia's NCC (National Construction Code) similarly shape software localization requirements for multi-jurisdiction vendors. Stakeholders must monitor whether AI-generated structural plans trigger new professional liability frameworks that redefine the boundary between software tool and engineering judgment.
Market Dynamics
Subscription-based feature modules are decoupling perpetual license revenue from core CAD engine sales, forcing vendors to rebuild recurring revenue architectures around browser-native deployment and cloud rendering infrastructure.
Growth Catalysts
- Building code digitization:ICC-adopted regulations across US municipalities accelerate specification of code-compliant design tools that auto-validate structural parameters against local ordinances.
- Outdoor living investment:North American suburban homeowners are prioritizing deck renovation projects, driving contractor procurement of visualization software to accelerate homeowner approvals.
- Cloud rendering:Browser-native architectures eliminate hardware barriers for distributed contractor teams, expanding addressable market to smaller residential builders without workstation investments.
Market Restraints
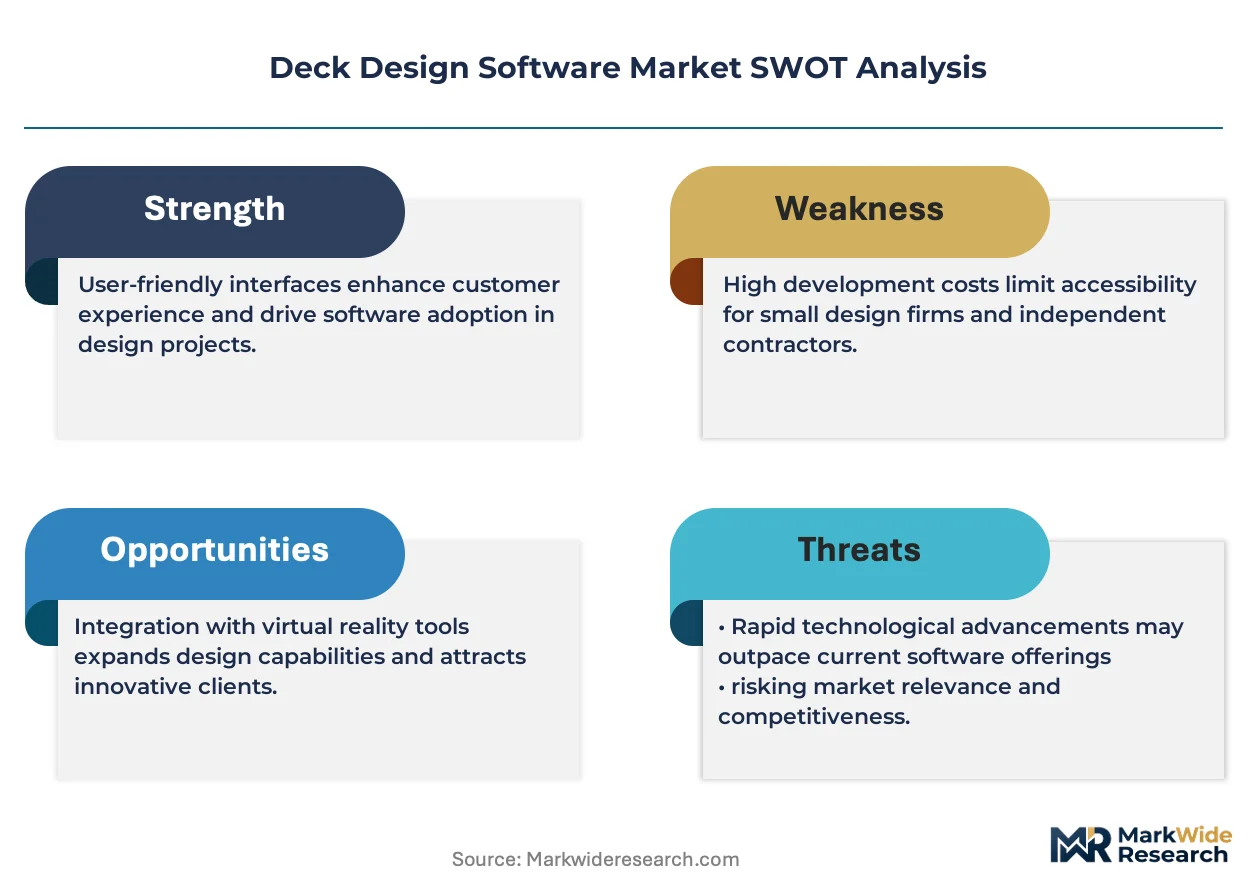
- Professional liability ambiguity:AI-generated structural plans create unresolved boundaries between software tool and engineering judgment, exposing vendors to litigation frameworks not designed for algorithmic design outputs.
- Input cost volatility:Lumber price fluctuations compress contractor margins, reducing discretionary software spending during material inflation cycles.
- Localization burden:Multi-jurisdiction vendors must maintain separate code libraries for National Building Code of Canada, Australia's NCC, and US ICC standards, fragmenting R&D resources.
Strategic Opportunities
- Augmented Reality convergence:AR visualization features command premium positioning by collapsing sell-cycles between designer presentation and homeowner approval in residential renovation workflows.
- OSHA compliance integration:Fall protection protocol automation in railing height and baluster spacing algorithms creates differentiation for contractors serving commercial multi-family projects.
- Material takeoff automation:Joist spacing algorithms paired with supplier API integrations enable direct-to-distributor ordering, capturing procurement margin from traditional lumber yards.
Industry Challenges
- Legacy system integration:Established contractors running on-premise CAD installations face data migration friction when transitioning to cloud-native platforms, lengthening sales cycles.
- Building code update latency:Municipal ordinance changes require real-time algorithm adjustments; vendors lacking automated code library pipelines risk non-compliance during permit submission windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deck Design Software Market |
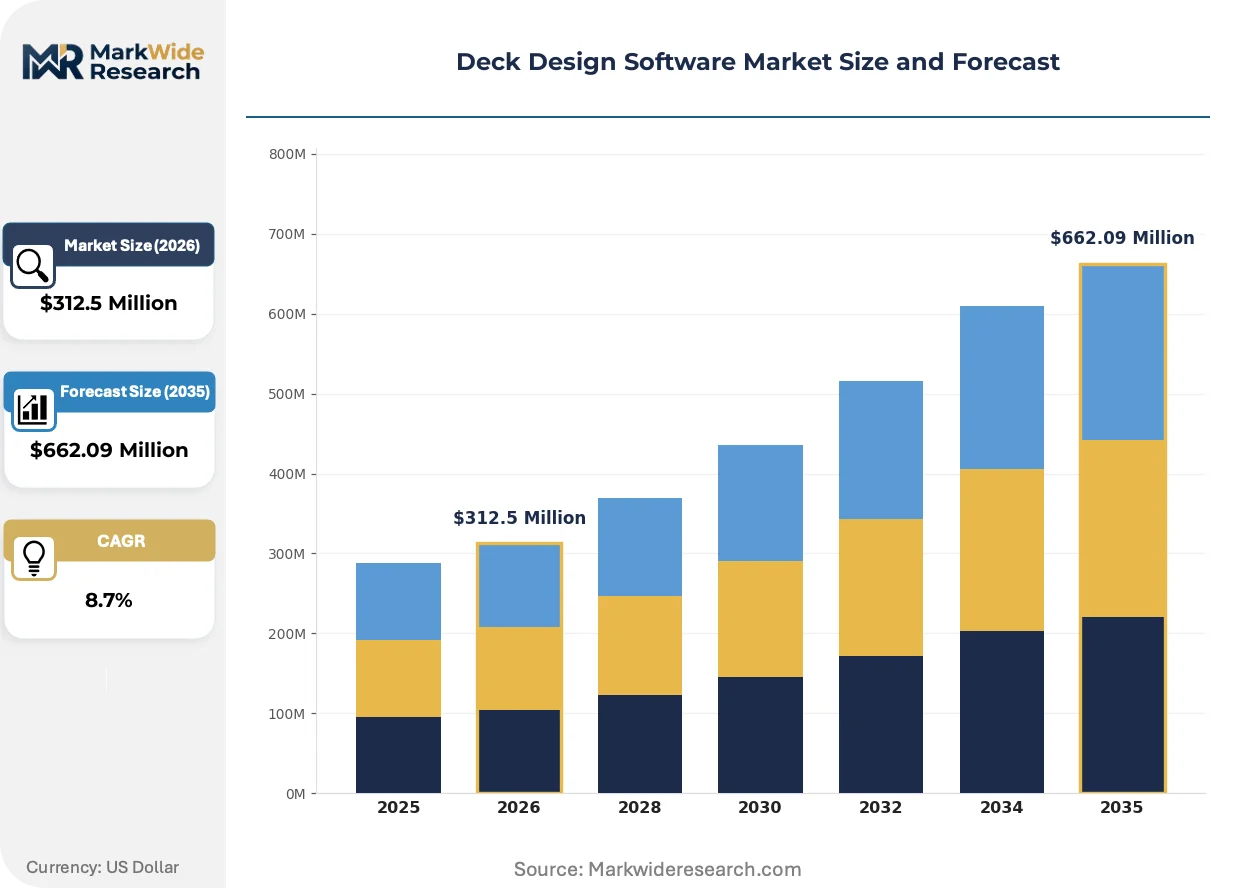
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Software, Commercial Software, Online Platforms, Mobile Applications End User: Contractors, Homeowners, Architects, Designers Deployment: Cloud-based, On-premises, Hybrid Solutions, Subscription Models Feature: 3D Visualization, Material Estimator, Design Templates, Augmented Reality |
| Companies Covered | Autodesk Inc., Chief Architect, Inc., Cedreo, Dassault Systèmes, Trimble Inc., SmartDraw, LLC, RoomSketcher AS, Idea Spectrum, Inc., Trex Company, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deck Design Software Market Strategic Shifts
Browser-native rendering architectures are compressing hardware requirements and reshaping competitive positioning around accessibility rather than processing power. Three developments are restructuring value capture in deck design software.
Cloud-based deployment is decentralizing computational workloads from contractor workstations to vendor-managed servers. Small residential builders without dedicated IT infrastructure are adopting these platforms fastest, eliminating upfront capital barriers that previously excluded them from professional-grade visualization tools. This shift is decentralizing market power from established CAD incumbents toward specialized browser-native competitors.
OSHA fall protection protocols are embedding directly into design algorithms, automating railing height and baluster spacing calculations that previously required manual engineering review. The industrial consequence is reduced permit rejection rates for contractors serving commercial multi-family projects. Commercial specification teams are responding by mandating software that pre-validates against OSHA standards before submittal.
Homeowner-driven visualization fidelity is displacing engineering depth as the primary procurement criterion in residential renovation. Contractors are unbundling photorealistic rendering from structural calculation modules, purchasing visualization-only subscriptions for client presentations. This pattern concentrates most visibly in United States suburban markets where outdoor living investment sustains premium positioning for presentation-grade outputs.
Deck Design Software Market Segmentation
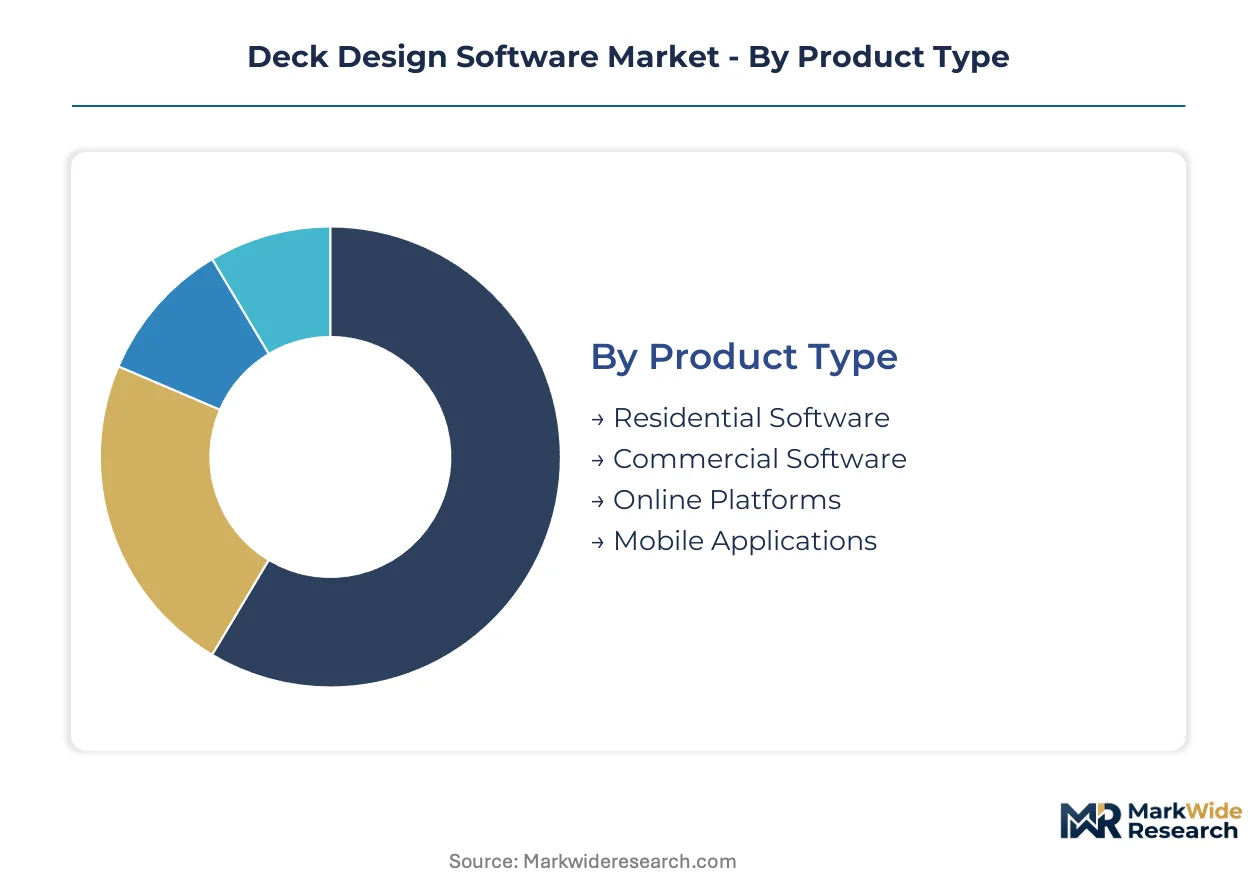
Deck design software vendors configure product architectures around distinct buyer workflows, from permit-driven contractors requiring code compliance to homeowners prioritizing photorealistic visualization. Segmentation reveals where engineering depth commands premium pricing versus where accessibility drives volume adoption.
Product Type:
Residential Software anchors volume sales through renovation-driven homeowner demand, while Commercial Software captures premium pricing through structural engineering depth and multi-jurisdiction code libraries.
- Residential Software:Visualization-centric applications optimized for single-family deck projects with automated joist spacing and material takeoff calculators. Demand concentrates in United States suburban markets where outdoor living renovation permits are surging, with contractors purchasing visualization-first subscriptions to accelerate homeowner approvals.
- Commercial Software:Engineering-grade platforms integrating ICC code validation, load-bearing calculations, and OSHA fall protection compliance for multi-family and hospitality projects. Procurement is strongest among contractors serving municipal and commercial multi-family developments where permit rejection carries heavy cost penalties.
- Online Platforms:Browser-native tools eliminating hardware barriers for distributed contractor teams.
- Mobile Applications:Field-optimized interfaces for on-site measurement capture and client presentation.
Mature deployment sits with Commercial Software. Newer deployment is concentrated in Online Platforms.
End User:
Contractor procurement patterns split between established firms investing in comprehensive platforms and independent operators adopting modular, subscription-based tools.
- Contractors:Primary revenue source spanning residential renovation specialists and commercial deck builders. United States residential contractors represent the steepest expansion trajectory as deck renovation permits surge in North American suburbs, driving software procurement cycles tied to visualization and code compliance needs.
- Homeowners:Direct purchasers of simplified design tools for DIY project planning and material estimation.
- Architects:Specification influencers requiring BIM interoperability and structural calculation depth for integrated building designs.
- Designers:Visualization-focused users prioritizing photorealistic rendering for client presentation workflows.
Established specification authority rests with Architects. Fastest adoption velocity appears among Contractors.
Deployment:
Cloud migration is redistributing computational workloads from buyer-owned infrastructure to vendor-managed servers, reshaping pricing architectures around recurring subscription revenue.
- Cloud-based:Browser-native architectures rendering photorealistic visualizations on remote servers. Small residential builders without workstation investments are adopting these platforms fastest, eliminating upfront capital barriers that previously excluded them from professional-grade tools.
- On-premises:Legacy CAD installations maintained by established contractors with dedicated IT infrastructure and data sovereignty requirements.
- Hybrid Solutions:Mixed deployments combining local processing for sensitive structural calculations with cloud rendering for client presentations.
- Subscription Models:Feature-modular pricing decoupling perpetual licenses from core engine access, enabling tiered access to visualization, engineering, and code library functions.
Legacy dominance persists in On-premises. Subscription Models are gaining share fastest among new adopters.
Feature:
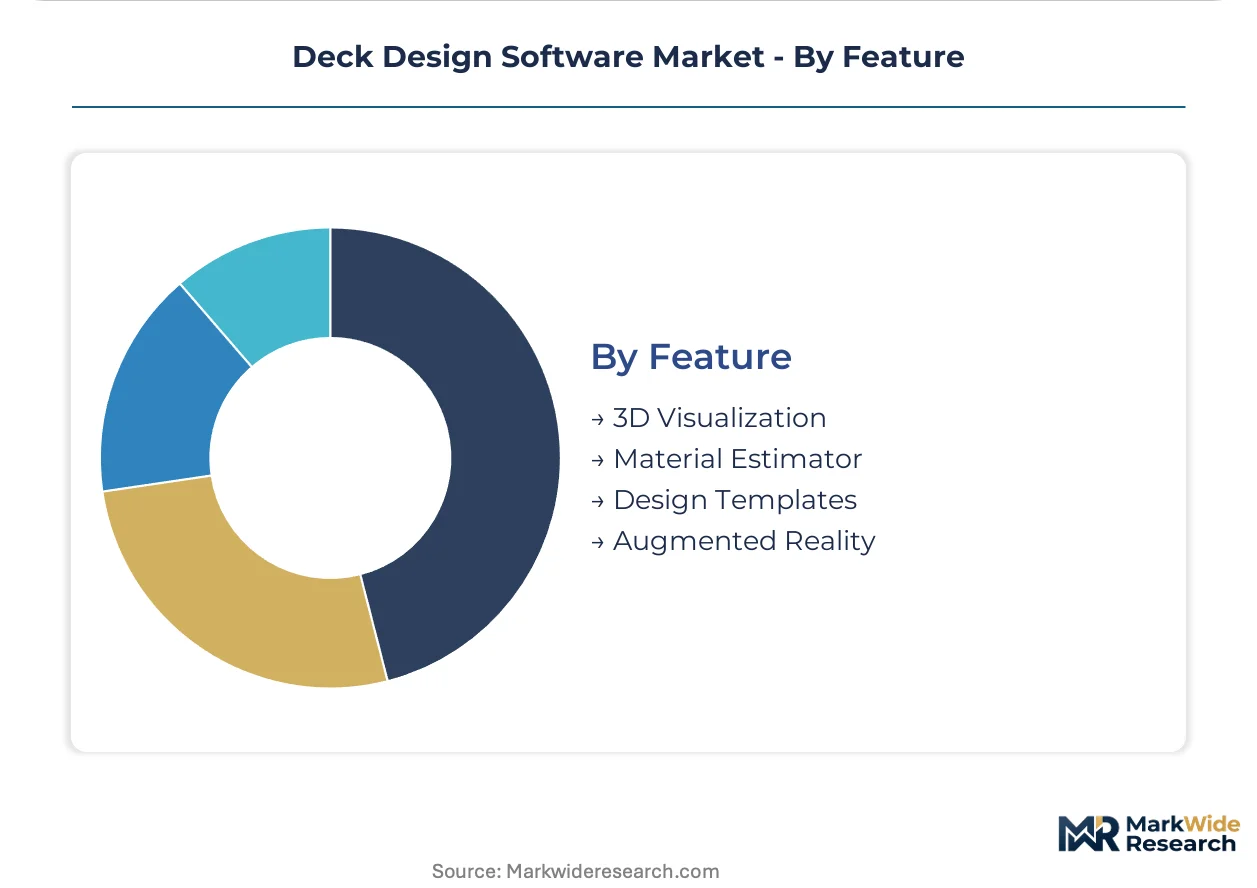
Capability unbundling allows buyers to purchase visualization depth separately from engineering functions, concentrating premium pricing in modules that collapse design-to-approval timelines.
- 3D Visualization:Photorealistic rendering engines producing presentation-grade deck models for homeowner approval. Contractors in United States suburban markets are unbundling this capability from structural modules, purchasing visualization-only subscriptions where outdoor living investment sustains premium positioning.
- Material Estimator:Automated takeoff calculators integrating joist spacing algorithms with supplier pricing databases.
- Design Templates:Pre-configured deck layouts accelerating project initiation for novice users and standardized builds.
- Augmented Reality:Overlay visualization collapsing sell-cycles between designer presentation and homeowner approval. AR-enabled platforms command premium positioning in residential renovation workflows by enabling real-time spatial validation on-site.
Baseline functionality concentrates in Design Templates. Augmented Reality is climbing the fastest as a differentiation lever.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in established technology corridors, while consumption clusters in suburban construction markets where renovation permits drive procurement cycles. The United States generates disproportionate demand from single-family housing starts and outdoor living investment. Canada and Australia follow with code-digitization initiatives accelerating vendor specification.
United States
Deck renovation permits in North American suburbs are surging, driving contractor procurement of visualization and code-compliance tools. OSHA governs fall protection protocols that influence railing height and baluster spacing parameters embedded in design algorithms. Dallas-Fort Worth and Phoenix construction corridors are seeing concentrated adoption of browser-native platforms among distributed residential builders.
Canada
The National Building Code of Canada shapes software localization requirements for multi-jurisdiction vendors serving cross-border contractors. Municipal digitization initiatives in Ontario and British Columbia are accelerating specification of code-compliant design tools. Toronto's residential construction cluster is driving demand for cloud-based deployment among mid-sized renovation specialists.
Australia
The National Construction Code (NCC) mandates compliance checking that influences algorithm development for deck load-bearing calculations. Sydney and Melbourne metropolitan areas are seeing outdoor living investment sustain procurement of photorealistic visualization modules. Local contractors are prioritizing AR-enabled platforms to collapse sell-cycles with homeowners.
United Kingdom
Building regulation digitization across English municipalities is creating specification pathways for automated compliance tools. London's architectural specification community is influencing BIM interoperability requirements for integrated deck designs. Southeast England renovation markets are driving contractor adoption of subscription-based visualization modules.
Germany
Precision engineering culture is shaping demand for structural calculation depth over presentation-grade rendering in commercial deck projects. The country's federal building code framework requires localized algorithm adaptations for permit validation. Munich and Stuttgart construction clusters are specifying platforms with integrated material takeoff automation for timber procurement efficiency.
Deck Design Software Market Competitive Environment
Capital-heavy construction software conglomerates compete with asset-light browser-native specialists for contractor mindshare. The vendor base splits between diversified CAD incumbents with cloud ecosystem leverage and focused deck-design specialists with code-library depth. Three archetypes dominate: platform conglomerates extending construction cloud footprints, vertical specialists anchoring on North American framing automation, and rendering-native challengers competing on hardware accessibility. Competitive moves concentrate on interoperability partnerships with building material distributors and AR feature development to capture residential renovation premiums.
Among North American specialists, Chief Architect, Inc. and Idea Spectrum, Inc. exemplify the vertical-specialist archetype with deep building-code library investments. Autodesk Inc. represents the platform-conglomerate tier, leveraging construction cloud infrastructure to extend tool interoperability across residential and commercial workflows. Cedreo occupies a position among browser-native challengers, competing on rendering speed to reduce hardware barriers for contractor adoption.
| Leading Market Players |
|---|
| Autodesk Inc. |
| Chief Architect, Inc. |
| Cedreo |
| Dassault Systèmes |
| Trimble Inc. |
| SmartDraw, LLC |
| RoomSketcher AS |
| Idea Spectrum, Inc. |
| Trex Company, Inc. |
| Others |
Value Chain & Pricing Dynamics
OSHA fall protection protocol digitization gates qualified supply for premium-tier deck design software, restricting vendor access to commercial multi-family project specifications while elevating pricing power for platforms with automated compliance validation. Contractors serving municipal developments face procurement thresholds that tie subscription tier eligibility to certified code library depth, compressing mid-market vendor margins while reinforcing incumbent pricing architecture.
Pricing Analysis
Margin tightening in cloud-native tiers reflects browser-based deployment cost structures displacing perpetual license premiums. Three-tier pricing structure across premium, standard, and economy levels segments on code library breadth, with ICC validation and OSHA automation commanding top-tier positioning. Price differentiation traces to certification depth and rendering fidelity, with visualization-only subscriptions facing downward pressure from open-source alternatives. Independent residential contractors exhibit highest price sensitivity, while commercial multi-family specifiers prioritize compliance accuracy over subscription cost.
Supply Chain Analysis
ISO 27001 and SOC 2 certification gating restricts cloud infrastructure vendor eligibility for enterprise contractor deployments, concentrating qualified hosting supply among US-based hyperscalers. Core algorithm development concentrates in the United States, Canada, and France, with rendering engine components drawing from specialized graphics processing foundries in Taiwan and South Korea. Supply chain risk centers on single-source vulnerability for ICC code library updates, where municipal ordinance changes require real-time vendor pipeline responsiveness. Distribution runs through direct SaaS provisioning and building material distributor API partnerships, with lumber yard channel integration emerging as a secondary pathway.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over building material supplier APIs represents the decisive downstream lever. Players capturing procurement workflow integration will extract margin from traditional lumber yard intermediaries.
For Market Incumbents: Extend cloud ecosystem interoperability to lock in contractor workflow dependency, while accelerating automated code library pipelines to neutralize municipal update latency risks. Browser-native challengers threaten established CAD incumbents through hardware accessibility; defend by embedding deeper framing automation and exclusive ICC validation partnerships. Prioritize API integration with top-10 North American building material distributors to capture procurement margin. For New Entrants and Emerging Players: Small residential builders without dedicated IT infrastructure represent the most penetrable buyer archetype, with visualization-first subscriptions offering lowest barrier to entry. White-space concentration appears in Australia and United Kingdom outdoor living renovation markets, where AR-enabled platforms remain underpenetrated. Target geographic expansion through browser-native deployment eliminating localization hardware requirements, with go-to-market positioning around collapsing homeowner approval cycles. For Investors and Strategic Acquirers: Surging deck renovation permit volumes in Dallas-Fort Worth and Phoenix construction corridors is the leading indicator that contractor software procurement cycles are entering sustained expansion. Long-term viability favors platforms with hybrid cloud-on-premise architectures serving established contractors with data sovereignty requirements. Acquisition target archetype: vertical specialists with deep North American framing automation and exclusive municipal code library relationships. Monitor ICC adoption velocity across mid-sized US municipalities as the leading inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API connectivity with Trex and TimberTech distributor systems captures procurement workflow control from lumber yards. |
| Geographic Expansion | Browser-native deployment into Toronto and Vancouver clusters leverages Canadian National Building Code digitization momentum. |
| Acquisition of Specialist Firm | Deep ICC code library assets neutralize municipal update latency risks threatening permit approval timelines. |
| Product Launch | AR visualization modules targeting Sydney and Melbourne contractors collapse sell-cycles in outdoor living renovation markets. |
| Strategic Partnership | OSHA compliance integration with commercial multi-family project managers differentiates against visualization-only competitors. |
Study Parameters
Multi-period observation of deck renovation permit filings, contractor software procurement cycles, and municipal code digitization timelines anchored the trend analysis, supplemented by interviews with residential construction software executives, building code compliance officers at ICC-adopted municipalities, lumber yard procurement directors, and cloud platform engineering leads. Secondary validation drew from municipal permit databases, SEC filings of publicly traded building material suppliers, construction industry association expenditure surveys, and hyperscaler cloud infrastructure disclosure reports. Bottom-up contractor adoption modeling triangulated against top-down market sizing across deployment modes and end-user segments.
Segment-weighting approaches distributed value estimates across cloud-based, on-premises, and hybrid deployment architectures, with additional stratification by residential versus commercial software product types and contractor versus homeowner end-user categories. CAGRs were derived from fitted growth curves applied to observed adoption velocity in United States suburban markets, with cross-validation against Australian and Canadian permit trend trajectories. Forecast inputs incorporated outdoor living investment indices, single-family housing start correlations, and building material price volatility assumptions.
Revisions become necessary when municipal ordinance automation mandates accelerate beyond vendor code library update capacities, or when AI-generated structural plan liability frameworks trigger professional insurance requirement changes. Forecasts reflect documented assumptions regarding contractor SaaS transition velocity and ICC adoption saturation curves across mid-sized US municipalities. A model refresh is warranted upon material change in lumber price volatility patterns or OSHA fall protection protocol algorithmic enforcement thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Legal Case Management Software Market
Software & Services
Legal Practice Management Software Market
Software & Services
Global Cinema Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Classified Platform Market
Software & Services
Global Cloud Based Collaboration Software Market
Software & Services
Online Recruitment Software Market
Software & Services
Software Release Management Tools Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Asia-Pacific Saas-Based SCM Market
Software & Services
Global Award Management Software Market
Software & Services
Global Brain Training Software Market
Software & Services
Global Blue Prism Technology Services Market
Software & Services
Metal Recycling Software Market
Software & Services
Automotive Design Software Market
Software & Services
Telecom IT Services Market