
 Truck Dispatch Software Market | 2026-2036
Truck Dispatch Software Market Size, Share, and Industry Trends Forecast 2026-2036
Truck Dispatch Software Market Insights
The shift from single-source dispatch tools to multi-platform ecosystems is broadening vendor opportunity in fleet technology. Samsara leverages cloud-native architecture to capture mid-market fleet operators seeking unified visibility. McLeod Software anchors enterprise-grade transportation management with deep workflow customization for large carriers. Trimble competes through GPS-integrated hardware-software bundles that dominate construction-adjacent trucking verticals.
Truck dispatch software coordinates freight assignment, route sequencing, and driver communication through algorithmic matching engines and real-time telematic feeds. Core systems process GPS location streams, engine diagnostics, and regulatory clock data to automate load matching against hours-of-service constraints. Cloud-based deployment leads segment adoption as operators abandon server maintenance for elastic compute scaling. Fleet operators represent the fastest-growing end-user category as private fleets insource dispatch control previously managed by third-party brokers. AI-driven route optimization commands premium pricing within solution segments by reducing empty-mile penalties and fuel burn.
The FMCSA enforces electronic logging device compliance that shapes product design around automated hours-of-service tracking. ISO 9001 quality management standards and emerging cybersecurity frameworks from NIST influence procurement criteria for enterprise buyers. Stakeholders must weigh API interoperability against vendor lock-in as dispatch platforms consolidate adjacent fleet functions into unified operating systems.
Market Dynamics
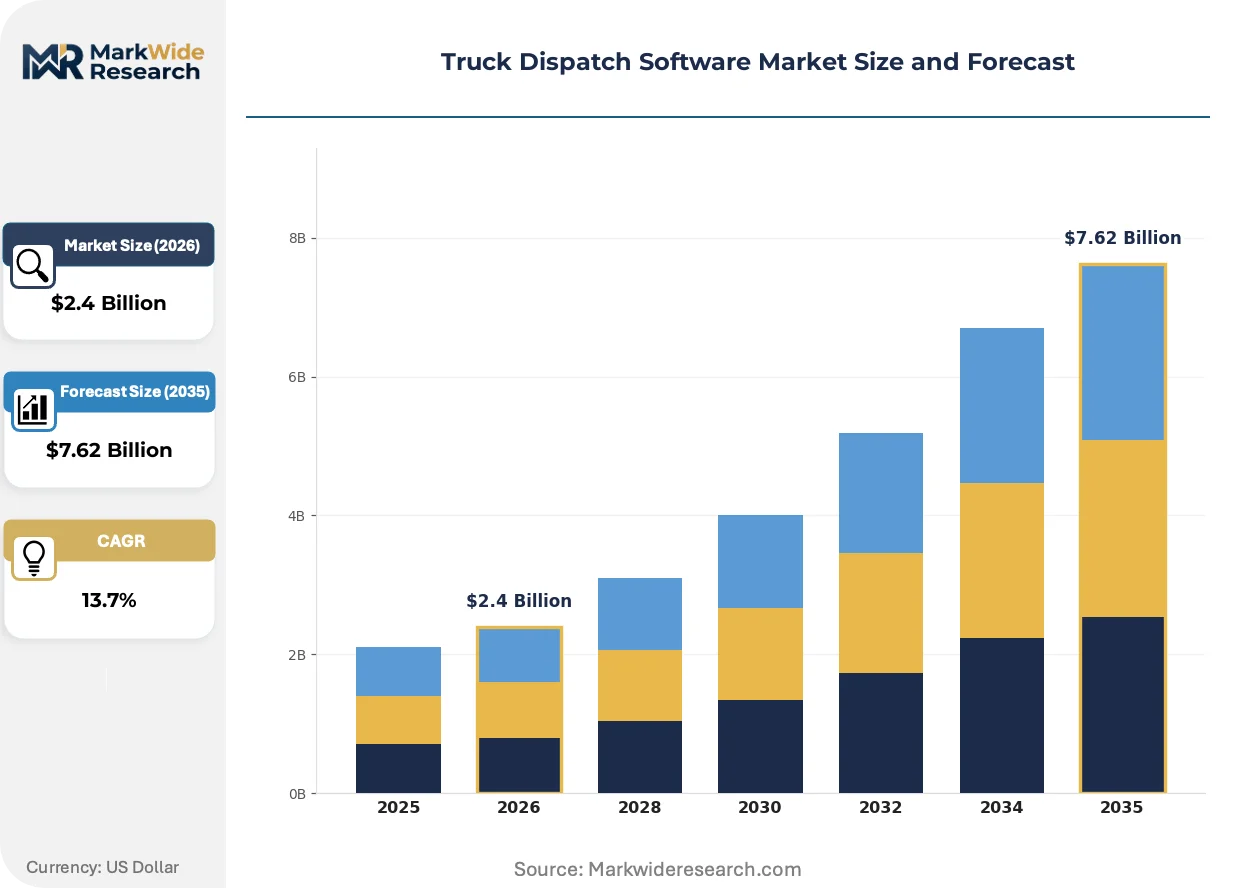
Cloud migration is compressing deployment timelines and collapsing the vendor landscape as fleet operators abandon on-premise infrastructure for elastic compute scaling. The FMCSA's ELD mandate created compliance-driven procurement cycles that now favor integrated dispatch-telematics bundles over point solutions.
Growth Catalysts
- ELD Compliance Mandates:FMCSA enforcement of electronic logging device rules forces carriers to adopt integrated dispatch systems that automate hours-of-service tracking and violation alerts.
- Private Fleet Expansion:Retailers and manufacturers are insourcing dispatch control from third-party brokers, driving direct software procurement by shippers with captive trucking assets.
- AI Route Optimization:Machine learning algorithms that minimize empty miles and fuel consumption command premium pricing as fuel volatility squeezes carrier margins.
Market Restraints
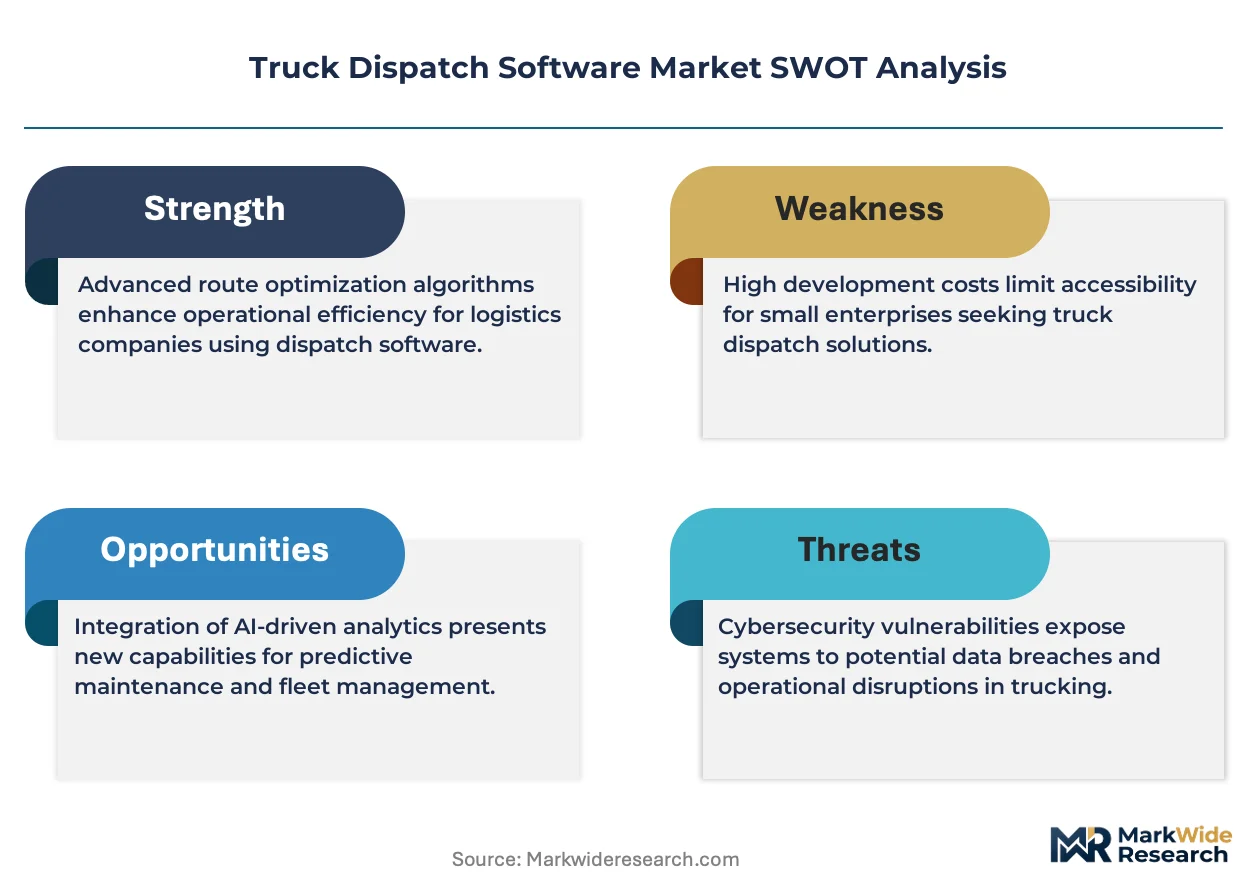
- API Fragmentation:Proprietary data formats between telematics hardware, TMS platforms, and broker networks force expensive custom integration work for multi-vendor fleets.
- Midwest Carrier Concentration:Demand clustering around Chicago and Dallas creates geographic dependency risk when regional freight volumes fluctuate seasonally.
- Cybersecurity Compliance Costs:Emerging NIST frameworks for connected vehicle systems impose audit and certification burdens that disproportionately strain small fleet operators.
Strategic Opportunities
- Construction-Adjacent Verticals:GPS-integrated dispatch platforms can capture specialty hauling segments serving aggregates, equipment, and materials transport with project-based scheduling needs.
- Broker Disintermediation:Direct shipper-carrier matching algorithms threaten traditional freight brokerage margins by automating spot market transactions.
- Carbon Accounting Integration:EU CSRD disclosure requirements and emerging EPA reporting rules create demand for dispatch software that tracks and optimizes emissions per load.
Industry Challenges
- Driver Technology Adoption:Aging driver demographics resist mobile app interfaces for load acceptance and electronic documentation, requiring parallel paper workflows.
- Legacy TMS Migration:Decades-old transportation management systems in enterprise carriers resist API connectivity, forcing expensive middleware development for unified visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck Dispatch Software Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premises, Hybrid, Mobile End User: Logistics Providers, Freight Carriers, Fleet Operators, Brokers Solution: Route Optimization, Real-time Tracking, Load Management, Fleet Reporting Technology: GPS, Telematics, AI, Mobile Applications |
| Companies Covered | Truckbase, Samsara, McLeod Software, ProTransport, AscendTMS, Trimble, Motive, Axon Software, ITS Dispatch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck Dispatch Software Market Trends and Innovations
Algorithmic matching engines are displacing human dispatchers in load assignment decisions, compressing response times from hours to seconds. This automation wave is restructuring workforce composition and vendor value propositions simultaneously.
Real-time telematic data fusion is rewriting how carriers manage asset utilization. Engine diagnostics, GPS streams, and driver behavior metrics now feed predictive maintenance models. Mid-market fleet operators are adopting these capabilities fastest as cloud-native platforms eliminate upfront infrastructure investment. The technology is rewriting competitive benchmarks for fleet efficiency and insurance risk scoring.
FMCSA hours-of-service enforcement is tightening compliance windows for electronic logging devices. Carriers face expanded audit scrutiny and automated violation flagging through roadside inspection systems. Large enterprise fleets are responding with integrated dispatch-compliance bundles that unify regulatory clocks across driver pools.
Shippers are consolidating vendor relationships around unified operating systems that combine dispatch, tracking, and settlement. This procurement compression favors platforms with native API ecosystems over point solutions requiring third-party connectors. The shift is most visible among retailers with private fleets serving regional distribution networks.
Truck Dispatch Software Market Segmentation
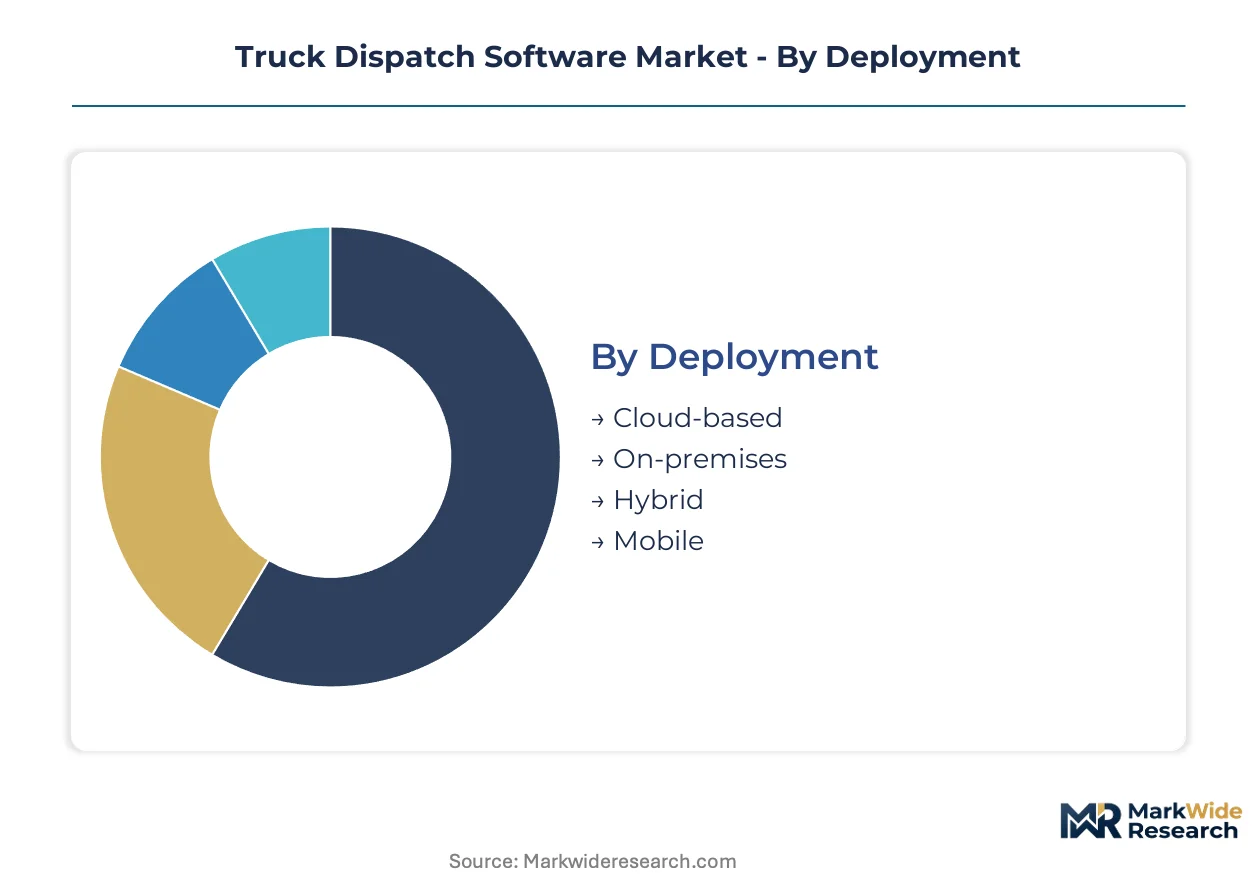
Truck dispatch software segments by deployment architecture, user type, functional module, and underlying sensor technology. Each dimension shapes integration complexity and procurement decisions differently.
Deployment:
Cloud-based platforms dominate new installations while on-premises systems persist in security-sensitive operations. Hybrid architectures bridge legacy infrastructure gaps.
- Cloud-based:Elastic compute scaling eliminates server maintenance overhead. Logistics providers in the US Midwest freight corridor favor SaaS models for volatile volume handling.
- On-premises:Local server installations retain control over sensitive driver data and broker rate intelligence. Large enterprise carriers with dedicated IT staff maintain these systems for compliance audit trails.
- Hybrid:Split architectures keep critical dispatch logic on-site while pushing telematic ingestion to cloud endpoints. This configuration addresses FMCSA data retention requirements without full infrastructure overhaul.
- Mobile:Native smartphone applications extend dispatch functionality to drivers and field supervisors. These lightweight clients depend on cellular connectivity across remote highway corridors.
Cloud-based leads volumes today; mobile deployment is gaining share fastest.
End User:
Procurement authority varies sharply across user categories, with fleet operators now driving direct software acquisition previously managed through intermediaries.
- Fleet Operators:Private fleet managers at retailers and manufacturers insource dispatch control from third-party brokers. These captive trucking assets demand unified visibility across distribution networks.
- Logistics Providers:Third-party logistics firms coordinate multi-carrier dispatch across fragmented capacity pools. Their platforms prioritize broker network connectivity over deep fleet customization.
- Freight Carriers:Asset-based trucking companies match available tractors against shipper tenders through algorithmic load boards. Hours-of-service compliance integration shapes their vendor selection.
- Brokers:Freight intermediaries license dispatch tools to maintain carrier relationships and spot market positioning. Margin compression from automated matching engines threatens their traditional fee structures.
Fleet operators command the steepest expansion trajectory; broker-facing procurement is flattening.
Solution:
Functional modules compete for platform centrality as vendors bundle adjacent capabilities into unified operating systems.
- Route Optimization:Machine learning algorithms minimize empty miles and fuel consumption across multi-stop sequences. Fuel volatility squeezes carrier margins and commands premium pricing for these capabilities.
- Real-time Tracking:GPS-telemetric fusion delivers location visibility to shippers and dispatchers simultaneously. Construction-adjacent hauling segments serving aggregates and equipment transport depend on project-based scheduling overlays.
- Load Management:Automated tendering and driver assignment replace human dispatcher decisions. These engines compress response times from hours to seconds in spot market transactions.
- Fleet Reporting:Aggregated performance dashboards support insurance risk scoring and maintenance planning. Predictive models feed on engine diagnostics and driver behavior metrics.
Route optimization leads volumes today; fleet reporting is climbing the fastest.
Technology:
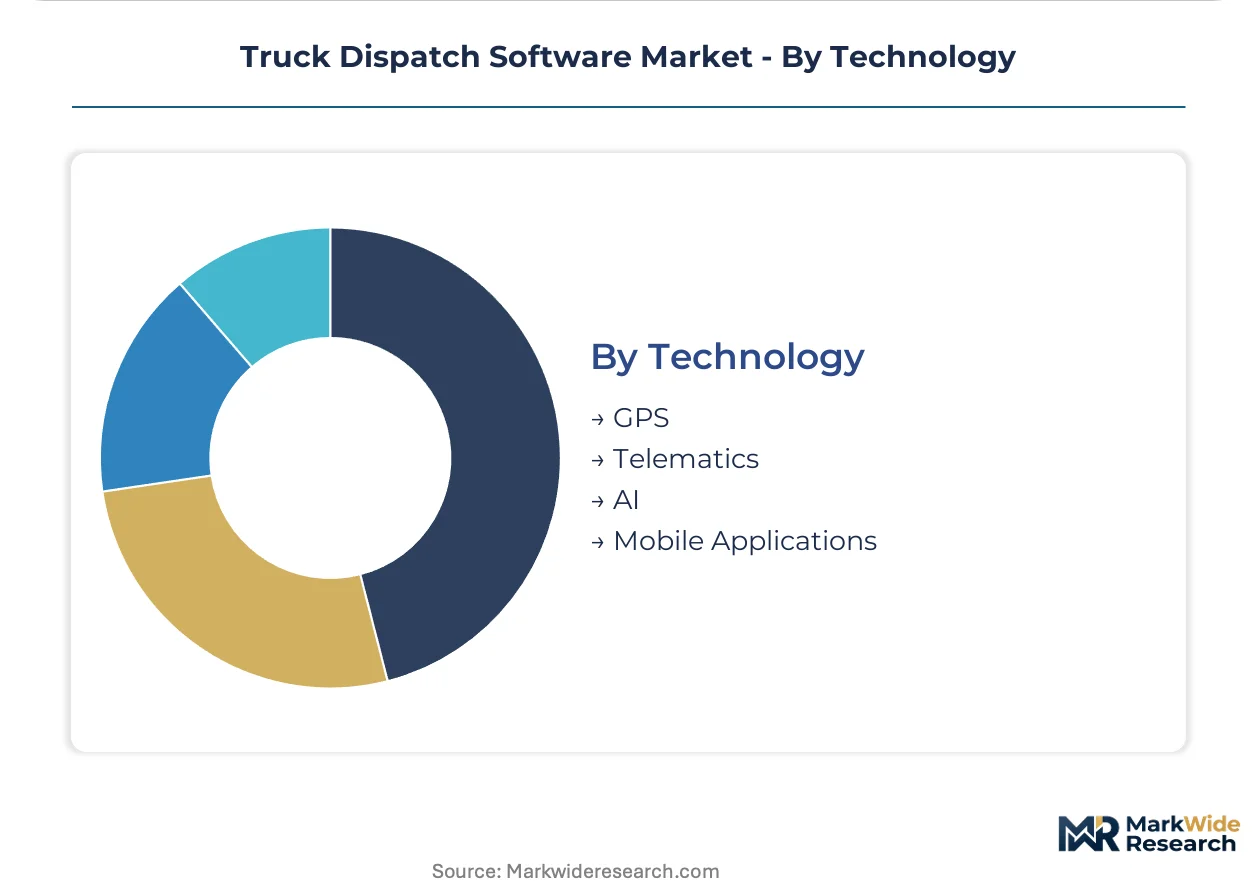
Sensor and compute layers determine data granularity and automation potential across dispatch workflows.
- AI:Predictive models forecast demand patterns, driver availability, and maintenance windows. These systems require clean historical data and continuous retraining.
- Telematics:Engine control unit integration captures diagnostics, hard braking events, and idle time. FMCSA ELD mandates standardized these data streams for hours-of-service enforcement.
- GPS:Satellite positioning enables geofencing, arrival estimation, and route deviation alerts. Rural coverage gaps persist in mountainous terrain and remote corridors.
- Mobile Applications:Smartphone interfaces handle load acceptance, document capture, and messaging. Aging driver demographics resist these interfaces and require parallel paper workflows.
Telematics anchors current installations; AI layers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Chicago-Dallas freight corridor anchors North American dispatch software procurement as volatile freight volumes push logistics providers toward cloud-based platforms. This concentration pattern repeats across industrialized economies where trucking density and regulatory enforcement intersect.
United States
The FMCSA enforces electronic logging device mandates that force carriers toward integrated dispatch-compliance systems. Hours-of-service tracking requirements shape vendor selection across the Midwest freight corridor. Chicago and Dallas broker clusters drive concentrated demand for algorithmic load matching and real-time telematic feeds.
Germany
The EU CSRD disclosure requirements create demand for dispatch platforms that track emissions per load across cross-border haulage. REACH and CE marking standards influence procurement criteria for fleet technology buyers. The Rhine-Ruhr industrial belt concentrates logistics providers adopting cloud-native dispatch solutions for volatile European freight flows.
China
Dual carbon goals from the Ministry of Ecology and Environment push fleet operators toward route optimization software that minimizes fuel burn. GB standards for connected vehicle data shape platform architecture decisions. The Yangtze River Delta manufacturing cluster drives adoption of AI-driven dispatch systems for dense port-to-inland container movements.
India
The PLI scheme for automotive and logistics infrastructure accelerates private fleet expansion and direct software procurement. BIS standards for telematics hardware influence platform integration requirements. The Delhi-Mumbai Industrial Corridor concentrates broker activity and dispatch technology adoption among third-party logistics firms managing fragmented capacity pools.
United Kingdom
GDPPR data protection rules shape cloud deployment decisions for fleet operators handling driver behavioral data. The country's national transport regulator enforces working time directives that parallel FMCSA compliance windows. The Midlands logistics triangle around Birmingham anchors dispatch software demand from retailers insourcing captive trucking assets.
Truck Dispatch Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue construction-adjacent verticals and carbon accounting integration. The vendor landscape compresses as cloud migration collapses deployment timelines and favors unified operating systems over point solutions. Three strategic archetypes dominate: cloud-native platforms with elastic compute scaling, hardware-software bundles anchored in GPS-telematics integration, and enterprise-grade systems offering deep workflow customization. Competitive moves concentrate on API ecosystem expansion and strategic partnerships that bridge telematics hardware with transportation management platforms.
Within the cloud-native tier, Samsara and Motive exemplify vendors capturing mid-market fleet operators through unified visibility architectures. McLeod Software anchors the enterprise-grade segment with workflow customization capabilities for large carriers. Trimble occupies a position at the hardware-software bundle intersection, leveraging GPS-integrated offerings in construction-adjacent hauling segments. These three representatives illustrate how vendor positioning stratifies across deployment complexity and fleet scale requirements.
| Leading Market Players |
|---|
| Truckbase |
| Samsara |
| McLeod Software |
| ProTransport |
| AscendTMS |
| Trimble |
| Motive |
| Axon Software |
| ITS Dispatch |
| Others |
Pricing and Supply Chain Analysis
Software engineering talent concentration in the US Midwest and Eastern Europe establishes labor-cost differentials that widen pricing-tier spreads between cloud-native SaaS platforms and customized enterprise deployments. Carriers in the Chicago-Dallas freight corridor absorb premium subscription rates for unified dispatch-telematics bundles, while smaller operators in secondary markets gravitate toward standardized tiers with limited API access.
Pricing Analysis
Input-cost pass-through from cloud infrastructure providers and telematics hardware vendors shapes SaaS subscription tiers across the market. Pricing stratifies across premium, standard, and economy tiers differentiated by integration complexity and hours-of-service compliance depth. Cost compression in the standard tier intensifies as mid-market fleet operators consolidate vendor relationships. Private fleet managers at large retailers exhibit lowest price sensitivity, prioritizing unified visibility over per-seat licensing costs.
Supply Chain Analysis
Domestic-content mandates in India's PLI scheme for automotive and logistics infrastructure reshape sourcing patterns for telematics hardware integrated into dispatch platforms. Software development centers in the United States, India, and Poland anchor the supply base for algorithmic matching engines and mobile application frameworks. Platform architecture draws from GPS chipsets manufactured in Taiwan, cloud compute provisioned through US hyperscalers, and cellular modems sourced from South Korean suppliers. Single-source vulnerability concentrates in specialized telematics hardware with limited vendor alternatives. Distribution runs through direct enterprise sales teams for large carriers and digital self-service channels for sub-50-truck operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in truck dispatch software rests on cloud infrastructure cost curves flattening and carriers upgrading to AI-enabled premium tiers. The shift from point solutions to unified operating systems creates pricing power for vendors with native API ecosystems.
For Market Incumbents: Anchor market position through backward integration into telematics hardware manufacturing, reducing dependency on third-party GPS-ELD device suppliers. Deepen workflow customization capabilities for enterprise carriers resisting platform migration from legacy TMS investments. Consolidate adjacent fleet functions—maintenance scheduling, fuel tax reporting, driver recruitment—into unified operating systems that raise switching costs. For New Entrants and Emerging Players: Small construction-adjacent haulers serving aggregates and equipment transport represent an underserved buyer archetype with project-based scheduling needs unmet by generic dispatch platforms. Specialty verticals in materials transport tolerate higher per-load pricing for dispatch software with geofenced delivery confirmation and project milestone tracking. Partner with equipment rental marketplaces to embed dispatch functionality into existing contractor workflows rather than building standalone sales channels. For Investors and Strategic Acquirers: Cloud-native fleet management platforms are the most active acquirer in this space, seeking dispatch software capabilities to complete unified visibility offerings. Long-term viability favors vendors with demonstrated API interoperability across telematics hardware brands and transportation management systems. Watch FMCSA enforcement intensity around automated violation flagging as the signal indicating accelerated procurement cycles for integrated dispatch-compliance bundles.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies dispatch, telematics, and compliance into single operating systems that reduce vendor fragmentation for mid-market fleets. |
| Strategic Partnership | Links dispatch software vendors with ELD hardware manufacturers to bundle compliance-ready solutions for FMCSA-mandated carriers. |
| Geographic Expansion | Targets private fleet expansion in India's Delhi-Mumbai Industrial Corridor where PLI scheme incentives accelerate direct software procurement. |
| Acquisition of Specialist Firm | Absorbs AI route optimization startups to embed fuel-saving algorithms that command premium pricing in volatile energy markets. |
| Product Launch | Introduces carbon accounting modules that track emissions per load for EU CSRD compliance and emerging EPA reporting requirements. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. The research incorporated structured interviews with fleet operations directors, logistics technology procurement officers, TMS integration specialists, and FMCSA compliance managers at carriers ranging from 10 to 10,000 tractors. Secondary sources included FMCSA regulatory filings, ELD mandate compliance databases, SEC 10-K disclosures from publicly traded fleet operators, customs data on telematics hardware imports, and cloud infrastructure capex reports from hyperscalers. Bottom-up triangulation across carrier fleet counts and software spend per truck was cross-checked against top-down market sizing from vendor revenue disclosures.
Rate-of-change decomposition across the analysis window separated volume effects from pricing mix shifts as carriers migrated from on-premise licenses to SaaS subscriptions. The forecast framework modeled deployment architecture, fleet size tier, functional module priority, and regional regulatory enforcement intensity as core segmentation dimensions. CAGRs were derived from elasticity-adjusted adoption curves calibrated to ELD mandate compliance deadlines and private fleet insourcing trends. Industry-specific inputs included fuel price volatility coefficients affecting route optimization module demand and FMCSA audit expansion timelines accelerating integrated system procurement.
Underlying measurement precision varies by segment; cloud-based deployment and large fleet operator categories carry tighter precision than hybrid architectures and broker-facing procurement. Forecasts reflect assumptions around ELD enforcement continuity, cloud infrastructure cost trajectories, and carrier consolidation rates that could shift if regulatory timelines or macroeconomic conditions diverge. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Asia-Pacific IT Services Market
Software & Services
Investor Relations (IR) Website Builder Software Market
Software & Services
Optical Coatings Design Software Market
Software & Services
North America Telecom Expense Management Services Software Market
Software & Services
Global Managed Application Services Market
Software & Services
Online Recruitment Software Market
Software & Services
Labeling Software Market
Software & Services
Landing Page Creation Software Market
Software & Services
Mobile Application Stores Market
Software & Services
Talent Acquisition Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Saas-Based SCM Market
Software & Services
Africa Financial Services Software Market
Software & Services
Small Business Manufacturing Software Market
Software & Services
Exercise and Weight Loss Apps Market
Software & Services
Enterprise Backup and Recovery Software Market